
 Filtration Paper Market | 2026-2036
Filtration Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Filtration Paper Market Analysis
Multi-source procurement for specialty cellulose pulp is shifting toward vertically integrated suppliers with captive fiber operations. Ahlstrom-Munksjö leverages its Nordic pulp assets to secure cost-advantaged raw material streams for high-purity filtration grades. Hollingsworth & Vose anchors North American automotive demand through localized melt-blown and wet-laid capacity. Sartorius AG dominates laboratory filtration with membrane-integrated paper composites that command premium positioning in pharmaceutical QC workflows.
Filtration paper consists of precisely engineered fibrous matrices, typically cellulose or synthetic blends, manufactured through controlled wet-laid forming and calendering to achieve defined pore sizes from 0.1 to 25 microns for particle retention and fluid clarification. Glass fiber filtration paper sustains the fastest growth trajectory as diagnostic laboratories demand sub-micron retention for nucleic acid and protein separation protocols. Specialty paper grades concentrate margin pools in pharmaceutical applications where endotoxin compliance and extractable limits exceed standard industrial specifications. Mixed fiber compositions compete aggressively in food industry segments requiring balance between throughput speed and microbial capture efficiency.
EMA MDR purity standards and FDA cGMP guidelines for sterile manufacturing compel filtration paper producers to maintain validated extractable profiles and batch-level certification documentation. REACH restrictions on formaldehyde-based wet-strength resins are forcing reformulation of cellulose grades for European laboratory and food applications. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP chapters as divergence in particulate testing protocols threatens to fragment qualification requirements for multinational supply.
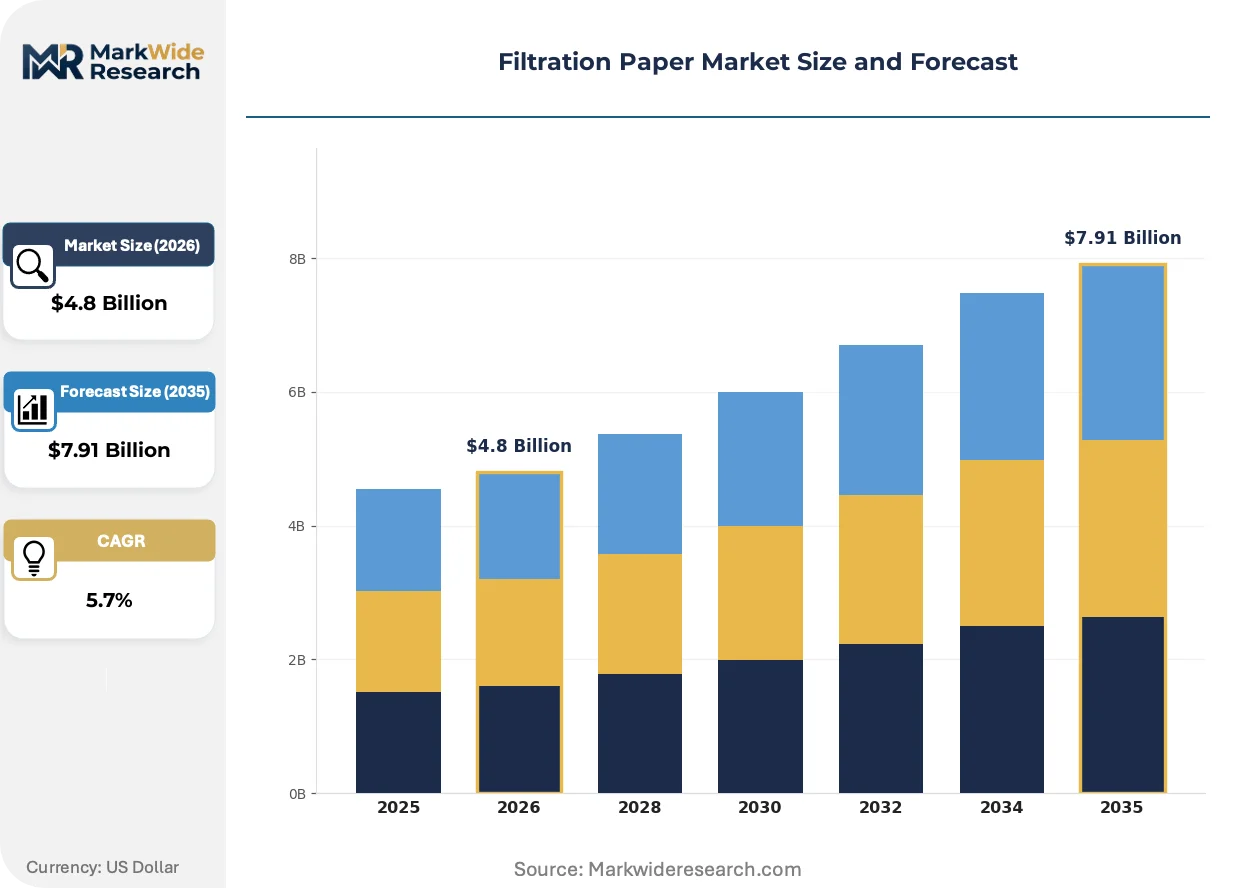
Market Dynamics
Specialty cellulose pulp supply concentration is compressing margin pools for filtration paper converters, forcing backward integration into Nordic and North American fiber assets to secure validated raw material streams for pharmaceutical-grade production.
Growth Catalysts
- EMA MDR purity mandates:Pharmaceutical manufacturers across Germany, France, and Italy are expanding sterile filtration paper procurement to meet tightened endotoxin and extractable compliance for drug manufacturing workflows.
- Glass fiber technology:Diagnostic laboratories are accelerating adoption of sub-micron retention media for nucleic acid separation protocols in molecular testing applications.
- Food safety enforcement:FDA cGMP guidelines for dairy and beverage processing are driving replacement cycles for cellulose-based filtration grades in United States processing facilities.
Market Restraints
- Specialty pulp cost volatility:Dissolving-grade cellulose prices fluctuate with viscose textile demand, squeezing converter margins on high-purity filtration grades.
- Nordic supply concentration:Captive fiber operations in Sweden and Finland control premium softwood pulp streams, creating bottleneck risk for non-integrated filtration paper producers.
- Membrane substitution threat:Polymeric track-etched membranes are capturing share in pharmaceutical sterile filtration where absolute retention requirements exceed cellulose capabilities.
Strategic Opportunities
- India pharmaceutical expansion:CDSCO manufacturing compliance deadlines are creating demand for validated filtration media in active pharmaceutical ingredient production clusters around Hyderabad and Ahmedabad.
- Cellulose-synthetic hybrid grades:Convergence of wet-laid cellulose with melt-blown polypropylene is enabling tailored pore structures for food industry microbial capture applications.
- Biopharma single-use systems:Pre-sterilized filtration assemblies for cell culture media preparation represent unpenetrated white space beyond traditional laboratory markets.
Industry Challenges
- Extractables validation timelines:USP <661> and EP 3.1 compliance documentation for each resin system and fiber blend extends product development cycles by 18-24 months.
- Cross-functional talent scarcity:Combined expertise in wet-laid papermaking and pharmaceutical regulatory affairs remains concentrated among legacy technical staff nearing retirement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filtration Paper Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filter Paper, Absorbent Paper, Specialty Paper, Lab Filter Paper Application: Laboratories, Food Industry, Automotive, Pharmaceuticals Material: Cellulose, Synthetic Fiber, Glass Fiber, Mixed Fiber End User: Research Institutions, Food Manufacturers, Chemical Producers, Health Care Providers |
| Companies Covered | Ahlstrom-Munksjö, Hollingsworth & Vose, GE Healthcare, Sartorius AG, Chmlab Group, Macherey-Nagel, Pall Corporation, Whatman, Advantec MFS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filtration Paper Market Emerging Trajectories
Material science convergence and regulatory harmonization pressures are reshaping filtration paper development priorities, with performance specifications tightening faster than manufacturing process innovation cycles can accommodate.
Glass microfiber filtration media is overtaking traditional cellulose in diagnostic laboratory applications requiring sub-micron particle retention for protein and nucleic acid separation. Clinical reference laboratories in the United States and Western Europe are converting qualitative analytical workflows to quantitative protocols that demand consistent fiber matrix density. This shift is compressing addressable volume for standard qualitative grades while expanding premium positioning for borosilicate glass formulations with defined particle retention curves.
REACH restrictions on formaldehyde-based wet-strength resins are forcing European filtration paper producers to reformulate cellulose grades for laboratory and food contact applications. ECHA substance evaluation timelines are accelerating substitution investments ahead of 2026 authorization sunset dates. German and French converters are responding with citric acid crosslinking and glyoxal alternative chemistries, though these systems require revalidation of extractable profiles under EP 3.1 and USP <661> protocols.
Consolidated procurement by multinational pharmaceutical manufacturers is compressing supplier qualification timelines and unbundling after-sales technical support from unit pricing. Tier-one drug manufacturers in Switzerland and the United States are mandating single-source global contracts with batch-level certification documentation. This concentration is favoring filtration paper producers with integrated quality management systems spanning multiple manufacturing sites under unified pharmacopeial compliance frameworks.
Filtration Paper Market Segmentation
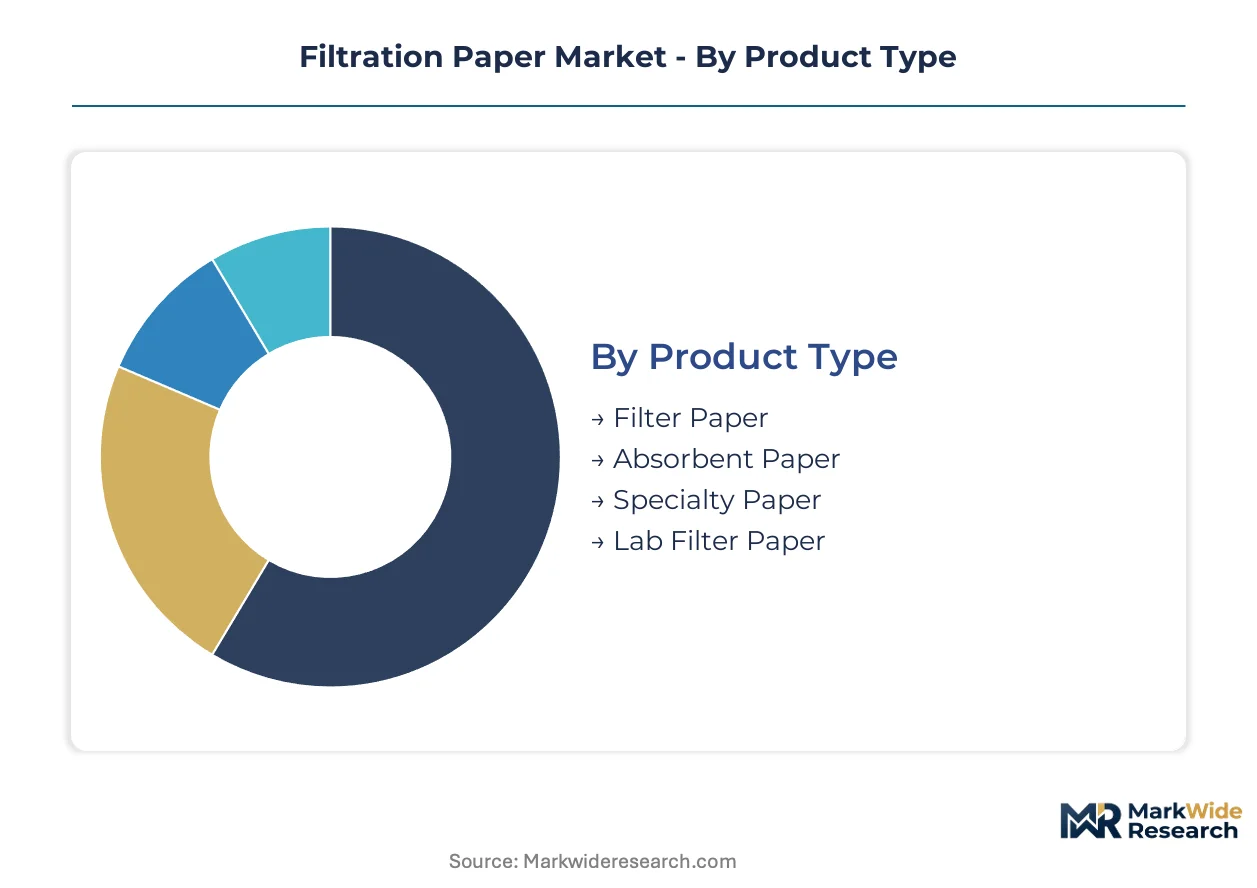
Filtration paper segmentation reflects divergent purity requirements across regulated industries. Pharmaceutical-grade specifications command validation documentation that standard industrial grades cannot support. Material composition and end-use compliance tiers create distinct margin pools that reshape supplier positioning strategies.
Product Type:
Customization intensity spans from commodity absorbent grades to validated laboratory specifications with extractable profiles.
- Filter Paper:Engineered cellulose matrices with defined pore structures from 1 to 25 microns serve clarification and particle retention in beverage processing and industrial fluid filtration. FDA cGMP protocols for dairy processors in Wisconsin and California drive replacement cycles for validated cellulose grades with batch certification.
- Specialty Paper:High-purity grades incorporate controlled fiber blends and surface treatments for endotoxin-sensitive pharmaceutical applications. German sterile drug manufacturers under EMA MDR mandates procure these grades with USP <661> and EP 3.1 extractable documentation, compressing supplier qualification timelines to 18-24 months.
- Absorbent Paper:High-bulk cellulose structures wick aqueous fluids in diagnostic test strips and food packaging applications.
- Lab Filter Paper:Qualitative and quantitative grades with ash content specifications support gravimetric analysis in academic and industrial laboratories.
Leading the category by volume: Filter Paper. Growing fastest: Specialty Paper.
Application:
Cost tiers separate regulated pharmaceutical workflows from price-sensitive automotive and food processing segments.
- Pharmaceuticals:Sterile filtration applications demand absolute retention validation and pyrogen-free certification for parenteral drug manufacturing. Swiss and German drug producers mandate single-source global contracts with unified pharmacopeial compliance across manufacturing sites.
- Laboratories:Analytical and diagnostic workflows require consistent fiber matrix density for quantitative protein and nucleic acid separation. United States clinical reference laboratories are converting to borosilicate glass microfiber for sub-micron retention protocols.
- Food Industry:Microbial capture and clarification applications balance throughput speed against filtration efficiency in dairy and beverage processing.
- Automotive:Engine oil and fuel filtration applications prioritize cost-efficient cellulose grades with pleatability for high-volume manufacturing.
Highest margin concentration: Pharmaceuticals. Steepest expansion trajectory: Laboratories.
Material:
Supply concentration for premium fiber streams creates sourcing advantages for integrated producers.
- Glass Fiber:Borosilicate formulations with defined particle retention curves below 1 micron enable nucleic acid and protein separation in molecular diagnostics. Diagnostic laboratories in the United States and Western Europe are accelerating conversion from cellulose to glass microfiber for quantitative analytical workflows.
- Cellulose:Softwood and hardwood pulp blends provide tunable porosity and biodegradability for food contact and laboratory applications. REACH restrictions on formaldehyde-based wet-strength resins are forcing European producers toward citric acid and glyoxal alternative chemistries.
- Synthetic Fiber:Polypropylene and polyester wet-laid media offer chemical resistance for aggressive solvent filtration.
- Mixed Fiber:Cellulose-synthetic hybrid compositions balance microbial capture efficiency with throughput speed in food industry applications.
Dominant by volume: Cellulose. Expanding most quickly: Glass Fiber.
End User:
Customer type determines procurement sophistication from centralized pharmaceutical tendering to fragmented food processor spot buying.
- Research Institutions:Academic and government laboratories procure qualitative and quantitative grades through distributor channels with specification flexibility. Budget constraints favor standard cellulose grades over premium glass fiber for routine analytical workflows.
- Health Care Providers:Hospital and clinical laboratories demand consistent supply of sterile filtration media for diagnostic applications. Consolidated procurement by United States health systems is compressing supplier margins while expanding volume commitments.
- Food Manufacturers:Dairy and beverage processors replace filtration media on preventive maintenance schedules driven by FDA cGMP enforcement.
- Chemical Producers:Industrial process filtration applications prioritize chemical compatibility and cost efficiency over extractable validation.
Largest procurement volume: Food Manufacturers. Fastest compliance escalation: Health Care Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturing clusters in Germany, the United States, and Switzerland concentrate the highest-value filtration paper procurement. Regulatory enforcement in these markets validates premium-grade supply chains while diagnostic laboratory expansion drives volume growth across secondary markets.
United States
FDA cGMP enforcement for dairy and beverage processing compels replacement cycles for cellulose-based filtration grades. Wisconsin and California processing facilities procure validated media with batch-level certification. Clinical reference laboratories in Boston and San Diego accelerate conversion to borosilicate glass microfiber for quantitative nucleic acid separation protocols.
Germany
EMA MDR purity mandates expand sterile filtration paper procurement for parenteral drug manufacturing. Heidelberg and Frankfurt pharmaceutical clusters demand endotoxin-compliant grades with USP extractable documentation. German converters reformulate cellulose grades with citric acid crosslinking to satisfy REACH restrictions on formaldehyde-based wet-strength resins.
India
CDSCO manufacturing compliance deadlines create demand for validated filtration media in active pharmaceutical ingredient production. Hyderabad and Ahmedabad clusters upgrade filtration infrastructure for export-oriented sterile manufacturing. Domestic converters face qualification timeline compression as multinational drug manufacturers consolidate procurement under single-source global contracts.
Switzerland
Swissmedic oversight of sterile drug manufacturing sustains premium positioning for membrane-integrated paper composites. Basel pharmaceutical manufacturers mandate unified pharmacopeial compliance across manufacturing sites. Swiss converters leverage proximity to Nordic pulp supply chains for cost-advantaged raw material access.
China
NMPA biopharma quality system reforms accelerate adoption of pre-sterilized filtration assemblies for cell culture media preparation. Shanghai and Suzhou diagnostic manufacturers expand glass microfiber capacity for molecular testing export markets. Domestic producers confront extractables validation gaps as multinational pharmaceutical tenders demand EP and USP chapter harmonization.
Filtration Paper Market Vendor Landscape
Backward integration into captive fiber operations dominates the current landscape as converters secure validated raw material streams. The vendor base stratifies across three tiers: integrated pulp-to-paper producers with Nordic assets, regional wet-laid specialists with localized melt-blown capacity, and membrane-integrated composite manufacturers serving pharmaceutical QC workflows. Strategic archetypes include upstream-controlled cost leaders, regulatory-compliance premium positioners, and hybrid-scale regional champions. Competitive intensity centers on fiber asset acquisition and pharmacopeial certification velocity rather than price-based displacement.
Among integrated Nordic producers, Ahlstrom-Munksjö exemplifies upstream-controlled positioning through captive softwood pulp operations. Hollingsworth & Vose anchors North American automotive and industrial demand through localized wet-laid manufacturing presence. Sartorius AG occupies the membrane-integrated premium tier, representing pharmaceutical QC workflow specialization with composite technologies that command qualification-intensive procurement channels.
| Leading Market Players |
|---|
| Ahlstrom-Munksjö |
| Hollingsworth & Vose |
| GE Healthcare |
| Sartorius AG |
| Chmlab Group |
| Macherey-Nagel |
| Pall Corporation |
| Whatman |
| Advantec MFS |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between USP-validated pharmaceutical grades and commodity cellulose separates margin pools by an order of magnitude, with each tier sourcing from fundamentally different fiber supply configurations. Premium grades draw from Nordic captive pulp operations with batch-level documentation chains, while standard industrial grades compete on spot-market softwood pricing with minimal traceability requirements.
Pricing Analysis
Volume concentration in automotive and food processing cellulose grades compresses margins through commoditized spot purchasing, while pharmaceutical and diagnostic segments sustain premium positioning via qualification-intensive procurement. Price differentiation rests on USP extractable documentation tiers and endotoxin compliance certification, with validated grades commanding substantial premiums over standard laboratory specifications. Pricing pressure stems from REACH-mandated wet-strength resin reformulation costs passing through to European converters. Food manufacturers exhibit highest price sensitivity through preventive maintenance schedule buying, whereas Swiss and German pharmaceutical tenders accept elevated pricing bundled with unified multi-site compliance documentation.
Supply Chain Analysis
Dual-sourcing mandates from multinational pharmaceutical manufacturers compel qualification of redundant Nordic pulp suppliers, extending validation timelines. Geographic supply concentration centers on Sweden and Finland for premium softwood dissolving pulp, Germany and France for conversion and coating capabilities, and the United States for glass microfiber borosilicate formulations. Raw material dependencies include specialty cellulose pulp, formaldehyde-free wet-strength chemistries, and precision-calendering equipment. Single-source vulnerability runs through Nordic fiber assets controlled by integrated producers. Distribution runs through direct pharmaceutical tender channels for premium grades and industrial distributor networks for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Filtration paper market structure favors consolidation plays as extractables validation timelines and REACH compliance investments force sub-scale European converters toward exit or acquisition. Regulatory burden escalation compresses viable competitor counts in pharmaceutical-grade supply.
For Market Incumbents: Acquire Nordic softwood pulp assets or long-term offtake contracts to secure cost-advantaged raw material streams against specialty pulp price volatility. Invest in unified pharmacopeial compliance frameworks spanning multiple manufacturing sites to capture consolidated multinational pharmaceutical tenders. Membrane substitution threats in absolute retention applications demand accelerated development of cellulose-synthetic hybrid composites with defined sub-micron performance curves.
For New Entrants and Emerging Players: Biopharma single-use system assemblers represent an underserved buyer archetype requiring pre-sterilized filtration media beyond traditional laboratory markets. CDSCO compliance deadlines in Indian API manufacturing clusters offer geographic white space with compressed qualification timelines favoring agile entrants. A go-to-market angle anchored in rapid extractables documentation turnaround under USP and EP protocols differentiates against legacy incumbents with 18-24 month development cycles.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale European converters possessing validated fiber supply relationships and existing pharmacopeial certification infrastructure, given REACH-driven competitor exits. Long-term viability over a multi-year horizon favors assets with demonstrated EMA MDR compliance velocity and capacity to serve consolidated Swiss and German pharmaceutical procurement. The signal to watch is CDSCO manufacturing compliance deadline adherence rates across Indian API clusters as demand inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Pulp Assets | Captive fiber supply secures cost advantage for USP-validated pharmaceutical grades against spot-market volatility. |
| Cellulose-Synthetic Hybrid Grade Development | Convergence of wet-laid cellulose with melt-blown polypropylene enables tailored microbial capture for food safety applications. |
| Unified Pharmacopeial Compliance Framework | Single-source global contracts from Swiss and German pharmaceutical manufacturers demand multi-site certification documentation. |
| Pre-Sterilized Filtration Assembly Expansion | Biopharma single-use systems for cell culture media preparation represent unpenetrated demand beyond laboratory markets. |
| Formaldehyde-Free Resin Reformulation | Citric acid and glyoxal alternative chemistries satisfy REACH restrictions while requiring EP 3.1 revalidation investment. |
Methodological Framework
Multi-period observation of EMA MDR implementation timelines, FDA cGMP enforcement patterns, and REACH authorization sunset dates anchored the trend analysis, supplemented by interviews with filtration paper plant managers, pharmaceutical procurement leads, diagnostic laboratory directors, and Nordic pulp supply specialists. Secondary validation drew from ECHA substance evaluation databases, USP chapter revision notices, EP monograph updates, and customs trade flow records for dissolving-grade cellulose. Bottom-up segment sizing triangulated against top-down market value reconstruction across material composition and end-use tiers.
Input-output matrix framing linked specialty pulp pricing indices to converter margin compression, regulatory compliance cost structures to product development cycle extension, and diagnostic laboratory conversion rates to glass microfiber demand trajectories. Segmentation dimensions modeled included product type, application purity tier, material composition, and end-user procurement sophistication. CAGRs were derived from regression analysis of historical procurement volumes against regulatory enforcement milestone timing. Industry-specific forecast inputs incorporated CDSCO compliance deadline schedules and NMPA biopharma quality system reform implementation velocity.
Revisions become necessary when EMA MDR purity mandates accelerate beyond current compliance infrastructure capacity, when REACH authorization timelines compress faster than alternative chemistry validation cycles, or when membrane substitution rates in pharmaceutical sterile filtration exceed cellulose hybrid development response speeds. Deviation in Nordic pulp supply concentration or pharmacopeial chapter harmonization progress would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
NCR Laser Paper Market
Paper Products
Stone Paper Market
Paper Products
Sawn Wood Market
Paper Products
Woodfree Paper Market
Paper Products
GCC Stone Paper Market
Paper Products
Inlay Paper Market
Paper Products
Latex-Saturated Paper Market
Paper Products
Graphic Paper Market
Paper Products
Decor Paper Market
Paper Products
Veneer Sheets Market
Paper Products
Billing Paper Market
Paper Products
Functional and Barrier Coatings for Paper Market
Paper Products
Global Copier Paper Market
Paper Products
Global Paperboard Market
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
Hardwood Pulp Market