
 Graphic Paper Market | 2026-2036
Graphic Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Graphic Paper Market Outlook
Commercial printing is expanding as a stabilizing force amid structural decline in newsprint consumption. Nippon Paper Industries Co. Ltd. leverages its integrated pulp-to-paper operations across Japan to sustain cost advantages in coated grades. Sappi Limited anchors its competitiveness through specialized cellulose derivatives and graphic paper co-production at South African and European mills. International Paper Company dominates North American distribution channels for uncoated freesheet while navigating secular volume erosion.
Graphic paper encompasses mechanically or chemically pulped sheets engineered for printed communication, typically specified by brightness (ISO 80-96), opacity, and surface finish calibrated for ink receptivity. Coated paper commands premium positioning in high-end catalog and magazine work due to superior halftone reproduction, while uncoated paper retains volume leadership in office documentation and book publishing where tactile quality outweighs gloss. Uncoated paper segments face margin compression from digital displacement, whereas coated paper and glossy paper variants serving advertising agencies and graphic designers concentrate value pools in shorter-run, higher-specification jobs. Matte paper occupies a defensible niche in art reproduction and luxury packaging inserts where subdued finish conveys premium positioning.
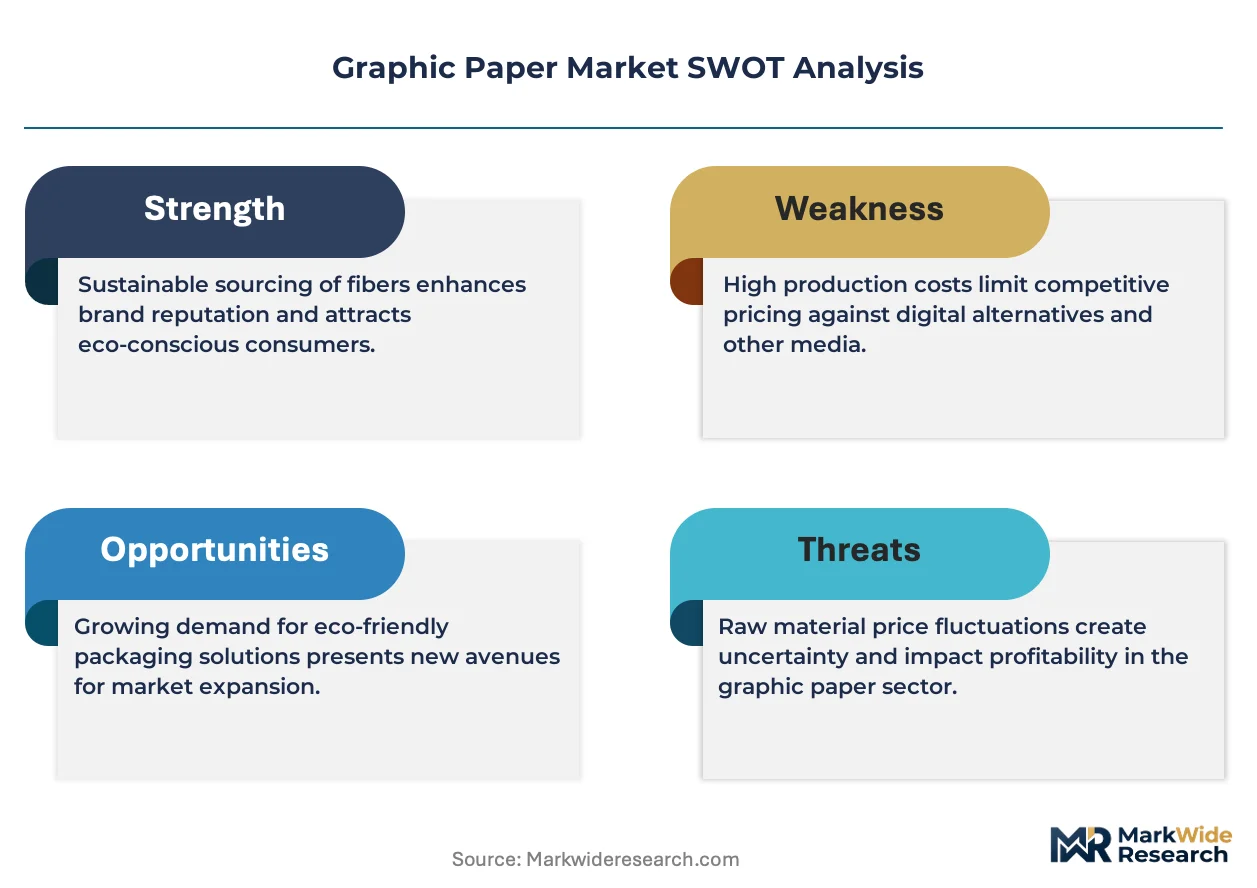
EPA effluent guidelines and OSHA workplace chemical standards constrain bleaching chemistries and wastewater discharge across US mill operations, while EU Ecolabel and FSC chain-of-custody certification shape procurement specifications for publishing houses and educational institutions in Europe. China's MEE enforces increasingly stringent COD and AOX discharge limits that elevate compliance capital for regional producers. Stakeholders must monitor regulatory divergence between jurisdictions as carbon border adjustments and recycled content mandates redefine competitive cost structures for cross-border paper trade.
Market Dynamics
Digital substitution of newsprint and directory paper is compressing commodity volumes while specialty packaging and high-specification commercial printing create offsetting value pools. China's dual carbon goals are forcing mill closures and technology upgrades that concentrate supply among integrated producers with capital access.
Growth Catalysts
- Specialty packaging migration:Premium cosmetics and electronics brands are converting folding carton demand toward coated graphic substrates with superior print fidelity and tactile surface properties.
- EPA effluent guideline tightening:US mills investing in oxygen-delignification and ozone bleaching sequences capture preferential sourcing contracts from publishers with public ESG commitments.
- Southeast Asia publishing modernization:Indonesia, Vietnam, and Thailand are expanding magazine and catalog print runs as advertising expenditure shifts from broadcast to print-media channels.
Market Restraints
- Pulp cost volatility:Hardwood and softwood fiber prices swing with Baltic freight rates and Russian log export restrictions, squeezing uncoated freesheet margins.
- Newsprint demand collapse:Daily newspaper circulation in North America and Western Europe has fallen below structural viability thresholds for many single-product mills.
- Digital document substitution:Enterprise content management platforms and e-invoicing mandates are permanently displacing carbonless copy and thermal paper applications.
Strategic Opportunities
- India educational publishing expansion:Government textbook procurement and private coaching material print runs are growing faster than domestic coated paper capacity.
- EU Ecolabel certification premium:Publishers in Germany and the Netherlands pay 8-12% premiums for FSC-chain-of-custody verified and chlorine-free bleached stocks.
- On-demand inkjet compatibility:Mills developing structured surfaces for water-based pigment ink adhesion capture share from digital print service providers expanding into short-run books.
Industry Challenges
- Process control engineering scarcity:Bleach plant optimization and closed-loop water system design require expertise that has aged out of the workforce without adequate replacement pipelines.
- MEE compliance timeline compression:Chinese mills face 18-month deadlines to install anaerobic wastewater treatment while maintaining production continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphic Paper Market |
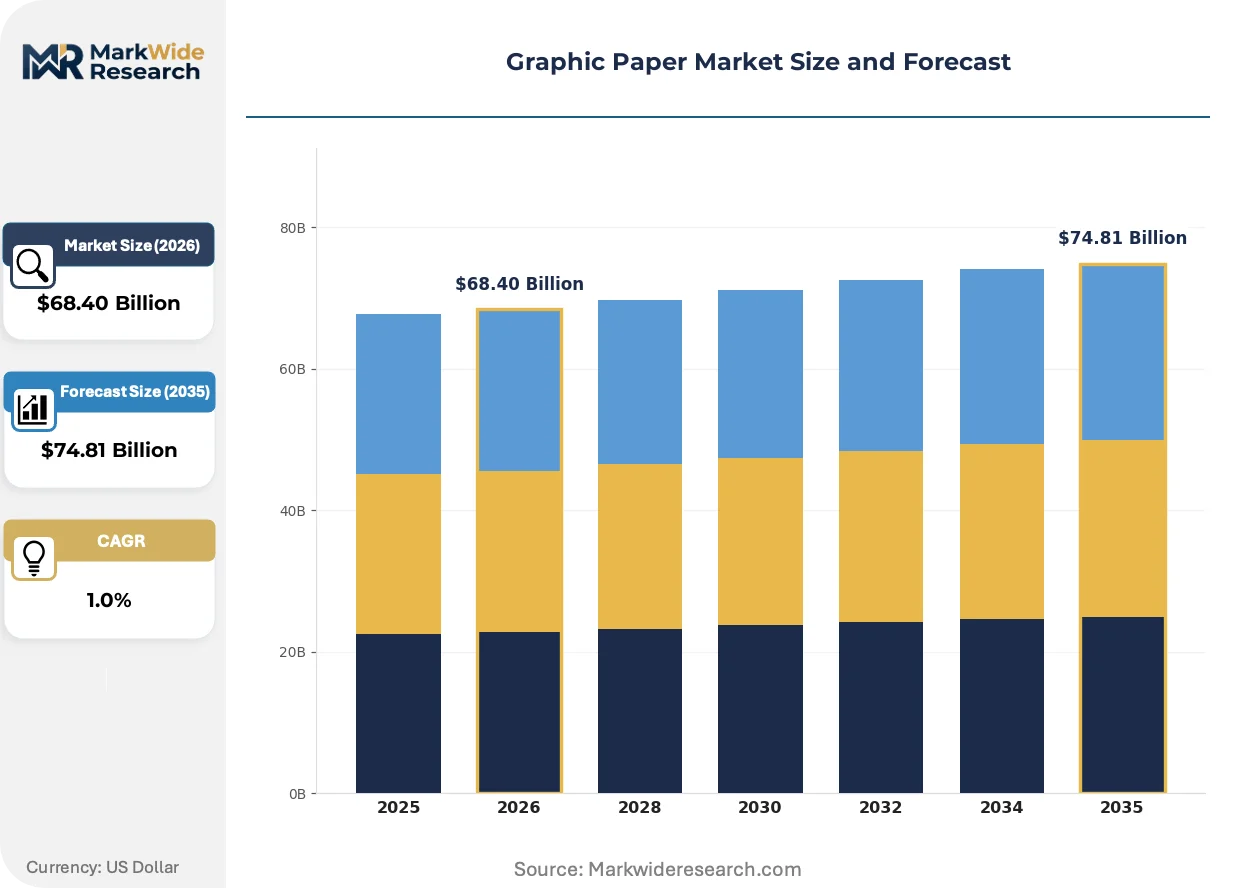
| Market Size in 2026 | $68.40 Billion |
| Market Size in 2035 | $74.81 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Glossy Paper, Matte Paper Application: Commercial Printing, Packaging, Stationery, Art & Craft End User: Publishing Houses, Educational Institutions, Advertising Agencies, Graphic Designers Thickness: Lightweight, Medium Weight, Heavyweight, Extra Heavyweight |
| Companies Covered | Nippon Paper Industries Co. Ltd., Sappi Limited, International Paper Company, Smurfit Kappa Group plc, Mondi Group, Stora Enso Oyj, Nine Dragons Paper (Holdings) Limited, Oji Holdings Corporation, UPM-Kymmene Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphic Paper Market Strategic Shifts
Production technology and regulatory frameworks are diverging across major economies, creating competitive advantage for mills that can navigate heterogeneous compliance requirements while serving fragmented demand for specialized substrates.
Water-based barrier coatings are decentralizing the food-contact paper supply chain by enabling graphic paper mills to enter folding carton segments previously reserved for integrated board producers. Specialty chemical suppliers including Michelman and Solenis have developed spray-applied formulations that achieve grease resistance without polyethylene lamination. Magazine printers in Italy and Spain are qualifying these substrates for confectionery and dry-goods inserts that require both high-quality halftone reproduction and direct food contact compliance.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating oil-and-grease-resistant treatments that relied on fluorochemical chemistry, forcing reformulation of food-service papers and release liners. ECHA's 2023 restriction proposal covers the entire substance class without grandfathering existing stocks. Finnish and Swedish mills with in-house R&D capabilities are commercializing cellulose-derivative and plant-wax alternatives, while smaller converters without formulation expertise face supply disruption and customer qualification delays.
Consolidation among commercial printers is compressing supplier negotiation cycles and concentrating volume among fewer procurement decision-makers. Large-format and web-offset houses in the US Midwest and German Rhine-Ruhr corridor are forming purchasing cooperatives to secure volume discounts and technical service commitments. This aggregation is squeezing smaller regional mills that lack the scale to meet consolidated tender requirements or the geographic reach to serve dispersed print networks efficiently.
Graphic Paper Market Segmentation
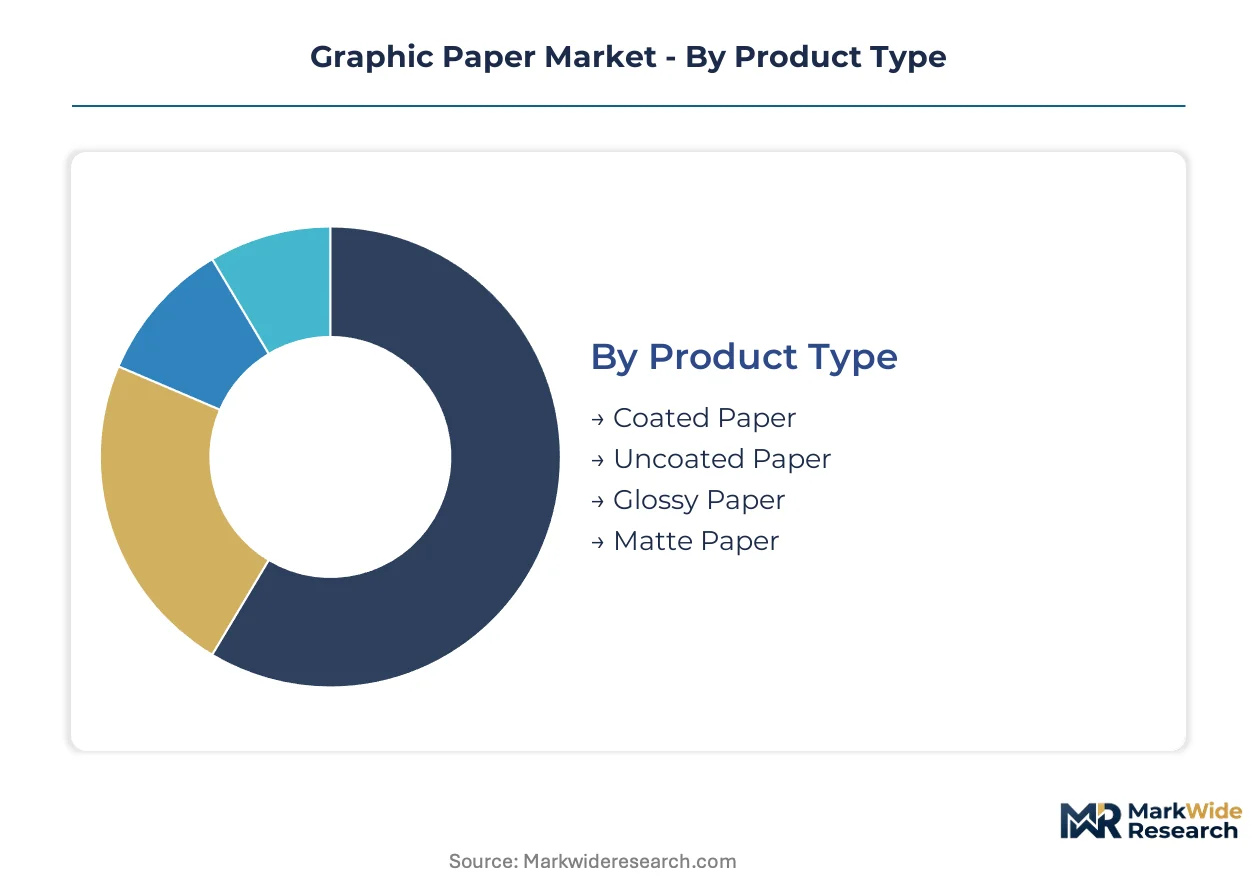
Graphic paper segmentation reveals how capital deployment and technical specifications fragment value pools across the supply chain. Mills configure pulping, coating, and calendering assets to serve distinct performance tiers rather than commodity volumes.
Product Type:
Coated paper demands the heaviest capital intensity due to multilayer coating towers and supercalendering investments required for glossy surface finish.
- Coated Paper:Clay or calcium carbonate coatings applied to base stock create controlled ink receptivity for halftone reproduction. Demand concentrates in high-end catalog and magazine work across Germany and Italy where advertising agencies specify brightness above ISO 90. EU Ecolabel certification requirements are forcing mills to reformulate coating binders away from synthetic latex.
- Uncoated Paper:Mechanically or chemically pulped sheets rely on fiber refining and wet-press optimization for surface smoothness without coating layers. Office documentation and book publishing in the United States absorb the largest volumes, though enterprise digitization is compressing run lengths and forcing mills toward on-demand inkjet compatibility investments.
- Glossy Paper:Cast-coated or film-coated variants achieve mirror-like reflectivity through specialized drying and polishing sequences.
- Matte Paper:Subdued surface finish engineered through controlled fiber distribution and minimal calendering pressure serves art reproduction and luxury packaging inserts.
Most installed capacity flows through uncoated paper. Expansion is steepest in matte paper serving premium cosmetic packaging applications.
Application:
Commercial printing generates the highest margin stability through shorter-run, higher-specification jobs that resist digital displacement.
- Commercial Printing:Brochures, annual reports, and direct mail demand precise color consistency and dimensional stability. Southeast Asian advertising expenditure shifts from broadcast to print-media channels are expanding magazine and catalog print runs in Indonesia, Vietnam, and Thailand.
- Packaging:Folding cartons and luxury box wraps require food-contact compliance alongside print fidelity. Water-based barrier coatings from Michelman and Solenis enable graphic paper mills to enter segments previously reserved for integrated board producers in Italy and Spain.
- Stationery:Writing paper and correspondence stocks prioritize tactile surface quality and fountain pen ink behavior over optical brightness.
- Art & Craft:Heavyweight sheets with cotton fiber content serve archival printmaking and mixed-media applications.
Commercial printing commands the largest revenue share. Packaging applications are gaining share fastest as cosmetic and electronics brands migrate toward coated graphic substrates.
End User:
Publishing houses represent the most consolidated procurement base with centralized tender processes that favor scale suppliers.
- Publishing Houses:Trade book, textbook, and periodical publishers specify bulk orders with strict shade consistency and roll-to-roll uniformity. Indian government textbook procurement and private coaching material print runs are expanding faster than domestic coated paper capacity can accommodate.
- Educational Institutions:University presses and K-12 worksheet printers prioritize cost efficiency over premium surface characteristics.
- Advertising Agencies:Creative departments specify substrates for campaign collateral where tactile impression influences brand perception.
- Graphic Designers:Freelance and studio practitioners drive demand for sample swatch diversity and short-run availability.
Publishing houses direct the highest absolute tonnage. Advertising agencies are expanding specification influence fastest as brand owners prioritize sensory marketing.
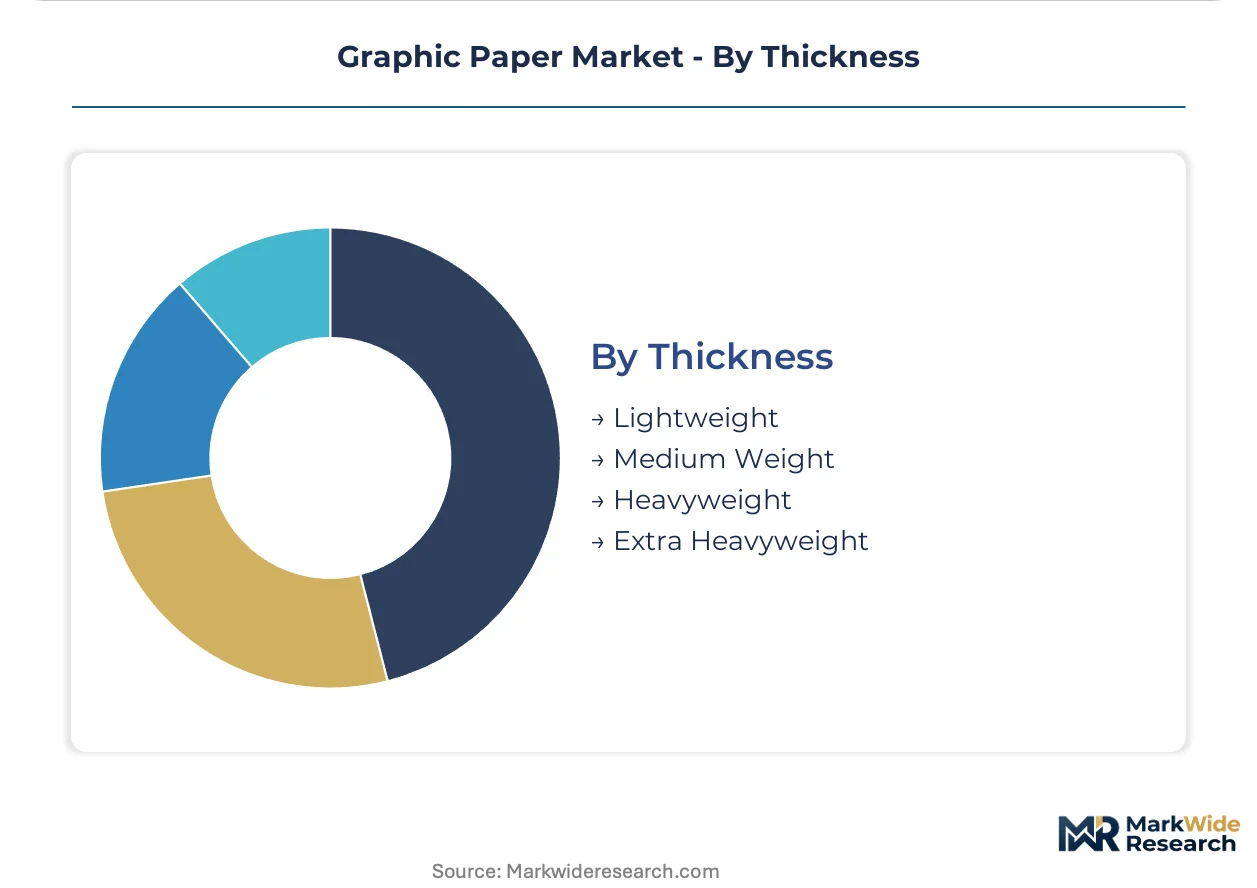
Thickness:
Medium weight grades balance machine runnability with finished product rigidity across the broadest application range.
- Lightweight:Sub-60 gsm bible and dictionary papers maximize opacity per fiber unit through high-yield mechanical pulping.
- Medium Weight:70-100 gsm stocks serve general commercial printing and office copying with optimized stiffness-to-bulk ratios.
- Heavyweight:120-200 gsm cover stocks and card grades require extended wet-pressing and through-air drying capacity.
- Extra Heavyweight:Above 200 gsm board-like products approach folding carton specifications with multi-ply construction.
Medium weight dominates machine utilization. Extra heavyweight is climbing fastest as packaging substitution accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing production maps as mills migrate toward jurisdictions with lower carbon compliance costs and less stringent effluent enforcement. China's dual carbon timeline and MEE discharge limits are accelerating capacity rationalization, while Southeast Asian nations attract investment through relaxed environmental timelines and expanding domestic demand.
China
Beijing-Tianjin-Hebei and the Yangtze River Delta host the majority of coated paper capacity serving domestic publishing and export markets. MEE enforcement of COD and AOX discharge limits is forcing 18-month compliance deadlines that favor integrated producers with capital reserves. Shandong Province mills are consolidating through state-directed mergers to meet dual carbon closure targets.
United States
EPA effluent guideline tightening and OSHA workplace chemical standards are elevating capital requirements for oxygen-delignification and ozone bleaching investments. Wisconsin and Maine mill clusters serve magazine and catalog printers with preferential sourcing contracts from publishers with public ESG commitments. Midwest purchasing cooperatives are compressing supplier negotiation cycles among consolidated commercial printers.
Germany
Rhine-Ruhr corridor web-offset houses and Bavarian packaging converters drive specification demand for EU Ecolabel-certified stocks. REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorochemical-based grease-resistant treatments, forcing reformulation of food-contact papers. Hamburg and North Rhine-Westphalia mills with in-house R&D capabilities are commercializing cellulose-derivative barrier alternatives.
India
Maharashtra and Gujarat mill clusters face coated paper supply shortages against accelerating government textbook procurement and private coaching material print runs. BIS standards and DGFT import policies shape raw fiber sourcing strategies for domestic producers. Tamil Nadu educational publishers are expanding magazine and workbook specifications faster than regional capacity can accommodate.
Indonesia
Java-based mills are capturing Southeast Asian advertising expenditure shifts from broadcast to print-media channels. Relaxed environmental enforcement relative to Northeast Asian competitors is attracting Japanese and Korean joint venture investments in coated graphic paper capacity. Jakarta and Surabaya printer networks are expanding catalog and direct mail runs for regional consumer brands.
Graphic Paper Market Competitive Environment
Capacity rationalization dominates the current landscape as single-product newsprint mills face structural viability thresholds and integrated producers capture preferential contracts. The vendor base segments into three tiers: multinational integrated pulp-to-paper operators with global distribution networks, regional specialists co-producing graphic paper alongside packaging grades, and distressed commodity players exiting newsprint. Strategic archetypes include ESG-compliant premium suppliers, cost-focused mechanical pulp integrators, and technology-forward inkjet substrate developers. M&A consolidation and geographic repositioning toward lower-compliance jurisdictions represent the dominant competitive moves.
Within the integrated multinational tier, Nippon Paper Industries Co. Ltd. and International Paper Company exemplify divergent geographic strategies. Japanese and North American-based operators occupy positions shaped by domestic regulatory stringency and consolidated procurement channels. South African and European-anchored specialists including Sappi Limited sit within the cellulose derivative co-production segment, leveraging integrated chemical pulp operations to sustain margin pools. Chinese producers such as Nine Dragons Paper (Holdings) Limited and Oji Holdings Corporation represent scale-driven archetypes with backward integration into recovered fiber and virgin pulp supply chains.
| Leading Market Players |
|---|
| Nippon Paper Industries Co. Ltd. |
| Sappi Limited |
| International Paper Company |
| Smurfit Kappa Group plc |
| Mondi Group |
| Stora Enso Oyj |
| Nine Dragons Paper (Holdings) Limited |
| Oji Holdings Corporation |
| UPM-Kymmene Corporation |
| Others |
Value Chain & Pricing Dynamics
Backward integration into captive pulp supply anchors pricing power for mills operating across China's Yangtze River Delta and Germany's North Rhine-Westphalia corridor. This structural choice insulates integrated producers from Baltic freight rate swings and Russian log export restrictions that compress margins for fiber-dependent competitors.
Pricing Analysis
Distributor margins absorb compression as consolidated commercial printers in the US Midwest and German Rhine-Ruhr corridor form purchasing cooperatives to extract volume discounts. Three-tier pricing structure across premium, standard, and economy levels stratifies by EU Ecolabel certification and FSC chain-of-custody verification, with German and Dutch publishers paying premiums for chlorine-free stocks. Pricing pressure stems from newsprint demand collapse in North America and Western Europe, where single-product mills face structural viability thresholds. Educational institutions and K-12 worksheet printers exhibit highest price sensitivity, while advertising agencies specifying luxury cosmetic packaging inserts demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
Dual-sourcing requirements from consolidated publishing houses and advertising agency procurement desks mandate multi-supplier qualification across Chinese, Finnish, and South African mill networks. Geographic supply concentrates in China, Indonesia, and Germany, with hardwood and softwood fiber dependencies tethered to Baltic shipping routes and Russian log export policies. Single-source vulnerability escalates where mills rely on single-region bleaching chemical suppliers facing REACH per- and polyfluoroalkyl substance restrictions. Distribution runs through integrated pulp-to-paper operators with direct mill-to-printer relationships, bypassing traditional merchant intermediaries in high-specification coated paper segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Graphic paper functions as a stable compounder where specialty packaging migration and Southeast Asian publishing modernization offset secular decline in newsprint consumption. Steady demand from premium cosmetics and electronics brands for coated folding carton substrates sustains value pool expansion.
For Market Incumbents: Anchor competitiveness through oxygen-delignification and ozone bleaching investments that capture preferential sourcing contracts from publishers with public ESG commitments. Defend against digital displacement by developing structured surfaces for water-based pigment ink adhesion serving on-demand inkjet print service providers. Prioritize certification investment in EU Ecolabel and FSC chain-of-custody verification to sustain premium positioning in German and Dutch procurement channels.
For New Entrants and Emerging Players: Water-based barrier coating technology serves as a technology-first wedge into food-contact folding carton segments previously reserved for integrated board producers in Italy and Spain. Target India's educational publishing expansion, where government textbook procurement and private coaching material print runs outpace domestic coated paper capacity. Pursue joint venture structures with established chemical suppliers including Michelman and Solenis to accelerate substrate qualification timelines.
For Investors and Strategic Acquirers: Consolidation pressure builds where single-product newsprint mills fall below structural viability thresholds and integrated producers capture preferential contracts. Long-term viability favors cellulose derivative co-production capabilities and geographic repositioning toward Southeast Asian jurisdictions with relaxed environmental enforcement. Monitor Chinese MEE compliance timeline compression as inflection indicator for regional capacity rationalization and state-directed merger activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive fiber sourcing from Brazilian eucalyptus or Nordic softwood insulates margin pools from Baltic freight volatility. |
| EU Ecolabel Certification Investment | Chlorine-free bleaching sequences unlock 8-12% pricing premiums from German and Dutch publishing houses. |
| Water-Based Barrier Coating Development | Spray-applied Michelman and Solenis formulations enable entry into food-contact folding carton segments. |
| Southeast Asian Capacity Expansion | Indonesian and Vietnamese mill investments capture advertising expenditure shifts from broadcast to print-media channels. |
| On-Demand Inkjet Substrate Engineering | Structured surface development captures share from digital print service providers expanding into short-run books. |
Study Parameters
Multiple input streams — primary interviews with mill operations directors, pulp procurement managers, and commercial printer purchasing heads; secondary validation through trade association capacity databases, customs export records, and EPA effluent compliance filings — were reconciled through bottom-up and top-down triangulation. Primary fieldwork encompassed technical discussions with coating chemical suppliers and regulatory affairs specialists at publishing houses. Secondary sources included FSC chain-of-custody certification registries, EU Ecolabel product databases, and MEE discharge compliance disclosures.
Data-stream reconciliation anchored volume and value outputs across product type, application, end user, and thickness segmentation dimensions. Modeled projections incorporated pulp cost volatility indices, regulatory enforcement timelines, and regional advertising expenditure shifts. CAGRs were derived from installed capacity utilization rates and demand elasticity parameters specific to coated and uncoated paper grades.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese dual carbon policy acceleration, REACH chemical restriction expansion, and digital substitution rates in enterprise documentation. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and fiber sourcing geography. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Cheque Paper Market
Paper Products
Compressed Fiberboard Market
Paper Products
Paper Doilies Market
Paper Products
Hardwood Pulp Market
Paper Products
Fluff Pulp Market
Paper Products
Paper Products Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Paper Pigment Market
Paper Products
Glassine Paper Market
Paper Products
Paper and Board Technologies Market
Paper Products
Wood Paper and Paperboard Recycling Market
Paper Products
Acrylic Paper Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Dissolving Pulp Market
Paper Products
GCC Stone Paper Market
Paper Products
Speciality Pulp and Paper Chemicals Market