
 Stone Paper Market | 2026-2036
Stone Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Stone Paper Market Intelligence
Project finance for calcium carbonate mining and extrusion equipment is reconfiguring competitive entry in stone paper manufacturing, lowering capital barriers for mid-scale producers. TBM Co., Ltd. leverages its integrated mineral sourcing to control raw material costs across Japanese operations. Taiwan Lung Meng Advanced Composite Materials Co., Ltd. anchors its position through proprietary blown-film extrusion expertise. Karst Stone Paper differentiates via direct-to-consumer branding in premium stationery channels.
Stone paper consists primarily of calcium carbonate powder bound with a small proportion of high-density polyethylene resin through a blown-film extrusion process, yielding a waterproof, tear-resistant substrate that replaces wood-pulp paper and synthetic films in printing and packaging applications. Packaging applications lead volume consumption due to moisture resistance requirements in food and retail logistics, while labels represent the fastest-expanding segment as brands seek barcode-compatible sustainable substrates. Writing paper occupies the premium margin pool, where A4 and A5 formats command price premiums through certified carbon-footprint claims.
The EPA regulates calcium carbonate mining discharge under Clean Water Act provisions, while REACH compliance governs PE resin additives for European market access, and China's MEE enforces dual carbon targets that favor stone paper's lower water intensity against conventional pulp. These frameworks collectively shift procurement specifications toward substrates with verified lifecycle assessments and restricted substance documentation. Stakeholders must monitor evolving extended producer responsibility schemes that could mandate recycled-content thresholds or carbon-border adjustments affecting import competitiveness.
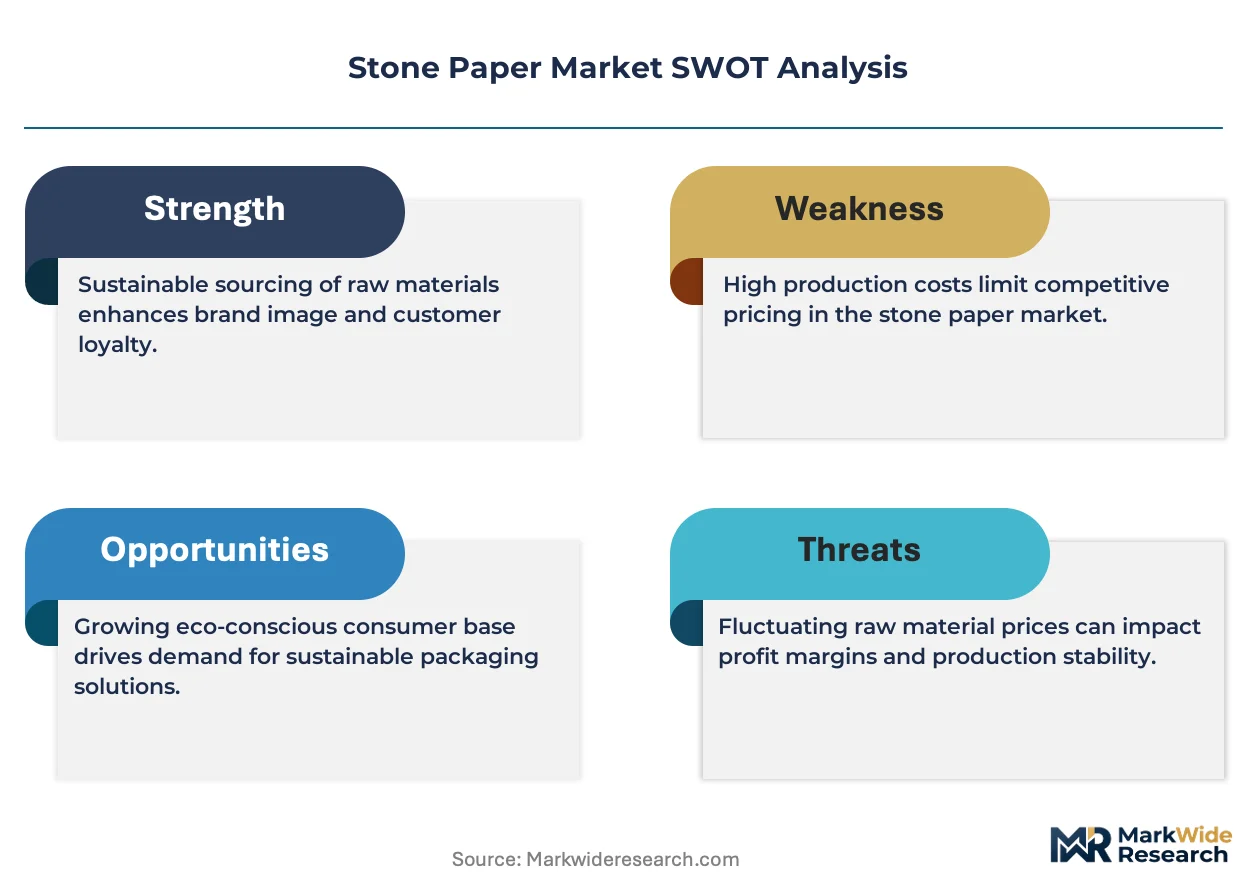
Market Dynamics
Calcium carbonate supply concentration in China's Guangdong province and REACH chemical restrictions across Germany are restructuring procurement specifications toward substrates with verified lifecycle assessments and restricted substance documentation.
Growth Catalysts
- REACH chemical restrictions:European food packaging buyers face tightened limits on conventional pulp and plastic additives, redirecting procurement toward calcium carbonate-based substrates with compliant additive profiles.
- China's dual carbon goals:MEE enforcement of water intensity targets favors stone paper's lower consumption metrics against wood-pulp alternatives in domestic manufacturing supply chains.
- Blown-film extrusion advancement:Equipment suppliers are delivering modular extrusion lines that reduce capital barriers for mid-scale producers entering packaging-grade production.
Market Restraints
- HDPE resin price volatility:Stone paper's binding polymer tracks petrochemical feedstock costs, creating margin compression when crude oil benchmarks spike.
- Mineral sourcing concentration:High-purity calcium carbonate deposits cluster in specific Chinese provinces, exposing producers to localized environmental permitting delays.
- Printing equipment incompatibility:Conventional offset presses require retrofitting for stone paper's thermal properties, slowing adoption among commercial printers with sunk capital in legacy machinery.
Strategic Opportunities
- Label segment penetration:Barcode-compatible sustainable substrates remain underdeployed in European logistics networks, creating whitespace for moisture-resistant alternatives.
- Extended producer responsibility schemes:Emerging EU mandates on recycled-content thresholds will advantage stone paper's mineral-based recyclability against synthetic films.
- Direct-to-consumer stationery channels:Premium A4 and A5 formats with certified carbon-footprint claims command price premiums in branded retail positioning.
Industry Challenges
- Blown-film extrusion technician scarcity:Specialized knowledge of mineral-polymer mixing ratios and thermal calibration remains concentrated among experienced operators in East Asian manufacturing clusters.
- Carbon footprint certification timelines:Third-party lifecycle assessment validation for water and energy claims requires 12-18 month documentation cycles, delaying market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stone Paper Market |
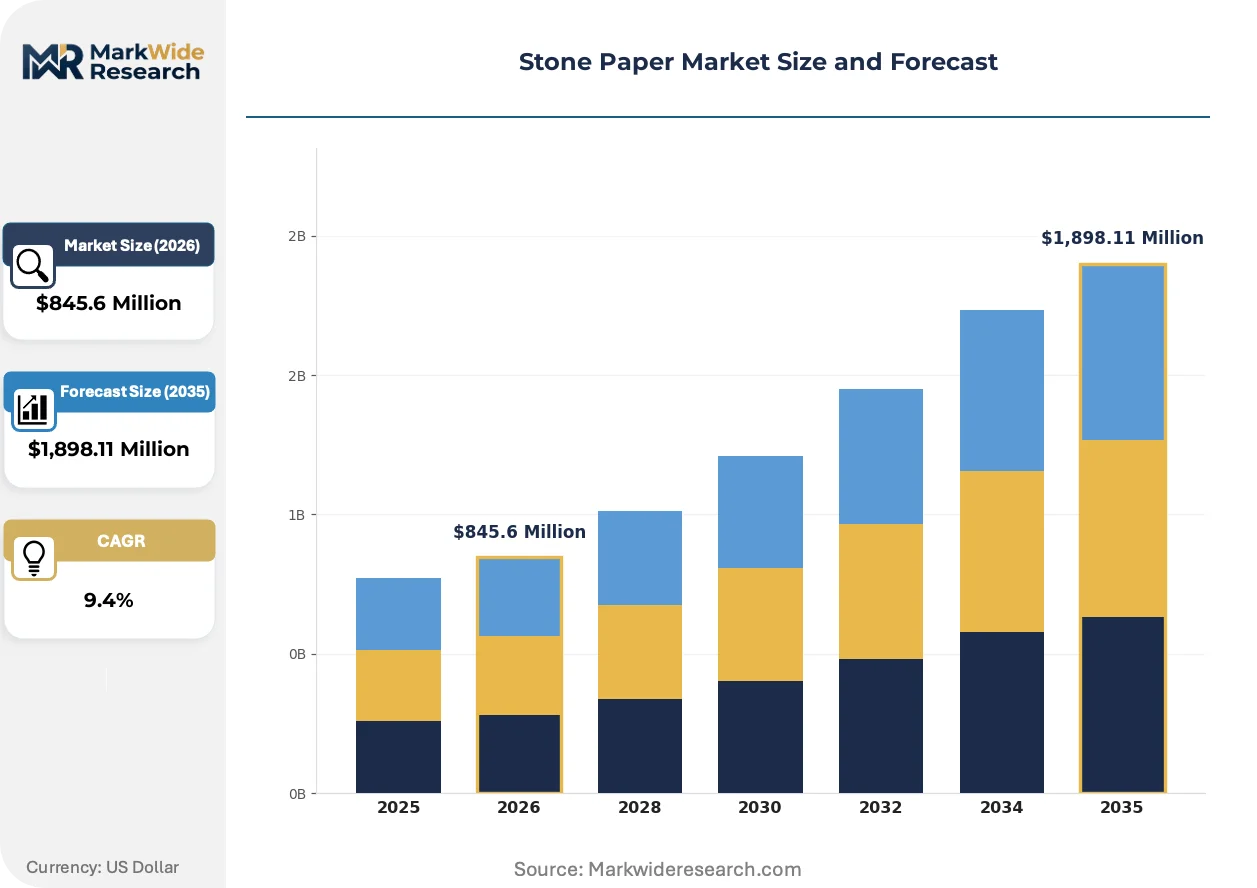
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,898.11 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Writing Paper, Packaging, Labels, Business Cards Form: A4, A5, Roll, Sheets End User: Publishing, Education, Retail, Food Packaging Technology: Coating, Printing, Laminating, Finishing |
| Companies Covered | TBM Co., Ltd., Taiwan Lung Meng Advanced Composite Materials Co., Ltd., Shenzhen Stone Paper Enterprise Ltd., Pishgaman Sanat Sabz, AM Packaging Co. Ltd., Sphera International, STP Stone Paper Products GmbH, Stone Paper Global Technologies Ltd., Karst Stone Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stone Paper Market Strategic Shifts & Innovations
Extrusion technology maturation and regulatory carbon accounting are compressing the competitive window for conventional substrates while opening premium positioning for verified alternative materials.
High-density polyethylene loading reduction in calcium carbonate matrix formulations is collapsing the cost gap between stone paper and wood-pulp grades. Japanese packaging converters are adopting these reformulated substrates for moisture-sensitive food applications at accelerating trial-to-contract conversion rates. The technology is collapsing legacy assumptions about mineral-paper printability limits.
EU Green Deal carbon-border adjustment mechanisms are reshaping import competitiveness for substrate producers. The framework penalizes embodied carbon in conventional pulp imports while exempting mineral-based alternatives with lower water intensity profiles. German retail chains are now requiring supplier documentation of cradle-to-gate emissions for private-label packaging procurement.
Certification-driven preference shifts are restructuring buyer-seller relationships in premium channels. Sustainability officers at European consumer goods firms are mandating restricted substance documentation ahead of price negotiations, displacing traditional specification-by-basis-weight procurement. This pattern concentrates among cosmetics and specialty food brands in France and Germany.
Stone Paper Market Segmentation
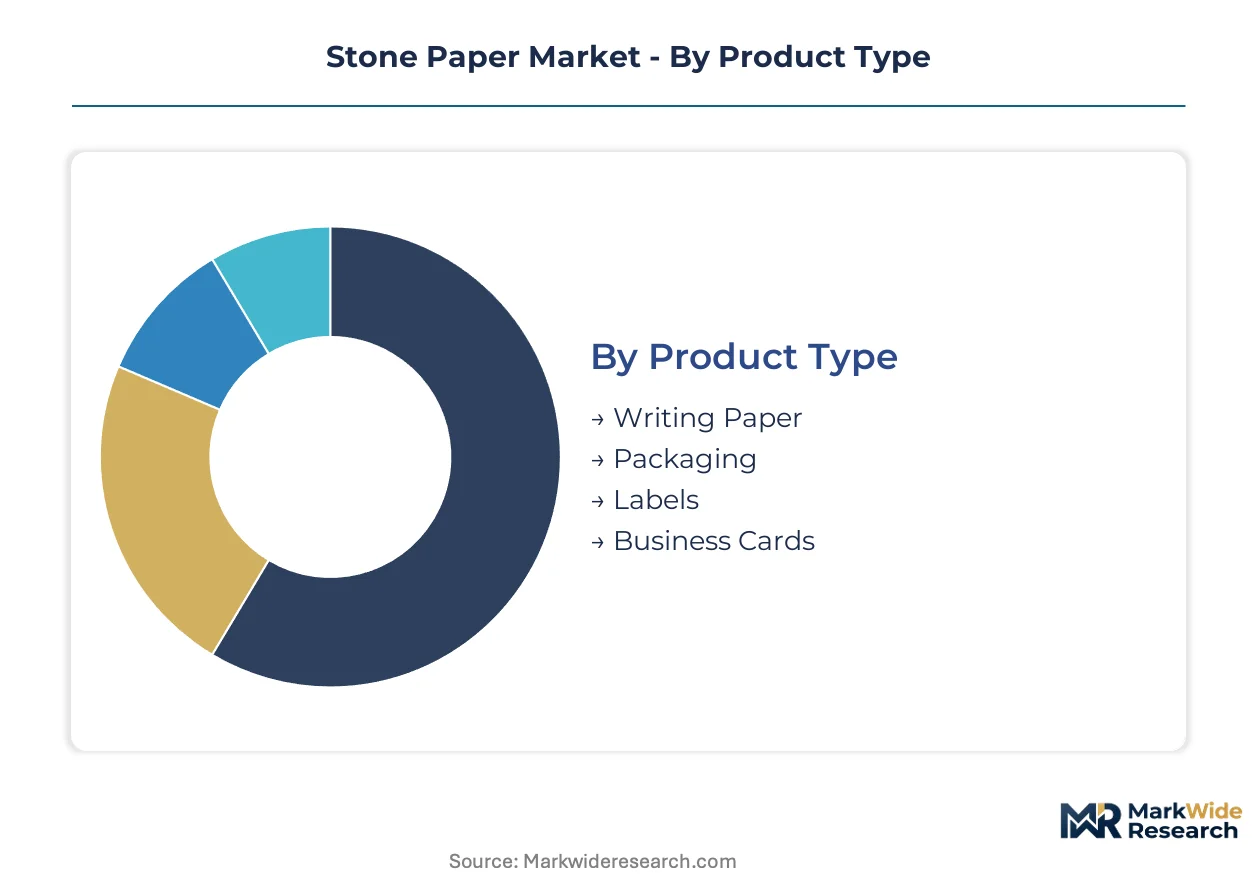
Stone paper's mineral-polymer composition creates distinct performance profiles across product formats, forcing buyers to match substrate specifications to end-use moisture resistance, printability, and folding requirements. Segmentation reveals how calcium carbonate loading ratios and HDPE binder percentages shift competitive positioning across writing, packaging, and label applications.
Product Type:
Writing paper and packaging dominate commercial volumes, while labels and business cards occupy specialized niches where moisture resistance or tactile premiumization commands price premiums.
- Writing Paper:High calcium carbonate content (80-85%) bound with minimal HDPE resin yields a smooth, fountain-pen-compatible surface. A4 and A5 formats with certified carbon-footprint claims concentrate demand among German and French corporate procurement officers under EU Green Deal supplier mandates.
- Packaging:Thicker gauge formulations with enhanced tear resistance serve moisture-sensitive food logistics. China's Guangdong manufacturing belt anchors supply for East Asian retail chains facing MEE water intensity enforcement against conventional pulp alternatives.
- Labels:Barcode-compatible stone paper substrates with thermal transfer printability address logistics sector sustainability mandates.
- Business Cards:Premium tactile grades with elevated density and rigidity differentiate professional services branding in direct-to-consumer channels.
Established volume favors packaging; emerging adoption favors labels.
Form:
Format dimensions directly determine extrusion line configuration and downstream cutting equipment compatibility, creating customer lock-in effects.
- A4:Standard 210x297mm sheets command the largest production runs across European education and office supply procurement. REACH-compliant additive profiles in German-sourced grades satisfy restricted substance documentation requirements for institutional buyers.
- A5:Half-letter formats concentrate in premium stationery and notebook applications where portability drives consumer preference.
- Roll:Continuous web formats serve high-volume packaging converters with inline printing and die-cutting capabilities.
- Sheets:Custom-cut dimensions address specialty commercial printing requirements outside standard ISO formats.
Roll formats capture packaging scale economies; A4 dominates education procurement concentration.
End User:
Buyer sophistication varies sharply across sectors, with food packaging and retail demanding certified lifecycle documentation while education prioritizes unit cost.
- Publishing:Magazine and book printers evaluate stone paper for moisture-resistant outdoor editions and specialty art books.
- Education:K-12 and university procurement offices in Germany and France trial calcium carbonate notebooks under carbon reduction targets.
- Retail:Private-label packaging buyers at German retail chains now mandate cradle-to-gate emissions documentation from substrate suppliers.
- Food Packaging:Moisture resistance requirements in fresh produce and frozen goods logistics drive trial-to-contract conversion among Japanese packaging converters.
Food packaging leads technical specification intensity; education represents volume scale opportunity.
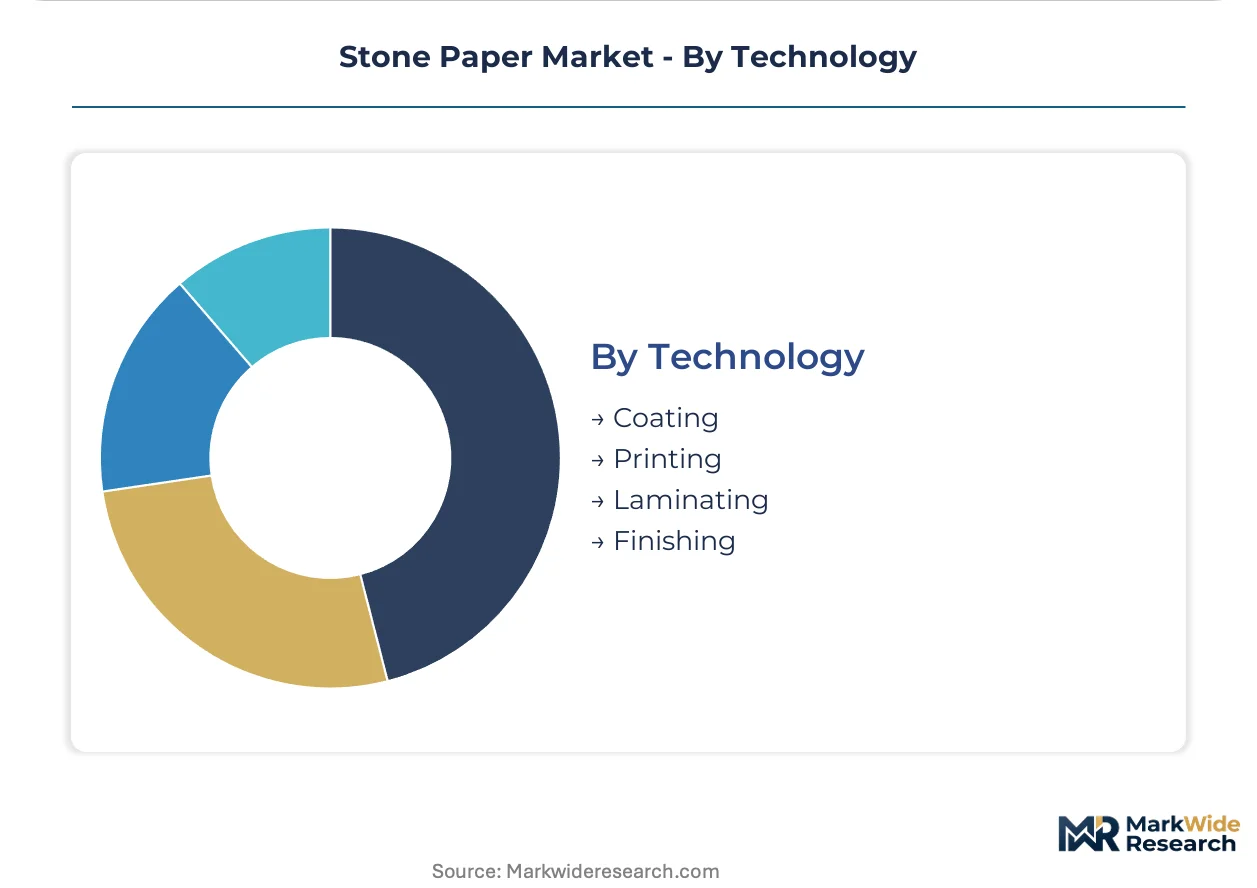
Technology:
Downstream processing compatibility determines stone paper's addressable market within existing print and packaging infrastructure.
- Coating:Surface treatment with mineral or polymer layers enhances ink adhesion and gloss control for high-end commercial applications.
- Printing:Offset, flexographic, and digital press compatibility varies by stone paper thermal properties; retrofitting requirements slow commercial printer adoption.
- Laminating:Bonding stone paper to conventional substrates or barrier films extends application range in multi-layer packaging structures.
- Finishing:Die-cutting, folding, and embossing processes require calibration for stone paper's distinct stress-strain behavior compared to wood-pulp grades.
Printing compatibility constraints limit near-term penetration; coating advancement unlocks premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon-border adjustments and China's dual carbon enforcement are redirecting procurement toward mineral-based substrates with verified lifecycle documentation. National regulators are tightening water intensity standards against conventional pulp alternatives. Industrial clusters in East Asia and Western Europe anchor extrusion capacity expansion.
China
MEE water intensity targets favor stone paper's lower consumption metrics against wood-pulp alternatives in domestic manufacturing supply chains. The dual carbon goals framework penalizes embodied carbon in conventional imports while exempting mineral-based alternatives. Guangdong province's manufacturing belt anchors regional supply, with Shenzhen Stone Paper Enterprise Ltd. concentrating blown-film extrusion expertise.
Germany
REACH chemical restrictions tighten limits on conventional pulp and plastic additives in food packaging procurement. ECHA enforcement mandates restricted substance documentation ahead of price negotiations for institutional buyers. Retail chains in North Rhine-Westphalia now require cradle-to-gate emissions documentation for private-label packaging sourcing.
Japan
METI industrial efficiency standards accelerate trial-to-contract conversion for moisture-sensitive food packaging applications. National carbon accounting frameworks advantage substrates with lower water intensity profiles against conventional alternatives. Packaging converters in the Kanto region adopt reformulated calcium carbonate substrates at accelerating rates.
United States
EPA Clean Water Act provisions regulate calcium carbonate mining discharge, shaping raw material access for domestic producers. California's extended producer responsibility schemes advance recycled-content thresholds that favor mineral-based recyclability. West Coast logistics networks trial barcode-compatible sustainable substrates for moisture-resistant label applications.
Taiwan
Industrial technology upgrading programs support proprietary blown-film extrusion expertise development among materials specialists. National innovation incentives target mineral-polymer mixing ratio optimization for packaging-grade production. Manufacturing clusters in Taichung anchor regional supply for East Asian retail chain procurement.
Stone Paper Market Key Industry Players
On the supply side, the industry is consolidating around integrated mineral sourcing and proprietary extrusion expertise. Mid-scale producers face capital barriers from modular equipment requirements, while established players leverage backward integration into calcium carbonate deposits. Three archetypes dominate: integrated mineral-polymer compounders, blown-film extrusion specialists, and direct-to-consumer brand builders. Competitive moves concentrate on capacity expansion in Guangdong and technology licensing agreements for REACH-compliant additive formulations.
Among East Asian integrated compounders, TBM Co., Ltd. and Taiwan Lung Meng Advanced Composite Materials Co., Ltd. exemplify the mineral-sourcing-to-extrusion archetype, while Shenzhen Stone Paper Enterprise Ltd. anchors Guangdong-based supply concentration. STP Stone Paper Products GmbH represents European market access specialization, and Karst Stone Paper occupies premium stationery positioning. These five entities illustrate the geographic and strategic segmentation structuring competitive rivalry.
| Leading Market Players |
|---|
| TBM Co., Ltd. |
| Taiwan Lung Meng Advanced Composite Materials Co., Ltd. |
| Shenzhen Stone Paper Enterprise Ltd. |
| Pishgaman Sanat Sabz |
| AM Packaging Co. Ltd. |
| Sphera International |
| STP Stone Paper Products GmbH |
| Stone Paper Global Technologies Ltd. |
| Karst Stone Paper |
| Others |
Cost & Logistics Intelligence
Overcapacity signals in China's Guangdong extrusion corridor are compressing spot pricing for standard-grade stone paper while tightening margins for non-integrated producers, forcing procurement officers to renegotiate contract terms around mineral sourcing transparency and REACH-compliant additive documentation.
Pricing Analysis
Certification level creates the primary spread across stone paper tiers, with cradle-to-gate emissions documentation commanding premiums from German retail chains while uncertified commodity grades face price erosion. Three-tier pricing structure across premium, standard, and economy levels tracks calcium carbonate purity and HDPE loading ratios. Cost compression in standard grades is intensifying because modular extrusion equipment is lowering entry barriers for mid-scale Chinese producers. Education procurement offices exhibit highest price sensitivity, while cosmetics and specialty food brands in France prioritize certified carbon-footprint claims over unit cost.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for stone paper distributors serving REACH-regulated markets. High-purity calcium carbonate deposits concentrate in China's Guangdong and Fujian provinces, with secondary sourcing from Vietnam's emerging mineral processing zones. HDPE resin feedstocks draw from South Korean and Saudi Arabian petrochemical complexes, creating margin volatility when crude benchmarks spike. Single-source vulnerability clusters around blown-film extrusion technician pools in East Asian manufacturing hubs. Distribution runs through regional packaging converters with inline printing capabilities, bypassing traditional paper merchant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized knowledge of mineral-polymer mixing ratios and thermal calibration remains trapped within experienced operator cohorts in East Asia, creating a bottleneck that constrains capacity expansion regardless of capital availability.
For Market Incumbents: Harden supply security through captive calcium carbonate deposits in Guangdong or Fujian provinces to offset MEE environmental permitting delays that disrupt competitor raw material access. Deepen backward integration into HDPE compounding operations to buffer margin compression from petrochemical feedstock volatility. Prioritize certification investment for cradle-to-gate emissions documentation to defend premium positioning against emerging modular extrusion entrants. For New Entrants and Emerging Players: Mid-market packaging converters in Southeast Asia represent the most penetrable entry point, where moisture-resistance requirements for tropical logistics outstrip local stone paper supply. European label applications for barcode-compatible sustainable substrates offer second-mover advantages as logistics sector sustainability mandates tighten. Pursue technology licensing agreements with established East Asian extrusion specialists rather than greenfield capability development. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular blown-film extrusion equipment, compressing the returns window for scale-focused greenfield investments. Target acquisition archetypes include distressed mid-scale producers with validated REACH-compliant additive formulations but underutilized capacity. Watch for inflection signals in HDPE resin price volatility indices, which trigger margin stress that forces asset sales from non-integrated operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Sourcing | Captive calcium carbonate deposits in Guangdong insulate producers from MEE permitting delays affecting regional competitors. |
| REACH-Compliant Additive Certification | Validated restricted substance documentation unlocks German and French food packaging procurement under ECHA enforcement. |
| Modular Extrusion Capacity Expansion | Equipment suppliers delivering standardized lines lower capital barriers for mid-scale entrants in packaging-grade production. |
| Direct-to-Consumer Stationery Launch | Premium A4 and A5 formats with certified carbon-footprint claims capture margin pools in branded retail channels. |
| Technology Licensing Partnership | Knowledge transfer agreements concentrate proprietary blown-film expertise among East Asian manufacturing clusters. |
Research Approach
A spread of perspectives from blown-film extrusion engineers, calcium carbonate procurement managers at packaging converters, REACH compliance officers, and retail sustainability directors converged on the working assumptions. Primary interviews with equipment suppliers and mineral processing operators were cross-referenced against customs trade data, MEE water intensity enforcement records, SEC filings from petrochemical feedstock providers, and ECHA restricted substance documentation databases. Bottom-up capacity assessments across Guangdong manufacturing clusters were triangulated with top-down demand modeling from European retail chain procurement disclosures.
Demand-supply balance dynamics across calcium carbonate deposits, HDPE resin availability, and extrusion line utilization rates anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, form factor, end-use application, and technology compatibility tier. CAGRs were derived from capacity expansion pipelines and procurement specification shifts across the analysis window. Industry-specific forecast inputs incorporated MEE dual carbon enforcement trajectories and EU Green Deal carbon-border adjustment implementation patterns.
Stress conditions across HDPE price volatility bands, MEE permitting delay scenarios, and REACH additive restriction timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding extrusion technology maturation and regulatory carbon accounting adoption rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
North America Specialty Paper Market
Paper Products
Asia-Pacific Thermal Paper Market
Paper Products
Paper Glass Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Global Molded Pulp Products Market
Paper Products
Printing and Writing Papers Market
Paper Products
Dissolving Pulp Market
Paper Products
Sawn Wood Market
Paper Products
Overlay Paper Market
Paper Products
Printing Paper Market
Paper Products
White Top Testliner Market
Paper Products
Filtration Paper Market
Paper Products
Greaseproof Paper Sheets Market
Paper Products
Paper Machinery Market
Paper Products
GCC Stone Paper Market
Paper Products
Paper Based Laminates Market