
 Hardwood Pulp Market | 2026-2036
Hardwood Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Hardwood Pulp Market Outlook
Indonesia is rewriting regional supply dynamics through major hardwood pulp capacity expansions. APRIL Group leverages integrated plantation-to-mill operations across Riau Province. Suzano sustains its dominance in South American eucalyptus pulp through proprietary clonal forestry programs. Metsä Fibre anchors Nordic birch pulp output with advanced biorefinery co-product streams.
Hardwood pulp consists primarily of short-fiber cellulose derived from deciduous tree species such as eucalyptus, birch, and acacia, typically processed via the kraft method to achieve lignin content below 2% for premium printing and hygiene applications. Its commercial purpose centers on providing superior formation uniformity, opacity, and softness in tissue, coated paper, and dissolving-grade applications where long-fiber softwood pulp alone performs inadequately. Bleached kraft pulp occupies the largest value pool given its ubiquity in graphic paper and tissue manufacturing, while dissolving pulp represents the fastest-expanding category as viscose staple fiber producers convert textile feedstocks away from cotton. Specialty pulp commands disproportionate margins due to narrow certification requirements and limited qualified supply.
EPA effluent guidelines constrain US mill discharge parameters, while EU Ecodesign and REACH frameworks govern chemical inputs and product recyclability claims across European value chains. China's MEE enforces wastewater and air emission standards that reshape operating costs for imported hardwood pulp versus domestic production. Stakeholders must monitor how carbon border adjustment mechanisms and evolving forest certification schemes restructure procurement geography and mill investment returns.
Market Dynamics
Hardwood pulp supply chains are tightening around plantation-controlled fiber security, as Indonesian and Brazilian producers consolidate upstream timber assets while European and North American mills face escalating carbon compliance costs that reshape competitive positioning.
Growth Catalysts
- EU Ecodesign standards:Mandatory product recyclability claims drive certified fiber demand across European tissue and packaging converters, tightening specifications for bleached kraft grades.
- Viscose staple fiber producers:Textile manufacturers in Bangladesh and Turkey accelerate dissolving pulp offtake as cotton substitution accelerates, pulling hardwood cellulose into apparel supply chains.
- Integrated plantation-to-mill operations:Riau Province and Mato Grosso do Sul concentrate new capacity with captive acacia and eucalyptus supply, compressing delivered fiber costs below spot-market dependent competitors.
Market Restraints
- Energy cost volatility:Natural gas and black liquor pricing swings compress kraft mill operating margins, particularly for European producers without biomass co-generation assets.
- Supply concentration in Southeast Asia:Indonesian producers control roughly one-third of incremental hardwood pulp capacity additions, creating single-source vulnerability for Japanese and South Korean buyers.
- Softwood pulp substitution:Northern bleached softwood kraft from Scandinavian and Canadian mills competes for premium tissue applications where fiber length specifications permit blending flexibility.
Strategic Opportunities
- India's packaging board expansion:Domestic folding carton and liquid packaging investments outpace local pulp supply, creating import dependency for hardwood grades with FSC certification.
- Biorefinery co-product streams:Tall oil and lignin valorization from Nordic birch pulp operations generates ancillary revenue streams that subsidize commodity pulp production.
- China's dual carbon goals:MEE wastewater and air emission enforcement raises operating costs for domestic mills, improving landed cost competitiveness for imported Indonesian and Brazilian hardwood pulp.
Industry Challenges
- Clonal forestry expertise scarcity:Eucalyptus productivity gains depend on proprietary germplasm management capabilities concentrated among Brazilian and Australian research programs, limiting technology transfer to new entrants.
- PEFC and FSC certification timelines:Chain-of-custody audits for plantation-origin pulp require 18-24 month implementation cycles, delaying market access for greenfield Indonesian mills serving European buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hardwood Pulp Market |
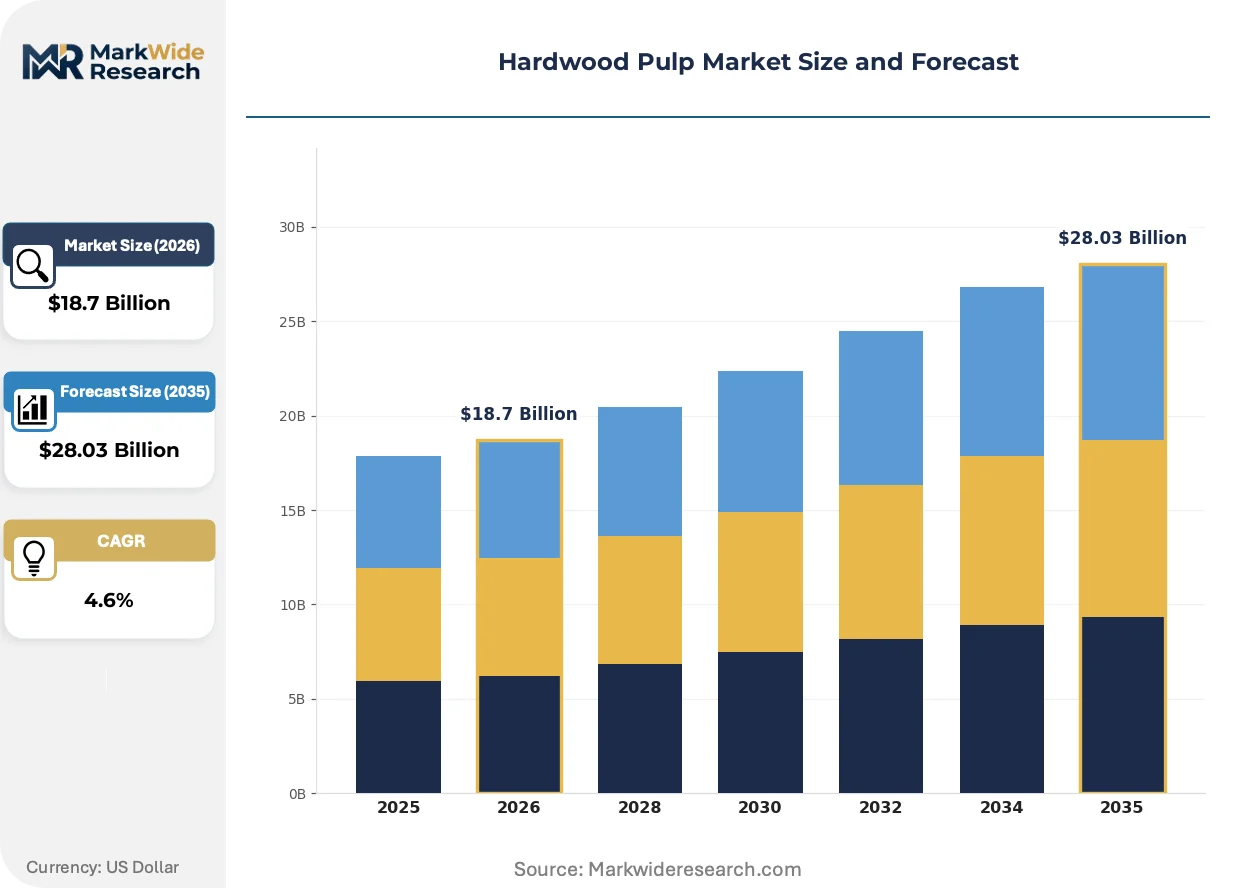
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bleached Kraft Pulp, Unbleached Kraft Pulp, Dissolving Pulp, Specialty Pulp End Use: Paper Production, Textile Industry, Packaging Materials, Non-Wovens Grade: High-Quality, Standard-Quality, Industrial-Grade, Specialty-Grade Distribution Channel: Direct Sales, Distributors, E-Commerce, Retailers |
| Companies Covered | Sappi, APRIL Group, Suzano, Cenibra, Metsä Fibre, Stora Enso, Domtar, CMPC, UPM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hardwood Pulp Market Strategic Shifts
Hardwood pulp processing is hybridizing with adjacent biorefinery technologies, as kraft mills diversify revenue beyond commodity cellulose into extractives, biochemicals, and textile-grade dissolving streams.
Continuous digester technology is hybridizing with oxygen delignification stages to reduce chlorine dioxide consumption in bleached kraft sequences. Finnish and Swedish equipment suppliers deploy these integrated systems across Iberian and Latin American mill expansions. The technology is compressing chemical input costs while enabling compliance with EU REACH restrictions on adsorbable organic halogen discharge.
China's MEE enforcement of GB standards for wastewater COD and particulate emissions is forcing coastal kraft mills to retrofit recovery boiler electrostatic precipitators and secondary effluent treatment. Domestic hardwood pulp production costs are rising relative to imported alternatives. Indonesian suppliers with integrated plantation operations capture displaced volume in East Asian tissue and packaging markets.
Textile brand sustainability commitments are reshaping dissolving pulp procurement specifications. H&M, Inditex, and Zara parent companies mandate CanopyStyle audit compliance for viscose supply chains, filtering hardwood pulp purchases toward producers with verified deforestation-free fiber sourcing. Bangladeshi and Turkish fiber producers now require documentation of plantation origin and conservation set-asides, compressing spot-market sales of uncertified Indonesian and Brazilian grades.
Hardwood Pulp Market Segmentation
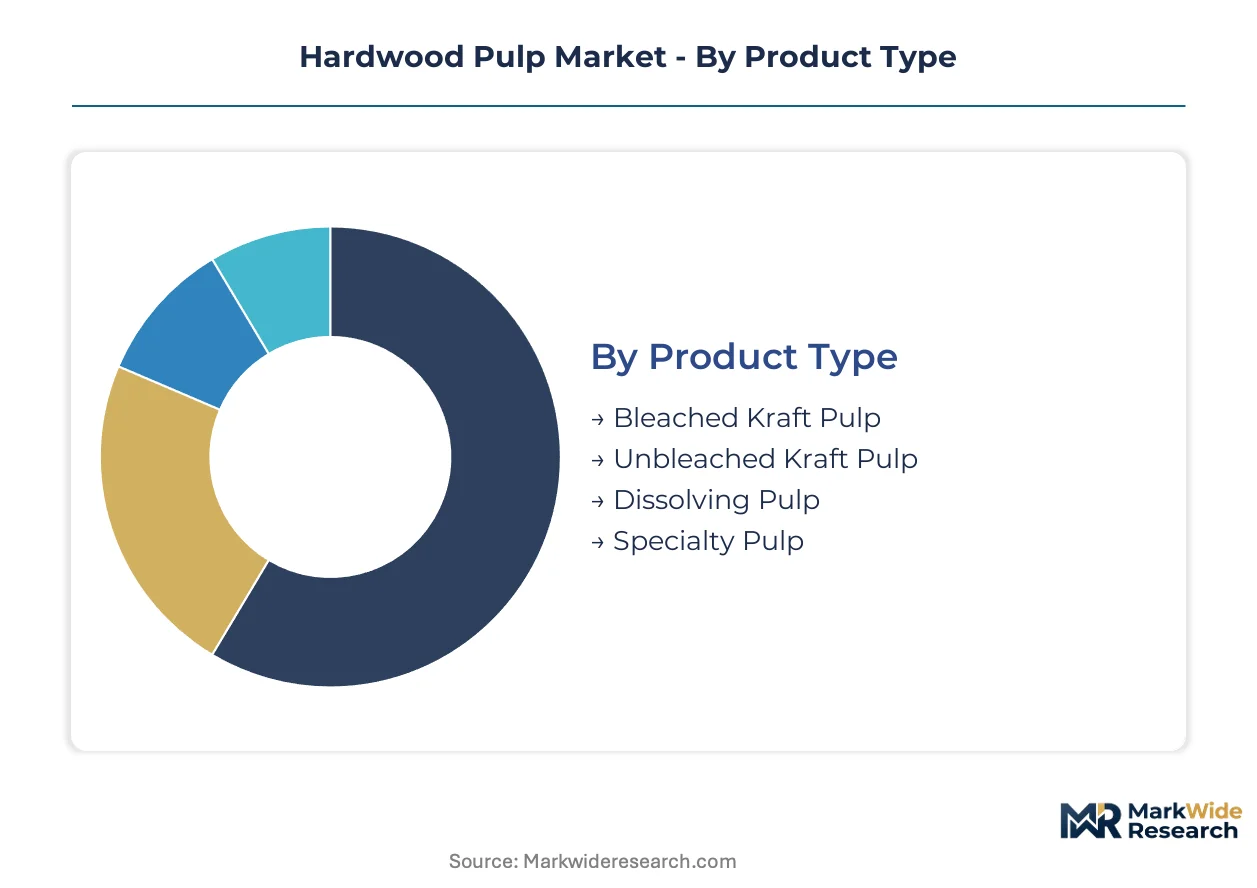
Hardwood pulp segmentation reveals divergent margin structures across product chemistry and end-use specifications. Each dimension carries distinct procurement patterns, certification requirements, and geographic concentration that reshape competitive positioning.
Product Type:
Mature kraft grades dominate volume flows while emerging dissolving streams capture textile substitution demand.
- Bleached Kraft Pulp:Refined cellulose processed through multi-stage bleaching achieves lignin content below 2%, delivering superior brightness and formation uniformity for coated paper and premium tissue. European tissue converters in Germany and France drive certified fiber procurement under EU Ecodesign recyclability mandates.
- Dissolving Pulp:High-alpha cellulose exceeding 92% purity serves as feedstock for viscose staple fiber production, replacing cotton in fast-fashion supply chains. Bangladeshi and Turkish textile manufacturers accelerate offtake as H&M and Inditex parent companies enforce CanopyStyle audit compliance.
- Unbleached Kraft Pulp:Retains natural lignin content for packaging applications requiring structural rigidity rather than brightness.
- Specialty Pulp:Narrow specification grades command disproportionate margins through limited qualified supply and extended certification timelines.
Bleached kraft pulp retains volume leadership; dissolving pulp holds the steepest expansion curve.
End Use:
Application diversity spans commodity packaging through high-specification textile feedstocks with divergent price elasticity profiles.
- Paper Production:Coated woodfree and uncoated grades consume the majority of bleached hardwood fiber, with Japanese and South Korean mills blending eucalyptus and birch for opacity and printability. EU REACH frameworks on adsorbable organic halogen discharge tighten bleaching sequence specifications.
- Textile Industry:Viscose staple fiber producers convert dissolving pulp into apparel feedstock as cotton price volatility and water scarcity reshape agricultural textile economics. Indonesian suppliers with integrated plantation operations capture displaced volume from Chinese domestic mill closures.
- Packaging Materials:Folding carton and liquid packaging board applications favor hardwood fiber for surface smoothness and print receptivity.
- Non-Wovens:Hygiene product manufacturers specify short-fiber cellulose for softness and liquid acquisition performance in diaper and feminine care applications.
Paper production retains volume leadership; textile industry applications hold the steepest expansion curve.
Grade:
Quality stratification aligns with end-use performance requirements and certification stringency tiers.
- High-Quality:Premium brightness and cleanliness specifications serve pharmaceutical and food-contact applications with zero-defect tolerance. Nordic birch pulp from Finnish biorefinery operations anchors this tier through advanced extractives recovery and lignin valorization co-product streams.
- Specialty-Grade:Custom-engineered fiber properties including controlled hemicellulose retention and tailored viscosity profiles address narrow technical specifications in filtration and specialty paper.
- Standard-Quality:General-purpose brightness and strength properties satisfy mainstream graphic paper and tissue applications.
- Industrial-Grade:Lower brightness tolerance accepts higher shive content for corrugated medium and construction board applications.
Standard-quality grades retain volume leadership; specialty-grade segments hold the steepest expansion curve.
Distribution Channel:
Channel selection reflects order scale, certification documentation requirements, and geographic proximity to integrated mill operations.
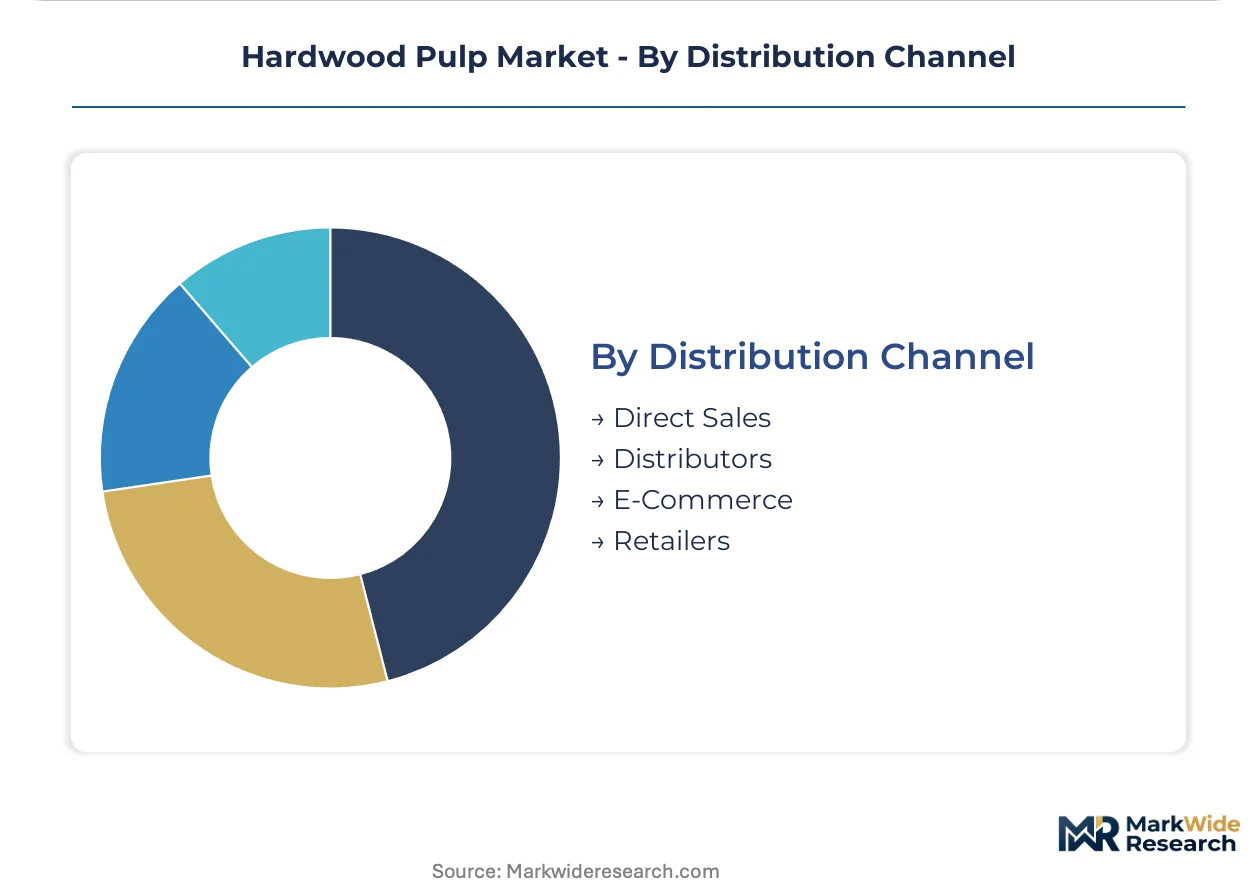
- Direct Sales:Long-term offtake agreements between Indonesian and Brazilian producers and Japanese or South Korean tissue mills secure volume commitments with FSC and PEFC chain-of-custody documentation. Suzano and APRIL Group leverage direct relationships to compress spot market exposure.
- Distributors:Regional inventory positioning serves mid-scale European converters requiring smaller lot sizes and blended grade procurement.
- E-Commerce:Digital platforms facilitate spot transactions for uncertified grades with limited documentation requirements.
- Retailers:Consumer-facing channels supply craft and artisanal paper segments with packaged specialty pulp products.
Direct sales retains volume leadership; distributor channels hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardwood pulp capacity additions cluster in Indonesia and Brazil, where integrated plantation-to-mill operations compress delivered fiber costs below spot-market dependent competitors. Chinese import dependency deepens as domestic mills face escalating MEE compliance burdens. European tissue converters accelerate certified fiber procurement under tightening EU Ecodesign recyclability mandates.
Indonesia
Riau Province anchors Southeast Asia's hardwood pulp expansion through captive acacia plantations feeding integrated kraft mills. The Ministry of Environment and Forestry enforces sustainable forest management certification timelines that extend 18-24 months for new market entrants. APRIL Group's operations across Sumatra exemplify the plantation-controlled fiber security model reshaping regional supply dynamics.
Brazil
Mato Grosso do Sul concentrates eucalyptus pulp investments serving viscose staple fiber producers in Bangladesh and Turkey. IBAMA licensing requirements govern plantation expansion into Cerrado biomes, constraining annual hectare development rates. Suzano's proprietary clonal forestry programs in the region sustain productivity advantages that limit technology transfer to rival producers.
China
Shandong and Jiangsu provinces host coastal kraft mills retrofitting recovery boilers to meet GB wastewater and particulate emission standards. MEE enforcement raises operating costs for domestic hardwood pulp production versus imported Indonesian alternatives. Qingdao and Ningbo port clusters increasingly function as distribution hubs for certified bleached kraft grades serving tissue converters.
Finland
Kemi and Äänekoski biorefinery complexes anchor Nordic birch pulp output with integrated tall oil and lignin valorization streams. EU REACH restrictions on adsorbable organic halogen discharge compress chemical input tolerances for bleaching sequences. Metsä Fibre's operations exemplify the ancillary revenue model subsidizing commodity cellulose production through extractives recovery.
United States
Southeastern pulp mills in Georgia and Alabama blend hardwood fiber for tissue and packaging applications requiring formation uniformity. EPA effluent guidelines constrain discharge parameters for kraft operations, particularly regarding color and biochemical oxygen demand. The region's integrated paperboard converters increasingly specify FSC-certified fiber for folding carton and liquid packaging board end uses.
Hardwood Pulp Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in plantation management and pulping technology. The hardwood pulp sector structures around three archetypes: integrated plantation-to-mill operators controlling captive fiber supply, Nordic biorefinery players monetizing co-product streams, and merchant market suppliers dependent on spot pulp sales. Consolidation pressures intensify as carbon compliance costs reshape European and North American mill economics. Dominant competitive moves include backward integration into plantation assets and strategic partnerships with textile brand sustainability programs.
Among integrated plantation operators, APRIL Group and Suzano exemplify the captive fiber security model compressing delivered costs below spot-market competitors. Metsä Fibre anchors the Nordic biorefinery archetype through advanced extractives recovery operations. These three entities occupy positions across the value chain spectrum from upstream timber control through downstream specialty pulp specification.
| Leading Market Players |
|---|
| Sappi |
| APRIL Group |
| Suzano |
| Cenibra |
| Metsä Fibre |
| Stora Enso |
| Domtar |
| CMPC |
| UPM |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam container corridor anchors cost dynamics across the hardwood pulp trade, with freight rate volatility compressing margins for European tissue converters while Indonesian plantation operators leverage captive fiber supply to sustain price differentiation against spot-market dependent competitors.
Pricing Analysis
EU Ecodesign standards dictate the pricing tier structure across bleached kraft and dissolving pulp grades. Three-tier pricing stratifies across premium certified, standard compliance, and economy uncertified levels, with FSC and PEFC chain-of-custody documentation commanding substantial premiums from German and French tissue converters. Price differentiation rests on certification grade and volume scale, with long-term offtake agreements securing 15-20% discounts below spot indices. Cost compression in standard grades is intensifying because MEE enforcement in China raises domestic mill operating costs against imported Indonesian alternatives. Merchant buyers in Japan and South Korea exhibit highest price sensitivity, while specialty-grade pharmaceutical and food-contact purchasers demonstrate inelastic demand.
Supply Chain Analysis
Single-source vulnerability from Indonesian production concentration dominates supply chain risk assessment for East Asian buyers. Geographic supply concentrates in Indonesia, Brazil, and Finland, with Riau Province and Mato Grosso do Sul anchoring incremental capacity additions. Raw material dependencies center on acacia and eucalyptus plantation fiber, chlorine dioxide for bleaching sequences, and natural gas for lime kiln operations. Distribution runs through direct mill-to-converter relationships for large-scale tissue and packaging manufacturers, while regional distributors serve mid-scale European converters requiring smaller lot sizes and blended grade procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hardwood pulp market is approaching a platform-economics inflection as textile brand sustainability programs interoperate with plantation certification databases, creating network effects that reward early movers with verified deforestation-free fiber sourcing.
For Market Incumbents: Build certification moats through accelerated FSC and PEFC chain-of-custody investments ahead of EU Ecodesign enforcement timelines. Suzano and APRIL Group should deepen backward integration into clonal forestry R&D to defend against emerging plantation operators in Cambodia and Laos. Priority levers include captive acacia supply security and CanopyStyle audit pre-certification for viscose staple fiber supply chains. For New Entrants and Emerging Players: India's packaging board expansion represents the most penetrable entry point, with domestic folding carton and liquid packaging investments outrunning local pulp supply and creating import dependency for certified hardwood grades. Secondary white-space targets include biorefinery co-product valorization in Nordic markets where tall oil and lignin recovery subsidizes commodity production. Go-to-market positioning should emphasize FSC-certified direct sales relationships with mid-scale European converters bypassing distributor markups. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated plantation-to-mill operators with proprietary germplasm management capabilities. Long-term viability across the projection horizon hinges on carbon border adjustment resilience and textile supply chain sustainability verification. Acquisition targets should display integrated plantation control, dissolving pulp fractionation expertise, or advanced biorefinery co-product streams. The signal to watch is CanopyStyle audit compliance rates among Indonesian suppliers as a proxy for premium market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive acacia and eucalyptus supply in Riau Province compresses delivered fiber costs below spot-market competitors. |
| Dissolving Pulp Capacity Expansion | High-alpha cellulose investments in Mato Grosso do Sul capture viscose staple fiber demand from Bangladeshi textile manufacturers. |
| Biorefinery Co-Product Valorization | Tall oil and lignin recovery from Nordic birch operations generates ancillary revenue subsidizing commodity pulp production. |
| Certification Pre-Investment | Accelerated FSC chain-of-custody implementation secures EU Ecodesign-compliant market access before 18-24 month audit timelines. |
| Long-Term Offtake Agreements | Direct mill relationships with Japanese tissue converters reduce spot market exposure and stabilize revenue visibility. |
Study Parameters
A standing panel of kraft mill operations directors, tissue converter procurement managers, textile fiber sourcing leads, and plantation forestry technical officers provided ongoing calibration across primary fieldwork and secondary validation. Secondary sources included customs and trade flow databases, FSC and PEFC certification registries, EPA effluent guideline filings, and EU Ecodesign directive implementation reports. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic and end-use consumption projections.
Scenario bracketing around energy cost volatility, carbon border adjustment implementation, and textile substitution rates framed the analytical approach across the projection horizon. Segmentation dimensions modeled included product chemistry tier, end-use application, grade specification, and distribution channel structure. CAGRs derived from fitted growth curves applied to disclosed capacity additions and demand elasticity estimates for dissolving pulp and packaging board applications.
Macroeconomic conditions sit as an overlay; deviation in energy prices, freight rates, or cotton-agriculture economics would shift the trajectory for dissolving pulp substitution demand and regional competitiveness. Forecasts reflect documented assumptions on MEE enforcement intensity, EU Ecodesign timeline adherence, and clonal forestry productivity gains. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Organic Tissue Paper Market
Paper Products
Household Paper Market
Paper Products
Billing Paper Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Office Printing Papers Market
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
Overlay Paper Market
Paper Products
Inkjet Papers and Films Market
Paper Products
Duplex Paper and Board Market
Paper Products
Synthetic Paper Market
Paper Products
Digital Printing Paper Market
Paper Products
Paper Goods Market
Paper Products
Pulp and Paper Chemicals Market
Paper Products
Metallized Paper Market
Paper Products
Global Security Paper Market
Paper Products
Aramid Paper Market