
 Global Copier Paper Market | 2026-2036
Global Copier Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Copier Paper Market Analysis
Educational institutions and government procurement offices are redrawing demand patterns across the copier paper value chain. UPM-Kymmene Corporation leverages its Nordic timber base to sustain integrated pulp-to-paper operations across European distribution networks. International Paper Company anchors North American supply through massive scale manufacturing complexes serving enterprise contract accounts. Stora Enso Oyj differentiates via bioproduct mill integration, converting wood residues into energy coproducts that offset copier paper production costs.
Copier paper comprises wood pulp-derived sheets engineered to uniform grammage, brightness, and dimensional stability for high-speed mechanical reproduction. Standard 75-80 gsm weights dominate office environments, while smoother calendered finishes minimize toner adhesion defects in laser and inkjet systems. A4 dimensions command the largest volume share across European and Asian procurement contracts, though Letter format persists in North American institutional purchasing. Uncoated finishes lead in cost-sensitive educational and administrative segments, while coated variants capture margin pools in premium presentation and marketing reproduction applications.
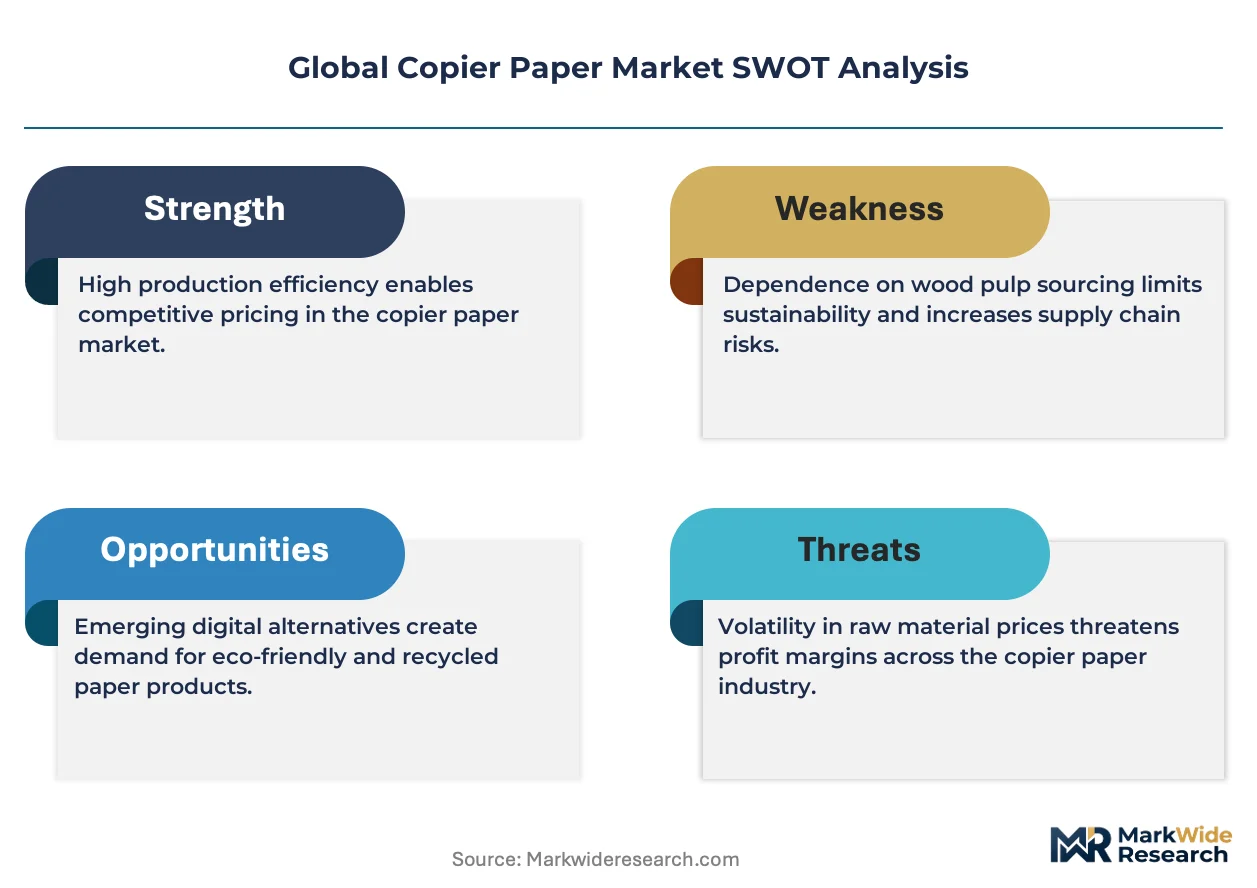
Forest Stewardship Council chain-of-custody standards, EPA emissions guidelines for pulp mill effluent, and India's BIS paper quality specifications collectively shape product compliance costs and mill siting decisions. REACH chemical restrictions in Europe limit certain bleaching agent formulations, redirecting capital toward elemental chlorine-free process investments. Stakeholders must monitor pulp fiber cost trajectories against recycled content mandates that threaten virgin fiber economics without adequate collection infrastructure scaling.
Market Dynamics
EU Green Deal forestry certification requirements are redirecting pulp sourcing toward sustainably managed supplies, compressing margins for mills dependent on uncertified fiber while rewarding integrated Nordic operators with captive timber bases.
Growth Catalysts
- Educational institutional expansion:India's government documentation mandates and school construction programs sustain physical paper procurement volumes despite surrounding digital adoption.
- REACH chemical restrictions:Europe's chlorine-free process mandates redirect capital toward elemental chlorine-free investments, creating compliance-based competitive moats for early movers.
- Hybrid workplace normalization:Corporate offices maintain bulk contract structures for in-person documentation needs even as remote workflows expand elsewhere.
Market Restraints
- Pulp fiber cost volatility:Softwood and hardwood pulp prices swing with energy costs and freight rates, compressing copier paper margins without pricing power recovery.
- Recycled content mandates:Collection infrastructure scaling lags regulatory targets in India and Europe, threatening virgin fiber economics without adequate secondary supply.
- Digital document substitution:Cloud-based workflow platforms and e-signature frameworks displace routine photocopying and printing volumes in administrative segments.
Strategic Opportunities
- Bioproduct mill integration:Wood residue-to-energy coproduction offsets copier paper manufacturing costs while meeting EU emissions guidelines for pulp mill effluent.
- Premium coated segment expansion:Marketing reproduction and presentation applications command margin pools above commodity uncoated grades.
- Forest Stewardship Council chain-of-custody certification:Procurement offices in Germany and France now require verified sustainable sourcing, creating contract eligibility barriers for uncertified competitors.
Industry Challenges
- Elemental chlorine-free process retooling:Mills face 18-24 month certification timelines and capital intensity for bleaching agent formulation changes.
- BIS paper quality specification compliance:India's national standards body enforces dimensional stability and brightness testing that delays market entry for new suppliers.
- Legacy equipment incompatibility:High-speed laser and inkjet systems demand precise calendered finishes that constrain feedstock flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Copier Paper Market |
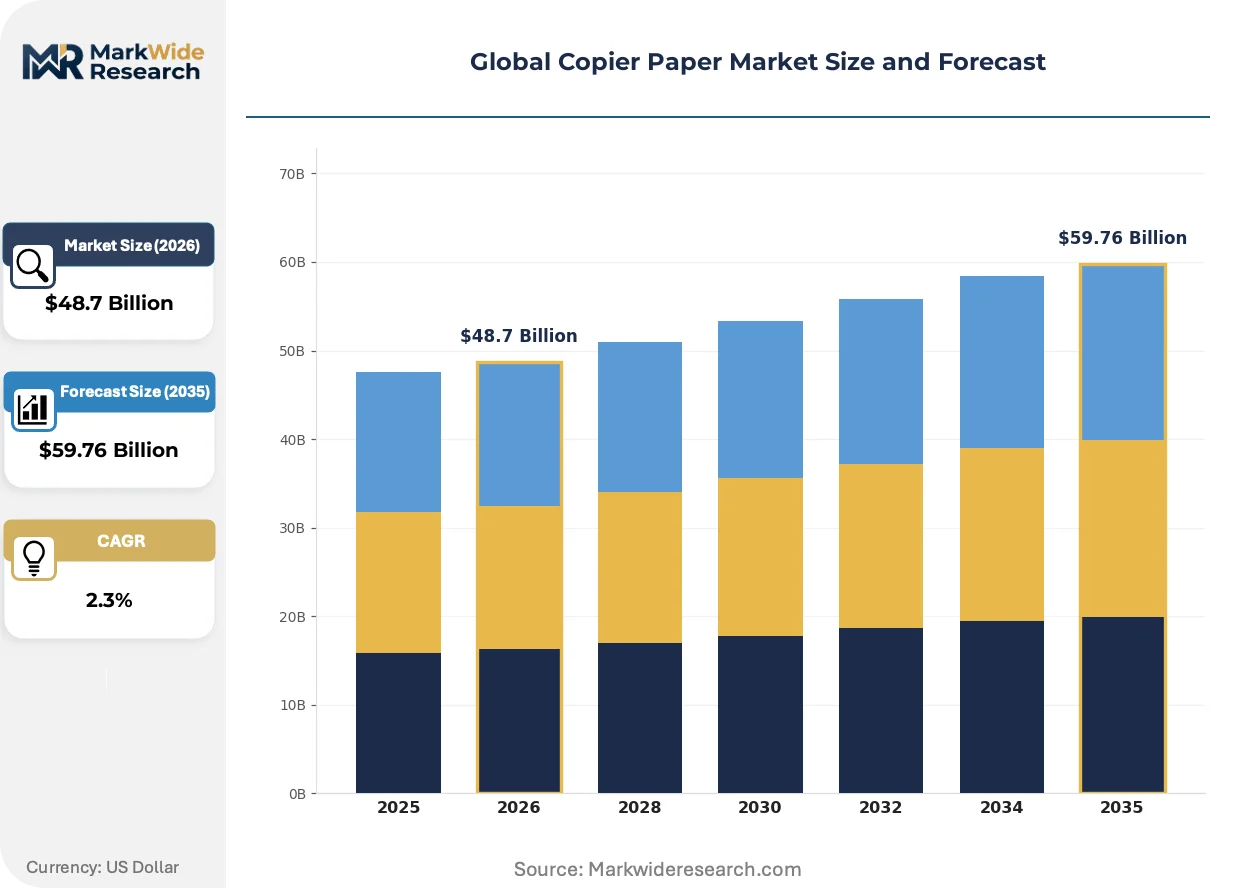
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $59.76 Billion |
| CAGR (2026 – 2036) | 2.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Paper Type: A4, A3, Letter, Legal Weight Category: Lightweight, Standard, Heavyweight, Ultra-Heavyweight Finish Type: Smooth, Textured, Coated, Uncoated Packaging Type: Reams, Boxes, Pallets, Bulk |
| Companies Covered | Asia Pulp and Paper, UPM-Kymmene Corporation, International Paper Company, Oji Holdings Corporation, Stora Enso Oyj, Sylvamo, Domtar Corporation, WestRock Company, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Copier Paper Market Emerging Trajectories
Pulp-to-paper operations are converging with energy coproduction and circular fiber recovery systems, reshaping cost structures and environmental compliance profiles simultaneously.
Near-infrared spectroscopy is supplanting manual fiber sorting in recycled pulp preparation, enabling real-time contamination detection and grade optimization. Municipal collection facilities in Japan and South Korea deploy these systems to meet rising brightness specifications for office-grade output. The technology compresses processing costs while expanding viable secondary fiber sources.
EU Green Deal forestry certification requirements now mandate chain-of-custody documentation from harvest through distribution. Mills without Nordic or Baltic captive timber supplies face sourcing complexity and audit costs. German procurement offices enforce these standards through contract eligibility clauses that exclude non-compliant suppliers.
Enterprise buyers are consolidating vendor relationships and demanding volume-tiered service agreements with embedded logistics management. Distributors respond by integrating warehouse and delivery functions, displacing traditional merchant intermediaries. This concentration is most visible in France and the Netherlands where government and corporate accounts now contract directly with mill-aligned distributors.
Global Copier Paper Market Segmentation
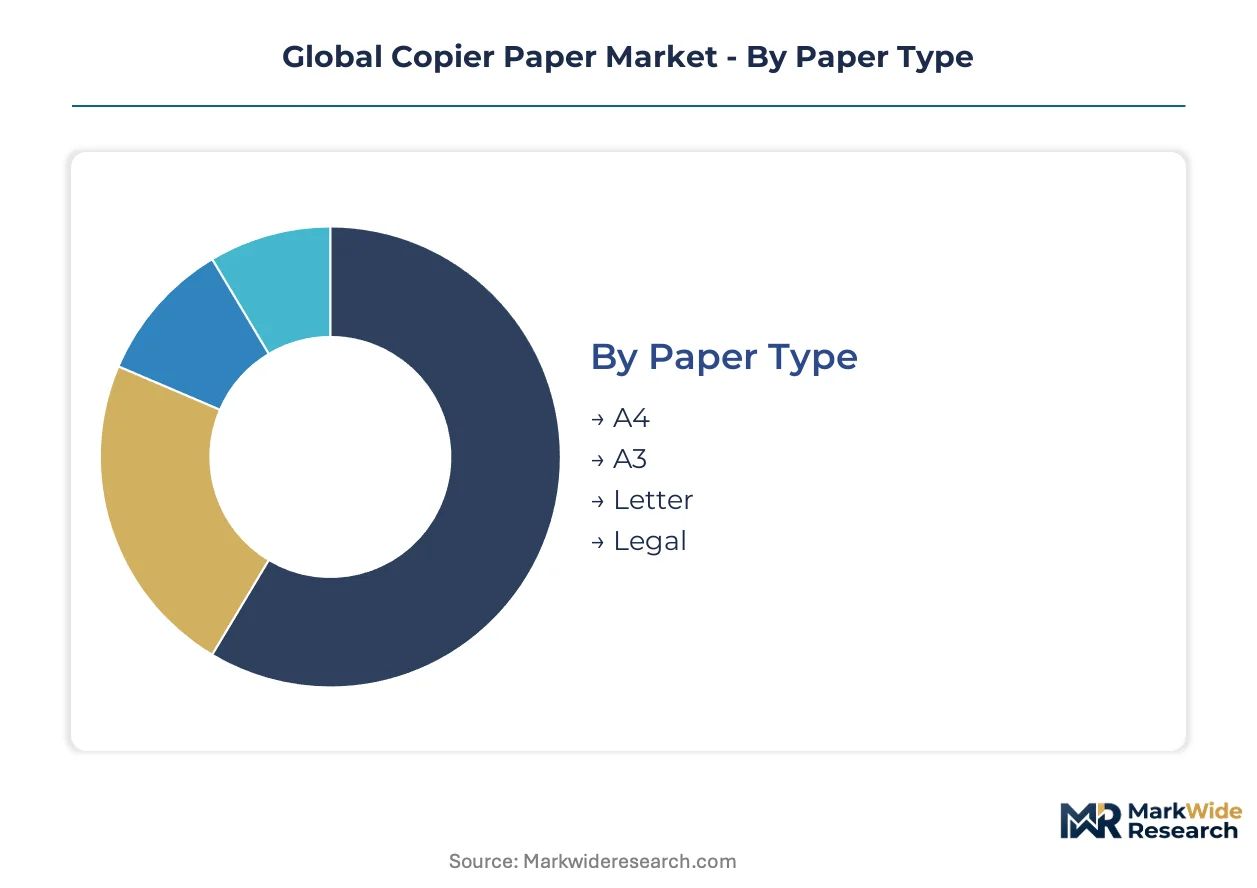
Paper specifications determine equipment compatibility and procurement contract structures across institutional buyers. Regulatory compliance costs and end-use performance requirements create divergent margin profiles within each dimensional and finish category.
Paper Type:
REACH chemical restrictions and India's BIS dimensional stability standards enforce divergent compliance burdens across format specifications.
- A4:ISO 216 standard dimensions dominate European and Asian procurement contracts. Indian government documentation mandates and educational institutional expansion sustain bulk volumes despite digital workflow adoption elsewhere.
- Letter:ANSI standard persists across North American enterprise accounts and federal procurement frameworks. US EPA emissions guidelines for pulp mill effluent shape domestic supply economics for this format.
- A3:Tabloid-equivalent dimensions serve architectural reproduction and spreadsheet applications. German procurement offices enforce EU Green Deal chain-of-custody requirements for large-format government contracts.
- Legal:Narrower elongated format retains niche demand in US legal documentation and contract filing systems. Format-specific manufacturing runs constrain mill flexibility and extend order fulfillment timelines.
Established volume favors Letter; emerging adoption favors A4.
Weight Category:
Grammage specifications determine toner adhesion performance and feed reliability in high-speed reproduction systems.
- Standard:75-80 gsm sheets balance cost efficiency with mechanical handling durability across laser and inkjet platforms. Corporate offices in France and the Netherlands maintain bulk contract structures for this specification.
- Lightweight:Sub-70 gsm grades reduce shipping costs and storage footprint for high-volume administrative applications. Japan's METI efficiency guidelines encourage procurement offices to specify reduced-weight alternatives.
- Heavyweight:90-120 gsm construction serves double-sided reproduction and report covers where stiffness prevents show-through. Premium presentation applications in marketing departments command margin pools above commodity grades.
- Ultra-Heavyweight:Exceeding 120 gsm, these grades serve certificate printing and archival documentation requiring extended durability. Limited production runs and specialized calendering equipment constrain supply availability.
Cost-sensitive procurement concentrates in Standard; premium positioning climbs fastest in Heavyweight.
Finish Type:
Surface treatment determines ink absorption rates and visual reproduction quality across output technologies.
- Smooth:Calendered surfaces minimize toner adhesion defects in laser systems and support fine-detail inkjet reproduction. South Korean municipal collection facilities deploy near-infrared spectroscopy to maintain brightness specifications for smooth-grade recycled pulp.
- Uncoated:Absorbent matte surfaces dominate cost-sensitive educational and administrative segments. India's BIS paper quality specifications enforce brightness testing that delays market entry for uncertified suppliers.
- Coated:Clay or polymer surface treatments capture margin pools in marketing reproduction and presentation applications. REACH chemical restrictions limit certain coating formulations, redirecting capital toward compliant process investments.
- Textured:Embossed or laid patterns serve specialty correspondence and premium stationery markets. Niche demand volumes constrain dedicated production line economics.
Commodity procurement anchors in Uncoated; margin expansion concentrates in Coated.
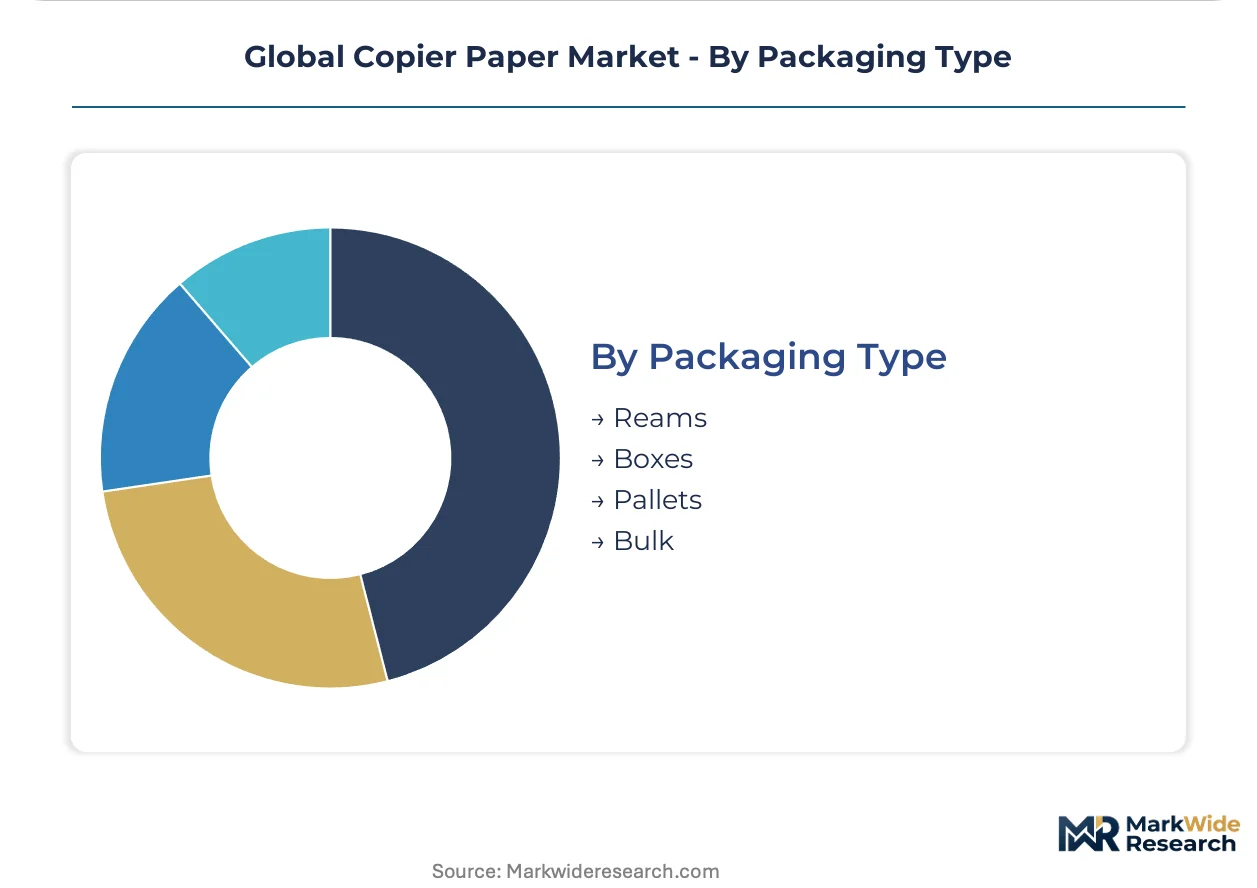
Packaging Type:
Logistics configuration determines handling efficiency and inventory carrying costs across distribution networks.
- Reams:500-sheet retail-ready packages serve small-office and home-office procurement through merchant channels. Japanese convenience retail networks stock ream-format copier paper for immediate consumer access.
- Boxes:Multi-ream containers balance portability with volume pricing for departmental purchasing. Enterprise buyers in Germany consolidate vendor relationships around box-format volume-tiered agreements.
- Pallets:Unitized loads enable forklift handling and warehouse efficiency for institutional storeroom replenishment. Direct mill-aligned distributors in France displace traditional merchant intermediaries through pallet-format logistics integration.
- Bulk:Unpackaged sheet deliveries minimize packaging waste for large-scale in-plant printing operations. EU Green Deal forestry certification requirements extend to packaging material sourcing for bulk-format government contracts.
Retail accessibility favors Reams; enterprise efficiency shifts toward Pallets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish pulp-to-paper exports supply German procurement offices under EU Green Deal chain-of-custody requirements, while Nordic integrated operators capture premium contract eligibility across Northern European distribution networks.
Germany
Federal and state procurement offices enforce EU Green Deal forestry certification through contract eligibility clauses that exclude non-compliant suppliers. REACH chemical restrictions redirect capital toward elemental chlorine-free process investments. The Rhine-Ruhr industrial corridor concentrates mill-aligned distributors displacing traditional merchant intermediaries through pallet-format logistics integration.
United States
Enterprise contract accounts and federal procurement frameworks sustain bulk volumes for Letter-format specifications despite digital workflow expansion. EPA emissions guidelines for pulp mill effluent shape domestic supply economics and mill siting decisions. Southeastern manufacturing complexes anchor North American supply through massive scale operations serving corporate accounts.
India
Government documentation mandates and educational institutional expansion sustain physical paper procurement volumes across A4-format contracts. BIS paper quality specifications enforce dimensional stability and brightness testing that delays market entry for uncertified suppliers. Maharashtra and Gujarat host distribution networks feeding government and school construction programs.
Japan
METI efficiency guidelines encourage procurement offices to specify reduced-weight alternatives in sub-70 gsm grades. Municipal collection facilities deploy near-infrared spectroscopy to meet rising brightness specifications for office-grade recycled pulp output. The Kanto region around Tokyo concentrates enterprise buyers consolidating vendor relationships around volume-tiered service agreements.
South Korea
Municipal collection infrastructure scales to support recycled content mandates in administrative segments. Near-infrared spectroscopy systems enable real-time contamination detection and grade optimization in secondary fiber preparation. The Seoul Capital Area drives demand for smooth-calendered finishes minimizing toner adhesion defects in high-speed laser systems.
Global Copier Paper Market Vendor Landscape
Listed leaders compete with private specialists across integrated pulp-to-paper operations and merchant distribution channels. The vendor base concentrates around Nordic timber-based integrated operators, North American scale manufacturers, and Asia-Pacific pulp conglomerates. Three archetypes dominate: captive timber-base integrators, recycled fiber specialists, and bioproduct mill operators converting wood residues to energy coproducts. Capacity expansion and Forest Stewardship Council chain-of-custody certification represent the dominant competitive moves reshaping contract eligibility.
Among Nordic integrated operators, UPM-Kymmene Corporation and Stora Enso Oyj exemplify the captive timber-base archetype with bioproduct mill integration offsetting manufacturing costs. International Paper Company anchors the North American scale-driven tier. Asia Pulp and Paper represents the Asia-Pacific pulp conglomerate model. These three occupy positions across distinct geographic and regulatory exposure profiles.
| Leading Market Players |
|---|
| Asia Pulp and Paper |
| UPM-Kymmene Corporation |
| International Paper Company |
| Oji Holdings Corporation |
| Stora Enso Oyj |
| Sylvamo |
| Domtar Corporation |
| WestRock Company |
| Mondi Group |
| Others |
Supply Flow & Price Mechanics
EU Green Deal forestry certification requirements gate both mill qualification and contract eligibility while simultaneously enabling price premiums for compliant Nordic integrated operators with captive timber bases. Procurement offices in Germany and France now exclude non-certified suppliers from government contracts, compressing pricing power for mills dependent on uncertified fiber while rewarding early movers with verified chain-of-custody documentation.
Pricing Analysis
Elemental chlorine-free process investments separate current-generation certified grades from prior-generation conventional bleaching and next-generation bioproduct-integrated output. Pricing stratifies across Forest Stewardship Council-certified premium tiers, standard commodity uncoated grades, and economy lightweight alternatives for cost-sensitive educational procurement. Cost compression in standard 75-80 gsm segments intensifies as recycled content mandates lag collection infrastructure scaling. Indian government documentation offices exhibit highest price sensitivity, while German federal procurement tolerates certified premiums for verified sustainable sourcing.
Supply Chain Analysis
Container availability constraints on Baltic-to-North Sea trade lanes elevate inbound logistics costs for Finnish pulp-to-paper exports serving German distribution networks. Supply concentrates in Finland, Sweden, and the United States, with Nordic integrated operators drawing from captive timber bases and North American scale manufacturers resting on Southeastern manufacturing complexes. Softwood and hardwood pulp prices hinge on energy costs and freight rate volatility, creating margin compression without pricing recovery. Distribution runs through mill-aligned distributors displacing traditional merchant intermediaries in France and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise buyer consolidation around volume-tiered service agreements with embedded logistics management signals platform-economics inflection, as direct mill-distributor relationships displace fragmented merchant channels across European procurement offices.
For Market Incumbents: Consolidate vendor relationships and certification portfolios to defend contract eligibility as EU Green Deal requirements harden. Deepen backward integration into captive timber supplies or bioproduct mill energy coproduction to offset manufacturing cost pressure from elemental chlorine-free process retooling. Anchor defensive positioning in Nordic or Baltic timber bases where chain-of-custody documentation is already operationalized. For New Entrants and Emerging Players: Anchor in India's government documentation and educational institutional expansion, where BIS quality specification barriers delay established competitors and physical paper procurement volumes sustain despite surrounding digital adoption. Target Maharashtra and Gujarat distribution networks feeding school construction programs with A4-format bulk contracts. Pursue direct relationships with state procurement offices rather than merchant channel dependence. For Investors and Strategic Acquirers: EU Green Deal implementation milestones reshape the acquisition landscape by privileging integrated operators with verified certification over merchant-dependent or uncertified mill assets. Five-to-ten year viability favors bioproduct mill operators converting wood residues to energy coproducts. Monitor pulp fiber cost trajectories against recycled content mandate enforcement as the inflection signal for virgin fiber economics disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Forest Stewardship Council Certification Investment | Chain-of-custody documentation unlocks German and French government contract eligibility. |
| Bioproduct Mill Integration | Wood residue-to-energy coproduction offsets copier paper manufacturing costs under EU emissions guidelines. |
| Elemental Chlorine-Free Process Retooling | REACH chemical restriction compliance creates competitive moats with 18-24 month certification timelines. |
| Direct Distributor Relationships | Mill-aligned logistics integration displaces merchant intermediaries in enterprise procurement consolidation. |
| Recycled Content Infrastructure Scaling | Municipal collection facility investment enables compliance with rising regulatory mandates in administrative segments. |
Methodological Framework
A standing panel of pulp mill operations directors, enterprise procurement managers, distribution channel partners, and regulatory compliance officers provided ongoing calibration across the research process. Primary interviews with these stakeholders combined with secondary validation against customs and trade data, forest industry association reports, SEC filings from listed paper manufacturers, and national standards body documentation. Bottom-up volume modeling across paper type, weight category, finish type, and packaging format segments triangulated with top-down macroeconomic consistency checks.
Consistency checks validated volume and value outputs against external benchmarks including pulp price indices, freight rate series, and procurement contract disclosure patterns across the projection horizon. The analytical framework modeled segmentation dimensions including dimensional format specifications, grammage tiers, surface treatment categories, and logistics configurations alongside regional regulatory cluster variations. CAGRs were derived from trend extrapolation adjusted for policy implementation timelines and technology substitution elasticities. Forecast inputs incorporated pulp fiber cost trajectories, recycled collection infrastructure scaling rates, and digital workflow adoption patterns in administrative segments.
Decision-makers should treat outputs as directional under base assumptions of sustained hybrid workplace documentation needs and gradual recycled content mandate enforcement; material deviation in digital substitution velocity or regulatory acceleration would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Coated Wood Free Papers Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Global Paper Chemical Market
Paper Products
Printing Paper Market
Paper Products
Paper Doilies Market
Paper Products
Writing Paper Market
Paper Products
Household Paper Market
Paper Products
Latex-Saturated Paper Market
Paper Products
Sawn Wood Market
Paper Products
Paper Coating Materials Market
Paper Products
Acrylic Paper Market
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
Bleached Hardwood Kraft Pulp Market
Paper Products
Chemical Pulp Market
Paper Products
Pigmented Paper Market
Paper Products
Africa Tissue Paper Market