
 Latex-Saturated Paper Market | 2026-2036
Latex-Saturated Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Latex-Saturated Paper Market Outlook
EU REACH restrictions on formaldehyde and volatile organic compound emissions from paper coating operations is consolidating demand toward low-emission latex formulations. Papierfabriek Schut B.V. anchors European supply through specialized coating capabilities in the Netherlands. The Griff Network competes across North American specialty paper distribution with tailored saturation services. UPM-Kymmene Oyj leverages integrated pulp-to-paper operations to sustain cost advantages in coated latex-saturated grades.
Latex-saturated paper refers to cellulosic substrates impregnated with aqueous polymer emulsions, typically styrene-butadiene or natural rubber latex at 15-40% dry weight add-on, to enhance tensile strength, moisture resistance, and fold endurance for demanding print and converting applications. Specialty paper grades command premium positioning due to custom saturation chemistries and tight caliper tolerances required for security and medical labeling. Uncoated paper segments dominate volume throughput in commercial printing, while coated variants capture margin pools in high-end packaging and graphic arts applications where surface smoothness and ink holdout prove critical.
FDA regulations govern latex-saturated papers in indirect food contact packaging and medical label applications, while EPA emission standards shape domestic manufacturing compliance costs. ISO 9001 and FSC chain-of-custody certifications increasingly gate market access for European and North American buyers demanding traceable fiber sourcing. Stakeholders must monitor evolving chemical disclosure requirements under EU MDR and state-level extended producer responsibility laws to anticipate reformulation investments and qualify for premium supply contracts.
Market Dynamics
REACH compliance on chemical emissions is consolidating European coating operations toward low-emission latex formulations, compressing supplier margins while elevating technical barriers to market entry.
Growth Catalysts
- EU MDR traceability mandates:Medical device labeling requirements under the EU Medical Device Regulation are accelerating demand for certified latex-saturated substrates with full fiber provenance documentation.
- Security printing applications:Governmental and financial document producers are specifying custom-saturated papers with embedded authentication features for tax stamps and banknote substrates.
- Italy's premium packaging cluster:Northern Italian converters serving luxury cosmetics and spirits brands are expanding procurement of high-gloss latex-saturated label stocks for pressure-sensitive applications.
Market Restraints
- Styrene-butadiene latex price volatility:Petrochemical feedstock fluctuations are compressing coating margins and forcing quarterly contract renegotiations with paper mills.
- Netherlands supply concentration:Papierfabriek Schut B.V. and limited adjacent coating specialists control European specialty-grade capacity, creating single-source vulnerability for security-grade formulations.
- Water-based saturation energy intensity:Drying ovens for aqueous latex coatings consume substantial natural gas, exposing producers to EU ETS carbon pricing and utility cost spikes.
Strategic Opportunities
- German pharmaceutical serialization:The Bundesinstitut für Arzneimittel und Medizinprodukte track-and-trace requirements are opening demand for latex-saturated tamper-evident labels in cold-chain logistics.
- Bio-based latex emulsions:Natural rubber and guayule-derived polymer substitutes are enabling premium positioning for sustainability-certified packaging converters in France.
- Direct mill-to-converter digital platforms:Specialized paper distributors are deploying configure-to-order portals that bypass traditional merchant networks for custom caliper and saturation specifications.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise combining polymer science with paper machine wet-end chemistry is retiring faster than European technical universities can replenish pipelines.
- FSC chain-of-custody audit burden:Annual certification costs and documentation requirements are disproportionately burdening mid-volume converters serving fragmented label markets.
- Legacy saturation line retrofit complexity:Converting antique size presses for controlled latex pickup requires mechanical rebuilds that strain capital allocation against shorter product lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latex-Saturated Paper Market |
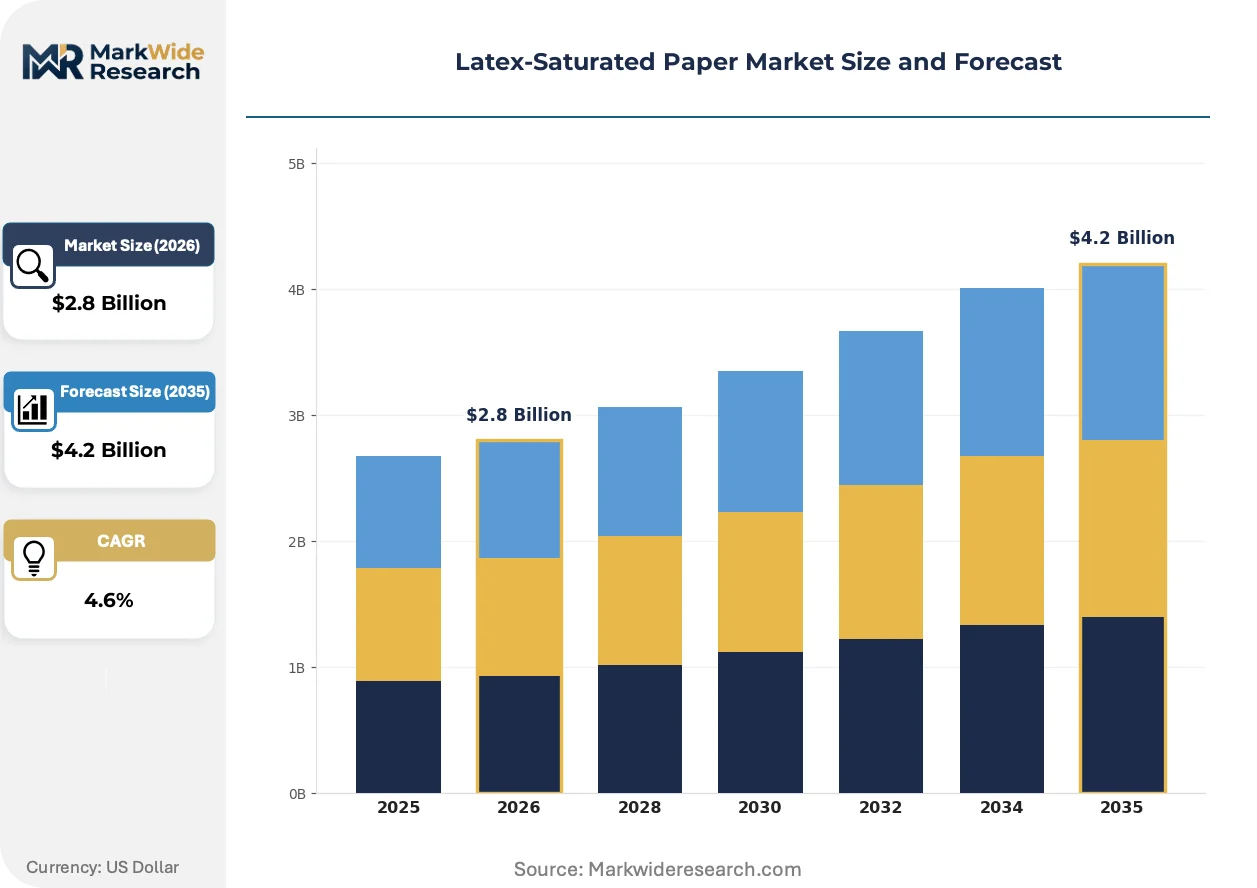
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Specialty Paper, Recycled Paper End User: Publishing Industry, Packaging Industry, Graphic Arts, Commercial Printing Application: Labels, Invitations, Posters, Stationery Printing Technology: Offset Printing, Digital Printing, Flexography, Gravure Printing |
| Companies Covered | Papierfabriek Schut B.V., The Griff Network, Potsdam Specialty Paper Inc., Sihl AG, Daifuku Paper Mfg. Co., Ltd., Neenah Inc., UPM-Kymmene Oyj, Mafcote, Inc., EMI Specialty Papers, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latex-Saturated Paper Market Strategic Shifts
Digital print compatibility requirements are restructuring latex saturation chemistries, while regulatory disclosure mandates and procurement centralization are reshaping how specifications travel through the value chain.
Hybrid aqueous-UV curable latex systems are unifying the historically separate pre-treatment and top-coating stages in label stock production. Pharmaceutical and security printers in Germany and Switzerland are specifying these unified substrates to eliminate interlayer adhesion failures. The technology is compressing lead times for custom security grades from twelve weeks to four while reducing coating line changeover waste.
REACH Annex XVII restrictions on formaldehyde-releasing agents in paper coatings are forcing reformulation of urea-formaldehyde wet-strength additives. Coating operations across Belgium and the Netherlands are qualifying glyoxal and polyamide-amine-epichlorohydrin substitutes at 15-30% higher chemical cost. Security and medical labeling segments are absorbing these premiums through specification lock-ins, while commercial printing grades face margin compression.
Consolidated procurement by pan-European packaging groups is displacing fragmented merchant purchasing for latex-saturated substrates. Label converters serving Unilever and L'Oréal beauty divisions are consolidating specifications across six to eight national production sites, demanding uniform caliper and porosity ranges that only integrated pulp-to-paper suppliers can guarantee. France and Germany host the most visible concentration of this specification rationalization.
Latex-Saturated Paper Market Segmentation
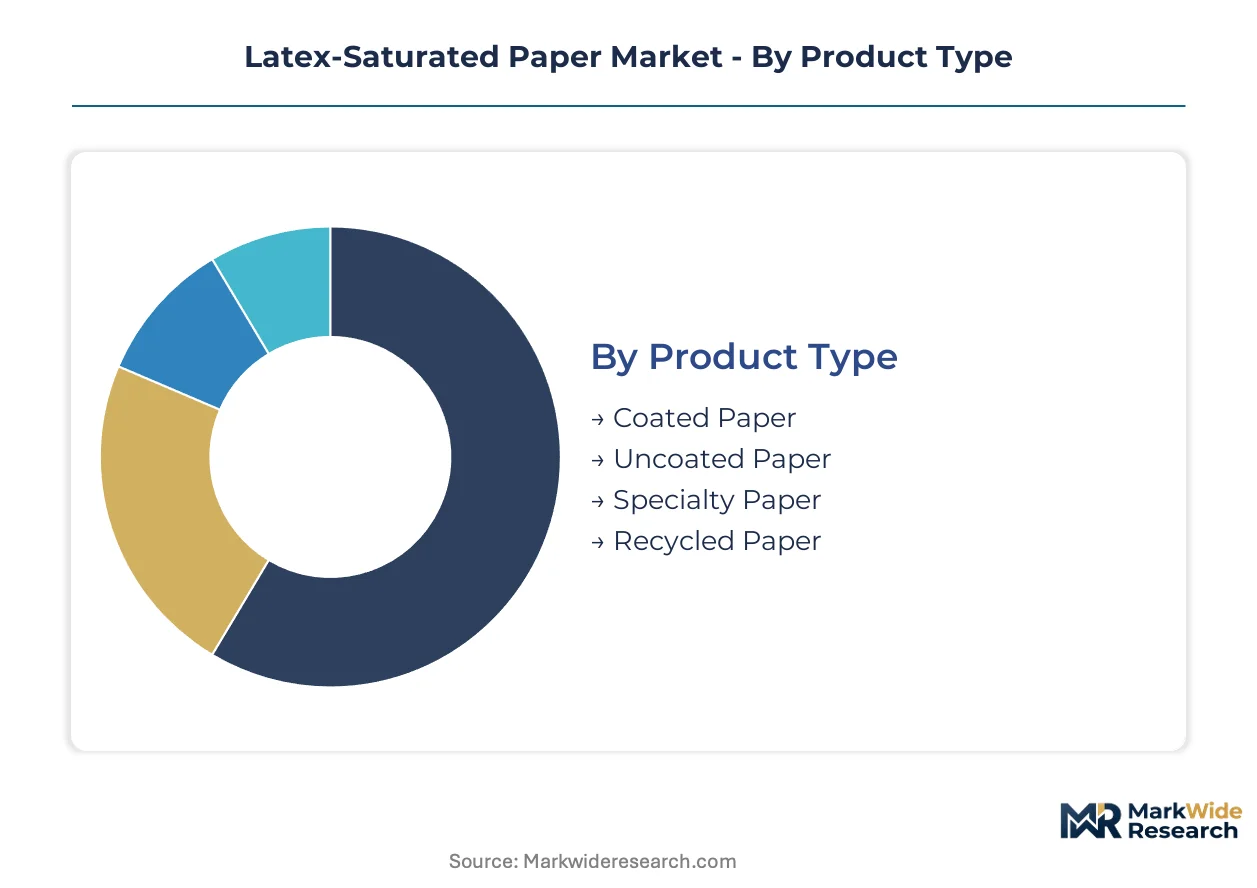
Latex saturation chemistry varies sharply by substrate grade, creating divergent margin profiles and technical qualification requirements across the value chain. Each segment tier demands distinct coating line configurations, drying energy inputs, and regulatory compliance investments that reshape supplier competitiveness.
Product Type:
Buyers differentiate primarily by surface finish requirements and caliper tolerances rather than base fiber composition.
- Specialty Paper:Custom-saturated substrates engineered for security printing and medical labeling carry 15-40% dry weight polymer add-on with tight porosity control. Northern Italian luxury packaging converters and German pharmaceutical label producers concentrate procurement here, absorbing premium pricing for REACH-compliant low-emission formulations.
- Coated Paper:Pre-coated base stocks receive additional latex saturation for high-gloss label applications requiring superior ink holdout. French and German beauty brand packaging specifications are consolidating demand toward unified aqueous-UV curable systems that compress lead times from twelve weeks to four.
- Uncoated Paper:Volume throughput leader in commercial printing applications where fold endurance and moisture resistance suffice without surface smoothness premiums.
- Recycled Paper:FSC-certified fiber streams serving sustainability-positioned converters in France; limited by fiber variability constraints on saturation uniformity.
Volume sits with Uncoated Paper; growth tilts toward Specialty Paper.
End User:
Procurement scale and specification complexity separate enterprise buyers from fragmented merchant purchasers.
- Packaging Industry:Pan-European groups serving Unilever and L'Oréal are consolidating specifications across six to eight national production sites, demanding uniform caliper ranges that only integrated pulp-to-paper suppliers guarantee. Bundesinstitut für Arzneimittel und Medizinprodukte track-and-trace mandates are expanding demand for tamper-evident label stocks in German cold-chain logistics.
- Graphic Arts:Security printers in Germany and Switzerland specify custom-saturated papers with embedded authentication features for tax stamps and banknote substrates, requiring 12-week qualification cycles and specification lock-ins.
- Commercial Printing:Price-sensitive volume applications where styrene-butadiene latex price volatility forces quarterly contract renegotiations.
- Publishing Industry:Limited penetration due to digital displacement; residual demand concentrates in premium invitation and certificate stocks.
Revenue concentrates in Packaging Industry; specification complexity peaks in Graphic Arts.
Application:
Regulatory exposure and print technology compatibility determine substrate selection more than aesthetic requirements.
- Labels:Pressure-sensitive and wet-glue applications dominate latex-saturated paper consumption, with EU MDR traceability mandates accelerating demand for certified substrates with full fiber provenance documentation. Medical device and pharmaceutical segments absorb 15-30% chemical cost premiums for formaldehyde-free wet-strength substitutes.
- Stationery:Premium correspondence papers requiring fold endurance and moisture resistance for archival applications.
- Invitations:Luxury event stationery serving Northern Italian and French high-end print shops.
- Posters:Large-format display applications where dimensional stability under humidity variation proves critical.
Labels command the largest share; medical and security subsegments are expanding most quickly.
Printing Technology:
Digital compatibility requirements are restructuring saturation chemistries and drying protocols across coating operations.
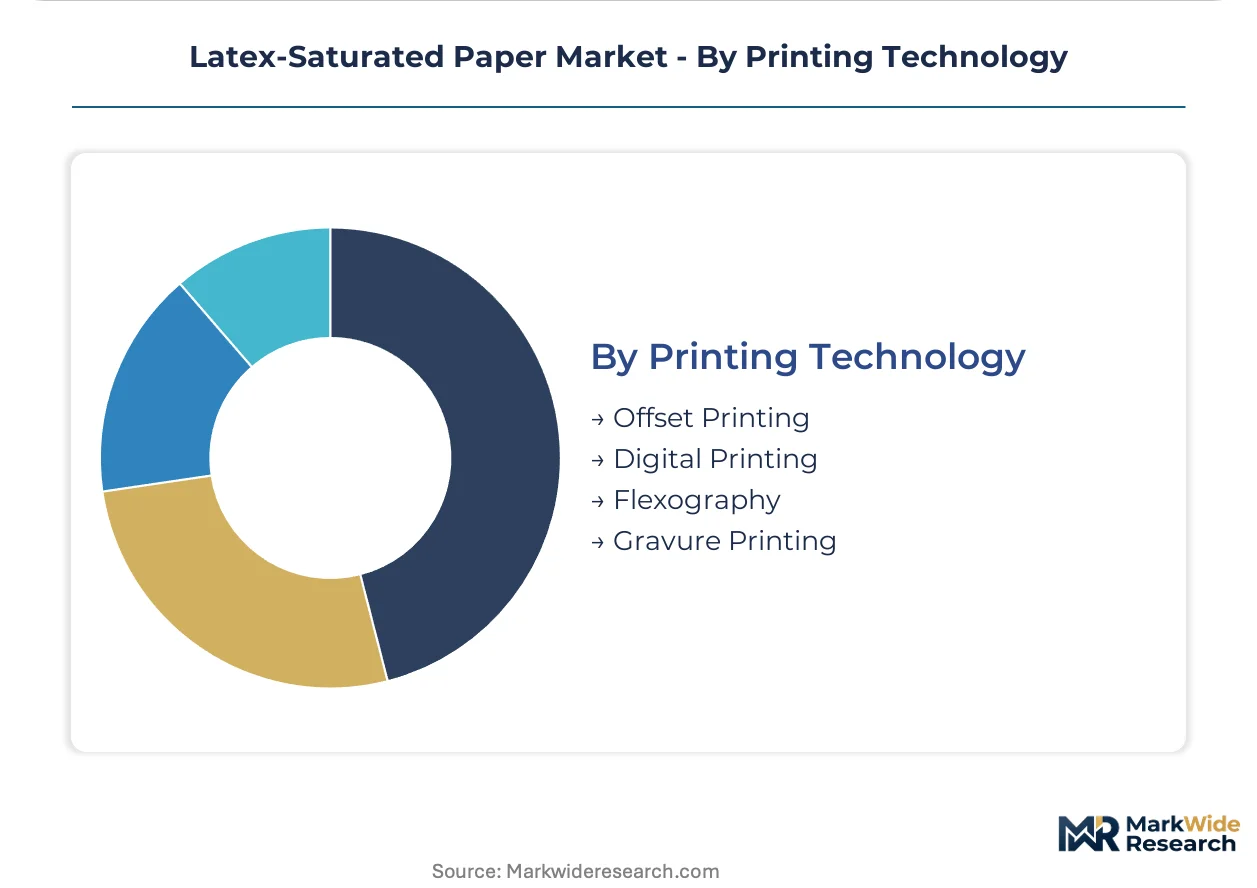
- Digital Printing:Toner and inkjet compatibility demands controlled surface resistivity and rapid ink absorption without interlayer adhesion failures. Hybrid aqueous-UV curable latex systems are unifying pre-treatment and top-coating stages, eliminating separate coating passes.
- Offset Printing:Conventional lithographic applications where fountain solution resistance and ink transfer efficiency dominate specification.
- Flexography:Water-based and UV flexo label printing requiring specific surface energy profiles for adhesive lamination.
- Gravure Printing:High-volume publication and decorative applications with stringent smoothness requirements.
Offset retains volume dominance; Digital Printing is gaining share fastest on pharmaceutical and security specification shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European coating capacity outpaces regional consumption, forcing specialty-grade producers to export security and medical label stocks to North American pharmaceutical printers. Asian converters in Japan and South Korea absorb premium substrates for electronics packaging and authentication documents.
Germany
Bundesinstitut für Arzneimittel und Medizinprodukte track-and-trace mandates are expanding procurement of tamper-evident latex-saturated labels for cold-chain pharmaceutical logistics. REACH Annex XVII formaldehyde restrictions are forcing Baden-Württemberg coating operations to qualify glyoxal-based wet-strength substitutes at elevated chemical cost. The Rhine-Main industrial corridor hosts concentrated demand from security printers serving federal tax stamp contracts.
France
L'Oréal and Unilever beauty divisions are consolidating label specifications across six to eight national production sites, demanding uniform caliper tolerances from integrated pulp-to-paper suppliers. ECHA disclosure requirements under REACH are tightening documentation burdens for coating chemistries used in luxury cosmetics packaging. The Île-de-France region anchors pan-European procurement centralization for premium label stocks.
Italy
Northern Italian converters serving luxury spirits and cosmetics brands are expanding procurement of high-gloss latex-saturated label stocks for pressure-sensitive applications. EU MDR traceability mandates are accelerating certification requirements for medical device labeling substrates with full fiber provenance. The Lombardy-Veneto packaging cluster concentrates specialty-grade demand from premium brand owners.
Netherlands
Papierfabriek Schut B.V. anchors European supply of security-grade latex-saturated papers through specialized coating capabilities in the Veluwe region. EU ETS carbon pricing is exposing aqueous saturation drying operations to natural gas cost volatility, compressing margins on standard commercial grades. The Randstad logistics hub facilitates distribution to German and French converting markets.
United States
FDA regulations governing indirect food contact and medical label applications are shaping formulation compliance investments for domestic coating operations. EPA emission standards for volatile organic compounds from paper finishing processes are elevating technical barriers for mid-volume converters. The Northeast corridor and Midwest label manufacturing belts concentrate demand from pharmaceutical serialization programs.
Latex-Saturated Paper Market Competitive Environment
The competitive structure tilts toward integrated pulp-to-paper suppliers with captive saturation capabilities. Three archetypes dominate: European specialty coating specialists with security-grade qualifications, North American distributors offering configure-to-order saturation services, and integrated forest products groups leveraging backward integration into latex formulation. Capacity expansion and specification lock-ins through pharmaceutical qualification cycles represent the dominant competitive moves, while strategic partnerships between coating operations and brand owner procurement groups are displacing traditional merchant networks.
Within the specialty coating tier, Papierfabriek Schut B.V. and Sihl AG exemplify European security-grade specialists with concentrated technical capabilities in controlled polymer add-on processes. UPM-Kymmene Oyj anchors the integrated archetype, representing forest products groups with captive pulp supply and in-house saturation lines. The Griff Network occupies a distributor position, exemplifying North American players that bridge mill production with converter specification requirements through tailored inventory and logistics services.
| Leading Market Players |
|---|
| Papierfabriek Schut B.V. |
| The Griff Network |
| Potsdam Specialty Paper Inc. |
| Sihl AG |
| Daifuku Paper Mfg. Co., Ltd. |
| Neenah Inc. |
| UPM-Kymmene Oyj |
| Mafcote, Inc. |
| EMI Specialty Papers, Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned Dutch coating specialists anchor European specialty-grade capacity, translating concentrated technical ownership into pricing discipline that resists commodity erosion despite petrochemical feedstock volatility. Their captive control over security-grade formulation expertise enables premium capture while mid-volume converters absorb margin compression from REACH compliance investments.
Pricing Analysis
Margin tightening in commercial printing grades reflects styrene-butadiene latex feedstock volatility and quarterly contract renegotiations with paper mills. Three-tier pricing structure across premium security grades, standard label stocks, and economy commercial grades separates buyers by certification burden and customization depth. Pricing pressure intensifies in uncoated segments as energy-intensive aqueous saturation drying exposes producers to EU ETS carbon pricing. Pharmaceutical and medical device label converters prove least price-sensitive, absorbing 15-30% chemical cost premiums for formaldehyde-free wet-strength substitutes.
Supply Chain Analysis
Domestic-content mandates under EU MDR traceability requirements are reshaping sourcing toward FSC-certified fiber streams with full provenance documentation. Supply concentrates in the Netherlands, Germany, and France, with Papierfabriek Schut B.V. anchoring security-grade coating capacity in the Veluwe region. Raw material dependencies center on styrene-butadiene latex emulsions, natural rubber substitutes, and glyoxal-based wet-strength additives. Single-source vulnerability for security-grade formulations creates structural risk, compounded by coating chemist talent scarcity. Distribution runs through specialized paper distributors and direct mill-to-converter digital platforms that bypass traditional merchant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over latex formulation and captive pulp supply determines margin capture. Players are pursuing upstream polymer chemistry capabilities and downstream specification lock-ins through pharmaceutical qualification cycles.
For Market Incumbents: Cement specification lock-ins through Bundesinstitut für Arzneimittel und Medizinprodukts track-and-trace qualification cycles that create 12-week switching barriers. Expand coating capacity in Baden-Württemberg to capture German pharmaceutical serialization demand while defending against bio-based latex substitutes from French sustainability-certified competitors. For New Entrants and Emerging Players: Begin with FSC-certified recycled fiber segments serving French sustainability-positioned converters, where fragmented demand and lower technical barriers offset incumbents' scale advantages. Target mid-volume Italian luxury packaging converters in the Lombardy-Veneto cluster through configure-to-order digital platforms that bypass established distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor European specialty coating specialists with security-grade qualifications and controlled polymer add-on capabilities in the Netherlands and Germany. Watch for EU ETS carbon pricing spikes that strain natural gas-dependent aqueous saturation operations and force consolidation. The signal to monitor is pharmaceutical serialization mandate acceleration across EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Latex Formulation | Captive polymer chemistry control insulates margins from petrochemical feedstock volatility. |
| EU MDR Certification Investment | Fiber provenance documentation opens pharmaceutical and medical device label procurement. |
| Hybrid Aqueous-UV Coating Line Deployment | Unified pre-treatment and top-coating stages compress lead times for German security printers. |
| Direct Mill-to-Converter Digital Platform | Bypasses traditional merchant networks for custom caliper specifications in Italian luxury packaging. |
| Bio-Based Latex Emulsion Development | Natural rubber and guayule substitutes enable premium positioning under French sustainability procurement. |
Study Parameters
Trade association filings, customs documentation, and SEC 10-K disclosures formed the secondary backbone, cross-referenced against primary interviews with coating operations managers, pharmaceutical label procurement leads, paper mill technical directors, and specialty paper distribution channel partners. Bottom-up and top-down triangulation validated volume estimates across substrate grades and end-use applications.
Bottom-up modeling aggregated segment-level demand from pharmaceutical serialization programs, security printing contracts, and luxury packaging specifications, while top-down approaches calibrated against pulp-to-paper supplier capacity disclosures. Segmentation dimensions spanned surface finish requirements, saturation chemistry tiers, end-use regulatory exposure, and print technology compatibility. CAGRs derived from trend extrapolation of EU MDR implementation timelines and REACH Annex XVII compliance investments.
Underlying measurement precision varies by segment; specialty security and medical label grades carry tighter precision than fragmented commercial printing volumes. Forecasts reflect assumptions around regulatory enforcement consistency and petrochemical feedstock stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Pulp and Paper Market
Paper Products
Asia-Pacific Thermal Paper Market
Paper Products
Thermal Paper Market
Paper Products
Woodfree Paper Market
Paper Products
Loose Leaf Paper Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Sawn Wood Market
Paper Products
Functional and Barrier Coatings for Paper Market
Paper Products
Super Calendered Glassine Paper Market
Paper Products
Dissolving Pulp Market
Paper Products
Wood Paper and Paperboard Recycling Market
Paper Products
Global Molded Pulp Products Market
Paper Products
Billing Paper Market
Paper Products
Softwood Pulp Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Household Paper Market