
 Viscose Staple Fiber Market | 2026-2036
Viscose Staple Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Viscose Staple Fiber Market Intelligence
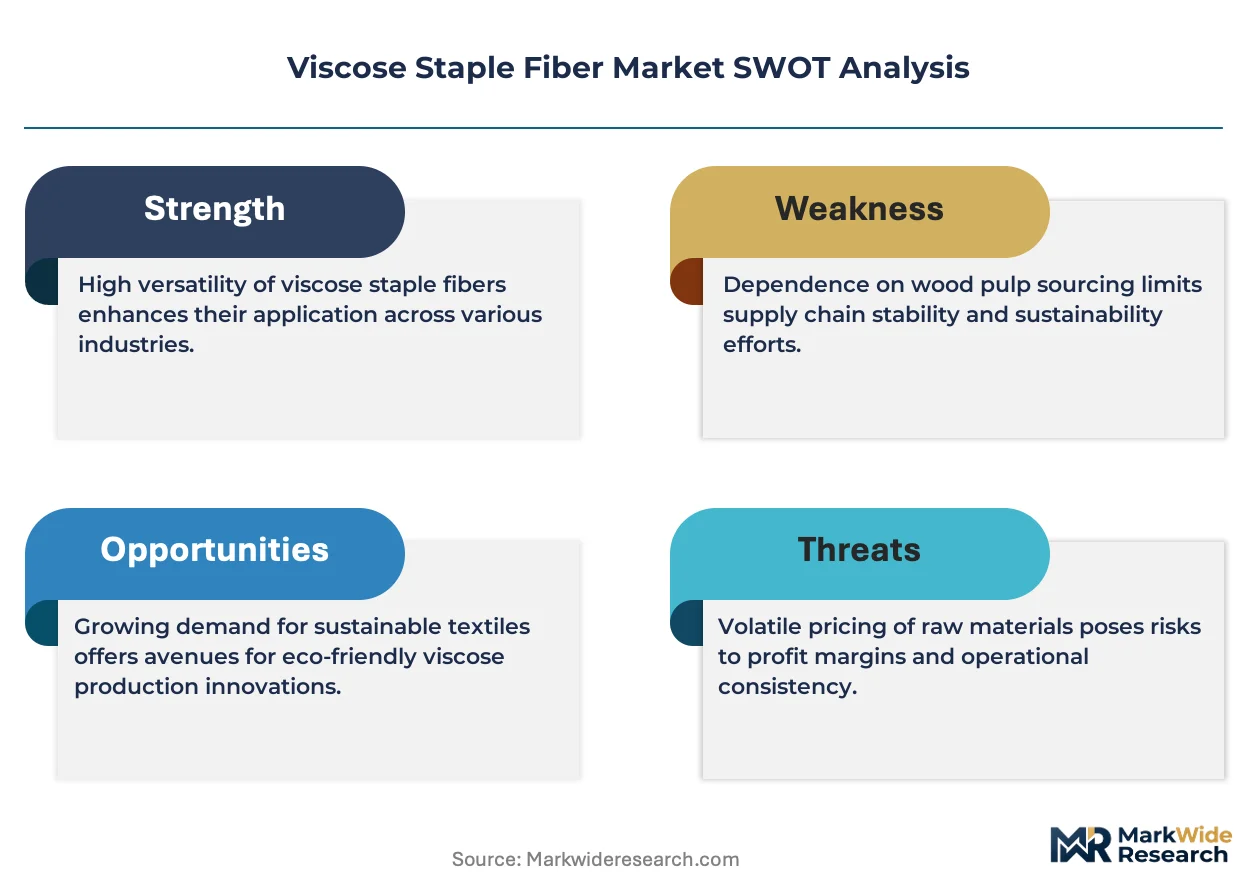
The capital-intensity divergence between integrated pulp producers and merchant fiber suppliers is rotating competitive advantage toward backward-linked operations. Lenzing AG leverages its wood-pulp integration and closed-loop manufacturing to sustain premium positioning in European and Asian markets. Grasim Industries Limited anchors South Asian supply through massive Indian manufacturing complexes that dominate regional cost curves.
Viscose staple fiber is a regenerated cellulose fiber produced from wood pulp or bamboo through the viscose process, typically measuring 1.2-1.5 denier with cotton-like handle and moisture absorbency exceeding synthetic alternatives. Its primary purpose is to substitute or blend with cotton in textile applications where softness, dye affinity, and breathability matter. Specialty viscose commands disproportionate margin pools as technical textile applications expand, while regular viscose remains the volume backbone for apparel and home furnishings. High tenacity grades are gaining traction in industrial applications where strength-to-weight ratios determine substitution against polyester.
REACH in Europe, China's MEE emissions standards, and India's CEA energy-efficiency mandates collectively tighten chemical recovery and wastewater requirements across major production bases. These frameworks elevate compliance costs for smaller merchant producers while rewarding integrated operators with captive chemical plants and effluent treatment systems. Stakeholders must monitor regulatory enforcement intensity in Indonesia and Vietnam as new capacity investments face evolving permitting standards.
Market Dynamics
Integrated pulp-to-fiber operations are capturing margin from merchant producers as carbon accounting and chemical recovery mandates intensify across European and Asian regulatory regimes.
Growth Catalysts
- India's PLI scheme for textiles:The production-linked incentive program subsidizes integrated spinning and fiber manufacturing, accelerating viscose procurement from domestic suppliers.
- Lyocell process adoption:Closed-loop solvent recovery technology reduces wastewater discharge and positions adopters ahead of tightening MEE standards in China.
- Fast-fashion cotton substitution:Apparel brands in Bangladesh and Vietnam are expanding viscose blend ratios to manage raw material cost volatility and dye-cycle efficiency.
Market Restraints
- Dissolving pulp supply concentration:Brazilian and Indonesian pulp producers control critical feedstock, exposing fiber manufacturers to input cost spikes and currency exposure.
- REACH chemical authorization delays:European carbon disulfide handling restrictions extend permitting timelines for new merchant capacity investments.
- Polyester price competitiveness:Recycled PET fiber advances in moisture-wicking applications limit viscose penetration in performance apparel segments.
Strategic Opportunities
- Indonesia's emerging integrated clusters:New pulp-fiber-textile corridors in Sumatra offer tariff-advantaged export platforms to ASEAN and Middle Eastern markets.
- Medical textile grades:High-purity viscose for surgical gauze and wound care applications commands specialty pricing and long-term supply contracts.
- EU Green Deal carbon border adjustments:European importers sourcing from low-emission fiber producers gain compliance advantages over conventional supply chains.
Industry Challenges
- CSRD reporting implementation:Scope 3 emissions disclosure requirements demand supply chain traceability systems that smaller merchant producers lack capital to deploy.
- Skilled chemical engineering scarcity:Viscose process optimization and closed-loop retrofitting require expertise concentrated at legacy European and Japanese operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viscose Staple Fiber Market |
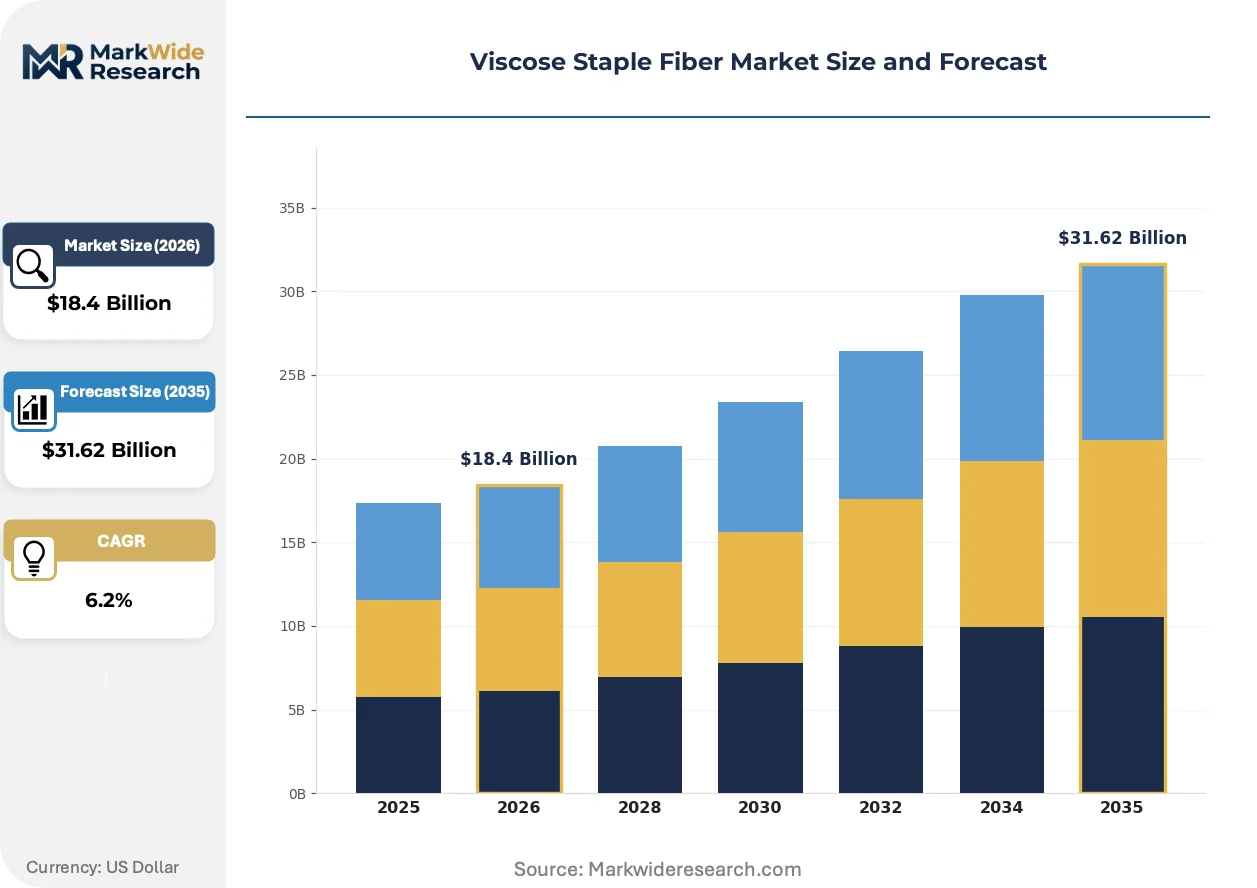
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $31.62 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Viscose, High Tenacity Viscose, Specialty Viscose, Bamboo Viscose End User: Textiles, Non-Woven Fabrics, Medical Supplies, Home Furnishings Application: Apparel, Upholstery, Industrial, Hygiene Products Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Tangshan Sanyou Xingda Chemical Fiber CO.,Ltd, Asia Pacific Rayon Limited, Lenzing AG, Jilin Chemical Fibre Group, Birla Cellulose, Grasim Industries Limited, Xinjiang Zhongtai Group, Kelheim Fibres GmbH, Sateri Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viscose Staple Fiber Market Strategic Shifts & Innovations
Carbon intensity accounting is reshaping procurement criteria across textile value chains, favoring producers with verified lifecycle data and solvent recovery systems.
Lyocell fiber technology is displacing conventional viscose in premium apparel applications through its closed-loop N-methylmorpholine N-oxide solvent system. Outdoor and activewear brands in Germany and Japan are specifying lyocell for base-layer products requiring moisture management without synthetic content. This displacement is compressing margin pools for commodity viscose producers lacking lyocell conversion capability.
China's MEE emissions standards for chemical fiber manufacturing now mandate 95 percent carbon disulfide recovery rates and real-time wastewater monitoring. Facilities in Jiangsu and Zhejiang provinces face retrofit deadlines that favor integrated operators with captive chemical plants over merchant converters dependent on third-party recovery services. The regulatory burden is accelerating consolidation among smaller producers in the Yangtze River Delta.
Brand-led fiber provenance verification is restructuring supplier qualification protocols in European markets. H&M Group and Inditex are deploying blockchain-tracked viscose from certified sustainable forestry, bypassing traditional commodity brokers. This behavioral shift concentrates procurement volumes with Lenzing and comparable integrated producers capable of farm-to-fiber documentation, marginalizing undifferentiated merchant supply.
Viscose Staple Fiber Market Segmentation
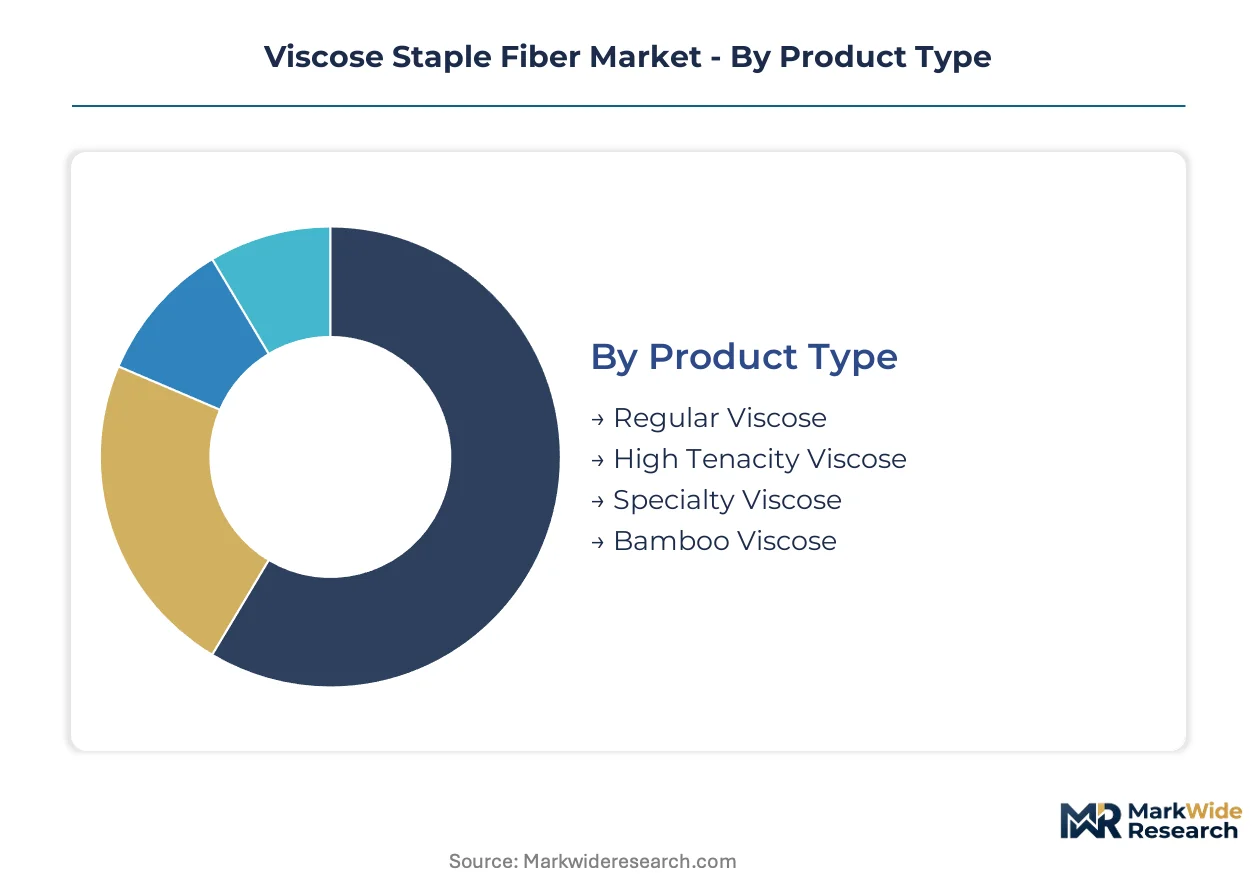
Viscose staple fiber segmentation reveals divergent margin structures across product grades and end-use applications. Specialty grades command premium pricing through technical specifications, while commodity segments compete on scale and chemical recovery efficiency.
Product Type:
Margin pools concentrate in specialty and high-tenacity grades where technical barriers limit merchant competition.
- Regular Viscose:Standard 1.2-1.5 denier fiber produced through conventional viscose process with cotton-like handle and moisture absorbency. Bangladesh and Vietnam apparel manufacturers are expanding blend ratios for fast-fashion applications to manage cotton price volatility.
- High Tenacity Viscose:Engineered for superior strength-to-weight ratios through controlled polymer orientation and spinning parameters. Industrial textile applications in Germany and Japan are adopting this grade for tire cord and conveyor belt reinforcement where polyester substitution faces sustainability scrutiny.
- Specialty Viscose:Modified cross-section and finish variants for technical textile applications.
- Bamboo Viscose:Regenerated cellulose derived from bamboo pulp feedstock, marketed under sustainability positioning.
Regular viscose holds installed capacity across South Asian manufacturing complexes. Specialty viscose is rotating up the share rankings as technical textile specifications tighten.
End User:
Volume concentration sits with textile applications, though medical and hygiene segments offer defensible margin structures.
- Textiles:Spinning and weaving operations consuming staple fiber for woven and knitted fabrics. India's PLI scheme for textiles is accelerating integrated spinning capacity expansion, concentrating procurement with domestic viscose suppliers in Gujarat and Maharashtra.
- Non-Woven Fabrics:Hydroentangled and thermobonded web structures for disposable and durable applications. Wet wipe and filtration manufacturers in Indonesia are scaling viscose procurement for biodegradable substrate alternatives to synthetic spunbond.
- Medical Supplies:Surgical gauze, wound dressings, and hygiene products requiring high-purity fiber.
- Home Furnishings:Upholstery, curtains, and bedding applications emphasizing drape and moisture management.
Textile end-use dominates production allocation. Medical supplies are climbing the fastest as certification requirements filter out undifferentiated supply.
Application:
Application-driven pricing stratifies across performance tiers, with industrial and hygiene commanding technical premiums over commodity apparel.
- Apparel:Woven and knitted garments leveraging viscose softness, dye affinity, and breathability. H&M Group and Inditex are deploying blockchain-tracked fiber from certified sustainable forestry, bypassing commodity brokers for provenance-verified supply.
- Upholstery:Furniture and automotive interior fabrics requiring abrasion resistance and colorfastness.
- Industrial:High-tenacity applications including tire cord, conveyor belts, and geotextiles. China's MEE emissions standards are favoring integrated producers with captive chemical plants for this specification-intensive segment.
- Hygiene Products:Absorbent cores and coverstock for personal care applications.
Apparel absorbs baseline capacity. Industrial applications are expanding most quickly as strength-to-weight specifications drive substitution from synthetic alternatives.
Distribution Channel:
Channel economics favor direct sales for volume accounts, with digital platforms emerging for specialty and small-lot procurement.
- Direct Sales:Mill-direct relationships between fiber producers and integrated spinners or textile manufacturers. Grasim Industries and Lenzing AG leverage long-term contracts with South Asian spinning complexes to lock in offtake and optimize production scheduling.
- Wholesalers:Merchant intermediaries aggregating supply for smaller converters lacking direct mill relationships.
- Online Retail:Digital platforms for specialty grades and small-lot procurement.
- Specialty Stores:Niche distributors serving technical textile and medical supply manufacturers.
Direct sales channels hold volume concentration with major integrated spinners. Online retail is gaining traction fastest for specialty grades and sustainability-certified lots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with integrated pulp producers in Austria and Indonesia while merchant converters in Bangladesh and Vietnam absorb margin compression from carbon accounting mandates.
China
Jiangsu and Zhejiang spinning complexes are retrofitting viscose capacity to meet MEE emissions standards requiring 95 percent carbon disulfide recovery. The dual carbon goals framework is accelerating consolidation among Yangtze River Delta producers lacking captive chemical plants. Suzhou and Hangzhou clusters now favor integrated operators with real-time wastewater monitoring systems.
India
Gujarat and Maharashtra textile exporters are scaling viscose procurement under the PLI scheme for integrated spinning capacity. CEA energy-efficiency mandates tighten chemical recovery requirements for fiber manufacturers in Surat and Ichalkaranji. Grasim Industries anchors regional supply through massive manufacturing complexes dominating domestic cost curves.
Indonesia
Sumatra's emerging pulp-fiber-textile corridors offer tariff-advantaged export platforms to ASEAN markets. The country's national environmental regulator is evolving permitting standards for new dissolving pulp investments. Asia Pacific Rayon and Sateri Holdings are building backward-integrated operations to capture margin from pulp supply concentration.
Germany
REACH chemical authorization delays for carbon disulfide handling extend permitting timelines for merchant capacity investments. ECHA compliance costs reward producers with closed-loop solvent recovery systems. Kelheim Fibres GmbH leverages technical textile specialization to command premium positioning in industrial applications.
Brazil
Dissolving pulp producers in São Paulo state control critical feedstock for Asian fiber manufacturers, exposing converters to currency exposure and input cost spikes. ANVISA purity standards for medical-grade viscose create certification barriers for undifferentiated supply. Eucalyptus plantation-to-pulp integration concentrates pricing power with backward-linked operators.
Viscose Staple Fiber Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with Austrian and German specialists commanding premium positioning through closed-loop manufacturing while South Asian scale operators dominate volume tiers. The vendor base separates into three strategic clusters: integrated pulp-to-fiber conglomerates with captive forestry, merchant converters dependent on spot pulp markets, and specialty producers serving technical textile niches. Consolidation pressures favor operators with in-house chemical recovery and carbon accounting systems. Dominant competitive moves include backward integration into dissolving pulp production and geographic expansion into tariff-advantaged ASEAN corridors.
Among Austrian and German specialists, Lenzing AG and Kelheim Fibres GmbH exemplify the technology-forward archetype through wood-pulp integration and farm-to-fiber documentation capabilities. At the scale-driven end, Grasim Industries Limited and Tangshan Sanyou Xingda Chemical Fiber Co.,Ltd represent the cost-leadership tier through massive manufacturing complexes in India and China. These five entities collectively illustrate how competitive positioning diverges between premium sustainability verification and regional volume dominance.
| Leading Market Players |
|---|
| Tangshan Sanyou Xingda Chemical Fiber CO.,Ltd |
| Asia Pacific Rayon Limited |
| Lenzing AG |
| Jilin Chemical Fibre Group |
| Birla Cellulose |
| Grasim Industries Limited |
| Xinjiang Zhongtai Group |
| Kelheim Fibres GmbH |
| Sateri Holdings Limited |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between dissolving pulp producers and integrated fiber manufacturers lock in feedstock access while anchoring price visibility against Brazilian real volatility and Indonesian pulp supply concentration. These arrangements concentrate procurement leverage with backward-linked operators capable of spanning the pulp-to-fiber value chain.
Pricing Analysis
The customization-premium spread separates commodity-grade viscose from specialty variants engineered for medical and industrial specifications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from lyocell displacement in premium apparel segments where brands specify closed-loop solvent recovery. Fast-fashion spinners in Bangladesh and Vietnam exhibit highest price sensitivity, while medical textile manufacturers accept technical premiums for ANVISA-certified supply.
Supply Chain Analysis
Inbound logistics costs from Santos port congestion and Asia-Europe container tightness amplify landed cost differentials for Brazilian pulp feedstock. Geographic supply concentrates in Brazil, Indonesia, and China for dissolving pulp, with viscose fiber manufacturing anchored in India, China, and Indonesia. Raw material dependencies rest on eucalyptus pulp, carbon disulfide, and caustic soda. Single-source vulnerability runs through Brazilian pulp concentration exposing converters to currency swings. Distribution runs through direct mill relationships for volume accounts and merchant intermediaries for smaller converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The viscose staple fiber market is cycling through recovery as cotton price volatility accelerates substitution demand from apparel manufacturers seeking cost predictability.
For Market Incumbents: Secure captive dissolving pulp supply through equity partnerships or long-term offtake with Brazilian and Indonesian producers to defend against feedstock cost spikes. Invest in lyocell conversion capability ahead of tightening MEE emissions standards that will strand conventional viscose capacity lacking closed-loop solvent recovery. For New Entrants and Emerging Players: Anchor in Indonesia's emerging pulp-fiber-textile corridors in Sumatra, where tariff-advantaged export platforms serve ASEAN and Middle Eastern markets with limited legacy competition. Target medical textile grades for surgical gauze and wound care applications, where ANVISA and FDA certification requirements filter out undifferentiated commodity supply and command specialty pricing. For Investors and Strategic Acquirers: Specialty viscose producers with technical textile certifications and farm-to-fiber traceability systems represent the most defensible acquisition profile for long-term viability across the next decade. Monitor carbon border adjustment implementation velocity under the EU Green Deal as the inflection indicator for premium pricing power migration toward verified low-emission supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dissolving Pulp | Captive eucalyptus plantation control in Brazil insulates Grasim and Asia Pacific Rayon from feedstock cost volatility. |
| Lyocell Process Conversion | Closed-loop N-methylmorpholine N-oxide recovery positions Lenzing ahead of China's MEE wastewater mandates. |
| Carbon Accounting Certification | Farm-to-fiber blockchain documentation enables H&M Group and Inditex compliance with EU Green Deal border adjustments. |
| Medical Grade Specialization | ANVISA purity standards for surgical gauze create certification barriers that filter undifferentiated commodity supply. |
| ASEAN Corridor Expansion | Sumatra integrated clusters offer tariff-advantaged export platforms bypassing Bangladesh and Vietnam logistics chokepoints. |
Research Approach
A standing panel of plant managers at integrated fiber complexes, procurement leads at South Asian spinning mills, and technical R&D directors at dissolving pulp producers provided ongoing calibration across the study period. Primary interviews combined with secondary validation from customs trade data, CEFIC chemical industry reports, SEC filings of listed fiber producers, and MEE emissions disclosure databases. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. The analytical framework modeled segmentation across product grade tier, end-use industry, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules. Industry-specific forecast inputs included cotton-to-viscose substitution ratios and lyocell displacement trajectories in premium apparel.
Decision-makers should treat outputs as directional under assumptions of continued REACH enforcement intensity and China's dual carbon goal implementation; material deviation would warrant model refresh. Forecasts reflect assumptions of stable Brazilian real exchange rates and no major dissolving pulp supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Ultra-High Molecular Weight Polyethylene Fibers Market
Fibers
Viscose Market
Fibers
Thermoformed Fiber Market
Fibers
Keratin Market
Fibers
Dry-Molded Fibre Market
Fibers
Global Metal Fiber Market
Fibers
Global Concrete Fiber Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
Global Bicomponent Fiber Market
Fibers
Artificial Muscle Fibers Market
Fibers
4-Strand Fan-Shaped Strand Wire Rope Market
Fibers
Europe Carbon Fiber Market
Fibers
Fiber Metal Laminate (FML) Market
Fibers
Carbon Fiber Tapes Market
Fibers
Asia-Pacific Optical Fiber Raw Material Market
Fibers
Viscose Filament Yarn Market