
 Inlay Paper Market | 2026-2036
Inlay Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Inlay Paper Market Foresight
Premium-grade inlay substrates is rotating toward higher-brightness, lower-caliber variants engineered for dual-frequency RFID and NFC applications. Avery Dennison Corporation leverages its adhesive-coating infrastructure to dominate North American supply chains for wet inlay formats. HID Global Corporation anchors European demand through its secure-credential substrate partnerships with government ID programs. Zebra Technologies Corporation specializes in thermal-transfer-compatible inlay papers that serve retail and logistics end users.
Inlay paper constitutes a precision-caliber substrate, typically manufactured from bleached kraft pulp or cotton linters, engineered to carry embedded RFID chips and antennae with dielectric stability across 50–200 gsm basis weights. Its primary commercial purpose centers on enabling wireless item-level identification in supply chains, access credentials, and product authentication systems. Specialty paper substrates command the strongest margin pools due to customized dielectric constants and tear-resistance specifications demanded by pharmaceutical and luxury-goods clients. Coated paper formats lead volume shipments for standard retail tagging, while woodfree grades sustain demand in publishing-industry library and archival applications.
FDA serialization mandates for pharmaceutical track-and-trace elevate demand for tamper-evident inlay substrates in the United States. ECHA REACH compliance and EU Green Deal sourcing rules restrict certain chemical coatings in European inlay production, redirecting R&D toward bio-based barrier treatments. China's GB standards and SAMR quality certifications shape import-access conditions for foreign substrate suppliers. Stakeholders must monitor evolving electromagnetic-compatibility thresholds and polymer-substitution timelines to preserve formulation relevance and regional market access.
Market Dynamics
RFID serialization mandates across pharmaceutical supply chains are compressing substrate qualification timelines while elevating dielectric performance thresholds for inlay manufacturers.
Growth Catalysts
- Pharmaceutical Track-and-Trace Mandates:FDA Drug Supply Chain Security Act requirements for unit-level serialization are expanding addressable substrate volumes for tamper-evident inlay formats in the United States.
- EU Green Deal Sourcing Rules:Bio-based barrier coating specifications under ECHA REACH compliance are redirecting R&D investment toward sustainable pulp sourcing and water-based adhesive systems.
- Dual-Frequency RFID Convergence:UHF-NFC hybrid chip architectures are creating demand for engineered substrates with stable dielectric constants across 860-960 MHz and 13.56 MHz bands.
Market Restraints
- Bleached Kraft Pulp Volatility:Northern European pulp mill capacity constraints and energy cost fluctuations are compressing margin structures for specialty substrate grades.
- Electromagnetic Compatibility Thresholds:ETSI EN 302 208 and FCC Part 15 certification complexity is extending product development cycles for new inlay substrate formulations.
- Polymer Film Substitution:PET and PP synthetic substrates for harsh-environment tagging are capturing volume in industrial asset-tracking applications.
Strategic Opportunities
- India PLI Scheme for Electronics:Domestic semiconductor packaging incentives are creating import-substitution potential for RFID inlay substrate manufacturing.
- Luxury Goods Authentication:NFC-enabled product provenance systems for high-value watches and spirits are demanding premium cotton-linter substrates with embedded security fibers.
- Wet Inlay Format Expansion:Pressure-sensitive adhesive coating partnerships with label converters are opening direct-to-brand channel access beyond traditional dry inlay distribution.
Industry Challenges
- Dielectric Engineering Talent Scarcity:RF substrate design expertise combining papermaking science with antenna impedance matching remains concentrated among a limited pool of specialized engineers.
- Multi-Jurisdiction Certification Overlap:Simultaneous FDA, EMA, and SAMR serialization compliance requirements are fragmenting product qualification protocols and extending time-to-market.
- Legacy Thermal Transfer Integration:Backward compatibility with installed Zebra and Sato printer bases constrains substrate surface chemistry innovation for new coating formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inlay Paper Market |
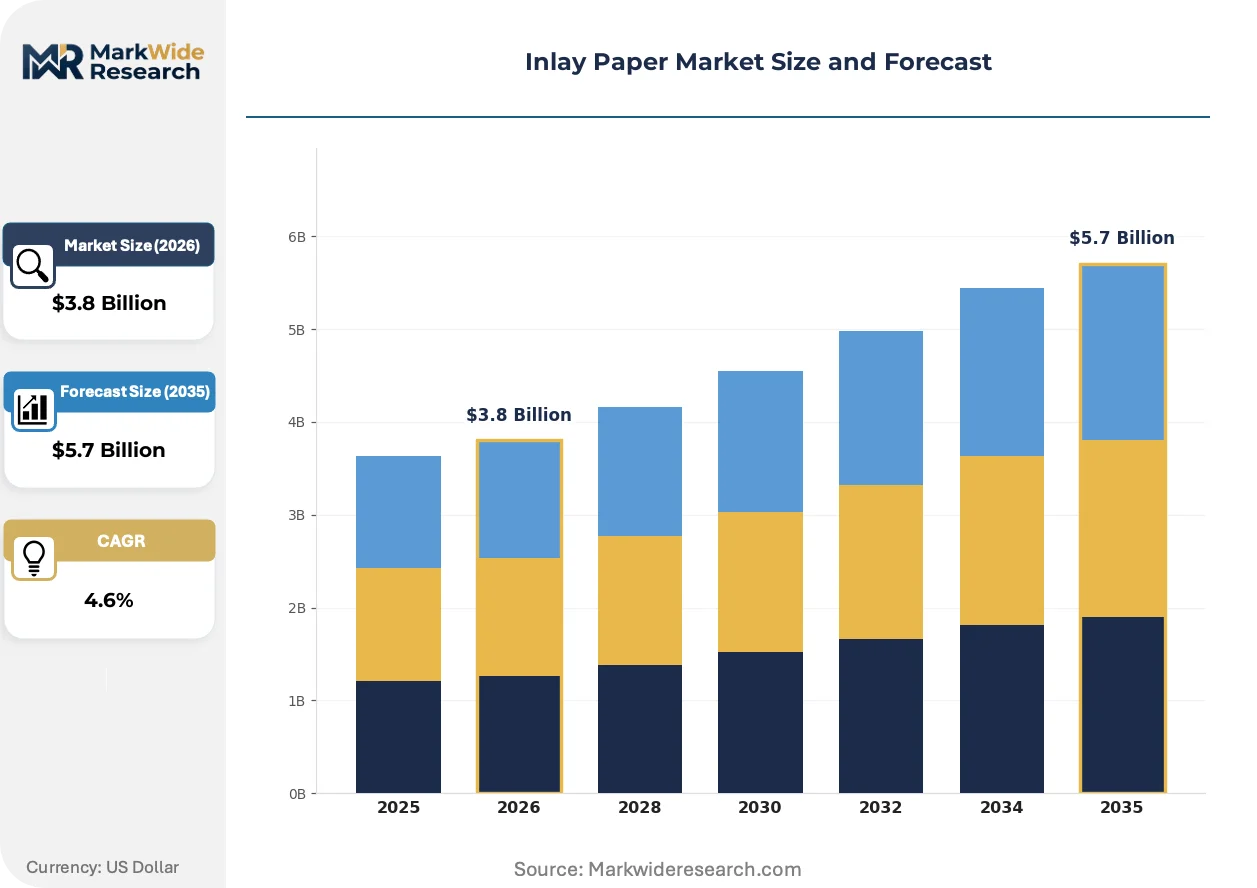
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woodfree Paper, Coated Paper, Uncoated Paper, Specialty Paper End User: Publishing Industry, Packaging Industry, Stationery Manufacturers, Advertising Agencies Packaging Type: Wraps, Envelopes, Boxes, Rolls Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Avery Dennison Corporation, HID Global Corporation, Alien Technology, Invengo Information Technology, Tageos, Lahnpaper GmbH, Zebra Technologies Corporation, Confidex, SML Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inlay Paper Market Shifts & Advancements
Substrate engineering is pivoting toward functional differentiation as commodity coating technologies face margin compression and end-users demand application-specific performance guarantees.
Advanced dielectric coating systems is bifurcating the competitive landscape between precision-caliber substrates for pharmaceutical serialization and cost-optimized grades for retail apparel tagging. Pharmaceutical contract packagers are specifying customized permittivity values within ±0.2 tolerance bands, while fast-fashion retailers are accepting wider variance for inventory management applications. This technical stratification is compressing mid-tier substrate suppliers into niche positioning or forced capability upgrades.
REACH Annex XVII restrictions on perfluorinated compounds are eliminating legacy grease-resistant barrier treatments from European inlay production lines. ECHA substance evaluation timelines are accelerating reformulation investments toward cellulose-based oil barriers and chitosan antimicrobial coatings. Wet inlay converters serving German automotive suppliers are absorbing 12-18 month requalification cycles to maintain OEM tier-one status.
Brand-direct procurement models are disintermediating traditional label converter channels for high-volume retail deployments. Walmart and Target are establishing substrate qualification programs that bypass converter specifications, creating direct supplier relationships with Avery Dennison and HID Global for private-label RFID programs. This channel compression is most visible in United States apparel and general merchandise categories where annual tag volumes exceed 500 million units.
Inlay Paper Market Segmentation
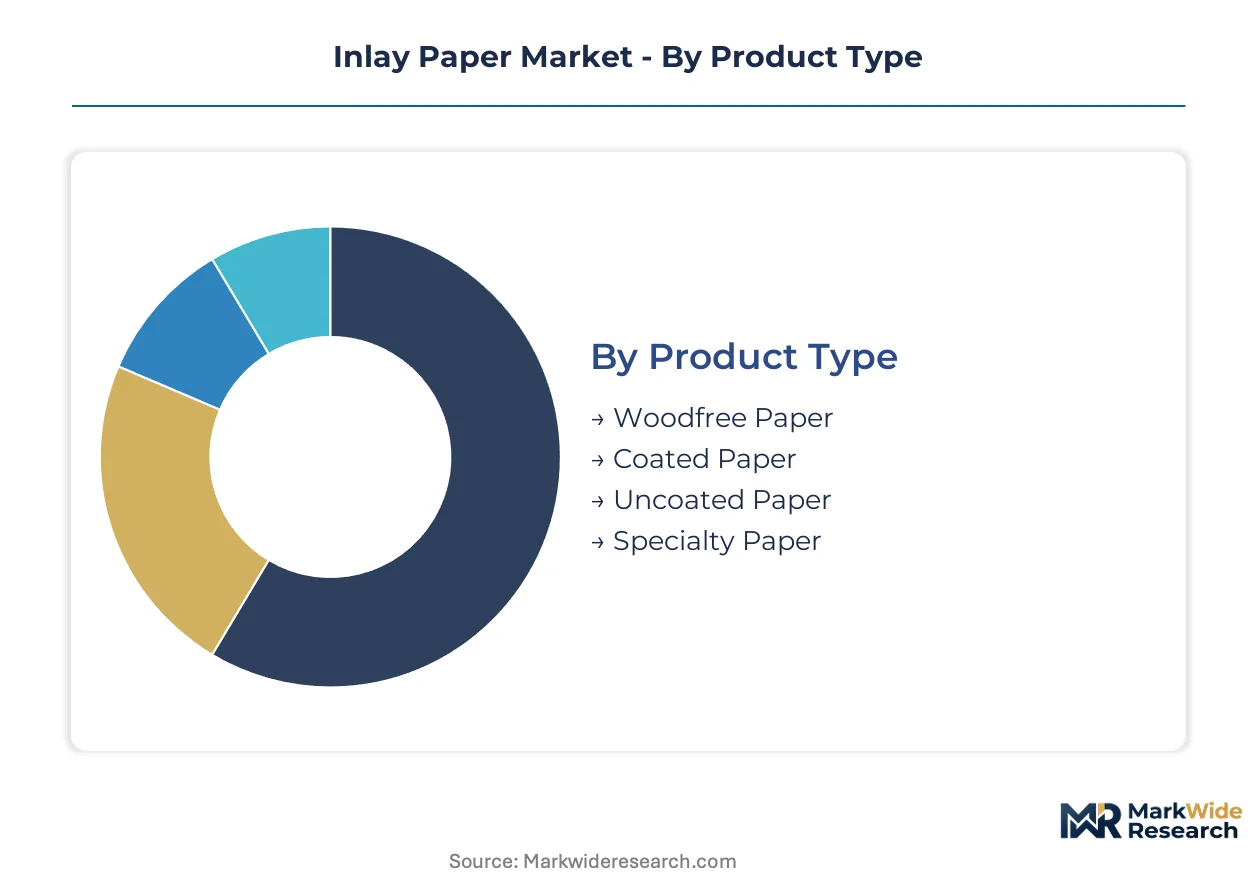
Inlay paper segmentation reveals divergent margin structures across substrate engineering tiers and channel configurations. Pharmaceutical serialization and luxury authentication applications command premium pricing through customized dielectric specifications, while retail inventory tracking segments compete on coating consistency and converter integration speed.
Product Type:
Specialty paper substrates capture the deepest margin pools due to engineered dielectric constants and tear-resistance specifications demanded by pharmaceutical and luxury-goods clients.
- Specialty Paper:Manufactured from bleached kraft pulp or cotton linters with precision-caliber dielectric stability across 50–200 gsm basis weights. Demand concentrates in pharmaceutical serialization for FDA-mandated track-and-trace systems and NFC-enabled luxury watch authentication where customized permittivity tolerances of ±0.2 are specified.
- Coated Paper:Pressure-sensitive adhesive-compatible formats engineered for thermal-transfer printing compatibility. Volume concentrates in United States apparel retail through Walmart and Target private-label RFID programs where annual tag volumes exceed 500 million units and converter bypass models are displacing traditional distribution.
- Woodfree Paper:Archival-grade substrates sustaining demand in library and publishing-industry applications with lignin-free composition for long-term document preservation.
- Uncoated Paper:Cost-optimized grades for standard inventory management applications accepting wider dielectric variance in fast-fashion retail environments.
Specialty paper holds installed capacity. Coated paper is rotating up the share rankings.
End User:
Packaging industry applications generate the highest revenue concentration through pharmaceutical contract packaging specifications and brand-direct procurement models.
- Packaging Industry:Pharmaceutical serialization mandates under FDA DSCA and EMA track-and-trace requirements drive substrate qualification for tamper-evident inlay formats. German automotive suppliers specify REACH-compliant wet inlay formats with 12-18 month OEM requalification cycles.
- Publishing Industry:Library and archival systems deploy woodfree substrates for long-term document RFID tagging with backward compatibility requirements for installed printer bases constraining surface chemistry innovation.
- Stationery Manufacturers:Premium cotton-linter substrates with embedded security fibers serve high-value credential and certificate applications.
- Advertising Agencies:NFC-enabled promotional materials and interactive print campaigns utilizing dual-frequency UHF-NFC hybrid chip architectures.
Packaging industry volume dominates current procurement. Publishing industry applications are climbing the fastest as archival digitization accelerates.
Packaging Type:
Roll formats command supply chain efficiency advantages through continuous-feed converter operations and automated antenna embedding processes.
- Rolls:Continuous-web substrates enabling high-speed rotary die-cutting and wet inlay coating lines at Avery Dennison and converter partners across North American supply chains.
- Envelopes:Pre-converted formats for secure credential and pharmaceutical sample distribution with integrated tamper-evident features.
- Wraps:Flexible packaging applications for retail apparel and general merchandise tagging with pressure-sensitive adhesive backing.
- Boxes:Rigid substrate formats for luxury goods authentication and high-value product provenance systems.
Rolls maintain production scale leadership. Envelopes are gaining share fastest through secure logistics channel expansion.
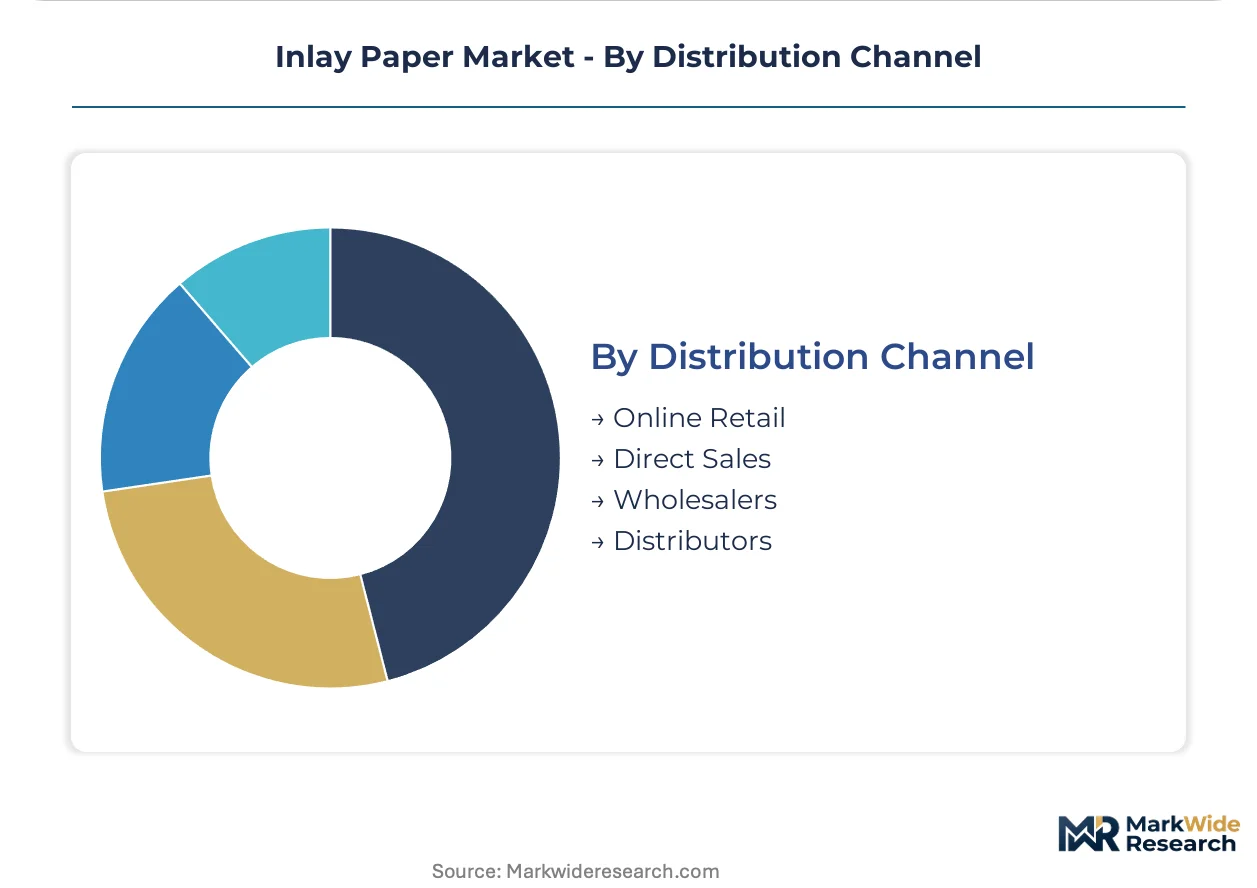
Distribution Channel:
Direct sales relationships are displacing traditional converter intermediation as brand-direct procurement models compress channel economics.
- Direct Sales:Walmart and Target qualification programs bypass traditional label converter specifications to establish direct supplier relationships with substrate manufacturers for private-label RFID deployments.
- Distributors:Regional inventory positioning for mid-volume pharmaceutical and retail customers requiring rapid substrate qualification and technical support.
- Wholesalers:Bulk volume aggregation for standard-grade coated paper formats serving cost-optimized retail inventory management segments.
- Online Retail:E-procurement platforms for small-volume stationery and advertising agency customers with standardized specification requirements.
Direct sales holds the deepest account relationships. Distributor channels are expanding most quickly through technical service differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in inlay paper substrates track closely to RFID converter capacity and pharmaceutical serialization mandates. Germany and China maintain trade surpluses in specialty grades, while the United States absorbs premium volumes for FDA-compliant track-and-trace applications.
United States
FDA DSCA unit-level serialization deadlines drive pharmaceutical contract packagers toward tamper-evident inlay substrates with precise dielectric tolerances. FCC Part 15 electromagnetic compatibility certification creates entry barriers for foreign substrate suppliers. Converter clusters in Ohio and Illinois process wet inlay formats for Walmart and Target private-label RFID programs exceeding 500 million annual units.
Germany
ECHA REACH Annex XVII restrictions on perfluorinated compounds force reformulation of grease-resistant barrier coatings toward cellulose-based alternatives. OEM automotive suppliers in Stuttgart and Munich impose 12-18 month requalification cycles on wet inlay converters to maintain tier-one status. Bavarian pulp mills supply bleached kraft fiber for high-brightness specialty grades serving luxury goods authentication.
China
GB standards and SAMR quality certifications shape import-access conditions for foreign substrate manufacturers seeking participation in domestic RFID deployment. Yangtze River Delta converter clusters in Shanghai and Jiangsu province scale production of cost-optimized coated papers for retail inventory management. Dual carbon goals redirect state-backed R&D toward bio-based adhesive systems and sustainable pulp sourcing.
India
PLI scheme incentives for domestic semiconductor packaging create import-substitution potential for RFID inlay substrate manufacturing. CDSCO pharmaceutical track-and-trace requirements elevate demand for serialization-compatible substrates in contract packaging hubs. Maharashtra and Gujarat host emerging converter operations serving apparel retail and logistics end users with pressure-sensitive adhesive formats.
Japan
METI industrial standards and PMDA pharmaceutical serialization rules sustain demand for premium cotton-linter substrates with embedded security fibers. Kanto region converter clusters around Tokyo supply NFC-enabled authentication systems for high-value watches and spirits. JIS certification requirements preserve technical barriers protecting domestic specialty paper manufacturers from commodity-grade imports.
Inlay Paper Market Competitive Landscape
Concentration sits with adhesive-coating specialists and secure-credential substrate partners that control qualification relationships with pharmaceutical and retail end users. The vendor base spans three tiers: integrated materials-science conglomerates with global converter networks, regional wet inlay specialists serving automotive and logistics verticals, and niche cotton-linter producers targeting luxury authentication. Dominant competitive moves include strategic partnerships with brand-direct procurement programs and capacity expansion in India and Southeast Asia to capture PLI scheme benefits.
Within the integrated materials-science tier, Avery Dennison Corporation and Zebra Technologies Corporation exemplify players leveraging North American adhesive-coating infrastructure and thermal-transfer printer compatibility requirements to defend account relationships. HID Global Corporation anchors a distinct archetype focused on secure-credential substrate partnerships with government ID programs across European markets. Regional specialists including Lahnpaper GmbH occupy positions serving German automotive OEM requalification cycles, while Invengo Information Technology represents Asia-Pacific-based fabricators scaling for domestic RFID deployment under Chinese certification regimes.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| HID Global Corporation |
| Alien Technology |
| Invengo Information Technology |
| Tageos |
| Lahnpaper GmbH |
| Zebra Technologies Corporation |
| Confidex |
| SML Group |
| Others |
Supply & Pricing Matrix
FDA DSCA serialization mandates gate both substrate qualification timelines and price differentiation between pharmaceutical-grade and retail-grade inlay formats. EMA track-and-trace requirements in Europe and SAMR certifications in China create parallel compliance-cost structures that segment pricing power by end-use application and geographic market access.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Pharmaceutical contract packagers purchasing FDA-compliant specialty substrates with ±0.2 permittivity tolerances face the least price sensitivity, while fast-fashion retailers accepting wider dielectric variance drive cost compression in coated paper tiers. Price differentiation rests on certification grade and customization level, with REACH-compliant bio-based barrier coatings commanding sustained premiums against legacy formulations. Margins are tightening in mid-tier coated paper segments as Walmart and Target direct-procurement programs compress converter markups.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes elevate inbound logistics costs for bleached kraft pulp shipments to North American converter clusters. Supply concentrates in Germany, China, and the United States, with Bavarian pulp mills and Yangtze River Delta coating operations feeding global wet inlay production. Raw material dependencies draw from Northern European pulp fiber, pressure-sensitive adhesive resins, and RFID chip antennae substrates. Single-source vulnerability in specialty cotton-linter grades for luxury authentication applications presents structural risk. Distribution runs through direct brand relationships and regional distributor networks serving pharmaceutical and retail end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as pharmaceutical serialization mandates compress replacement cycles and elevate substrate refresh rates across installed converter bases.
For Market Incumbents: Secure qualification relationships with brand-direct procurement programs at major retailers to defend against channel disintermediation. Prioritize backward integration into sustainable pulp sourcing to meet EU Green Deal compliance timelines and offset energy cost volatility in European mill operations. Invest in dielectric engineering talent retention as RF substrate design expertise concentrates among limited specialized pools. For New Entrants and Emerging Players: Differentiate on REACH-compliant bio-based barrier coatings to capture reformulation demand from German automotive and pharmaceutical OEMs facing 12-18 month requalification cycles. Target India's PLI scheme incentives for domestic semiconductor packaging to establish import-substitution manufacturing capacity. Pursue wet inlay converter partnerships as the most penetrable channel for bypassing incumbent direct-sales lockups. For Investors and Strategic Acquirers: ECHA Annex XVII perfluorinated compound restrictions reshape the acquisition landscape toward cellulose-based oil barrier specialists with proven OEM requalification track records. Five-to-ten year viability favors regional wet inlay specialists serving automotive tier-one status requirements over commodity-coated paper operations exposed to retail price compression. Monitor electromagnetic compatibility certification backlog at ETSI and FCC as an inflection indicator for product development cycle delays that would strain working capital at target firms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sustainable Pulp Sourcing | Ensures EU Green Deal compliance for German automotive supplier contracts. |
| Dielectric Engineering Talent Acquisition | Addresses scarcity of RF substrate design expertise combining papermaking and antenna impedance matching. |
| Wet Inlay Converter Partnership Expansion | Opens direct-to-brand channel access beyond traditional dry inlay distribution networks. |
| India PLI Scheme Manufacturing Scale-Up | Captures domestic semiconductor packaging incentives for RFID inlay substrate production. |
| REACH-Compliant Bio-Based Barrier R&D | Accelerates reformulation investments toward cellulose-based alternatives for European market access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from substrate manufacturers, ECHA substance evaluation databases, and FDA DSCA guidance documents. Primary interviews engaged dielectric engineers at inlay converters, procurement leads at pharmaceutical contract packagers, technical R&D directors at adhesive coating operations, and regulatory affairs specialists at RFID chip manufacturers. Bottom-up volume modeling triangulated against top-down market sizing derived from pulp mill capacity disclosures and converter shipment patterns.
Segmentation dimensions modeled include substrate engineering tier, end-use application, packaging format configuration, and regional regulatory cluster across the analysis window. CAGRs were derived from trend extrapolation of qualification timelines, substitution elasticity estimates for polymer film alternatives, and capacity expansion announcements. Forecast inputs incorporated pharmaceutical serialization mandate deadlines, electromagnetic compatibility certification throughput rates, and bio-based coating reformulation investment cycles.
Forecasts assume regulatory continuity in FDA DSCA, EMA track-and-trace, and ECHA REACH regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Coating Materials Market
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
Wood-Based Panel Market
Paper Products
Dissolving Pulp Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Africa Tissue Paper Market
Paper Products
Global Kraft Paper Market
Paper Products
Decor Paper Market
Paper Products
Thin Printing Paper Market
Paper Products
Carbonless Paper Market
Paper Products
Stone Paper Market
Paper Products
Filtration Paper Market
Paper Products
Specialty Paper Market
Paper Products
Global Paper Chemical Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Leatheroid Paper Market