
 Filter Paper Market | 2026-2036
Filter Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Filter Paper Market Foresight
A shift from single-source cellulose supply contracts toward multi-source agreements spanning cellulose and synthetic feedstocks is realigning procurement economics for filter paper converters. Ahlstrom-Munksjö leverages its Nordic pulp integration to control raw material quality for laboratory grades. Sartorius AG anchors its position through membrane-filter hybrid portfolios that compete directly with traditional paper media in pharmaceutical validation protocols. Glatfelter differentiates via specialty wet-laid nonwoven capabilities that extend its reach beyond conventional air and liquid filtration into diagnostic substrates.
Filter paper consists of porous sheet media engineered from cellulose fibers, synthetic polymers, or glass microfibers with defined pore size ratings, thickness, and ash content specifications; manufacturers form these sheets through wet-laid processes followed by calendering or resin bonding to achieve precise flow rates and particle retention for analytical separation and industrial clarification tasks. Qualitative grades retain their dominance in educational and routine testing environments where exact gravimetric recovery is unnecessary, while glass fiber segments capture the fastest expansion as environmental monitoring protocols and pharmaceutical sterility testing migrate toward binder-free borosilicate media with superior thermal and chemical resistance. Specialty filter papers concentrate margin pools where customized surface chemistries or pre-activated layers command premium positioning in point-of-care diagnostic and food safety applications.
ISO 9001 quality management frameworks govern manufacturing consistency across export-oriented producers, while FDA 21 CFR Part 211 compliance shapes product validation requirements for pharmaceutical end users seeking filter paper with documented extractables and compatibility profiles. The EPA's reference methods for particulate and dissolved contaminant analysis directly specify certified filter media grades, creating a regulated demand floor for environmental testing laboratories. Stakeholders must monitor how evolving bioprocessing single-use system standards and tightening particulate limits in injectable drug manufacturing redirect material specifications toward synthetic and composite substrates that challenge traditional cellulose incumbency.
Market Dynamics
Pharmaceutical sterility testing mandates are compressing material qualification timelines while simultaneously elevating performance thresholds for particulate retention and extractables documentation across filter paper supply chains.
Growth Catalysts
- FDA 21 CFR Part 211 compliance:Injectable drug manufacturers now require filter papers with validated extractables profiles, creating a regulated demand floor for certified laboratory grades.
- Glass microfiber technology:Environmental monitoring laboratories are migrating toward borosilicate media for thermal and chemical resistance in air quality protocols.
- German chemical manufacturing clusters:Concentrated laboratory infrastructure in Rhineland and Bavaria sustains above-average consumption of quantitative filter grades.
Market Restraints
- Cellulose pulp price volatility:Nordic pulp integration controls quality but exposes converters to commodity fiber cost swings.
- Membrane filter substitution:Synthetic polymer membranes are capturing share in pharmaceutical validation workflows previously served by cellulose.
- REACH chemical registration burdens:European specialty coating chemistries face extended compliance timelines that delay product launches.
Strategic Opportunities
- Point-of-care diagnostic substrates:Pre-activated surface chemistries command premium positioning in lateral flow devices.
- India's expanding CDMO sector:Contract development and manufacturing organizations are building quality control laboratories requiring imported quantitative grades.
- EPA reference method alignment:Certified filter media for particulate analysis creates recurring revenue streams in environmental testing.
Industry Challenges
- Extractables validation expertise:Pharmaceutical customers demand documented compatibility studies that strain analytical chemistry capacity at mid-tier converters.
- Wet-laid nonwoven equipment retrofitting:Specialty grade production requires capital-intensive machine modifications for thickness and porosity precision.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filter Paper Market |
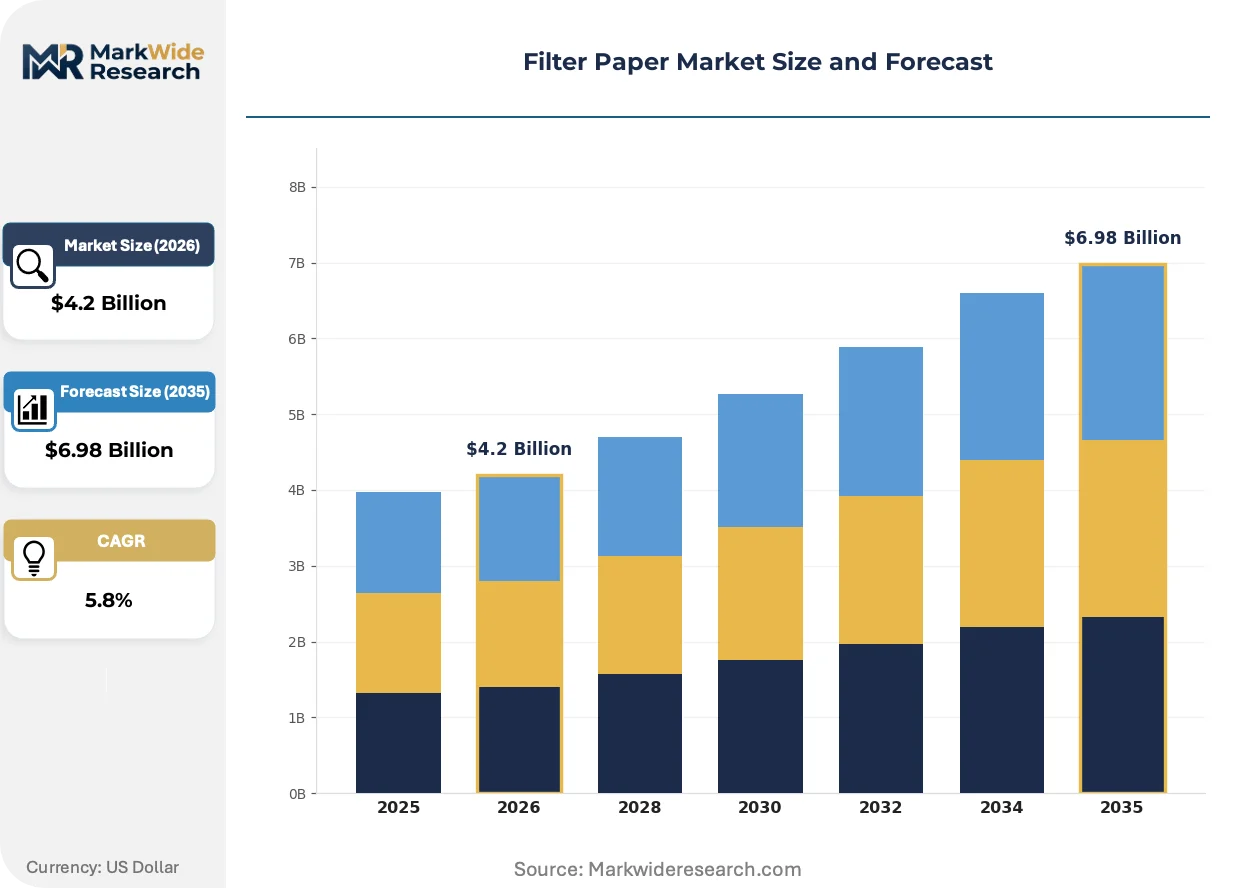
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $6.98 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Qualitative, Quantitative, Specialty, Glass Fiber Application: Laboratory, Industrial, Environmental, Pharmaceutical Material: Cellulose, Synthetic, Composite, Microfiber End User: Research Institutions, Academia, Pharmaceutical Companies, Food Industry |
| Companies Covered | Rockline Industries, Sartorius AG, Ahlstrom-Munksjö, Purico, Hahnemühle, Glatfelter, Twin Rivers Paper Company, Terranova Papers, Melitta Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filter Paper Market Shifts & Advancements
Material science advances and regulatory stringency are rewriting performance specifications while procurement patterns fragment traditional supply relationships.
Cellulose nanofiber reinforcement is converging with synthetic polymer binders to create hybrid filter media with enhanced mechanical strength and defined pore structures. Bioprocessing single-use system manufacturers are piloting these composites for sterile filtration applications. The structural consequence is converging with traditional membrane territory, compressing the performance gap between paper and polymer technologies.
REACH restrictions on perfluorinated compounds are forcing reformulation of hydrophobic surface treatments used in air monitoring filters. Industrial hygiene laboratories must qualify replacement chemistries without disrupting EPA reference method compliance. Glass fiber segments in European environmental testing are responding fastest, leveraging inherent hydrophobicity without additive coatings.
Multi-source feedstock agreements are displacing single-source cellulose contracts as procurement risk management tools. Large pharmaceutical buyers now require documented supply redundancy spanning Nordic pulp and synthetic fiber sources. This pattern is most visible in German and Swiss laboratory supply chains, where quality managers audit upstream pulp provenance alongside finished good performance data.
Filter Paper Market Segmentation
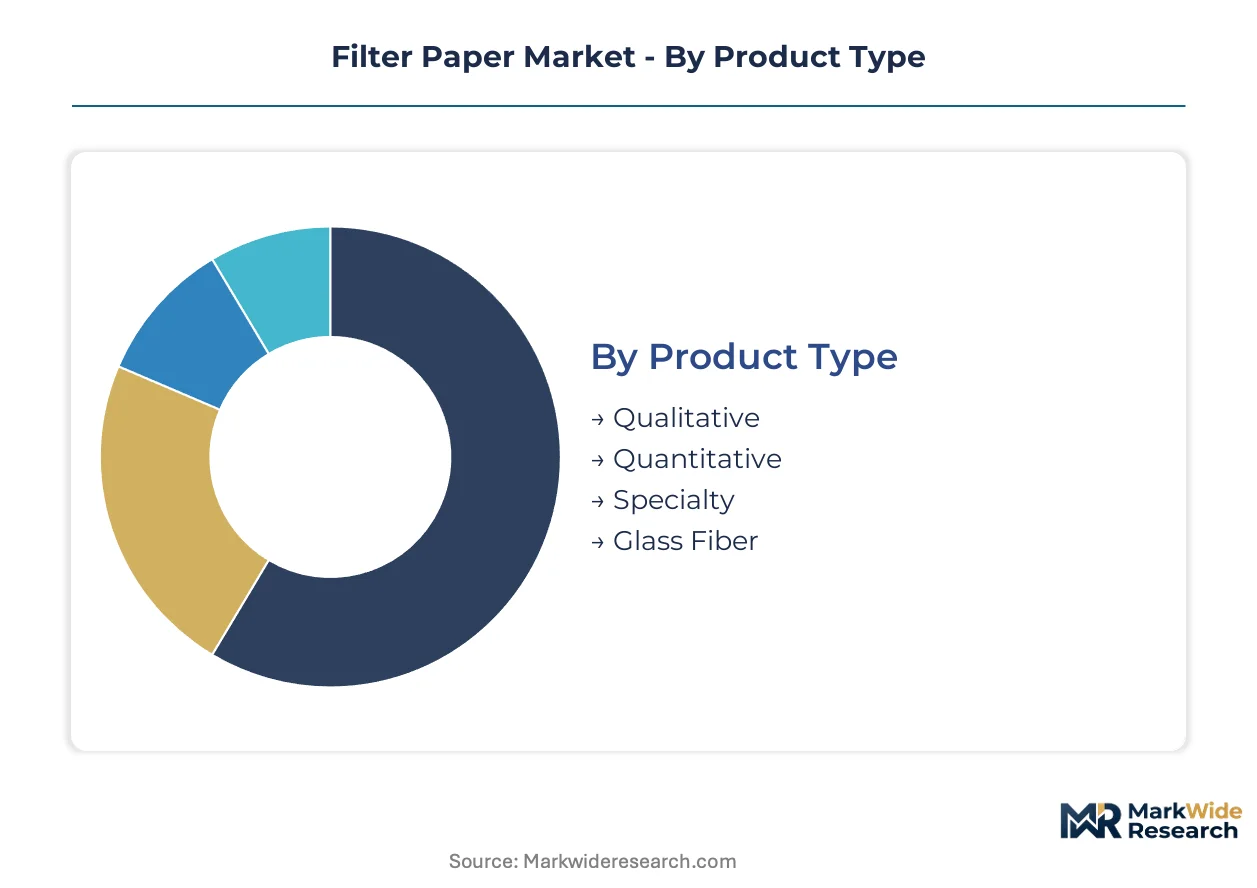
Filter paper procurement decisions hinge on balancing analytical precision requirements against total cost of ownership, with specification-grade segments commanding premiums while commodity grades drive volume economics. Segmentation clarity enables converters to align wet-laid production assets with end-use validation protocols and regional regulatory frameworks.
Product Type:
Volume concentrates in educational and routine testing grades, while premium positioning accrues to certified laboratory and diagnostic substrates.
- Qualitative:Ungraded cellulose sheets with undefined ash content serve educational laboratories and routine separations where exact gravimetric recovery is unnecessary. Demand clusters in India's expanding academic infrastructure and secondary school science programs across Southeast Asia, constrained by procurement budgets that prioritize cost over certification.
- Quantitative:Ashless cellulose media with defined particle retention ratings support gravimetric analysis in German chemical manufacturing clusters and Swiss pharmaceutical quality control workflows. FDA 21 CFR Part 211 compliance mandates for documented extractables profiles are elevating procurement specifications for validated grades.
- Specialty:Pre-activated surface chemistries and customized porosities command premium positioning in lateral flow diagnostic devices.
- Glass Fiber:Binder-free borosilicate media with superior thermal resistance are gaining share in environmental air monitoring protocols.
Today's leader: Quantitative. Tomorrow's challenger: Glass Fiber.
Application:
Certification requirements fragment demand across validation-intensive pharmaceutical workflows versus cost-sensitive industrial clarification.
- Laboratory:Analytical separation tasks in research institutions and quality control facilities require documented performance consistency. German Rhineland and Bavaria laboratory infrastructure sustains above-average consumption of quantitative and glass fiber grades.
- Pharmaceutical:Sterile filtration and parenteral drug particulate testing mandate validated extractables documentation. FDA guidance on injectable manufacturing is compressing material qualification timelines while elevating performance thresholds.
- Industrial:Process clarification and air filtration in chemical manufacturing prioritize throughput economics over analytical precision.
- Environmental:EPA reference methods for particulate analysis specify certified filter media grades, creating recurring demand floors in testing laboratories.
Pharmaceutical applications extract the highest margins; environmental monitoring offers the steadiest replacement cycles.
Material:
Feedstock selection determines compatibility profiles and supply chain risk exposure across cellulose-dependent versus synthetic-resilient specifications.
- Cellulose:Nordic pulp integration controls raw material quality for laboratory grades but exposes converters to commodity fiber cost volatility.
- Microfiber:Glass microfiber technology delivers thermal and chemical resistance for environmental monitoring without hydrophobic coating dependencies.
- Synthetic:Polymer membranes are capturing share in pharmaceutical validation workflows previously served by cellulose incumbents.
- Composite:Cellulose nanofiber reinforcement converging with synthetic binders creates hybrid media for bioprocessing single-use applications.
Cellulose retains volume dominance; composites are climbing the fastest as membrane-paper boundaries blur.
End User:
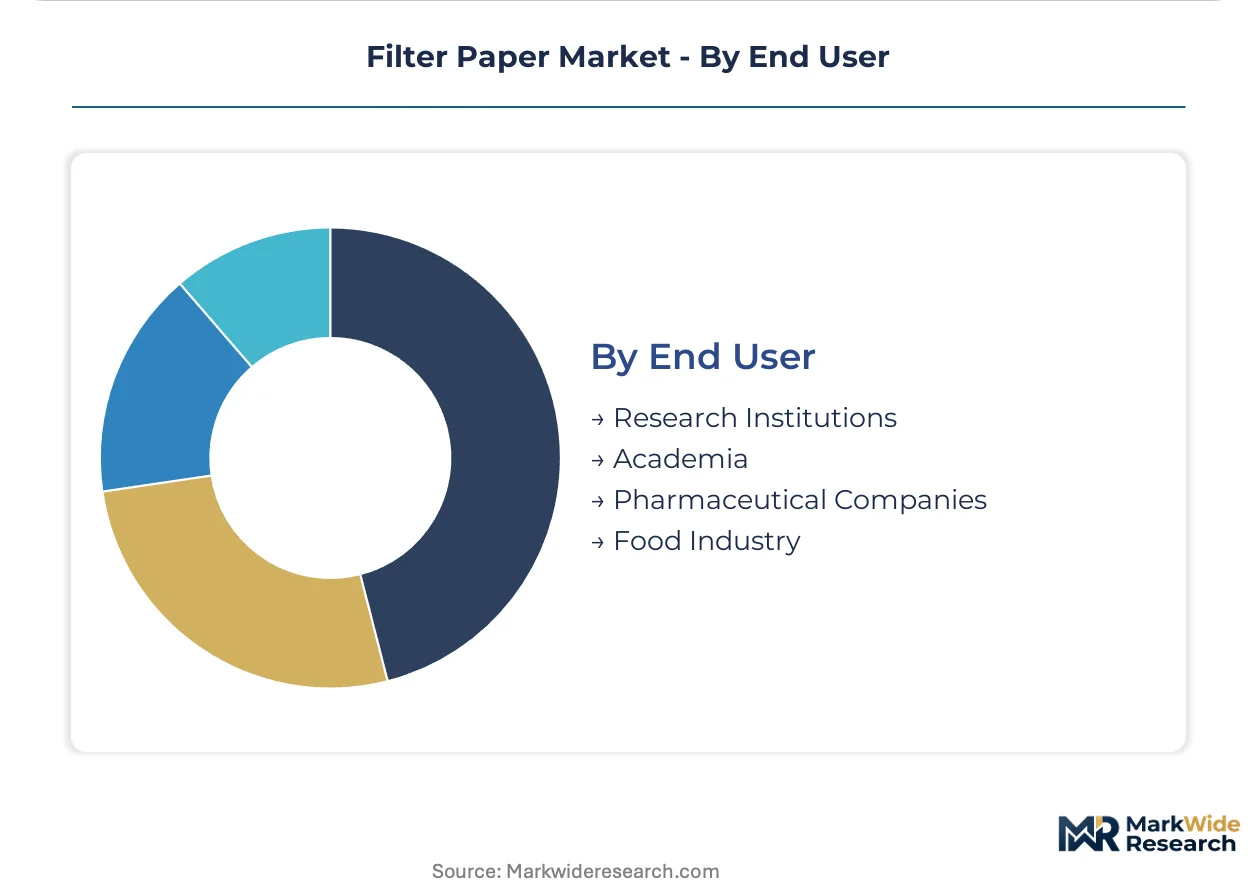
Procurement sophistication varies from standardized academic supply contracts to customized pharmaceutical validation protocols.
- Pharmaceutical Companies:Injectable drug manufacturers require filter papers with validated extractables profiles and documented compatibility studies. Multi-source feedstock agreements spanning Nordic pulp and synthetic fibers are displacing single-source contracts as risk management tools.
- Research Institutions:National laboratories and contract research organizations balance analytical precision requirements against grant-funded budget constraints.
- Academia:Educational institutions prioritize cost-efficient qualitative grades for teaching laboratories.
- Food Industry:Safety testing protocols drive demand for certified media in contaminant analysis workflows.
Pharmaceutical buyers set the specification ceiling; academic volume sustains converter utilization rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting filter paper procurement toward jurisdictions where REACH compliance costs and FDA validation timelines create divergent cost structures for laboratory-grade production.
Germany
Rhineland and Bavaria chemical manufacturing clusters sustain concentrated demand for quantitative and glass fiber filter grades. ECHA registration requirements for specialty coating chemistries compress product launch timelines for European converters. Frankfurt and Munich laboratory infrastructure anchors above-average consumption of ashless cellulose media for gravimetric analysis workflows.
United States
Injectable drug manufacturers in the Northeast and Mid-Atlantic corridors drive demand for validated extractables documentation under FDA 21 CFR Part 211. EPA reference methods for particulate analysis create recurring procurement floors in environmental testing laboratories. Boston and Philadelphia pharmaceutical quality control facilities are migrating toward multi-source feedstock agreements spanning Nordic pulp and synthetic fibers.
China
NMPA pharmaceutical manufacturing standards are elevating import requirements for quantitative filter grades in bioprocessing applications. Yangtze River Delta contract development organizations are building analytical chemistry capacity requiring certified laboratory media. Shanghai and Suzhou laboratory supply chains are diversifying away from single-source cellulose contracts toward hybrid feedstock portfolios.
India
CDMO sector expansion in Maharashtra and Gujarat is generating quality control laboratory buildouts requiring imported quantitative grades. BIS certification timelines for laboratory consumables create procurement friction for domestic converters. Mumbai and Ahmedabad pharmaceutical clusters are prioritizing FDA-aligned validation protocols for sterile filtration workflows.
Switzerland
Swissmedic pharmaceutical manufacturing standards anchor premium positioning for validated filter media in parenteral drug testing. Basel and Zurich quality control infrastructure sustains above-average consumption of specialty grades with documented compatibility profiles. Swiss laboratory buyers are auditing upstream pulp provenance alongside finished good performance data.
Filter Paper Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue diagnostic substrate specialization and composite material hybrids. The market structures around three maturity tiers: integrated pulp-to-paper converters with captive Nordic fiber supply, membrane-filter hybrid specialists competing at the paper-polymer boundary, and wet-laid nonwoven fabricators extending into diagnostic applications. Dominant competitive moves include backward integration into pulp sourcing and strategic partnerships with bioprocessing single-use system manufacturers.
Within the integrated converter tier, Ahlstrom-Munksjö and Glatfelter occupy positions exemplifying Nordic pulp integration and specialty wet-laid capabilities respectively. Sartorius AG anchors the membrane-paper hybrid vector, representing competitive pressure from synthetic polymer technologies. These three entities illustrate the strategic divergence between cellulose incumbency and synthetic substitution patterns reshaping procurement specifications.
| Leading Market Players |
|---|
| Rockline Industries |
| Sartorius AG |
| Ahlstrom-Munksjö |
| Purico |
| Hahnemühle |
| Glatfelter |
| Twin Rivers Paper Company |
| Terranova Papers |
| Melitta Group |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FDA-validated quantitative media and ungraded educational cellulose creates parallel pricing universes that map onto entirely different supply chain configurations. Pharmaceutical buyers absorb premium positioning for documented extractables profiles while academic procurement in India and Southeast Asia prioritizes volume economics over certification.
Pricing Analysis
Distributor margins of 25-35% separate OEM direct contracts from laboratory supply house transactions across German and Swiss procurement channels. Pricing stratifies across premium validated grades, standard laboratory tiers, and economy educational levels, with differentiation driven by ash content precision and FDA 21 CFR Part 211 documentation completeness. Cost compression in commodity qualitative grades is intensifying because Indian CDMOs are forcing volume discounts on imported ashless media. Academic buyers in Maharashtra and Gujarat exhibit highest price sensitivity; Swiss pharmaceutical quality control facilities show least.
Supply Chain Analysis
FDA and EPA qualification gating restricts viable suppliers to converters with documented pulp provenance and validated wet-laid production protocols. Geographic concentration centers on Finland and Sweden for Nordic pulp integration, Germany for quantitative grade finishing, and the United States for pharmaceutical validation workflows. Raw material dependencies rest on bleached softwood kraft pulp, borosilicate glass microfiber feedstock, and synthetic polymer binders for composite grades. Single-source cellulose vulnerability persists as large buyers demand multi-source redundancy. Distribution runs through laboratory supply distributors in Europe and direct OEM contracts in North American pharmaceutical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Filter Paper Market functions as a stable compounder where regulatory validation requirements create recurring replacement demand that compounds predictably across pharmaceutical and environmental testing workflows.
For Market Incumbents: Deploy backward integration into Nordic pulp sourcing to defend margin position against commodity fiber volatility. Anchor capacity in German Rhineland and Bavaria clusters to capture pharmaceutical quality control demand. Invest in extractables validation laboratories to meet FDA 21 CFR Part 211 documentation requirements that synthetic membrane competitors exploit. Control channel relationships with Swissmedic-aligned buyers in Basel and Zurich. For New Entrants and Emerging Players: The price-point gap between Sartorius-grade premium membranes and Indian-imported qualitative cellulose creates white-space opportunity for mid-tier validated grades. Target Maharashtra and Gujarat CDMO buildouts requiring quantitative media without Swiss-level certification premiums. Pursue point-of-care diagnostic substrate specialization where pre-activated surface chemistries command positioning. Partner with Yangtze River Delta bioprocessing single-use system manufacturers for composite media pilot programs. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier converters lack extractables validation capacity to serve pharmaceutical procurement specifications. Frame long-term viability around regulatory validation moats that compound replacement revenue across environmental monitoring and sterile filtration workflows. Target acquisition archetype: wet-laid nonwoven fabricators with diagnostic substrate capabilities and untapped pharmaceutical certification pathways. Watch for inflection when EPA reference method revisions mandate new particulate retention specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Nordic fiber sourcing secures quality consistency for laboratory-grade production against commodity volatility. |
| Extractables Validation Laboratory Investment | FDA 21 CFR Part 211 documentation capabilities unlock pharmaceutical procurement specifications. |
| Diagnostic Substrate Specialization | Pre-activated surface chemistries capture premium positioning in lateral flow device manufacturing. |
| Multi-Source Feedstock Agreements | Supply redundancy spanning cellulose and synthetic fibers satisfies pharmaceutical risk management protocols. |
| EPA Reference Method Alignment | Certified particulate analysis media create recurring revenue streams in environmental testing laboratories. |
Research Methodology
Direct dialogue with filter paper procurement managers at pharmaceutical quality control facilities, laboratory supply distributors, wet-laid nonwoven production engineers, and regulatory affairs specialists at CDMOs grounded qualitative findings. Secondary validation drew from FDA 21 CFR guidance documents, EPA reference method specifications, ECHA REACH registration databases, and customs trade data for laboratory consumables. Bottom-up demand modeling across end-use segments triangulated against top-down market sizing from pulp consumption and filtration media production capacity.
Bottom-up volume builds aggregated segment demand across pharmaceutical sterile filtration, environmental monitoring, laboratory analytical separation, and diagnostic substrate applications. Top-down cross-checks rest on Nordic pulp production allocation to specialty paper grades and wet-laid nonwoven capacity utilization across European and North American converters. Segmentation dimensions include product type tier, application validation intensity, material feedstock category, and end-user procurement sophistication. CAGRs derive from regression analysis of historical pharmaceutical manufacturing expansion and environmental testing laboratory buildouts across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for cellulose nanofiber-synthetic polymer composites would alter the outlook if bioprocessing single-use system standards accelerate membrane-paper convergence. Forecasts reflect assumptions about regulatory validation timeline stability and pulp commodity price mean reversion. A model refresh is warranted upon material change in FDA particulate testing guidance or ECHA perfluorinated compound restriction enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Chloramine Filter Market
Filters
Fabric Filters Market
Filters
Aerospace Filter Market
Filters
Global Pleated Filters Market
Filters
Global Industrial Filters Market
Filters
Diatomaceous Filter Aid Market
Filters
Industrial Filter Paper Market
Filters
Activated Carbon Filter Market
Filters
Global Laboratory Filtration Market
Filters
United States Activated Carbon Market
Filters
Global Gas Phase Filtration Market
Filters
Europe Activated Carbon Market
Filters
North America Gas Filtration Media Market
Filters
Hydraulic Filters Market
Filters
Intake Filter Media Market
Filters
Activated Carbon Market