
 Veneer Sheets Market | 2026-2036
Veneer Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Veneer Sheets Market Analysis
Aftermarket veneer refurbishment and re-lamination services is rewriting margin capture across the value chain, pulling profitability away from first-sale manufacturing. Louisiana-Pacific Corporation leverages its integrated timberland base to control raw material flows from harvest to sheet production. Columbia Forest Products sustains competitive position through proprietary soy-based adhesive formulations that meet stringent indoor air quality standards. Roseburg Forest Products anchors its western US presence with large-scale softwood veneer capacity serving structural applications.
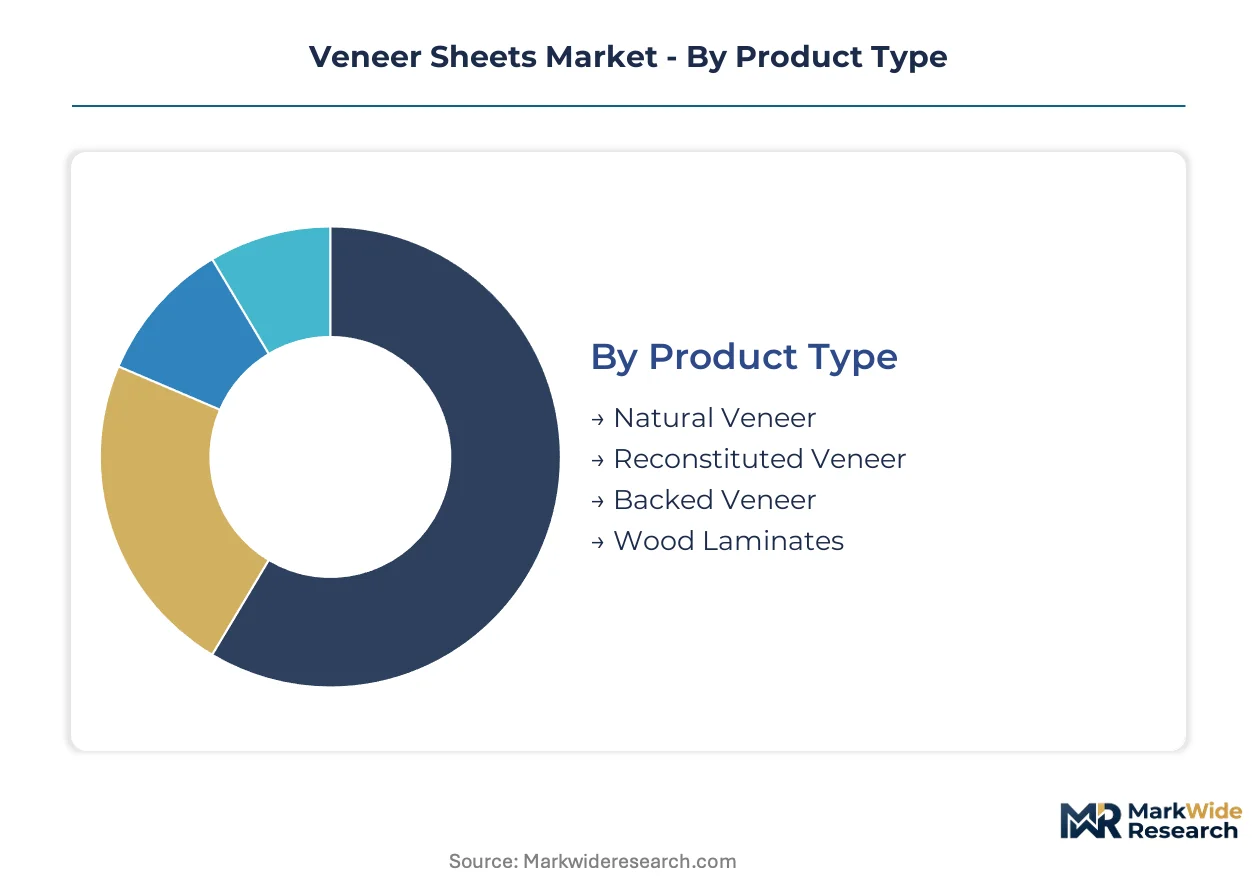
Veneer sheets are thin slices of wood, typically 0.5 to 3 millimeters thick, peeled or sliced from logs and bonded to substrates such as particleboard or medium-density fiberboard to provide decorative surfaces with authentic grain patterns. The primary commercial purpose is delivering premium aesthetic finishes at lower material cost than solid wood for furniture, architectural interiors, and specialty building products. Natural veneer commands the largest revenue share among product types due to enduring preference for authentic grain variation in high-end residential and hospitality applications, while reconstituted veneer grows fastest as manufacturers engineer consistent color and pattern matching for large commercial projects. Furniture represents the dominant application channel by volume, though wall paneling generates higher per-square-foot margins in commercial and institutional end-user segments where designers specify custom-grade material.
The US Lacey Act and EU Timber Regulation enforce chain-of-custody documentation that raises compliance costs for importers but simultaneously creates market access advantages for North American and European producers with certified sustainable sourcing. EPA formaldehyde emission standards under TSCA Title VI and California Air Resources Board Phase 2 requirements restrict adhesive chemistry choices, pushing manufacturers toward no-added-formaldehyde and bio-based resin systems. Stakeholders must monitor evolving building code adoption of mass timber construction standards, as cross-laminated timber and nail-laminated timber growth could redirect veneer sheet supply toward structural engineered wood products or intensify competition for premium peelable logs.
Market Dynamics
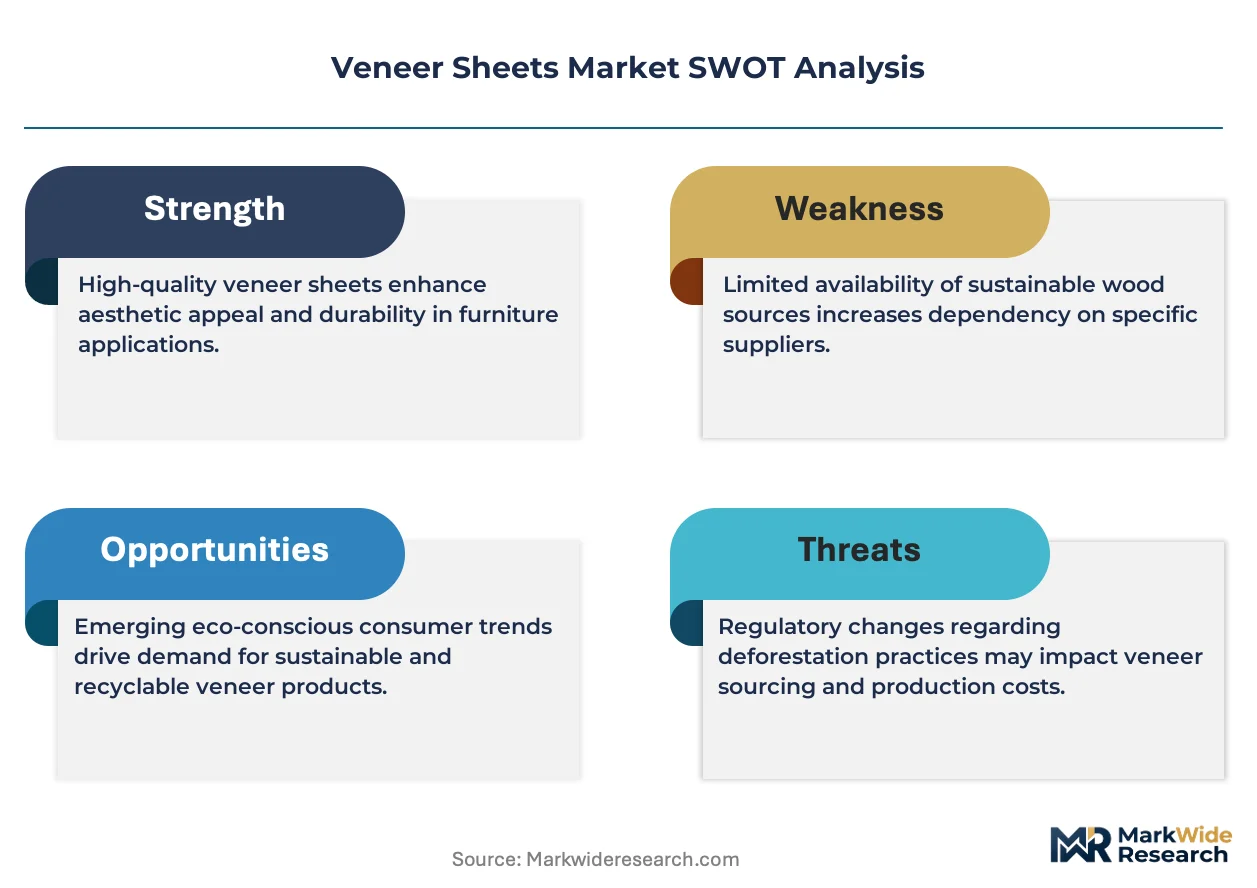
Raw material traceability mandates under the EU Timber Regulation and US Lacey Act are fragmenting supply chains, forcing importers to absorb documentation costs while certified North American and European producers gain preferential market access. This regulatory asymmetry is compressing margins for non-compliant traders and concentrating procurement relationships around vertically integrated suppliers with captive timberland bases.
Growth Catalysts
- Mass timber construction codes:Building code adoption of cross-laminated timber and nail-laminated timber standards in jurisdictions like Oregon and Austria is redirecting premium peelable logs toward structural engineered wood products, tightening decorative veneer feedstock and elevating prices for certified material.
- Vietnam furniture manufacturing:Export-oriented clusters near Ho Chi Minh City are concentrating demand for reconstituted veneer with engineered color consistency, pulling procurement volumes from traditional European decorative suppliers toward Asian integrated producers.
- Indoor air quality mandates:California Air Resources Board Phase 2 and EPA TSCA Title VI formaldehyde emission limits are accelerating no-added-formaldehyde adhesive adoption, creating product differentiation for manufacturers with bio-based resin capabilities.
Market Restraints
- Log supply concentration:Premium decorative veneer-quality timber concentrates in specific temperate hardwood regions of the eastern United States and western Europe, exposing processors to weather-driven harvest volatility and regional pest pressures.
- Peeling technology limitations:Rotary cutting of small-diameter logs below 30 centimeters yields excessive breakage and grain distortion, restricting usable raw material pools and elevating recovery costs for plantation-grown timber.
- Substitute surface materials:High-pressure laminates and digital printing technologies on melamine-faced panels are capturing mid-market furniture and cabinetry applications where authentic grain variation carries insufficient premium.
Strategic Opportunities
- Aftermarket refurbishment services:Re-lamination and veneer replacement for hospitality interiors is creating recurring revenue streams separate from new construction cycles, with service margins exceeding first-sale manufacturing profitability.
- EU Green Deal procurement incentives:Public building renovation wave funding prioritizes bio-based interior finishes with verified chain-of-custody, opening institutional specification channels for certified European veneer suppliers.
- Blockchain traceability integration:Distributed ledger systems for timber origin verification are converging with IoT sensor networks in sawmills, enabling real-time compliance documentation that satisfies EUTR due diligence with reduced manual audit burden.
Industry Challenges
- Skilled veneer cutting operator scarcity:Traditional flitch matching and book-matching for high-end architectural specifications requires tacit knowledge transfer that vocational training programs have failed to replenish as experienced craftspeople retire.
- Multi-certification compliance timelines:Simultaneous pursuit of FSC chain-of-custody, PEFC sustainable sourcing, and LEED v4.1 indoor air quality credits extends product qualification cycles by 8-14 months for specification-driven projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veneer Sheets Market |
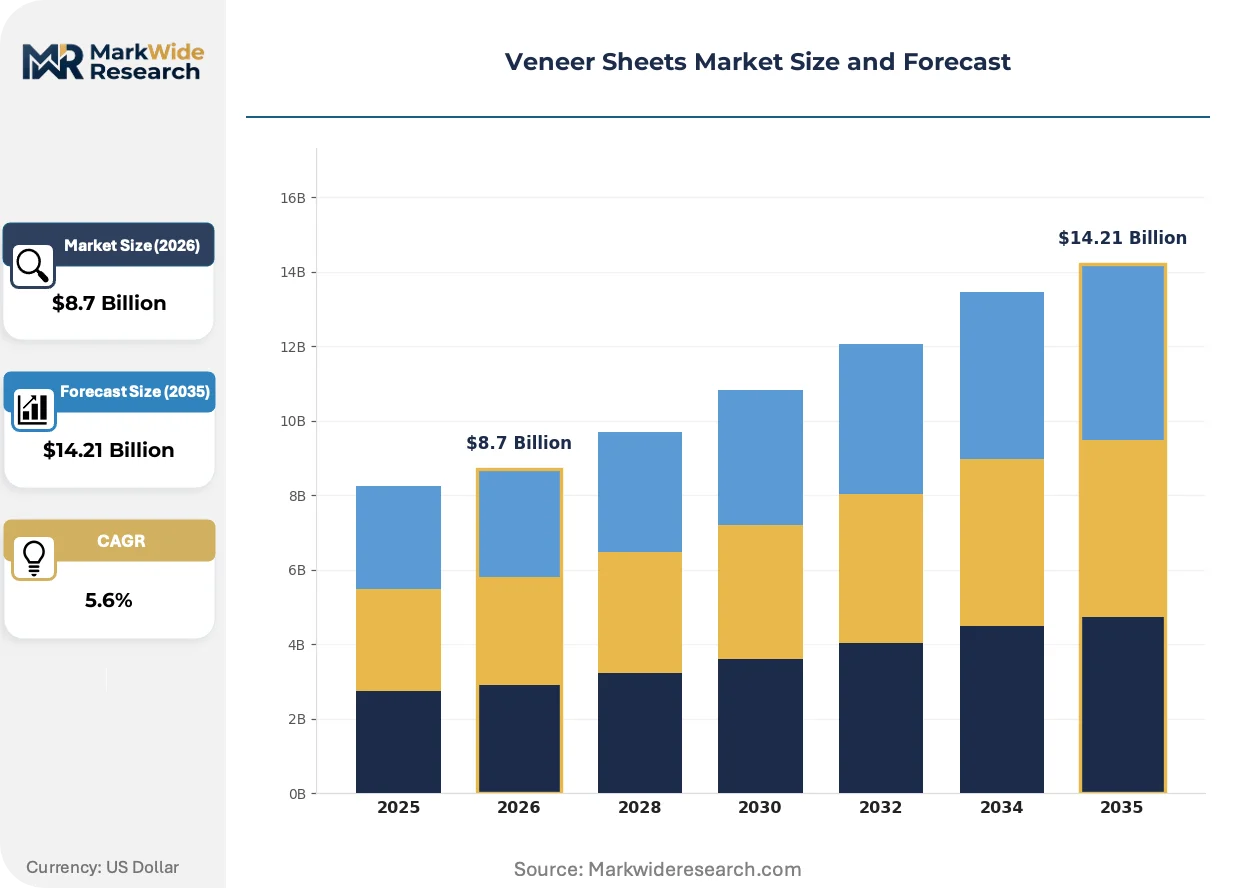
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Veneer, Reconstituted Veneer, Backed Veneer, Wood Laminates Application: Furniture, Wall Paneling, Cabinetry, Flooring End User: Residential, Commercial, Institutional, Hospitality Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Wholesale |
| Companies Covered | Louisiana-Pacific Corporation, Columbia Forest Products, Boise Cascade Company, Oakwood Veneer Company, Murphy Plywood, Georgia-Pacific Wood Products, Roseburg Forest Products, UFP Industries, Weyerhaeuser Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veneer Sheets Market Emerging Trajectories
Digital manufacturing and bio-based chemistry are converging to reshape how veneer surfaces are engineered, specified, and installed. These developments are compressing traditional batch-production timelines while elevating performance requirements that favor integrated suppliers.
Reconstituted veneer manufacturing is hybridizing rotary-cut low-grade hardwood and fast-growing plantation species with phenolic resin impregnation to produce engineered sheets with consistent color matching across commercial-scale projects. Hospitality interior designers in Dubai and Singapore are specifying these materials for 500+ room fit-outs where natural grain variation would create unacceptable visual discontinuity. The technology is hybridizing the aesthetic authenticity premium historically captured by natural veneer with the supply security and scale economics of synthetic surfacing.
REACH SVHC candidate list expansion and ECHA restrictions on formaldehyde-releasing substances are compelling adhesive reformulation across European manufacturing bases. Manufacturers serving the German kitchen cabinet and Austrian architectural millwork sectors are transitioning to soy-protein and lignin-based resin systems ahead of anticipated 2025 regulatory tightening. The policy shift most acutely affects medium-density fiberboard substrate bonding operations, where incumbent urea-formaldehyde chemistry faces phase-out pressure.
Buyers in the luxury residential segment are unbundling material procurement from installation services, contracting directly with veneer importers and engaging specialized craftspeople for substrate preparation and pressing. This disintermediation compresses distributor margins while elevating specification control for architects and interior designers. The pattern is most visible in London and New York high-end residential markets, where project-specific flitch selection and custom dyeing commands premium positioning unavailable through standard distribution channels.
Veneer Sheets Market Segmentation
Veneer sheet procurement cycles vary dramatically by application, with hospitality refurbishment turning inventory every 18-24 months while residential furniture stretches to 7-10 years. Understanding these velocity differentials helps suppliers align working capital deployment with margin capture opportunities across the value chain.
Product Type:
Natural veneer commands the longest specification cycles as architects inspect individual flitches, while reconstituted veneer compresses procurement timelines through engineered consistency.
- Natural Veneer:Thin slices peeled or sliced from solid logs, typically 0.5-3 millimeters thick, retaining authentic grain variation prized in high-end residential and hospitality applications. Demand concentrates in London and New York luxury residential markets where project-specific flitch selection commands premium positioning. The segment faces tightening feedstock constraints as mass timber construction redirects premium peelable logs toward structural engineered wood products.
- Reconstituted Veneer:Engineered sheets produced from rotary-cut low-grade hardwood and fast-growing plantation species impregnated with phenolic resin, delivering consistent color matching across commercial-scale projects. Procurement is accelerating near Ho Chi Minh City export-oriented furniture manufacturing clusters where 500+ room hospitality fit-outs require visual uniformity impossible with natural material. The technology hybridizes aesthetic authenticity with supply security at scale.
- Backed Veneer:Natural or reconstituted faces bonded to paper, fleece, or composite backings for enhanced flexibility and crack resistance during installation.
- Wood Laminates:Multi-layer composite products combining veneer surfaces with engineered substrates for dimensional stability in demanding environments.
Natural veneer dominates installed base across premium architectural specifications. Reconstituted veneer is where expansion concentrates as Asian manufacturing scales meet commercial project standardization requirements.
Application:
Margin structures invert across applications, with wall paneling generating higher per-square-foot returns than volume-heavy furniture despite smaller absolute throughput.
- Furniture:The dominant volume channel encompassing residential case goods, office systems, and hospitality case pieces where veneer provides premium aesthetics at reduced material cost versus solid wood. Production concentrates in Vietnam's export manufacturing clusters and North Carolina's remaining domestic upholstery and case goods operations. EPA TSCA Title VI formaldehyde emission standards are accelerating no-added-formaldehyde adhesive adoption among suppliers serving this channel.
- Wall Paneling:Architectural interior surfaces for commercial, institutional, and luxury residential environments where custom-grade material commands specification premiums. Demand clusters in Dubai and Singapore hospitality developments where designers source engineered consistency for large-format installations. California Air Resources Board Phase 2 requirements restrict adhesive chemistry choices, pushing manufacturers toward bio-based resin systems.
- Cabinetry:Kitchen, bath, and storage applications spanning residential renovations and new construction, with German and Austrian manufacturers leading adhesive reformulation ahead of anticipated ECHA restrictions.
- Flooring:Specialty applications including parquet and engineered plank surfaces where veneer wear layers balance aesthetics with structural substrate economics.
Furniture holds the largest installed base by square footage. Wall paneling is climbing the fastest as commercial interior renovation cycles accelerate.
End User:
Procurement authority fragmentation distinguishes end-user segments, with hospitality chains centralizing specification while residential buyers disintermediate distributors.
- Residential:Individual homeowners and custom builders purchasing through distributors or directly from importers, increasingly unbundling material procurement from installation services. Specification control is elevating for architects and interior designers in high-end markets.
- Commercial:Office, retail, and mixed-use developers prioritizing durability and code compliance over aesthetic variation, with procurement consolidating around certified suppliers meeting LEED v4.1 indoor air quality credits.
- Institutional:Government, education, and healthcare facilities where EU Green Deal procurement incentives prioritize bio-based interior finishes with verified chain-of-custody.
- Hospitality:Hotel and resort operators driving aftermarket refurbishment and re-lamination services with recurring revenue streams separate from new construction cycles, generating service margins exceeding first-sale manufacturing profitability.
Residential commands the broadest installed base. Hospitality is gaining share fastest through accelerated refurbishment cycles and brand-standard refresh programs.
Distribution Channel:
Channel economics are compressing as digital platforms disintermediate traditional stocking distributors, particularly in specification-driven segments.
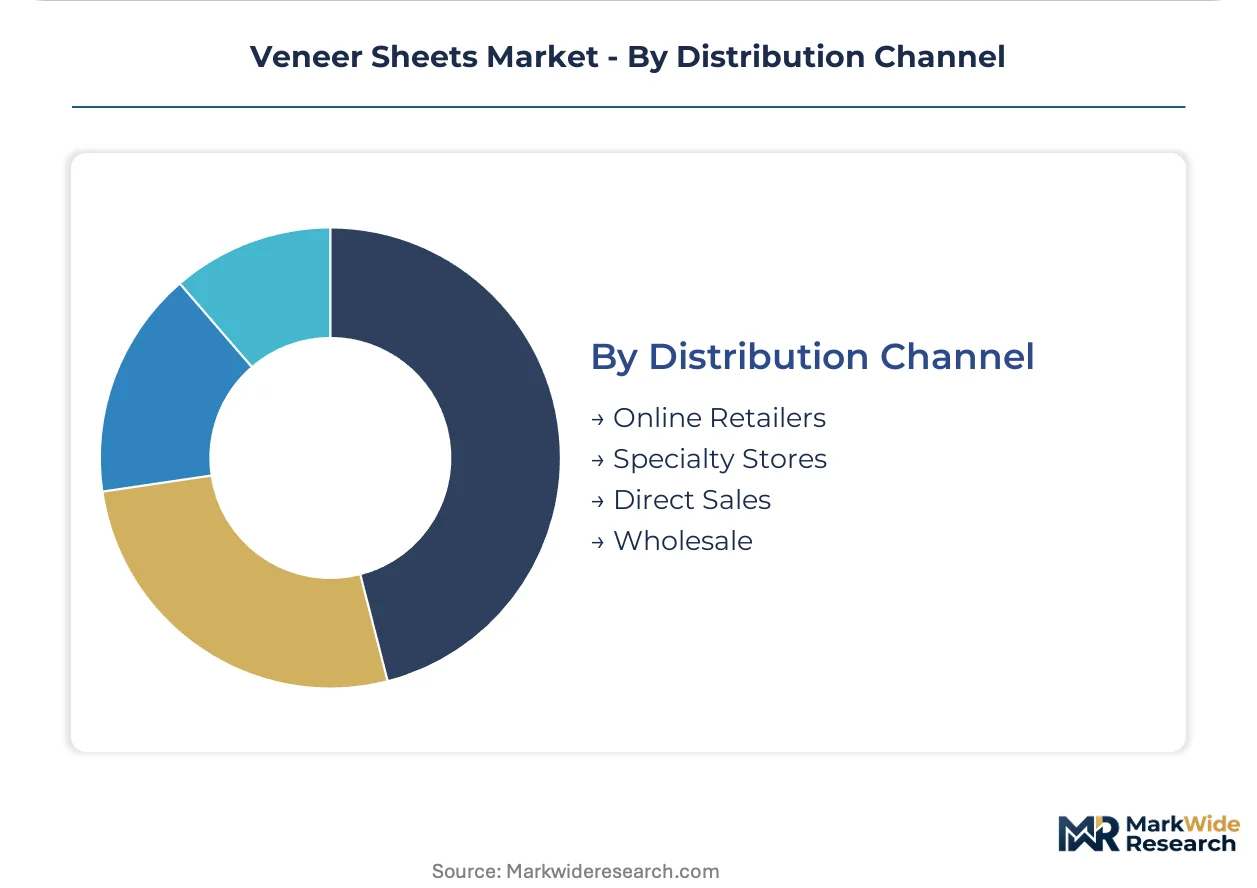
- Online Retailers:Digital platforms capturing mid-market furniture and cabinetry applications where standard grades suffice, with logistics networks enabling direct-to-fabricator delivery.
- Specialty Stores:Physical showrooms maintaining relevance in high-end residential and architectural specification where tactile material evaluation precedes procurement decisions.
- Direct Sales:Manufacturer-to-fabricator relationships concentrated in large commercial and hospitality projects requiring custom flitch selection and volume commitments.
- Wholesale:Traditional distributors serving regional furniture manufacturers and millwork operations with inventory breadth and technical support services.
Wholesale retains the deepest installed base relationships. Direct sales is expanding most quickly as large project buyers seek specification control and volume pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium peelable hardwood concentrates in temperate zones across the eastern United States and western Europe, while furniture manufacturing demand clusters in Southeast Asian export hubs. This geographic split between raw material origins and finished goods production defines procurement flows and regulatory exposure.
United States
Domestic veneer production draws on Appalachian and Pacific Northwest timber bases, with EPA TSCA Title VI formaldehyde standards pushing adhesive reformulation toward no-added-formaldehyde systems. The Lacey Act enforces chain-of-custody documentation that raises compliance costs for imported material while advantaging certified domestic suppliers. Manufacturing clusters in North Carolina and the Pacific Northwest serve remaining domestic furniture operations and specialty architectural millwork.
Germany
German kitchen cabinet and architectural millwork manufacturers lead European adhesive transition ahead of anticipated ECHA restrictions on formaldehyde-releasing substances. The EU Timber Regulation mandates due diligence documentation that fragments supply chains and concentrates procurement around vertically integrated suppliers. Production concentrates in Bavaria and Baden-Württemberg, where engineered wood product expertise supports both decorative veneer and structural mass timber feedstock competition.
Vietnam
Export-oriented furniture manufacturing near Ho Chi Minh City drives accelerating procurement of reconstituted veneer with engineered color consistency for large commercial fit-outs. Domestic regulations on timber legality are tightening alongside EU market access requirements. The Binh Duong and Dong Nai industrial provinces host integrated producers serving hospitality and residential export contracts.
Austria
Austrian building code adoption of cross-laminated timber standards redirects premium peelable logs toward structural engineered wood products, tightening decorative veneer feedstock availability. EU Green Deal procurement incentives prioritize bio-based interior finishes with verified chain-of-custody for public building renovations. Production clusters in Styria and Upper Austria leverage proximity to Alpine hardwood resources and mass timber construction expertise.
China
Domestic veneer manufacturing scales through rotary-cut plantation timber processing, though quality limitations from small-diameter logs restrict premium decorative output. The country's dual carbon goals pressure energy-intensive drying and pressing operations toward efficiency upgrades. Manufacturing concentrates in the Yangtze River Delta and Pearl River Delta, serving both domestic furniture production and re-export processing for Southeast Asian assembly.
Veneer Sheets Market Vendor Landscape
Timberland-integrated producers and adhesive-specialized fabricators split the market between raw material security and specification differentiation. The vendor base concentrates around captive forestland operations in North America and engineered chemistry capabilities in Europe. Three archetypes dominate: vertically integrated timberland owners controlling harvest-to-sheet flows, bio-based adhesive specialists capturing indoor air quality premiums, and Asian integrated producers scaling reconstituted veneer for export manufacturing. Competitive dynamics center on backward integration into timberland assets and strategic partnerships with hospitality chains for refurbishment service contracts.
Within the timberland-integrated tier, Louisiana-Pacific Corporation and Weyerhaeuser Company represent archetypes of captive raw material control. Among adhesive-differentiated specialists, Columbia Forest Products exemplifies positioning through proprietary soy-based formulations. Roseburg Forest Products occupies a position anchoring western US softwood veneer capacity for structural applications. These named entities illustrate how geographic timber access and chemistry capabilities define competitive segmentation without requiring exhaustive player enumeration.
| Leading Market Players |
|---|
| Louisiana-Pacific Corporation |
| Columbia Forest Products |
| Boise Cascade Company |
| Oakwood Veneer Company |
| Murphy Plywood |
| Georgia-Pacific Wood Products |
| Roseburg Forest Products |
| UFP Industries |
| Weyerhaeuser Company |
| Others |
Supply Flow & Price Mechanics
Appalachian and Pacific Northwest timberland concentration hands pricing leverage to vertically integrated producers with captive log supplies, while independent processors absorb volatility through spot-market procurement. This upstream control concentrates margin capture at the harvest-to-sheet conversion tier, squeezing midstream distributors and fabricators lacking backward integration into timber assets.
Pricing Analysis
Aftermarket refurbishment and re-lamination services now drive lifetime value capture, with hospitality operators contracting multi-year maintenance agreements that exceed first-sale manufacturing margins. Three-tier pricing structure across premium flitch-grade natural veneer, standard reconstituted sheets, and economy-backed utility grades differentiates procurement tiers. Cost compression in standard-grade furniture veneer is intensifying because Asian integrated producers scale rotary-cut plantation timber output. Residential custom builders exhibit highest price sensitivity, while luxury hospitality chains prioritize specification control over unit economics.
Supply Chain Analysis
Tariff exposure between Vietnam and the European Union dominates supply chain risk planning for export-oriented furniture manufacturers. Premium peelable hardwood concentrates in the eastern United States, western Europe, and select temperate zones of China, drawing from old-growth and plantation timber bases. Rotary cutting technology for small-diameter logs below 30 centimeters rests on phenolic resin impregnation and drying equipment sourced from German and Italian machinery specialists. Single-source vulnerability concentrates in adhesive chemistry, where soy-protein and lignin-based alternatives remain nascent. Distribution runs through direct manufacturer-to-fabricator relationships for large commercial projects, with wholesale distributors serving regional millwork operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EU Timber Regulation and US Lacey Act documentation requirements erect compliance barriers that certified incumbents leverage to exclude non-compliant traders.
For Market Incumbents: Harden timberland-integrated supply positions through captive harvest-to-sheet control, locking in feedstock security as mass timber construction intensifies log competition. Accelerate no-added-formaldehyde adhesive certification ahead of anticipated ECHA restrictions, converting compliance investment into specification premiums for German kitchen cabinet and Austrian architectural millwork channels. Defensive consolidation around blockchain-IoT traceability systems will satisfy EUTR due diligence with reduced audit burden, disadvantaging fragmented importers lacking capital for distributed ledger infrastructure. For New Entrants and Emerging Players: Pursue aftermarket refurbishment service contracts with hospitality chains in Dubai and Singapore, where 18-24 month interior refresh cycles generate recurring revenue streams insulated from new construction volatility. White-space opportunity concentrates in EU Green Deal-funded public building renovations, where bio-based interior finish requirements favor certified European suppliers with verified chain-of-custody. Go-to-market positioning should anchor on institutional procurement channels rather than residential distribution, leveraging compliance documentation as competitive wedge against incumbent distributors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed timberland-integrated producers seeking exit liquidity after decade-long holding periods. Five-to-ten year viability hinges on adhesive chemistry transition execution and mass timber construction feedstock competition resolution. Acquisition target archetype: mid-cap veneer processors with captive Appalachian or Alpine hardwood access and incomplete downstream integration. Signal to monitor: hospitality chain consolidation of refurbishment service procurement away from distributor intermediaries toward direct manufacturer relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timberland Assets | Captive log supply secures feedstock priority as mass timber construction redirects premium peelable timber toward structural engineered wood products. |
| No-Added-Formaldehyde Adhesive Transition | California Air Resources Board Phase 2 and EPA TSCA Title VI compliance creates specification premium capture in indoor air quality-sensitive segments. |
| Blockchain-IoT Traceability Deployment | Real-time origin verification satisfies EU Timber Regulation due diligence with reduced manual audit burden versus fragmented documentation systems. |
| Hospitality Refurbishment Service Contracts | Recurring revenue from 18-24 month interior refresh cycles exceeds first-sale manufacturing margins and insulates against construction cyclicality. |
| Reconstituted Veneer Scale Expansion | Engineered color consistency meets 500+ room commercial fit-out requirements in Vietnam export manufacturing clusters near Ho Chi Minh City. |
Methodological Framework
Desk research of trade flow databases, customs records, and timber industry association publications preceded structured interviews with sawmill operations managers, veneer cutting technicians, hospitality procurement directors, and architectural millwork specification consultants. Primary fieldwork across North Carolina, Bavaria, and Ho Chi Minh City industrial provinces captured operational practices and procurement decision frameworks. Secondary validation drew from EPA enforcement actions, EUTR compliance guidance documents, and SEC filings of timberland-integrated public companies. Bottom-up volume modeling triangulated against top-down demand segmentation across furniture, wall paneling, and cabinetry applications.
Assumptions held fixed include existing regulatory enforcement intensity, current building code adoption timelines for mass timber construction, and prevailing adhesive chemistry cost structures. Variables incorporated across the analysis window encompass EU Green Deal procurement incentive scaling, hospitality refurbishment cycle acceleration, and reconstituted veneer technology yield improvements. Segmentation dimensions modeled cover product type, application channel, end-user category, and distribution structure. CAGRs derived from historical volume trajectories adjusted for feedstock competition effects and certification-driven demand shifts. Industry-specific inputs include rotary cutting recovery rates by log diameter class and phenolic resin pricing sensitivity to petrochemical feedstock movements.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles, currency exchange rate volatility affecting Vietnam export competitiveness, or hardwood timber harvest disruptions from pest pressures or extreme weather would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement consistency and technology adoption curves in adhesive reformulation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
White Line Chipboard Market
Paper Products
Solar Paper Market
Paper Products
Paper Products Market
Paper Products
Decor Paper Market
Paper Products
Specialty Paper Market
Paper Products
Global Wood Pulp Market
Paper Products
Global Paperboard Market
Paper Products
Hardwood Pulp Market
Paper Products
GCC Paper Products Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Pulp Market
Paper Products
Cheque Paper Market
Paper Products
Digital Printing Paper Market
Paper Products
Global Carpet Backing Material Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
North America Medium-Density Fiberboard Market