
 NCR Laser Paper Market | 2026-2036
NCR Laser Paper Market Size, Share, and Industry Trends Forecast 2026-2036
NCR Laser Paper Market Foresight
Buyer concentration among commercial printing houses is expanding as mid-sized print shops merge operations and consolidate supplier rosters. Koehler Paper Group leverages its European manufacturing base to sustain long-term contracts with form printers. Nekoosa Coated Products anchors North American supply through specialized coating capabilities. Pixelle Specialty Solutions competes on thermal-mechanical integration for laser-compatible substrates.
NCR laser paper consists of coated sheets engineered with microencapsulated dye and developer layers that react under mechanical pressure to produce duplicate copies without carbon interleaves, typically manufactured in 70 GSM to 110 GSM weights for laser printer compatibility. Multi-part forms dominate volume consumption in commercial printing due to persistent demand for triplicate invoicing, while 80 GSM thickness captures the widest end-user adoption across retail and healthcare documentation. Colored NCR laser paper differentiates through visual coding systems in logistics and medical records management.
REACH compliance governs chemical coatings across European supply chains, while FDA record-keeping standards shape healthcare documentation substrates in the United States. ISO paper durability standards further constrain product specifications for archival business forms. Stakeholders must monitor regulatory alignment between coating chemistry and printer OEM compatibility requirements as equipment specifications evolve.
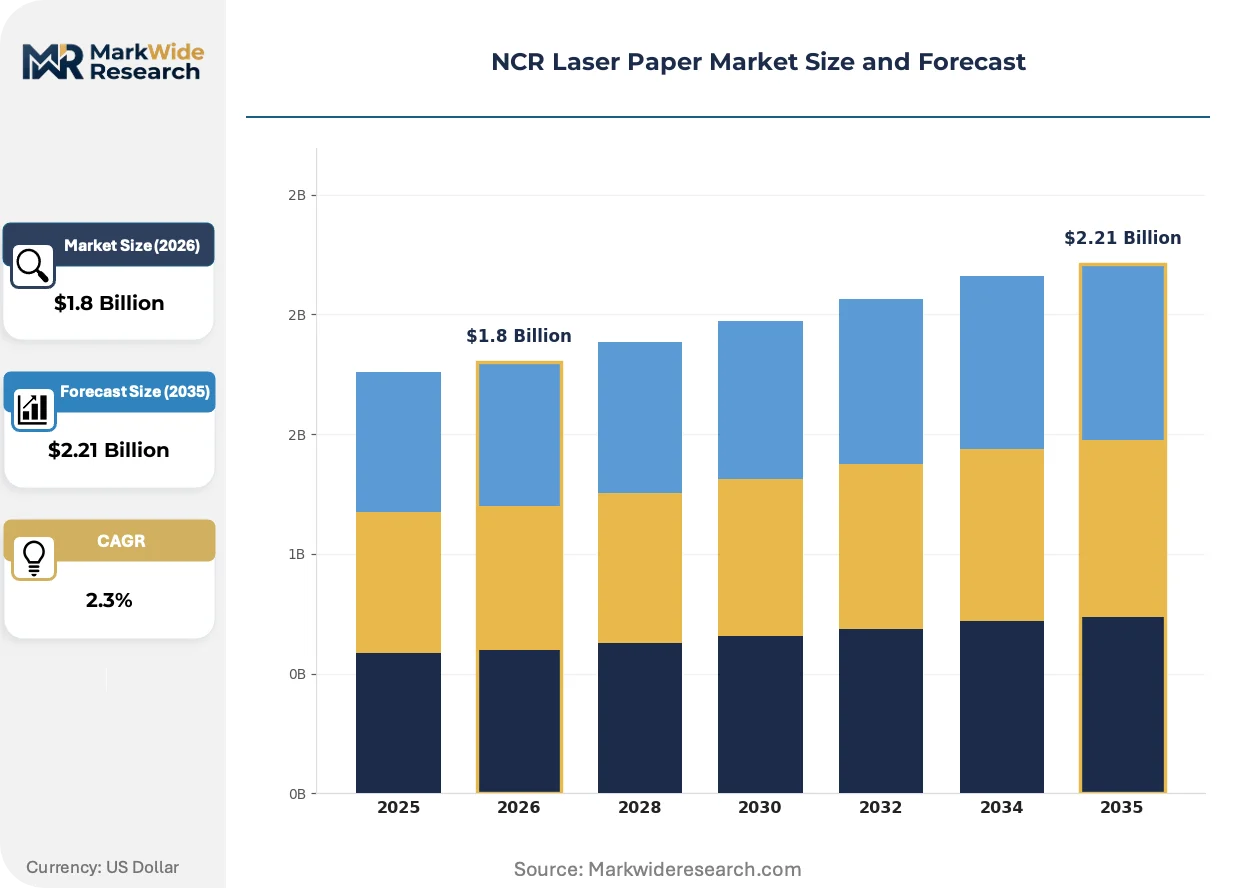
Market Dynamics
Commercial printing house consolidation is compressing supplier rosters and amplifying contract scale requirements, forcing coating specialists to secure multi-year supply agreements or exit the segment entirely.
Growth Catalysts
- REACH chemical compliance:European ECHA enforcement is filtering non-compliant Asian imports, creating procurement windows for certified domestic manufacturers in Germany and Finland.
- Healthcare documentation digitization mandates:US FDA record-keeping standards for patient forms sustain demand for archival-grade laser-compatible substrates in hospital systems and insurance workflows.
- Microencapsulation chemistry:Advances in solvent-free dye coating processes reduce VOC emissions while maintaining pressure-reactivity thresholds for triplicate form duplication.
Market Restraints
- Pulp input cost volatility:Hardwood pulp prices fluctuate with Brazilian and Indonesian supply disruptions, squeezing margin structures for unhedged coating operations.
- Substitution by thermal paper:Point-of-sale terminals increasingly deploy thermal receipt printers, displacing NCR laser paper in retail checkout workflows.
- REACH registration burdens:Small coating houses face disproportionate compliance costs for novel chemical formulations, consolidating innovation capacity among capital-rich players.
Strategic Opportunities
- China domestic form consumption:Regional business process outsourcing expansion creates localized demand for Mandarin-language multi-part invoicing substrates.
- Color-coded logistics tracking:Warehouse management systems adopt chromatic NCR layers for visual shipment segregation, opening specification premiums beyond standard white stock.
- ISO 9706 archival certification:Permanent paper standards for legal and financial records create compliance-driven pricing tiers for 100+ year durability guarantees.
Industry Challenges
- OEM printer compatibility testing:Each new laser printer generation requires recertification of coating friction coefficients and heat resistance, extending product launch timelines.
- Coating technician skill scarcity:Microencapsulation process expertise concentrates among aging workforces in German and Japanese paper mills, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NCR Laser Paper Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 2.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Part, Multi-Part, Colored, White End User: Commercial Printing, Retail, Education, Healthcare Thickness: 70 GSM, 80 GSM, 90 GSM, 110 GSM Packaging Type: Reams, Pallets, Shrink Wrap, Bundles |
| Companies Covered | Koehler Paper Group, Nekoosa Coated Products, Pixelle Specialty Solutions, Mitsubishi HiTec Paper, Jinyi Paper Co., Ltd., Yulu Paper Industry Co., Ltd., Asia Pulp & Paper, Shenzhen Sycda Co., Ltd., Millenium Papers Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NCR Laser Paper Market Shifts & Advancements
Substrate engineering is converging with digital printing requirements as legacy offset workflows contract, reshaping how coating properties align with toner adhesion and heat tolerance specifications.
Water-based barrier coatings are modularizing the traditional solvent-dependent architecture of NCR laser paper, enabling food-contact compliant receipt formats that retail chains in France and Japan are adopting for integrated labeling applications. Quick-service restaurant operators specify these substrates for allergen-warning documentation that withstands kitchen humidity without dye migration. The technology is modularizing supply chain configurations by allowing single-facility production of both standard and food-grade stocks.
REACH Annex XVII restrictions on formaldehyde-releasing substances are compelling coating reformulations across European supply chains, with ECHA guidance pushing manufacturers toward phenol-free developer chemistries. German form printers now require supplier declarations covering full substance inventories down to 0.1% concentration thresholds. Healthcare documentation suppliers in the Netherlands and Belgium are accelerating certification timelines to preempt enforcement actions.
Buyer consolidation among merged commercial printing houses is compressing supplier negotiation cycles from annual to quarterly reviews, with procurement teams demanding volume-tiered pricing indexed to pulp futures. Mid-sized print shops in the US Midwest and UK Midlands are pooling purchasing through cooperative buying groups to match contract scale requirements. This concentration is most visible in invoice and statement printing, where three national providers now control majority procurement decisions.
NCR Laser Paper Market Segmentation
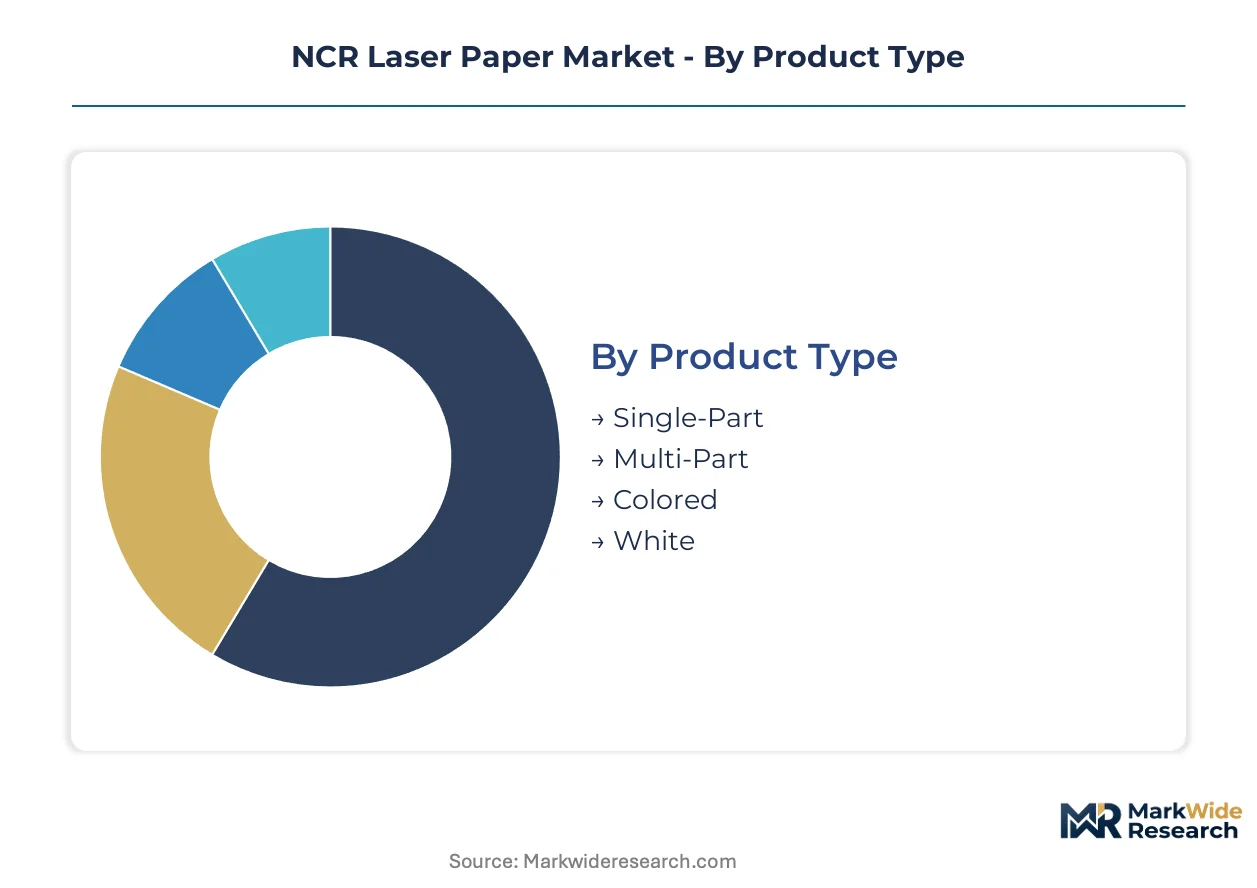
NCR laser paper segmentation reflects divergent technical requirements across form duplication workflows. Specification choices in coating chemistry, sheet thickness, and part configuration directly determine printer compatibility and end-use compliance.
Product Type:
Microencapsulation layer architecture defines pressure-reactivity thresholds and copy fidelity across laser printing environments.
- Multi-Part:Triplicate and quadruplicate sheet assemblies with interleaved carbonless coatings enable simultaneous duplicate generation under mechanical pressure. Commercial printing houses in Germany and the United States specify these for invoice and statement workflows where archival retention is mandatory. FDA record-keeping standards for healthcare documentation sustain procurement volumes despite digitization pressures.
- Colored:Pigmented base stocks in pink, yellow, and blue enable visual coding systems for logistics tracking and medical records segregation. Warehouse management systems in France and Japan specify chromatic layers for shipment identification without barcode scanning infrastructure. REACH-compliant dye formulations now dominate European supply chains following ECHA enforcement actions.
- Single-Part:Uncoated or single-layer sheets for simplex laser printing without duplicate generation.
- White:Standard unbleached or bleached substrates for general-purpose business forms without color-coding requirements.
Multi-Part leads on scale; Colored leads on momentum.
End User:
Procurement concentration varies sharply by sector compliance burdens and form duplication intensity.
- Commercial Printing:Consolidated print houses generate majority volume demand for invoice, statement, and certificate production. Merged operators in the US Midwest and UK Midlands now control majority procurement decisions through cooperative buying groups.
- Healthcare:Hospital systems and insurance workflows require ISO 9706 archival-grade substrates for patient documentation with century-scale durability guarantees. FDA record-keeping standards mandate laser-compatible substrates that withstand toner fusion temperatures without coating degradation.
- Retail:Point-of-sale receipt and return documentation applications facing displacement by thermal printer substitution.
- Education:Examination materials and administrative forms with seasonal procurement patterns tied to academic calendars.
Commercial Printing dominates procurement volume; Healthcare maintains steepest specification premiums.
Thickness:
Grammage selection balances mechanical feeding reliability against postal cost optimization in mailed form applications.
- 80 GSM:Mid-weight specification captures widest adoption across retail and healthcare documentation due to optimal balance of printer feed compatibility and handling durability. German form printers specify this grammage as default for patient records and insurance correspondence.
- 70 GSM:Lightweight stock for high-volume mailed statements where postal weight thresholds determine cost structure. Financial services providers in the Netherlands specify this grammage for monthly account communications.
- 90 GSM:Heavier substrate for certificate and legal document applications requiring enhanced tactile perception.
- 110 GSM:Maximum grammage for prestige documentation and archival inserts with extended durability requirements.
80 GSM leads on adoption breadth; 70 GSM leads on volume throughput.
Packaging Type:
Logistics configuration determines warehouse handling efficiency and moisture protection through distribution chains.
- Reams:Standard 500-sheet retail and small-office packaging with individual moisture barrier wrapping. Japanese distributors specify ream configurations for just-in-time delivery to mid-sized print shops.
- Pallets:Bulk unitization for national print house contracts with automated warehouse systems. Finnish manufacturers palletize to 48-inch specifications for European retail chain distribution centers.
- Shrink Wrap:Weather-resistant outer sealing for outdoor storage tolerance in humid climates.
- Bundles:Intermediate quantity packaging for regional distributor replenishment without full pallet commitment.
Pallets lead on contract scale; Reams lead on distribution point density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany sustains higher specification premiums than China despite narrower volume throughput, while the United States maintains distinct procurement patterns shaped by healthcare documentation mandates. National regulatory frameworks and industrial clustering determine competitive positioning across major consuming markets.
United States
Hospital systems and insurance workflows sustain procurement of archival-grade laser-compatible substrates under FDA record-keeping standards. The Midwest industrial corridor hosts consolidated commercial printing houses that control majority procurement decisions through cooperative buying groups. Chicago-area form printers specify 80 GSM grammage as default for patient records and monthly account statements.
Germany
REACH Annex XVII enforcement filters non-compliant imports, creating procurement windows for certified domestic manufacturers. ECHA guidance pushes coating specialists toward phenol-free developer chemistries with full substance inventory declarations. The Baden-Württemberg paper cluster concentrates microencapsulation expertise among established coating operations serving European form printers.
China
Domestic business process outsourcing expansion generates localized demand for Mandarin-language multi-part invoicing substrates. GB standards and MIIT directives shape substrate compliance for regional specialty paper output. The Yangtze River Delta hosts scaled coated specialty manufacturers supplying business forms consumption across East Asian markets.
Japan
METI industrial standards and JIS specifications constrain coating chemistry for laser printer compatibility in precision documentation workflows. Quick-service restaurant operators specify water-based barrier coatings for allergen-warning documentation in kitchen environments. The Kanto region anchors distribution networks serving just-in-time delivery requirements for mid-sized print shops.
Netherlands
Financial services providers specify lightweight 70 GSM stocks for high-volume mailed statements where postal weight thresholds determine cost structures. Healthcare documentation suppliers accelerate certification timelines to preempt REACH enforcement actions. The Randstad logistics hub enables efficient pallet distribution to European retail chain distribution centers.
NCR Laser Paper Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: European coating specialists leveraging regulatory compliance advantages, Asian integrated pulp-to-paper operators optimizing scale economics, and North American substrate engineers competing on thermal-mechanical integration. Dominant competitive moves include multi-year supply agreement consolidation among merged commercial printing houses and solvent-free coating chemistry licensing for REACH compliance.
Among European coating specialists, Koehler Paper Group and Nekoosa Coated Products exemplify the compliance-driven archetype, occupying positions sustained by long-term contracts with form printers. Pixelle Specialty Solutions represents the North American integration-focused tier, anchoring supply through specialized coating capabilities. Mitsubishi HiTec Paper sits within the precision-engineering segment, while Chinese operators including Jinyi Paper Co., Ltd. and Yulu Paper Industry Co., Ltd. exemplify scale-oriented domestic supply configuration.
| Leading Market Players |
|---|
| Koehler Paper Group |
| Nekoosa Coated Products |
| Pixelle Specialty Solutions |
| Mitsubishi HiTec Paper |
| Jinyi Paper Co., Ltd. |
| Yulu Paper Industry Co., Ltd. |
| Asia Pulp & Paper |
| Shenzhen Sycda Co., Ltd. |
| Millenium Papers Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
REACH Annex XVII compliance gates qualified supply access and premium-tier pricing power across European NCR laser paper markets, with phenol-free developer certifications separating certified domestic manufacturers from filtered Asian imports. Buyers in Germany and the Netherlands now demand full substance inventory declarations down to 0.1% concentration thresholds, compressing supplier rosters and amplifying contract scale requirements for coating specialists.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade multi-part forms, while REACH-compliant European output commands specification premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and archival durability guarantees, with ISO 9706-certified stocks capturing the widest margins. Price erosion runs through lightweight 70 GSM segments as Brazilian hardwood pulp volatility squeezes unhedged coating operations. Retail point-of-sale applications exhibit highest price sensitivity due to thermal printer substitution, while healthcare documentation buyers prioritize specification compliance over unit cost.
Supply Chain Analysis
Microencapsulated dye supply rests on Japanese and German specialty chemical producers, with developer layer chemistry concentrated among established coating operations in Baden-Württemberg and the Kanto region. Hardwood pulp feeds from Brazilian and Indonesian sources, solvent-free coating formulations draw from proprietary process licensing, and laser printer compatibility testing hinges on OEM recertification protocols. Single-source vulnerability concentrates in aging coating technician expertise among German and Japanese paper mills. Distribution runs through palletized bulk unitization for national print house contracts and ream configurations for just-in-time mid-sized shop delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NCR laser paper functions as a late-cycle quality story where buyer consolidation and regulatory tightening concentrate procurement among specification-compliant suppliers, with healthcare documentation digitization mandates sustaining demand for archival-grade laser-compatible substrates despite secular headwinds.
For Market Incumbents: To counter thermal printer substitution in retail workflows, secure multi-year supply agreements with merged commercial printing houses through volume-tiered pricing indexed to pulp futures, and accelerate phenol-free developer chemistry certification to preempt REACH enforcement windows in Benelux markets. For New Entrants and Emerging Players: Launch via cooperative buying group partnerships serving pooled Midwest and UK Midlands print shop procurement, targeting color-coded logistics tracking specifications in warehouse management systems where chromatic layer premiums exceed standard white stock economics and barcode scanning infrastructure remains underdeployed. For Investors and Strategic Acquirers: Roll-up economics work for European coating specialists with captive REACH compliance capabilities because regulatory registration burdens disproportionately burden small formulation houses and consolidate innovation capacity among capital-rich players. Five-to-ten year viability hinges on solvent-free process licensing traction. Watch ECHA enforcement action intensity as inflection indicator for certification-driven pricing power expansion.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Reformulation | ECHA enforcement actions filter non-compliant imports, creating procurement windows for certified German and Finnish manufacturers. |
| Multi-Year Supply Agreement Consolidation | Merged commercial printing houses in the US Midwest compress supplier rosters and amplify contract scale requirements. |
| Water-Based Barrier Coating Modularization | Quick-service restaurant operators in France and Japan specify food-contact compliant formats for allergen-warning documentation. |
| ISO 9706 Archival Certification Investment | Legal and financial records create compliance-driven pricing tiers for 100+ year durability guarantees in healthcare and insurance workflows. |
| Cooperative Buying Group Penetration | Mid-sized print shops pool purchasing to match contract scale requirements and access volume-tiered pricing structures. |
Research Methodology
Coverage spans Germany, the United States, China, Japan, and the Netherlands, with primary inputs from each market combining interviews with coating operations managers, commercial printing house procurement leads, healthcare documentation compliance officers, and distribution channel partners. Secondary validation draws from ECHA regulatory filings, FDA record-keeping guidance documents, customs trade data for hardwood pulp flows, and SEC filings of diversified paper conglomerates. Bottom-up volume modeling triangulates against top-down market sizing across the analysis window.
Segmentation granularity extends to microencapsulation layer architecture, grammage specifications, part configurations, and end-use compliance burdens. CAGRs derive from trend extrapolation of procurement concentration patterns, regulatory enforcement timelines, and printer OEM compatibility recertification cycles. Forecast inputs incorporate pulp futures volatility indices and business process outsourcing expansion rates in East Asian markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden REACH Annex XVII amendment scenarios or accelerated thermal printer substitution in retail point-of-sale terminals. Projections reflect assumptions about coating technician workforce stability and hardwood pulp supply continuity. A small set of named triggers—ECHA enforcement intensity, FDA digitization mandate revisions, and Brazilian pulp export disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Tissue Paper Market
Paper Products
Pulp and Paper Chemicals Market
Paper Products
Paper Core Market
Paper Products
Global Security Paper Market
Paper Products
Global Carpet Backing Material Market
Paper Products
Latex-Saturated Paper Market
Paper Products
Global Dye Sublimation Paper Market
Paper Products
Greaseproof Paper Market
Paper Products
Organic Tissue Paper Market
Paper Products
Greaseproof Paper Sheets Market
Paper Products
Carbonless Paper Market
Paper Products
Decorative Plastic and Paper Laminates Market
Paper Products
Unbleached Kraft Pulp Market
Paper Products
Unbleached Hardwood Kraft Pulp Market
Paper Products
Plywood Market
Paper Products
North America Decor Paper Market