
 Billing Paper Market | 2026-2036
Billing Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Billing Paper Market Analysis
Healthcare facilities is redrawing procurement priorities across the billing paper value chain as patient invoicing and insurance claim documentation requirements intensify. International Paper leverages its North American manufacturing footprint to sustain supply continuity for high-volume institutional buyers. Stora Enso anchors its position through certified sustainable fiber sourcing that meets corporate procurement mandates. Koehler Paper Group specializes in thermal coating technologies that serve point-of-sale and medical device integration applications.
Billing paper denotes substrate grades engineered for transactional documentation, typically incorporating thermal-sensitive coatings, carbonless microencapsulated layers, or traditional wood-pulp bases with controlled opacity and print receptivity; basis weights range from 45 to 80 gsm depending on application durability requirements. Thermal paper dominates volume flows through retail and hospitality point-of-sale terminals where instant print speed outweighs unit cost considerations. Carbonless paper retains structural importance in healthcare and logistics sectors requiring multi-part forms without electronic duplication infrastructure. Specialty paper grades command margin concentration where custom security features or extended archival specifications justify premium positioning.
The US FDA and HIPAA frameworks mandate legibility and retention standards for healthcare billing documentation, directly shaping product specifications for archival-grade substrates. EPA regulations on bisphenol-A content in thermal coatings are forcing reformulation investments across coating lines serving North American buyers. ISO 9706 permanence standards influence procurement specifications for financial institutions requiring century-grade document retention. Stakeholders must monitor regulatory divergence between US and European chemical safety standards as reformulation timelines create temporary supply asymmetries.
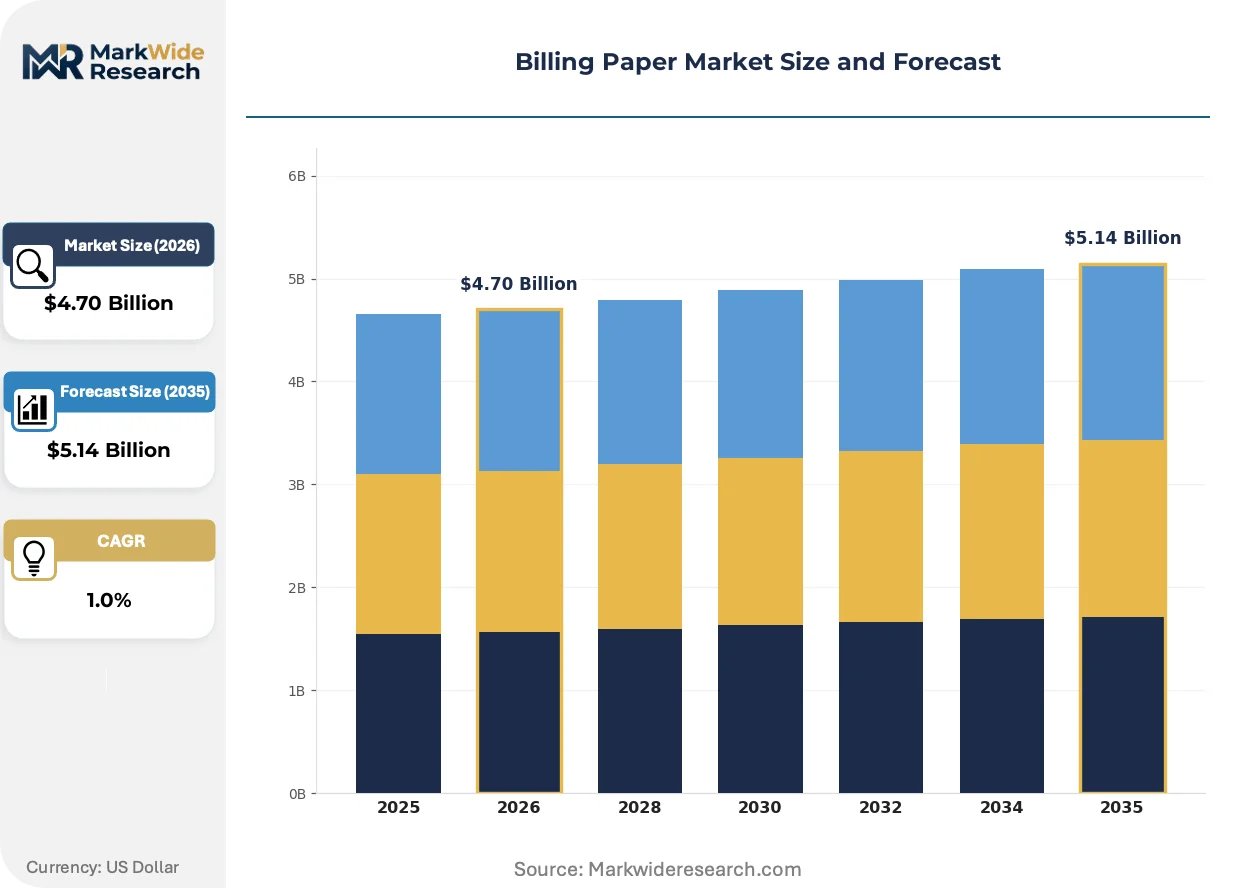
Market Dynamics
The billing paper market is experiencing structural compression as healthcare digitization accelerates while regulatory retention mandates sustain physical substrate demand. Thermal coating reformulation pressures and insurance documentation volume create competing forces on procurement budgets.
Growth Catalysts
- HIPAA Retention Mandates:US healthcare facilities must maintain legible billing records for extended periods, driving demand for archivable thermal and carbonless grades with ISO 9706 permanence ratings.
- Point-of-Sale Terminal Expansion:Retail and hospitality sectors continue deploying thermal receipt printers where instant output speed outweighs digital receipt alternatives.
- Insurance Claim Documentation:The United States generates substantial recurring volume through complex multi-party billing workflows requiring durable multi-part forms.
Market Restraints
- Bisphenol-A Regulatory Friction:EPA restrictions on thermal coating chemistry force costly reformulation investments without immediate pass-through pricing power.
- Pulp Input Volatility:Softwood pulp prices fluctuate with energy and freight costs, compressing margins for uncoated base stock producers.
- Digital Receipt Substitution:Mobile payment platforms and email invoicing displace thermal paper in retail environments where regulatory retention is minimal.
Strategic Opportunities
- Phenol-Free Thermal Coatings:Early movers in BPA-alternative chemistry capture procurement contracts from institutional buyers with corporate sustainability mandates.
- Medical Device Integration:Specialized billing paper grades that interface with diagnostic equipment printouts create premium positioning in hospital supply chains.
- Extended Archival Specifications:Century-grade document retention standards open margin concentration in financial services and legal documentation segments.
Industry Challenges
- Coating Line Reconfiguration:Thermal paper manufacturers face 18-24 month timelines to certify phenol-free formulations without disrupting existing contract fulfillment.
- Legacy Form Integration:Healthcare administrators struggle to synchronize new substrate specifications with existing multi-part form printing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Billing Paper Market |
| Market Size in 2026 | $4.70 Billion |
| Market Size in 2035 | $5.14 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Paper, Carbonless Paper, Specialty Paper, Traditional Paper End User: Retail Sector, Hospitality Industry, Healthcare Facilities, Educational Institutions Form: Roll, Sheet, Custom Size, Pre-printed Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | International Paper, UPM-Kymmene Corporation, Stora Enso, Koehler Paper Group, Domtar Corporation, Sappi Limited, Oji Paper Company, Kimberly-Clark Corporation, Mitsubishi HiTec Paper Europe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Billing Paper Market Emerging Trajectories
Thermal coating chemistry is undergoing forced transformation while procurement patterns bifurcate between high-specification institutional buyers and cost-sensitive retail segments. Three developments are restructuring competitive positioning.
Developer-stabilized thermal coatings are miniaturizing the chemical footprint required for equivalent image permanence. Medical device manufacturers are adopting these reformulated grades for integrated diagnostic printouts. The technology is miniaturizing coating layer thickness while maintaining FDA-mandated legibility standards, compressing material costs per linear meter.
REACH chemical safety standards in Europe are accelerating ahead of US EPA timelines, creating asynchronous reformulation requirements for multinational coating suppliers. Manufacturers serving both markets must maintain dual inventory or advance European compliance schedules. Thermal paper importers into Germany and France face earlier deadlines for phenol-free certification than their North American counterparts.
Hospital procurement departments are consolidating vendor relationships around single-source contracts with guaranteed supply continuity clauses. Group purchasing organizations are displacing fragmented departmental buying, concentrating volume with manufacturers offering North American manufacturing footprints. This concentration is most visible in the United States, where health system mergers have reduced the number of independent contracting entities by half over the past decade.
Billing Paper Market Segmentation
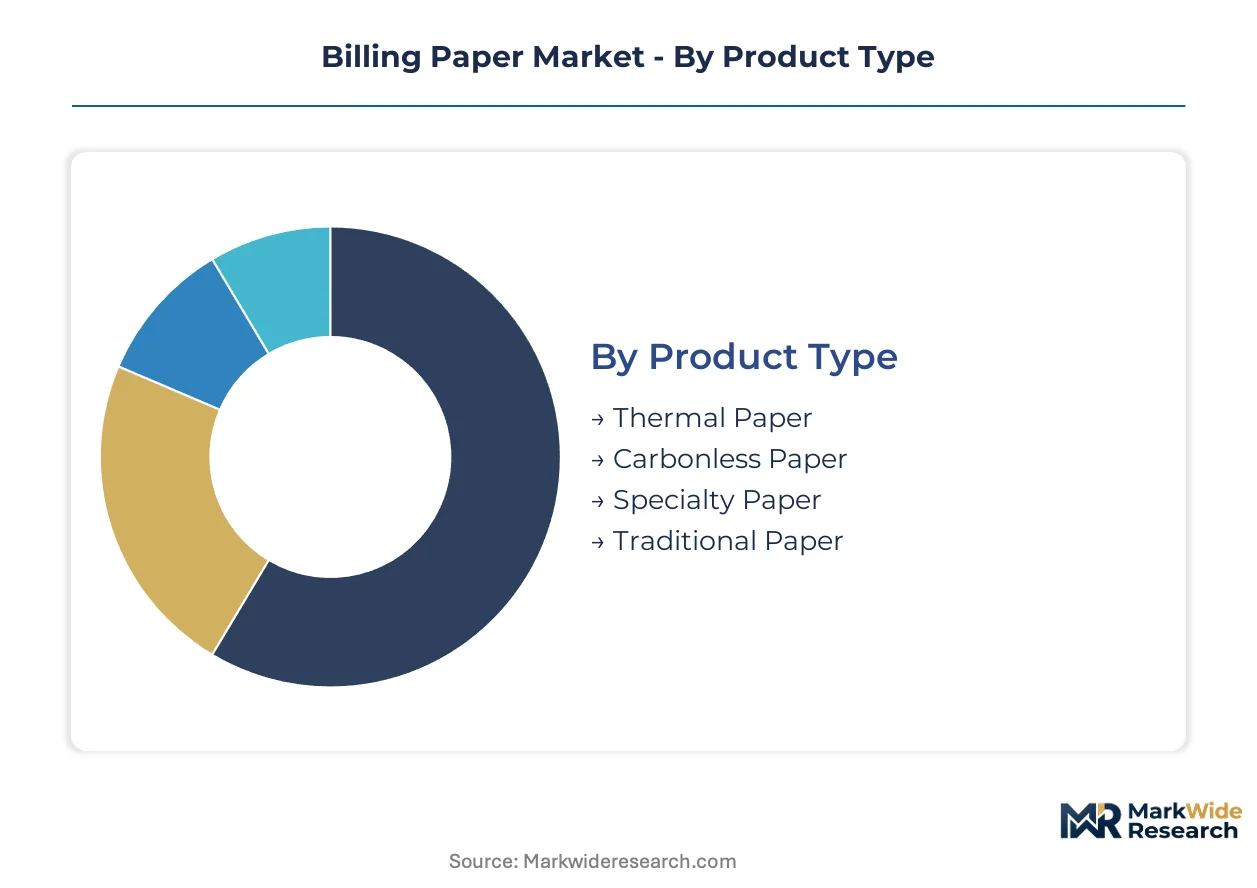
Billing paper segmentation reveals divergent vulnerability to digital substitution across substrate grades and end-use applications. Product chemistry and regulatory retention requirements determine which segments retain structural demand versus those facing accelerated displacement.
Product Type:
Thermal paper faces the most acute substitution pressure from mobile payment platforms and email receipt systems, while archival-grade substrates maintain defensive positioning through compliance mandates.
- Thermal Paper:Heat-sensitive coatings containing leuco dyes and developers enable instant image formation without ink. Retail point-of-sale terminals in the United States generate concentrated demand, though EPA bisphenol-A restrictions are forcing costly reformulation investments across North American coating lines.
- Carbonless Paper:Microencapsulated dye and developer coatings transfer images through pressure without carbon interleaves. Healthcare facilities in the United States depend on multi-part forms for insurance claim workflows, sustaining volume despite administrative digitization efforts.
- Specialty Paper:Custom security features and extended archival specifications serve financial services and legal documentation with premium positioning.
- Traditional Paper:Uncoated wood-pulp substrates with controlled opacity serve basic invoicing needs in cost-sensitive procurement environments.
Thermal paper anchors the volume base while specialty paper gains share at the steepest rate.
End User:
Procurement concentration varies sharply by sector, with institutional buyers prioritizing supply continuity and compliance certification over unit cost optimization.
- Healthcare Facilities:HIPAA retention mandates and FDA legibility requirements sustain demand for ISO 9706-certified archival grades. Hospital group purchasing organizations in the United States are consolidating vendor relationships around single-source contracts with guaranteed supply clauses.
- Retail Sector:High-volume thermal receipt consumption at point-of-sale terminals faces erosion from digital receipt platforms where regulatory retention is minimal.
- Hospitality Industry:Hotels and restaurants deploy thermal paper for guest folios and payment receipts, with procurement sensitivity to coating chemistry reformulation costs.
- Educational Institutions:Administrative billing and student account documentation generate steady but fragmented demand across decentralized procurement systems.
Healthcare facilities command the highest specification premiums while retail sector volume faces the steepest compression trajectory.
Form:
Physical configuration directly determines compatibility with installed printer infrastructure and automation integration depth.
- Roll:Continuous-feed thermal rolls dominate high-speed point-of-sale and medical device integration applications.
- Sheet:Cut-sheet formats serve desktop laser and inkjet printers in administrative billing environments.
- Custom Size:Dimensional specifications tailored to proprietary equipment create captive demand relationships.
- Pre-printed:Branded and regulatory-formatted substrates reduce downstream processing steps for institutional buyers.
Roll format maintains the largest installed base while custom sizing commands the most favorable margin structure.
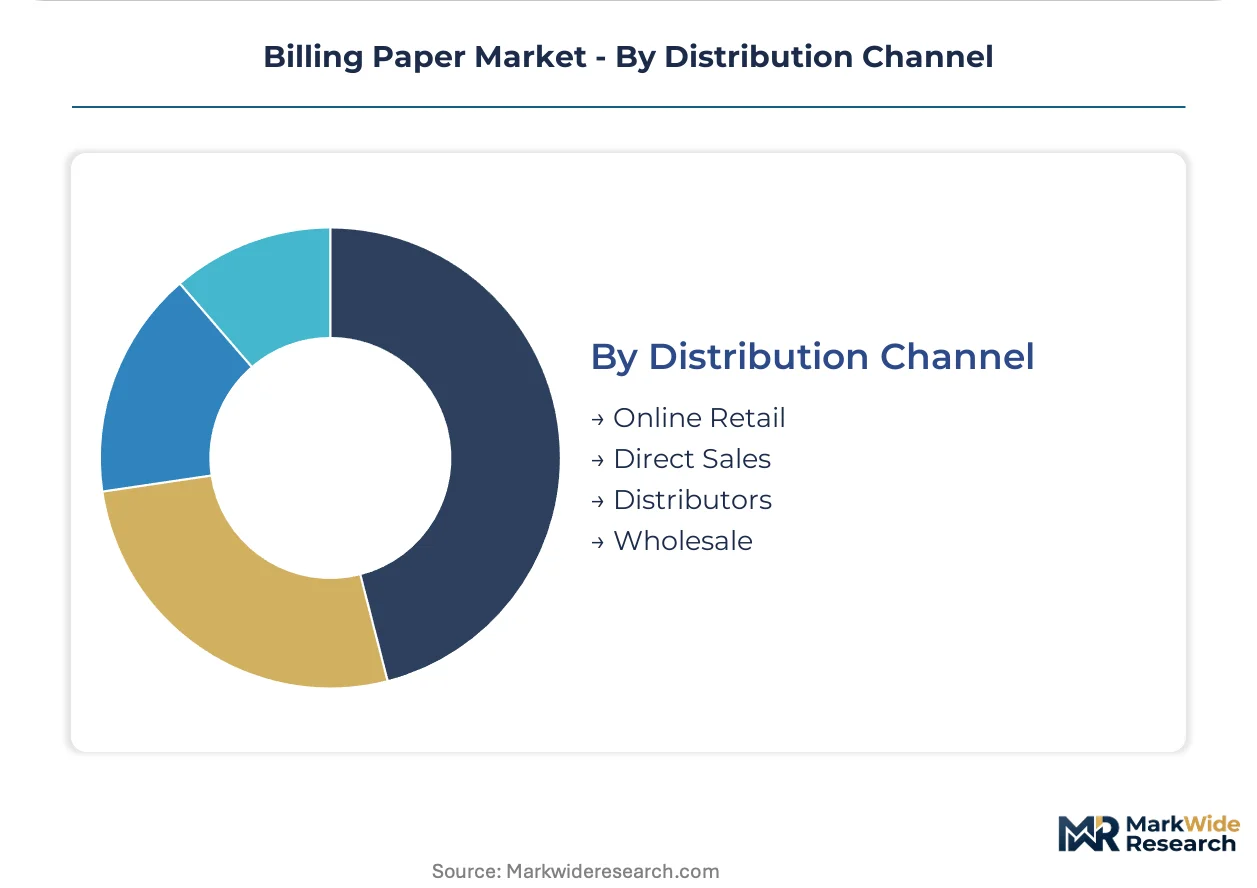
Distribution Channel:
Channel selection reflects order scale, specification complexity, and inventory carrying cost tradeoffs across buyer segments.
- Direct Sales:Manufacturer relationships with health systems and retail chains enable specification co-development and volume commitments.
- Distributors:Regional paper merchants provide just-in-time fulfillment and technical support for mid-scale institutional buyers.
- Wholesale:Bulk purchasing aggregators serve cost-optimized retail and hospitality procurement with standardized grades.
- Online Retail:E-commerce platforms capture small-order, low-specification demand with minimal service overlay.
Direct sales capture the highest-value contracts while online retail expands most quickly in the long-tail segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex underwrites North America's billing paper distribution capacity, handling containerized pulp imports and coated paper exports that sustain cross-border supply chains to healthcare and retail buyers.
United States
Hospital group purchasing organizations in Texas and Florida drive institutional procurement concentration for HIPAA-compliant thermal grades. FDA record retention mandates for healthcare billing documentation sustain demand for ISO 9706-certified archival substrates. The Chicago-Milwaukee corridor hosts converting operations that serve midwestern health systems with just-in-time roll stock fulfillment.
Germany
REACH chemical safety standards accelerate phenol-free thermal coating reformulation timelines ahead of North American schedules. ECHA registration requirements for leuco dye developers increase compliance costs for coating suppliers serving Düsseldorf and Frankfurt medical device clusters. The Ruhr industrial region maintains specialty paper converting capacity for financial services archival documentation.
China
MIIT standards for point-of-sale terminal manufacturing concentrate thermal roll demand in Guangdong and Zhejiang provinces. GB standards for paper permanence influence export-grade substrate specifications serving Southeast Asian healthcare markets. The Yangtze River Delta hosts integrated pulp-to-coating operations that supply domestic retail and hospitality sectors.
Japan
METI energy efficiency regulations shape thermal coating line investments in Shizuoka and Mie prefectures. JIS permanence standards for financial documentation sustain premium-grade carbonless paper demand from Tokyo and Osaka banking clusters. The Kansai region maintains legacy multi-part form printing infrastructure for insurance sector workflows.
India
BIS certification requirements for paper quality create entry barriers for imported thermal grades serving Mumbai and Delhi retail chains. The PLI scheme for domestic manufacturing incentivizes coating line investments in Gujarat and Maharashtra. Bangalore's hospital procurement networks generate fragmented but growing demand for patient billing documentation substrates.
Billing Paper Market Vendor Landscape
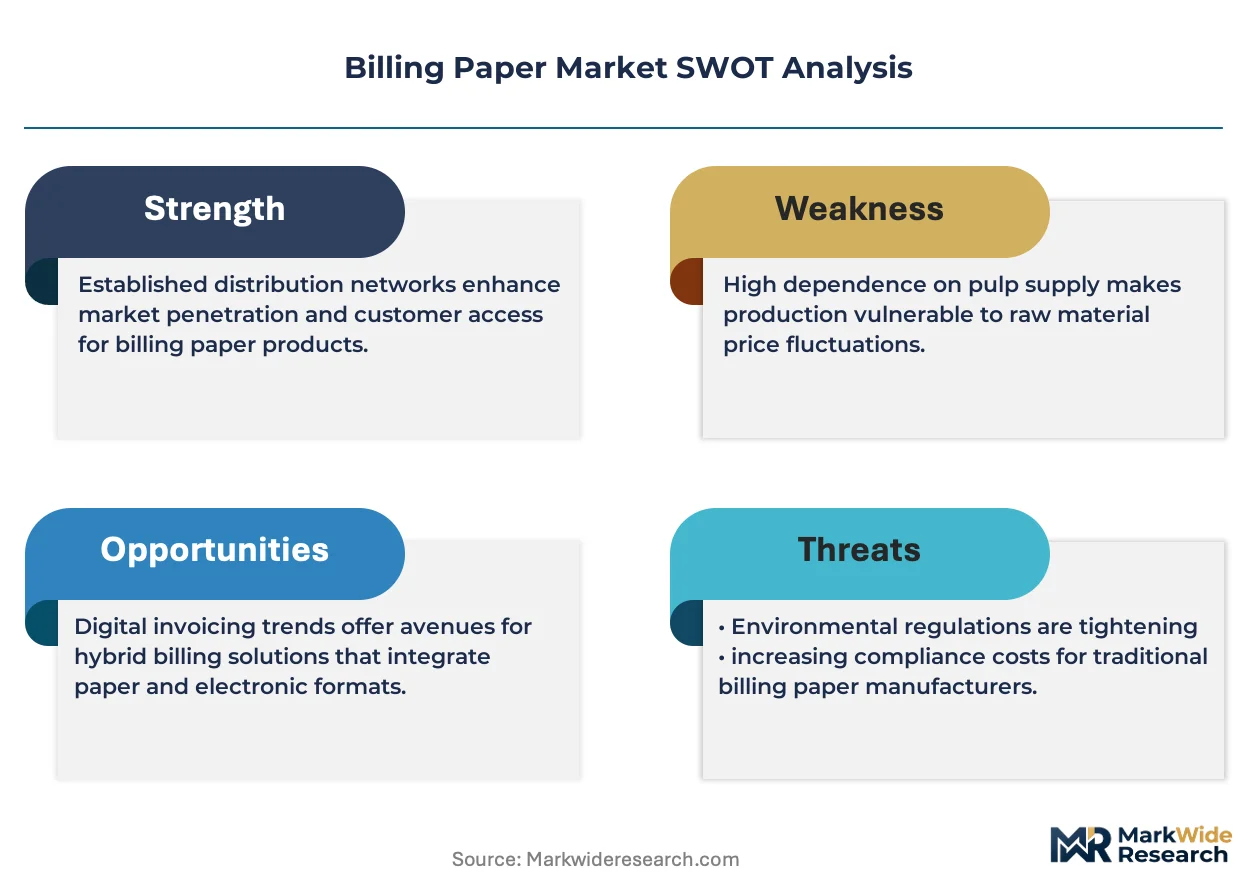
Listed leaders compete with private specialists across capital access and niche technology dimensions, producing a tiered structure where scale-driven pulp producers coexist with coating technology specialists. The market fragments across three strategic archetypes: integrated forest products conglomerates with captive pulp supply, independent coating specialists with proprietary thermal chemistry, and regional converters with health system contracting relationships. Capacity expansion and phenol-free formulation certification represent the dominant competitive moves as regulatory deadlines approach.
Within the integrated producer tier, International Paper and UPM-Kymmene Corporation exemplify scale-driven positioning through North American and Nordic manufacturing footprints. Stora Enso occupies a sustainability-focused position serving corporate procurement mandates with certified fiber sourcing. These three entities anchor the competitive landscape through supply continuity guarantees that hospital group purchasing organizations prioritize over unit cost optimization.
| Leading Market Players |
|---|
| International Paper |
| UPM-Kymmene Corporation |
| Stora Enso |
| Koehler Paper Group |
| Domtar Corporation |
| Sappi Limited |
| Oji Paper Company |
| Kimberly-Clark Corporation |
| Mitsubishi HiTec Paper Europe |
| Others |
Supply Flow & Price Mechanics
Phenol-free thermal coating chemistry substitution is redrawing supply geography and pricing economics across the billing paper value chain. Manufacturers reformulating BPA-alternative coatings face extended certification timelines that compress near-term margins while creating procurement premiums for early movers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates institutional procurement contracts. Price differentiation hinges on ISO 9706 archival certification and guaranteed supply continuity clauses. Pricing pressure stems from EPA-mandated coating reformulation investments that lack immediate pass-through mechanisms. Retail sector buyers exhibit highest price sensitivity, while hospital group purchasing organizations prioritize specification compliance over unit cost.
Supply Chain Analysis
Inbound logistics costs through the Port of Los Angeles-Long Beach complex influence domestic coating line economics and regional competitiveness. Softwood pulp supply concentrates in Canada, Sweden, and Finland, while thermal coating chemical production rests on German and Japanese specialty chemical clusters. Single-source vulnerability runs through concentrated leuco dye developer suppliers. Distribution runs through direct manufacturer relationships with health systems and retail chains, supplemented by regional paper merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Billing paper sits in early-cycle expansion as phenol-free coating certification creates replacement demand across institutional installed bases. HIPAA retention mandates sustain physical substrate demand even as digital alternatives penetrate retail segments.
For Market Incumbents: Shield market position through backward integration into certified sustainable fiber sourcing and captive North American coating capacity. Secure multi-year contracts with hospital group purchasing organizations before phenol-free reformulation deadlines consolidate procurement around qualified suppliers. Prioritize ISO 9706 certification investments to defend premium positioning against commodity thermal grades. For New Entrants and Emerging Players: Lead with phenol-free thermal coating specialization targeting European REACH compliance deadlines ahead of North American schedules. Penetrate mid-scale healthcare facilities in Texas and Florida where fragmented procurement escapes consolidated GPO contracts. Deploy technical sales teams emphasizing coating chemistry expertise over volume scale. For Investors and Strategic Acquirers: EPA bisphenol-A phase-out deadlines reshape the acquisition landscape toward coating technology specialists with certified reformulation pipelines. Long-term viability favors targets with health system contracting relationships and North American manufacturing footprints. Watch for coating line certification delays as the primary inflection signal for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Phenol-Free Coating Certification | EPA compliance deadlines force 18-24 month reformulation investments across North American production lines. |
| Hospital GPO Contract Consolidation | Single-source agreements with supply continuity clauses displace fragmented departmental procurement. |
| Backward Integration into Pulp Supply | Captive softwood fiber sourcing insulates margins from energy and freight cost volatility. |
| Medical Device Integration Partnerships | Specialized billing paper grades for diagnostic equipment printouts open premium hospital supply chain positioning. |
| Extended Archival Specification Development | Century-grade document retention standards command margin concentration in financial services segments. |
Methodological Framework
A standing panel of coating line engineers, hospital procurement managers, health system GPO contract specialists, and thermal paper distribution channel heads provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against FDA guidance documents, EPA chemical safety filings, ISO permanence standards, and hospital procurement database extracts. Bottom-up volume modeling and top-down market sizing underwent iterative reconciliation.
Consistency checks validated projections against external benchmarks including pulp input cost trajectories, point-of-sale terminal deployment data, and health system capital expenditure disclosures. Segmentation modeling spanned substrate chemistry, end-use application, physical form factor, and distribution channel across the analysis window. CAGR derivation incorporated coating line capacity utilization rates, regulatory compliance timeline assumptions, and digital substitution elasticity estimates.
The analysis sits within stated boundaries; outcomes outside sustained HIPAA retention mandates and phenol-free coating certification schedules would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and health system merger trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Bleached Softwood Kraft Pulp Market
Paper Products
Paper Core Market
Paper Products
Greaseproof Paper Sheets Market
Paper Products
Recovered Paper Market
Paper Products
Middle East and Africa Decor Paper Market
Paper Products
BPA Free Thermal Paper Market
Paper Products
Insulation Paper Market
Paper Products
Cheque Paper Market
Paper Products
Drum Pulper Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Sawn Wood Market
Paper Products
Europe Paper Market
Paper Products
Global Security Paper Market
Paper Products
Pharma Grade Paper Market
Paper Products
Thermal Paper Market
Paper Products
Polyester Synthetic Paper Market