
 Decor Paper Market | 2026-2036
Decor Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Decor Paper Market Analysis
Specialty paper distribution through European wholesalers is reconfiguring as laminate producers consolidate supplier bases. Felix Schoeller Group leverages its integrated pulp-to-paper operations across German mills to sustain margin control on coated decor grades. Schattdecor AG anchors global printed paper supply through dedicated service centers in multiple countries. Koehler Paper competes on thermal-cured ink compatibility, a technical specification that differentiates its output for high-speed laminate presses.
Decor paper is a specialty cellulose substrate, typically weighing 60–130 gsm, impregnated with melamine-formaldehyde resins and printed with gravure or digital inks to simulate wood grain, stone, or abstract patterns for lamination onto particleboard or MDF. Its primary purpose is to provide wear-resistant, aesthetically controlled surfaces for furniture, flooring, and interior paneling. Kraft paper grades dominate volume in laminate flooring substrates due to structural tensile requirements during resin saturation and hot pressing. Coated paper commands premium positioning in home decor and wallpaper applications where print fidelity and surface smoothness determine visual quality. Bond paper persists in gift wrapping segments where foldability and crease retention matter more than resin absorption capacity.
REACH registration requirements in Europe and EPA formaldehyde emission standards in the United States constrain resin chemistry choices and limit market access for non-compliant imports. ECHA substance evaluation cycles are accelerating testing obligations for novel pigment formulations used in decor paper printing. ISO 4586 laminate performance standards shape product specifications that ripple back to decor paper basis weight and resin pick-up requirements. Stakeholders must monitor regulatory divergence between EU chemical restrictions and emerging Asian national standards as they decide regional production footprints and certification investments.
Market Dynamics
European laminate flooring manufacturers are consolidating supplier bases around REACH-compliant resin systems, compressing procurement cycles and forcing decor paper mills to certify melamine-formaldehyde formulations at shorter intervals.
Growth Catalysts
- Low-emission adhesive mandates:Germany's engineered wood clusters now require decor papers meeting E1 emission classifications, pulling premium coated grades into residential flooring specifications.
- Digital gravure hybridization:High-speed laminate presses are adopting thermal-cured ink systems that demand specialized substrate porosity profiles, expanding addressable output for technical paper grades.
- Reshoring of laminate production:Particleboard and MDF capacity expansion in Poland and the Czech Republic is shortening logistics loops for decor paper distribution across Central Europe.
Market Restraints
- Pulp cost volatility:Softwood kraft pulp prices fluctuate with Nordic forestry harvest cycles, squeezing margin predictability for uncoated decor paper grades.
- Resin chemistry lock-in:REACH substance evaluation cycles for novel pigments create twelve-to-eighteen-month registration delays that freeze formulation innovation pipelines.
- Substitution by rigid vinyl:SPC flooring manufacturers in residential construction are displacing laminate demand in moisture-prone applications, compressing kraft paper substrate volumes.
Strategic Opportunities
- Wallpaper revival segments:Coated decor papers with enhanced print fidelity are penetrating premium interior paneling applications in France and Italy beyond traditional flooring.
- EU Green Deal alignment:Bio-based resin impregnation technologies qualify for circular economy procurement tenders in public construction projects across the Netherlands and Belgium.
- Service center proximity:Dedicated inventory positioning near laminate press clusters in Austria and Switzerland reduces working capital requirements for just-in-time buyers.
Industry Challenges
- Gravure cylinder engraving scarcity:Skilled technicians capable of precision wood-grain pattern engraving are retiring faster than apprenticeship programs replace them.
- Hot press calibration complexity:Legacy laminate lines require manual adjustment to accommodate decor paper basis weight variations, slowing changeover times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decor Paper Market |
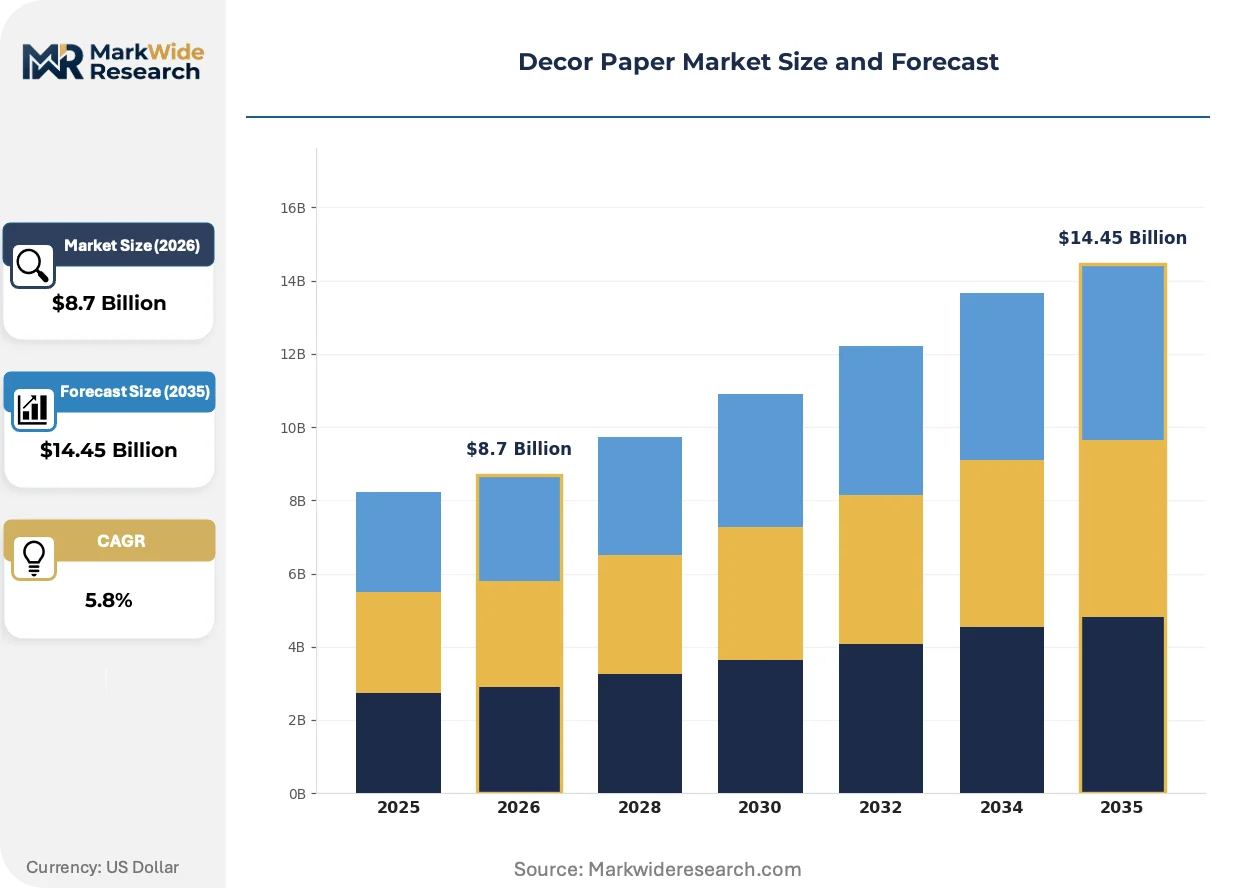
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bond Paper, Kraft Paper, Coated Paper, Mica Paper Application: Gift Wrapping, Home Decor, Wallpaper, Crafting End User: Retailers, Manufacturers, Interior Designers, Consumers Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Supermarkets |
| Companies Covered | Felix Schoeller Group, Toppan Holdings Inc, Schattdecor AG, Lamigraf, ITC Limited, Ahlstrom-Munksjö, SURTECO Group SE, Koehler Paper, Interprint GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decor Paper Market Emerging Trajectories
Decor paper production is bifurcating between commodity kraft substrates for flooring and precision-coated grades for interior surfacing, with digital printing workflows compressing pattern development cycles from months to weeks.
Water-based inkjet deposition systems are virtualizing traditional gravure pattern reproduction for short-run custom decor batches. Boutique furniture manufacturers in Northern Italy are adopting these systems for limited-edition surface collections. The technology is virtualizing economies of scale in pattern design, enabling thousand-meter production runs that were previously uneconomical against cylinder-engraved minimums.
REACH substance evaluation cycles are accelerating testing obligations for novel pigment formulations used in decor paper printing. ECHA's 2024-2025 work program prioritizes azo dye assessments that directly constrain colorant choices for wood-grain simulation. German mills are responding by pre-registering alternative organic pigment portfolios eighteen months ahead of formal evaluation deadlines.
Buyer concentration among laminate flooring OEMs is compressing supplier qualification timelines and unbundling technical service from material supply contracts. Procurement teams at major flooring groups now separate decor paper sourcing from press-line calibration support, treating substrate supply as commodity input. This disintermediation is most pronounced in Austria, where three laminate producers account for the majority of regional decor paper offtake.
Decor Paper Market Segmentation
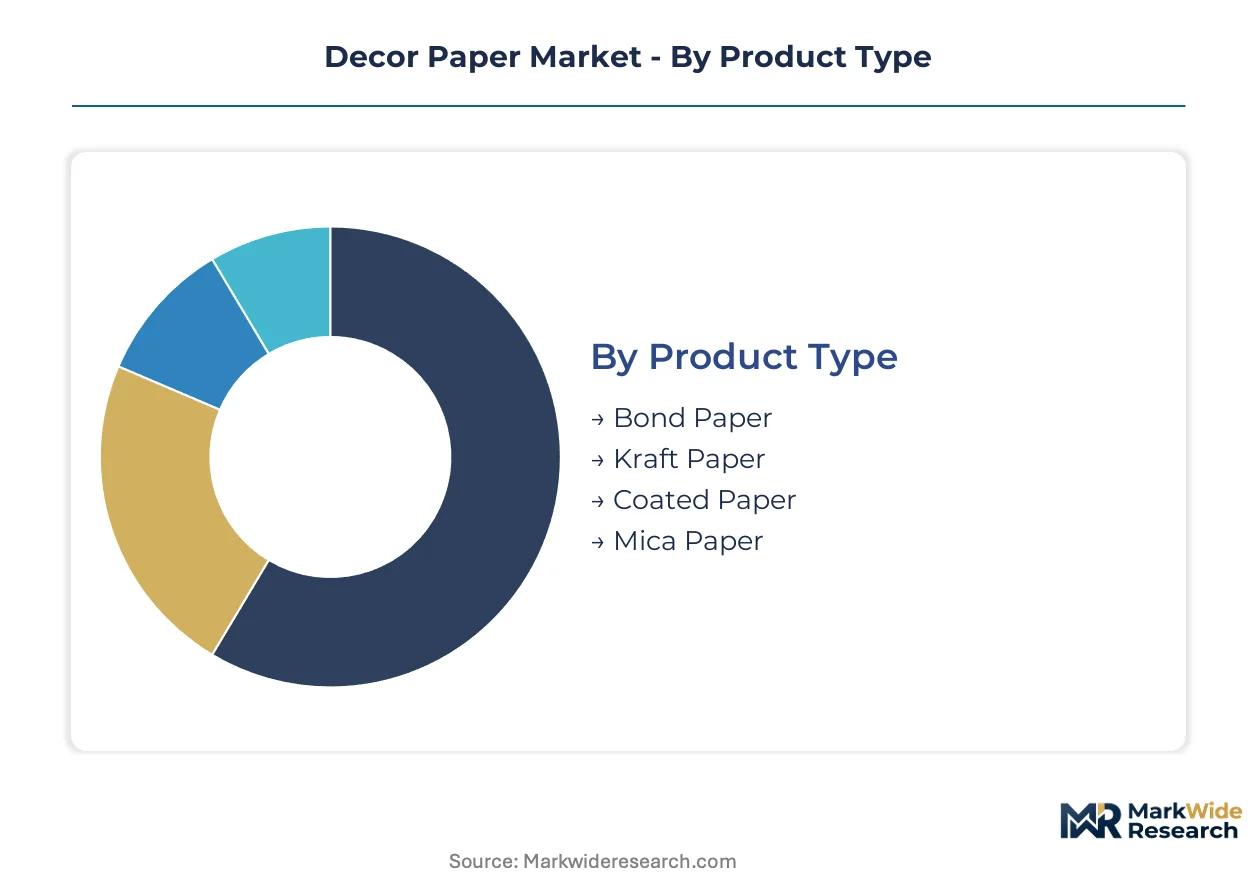
Decor paper procurement cycles vary dramatically across product grades, with flooring substrates turning every 4-6 weeks versus wallpaper stocks rotating quarterly. Understanding these velocity differentials helps mills align capacity scheduling with working capital requirements.
Product Type:
Kraft paper turns fastest in laminate flooring supply chains, while coated grades move slowly through interior design specification channels.
- Kraft Paper:Unbleached softwood pulp substrate weighing 70-130 gsm, engineered for high tensile strength during melamine resin saturation and hot pressing. German engineered wood clusters in the Rhineland and Bavaria anchor procurement volumes as REACH-compliant E1 emission classifications tighten substrate specifications. Pulp cost volatility from Nordic forestry harvest cycles squeezes margin predictability.
- Coated Paper:Kaolin-clay surface treatment over cellulose base, delivering print fidelity for gravure and digital ink systems simulating wood grain or stone patterns. French and Italian interior paneling applications beyond traditional flooring are pulling premium grades into wallpaper revival segments where visual smoothness determines specification.
- Bond Paper:Refined wood pulp substrate with high foldability and crease retention for gift wrapping applications where resin absorption capacity matters less than handling performance.
- Mica Paper:Mineral-reinforced cellulose composite providing thermal resistance and electrical insulation properties for specialty industrial laminates outside mainstream decorative applications.
Kraft paper anchors the volume base while coated paper gains share at the steepest rate.
Application:
Cost tier stratification separates commodity flooring surfaces from premium interior finishes with 3-4x price multiples.
- Home Decor:Laminate flooring and furniture surfacing represents the revenue concentration point, with thermal-cured ink compatibility differentiating technical grades for high-speed press operations. Polish and Czech particleboard capacity expansion is shortening logistics loops across Central Europe.
- Wallpaper:Boutique furniture manufacturers in Northern Italy are adopting water-based inkjet systems for limited-edition surface collections, virtualizing economies of scale in pattern design.
- Gift Wrapping:Seasonal demand spikes concentrate procurement in Q3, with foldability specifications trumping print resolution requirements.
- Crafting:Hobby and DIY segments absorb lower-grade offcuts with minimal technical specification barriers to entry.
Home decor commands the revenue concentration while wallpaper climbs the fastest as digital workflows compress pattern development cycles.
End User:
Customer type determines service intensity, with manufacturers demanding press-line calibration support that retailers no longer bundle with material supply.
- Manufacturers:Laminate flooring OEMs in Austria consolidate procurement among three major producers, unbundling technical service from substrate contracts and treating supply as commodity input.
- Interior Designers:Specification authority in French and Italian premium paneling segments drives coated paper selection based on print fidelity rather than unit cost.
- Retailers:Big-box flooring chains compress supplier qualification timelines and demand just-in-time inventory positioning.
- Consumers:Direct purchasing remains fragmented across online channels with minimal technical consultation requirements.
Manufacturers anchor the volume base while interior designers expand most quickly as specification authority shifts upstream.
Distribution Channel:
Supply concentration in European wholesaler networks is reconfiguring as laminate producers consolidate supplier bases around REACH-compliant resin systems.
- Wholesalers:Specialty paper distribution through European intermediaries is compressing procurement cycles, with dedicated inventory positioning near Austrian and Swiss press clusters reducing working capital for just-in-time buyers.
- Online Retail:Digital channels are penetrating crafting and small-batch gift wrapping segments where pattern variety outweighs bulk pricing advantages.
- Specialty Stores:Regional decor paper merchants in Germany maintain gravure cylinder inventory and pattern libraries that virtual workflows have not yet displaced.
- Supermarkets:Mass retail captures seasonal gift wrapping volume with standardized SKU offerings and minimal technical differentiation.
Wholesalers anchor the volume base while online retail gains share at the steepest rate among non-industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in decor paper logistics, connecting German pulp mills to Austrian laminate press clusters with minimal transshipment friction.
Germany
Engineered wood product clusters in Bavaria and North Rhine-Westphalia pull premium coated grades for residential flooring specifications. REACH substance evaluation cycles through ECHA constrain melamine-formaldehyde resin chemistry choices, forcing mills to pre-register alternative pigment portfolios eighteen months ahead of deadlines. The Rhineland corridor anchors procurement volumes as E1 emission classifications tighten substrate specifications for laminate producers.
Poland
Particleboard and MDF capacity expansion around Poznań and Wrocław shortens logistics loops for kraft paper distribution across Central Europe. The country's national environmental regulator enforces EU-derived low-emission standards that mirror German E1 classifications, enabling seamless cross-border supply integration. Silesian industrial zones concentrate new laminate press installations that source decor paper through just-in-time wholesaler networks.
Czech Republic
Reshoring of laminate production near Brno and Ostrava compresses procurement cycles for decor paper mills serving the Austrian and German markets. EU Green Deal alignment requirements shape public construction tender specifications, favoring bio-based resin impregnation technologies in regional procurement. Moravian manufacturing corridors host expanding service center operations that reduce working capital requirements for press-line operators.
France
Premium interior paneling applications in Île-de-France and Auvergne-Rhône-Alpes drive coated paper selection based on print fidelity rather than unit cost. ANSM and CNIL oversight of chemical safety intersects with EU REACH implementation, creating layered compliance obligations for pigment formulations. Lyon-based design studios specification authority pulls boutique decor paper grades into wallpaper revival segments beyond traditional flooring.
Italy
Boutique furniture manufacturers in Lombardy and Veneto adopt water-based inkjet deposition systems for limited-edition surface collections. The Ministry of Health enforces EU harmonized standards for formaldehyde emissions in wood-based panels, constraining resin chemistry choices for laminate producers. Northern Italian industrial districts concentrate digital printing workflows that compress pattern development cycles from months to weeks.
Decor Paper Market Vendor Landscape
On the supply side, the industry is consolidating around integrated pulp-to-paper operations and specialized printing service centers that compress procurement cycles for laminate OEMs. Three strategic archetypes dominate: vertically integrated German mills controlling coated grade margins, global printed paper specialists operating multi-country service networks, and technical substrate innovators competing on thermal-cured ink compatibility. Capacity expansion near Central European press clusters and strategic partnerships for bio-based resin development represent the dominant competitive moves reshaping positioning.
Among Germany-based integrated producers, Felix Schoeller Group anchors the premium coated grade segment through captive pulp operations. Schattdecor AG exemplifies the global printed paper specialist archetype with dedicated service center positioning across multiple countries. Koehler Paper occupies a position within the technical innovation tier, differentiating output through substrate engineering for high-speed laminate press compatibility. These three entities collectively represent the structural tension between margin control, geographic proximity, and technical specification leadership that defines competitive dynamics.
| Leading Market Players |
|---|
| Felix Schoeller Group |
| Toppan Holdings Inc |
| Schattdecor AG |
| Lamigraf |
| ITC Limited |
| Ahlstrom-Munksjö |
| SURTECO Group SE |
| Koehler Paper |
| Interprint GmbH |
| Others |
Supply Flow & Price Mechanics
REACH substance evaluation cycles for novel pigment formulations create regulatory chokepoints that compress pricing tier spreads between E1-certified coated grades and uncertified kraft substrates while simultaneously forcing mills to regionalize supply chain footprints around ECHA-compliant resin chemistry clusters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates thermal-cured ink-compatible coated grades from commodity kraft paper and off-spec bond paper. Price differentiation hinges on REACH certification status and volume scale, with laminate flooring OEMs extracting steepest discounts through consolidated procurement. Pricing pressure stems from pulp cost volatility in Nordic softwood markets, compressing margins for uncoated grades. Big-box retailers exhibit highest price sensitivity, while interior designers in French premium paneling segments prioritize print fidelity over unit cost.
Supply Chain Analysis
Contract manufacturing concentration sits with Felix Schoeller Group, Schattdecor AG, and Koehler Paper holding integrated pulp-to-paper capacity across German mill networks. Geographic supply concentrates in Germany, Poland, and the Czech Republic, drawing from Nordic softwood pulp, kaolin clay coatings, and melamine-formaldehyde resin systems. Single-source vulnerability runs through gravure cylinder engraving capacity as skilled technician retirements outpace apprenticeship replacement. Distribution runs through European wholesaler networks with dedicated inventory positioning near Austrian and Swiss press clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
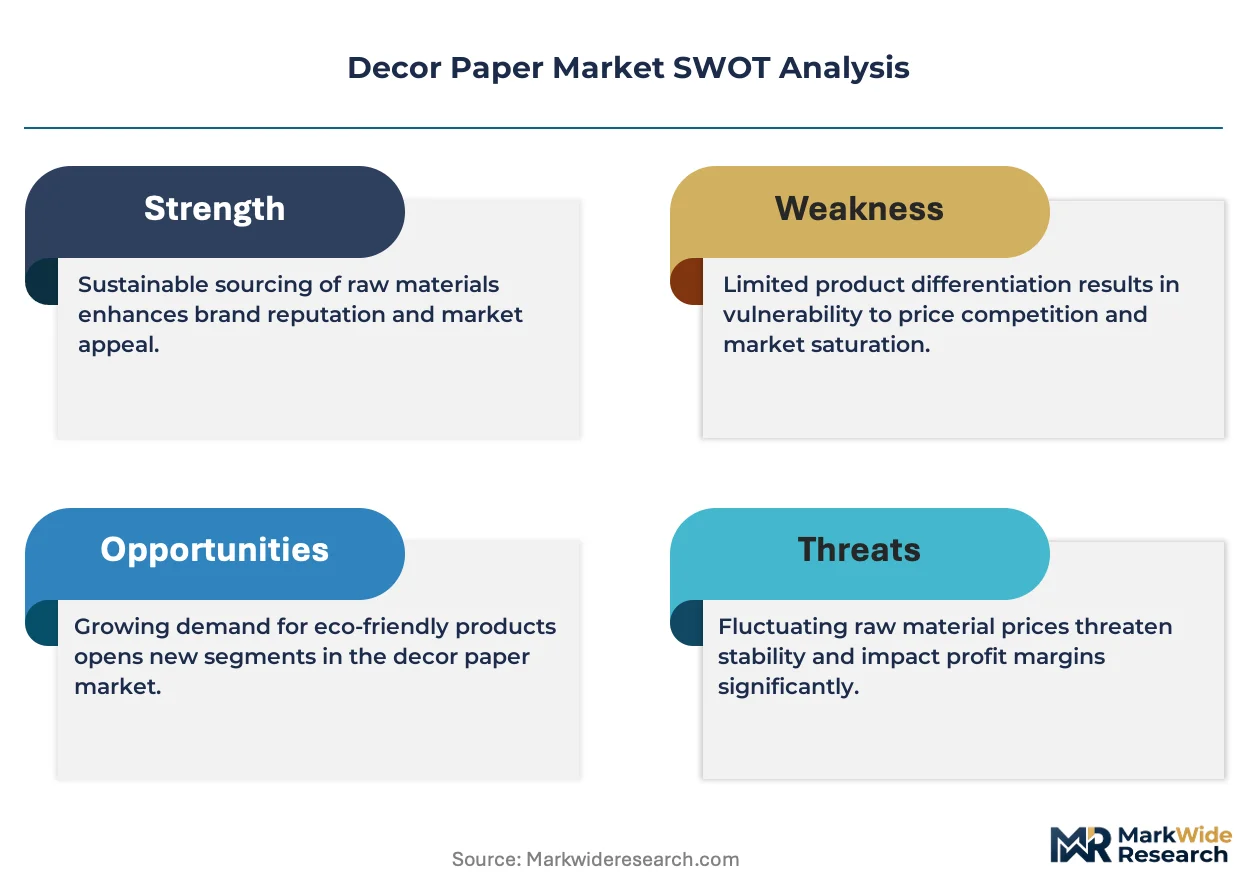
The decor paper market functions as a defensive-moat story anchored in regulatory entrenchment, where REACH compliance investments and E1 certification requirements create switching costs that lock laminate OEMs into qualified supplier relationships.
For Market Incumbents: Entrench position through backward integration into captive pulp operations and pre-registration of alternative organic pigment portfolios eighteen months ahead of ECHA evaluation deadlines. Capacity addition in Polish particleboard corridors captures reshoring laminate production. Digital gravure hybridization threatens cylinder-engraved volume; respond with thermal-cured ink substrate engineering to maintain technical specification leadership.
For New Entrants and Emerging Players: Pursue white-space opportunities in bio-based resin impregnation technologies aligned with EU Green Deal circular economy procurement tenders across Dutch and Belgian public construction. Wallpaper revival segments in French and Italian interior paneling offer most penetrable entry point with lower certification barriers than flooring. Go-to-market through boutique furniture manufacturers adopting water-based inkjet systems for limited-edition surface collections.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated pulp-to-paper specialists with REACH-compliant resin chemistry capabilities and multi-country service center networks. Long-term viability over a five-to-ten year window rests on regulatory compliance infrastructure rather than commodity scale. Acquisition target archetype: technical substrate innovators competing on thermal-cured ink compatibility with established laminate press calibration relationships. Monitor ECHA substance evaluation cycle acceleration as inflection indicator for pigment formulation disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Operations | Felix Schoeller Group's captive softwood supply insulates margin control from Nordic harvest volatility. |
| Multi-Country Service Center Expansion | Schattdecor AG's dedicated inventory positioning near Austrian press clusters compresses procurement cycles. |
| Bio-Based Resin Technology Partnership | EU Green Deal alignment in Netherlands and Belgium unlocks circular economy public tender access. |
| Digital Gravure Hybridization Investment | Thermal-cured ink compatibility differentiates Koehler Paper output for high-speed laminate press operations. |
| Alternative Pigment Portfolio Pre-Registration | German mills' eighteen-month ECHA advance registration defends against azo dye assessment disruption. |
Methodological Framework
A standing panel of laminate flooring procurement directors, decor paper mill technical managers, gravure cylinder engraving specialists, and European specialty paper distributors provided ongoing calibration across the study. Primary interviews combined with secondary validation from ECHA substance evaluation databases, EU customs trade records for pulp and paper flows, SEC filings of publicly listed laminate producers, and ISO 4586 laminate performance standard documentation. Bottom-up capacity modeling triangulated against top-down consumption estimates across product grades and application segments.
Scenario-bracketing framed analytical approach across the projection horizon, modeling volume and value outputs through segmentation by product type (kraft, coated, bond, mica), application (home decor, wallpaper, gift wrapping, crafting), end user (manufacturers, interior designers, retailers, consumers), and distribution channel (wholesalers, online retail, specialty stores, supermarkets). CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology substitution curves. Industry-specific forecast inputs included Nordic softwood pulp price cycles and ECHA work program prioritization schedules.
Sensitivities concentrate around ECHA substance evaluation acceleration, SPC flooring substitution rates in moisture-prone residential applications, and gravure cylinder engraving capacity attrition. Forecasts reflect assumptions on REACH compliance cost pass-through and laminate production reshoring momentum. Quarterly review of ECHA pre-registration volumes, Polish particleboard capacity utilization, and Italian digital printing adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Global Electrical Insulation Paper Market
Paper Products
Sawn Wood Market
Paper Products
Global Kraft Paper Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Aramid Paper Market
Paper Products
Glassine Paper Market
Paper Products
Asia-Pacific Thermal Paper Market
Paper Products
Household Paper Market
Paper Products
Americas Stone Paper Market
Paper Products
Saturated Kraft Paper Market
Paper Products
Clay Coated Paper Market
Paper Products
Global Molded Pulp Products Market
Paper Products
GCC Paper Products Market
Paper Products
Greaseproof Paper Market
Paper Products
Writing Paper Market
Paper Products
Overlay Paper Market