
 Asia-Pacific Tank Insulation Market | 2026-2036
Asia-Pacific Tank Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Tank Insulation Market Insights
Liquefied natural gas storage is realigning demand patterns across the Asia-Pacific tank insulation landscape. Owens Corning leverages its fiberglass technology leadership to anchor supply relationships with Australian LNG terminal operators. BASF SE competes through polyurethane foam formulations engineered for extreme cryogenic temperatures. Omkar Puf Insulation Pvt. Ltd. dominates domestic project execution across India's expanding petroleum refining network.
Asia-Pacific tank insulation comprises engineered thermal barrier systems applied to stationary and transport vessels to minimize heat transfer and maintain stored contents at specified temperatures, typically incorporating fiberglass, polyurethane foam, or rock wool composites with lambda values below 0.025 W/mK. These systems prevent energy loss, reduce vaporization in cryogenic applications, and ensure regulatory compliance for hazardous material containment. Rigid insulation products occupy the premium tier in LNG and chemical storage, while flexible blanket formats lead retrofit installations across aging oil storage terminals. Spray foam applications represent the fastest-growing product category, driven by complex geometries in pharmaceutical processing equipment and food-grade tank construction across Japan and South Korea.
China's MEE enforces escalating thermal efficiency mandates for industrial storage facilities under national dual carbon targets, while India's BIS certifies insulation materials for fire safety and thermal conductivity thresholds in hydrocarbon processing. South Korea's MFDS and Japan's METI coordinate standards for pharmaceutical and food-contact insulation systems, creating segmented compliance pathways. Stakeholders must monitor divergence between national certification regimes and the emerging ISO harmonization timeline to optimize regional manufacturing footprints.
Market Dynamics
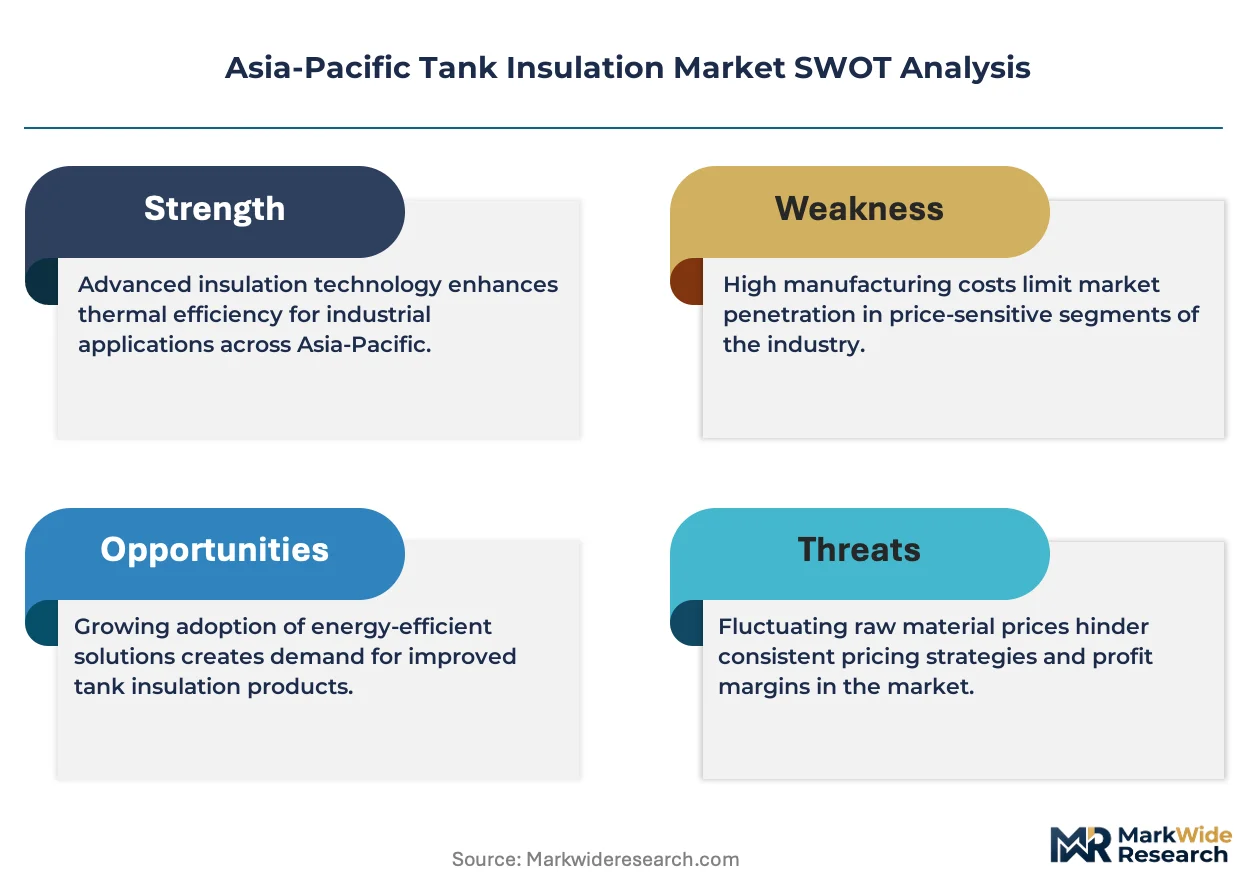
China's dual carbon mandates and India's BIS thermal certification regime are forcing material specification upgrades across Asia-Pacific industrial storage, compressing supplier margins while accelerating substitution toward cryogenic-grade polyurethane and aerogel composites.
Growth Catalysts
- LNG infrastructure buildout:Southeast Asian terminal operators are procuring multi-layer vacuum insulation systems for import facilities in Vietnam, Thailand, and the Philippines. This creates sustained demand for cryogenic-grade material suppliers.
- India's PLI scheme for petrochemicals:The production-linked incentive framework is expanding refining capacity along the Gujarat-Maharashtra corridor, requiring fire-rated tank insulation for new storage assets.
- South Korea's hydrogen economy roadmap:Liquid hydrogen storage protocols are mandating ultra-low thermal conductivity barriers, opening specialized procurement channels for advanced composite systems.
Market Restraints
- MDI price volatility:Polyurethane feedstock costs fluctuate with crude oil indices, squeezing margin predictability for spray foam applicators across Japanese pharmaceutical tank projects.
- Supplier concentration in glass fiber:Australian LNG terminal operators depend on a narrow base of fiberglass mat producers, creating vulnerability to allocation constraints during peak construction windows.
- Technical limitation in retrofit compatibility:Aging oil storage terminals in Indonesia and Malaysia cannot accommodate rigid panel systems without structural reinforcement, limiting addressable volume.
Strategic Opportunities
- Vietnam's emerging LNG import capacity:First-mover insulation contractors can establish specification relationships before terminal operators finalize long-term maintenance contracts.
- Modular prefabrication convergence:Factory-applied insulation panels integrated with IoT temperature monitoring are compressing field installation timelines for Japanese food-grade tank builders.
- China's MEE efficiency mandates:Escalating thermal performance thresholds for industrial storage are disqualifying legacy mineral wool suppliers, creating substitution openings for aerogel composite specialists.
Industry Challenges
- Cryogenic welding certification gaps:Qualified technicians for vacuum-insulated pipe connections remain scarce across Southeast Asian project sites, extending commissioning timelines.
- Multi-jurisdiction compliance complexity:Suppliers serving Australia, South Korea, and Japan simultaneously must maintain parallel certification tracks with TGA, MFDS, and METI, inflating quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Tank Insulation Market |
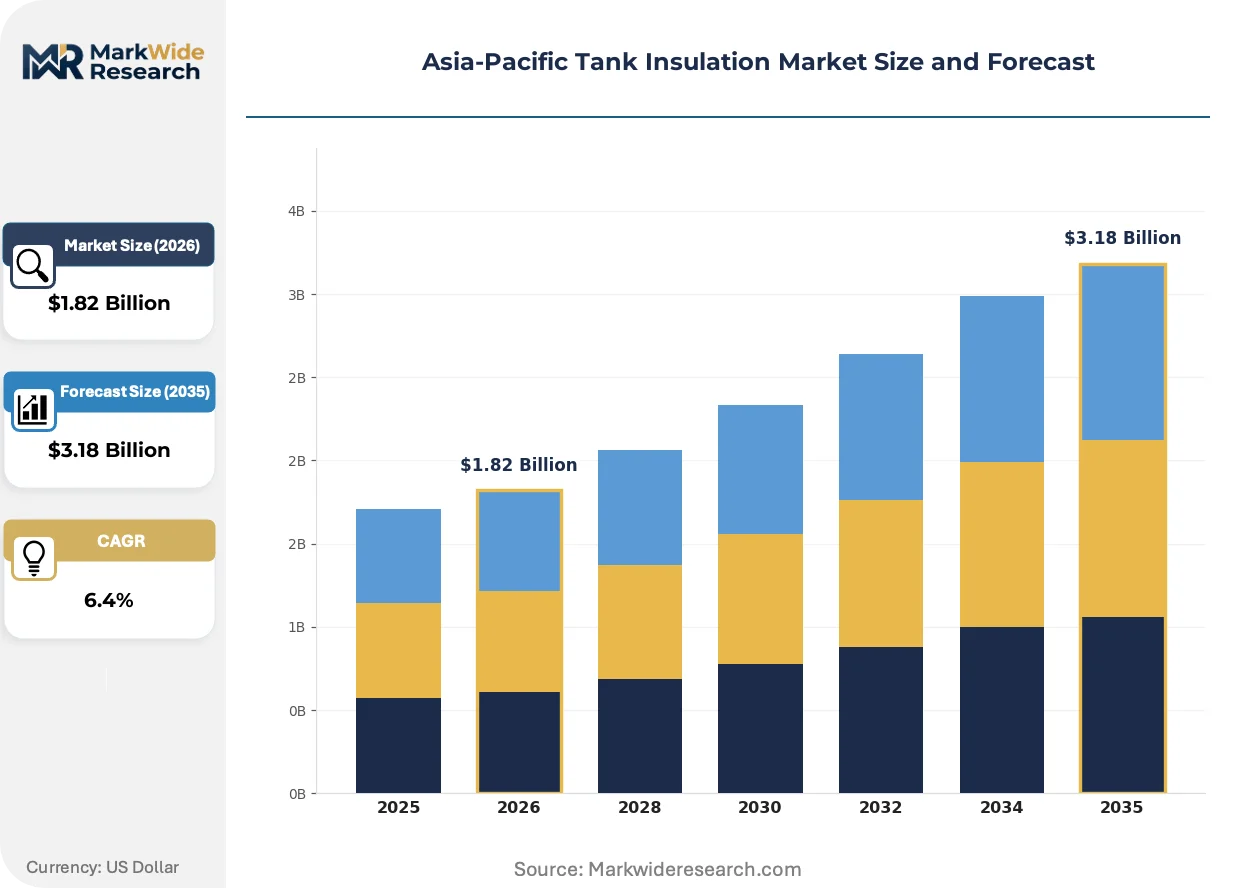
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insulation Material: Fiberglass, PVC, Rock Wool, Foam Application Area: Chemical Storage, Liquefied Gas, Oil Storage, Food Processing End User Industry: Oil & Gas, Chemicals, Pharmaceuticals, Food & Beverage Product Type: Rigid Insulation, Flexible Insulation, Blanket Insulation, Spray Foam |
| Companies Covered | BASF SE, Owens Corning, Armacell International S.A., Johns Manville, Rockwool International A/S, Saint-Gobain, Knauf Insulation, Kingspan Group, Omkar Puf Insulation Pvt. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Tank Insulation Market Trends and Innovations
Spray-applied polyurethane systems with embedded sensor networks are displacing conventional blanket formats across Asia-Pacific tank construction, while regulatory pressure on embodied carbon is reshaping material selection protocols.
Aerogel-infused blanket insulation is decentralizing project execution for pharmaceutical and biotech tank fabricators in Japan and South Korea. Manufacturers are specifying these composites for complex vessel geometries where rigid panels fail. The technology is decentralizing installation expertise requirements, allowing smaller regional contractors to bid on precision-grade projects previously reserved for specialized firms.
China's MEE thermal efficiency mandates under national dual carbon targets are disqualifying conventional fiberglass systems from new industrial storage permits. Facility operators in Shandong and Jiangsu provinces face retrofit deadlines that compress procurement cycles. Cryogenic LNG terminals are responding fastest, accelerating specification shifts toward vacuum-insulated panel alternatives.
Japanese pharmaceutical tank operators are unbundling insulation specification from general construction contracts, creating direct procurement relationships with material specialists. This pattern compresses distributor margins while rewarding technical advisory capabilities. South Korean shipbuilders are replicating the model for LNG carrier cargo tank insulation, bypassing traditional marine engineering intermediaries.
Asia-Pacific Tank Insulation Market Segmentation
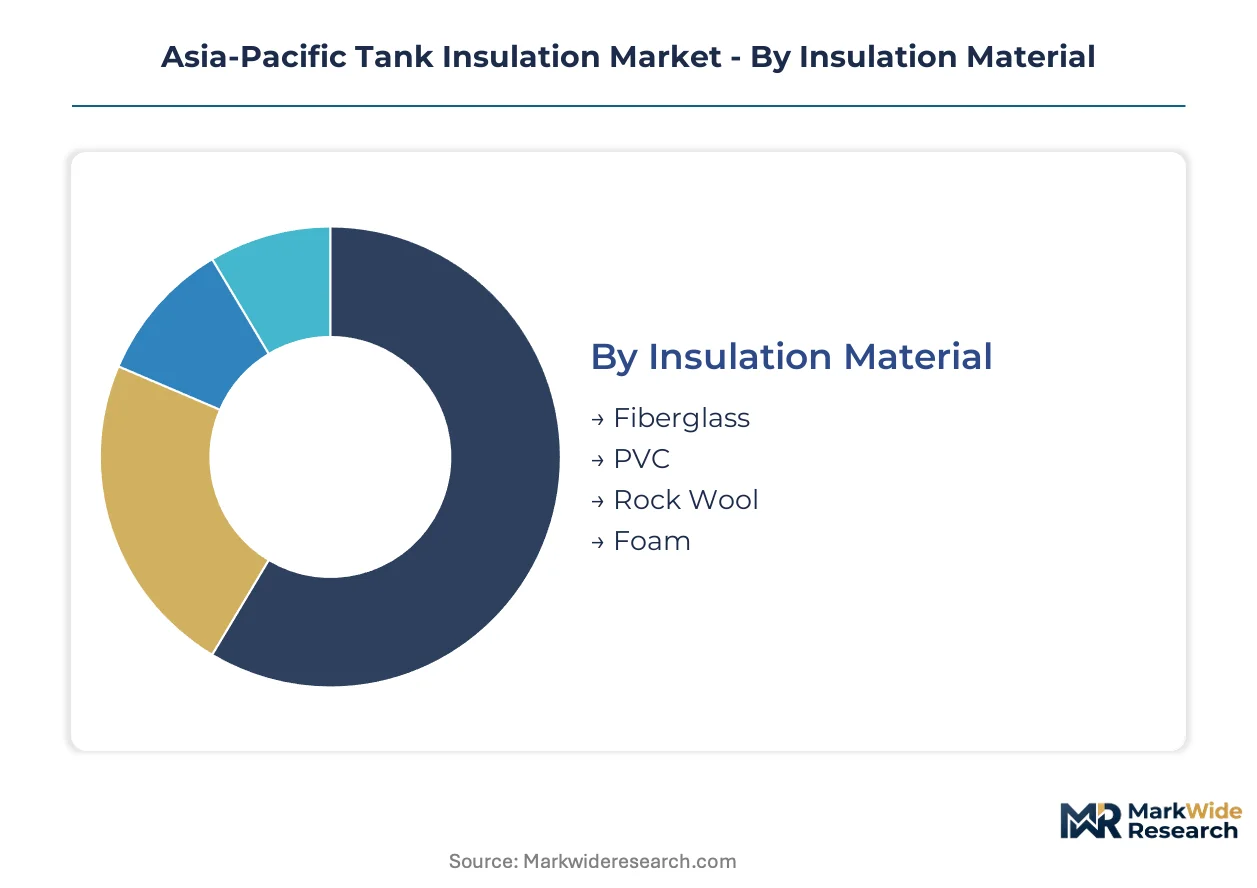
Tank insulation procurement in Asia-Pacific fragments across material chemistry, application temperature requirements, and installation methodology. Specification decisions hinge on compliance with national thermal performance mandates and end-use certification regimes.
Insulation Material:
Certification burden varies sharply by material chemistry. India's BIS thermal conductivity thresholds and China's MEE efficiency mandates disqualify certain formulations from industrial permits, while cryogenic applications require additional cryogenic-grade validation.
- Fiberglass:Woven glass fiber mats with lambda values near 0.035 W/mK dominate Australian LNG terminal construction. Owens Corning anchors supply relationships with Queensland and Western Australia export hub operators, though supplier concentration creates allocation vulnerability during peak buildout windows.
- Foam:Polyurethane and polyisocyanurate formulations engineered for lambda values below 0.025 W/mK lead cryogenic LNG storage specifications. BASF SE competes through extreme low-temperature formulations, while MDI feedstock price volatility compresses margin predictability for Japanese pharmaceutical tank applicators.
- Rock Wool:Mineral fiber batts with fire-rated performance serve India's petrochemical corridor under BIS fire safety certification. Gujarat-Maharashtra refining expansion drives specification volume.
- PVC:Closed-cell foam sheets with moisture resistance properties address food-contact applications in Japan and South Korea under METI and MFDS standards.
Fiberglass sits at the top of the volume ranking, with foam climbing the fastest.
Application Area:
Operating temperature regimes determine material specification tiers. Cryogenic applications command premium-grade systems with multi-layer vacuum construction, while ambient storage accepts conventional blanket formats.
- Liquefied Gas:LNG and liquid hydrogen storage mandate ultra-low thermal conductivity barriers with vacuum-insulated panel alternatives. Vietnam, Thailand, and Philippines terminal buildouts are accelerating procurement of cryogenic-grade systems.
- Chemical Storage:Corrosion-resistant fiberglass and PVC composites serve aggressive chemical environments. India's expanding refining network under PLI scheme incentives drives fire-rated specification volume.
- Oil Storage:Aging terminals across Indonesia and Malaysia face retrofit constraints where rigid panel systems require structural reinforcement, limiting addressable volume for conventional formats.
- Food Processing:Food-contact certified insulation with embedded temperature monitoring serves Japanese and South Korean pharmaceutical and biotech tank fabricators. Direct procurement relationships with material specialists are displacing distributor channels.
Liquefied gas commands the steepest price tier, with food processing gaining share fastest.
End User Industry:
Industry-specific regulatory tracks fragment supplier certification requirements. Oil and gas operators prioritize fire safety ratings, while pharmaceutical and food processors demand food-contact compliance with traceability protocols.
- Oil & Gas:Hydrocarbon storage and LNG export infrastructure across Australia, India, and Southeast Asia require BIS, TGA, and national fire code compliance. Terminal operators are unbundling insulation specification from general construction contracts.
- Chemicals:Petrochemical processing and hazardous material containment in China's Shandong and Jiangsu provinces face MEE retrofit deadlines that compress procurement cycles.
- Pharmaceuticals:Japanese tank operators under PMDA and METI oversight specify aerogel-infused blankets for complex vessel geometries where rigid panels fail.
- Food & Beverage:South Korean and Japanese food-grade tank builders source factory-applied insulation panels with IoT temperature monitoring to compress field installation timelines.
Oil and gas anchors revenue concentration, with pharmaceuticals expanding most quickly.
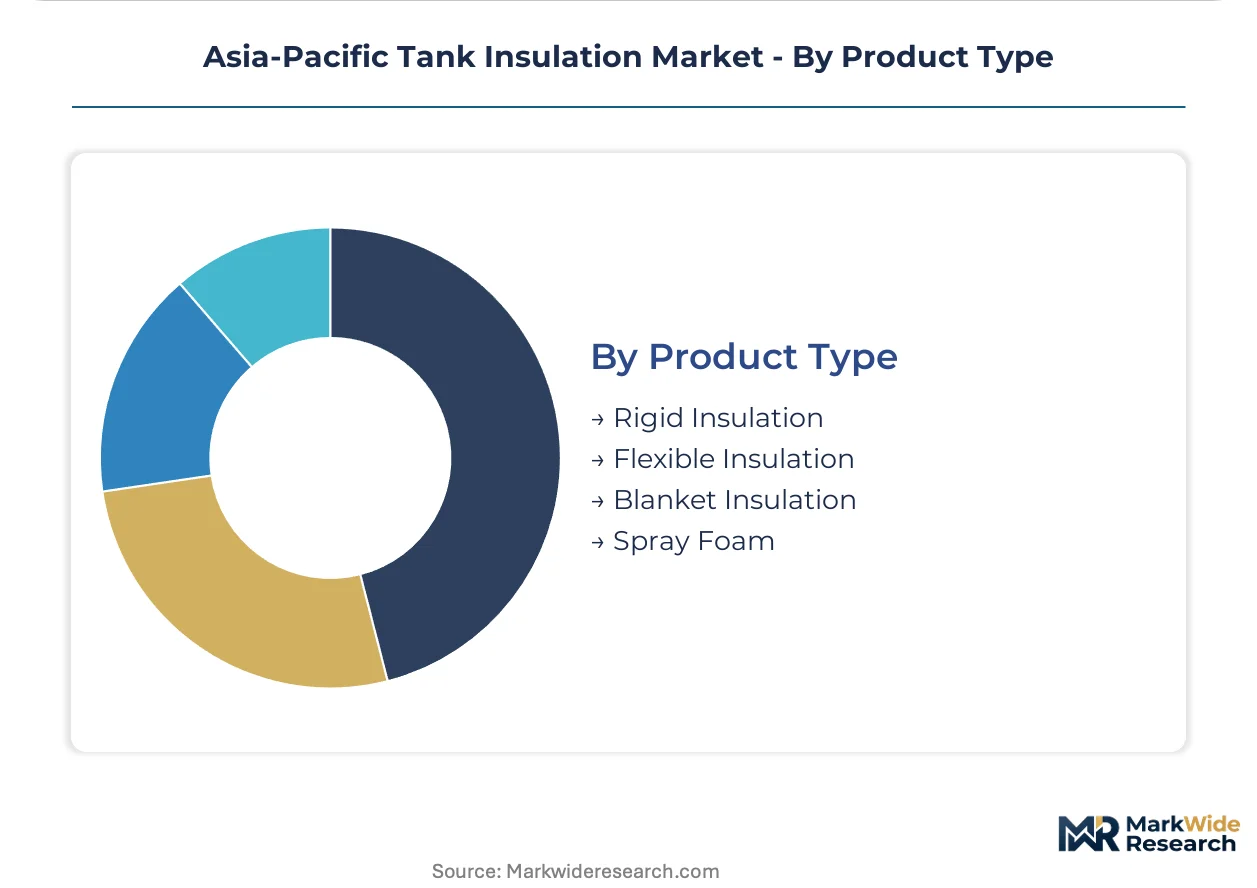
Product Type:
Installation methodology determines labor cost structure and field execution timeline. Factory-applied systems reduce site labor but require precise dimensional coordination, while field-applied formats accommodate retrofit constraints.
- Spray Foam:Polyurethane systems with embedded sensor networks are displacing conventional blankets across Asia-Pacific tank construction. Complex geometries in pharmaceutical processing equipment and food-grade tank construction in Japan and South Korea drive specification.
- Rigid Insulation:Pre-formed panels with factory-integrated vapor barriers serve new LNG terminal construction. Premium positioning in cryogenic and chemical storage segments supports margin structure.
- Flexible Insulation:Wrap-around blanket formats lead retrofit installations across aging oil storage terminals where structural reinforcement is impractical.
- Blanket Insulation:Aerogel-infused composites decentralize project execution for pharmaceutical and biotech tank fabricators, allowing smaller regional contractors to bid on precision-grade projects.
Rigid insulation captures the premium tier, with spray foam showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing tank insulation procurement across Asia-Pacific as manufacturers migrate production toward jurisdictions with narrower certification burdens. Cost-of-compliance gaps between national thermal performance regimes are reshaping regional supply footprints and project execution strategies.
China
Shandong and Jiangsu province refineries face compressed retrofit cycles under MEE thermal efficiency mandates. The national dual carbon targets disqualify legacy mineral wool systems from new industrial permits. Cryogenic LNG terminals in Yangkou and Tianjin accelerate vacuum-insulated panel adoption ahead of enforcement deadlines.
India
Petrochemical storage expansion along the Gujarat-Maharashtra corridor drives fire-rated specification volume. BIS thermal conductivity certification and PLI scheme incentives align procurement toward domestic execution capabilities. Reliance Industries and Indian Oil terminal operators unbundle insulation specification from general EPC contracts.
Australia
Queensland and Western Australia LNG export hubs anchor regional demand for woven fiberglass mat systems. TGA certification requirements for hazardous material containment create procurement friction for non-domestic suppliers. Peak construction windows expose allocation vulnerability in glass fiber feedstock channels.
Japan
Pharmaceutical tank fabricators in Kanto and Kansai regions specify aerogel-infused blankets for complex vessel geometries. METI food-contact standards and PMDA oversight compress distributor margins through direct material specialist relationships. Embedded sensor network integration differentiates supplier selection in biotech processing equipment.
South Korea
Busan-Ulsan shipbuilding clusters and Seoul Capital Area hydrogen storage projects mandate ultra-low thermal conductivity barriers. MFDS pharmaceutical certification and the national hydrogen economy roadmap open specialized procurement channels for advanced composite systems. Factory-applied panels with IoT monitoring compress field installation timelines.
Asia-Pacific Tank Insulation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cryogenic-grade system providers commanding premium positioning against commodity blanket fabricators. The vendor base concentrates around three strategic archetypes: multinational chemical conglomerates with polyurethane formulation depth, regional fiberglass mat producers serving LNG terminal construction, and domestic execution specialists anchored to national certification regimes. Competitive moves center on backward integration into MDI feedstock channels and technology licensing partnerships for aerogel composite manufacturing.
Among multinational chemical conglomerates, BASF SE and Owens Corning occupy positions exemplifying divergent specialization vectors. BASF SE represents the extreme low-temperature formulation archetype, while Owens Corning anchors the fiberglass technology leadership tier. Omkar Puf Insulation Pvt. Ltd. sits within the domestic execution specialist category, its Mumbai-based structure reflecting the India-centric certification alignment pattern visible across regional contract manufacturers.
| Leading Market Players |
|---|
| BASF SE |
| Owens Corning |
| Armacell International S.A. |
| Johns Manville |
| Rockwool International A/S |
| Saint-Gobain |
| Knauf Insulation |
| Kingspan Group |
| Omkar Puf Insulation Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
MDI spot price indices cascading from crude oil benchmarks compress margin predictability for polyurethane foam applicators across Japanese pharmaceutical tank projects, while fiberglass mat allocations from concentrated Australian suppliers create tiered pricing pressure across LNG terminal procurement cycles. Buyers in cryogenic-grade segments face asymmetric cost exposure where feedstock volatility in MDI channels contrasts with allocation-constrained glass fiber premiums in Queensland and Western Australia export hub construction.
Pricing Analysis
Distributor margins in blanket insulation formats face compression as Japanese pharmaceutical tank operators unbundle specification from general construction contracts and source aerogel composites directly from material specialists. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-insulated panel systems for cryogenic LNG storage from conventional fiberglass mats in ambient chemical storage and flexible retrofit formats in aging Indonesian oil terminals. Price differentiation hinges on BIS fire safety certification grade in India's petrochemical corridor and METI food-contact compliance in Japanese biotech processing. Cost compression in spray polyurethane tiers is intensifying because MDI feedstock costs fluctuate with energy indices. Refinery operators under India's PLI scheme demonstrate highest price sensitivity due to volume-scale procurement, while South Korean hydrogen storage projects show lowest sensitivity given ultra-low thermal conductivity mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Australian LNG terminal operators and Indian refining majors, while specialized distributors serve fragmented pharmaceutical and food-grade tank fabricators in Japan and South Korea. Geographic supply concentration centers on China for MDI and polyol feedstocks, Australia for woven fiberglass mat production, and South Korea for advanced composite vacuum panel manufacturing. Raw material dependencies rest on crude oil derivatives for polyurethane formulations, silica-based precursors for aerogel composites, and borosilicate glass for high-temperature fiberglass systems. Single-source vulnerability in Australian glass fiber mat production creates allocation risk during peak Queensland and Western Australia construction windows. Distribution runs through national certification-aligned channels where BIS, TGA, and MFDS compliance requirements fragment cross-border supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's MEE thermal efficiency mandates and national dual carbon targets continuously escalate material specification thresholds, compressing legacy supplier margins while opening substitution premiums for cryogenic-grade and aerogel composite specialists.
For Market Incumbents: Acquire MDI feedstock capacity or secure long-term offtake agreements with Baselland and Shanghai-based polyol producers to anchor margin predictability against crude oil index volatility. Backward integration into glass fiber mat production in Queensland or Western Australia mitigates allocation vulnerability during Australian LNG terminal peak buildout windows. Certification investment in BIS thermal conductivity and fire safety tiers defends position against domestic Indian execution specialists capturing PLI scheme-driven refining expansion. For New Entrants and Emerging Players: Specialized insulation contractors in Vietnam's emerging LNG import terminal market offer first-mover specification relationships before operators finalize long-term maintenance contracts. Factory-applied panel integrators with embedded IoT temperature monitoring capabilities penetrate Japanese food-grade tank construction where field installation timeline compression commands premium positioning. Direct procurement relationships with pharmaceutical tank fabricators in Kanto and Kansai regions bypass distributor margin compression and reward technical advisory capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with aerogel composite specialists positioned for China's MEE retrofit deadlines in Shandong and Jiangsu province industrial storage. Long-term viability over the 5-10 year window favors acquisition targets with dual certification tracks across cryogenic-grade validation and national thermal performance regimes. Monitor specification unbundling velocity in Japanese pharmaceutical and South Korean shipbuilding segments as inflection indicator for distributor margin erosion and direct procurement normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Feedstock | Anchors margin predictability for polyurethane foam applicators against crude oil index volatility in Japanese pharmaceutical tank projects. |
| Aerogel Composite Manufacturing Scale-Up | Captures substitution openings as China's MEE mandates disqualify legacy mineral wool from new industrial permits. |
| Factory-Applied Panel IoT Integration | Compresses field installation timelines for South Korean food-grade tank builders under MFDS certification requirements. |
| Vietnam LNG Terminal First-Mover Positioning | Establishes specification relationships before terminal operators finalize long-term maintenance contracts in Southeast Asian import capacity buildout. |
| Dual Certification Track Investment | Enables simultaneous TGA, MFDS, and METI compliance for suppliers serving Australian, South Korean, and Japanese markets without parallel quality assurance overhead. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with LNG terminal procurement officers, petrochemical plant engineers, pharmaceutical tank fabricators, and insulation contractor project managers with secondary validation through customs trade data, BIS certification registries, MEE permit filings, and SEC disclosures from multinational chemical conglomerates. Bottom-up project pipeline assessment across Vietnam, Thailand, Philippines, and Australian LNG import and export facilities triangulated against top-down material consumption estimates from MDI and fiberglass mat producers.
Historical reference periods anchored volume and value outputs to demonstrated construction completion rates across the analysis window, with forward projections modeling material chemistry, application temperature tier, installation methodology, and end-use industry regulatory cluster as core segmentation dimensions. CAGRs derived from regression analysis of capital expenditure timing in LNG infrastructure, PLI scheme incentive disbursement patterns in Indian petrochemicals, and hydrogen economy roadmap implementation phases in South Korea.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MDI price volatility, Australian glass fiber allocation constraints during peak construction seasons, and divergence between national certification regimes and ISO harmonization timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Phase Change Materials Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
Americas Pipe Insulation Market
Insulation Materials
Flexible Insulation Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
Radiation Shielding Materials Market
Insulation Materials
Microporous Insulation Material Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
Industrial Insulation Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Asia-Pacific Insulation Materials Market
Insulation Materials
Insulation Products Market
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
Wire Insulation and Jacketing Compounds Market
Insulation Materials
Global Advanced Insulation Material Market