
 US Industrial Insulation Market | 2026-2036
US Industrial Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
US Industrial Insulation Market Insights
Aftermarket service revenue is fragmenting across the US industrial insulation value chain as original equipment margins compress and lifecycle contracting gains traction. Owens Corning leverages its fiberglass manufacturing scale to dominate specification-driven new construction channels. Johns Manville Corporation anchors its position through backward integration into mineral wool feedstock and captive distribution networks. Aspen Aerogels differentiates via aerogel technology leadership in subsea and cryogenic applications where thermal performance premiums command durable pricing power.
US industrial insulation comprises engineered thermal barriers—typically fiberglass batts rated to 1,000°F, mineral wool boards exceeding 2,200°F, or closed-cell foam systems with lambda values below 0.020 W/m·K—installed on process equipment to reduce heat loss, control surface temperatures, and conserve energy in continuous operations. Fiberglass retains the largest installed base across power generation and manufacturing facilities due to cost efficiency and code familiarity. Rock wool commands premium positioning in high-temperature process lines and fire-rated assemblies where ASTM E136 noncombustibility governs specification. The retrofit installation segment is expanding fastest as aging infrastructure across the Midwest and Southeast drives maintenance and repair volumes beyond new construction cycles.
OSHA 1910.147 lockout/tagout and thermal hazard standards mandate protective surface temperatures below 140°F on accessible equipment, directly expanding insulation specification scope in refineries and chemical plants. EPA New Source Performance Standards under the Clean Air Act enforce fugitive emissions controls that require intact insulation systems on valves, flanges, and pressure vessels. Stakeholders must monitor evolving Department of Energy efficiency rulemakings and state-level decarbonization mandates that will recalibrate payback thresholds for advanced insulation materials against conventional systems.
Market Dynamics
Retrofit installation volumes across the US Midwest and Southeast are outpacing new construction cycles as aging thermal infrastructure triggers mandatory efficiency upgrades under tightening federal mandates.
Growth Catalysts
- OSHA 1910.147 thermal hazard standards:Mandated surface temperature limits below 140°F on accessible refinery equipment are expanding specification scope for protective insulation systems in chemical processing corridors.
- Petrochemical corridor concentration:Texas and Louisiana Gulf Coast operators are accelerating thermal barrier procurement as plant efficiency mandates tighten and continuous operations demand heat loss minimization.
- Fiberglass cost efficiency:Code familiarity and installed base advantages in power generation facilities sustain specification dominance despite premium material availability.
Market Restraints
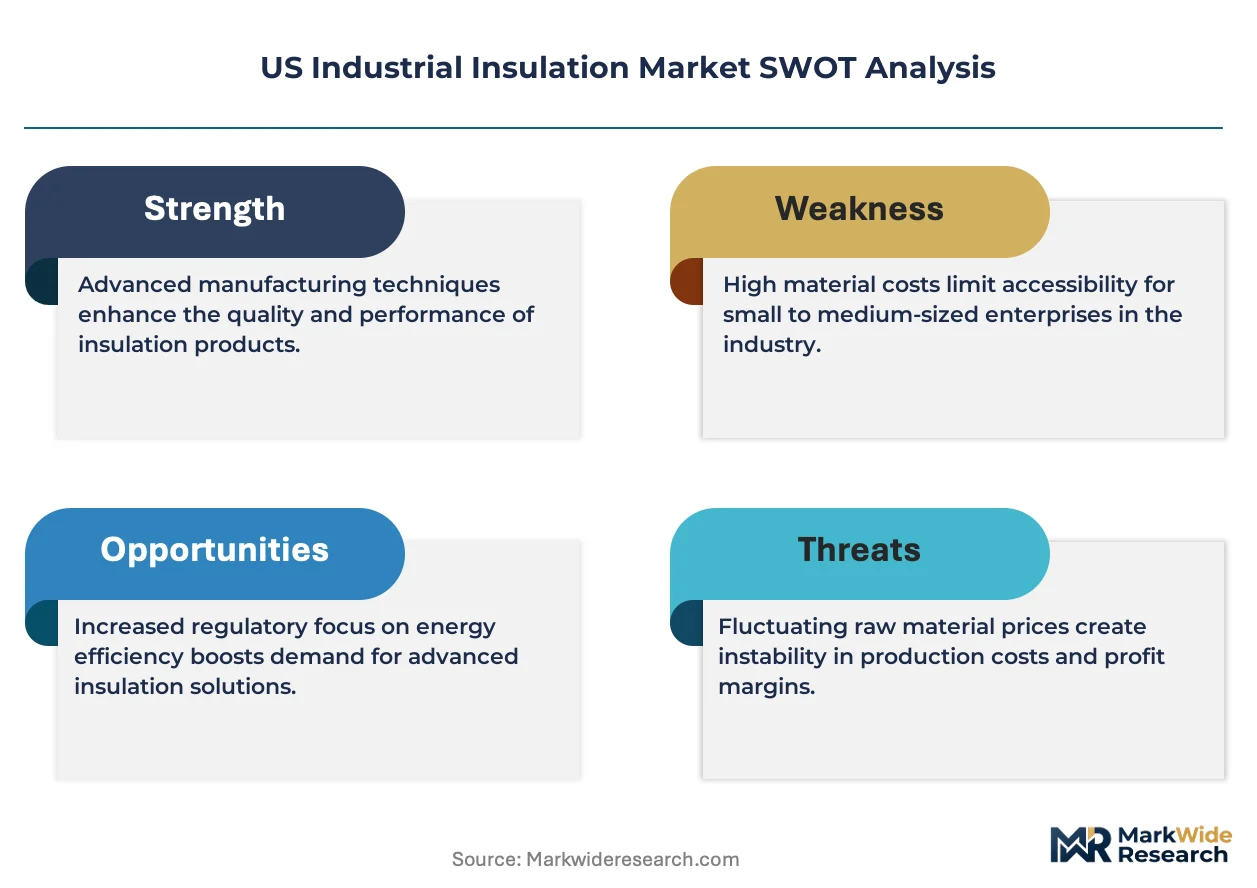
- Mineral wool feedstock volatility:Backward integration into slag and basalt supply chains concentrates pricing power among integrated manufacturers, squeezing specification margins for distributors.
- High-temperature technical ceiling:Conventional fiberglass batts rated to 1,000°F face displacement in process lines exceeding 2,200°F where ASTM E136 noncombustibility governs rock wool specification.
- EPA New Source Performance Standards friction:Fugitive emissions compliance timelines for valve and flange insulation systems compress installation windows and strain contractor availability.
Strategic Opportunities
- Georgia and Alabama manufacturing belts:Underpenetrated maintenance infrastructure in aging Southeast industrial parks offers retrofit volume expansion beyond saturated Gulf Coast markets.
- Aerogel-cryogenic convergence:Subsea pipeline and LNG terminal applications reward thermal performance premiums where lambda values below 0.020 W/m·K justify durable pricing power.
- Department of Energy efficiency rulemakings:Pending federal payback threshold recalibration for advanced materials against conventional systems will reshape specification economics in continuous process industries.
Industry Challenges
- Certified insulation mechanic scarcity:Specialized installation training for high-temperature rock wool and closed-cell foam systems lags demand growth in the Gulf Coast contractor pool.
- Legacy equipment integration complexity:Retrofit specification of advanced thermal barriers onto pre-1990 process vessels requires custom fabrication and extended outage scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Industrial Insulation Market |
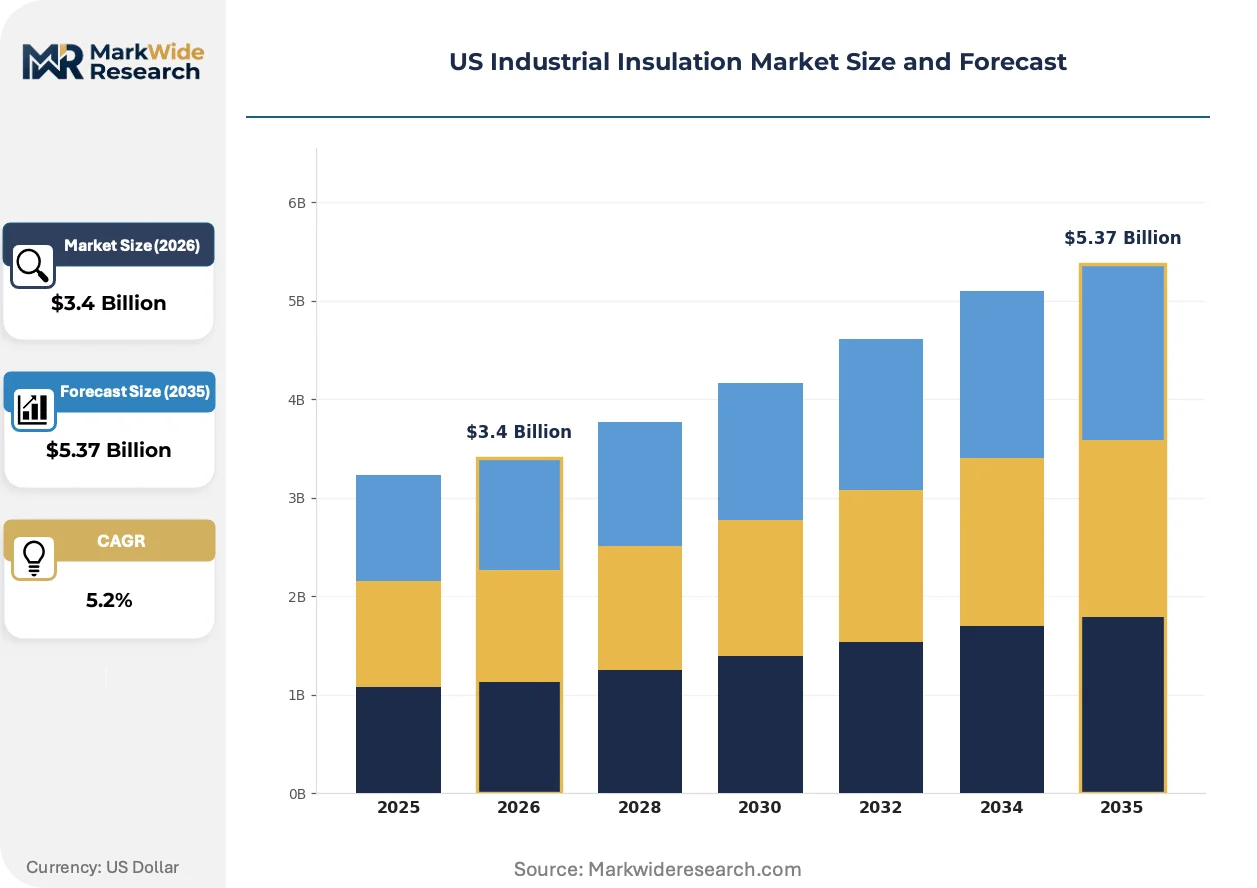
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.37 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Rock Wool, Foam, Cellular Glass Application: Piping, Ductwork, Tanks, Equipment End User: Oil & Gas, Power Generation, Manufacturing, Food Processing Installation Type: New Construction, Retrofit, Maintenance, Repair |
| Companies Covered | Johns Manville Corporation, Kingspan Group plc, Owens Corning, Cabot Corporation, Armacell International Holding GmbH, Rockwool International A/S, Saint-Gobain S.A., Aspen Aerogels, Inc., Knauf Insulation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Industrial Insulation Market Trends and Innovations
Material science advances and regulatory stringency are compressing specification cycles while fragmenting procurement authority across lifecycle contracting models and original equipment channels.
Silica aerogel blanket systems delivering thermal conductivity below 0.020 W/m·K are penetrating cryogenic storage and subsea pipeline specifications. LNG terminal operators in Texas and Louisiana are specifying aerogel for boil-off gas minimization. Conventional multi-layer insulation with higher lambda values is rendering obsolete in these premium thermal performance applications.
EPA enforcement of Clean Air Act fugitive emissions controls on valves, flanges, and pressure vessels is mandating intact insulation system documentation. Refinery operators must demonstrate continuous barrier integrity through inspection protocols. Chemical plants along the Houston Ship Channel are responding with predictive maintenance integration and thermal imaging audit cycles.
Lifecycle contracting is consolidating procurement authority under engineering-procurement-construction firms and specialized insulation contractors. Original equipment manufacturers face margin compression as aftermarket service revenue fragments across third-party maintenance agreements. Buyer concentration among integrated petrochemical operators in the Gulf Coast corridor accelerates this channel shift.
US Industrial Insulation Market Segmentation
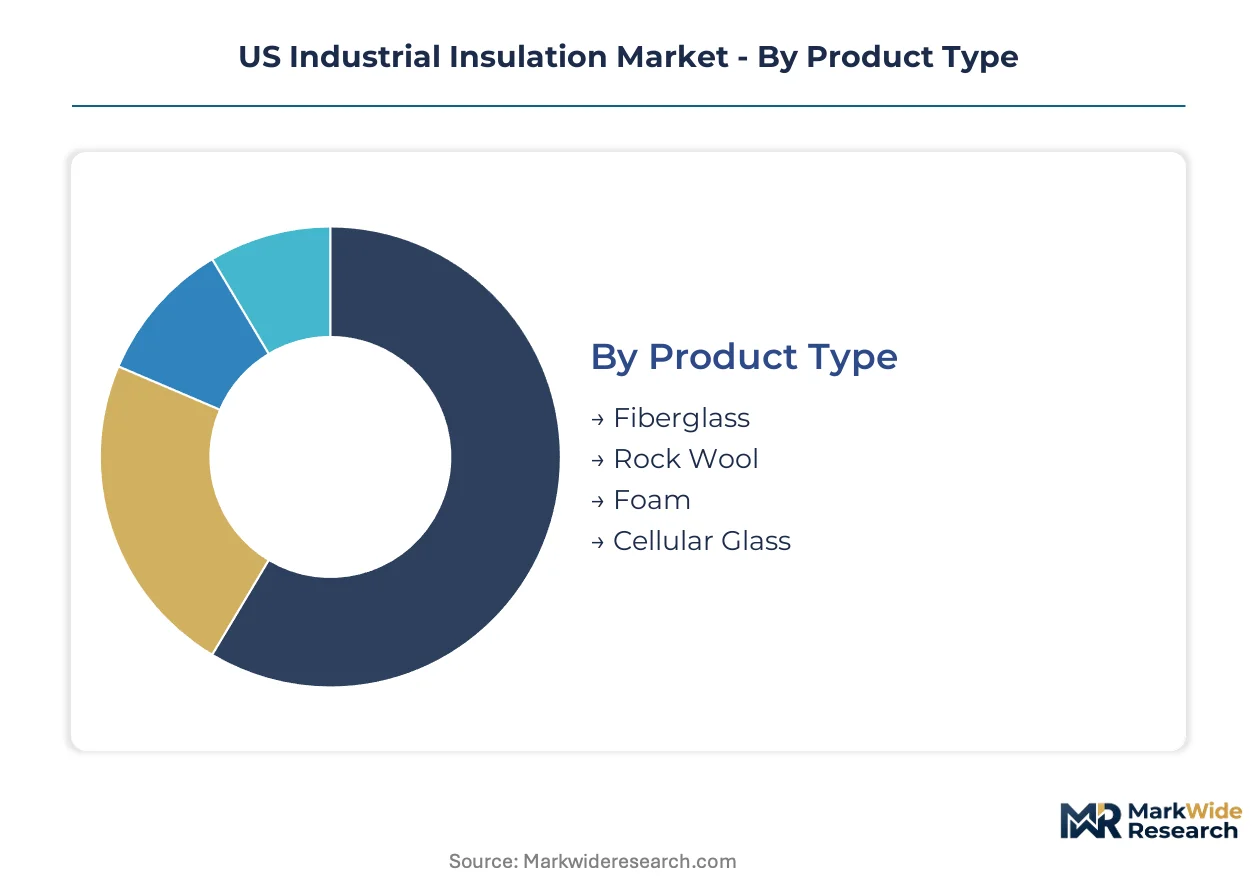
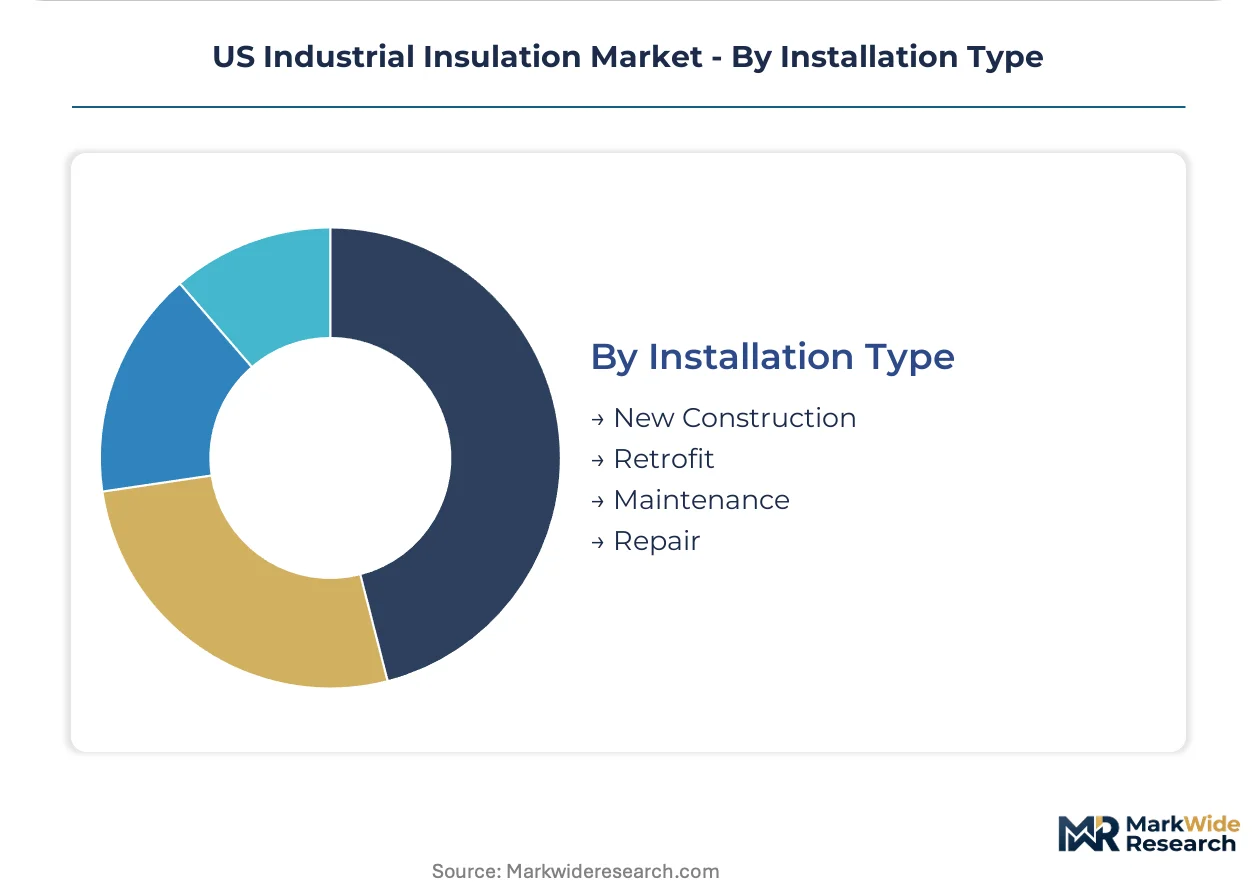
Industrial insulation procurement cycles vary dramatically by segment, with maintenance and repair turning over annually while new construction stretches across multi-year capital planning horizons. Understanding these velocity differentials enables suppliers to calibrate inventory and service models against predictable demand patterns.
Product Type:
Fiberglass and rock wool command the shortest replacement cycles due to thermal degradation and mechanical wear in continuous operations, while aerogel and cellular glass systems persist longer in cryogenic service.
- Fiberglass:Composed of fine glass fibers bonded with thermosetting resins, rated to 1,000°F with lambda values around 0.040 W/m·K. Demand concentrates in Texas and Louisiana power generation facilities where OSHA thermal hazard compliance mandates surface temperature controls on accessible equipment. The installed base advantage and code familiarity sustain specification dominance despite temperature limitations.
- Rock Wool:Manufactured from molten basalt or slag spun into fibers, achieving noncombustible ASTM E136 ratings and service temperatures exceeding 2,200°F. Gulf Coast petrochemical corridors specify rock wool for process lines and fire-rated assemblies where fiberglass fails, commanding premium positioning in high-temperature applications.
- Foam:Closed-cell polyurethane and polyisocyanurate systems delivering lambda values below 0.020 W/m·K for cryogenic and subsea specifications.
- Cellular Glass:Rigid foam glass boards with closed-cell structure providing moisture resistance and dimensional stability in tank base applications.
Fiberglass anchors the volume base while rock wool gains share at the steepest rate as process temperatures rise and fire safety codes tighten.
Application:
Cost tier differentiation separates commodity piping insulation from engineered tank systems, with specification complexity and material intensity driving margin stratification across application types.
- Piping:Straight-run and elbow insulation for process and utility lines, typically fiberglass or calcium silicate pre-formed sections. Manufacturing facilities across the Midwest specify piping systems for steam distribution efficiency, with EPA fugitive emissions rules mandating intact barrier documentation on valve and flange assemblies.
- Ductwork:HVAC and process air handling insulation, predominantly fiberglass board and flexible duct liner. Southeast commercial and industrial buildings drive specification for acoustic and thermal performance in climate control systems.
- Tanks:Large vessel insulation requiring custom-fitted panels or spray-applied systems for thermal storage and process containment.
- Equipment:Skid-mounted and standalone machinery insulation, often combining multiple materials for complex geometries and access requirements.
Piping systems dominate procurement volume while equipment applications command the highest specification premiums due to engineering complexity.
End User:
Customer type concentration shapes contracting models, with integrated oil and gas operators consolidating procurement authority under lifecycle agreements while fragmented manufacturing buyers sustain distributor channels.
- Oil & Gas:Upstream, midstream, and downstream operations spanning exploration through refining. Texas and Louisiana Gulf Coast operators are accelerating thermal barrier procurement as plant efficiency mandates tighten and continuous operations demand heat loss minimization.
- Power Generation:Fossil fuel, nuclear, and renewable electricity producers. Coal and gas-fired plants across the Midwest and Southeast specify insulation for boiler, turbine, and steam distribution efficiency under tightening federal efficiency standards.
- Manufacturing:Diverse industrial operations including steel, cement, and chemicals production.
- Food Processing:Temperature-controlled production and storage facilities requiring hygienic insulation systems.
Oil and gas anchors the revenue base while power generation expands most quickly under efficiency mandate pressure.
Installation Type:
Geography-driven demand patterns concentrate retrofit and maintenance activity in aging industrial corridors, while new construction tracks greenfield capital deployment in the Gulf Coast petrochemical expansion.
- New Construction:Greenfield plant and facility builds with specification-driven material selection and engineered installation sequences. Gulf Coast petrochemical expansions in Texas and Louisiana concentrate new construction demand as operators add capacity for export markets.
- Retrofit:Complete insulation system replacement on operating equipment during planned outages. Aging infrastructure across the Midwest and Southeast drives retrofit volumes beyond new construction cycles as pre-1990 facilities require mandatory efficiency upgrades.
- Maintenance:Scheduled inspection, repair, and replacement of degraded insulation sections.
- Repair:Unplanned remediation of damaged or failed thermal barriers.
Retrofit installation is climbing the fastest as infrastructure age and regulatory pressure compress replacement timelines, while maintenance sustains the recurring revenue foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across US sub-regions, with Gulf Coast petrochemical corridors prioritizing high-temperature rock wool for continuous process operations while Midwest manufacturing belts emphasize cost-efficient fiberglass retrofits on aging steam distribution infrastructure.
Texas Gulf Coast
Petrochemical expansion along the Houston Ship Channel and Port Arthur complex drives specification of ASTM E136-rated rock wool for process lines exceeding 2,200°F. EPA New Source Performance Standards enforcement mandates intact insulation documentation on valve and flange assemblies. LNG terminal operators in Freeport and Corpus Christi are specifying aerogel systems for boil-off gas minimization in cryogenic storage.
Louisiana Industrial Corridor
Refinery and chemical plant operators in Baton Rouge and Lake Charles face compressed installation windows under fugitive emissions compliance timelines. OSHA 1910.147 thermal hazard standards mandate surface temperatures below 140°F on accessible equipment, expanding protective insulation scope. The state's concentration of continuous process facilities sustains premium material procurement despite contractor availability constraints.
Midwest Manufacturing Belt
Aging power generation infrastructure across Illinois, Indiana, and Ohio triggers mandatory efficiency upgrades under tightening federal standards. Coal and gas-fired plants specify fiberglass batts for boiler and turbine insulation where code familiarity sustains specification dominance. The retrofit segment outpaces new construction as pre-1990 facilities require thermal barrier replacement cycles.
Southeast Growth Markets
Underpenetrated maintenance infrastructure in Georgia and Alabama industrial parks offers volume expansion beyond saturated Gulf Coast markets. Food processing and automotive manufacturing facilities drive demand for hygienic insulation systems and process air handling thermal barriers. State-level efficiency incentive programs are recalibrating payback thresholds for advanced materials against conventional systems.
California and Pacific Coast
Stringent state decarbonization mandates accelerate specification of high-performance thermal barriers in industrial process applications. Refinery operators in the San Francisco Bay Area and Los Angeles basin face dual pressure from CARB emissions rules and OSHA workplace safety standards. The state's emphasis on energy conservation in continuous operations supports premium material adoption despite higher upfront costs.
US Industrial Insulation Market Competitive Landscape
Capability concentration sits with specialized aerogel and high-temperature material innovators; scale advantage sits with integrated fiberglass and mineral wool manufacturers commanding feedstock and distribution infrastructure. The market structures around three tiers: multinational building materials conglomerates with captive mineral supply, mid-cap insulation specialists with regional fabrication networks, and technology-driven innovators focused on premium thermal performance segments. Dominant competitive moves include backward integration into slag and basalt feedstock to secure raw material pricing power, and strategic partnerships with engineering-procurement-construction firms to capture lifecycle contracting revenue.
Within the multinational tier, Owens Corning, Johns Manville Corporation, and Saint-Gobain S.A. occupy positions anchored by manufacturing scale and specification relationships with major petrochemical and power generation operators. Among technology-focused specialists, Aspen Aerogels, Inc. exemplifies the premium-performance archetype where thermal conductivity advantages command durable pricing in cryogenic and subsea applications. Rockwool International A/S and Kingspan Group plc represent European-originated competitors with established positions in fire-rated and high-temperature industrial specifications.
| Leading Market Players |
|---|
| Johns Manville Corporation |
| Kingspan Group plc |
| Owens Corning |
| Cabot Corporation |
| Armacell International Holding GmbH |
| Rockwool International A/S |
| Saint-Gobain S.A. |
| Aspen Aerogels, Inc. |
| Knauf Insulation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Gulf Coast fiberglass manufacturing is compressing spot-market premiums while sustaining project-based contract discipline among integrated operators. Utilization rates below nameplate capacity across Texas and Louisiana plants are forcing distributors toward extended payment terms, yet specification-driven procurement in petrochemical corridors preserves pricing power for ASTM E136-certified rock wool systems.
Pricing Analysis
Project-based contracting dominates the US industrial insulation market, with multi-year offtake agreements anchoring volume commitments from power generation operators and spot purchases filling maintenance gaps. Price differentiation rests on thermal performance certification and geographic delivery cost, with OSHA-compliant surface temperature systems commanding premiums over commodity fiberglass. Cost compression in standard-grade fiberglass is intensifying because Gulf Coast overcapacity strains distributor margins, while integrated petrochemical buyers exhibit lowest price sensitivity due to lifecycle contracting concentration.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for distributor-tier financing, with supply-chain finance facilities increasingly bridging working capital gaps for mid-cap contractors. Raw material supply draws from domestic slag processing in Indiana and Ohio, Canadian basalt fiber imports, and specialty silica feedstock for aerogel production. Single-source vulnerability concentrates in high-purity basalt supply for ASTM E136 rock wool, while distribution runs through engineering-procurement-construction firms consolidating procurement authority under lifecycle agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US industrial insulation market functions as a defensive-moat industry where regulatory entrenchment creates durable switching costs. EPA emissions documentation mandates and OSHA thermal hazard compliance embed incumbent specification relationships.
For Market Incumbents: Build certification moats around ASTM E136 noncombustibility and OSHA 1910.147 compliance documentation to lock out commodity fiberglass competitors. Backward integration into slag and basalt feedstock secures raw material pricing power against mineral wool volatility, while predictive maintenance service bundling captures fragmented aftermarket revenue from third-party contractors. For New Entrants and Emerging Players: Establish a beachhead in Georgia and Alabama manufacturing belts where maintenance infrastructure remains underpenetrated relative to saturated Gulf Coast markets. Aerogel-cryogenic applications in LNG terminals offer the most penetrable segment due to thermal performance premiums justifying durable pricing, with subsea pipeline specifications providing a technical differentiation angle against established fiberglass and rock wool channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across aerogel manufacturing as production scale economies mature, improving return thresholds for technology-focused specialists. Acquisition targets should emphasize firms with captive distribution networks and specification relationships in petrochemical corridors, with the signal to watch being Department of Energy efficiency rulemaking acceleration that would recalibrate payback thresholds for advanced materials.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slag Supply | Captive basalt feedstock secures ASTM E136 certification pipeline against mineral wool price volatility. |
| Predictive Maintenance Service Bundling | Thermal imaging audit cycles capture fragmented aftermarket revenue from third-party insulation contractors. |
| Aerogel Manufacturing Scale-Up | Production economies improve lambda-value positioning in LNG terminal boil-off gas minimization specifications. |
| Lifecycle Contracting Partnerships | EPC firm alliances consolidate procurement authority away from original equipment manufacturer channels. |
| Georgia-Alabama Distribution Expansion | Regional fabrication networks penetrate underdeveloped Southeast maintenance infrastructure beyond Gulf Coast saturation. |
Research Methodology
A standing panel of plant engineers, procurement directors at integrated petrochemical operators, insulation contractor operations managers, and EPC firm specification leads provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation through OSHA enforcement records, EPA New Source Performance Standards filings, Department of Energy efficiency rulemaking dockets, and American Chemistry Council petrochemical capacity reports. Bottom-up volume triangulation against top-down value estimates anchored the analytical framework.
Scenario-bracketing around regulatory enforcement intensity and feedstock price volatility shaped the projection methodology across the analysis window. Segmentation dimensions modeled include material type, application complexity, end-user industry concentration, and installation category velocity. CAGRs derived from elasticity-adjusted demand curves incorporating plant efficiency mandate compliance timelines and infrastructure age distributions. Industry-specific inputs encompassed thermal conductivity performance tiers and ASTM certification penetration rates.
Stress conditions across slag supply disruption, OSHA enforcement acceleration, and Gulf Coast hurricane frequency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory trajectory and capital expenditure cycles. Macroeconomic contraction, federal efficiency mandate delay, or breakthrough displacement of conventional thermal barriers would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Italy Industrial Insulation Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market
Insulation Materials
High-Performance Insulation Materials Market
Insulation Materials
North America Tank Insulation Market
Insulation Materials
Radiation Shielding Materials Market
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
Europe MDI-Based PU Technical Insulation Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Europe Phase Change Material Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
Silver Ion Antibacterial Insulation Cup Market
Insulation Materials
Mineral Wool Board Insulation Market