
 Global Chemical Mechanical Polishing Slurry Market | 2026-2036
Global Chemical Mechanical Polishing Slurry Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemical Mechanical Polishing Slurry Market Analysis
Advanced packaging and sub-7nm logic node manufacturing is expanding demand for ultra-high-purity ceria and silica slurries with tighter particle size distributions. DuPont de Nemours sustains technology leadership through its broad patent portfolio covering colloidal silica stabilization chemistries. Fujifilm Holdings Corporation leverages vertical integration from abrasive synthesis to final blending, securing supply security for Japanese semiconductor fabs. Entegris specializes in contamination-controlled packaging and point-of-use filtration systems that extend slurry shelf life in high-volume manufacturing environments.
Chemical mechanical polishing slurry comprises a colloidal suspension of nano-scale abrasive particles—typically silica, alumina, or ceria—dispersed within an engineered chemical matrix of oxidizers, surfactants, and pH buffers, designed to achieve atomic-level planarization of dielectric and metal films through simultaneous chemical etching and mechanical abrasion. Wafer polishing applications dominate value capture as logic and memory manufacturers pursue flatter surfaces for multi-layer stacking, while substrate polishing for silicon carbide power devices represents the fastest-growing application segment driven by electric vehicle inverter demand. Silica-based formulations occupy the largest product category due to mature supply chains and broad compatibility with oxide dielectrics, though ceria-based slurries command premium positioning in shallow trench isolation processes where selectivity ratios determine yield.
EPA hazardous waste rules and OSHA permissible exposure limits for respirable silica constrain U.S. manufacturing facility siting and worker protection protocols, while REACH registration requirements in Europe mandate comprehensive toxicological dossiers for novel abrasive chemistries before market authorization. China's MEE enforces wastewater discharge standards that affect slurry formulation plants serving domestic semiconductor clusters. Stakeholders must monitor regulatory divergence between jurisdictions as chemical registration timelines and waste classification rules directly influence product development cycles and geographic manufacturing allocation decisions.
Market Dynamics
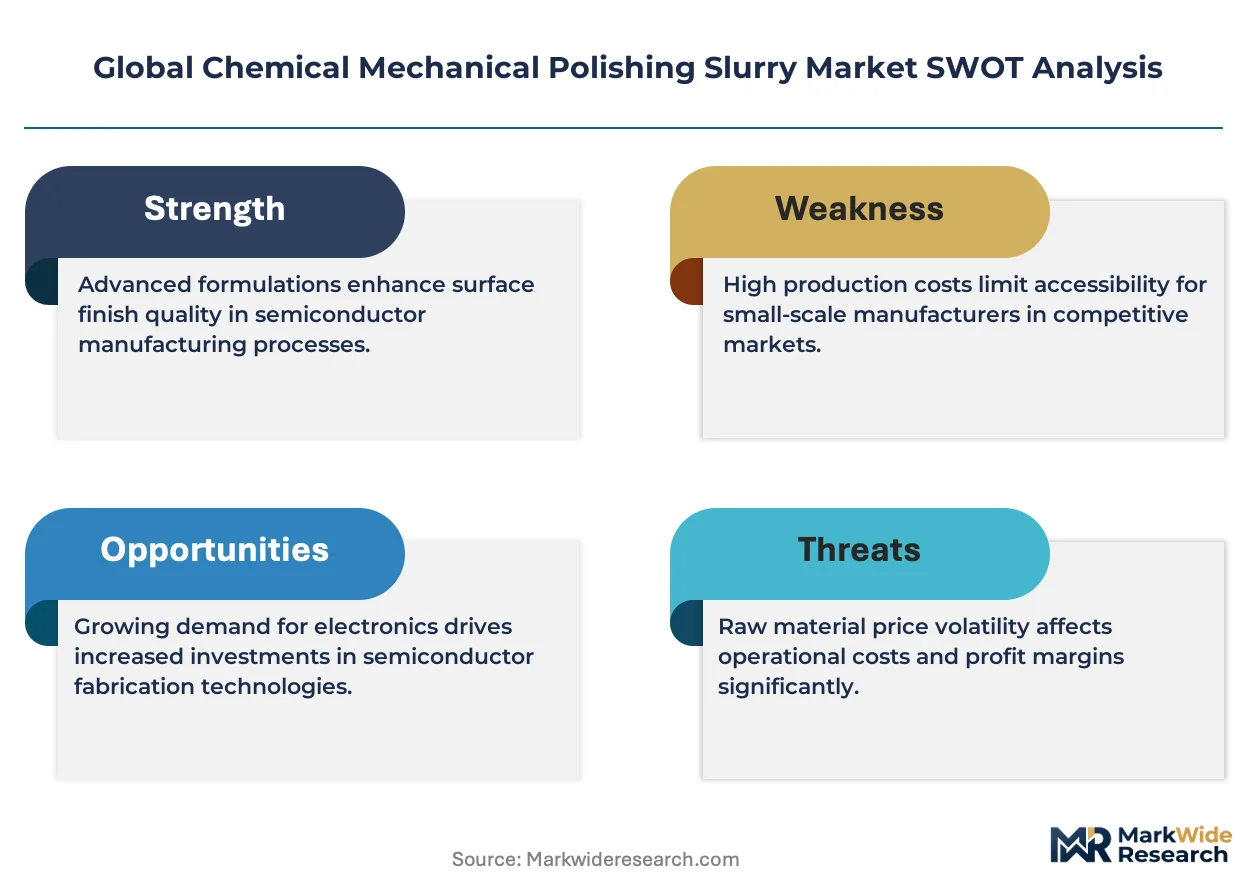
Sub-7nm logic node migration and silicon carbide substrate expansion are restructuring demand toward nano-abrasive formulations with atomic-level precision, compressing qualification cycles for slurry suppliers serving foundry and power semiconductor fabs.
Growth Catalysts
- Advanced Packaging Proliferation:Heterogeneous integration and chiplet architectures multiply polishing steps per wafer, expanding consumption of ultra-high-purity ceria slurries for through-silicon via planarization in Taiwan and South Korea.
- EU Green Deal Chemical Mandates:REACH registration requirements for novel abrasive chemistries accelerate substitution of legacy solvent-based formulations with aqueous, low-toxicity alternatives across European semiconductor clusters.
- Silicon Carbide Power Device Demand:Electric vehicle inverter manufacturing is pulling specialized alumina slurries for silicon carbide wafer substrate polishing, with Japanese and German automotive suppliers qualifying new abrasive specifications.
Market Restraints
- High-Purity Raw Material Concentration:Semiconductor-grade colloidal silica synthesis depends on captive supply from a limited set of Japanese and German chemical specialists, creating input bottleneck risk.
- EPA Respirable Silica Limits:OSHA permissible exposure standards constrain U.S. slurry blending facility expansion and necessitate costly ventilation and personal protective equipment protocols.
- Extended Qualification Timelines:Foundry customers require 12-18 month validation cycles for new slurry formulations, freezing out smaller suppliers lacking dedicated field application engineering resources.
Strategic Opportunities
- India Semiconductor Mission:Domestic fab construction under the PLI scheme creates first-mover advantage for slurry suppliers establishing local blending and technical service operations in Gujarat and Karnataka.
- Point-of-Use Filtration Integration:Slurry suppliers bundling contamination-controlled packaging with on-tool filtration systems can capture value previously retained by separate consumables vendors.
- Copper Barrier CMP Formulations:Cobalt and ruthenium replacement metals in advanced interconnects require entirely new chemical matrices, opening formulation patent space outside incumbent silica-ceria dominance.
Industry Challenges
- Specialized Formulation Chemistry Talent:The intersection of colloid science, semiconductor process engineering, and regulatory toxicology commands premium compensation, constraining R&D team scaling.
- Multi-Jurisdiction Registration Burden:Simultaneous EPA, REACH, and China MEE chemical dossier preparation stretches regulatory affairs capacity and delays regional product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemical Mechanical Polishing Slurry Market |
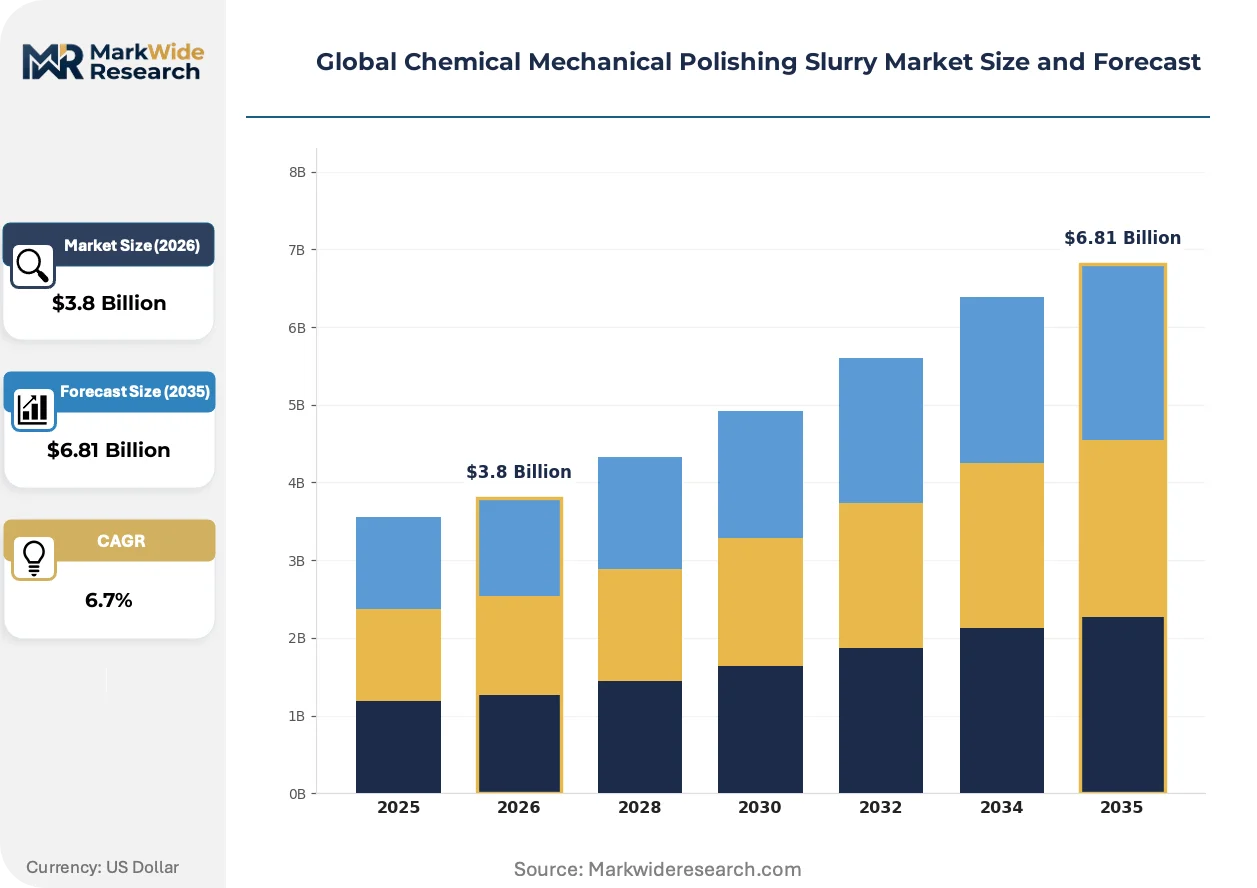
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica-Based, Alumina-Based, Ceria-Based, Others End User: Semiconductors, Photovoltaics, Glass Manufacturing, Optics Application: Wafer Polishing, Substrate Polishing, Optoelectronics, Coating Removal Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Ebara Corporation, BASF SE, Applied Materials Inc., Fujifilm Holdings Corporation, Cabot Corporation, Entegris Inc., Fujimi Incorporated, Resonac Holdings Corporation, DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemical Mechanical Polishing Slurry Market Emerging Trajectories
Formulation chemistry, regulatory compliance architecture, and procurement modalities are undergoing concurrent transformation as foundry customers consolidate supplier bases and tighten specification bands.
Ceria abrasive particles with engineered oxygen vacancy concentrations are overtaking conventional silica formulations for shallow trench isolation applications. Memory manufacturers at 3nm nodes and below are adopting these high-selectivity slurries to reduce dishing and improve within-die uniformity. The shift is compressing addressable volume for legacy fumed silica suppliers unable to pivot synthesis capabilities.
REACH authorization requirements for persistent organic pollutants and endocrine-disrupting chemistries are forcing reformulation of legacy surfactant packages in European-serving slurry plants. ECHA substance evaluation timelines now extend 24-36 months for novel organic additives, pushing suppliers toward inorganic stabilizer alternatives. German and Dutch semiconductor chemical clusters are accelerating pre-registration dossier preparation to avoid supply interruption.
Foundry customers are consolidating qualified slurry suppliers from six-to-eight per process node down to two-to-three strategic partners with captive technical service presence. Long-term supply agreements with fixed volume commitments and joint development clauses are displacing spot purchasing through distributors. This concentration is most pronounced in Taiwan, where TSMC and UMC captive polishing operations negotiate direct master service contracts bypassing traditional chemical distribution channels.
Global Chemical Mechanical Polishing Slurry Market Segmentation
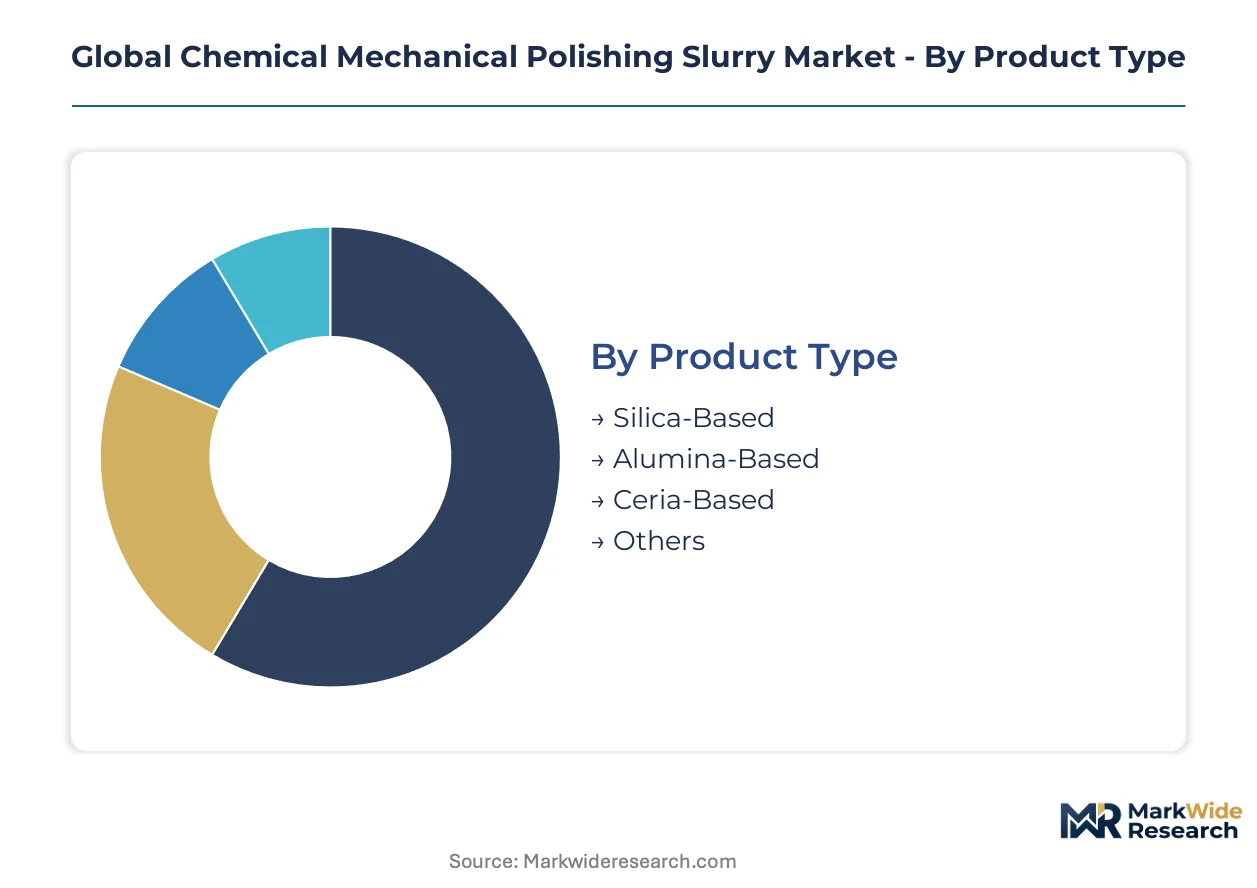
Chemical mechanical polishing slurry segmentation reveals how formulation chemistry, end-use process requirements, and procurement modalities create distinct commercial battlegrounds. Suppliers configure R&D priorities and supply chain investments differently across each dimension.
Product Type:
Buyers differentiate primarily by selectivity ratios required for their specific planarization steps and the defect sensitivity of their node geometry.
- Silica-Based:Colloidal silica suspensions dominate oxide dielectric polishing with established supply chains and broad compatibility across memory and logic fabs. Taiwan and South Korea foundries consume the largest volumes for interlayer dielectric planarization, though margin compression intensifies as specifications tighten below 5nm nodes.
- Ceria-Based:Engineered cerium oxide particles with controlled oxygen vacancy concentrations deliver superior selectivity for shallow trench isolation processes. Memory manufacturers at advanced nodes are accelerating adoption to reduce dishing and improve within-die uniformity, pulling demand toward Japanese and German abrasive synthesis specialists.
- Alumina-Based:Harder aluminum oxide abrasives serve silicon carbide substrate preparation and tungsten plug polishing where mechanical removal rates dominate.
- Others:Zirconia and mixed-oxide formulations address niche applications in sapphire substrate and compound semiconductor polishing.
Silica-based formulations lead volumes today; ceria-based slurries are gaining share fastest.
End User:
Process node migration and substrate material transitions are restructuring which end-use segments command supplier attention and technical service resources.
- Semiconductors:Logic and memory fabs account for the dominant value pool, with sub-7nm node qualification cycles and copper barrier CMP transitions driving formulation innovation. Taiwan's concentrated foundry capacity and captive polishing operations create the most demanding procurement environment.
- Photovoltaics:Silicon wafer saw damage removal and texturing applications consume commodity-grade slurries with limited purity requirements. Chinese cell manufacturers drive volume through high-throughput, cost-optimized specifications.
- Glass Manufacturing:Precision optics and display substrate polishing require controlled particle size distributions without semiconductor-grade contamination protocols.
- Optics:Lens and prism finishing applications demand specialized formulations for fused silica and exotic glass compositions.
Semiconductor end-users capture the highest margins; photovoltaics deliver the steepest volume expansion trajectory.
Application:
Surface finish specifications and removal rate requirements vary dramatically between front-end wafer processing and back-end substrate preparation.
- Wafer Polishing:Multi-layer stacking requirements in advanced packaging multiply polishing steps per wafer, expanding consumption of ultra-high-purity formulations. Heterogeneous integration and chiplet architectures are accelerating step-count growth in Taiwan and South Korea.
- Substrate Polishing:Silicon carbide wafer preparation for electric vehicle inverters is climbing fastest, with Japanese and German automotive suppliers qualifying new alumina abrasive specifications for power device manufacturing.
- Optoelectronics:LED and laser diode substrate polishing requires tight thickness uniformity control without the defect density standards of logic semiconductors.
- Coating Removal:Rework and reclamation processes consume lower-grade slurries with emphasis on throughput over surface quality.
Wafer polishing commands revenue concentration; substrate polishing is expanding most quickly.
Distribution Channel:
Foundry consolidation and captive technical service requirements are compressing the viable channel structure for premium formulations.
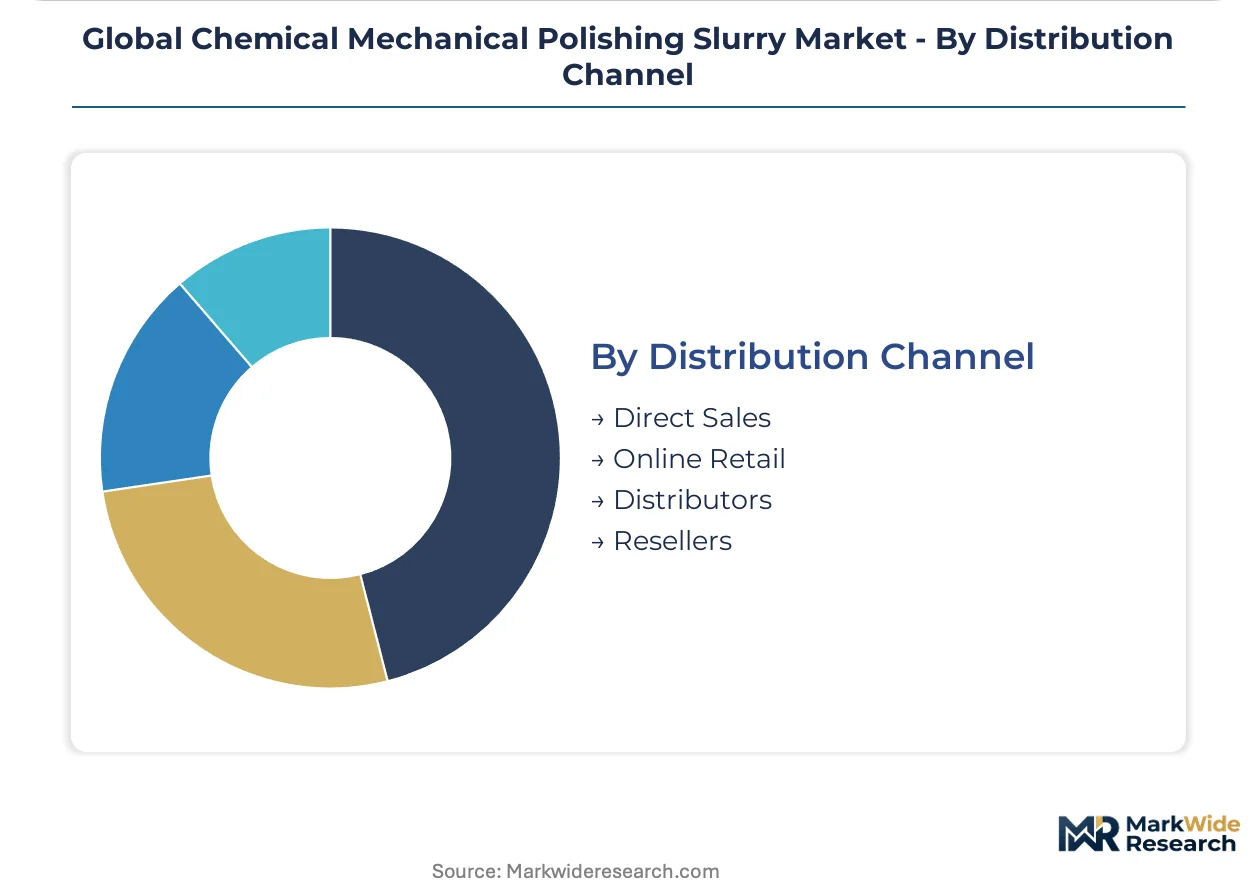
- Direct Sales:Strategic partnerships with volume commitments and joint development clauses now dominate at leading foundries. TSMC and UMC captive polishing operations negotiate master service contracts that bypass traditional chemical distribution entirely.
- Distributors:Regional chemical distributors retain relevance for smaller fabs and secondary applications where technical service intensity is lower.
- Online Retail:E-procurement platforms serve research institutions and prototype shops with standardized, low-volume formulations.
- Resellers:Independent resellers concentrate on geographic markets lacking direct supplier presence and legacy product lines approaching end-of-life.
Direct sales channels capture the premium tier; distributor relationships are concentrating among mid-volume customers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping slurry manufacturing geography as REACH compliance costs in Europe and EPA respirable silica enforcement in the United States push formulation capacity toward jurisdictions with streamlined chemical registration timelines. Suppliers are reallocating blending operations to exploit these cost-of-compliance gaps while maintaining proximity to concentrated foundry demand.
Taiwan
TSMC and UMC captive polishing operations consume the world's highest per-fab slurry volumes for sub-7nm logic manufacturing. The island's Environmental Protection Administration enforces wastewater discharge standards that favor aqueous formulation chemistries over solvent-based alternatives. Hsinchu Science Park anchors the densest cluster of qualified slurry technical service teams, with suppliers maintaining 24-hour on-site engineering presence.
South Korea
Samsung Electronics and SK Hynix memory fabs are accelerating ceria slurry adoption for 3nm node shallow trench isolation processes. The Ministry of Environment's chemical substance control act mandates pre-manufacture notification for novel abrasive additives, extending registration timelines for foreign suppliers. Pyeongtaek and Yongin semiconductor clusters concentrate demand for ultra-high-purity formulations with joint development clauses in direct supply contracts.
United States
Intel and GlobalFoundries are expanding domestic logic capacity under CHIPS Act incentives, pulling specialized copper barrier CMP formulations. OSHA permissible exposure limits for respirable silica constrain blending facility siting in Arizona and New Mexico, necessitating costly ventilation infrastructure. Greater Phoenix and Albany nanotech corridors are emerging as qualification hubs for next-generation cobalt and ruthenium replacement metal slurries.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor the deepest vertical integration from colloidal silica synthesis to final blending. METI's chemicals management policy prioritizes supply security for semiconductor materials, streamlining domestic registration for critical abrasive precursors. Kyushu and Tohoku regions concentrate captive abrasive particle production serving both domestic fabs and export markets.
Germany
Bosch and Infineon power semiconductor fabs are qualifying alumina slurries for silicon carbide substrate polishing amid electric vehicle inverter demand. ECHA REACH authorization requirements for persistent organic pollutants are forcing surfactant package reformulations at Leverkusen and Ludwigshafen chemical clusters. Bavaria and Saxony semiconductor corridors are consolidating qualified supplier bases from six-to-eight down to two-to-three strategic partners per process node.
Global Chemical Mechanical Polishing Slurry Market Vendor Landscape
Strategic partnerships with joint development clauses dominate the current landscape as foundry customers consolidate supplier bases and demand captive technical service presence. The vendor structure concentrates around three-to-five integrated specialists with backward integration into abrasive particle synthesis, alongside a fragmented tier of regional blenders serving secondary applications. Two archetypes define positioning: patent-rich formulation houses leveraging colloid chemistry expertise, and contamination-control specialists bundling filtration and packaging systems. M&A activity and capacity expansion in Taiwan and South Korea represent the dominant competitive moves as suppliers race to secure foundry qualification slots.
Among Japanese specialists, Ebara Corporation and Fujimi Incorporated exemplify the integrated abrasive-to-blending archetype, with geographic naming signaling Kyushu-region concentration in particle synthesis. DuPont de Nemours Inc. and Entegris Inc. represent the U.S.-based formulation and contamination-control tier respectively, with corporate suffixes indicating Delaware incorporation and Massachusetts operational roots. These three anchors occupy positions spanning the value chain from raw material synthesis through point-of-use delivery systems, with each exemplifying distinct strategic postures toward foundry customer consolidation.
| Leading Market Players |
|---|
| Ebara Corporation |
| BASF SE |
| Applied Materials Inc. |
| Fujifilm Holdings Corporation |
| Cabot Corporation |
| Entegris Inc. |
| Fujimi Incorporated |
| Resonac Holdings Corporation |
| DuPont de Nemours Inc. |
| Others |
Supply Flow & Price Mechanics
Premium-ceria and commodity-silica formulation divergence creates parallel supply chain configurations, with ultra-high-purity slurries commanding direct foundry contracts in Taiwan while standard oxide formulations flow through regional chemical distributors facing REACH registration cost absorption.
Pricing Analysis
Distributor margin layers compress as foundry consolidation accelerates direct procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with sub-7nm node formulations carrying the widest spreads. Cost compression in commodity silica tiers intensifies because Chinese photovoltaic manufacturers prioritize throughput over purity. Photovoltaic end-users exhibit highest price sensitivity; captive polishing operations at TSMC and Samsung demonstrate least.
Supply Chain Analysis
Dual-sourcing requirements from Intel, TSMC, and Samsung force suppliers to maintain redundant abrasive particle synthesis capabilities across Japan and Germany. Semiconductor-grade colloidal silica draws from Shin-Etsu Chemical and Evonik operations, while ceria precursors hinge on rare earth processing in China and Malaysia. Single-source vulnerability concentrates in high-purity cerium oxide feedstock. Distribution runs through direct master service agreements for premium tiers, with regional distributors serving mid-volume fabs in India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in ceria formulation premiums and point-of-use filtration bundling, as electric vehicle inverter demand pulls specialized alumina slurries into higher-value substrate polishing applications.
For Market Incumbents: Deploy captive technical service presence as the primary lever. DuPont and Entegris should expand Hsinchu Science Park engineering teams to defend against Fujifilm's backward integration into abrasive synthesis. Foundry consolidation from six-to-eight suppliers down to two-to-three partners per node threatens regional blenders lacking dedicated field application resources. Certification investment in China MEE pre-manufacture notification timelines secures qualification slots at Yangtze Memory and CXMT. For New Entrants and Emerging Players: Mid-tier memory fabs in India and Vietnam represent the most penetrable buyer archetype. Domestic fab construction under India's PLI scheme creates first-mover advantage for suppliers establishing local blending in Gujarat and Karnataka. Photovoltaic cell manufacturers in Southeast Asia tolerate lower purity specifications, enabling economy-tier entry without semiconductor-grade capital intensity. Go-to-market through equipment OEM partnerships—Applied Materials and Tokyo Electron qualification programs—bypasses direct foundry validation cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemistry talent scarcity intersects with multi-jurisdiction registration burdens. Long-term viability favors patent-rich specialists with captive abrasive synthesis or contamination-control bundling capabilities. Acquisition targets include regional Japanese blenders with METI-streamlined domestic registration and European surfactant reformulation expertise. Watch ECHA substance evaluation timelines for novel organic additives as inflection indicator—24-36 month delays signal incumbent advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Abrasive Synthesis | Fujifilm's colloidal silica production secures supply security for Japanese semiconductor fabs against German specialist concentration. |
| Point-of-Use Filtration Bundling | Entegris extends slurry shelf life through contamination-controlled packaging capturing value from separate consumables vendors. |
| Ceria Formulation Patent Expansion | DuPont leverages colloidal silica stabilization chemistry expertise into shallow trench isolation selectivity ratios. |
| India Local Blending Capacity | First-mover suppliers establish Gujarat technical service operations under PLI scheme domestic fab construction. |
| Copper Barrier CMP Development | Cobalt and ruthenium replacement metals open formulation patent space outside incumbent silica-ceria dominance. |
Methodological Framework
Multiple input streams—primary interviews with slurry formulation chemists, foundry procurement directors, and point-of-use filtration engineers; secondary validation through SEMI materials market data, EPA hazardous waste rule filings, and ECHA REACH registration dossiers—were reconciled through bottom-up volume modeling and top-down value triangulation. Stakeholder conversations spanned Taiwan's Hsinchu Science Park, South Korea's Pyeongtaek cluster, and Japan's Kyushu abrasive synthesis corridor.
Cross-referencing historical consumption patterns against expert panel inputs anchored the analytical framework across the analysis window. Segmentation dimensions modeled include abrasive chemistry type, end-use process node, substrate material, and distribution channel structure. CAGRs were derived from wafer start projections and step-count multiplication factors in advanced packaging architectures. Industry-specific forecast inputs incorporated electric vehicle inverter production ramps and silicon carbide substrate polishing qualification timelines.
Underlying measurement precision varies by segment; semiconductor-grade ceria formulations carry tighter precision than commodity photovoltaics applications due to concentrated foundry disclosure and captive consumption tracking. Forecasts reflect assumptions around node migration schedules, regulatory authorization timelines, and raw material supply continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Carbide Grinding Wheel Market
Abrasives
Chemical Mechanical Polishing Market
Abrasives
Middle East and Africa Abrasives Market
Abrasives
Tungsten Carbide Market
Abrasives
Abrasive Tools Market
Abrasives
Global Ceramic Flap Disc Market
Abrasives
North America Abrasives Market
Abrasives
Tungsten Carbide Powder Market
Abrasives
Fine Sandpaper Market
Abrasives
Superabrasive Electroplated Grinding Wheel Market
Abrasives
Tile Abrasion Testing Market
Abrasives
Tungsten Carbide Balls Market
Abrasives
Abrasive Base Paper Market
Abrasives
Glass Abrasives Market
Abrasives
Abrasive Rolls Market
Abrasives
Artificial Abrasives Market