
 Hot Insulation Materials Market | 2026-2036
Hot Insulation Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Insulation Materials Market Analytics
Specialized ceramic fiber technicians and industrial insulation engineers is reorganizing supply chains across the hot insulation materials sector as project complexity outpaces training pipelines. Morgan Advanced Materials leverages its fused silica and alumina-silicate expertise to anchor premium positions in aerospace and power generation. Promat competes through dense calcium silicate board production and fire-protection engineering services. Unifrax sustains broad geographic coverage with its spun and blown ceramic fiber manufacturing platforms.
Hot insulation materials encompass engineered thermal barriers—typically ceramic fibers, mineral wool, calcium silicate, or cellular glass—designed to withstand continuous operating temperatures from 300°C to over 1,400°C while minimizing heat loss and protecting substrate equipment. These materials function through low thermal conductivity matrices, often reinforced with inorganic binders or compressed into rigid monolithic forms, to maintain process efficiency and personnel safety in high-temperature industrial environments. Mineral wool occupies mature, high-volume positions across industrial insulation applications where cost sensitivity dominates procurement. Calcium silicate leads in pipe insulation and energy-sector deployments where compressive strength and hydrophobic performance command specification priority. Fiberglass segments specialize in HVAC systems and lower-temperature manufacturing envelopes where installation speed and flexibility drive contractor preference.
EPA emissions enforcement under the Clean Air Act shapes material selection in US refineries and petrochemical facilities, pushing operators toward thicker, higher-performance insulation to reduce fuel combustion intensity. OSHA heat-exposure standards and the EU F-Gas Regulation constrain permissible thermal losses and refrigerant-adjacent insulation practices, tightening compliance thresholds for cross-border equipment suppliers. Stakeholders must monitor how building-code harmonization between national fire-rating systems and industrial process-safety frameworks reshapes specification authority among engineering-procurement-construction contractors and end-user technical teams.
Market Dynamics
Power generation utilities are consolidating procurement specifications around high-temperature ceramic fiber systems, compressing vendor qualification timelines and elevating technical compliance burdens for insulation contractors serving boiler and turbine retrofits.
Growth Catalysts
- EU ETS carbon pricing:Steelworks and chemical processing clusters in Germany face escalating compliance costs, forcing rapid upgrades to calcium silicate and mineral wool insulation systems that cut fuel combustion intensity.
- Aerospace thermal management:Next-generation jet engine programs specify alumina-silicate ceramic fiber matrices for turbine shrouds and combustor liners, pulling material innovation toward higher temperature tolerances.
- Industrial clustering:The concentration of petrochemical infrastructure along the US Gulf Coast creates concentrated demand spikes for cellular glass and calcium silicate pipe insulation during turnaround seasons.
Market Restraints
- Refractory-grade alumina supply:Mining concentration in Guinea and Australia exposes ceramic fiber producers to bauxite price volatility and shipping disruption cascades.
- Technical service life limits:Organic binders in mineral wool degrade above 650°C, constraining deployment in emerging ultra-supercritical steam systems without costly inorganic reformulation.
- REACH substance restrictions:ECHA scrutiny of refractory ceramic fiber carcinogenicity classifications forces costly toxicology dossier preparation and potential reformulation across EU-manufactured product lines.
Strategic Opportunities
- India's PLI scheme for manufacturing:Domestic production incentives for capital goods create localized insulation demand as steel and cement capacity expands under government-backed investment programs.
- Green hydrogen electrolyzer integration:High-temperature solid oxide electrolysis cells require novel insulation architectures combining ceramic fiber with vacuum-formed microporous layers, opening specification white space.
- Performance-based contracting:Energy service companies are bundling insulation installation with guaranteed heat-loss reductions, shifting risk allocation and creating recurring revenue attachments.
Industry Challenges
- Ceramic fiber installation certification:Specialized technicians capable of dense-pack blowing and module anchoring in confined turbine spaces remain scarce relative to project pipeline growth.
- Legacy equipment compatibility:Retrofitting 1970s-era boilers with modern microporous insulation requires structural load recalculation and support steel modification, extending engineering timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Insulation Materials Market |
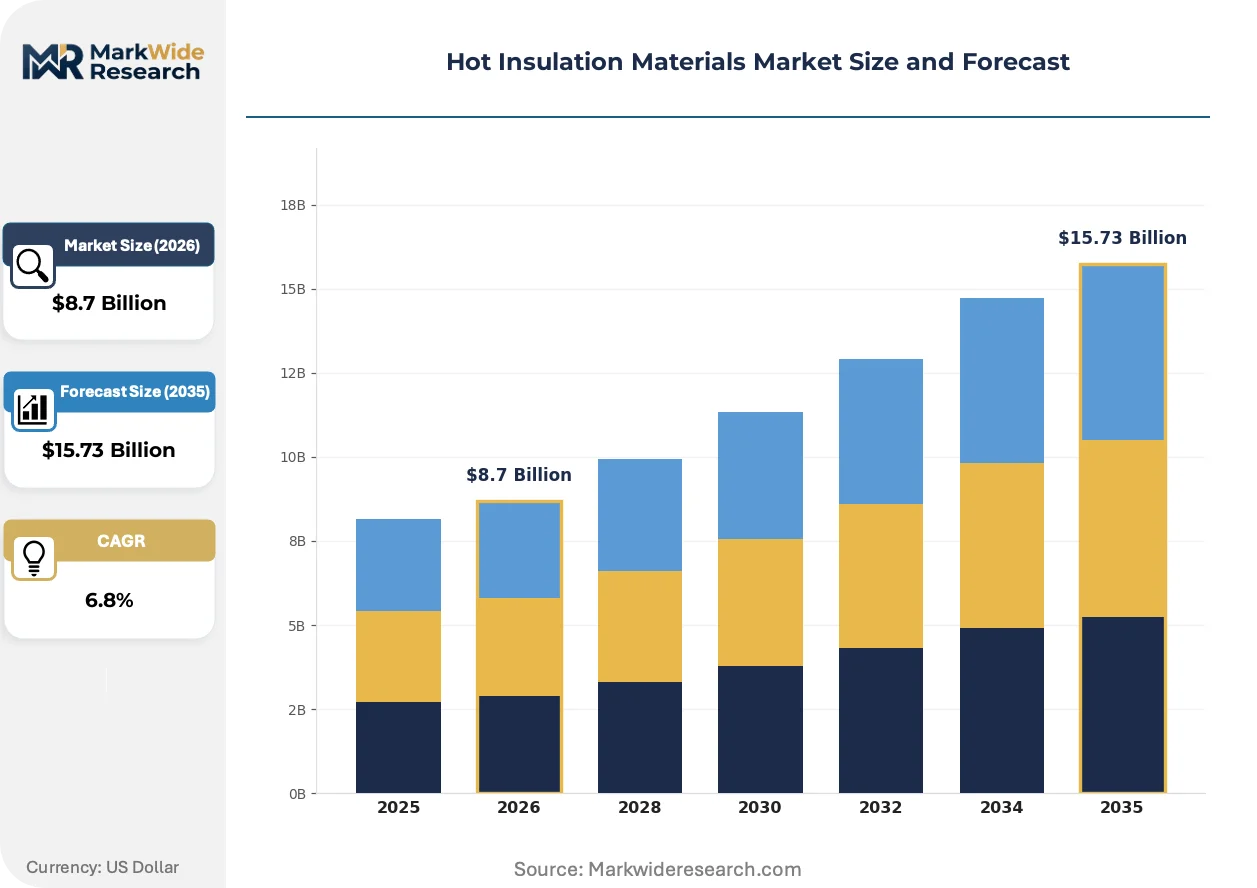
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fiberglass, Foam, Mineral Wool, Calcium Silicate Application: Industrial Insulation, Residential Insulation, HVAC Systems, Pipe Insulation Installation Method: Sprayed, Rigid Board, Blanket, Flexible End User: Construction, Oil & Gas, Energy, Manufacturing |
| Companies Covered | Morgan Advanced Materials, Promat, Unifrax, Alkegen, Luyang Energy-saving Materials Co., Ltd., Thermal Ceramics, Pyrotek, Isolite Insulating Products Co., Ltd., Skamol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Insulation Materials Market Evolving Landscape
Material science advances and regulatory tightening are converging to compress product lifecycles and elevate performance thresholds across high-temperature insulation applications. Specification authority is migrating from general contractors toward end-user engineering teams with direct emissions accountability.
Sol-gel derived microporous insulation is displacing conventional calcium silicate in ethylene cracker furnace linings. Petrochemical operators in the US Gulf Coast and Rotterdam-Antwerp corridor are specifying these materials for their 40% thermal conductivity reduction at 800°C. The technology is displacing established rigid board suppliers from premium turnaround contracts where downtime costs exceed material differentials.
The EU F-Gas Regulation phase-down schedule is accelerating inspection protocol harmonization across member states. Industrial refrigeration and heat pump adjacent insulation must now demonstrate zero ozone depletion and minimal global warming potential in blowing agents. German chemical processors are responding by qualifying cellular glass systems with CO2-based foam expansion, shifting procurement away from legacy phenolic-foam suppliers.
Engineering-procurement-construction contractors are unbundling insulation specification from general construction packages. Major refinery operators in Singapore and South Korea now retain independent thermal engineering consultants to validate contractor material selections against internal heat-loss benchmarks. This behavior concentrates buying power among technical specialists and compresses margins for distributors lacking in-house application engineering capabilities.
Hot Insulation Materials Market Segmentation
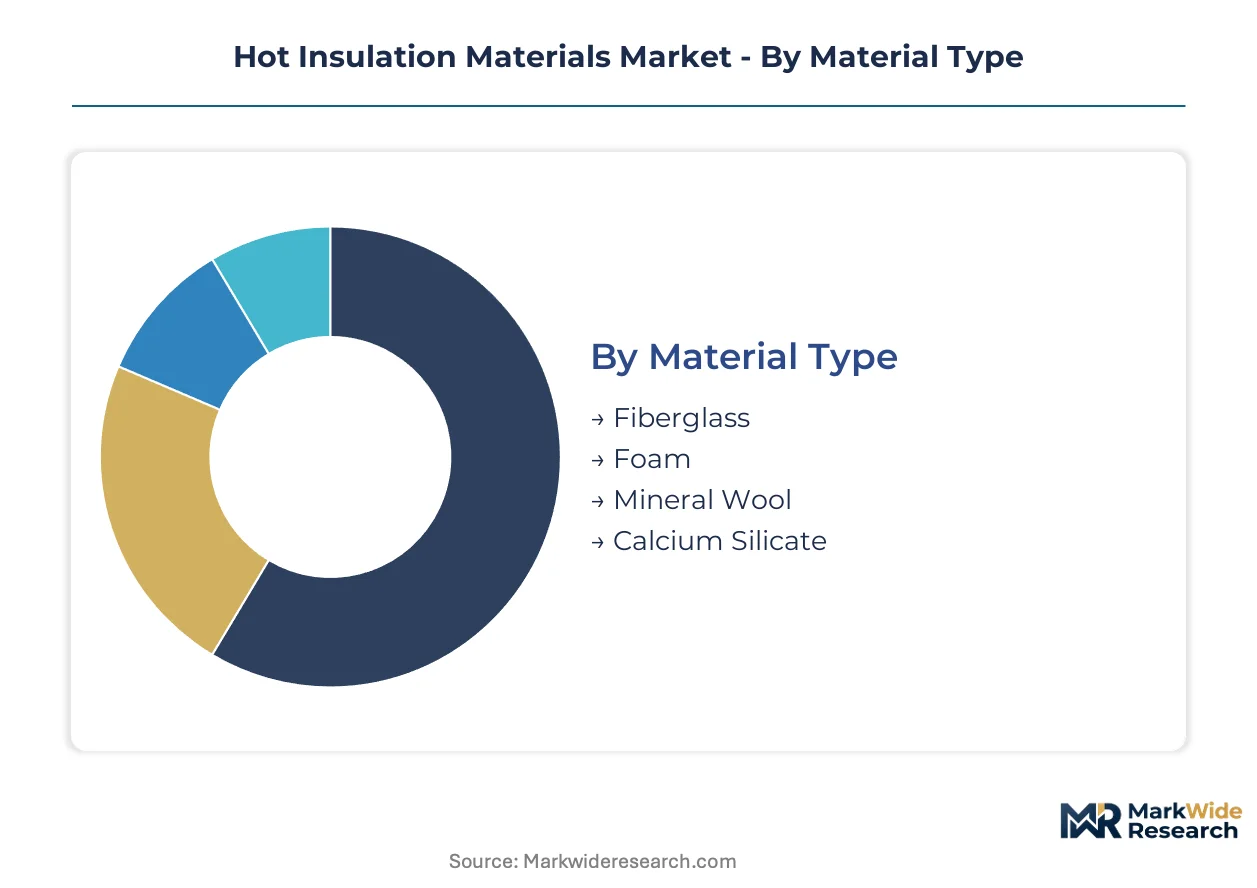
Hot insulation materials traverse distinct commercial channels depending on material chemistry and thermal performance tier. Specification authority migrates from general contractors toward end-user engineering teams with direct emissions accountability, reshaping how segments flow through distribution.
Material Type:
Channel mix varies sharply by thermal tolerance—high-temperature grades move through specialized refractory distributors while commodity grades flow through construction supply houses.
- Mineral Wool:Spun or blown inorganic fibers bound with phenolic or bio-based resins, delivering continuous service to 750°C. German steelworks and chemical processing clusters specify dense mineral wool for boiler lagging under tightening EU ETS carbon pricing. REACH substance restrictions on refractory ceramic fiber carcinogenicity classifications push some specifications toward mineral wool alternatives.
- Calcium Silicate:Hydrous calcium silicate crystal structure with xonotlite or tobermorite mineralogy, formed into rigid boards or pre-formed pipe covers. US Gulf Coast petrochemical turnarounds and power generation utilities prioritize calcium silicate for compressive strength and hydrophobic performance in steam pipe insulation. ECHA scrutiny of alternative materials reinforces specification stickiness in European energy-sector deployments.
- Fiberglass:Continuous or discontinuous glass fibers with organic binder systems, typically service-limited to 540°C. HVAC contractors and lower-temperature manufacturing envelopes favor fiberglass for installation speed and flexibility.
- Foam:Cellular polymer or glass structures including phenolic, polyisocyanurate, and cellular glass variants. Industrial refrigeration adjacent to heat pump systems drives qualification of CO2-blown cellular glass under EU F-Gas Regulation phase-down schedules.
By volume, mineral wool leads. By growth pace, calcium silicate is climbing the fastest.
Application:
Cost tier stratification separates premium engineered systems from commodity envelope insulation, with specification authority concentrated in high-downtime-cost environments.
- Industrial Insulation:High-temperature furnace linings, vessel insulation, and equipment lagging for continuous process industries. US EPA Clean Air Act enforcement pushes refineries toward thicker, higher-performance systems to reduce fuel combustion intensity.
- Pipe Insulation:Pre-formed or field-fabricated thermal barriers for steam, process, and cryogenic piping networks. Sol-gel derived microporous insulation is displacing conventional calcium silicate in ethylene cracker furnace linings across Rotterdam-Antwerp corridor facilities.
- HVAC Systems:Ductwork insulation, air handling equipment, and building envelope thermal barriers. Fiberglass dominates procurement where installation speed drives contractor preference.
- Residential Insulation:Lower-temperature applications in building construction, typically mineral wool or fiberglass batts. Building-code harmonization between national fire-rating systems and process-safety frameworks reshapes specification authority.
Industrial applications command premium pricing. Residential segments scale through volume.
Installation Method:
Customer type determines method selection—owner-operators with in-house maintenance crews favor rigid systems while contractors serving turnaround markets prefer flexible or spray-applied options.
- Rigid Board:Factory-formed calcium silicate, mineral wool, or cellular glass boards cut to specification on-site. Dense calcium silicate board production anchors premium positions in power generation and petrochemical maintenance contracts.
- Blanket:Flexible needled or woven ceramic fiber systems for turbine shrouds and irregular surfaces. Aerospace thermal management programs specify alumina-silicate ceramic fiber matrices for combustor liners.
- Sprayed:Wet or dry spray-applied systems for complex geometries and retrofit applications. Specialized ceramic fiber technicians capable of dense-pack blowing remain scarce relative to project pipeline growth.
- Flexible:Wraps, tapes, and removable covers for maintenance access points and expansion joints. Green hydrogen electrolyzer integration creates novel specification opportunities combining ceramic fiber with vacuum-formed microporous layers.
Rigid board dominates existing infrastructure. Sprayed methods are expanding most quickly in retrofit markets.
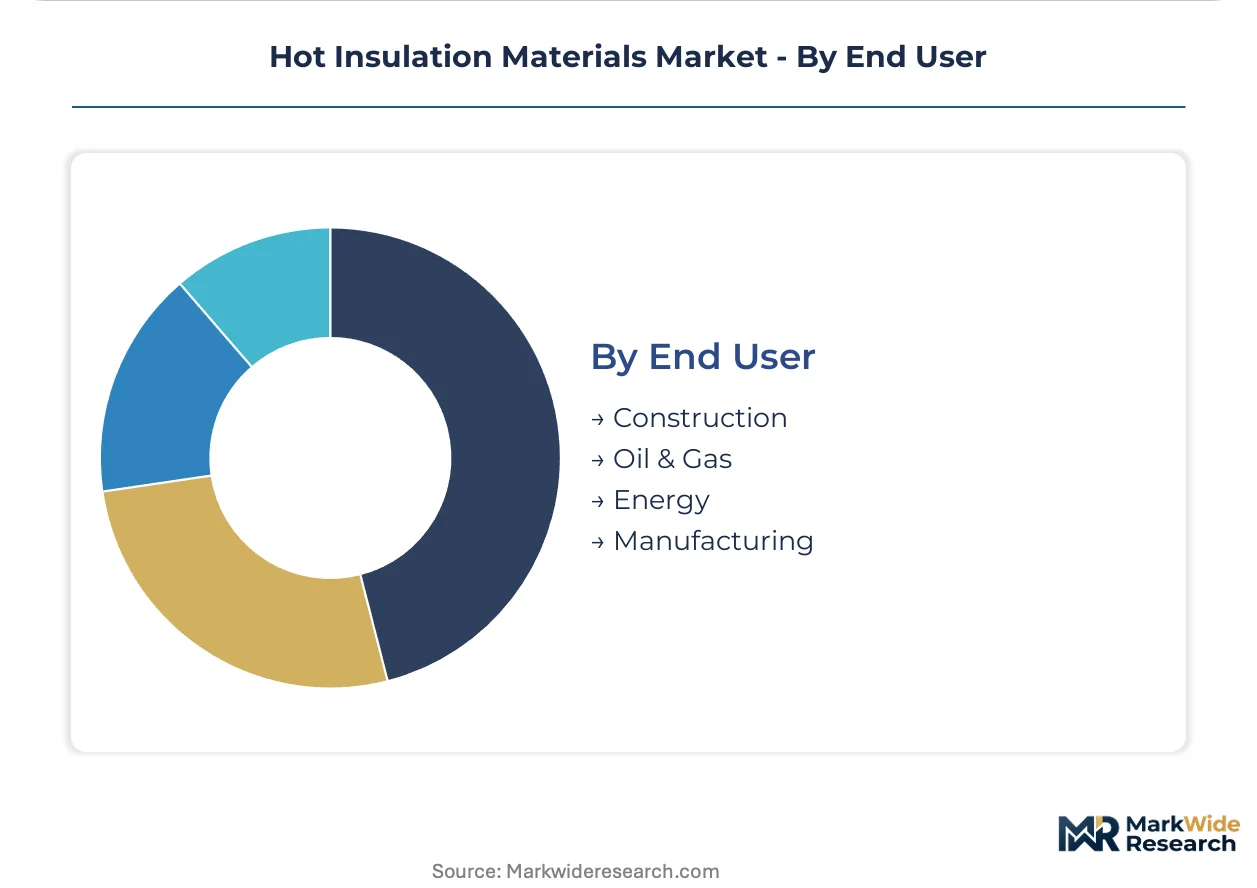
End User:
Supply concentration aligns with geographic clustering of heavy industry—energy and oil & gas procurement concentrates along the US Gulf Coast and German chemical processing corridors.
- Energy:Power generation utilities consolidating procurement around high-temperature ceramic fiber systems for boiler and turbine retrofits. India's PLI scheme for manufacturing creates localized insulation demand as domestic steel and cement capacity expands.
- Oil & Gas:Refinery and petrochemical facility operators facing EPA emissions enforcement under the Clean Air Act. OSHA heat-exposure standards constrain permissible thermal losses, tightening compliance thresholds.
- Manufacturing:Cement, steel, and glass production facilities with continuous high-temperature processes. Performance-based contracting from energy service companies bundles installation with guaranteed heat-loss reductions.
- Construction:Commercial and infrastructure building envelopes with lower thermal stress requirements. Building-code fire-rating harmonization reshapes specification authority among engineering-procurement-construction contractors.
Energy sector procurement leads by absolute volume. Manufacturing applications show steepest expansion trajectory under industrial decarbonization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: European buyers prioritize emissions-compliant calcium silicate systems, while US Gulf Coast operators favor cellular glass for petrochemical turnaround density, and Asian markets scale mineral wool for infrastructure buildouts.
United States
EPA emissions enforcement under the Clean Air Act drives refinery procurement of thicker, higher-performance insulation to reduce fuel combustion intensity. OSHA heat-exposure standards constrain permissible thermal losses across petrochemical facilities. Industrial clustering along the Texas and Louisiana Gulf Coast generates concentrated demand spikes for cellular glass and calcium silicate pipe insulation during seasonal turnaround windows.
Germany
Steelworks and chemical processing clusters face escalating compliance costs under EU ETS carbon pricing, forcing rapid upgrades to calcium silicate and mineral wool systems. ECHA scrutiny of refractory ceramic fiber carcinogenicity classifications pushes specifications toward mineral wool alternatives. The Rhine-Ruhr and Ludwigshafen chemical corridors anchor specification intensity for dense calcium silicate board in energy-sector deployments.
China
Domestic steel and cement capacity expansion under government-backed investment programs creates localized insulation demand at scale. MIIT industrial efficiency mandates tighten thermal performance requirements for high-temperature process equipment. The Yangtze River Delta and Pearl River Delta manufacturing belts concentrate procurement for mineral wool and ceramic fiber systems in power generation retrofits.
India
Domestic production incentives under the PLI scheme for capital goods stimulate insulation demand as steel and cement capacity expands. CEA power sector regulations push boiler operators toward higher-temperature material specifications. The Gujarat and Maharashtra industrial corridors drive procurement concentration for calcium silicate and mineral wool in chemical processing and power generation applications.
Saudi Arabia
Petrochemical infrastructure expansion along the Eastern Province creates sustained demand for high-temperature insulation in ethylene cracker and refinery construction. SAMR technical regulations harmonize with Gulf Standards Organization thermal performance benchmarks. The Jubail and Yanbu industrial cities concentrate specification authority for ceramic fiber and cellular glass systems in new-build petrochemical complexes.
Hot Insulation Materials Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding premium positions through captive raw material access and the latter competing on application engineering agility. The market structure compresses into three functional archetypes: diversified materials conglomerates with refractory heritage, pure-play insulation specialists with dense technical service capabilities, and regional fabricators serving cost-sensitive construction segments. Competitive intensity manifests through backward integration into alumina-silicate fiber production and strategic partnerships with engineering-procurement-construction contractors for specification lock-in.
Within the diversified materials tier, Morgan Advanced Materials and Unifrax occupy positions anchored by fused silica and ceramic fiber manufacturing heritage. Promat exemplifies the specialist archetype through its calcium silicate engineering focus. Among Asia-Pacific fabricators, Luyang Energy-saving Materials Co., Ltd. represents regional scale players competing on domestic supply chain proximity. Alkegen sits within the technology-transition segment, reflecting industry consolidation patterns around bio-soluble fiber alternatives.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| Promat |
| Unifrax |
| Alkegen |
| Luyang Energy-saving Materials Co., Ltd. |
| Thermal Ceramics |
| Pyrotek |
| Isolite Insulating Products Co., Ltd. |
| Skamol |
| Others |
Value Network & Pricing Analysis
EU ETS carbon pricing gates supply qualification and price differentiation simultaneously, forcing calcium silicate and mineral wool producers to absorb certification costs while premium ceramic fiber suppliers capture margin from emissions-accountable buyers. This regulatory filter compresses mid-tier pricing power and accelerates bifurcation between commodity and engineered thermal barrier tiers.
Pricing Analysis
Long-term offtake contracts dominate procurement for power generation utilities and petrochemical operators, insulating qualified suppliers from spot volatility while project-based spot purchases govern turnaround season demand spikes. Price differentiation hinges on REACH compliance tier and thermal performance certification, with EU-manufactured ceramic fiber commanding substantial premiums over mineral wool alternatives. Cost compression in standard-grade mineral wool intensifies as Chinese capacity expansion feeds global oversupply. Refinery maintenance contractors exhibit highest price sensitivity, whereas aerospace turbine programs demonstrate lowest elasticity due to specification lock-in and liability exposure.
Supply Chain Analysis
Strategic stockpiling of refractory-grade alumina and bauxite concentrates inventory preferences among ceramic fiber producers seeking buffer against Guinean mining disruption and Australian shipping cascades. Supply concentrates in China, Germany, and the United States for finished insulation systems, while raw material extraction draws from Guinea, Australia, and Brazil. Binder chemistry and inorganic fiber formulations rest on petrochemical and metallurgical coke inputs. Single-source vulnerability runs through Guinean bauxite concentration. Distribution runs through specialized refractory distributors for high-temperature grades and construction supply houses for commodity mineral wool.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerogel-derived microporous insulation threatens incumbent ceramic fiber positions in ethylene cracker and solid oxide electrolyzer applications, forcing established suppliers to defend specification authority through accelerated R&D and certification investment.
For Market Incumbents: Fortify specification lock-in with engineering-procurement-construction contractors by embedding thermal engineering consultants in client validation workflows, while accelerating backward integration into alumina-silicate fiber production to capture margin from refractory-grade alumina volatility. Aerogel substitution in premium furnace lining applications demands rapid microporous product line expansion and joint development partnerships with green hydrogen electrolyzer developers. For New Entrants and Emerging Players: CE marking fast-track for bio-soluble ceramic fiber alternatives opens specification pathways in German chemical processing clusters facing ECHA carcinogenicity scrutiny. Target India's PLI-scheme manufacturing corridors for calcium silicate and mineral wool capacity localization, where domestic steel and cement expansion outpaces qualified supplier presence. Lead with performance-based contracting models bundling installation with guaranteed heat-loss reductions to differentiate from established distributors lacking application engineering depth. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ceramic fiber manufacturing as sol-gel microporous technology requires specialized production infrastructure and toxicology dossier preparation for REACH compliance. Acquisition targets should emphasize specialists with captive raw material positions in alumina-silicate chemistry and dense technical service capabilities in turbine module anchoring. Monitor ECHA refractory ceramic fiber classification proceedings as signal for reformulation cost inflection and mineral wool substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina-Silicate Fiber Production | Captive supply of refractory-grade raw materials insulates margins from Guinean bauxite volatility and shipping disruption cascades. |
| Bio-Soluble Fiber Certification Investment | REACH-aligned toxicology dossiers open specification pathways in EU chemical processing clusters facing ECHA carcinogenicity scrutiny. |
| Performance-Based Contracting Expansion | Energy service company partnerships shift risk allocation and create recurring revenue attachments through guaranteed heat-loss outcomes. |
| Microporous Product Line Development | Sol-gel derived insulation captures ethylene cracker and solid oxide electrolyzer specifications from legacy calcium silicate suppliers. |
| India PLI Corridor Manufacturing Localization | Domestic capacity placement captures steel and cement expansion demand under government-backed capital goods incentives. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EU ETS compliance disclosures, and customs trade data for refractory material flows. Primary interviews engaged plant engineers at power generation utilities, procurement leads at petrochemical operators, technical R&D directors at ceramic fiber manufacturers, and engineering-procurement-construction contractor specification managers. Bottom-up triangulation across installation volume estimates and top-down validation against industrial capacity expansion databases ensured cross-verification of demand projections.
Segmentation dimensions modeled include material chemistry tier, thermal performance threshold, installation method rigidity, and end-use industry emissions accountability across the analysis window. CAGRs derived from regression analysis of historical procurement patterns against regulatory enforcement intensity and industrial clustering trajectories. Forecast inputs incorporated EU ETS carbon price pathways, MIIT efficiency mandate implementation schedules, and PLI scheme disbursement velocity for Indian manufacturing capacity.
Decision-makers should treat outputs as directional under assumptions of sustained EU ETS price escalation and stable alumina supply from existing mining concentrations; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA refractory ceramic fiber classification proceedings and green hydrogen electrolyzer deployment timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Wire Insulation and Jacketing Compounds Market
Insulation Materials
Cold-Air Diffusion Market
Insulation Materials
One-Component Foam Market
Insulation Materials
Impact Sound Insulation Acoustic Mat Market
Insulation Materials
France Foam Insulation Market
Insulation Materials
Global PVC Foam Sheet Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Carbon Foam Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
Radiation Shielding Materials Market
Insulation Materials
Global Insulation Market
Insulation Materials
Beryllium Oxide Market
Insulation Materials
UK Industrial Insulation Market
Insulation Materials
Thin Insulation Market
Insulation Materials
Rock Wool Insulation Board Market