
 Europe Construction Adhesives Market | 2026-2036
Europe Construction Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Construction Adhesives Market Foresight
Asset-light leasing models for application equipment are reshaping competitive entry in Europe's construction adhesives sector. Sika AG leverages its captive distribution network to sustain premium positioning across Swiss and German infrastructure projects. Henkel AG & Co. KGaA anchors its position through R&D intensity in reactive polyurethane systems for structural bonding. Bostik SA competes via specialized formulations tailored to French residential renovation contractors.
Europe construction adhesives are formulated polymer systems—typically acrylics, polyurethanes, epoxies, or silicones—engineered to bond structural and non-structural building materials under variable temperature and moisture conditions, with shear strengths ranging from flexible sealant grades to structural epoxies exceeding ten megapascals. Their primary purpose is to replace or supplement mechanical fasteners in modern building envelopes, enabling lighter assemblies and improved thermal bridging performance. Polyurethane adhesives dominate volume in flooring applications where flexibility and moisture resistance command margin premiums. Water-based acrylics represent the fastest-expanding technology segment as REACH VOC limits tighten across EU member states. Reactive systems occupy the highest-margin tier in structural wall assembly bonding for commercial and institutional builds.
EMA chemical safety assessments, REACH substance restrictions, and CE marking under the Construction Products Regulation collectively determine which adhesive chemistries gain market access across EU territory. ECHA's ongoing substance evaluations are forcing reformulation timelines that favor suppliers with in-house toxicology and regulatory affairs capabilities. Buyers and manufacturers must monitor the EU Green Deal's embodied carbon reporting requirements, as product-level environmental product declarations are becoming gatekeeping criteria in public procurement specifications.
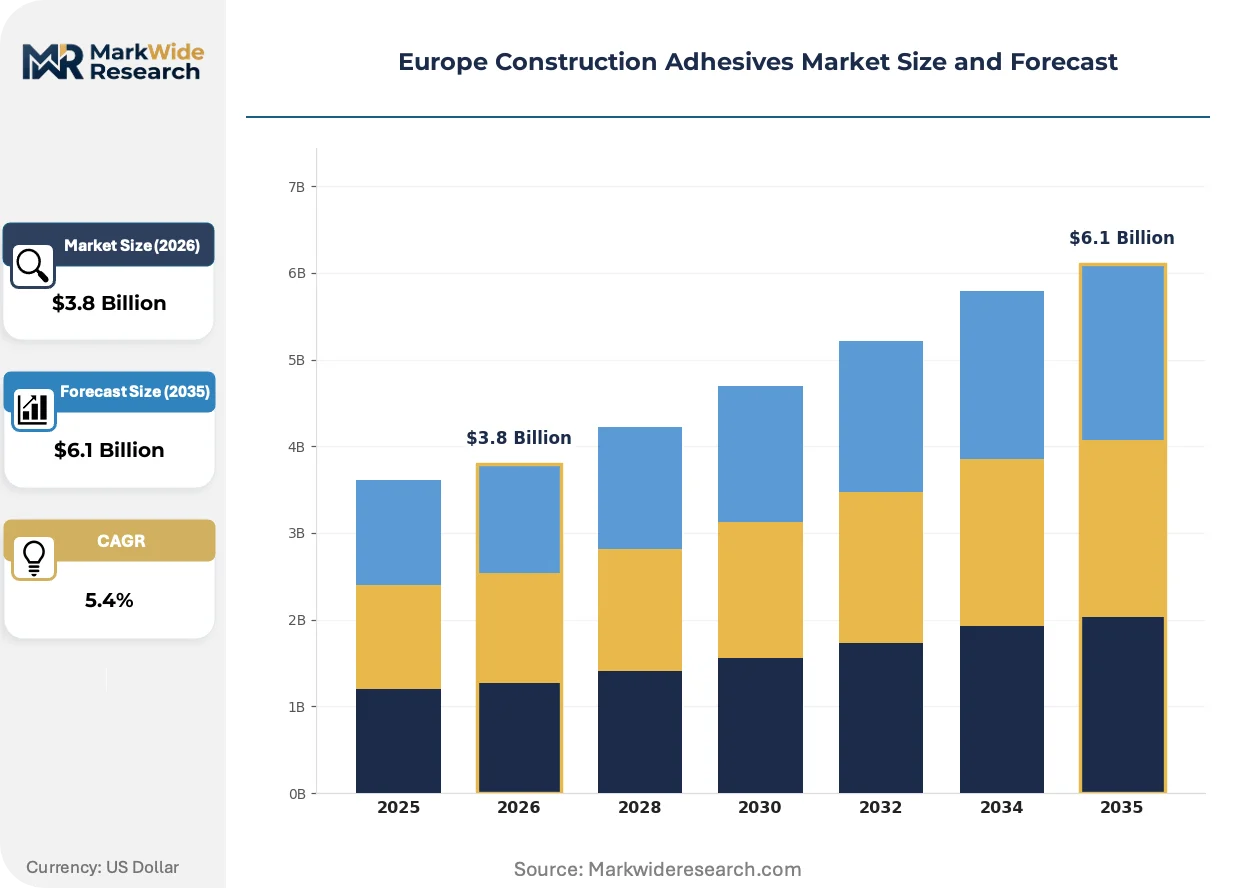
Market Dynamics
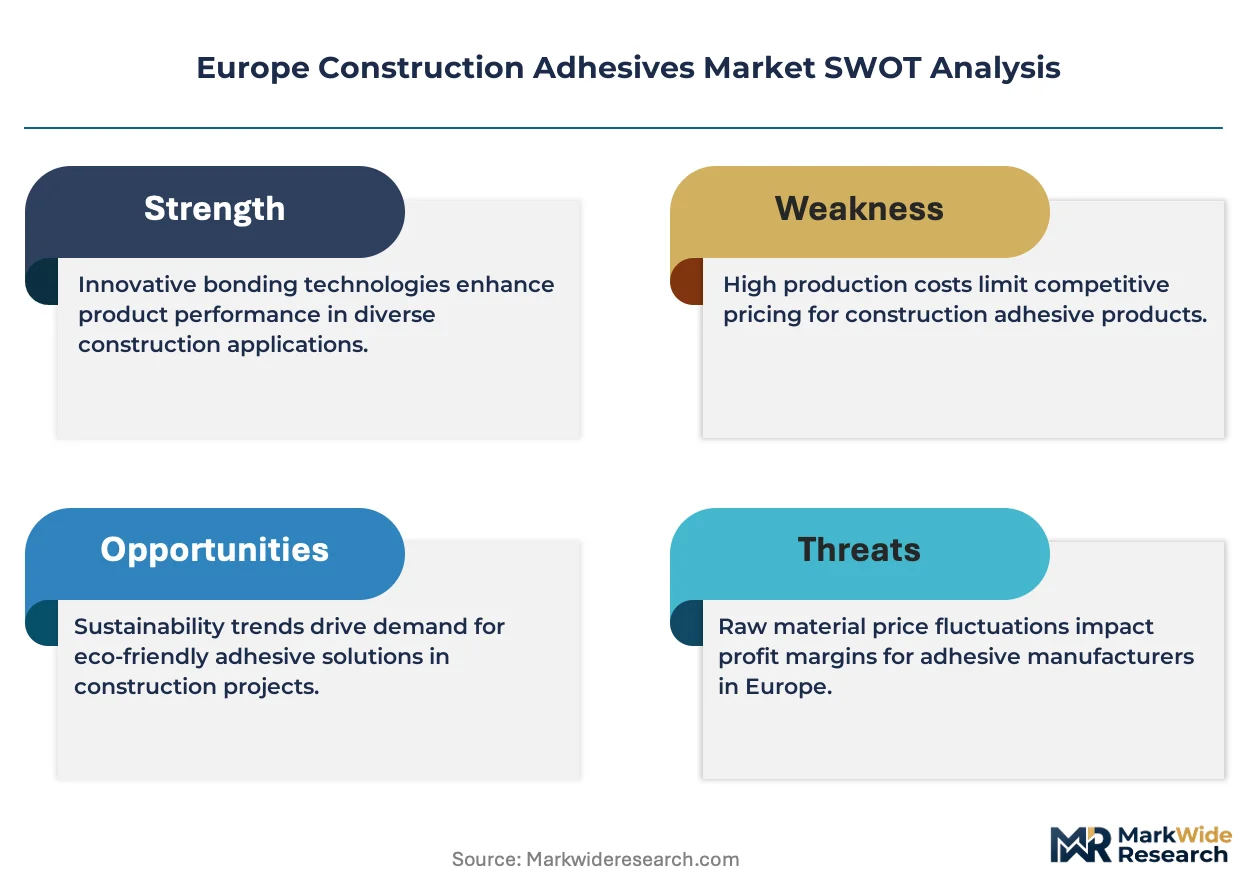
REACH substance restrictions and the EU Green Deal's embodied carbon mandates are compressing formulation windows across Europe's construction adhesives sector, favoring suppliers with captive toxicology and regulatory affairs capabilities.
Growth Catalysts
- Energy retrofit mandates:France's commercial building refurbishment regulations specify high-performance structural adhesives for thermal envelope upgrades.
- Water-based acrylics:REACH VOC limits are accelerating specification of low-emission flooring adhesives in German residential renovation.
- Insulation bonding:Cold climate construction in Nordic markets drives demand for moisture-curing polyurethane systems in exterior wall assemblies.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate input costs fluctuate with crude oil benchmarks, compressing margin visibility for reactive polyurethane producers.
- ECHA substance evaluation timelines:Ongoing SVHC assessments force reformulation cycles that disadvantage smaller formulators lacking in-house regulatory infrastructure.
- Mechanical fastening substitution:Structural screw and clip systems retain specification preference in seismic-rated commercial builds, limiting adhesive penetration in high-load applications.
Strategic Opportunities
- CE marking convergence:The Construction Products Regulation's harmonized technical specifications create pan-EU market access for certified structural bonding systems.
- Asset-light equipment leasing:Application tool rental models lower entry barriers for regional distributors seeking to capture contractor specification influence.
- Cross-laminated timber construction:Mass timber building codes in Austria and Germany specify engineered wood adhesives for structural panel bonding.
Industry Challenges
- Formulation chemist scarcity:Expertise in reactive system stabilization and rheology control concentrates among legacy European chemical conglomerates.
- Environmental product declaration data collection:Supply chain carbon accounting requirements demand granular upstream transparency that mid-tier formulators struggle to assemble.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Construction Adhesives Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Epoxy, Silicone Application: Flooring, Roofing, Wall Assembly, Insulation End User: Commercial, Residential, Industrial, Institutional Technology: Solvent-Based, Water-Based, Hot Melt, Reactive |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, Arkema Group, H.B. Fuller Company, MAPEI S.p.A., Bostik SA, Soudal Holding N.V., 3M, Dow Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Construction Adhesives Market Shifts & Advancements
Digital specification platforms and bio-based feedstocks are restructuring how adhesive chemistries reach European construction procurement channels.
Embedded sensor technology is digitizing quality assurance in structural adhesive applications. German infrastructure contractors now specify IoT-enabled cure monitoring for bridge deck bonding. Real-time viscosity and temperature data streams are compressing inspection cycles and reducing rework liability on public works projects.
REACH authorization requirements for diisocyanates are forcing segmentation between professional-grade and consumer-accessible polyurethane formulations. Industrial applicators must now document worker training certification to purchase high-performance structural products. This bifurcation is concentrating volume among certified installation networks in France and Benelux markets.
Consolidation among French residential renovation contractors is reshaping specification authority. Large multi-trade platforms now centralize adhesive procurement decisions that previously fragmented across individual flooring and insulation subcontractors. This buyer concentration is compressing supplier margins while elevating technical service demands in the Paris and Lyon metropolitan corridors.
Europe Construction Adhesives Market Segmentation
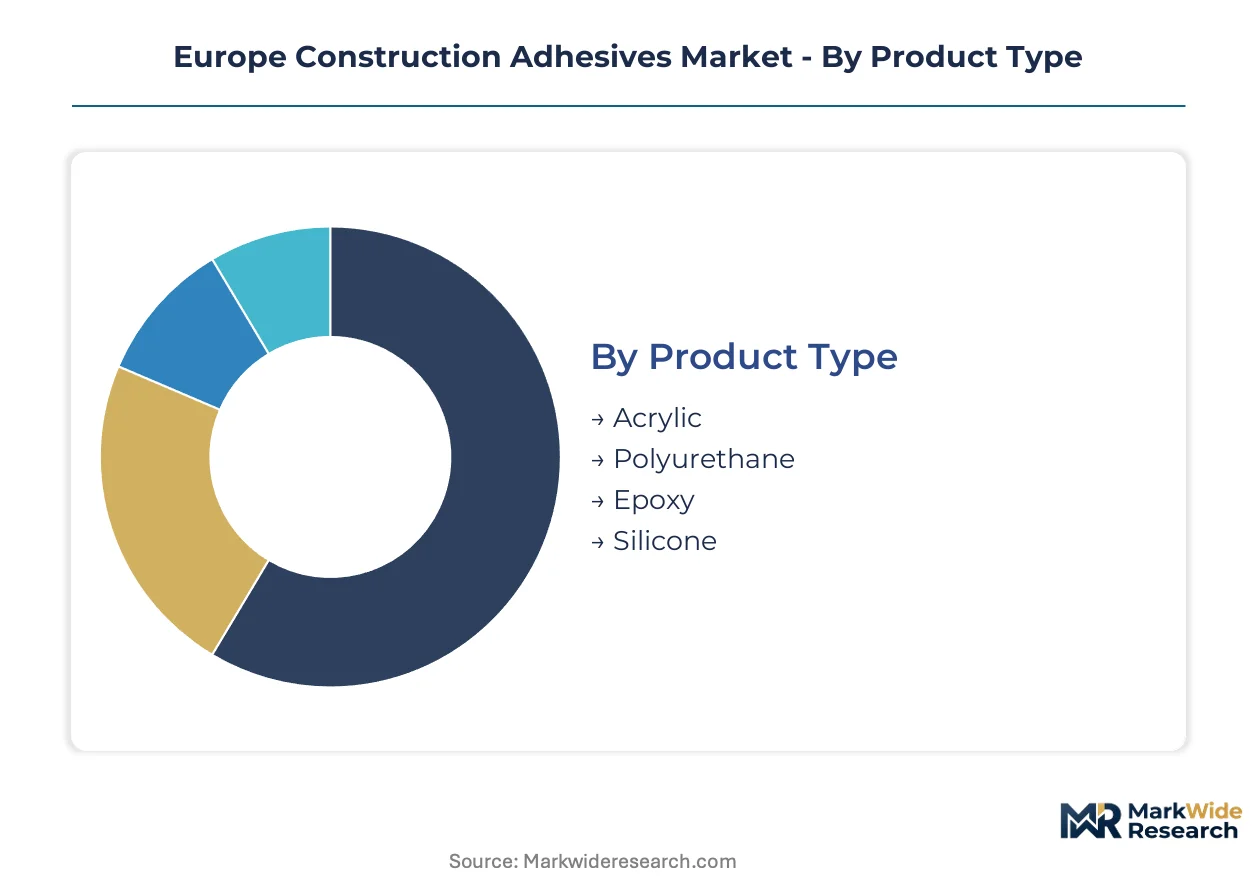
Adhesive specification in European construction flows through distinct technical and commercial channels. Product chemistry, application method, and end-use requirements create overlapping demand patterns that suppliers must navigate simultaneously.
Product Type:
Polyurethane formulations turn over fastest in renovation cycles, while epoxy systems persist for decades in structural installations. Acrylic volumes fluctuate with seasonal flooring activity.
- Polyurethane:Moisture-curing systems deliver flexibility and bond strength across temperature extremes. German flooring contractors specify these for heated screed applications where thermal cycling demands elasticity. Nordic exterior wall assembly specifications favor polyurethane for cold-climate moisture resistance.
- Acrylic:Water-dispersed polymer emulsions dominate low-VOC flooring adhesives under tightened REACH limits. French residential renovation contractors are switching specification from solvent systems to acrylics for parquet bonding in energy retrofit projects.
- Epoxy:Two-component thermoset systems anchor structural load-bearing connections in commercial builds.
- Silicone:Neutral-cure formulations seal expansion joints and curtain wall interfaces against weather intrusion.
Polyurethane anchors the volume base while acrylic gains share at the steepest rate.
Application:
Margin tiers separate permanent structural bonds from replaceable finish installations. Flooring applications command the highest adhesive consumption per square meter of built space.
- Flooring:Elastic bonding of engineered wood, luxury vinyl tile, and carpet systems requires rheology-tuned trowel-grade products. German residential renovation activity concentrates demand for low-emission acrylic and polyurethane flooring adhesives. REACH VOC thresholds are disqualifying solvent-based alternatives from specification.
- Wall Assembly:Structural panel bonding for cross-laminated timber and insulated metal panels demands engineered strength and fire performance. Austrian and German mass timber building codes specify certified structural adhesives for CLT panel lamination.
- Roofing:Membrane attachment and flashing sealant applications prioritize UV stability and ponding water resistance.
- Insulation:Exterior thermal envelope upgrades in France and Benelux drive specification of high-tack products for board attachment.
Wall assembly commands premium pricing while flooring delivers the deepest volume throughput.
End User:
Procurement sophistication varies sharply across buyer categories. Commercial developers centralize specification authority; residential contractors fragment decisions across trades.
- Commercial:Large-scale office and retail developments specify certified structural systems through architect-led procurement. France's commercial energy retrofit mandates are concentrating specification of high-performance adhesives for thermal envelope upgrades in Paris and Lyon metropolitan corridors.
- Residential:Individual renovation projects and single-family construction drive specification through flooring and insulation subcontractors. German residential renovation expansion is accelerating adhesive consumption for parquet bonding and exterior insulation finishing systems.
- Industrial:Manufacturing facility construction demands chemical-resistant flooring and containment system bonding.
- Institutional:Healthcare and education projects prioritize low-emission certifications and fire-rated assemblies.
Commercial buyers dominate premium segment value while residential channels expand most quickly.
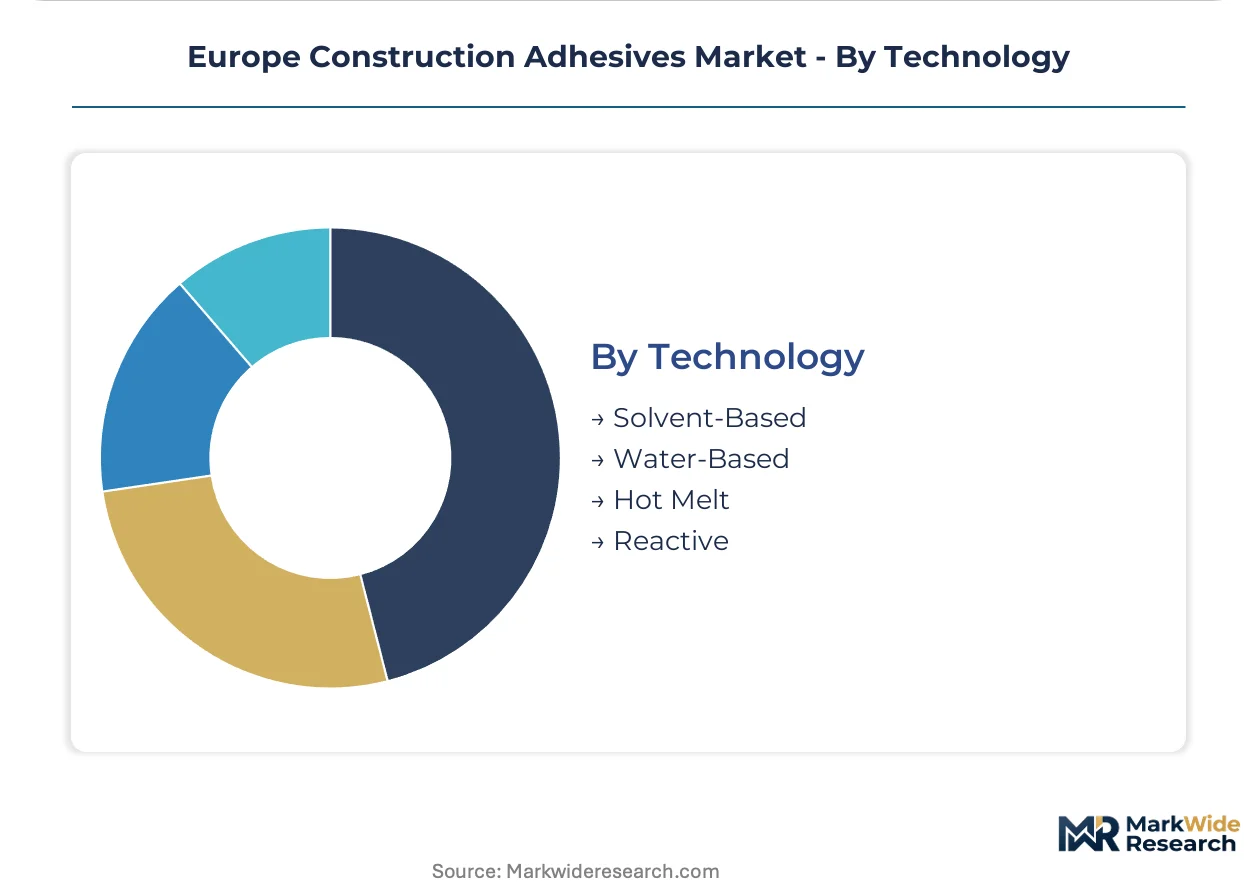
Technology:
Regulatory pressure is collapsing solvent-based volumes while reactive systems capture structural specification. Water-based formulations are crossing performance thresholds that previously required solvent carriers.
- Water-Based:Acrylic and polyurethane dispersions eliminate VOC emissions at point of application. REACH authorization timelines for diisocyanates are accelerating professional-grade water-based specification in German and French flooring markets.
- Reactive:Two-component polyurethane and epoxy systems cure through chemical reaction to deliver structural strength. CE marking under the Construction Products Regulation enables pan-EU market access for certified reactive structural bonding systems.
- Solvent-Based:Rapid-tack formulations retain niche specification where open time and initial grab outweigh emission concerns.
- Hot Melt:Thermoplastic systems serve prefabricated component manufacturing and temporary positioning applications.
Reactive technology commands the highest margin tier while water-based systems climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's commercial energy retrofit mandates and Germany's residential renovation incentives are concentrating adhesive demand across Western Europe. REACH compliance timelines and EU Green Deal carbon reporting requirements are reshaping supplier access in each national market. Nordic cold-climate construction specifications and Alpine mass timber building codes add technical complexity to regional procurement patterns.
Germany
Residential renovation activity for flooring and exterior insulation is expanding adhesive consumption in heated screed and energy retrofit applications. REACH VOC thresholds are disqualifying solvent-based formulations from specification in parquet bonding. The Rhine-Ruhr industrial corridor concentrates formulator R&D facilities serving Central European distribution networks.
France
Commercial building refurbishment regulations specify high-performance structural adhesives for thermal envelope upgrades in office and retail developments. The EU Green Deal's embodied carbon mandates are elevating environmental product declarations as procurement gatekeepers. The Paris and Lyon metropolitan corridors concentrate buyer consolidation among multi-trade renovation platforms.
Switzerland
Infrastructure project specifications for bridge deck and tunnel lining applications demand certified structural bonding systems. CE marking under the Construction Products Regulation enables cross-border supply into adjacent EU markets. The Zurich-Geneva axis concentrates captive distribution networks serving premium-tier public works procurement.
Austria
Mass timber building codes specify engineered wood adhesives for cross-laminated timber panel lamination in multi-story construction. ECHA substance evaluations for diisocyanates are forcing professional-grade formulation segmentation. The Vorarlberg-Tyrol alpine region concentrates CLT manufacturing capacity driving specialized adhesive specification.
Netherlands
Delta climate flood defense and marine infrastructure projects specify moisture-resistant polyurethane systems for submerged applications. The Construction Products Regulation's harmonized technical specifications facilitate pan-EU market access for certified suppliers. The Rotterdam-Amsterdam port corridor concentrates distribution logistics for Benelux and North Sea markets.
Europe Construction Adhesives Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Europe's construction adhesives sector. The market structure tiers between multinational chemical conglomerates with captive distribution and regional formulators serving contractor specification influence. Strategic archetypes include vertically integrated resin producers, application-equipment leasing platforms, and regulatory-compliance specialists. Dominant competitive moves encompass backward integration into petrochemical feedstocks and portfolio diversification into adjacent sealant and waterproofing categories.
Within the multinational chemical tier, Henkel AG & Co. KGaA and Sika AG occupy positions exemplifying divergent channel strategies. Henkel's KGaA structure represents the European corporate form anchoring reactive polyurethane system development. Sika's AG designation situates it within Swiss industrial conglomerate traditions emphasizing infrastructure project penetration. Bostik SA represents the specialized formulator archetype competing through contractor-tailored product ranges.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| Arkema Group |
| H.B. Fuller Company |
| MAPEI S.p.A. |
| Bostik SA |
| Soudal Holding N.V. |
| 3M |
| Dow Inc |
| Others |
Supply & Pricing Matrix
The Rhine-Ruhr industrial corridor concentrates polyurethane resin production capacity, and this geographic clustering of polyol and isocyanate manufacturing feeds directly into pricing leverage for German formulators serving Central European distribution networks.
Pricing Analysis
Certification level under the Construction Products Regulation creates the primary spread between premium structural bonding systems and commodity flooring adhesives. Three-tier pricing structure across premium CE-marked structural, standard professional-grade, and economy residential tiers reflects performance grade and regulatory compliance investment. Cost compression in the economy tier is intensifying because REACH-driven reformulation cycles demand R&D expenditure that smaller formulators cannot absorb. Residential renovation contractors exhibit the highest price sensitivity, while commercial developers specifying mass timber projects accept premium positioning for certified structural systems.
Supply Chain Analysis
Petrochemical feedstock volatility between Middle Eastern crude benchmarks and European natural gas pricing dominates margin visibility for reactive polyurethane producers. Manufacturing concentration rests on Germany, Belgium, and the Netherlands for base resin production, with specialty additive sourcing drawing from Switzerland and France. Supply chain risk centers on single-source vulnerability for aliphatic isocyanates used in UV-stable exterior applications. Distribution runs through captive networks for multinational formulators and independent regional distributors serving contractor specification influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated multi-trade renovation platforms in France and Germany, as contractor consolidation centralizes procurement decisions that previously fragmented across individual flooring and insulation subcontractors.
For Market Incumbents: Build regulatory affairs capabilities as a moat against REACH substance evaluation timelines that disadvantage smaller competitors. Deepen backward integration into specialty polyol production to secure margin visibility amid petrochemical volatility. Anchor position through captive distribution networks serving Swiss and German infrastructure project specifications. For New Entrants and Emerging Players: Pursue asset-light equipment leasing models to lower entry barriers and capture contractor specification influence in French residential renovation corridors. Target water-based acrylic formulations for German flooring applications where REACH VOC limits are disqualifying solvent-based alternatives. Enter through technical service partnerships with regional distributors lacking in-house application support. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulators with demonstrated EPD data collection capabilities and in-house toxicology infrastructure. Long-term viability over a five-to-ten year window hinges on EU Green Deal carbon reporting compliance. Acquisition targets should demonstrate regulatory affairs scale and REACH authorization track records. Watch ECHA substance evaluation announcements as the inflection indicator for reformulation-driven consolidation waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Polyols | Captive isocyanate supply secures margin stability against crude benchmark volatility. |
| CE Marking Investment for Structural Systems | Harmonized technical specifications enable pan-EU market access under Construction Products Regulation. |
| Environmental Product Declaration Program | Granular carbon accounting meets EU Green Deal procurement gatekeeping in French commercial retrofit. |
| Application Equipment Leasing Platform | Asset-light models lower distributor entry barriers and capture contractor specification authority. |
| Water-Based Formulation R&D Expansion | REACH VOC compliance accelerates specification shift away from solvent-based alternatives. |
Research Methodology
Cross-validation between primary interviews with plant managers at resin production facilities and secondary trade data from Cefic and customs records anchors the qualitative findings. Conversations with procurement leads at downstream flooring contractors, distribution channel partners, technical R&D directors at formulators, and regulatory affairs specialists at ECHA-notified bodies informed segmentation assumptions. Secondary sources include SEC 10-K filings of listed chemical conglomerates, EU Construction Products Regulation harmonized standards databases, and ECHA substance evaluation timelines. Bottom-up adhesive consumption estimates triangulate against top-down construction spending forecasts.
Calibration against historical volume trajectories and elasticity assumptions across product chemistry, application method, and end-use requirements shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include technology type, performance grade tier, end-use sector, and regional regulatory cluster. CAGRs derive from fitted growth curves against macro construction indicators and energy retrofit policy implementation rates. Industry-specific inputs encompass REACH authorization timelines and mass timber building code adoption patterns.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles or petrochemical feedstock pricing would shift the trajectory. Forecasts reflect assumptions about regulatory implementation pace and contractor consolidation trends. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Instant Adhesive Market
Adhesives & Sealants
Wearable Skin Adhesives Market
Adhesives & Sealants
Asia-Pacific Waterborne Adhesives Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
Saudi Arabia Adhesives Market
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
Global Engineering Adhesives Market
Adhesives & Sealants
Global Disposable Hygiene Adhesives Market
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
Europe Sealants Market
Adhesives & Sealants
Adhesive Primer Market
Adhesives & Sealants
Asia-Pacific Construction Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
Fuel Resistant Sealant Market
Adhesives & Sealants
Global Emulsion Adhesives Market
Adhesives & Sealants
Spray Fluxer Market