
 Global Fiberglass Market | 2026-2036
Global Fiberglass Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fiberglass Market Analysis
Direct supply contracts between fiberglass producers and wind turbine OEMs is reshaping procurement patterns across the value chain. Owens Corning leverages its North American manufacturing footprint to secure long-term blade supply agreements. China Jushi Co., Ltd. anchors global output through massive furnace operations in Zhejiang province. Saint-Gobain Vetrotex differentiates via specialized reinforcement products for European automotive tier ones.
Fiberglass consists of fine glass fibers drawn from molten silica, alumina, and lime formulations, typically measuring 5–25 micrometers in diameter and engineered for tensile strength above 3,400 MPa. Manufacturers extrude these fibers through platinum-rhodium bushings, then size and chop them for composite reinforcement, thermal insulation, or electrical substrate applications. Continuous fiberglass dominates volume flows into wind energy blade fabrication, where unidirectional rovings bear cyclical structural loads. Chopped fiberglass competes aggressively in automotive underbody shields and construction gypsum board facings, segments where cost-per-kilogram drives sourcing decisions. Fiberglass mats occupy stable margin pools in roofing membranes and bathroom fixture production, applications where surface finish consistency commands premium pricing.
The EU Green Deal and REACH chemical registration framework constrain resin formulations used in fiberglass composites, pushing manufacturers toward bio-based binders and lower-styrene chemistries. China's MIIT enforces GB standards on industrial glass fiber emissions, while the US EPA monitors air toxics from binder curing ovens under Clean Air Act permits. Buyers must track how carbon border adjustments and evolving product category rules for embodied emissions reshape supplier qualification criteria across jurisdictions.
Market Dynamics
Rotor diameter expansion in wind energy is compressing blade manufacturing timelines and forcing fiberglass suppliers to synchronize furnace output with turbine OEM production schedules. This demand-pull structure is reconfiguring capacity planning across the entire reinforcement materials sector.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbons in composite curing processes is accelerating adoption of thermoplastic resin systems compatible with standard fiberglass rovings.
- Wind turbine blade fabrication:Unidirectional fiberglass demand scales directly with rotor length increases, creating sustained volume commitments from Vestas, Siemens Gamesa, and Goldwind supply chains.
- China's dual carbon goals:MIIT enforcement of GB 31572 emissions standards for glass fiber production is consolidating domestic supply around Zhejiang and Jiangsu furnace clusters.
Market Restraints
- Platinum-rhodium bushing cost volatility:Precious metal price swings in bushings constitute 15-20% of direct materials cost, compressing margin predictability for continuous filament producers.
- Supply concentration in Zhejiang province:Three Chinese producers control over half of global E-glass capacity, creating geographic risk exposure for European and North American buyers.
- Carbon fiber substitution in aerospace:High-performance applications above 50-meter blade lengths increasingly specify T700-grade carbon, displacing S-glass in primary load-bearing structures.
Strategic Opportunities
- India's renewable energy corridor:Gujarat and Tamil Nadu wind installations remain undersupplied with domestic fiberglass conversion capacity, creating import-substitution openings for integrated roving-chopping operations.
- Recycled fiberglass reinforcement:Pyrolysis-based fiber recovery from decommissioned turbine blades is converging with chopped strand mat production, enabling closed-loop raw material sourcing.
- US Inflation Reduction Act:Domestic content bonuses for clean energy manufacturing are incentivizing North American furnace restarts and backward integration into boron-free glass formulations.
Industry Challenges
- Platinum alloy metallurgy expertise:Qualified bushing design engineers command premium compensation, constraining furnace expansion timelines for second-tier producers.
- REACH registration timelines:Novel sizing chemistries for bio-based binders require 18-24 month ECHA dossier preparation, delaying product launches versus incumbent epoxy-compatible formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fiberglass Market |
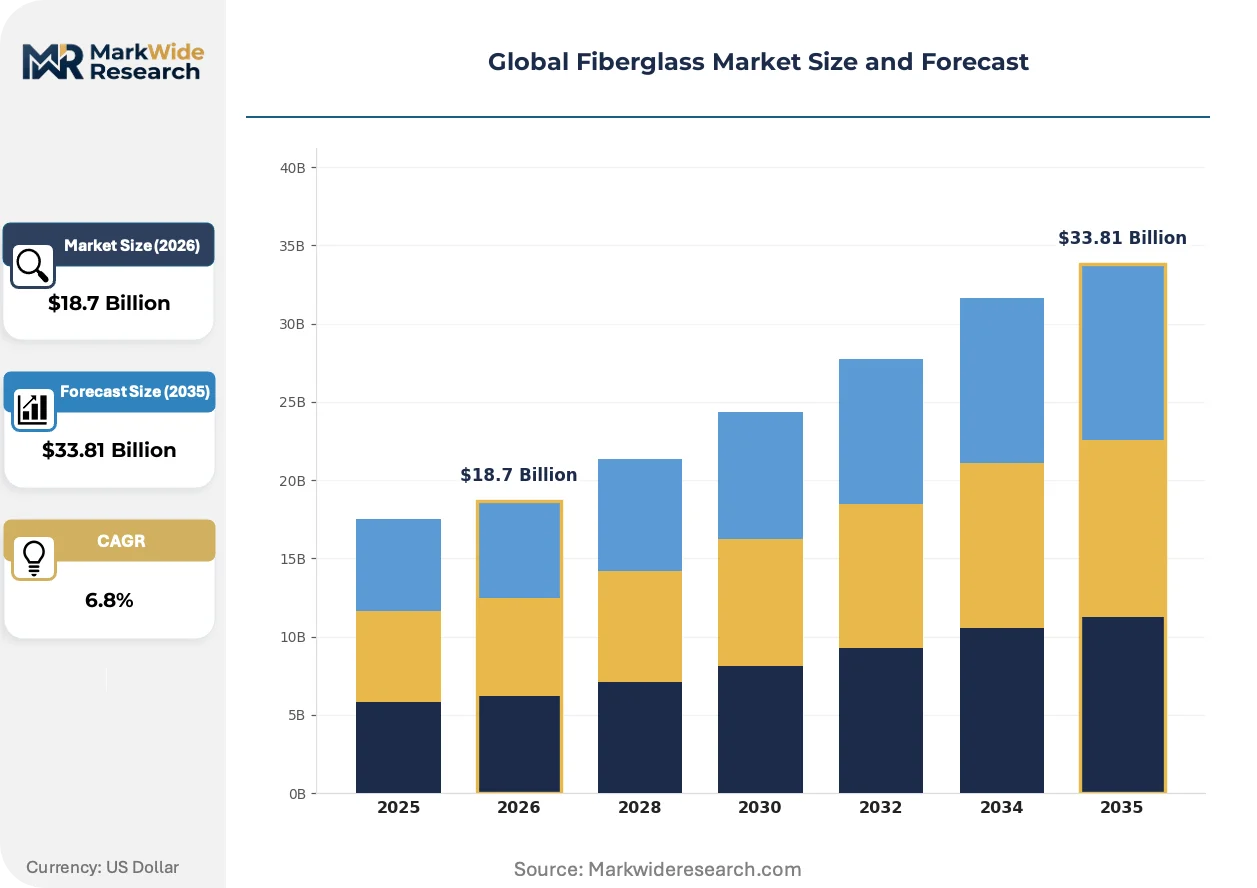
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Fiberglass, Chopped Fiberglass, Fiberglass Wool, Fiberglass Mats End Use Industry: Aerospace, Marine, Construction, Automotive Form: Composite, Reinforcement, Insulation, Sheet Application: Transport, Wind Energy, Electronics, Building & Construction |
| Companies Covered | China Jushi Co., Ltd., Owens Corning, Saint-Gobain Vetrotex, Nippon Electric Glass, Taishan Fiberglass, PPG Industries, 3B - The Fiberglass Company, Johns Manville, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fiberglass Market Emerging Trajectories
Digital thread technologies are compressing the design-to-fabrication cycle for composite components, forcing raw material suppliers to embed sensor-ready traceability into every roving package. This connectivity layer is becoming a baseline qualification criterion for tier-one wind and automotive supply contracts.
Virtual process twinning is virtualizing how fiberglass producers optimize furnace energy profiles and bushing maintenance schedules. Owens Corning and Jushi have deployed AI-driven thermal models across multi-facility networks, reducing unplanned downtime by predicting platinum alloy degradation before filament quality drifts. The technology is virtualizing capital allocation decisions, enabling smaller batch runs without efficiency penalties.
REACH chemical registration is tightening disclosure requirements for styrene-based polyester resins used in 80% of fiberglass composite formulations. ECHA's 2024 update to restriction proposals targets residual monomer content in finished articles, pushing compounders toward vinyl ester and epoxy alternatives. European automotive tier ones are responding by dual-qualifying resin systems, extending material approval cycles by 8-12 months.
Direct mill-to-blade-factory contracts are displacing distributor-mediated procurement in wind energy supply chains. Siemens Gamesa and Vestas now negotiate multi-year roving supply agreements with volume commitments indexed to installed capacity forecasts, bypassing traditional reinforcement distributors. This pattern is most pronounced in Denmark, Spain, and China's coastal manufacturing zones where blade fabrication clusters concentrate.
Global Fiberglass Market Segmentation
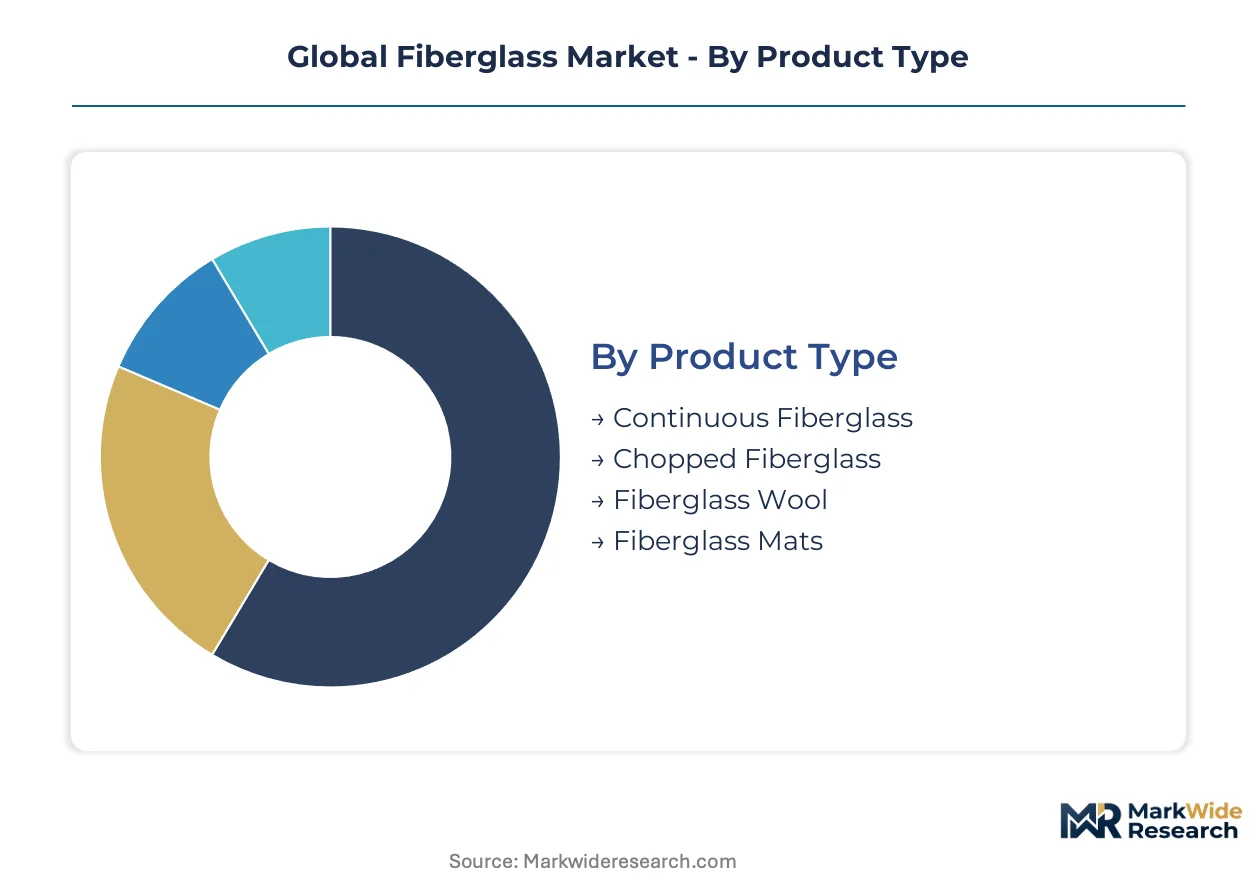
Segmentation in fiberglass markets exposes how technical specifications and regulatory exposure vary dramatically across product forms and end-use applications. Procurement teams must align supplier qualification with the specific performance thresholds and compliance burdens inherent to each segment category.
Product Type:
After-sales service intensity varies sharply across product types, with continuous filament formats demanding specialized metallurgical maintenance support that chopped formats rarely require.
- Continuous Fiberglass:Extruded as unbroken filaments through platinum-rhodium bushings, this format achieves tensile strengths exceeding 3,400 MPa. Demand concentrates in Denmark and China's coastal blade fabrication clusters, where Vestas and Goldwind specify unidirectional rovings for 80-meter-plus rotors. Furnace synchronization with OEM production schedules creates premium service contracts around bushing refurbishment and thermal optimization.
- Chopped Fiberglass:Cut to 3–50 millimeter lengths and treated with silane sizing agents, this grade feeds automotive underbody shields and construction gypsum facing. Germany's automotive tier ones source aggressively from Zhejiang suppliers, prioritizing cost-per-kilogram over technical service intensity. ECHA's evolving styrene restrictions are pushing compounders toward vinyl ester compatibility testing.
- Fiberglass Wool:Spun into non-woven thermal and acoustic insulation matrices for building envelopes. India's construction boom and Saudi Arabia's NEOM development are absorbing volume from Egyptian and Turkish furnace operations.
- Fiberglass Mats:Chopped strands bound with powder or emulsion binders for surface layer applications in roofing membranes and bathroom fixtures. Surface finish consistency commands premium pricing from Japanese and South Korean fixture manufacturers.
Continuous fiberglass holds the largest share; momentum sits with chopped fiberglass as automotive lightweighting accelerates.
End Use Industry:
Cost tier stratification separates aerospace qualification expenses from construction commodity purchasing, with marine and automotive occupying intermediate positions on the specification-cost spectrum.
- Construction:Gypsum board facings, exterior insulation finish systems, and roofing membranes consume chopped strand and mat formats in high volumes. China's MIIT emissions enforcement is consolidating supply around Jiangsu province furnace clusters serving domestic infrastructure buildouts.
- Automotive:Underbody shields, bumper beams, and battery enclosures specify chopped and continuous formats depending on structural load requirements. Germany's KBA type-approval processes and US NHTSA crash standards drive dual-qualification of resin-glass combinations.
- Marine:Hull laminates and deck structures in recreational and commercial vessels demand corrosion-resistant E-glass and vinyl ester compatibility. Italian and Turkish boatbuilders source from Egyptian suppliers to manage working capital cycles.
- Aerospace:Secondary structures and interior panels specify S-glass for modulus advantages, though T700 carbon fiber is displacing primary load paths in next-generation programs. FAA certification timelines extend material approval cycles substantially.
Construction dominates volume; aerospace represents the fastest-growing trajectory for high-modulus specialty grades.
Form:
Application context determines whether fiberglass functions as structural reinforcement, thermal barrier, or finished surface, with each form carrying distinct margin profiles and technical service requirements.
- Composite:Embedded in polymer matrices for structural applications across wind blades and automotive components. The EU F-Gas Regulation is accelerating thermoplastic resin system adoption compatible with standard rovings.
- Insulation:Deployed as batt, loose-fill, or spray-applied thermal barriers in residential and commercial building envelopes. US IRA domestic content bonuses are incentivizing North American furnace restarts for boron-free formulations.
- Reinforcement:Integrated into concrete, asphalt, and gypsum to control shrinkage cracking and improve durability. India's infrastructure corridors are absorbing imported roving volumes ahead of domestic conversion capacity expansion.
- Sheet:Manufactured as flat or corrugated panels for roofing, cladding, and greenhouse applications. Surface UV resistance specifications vary sharply between Mediterranean and Nordic installations.
Composite form holds the largest share; insulation is climbing the fastest on building energy code tightening across multiple jurisdictions.
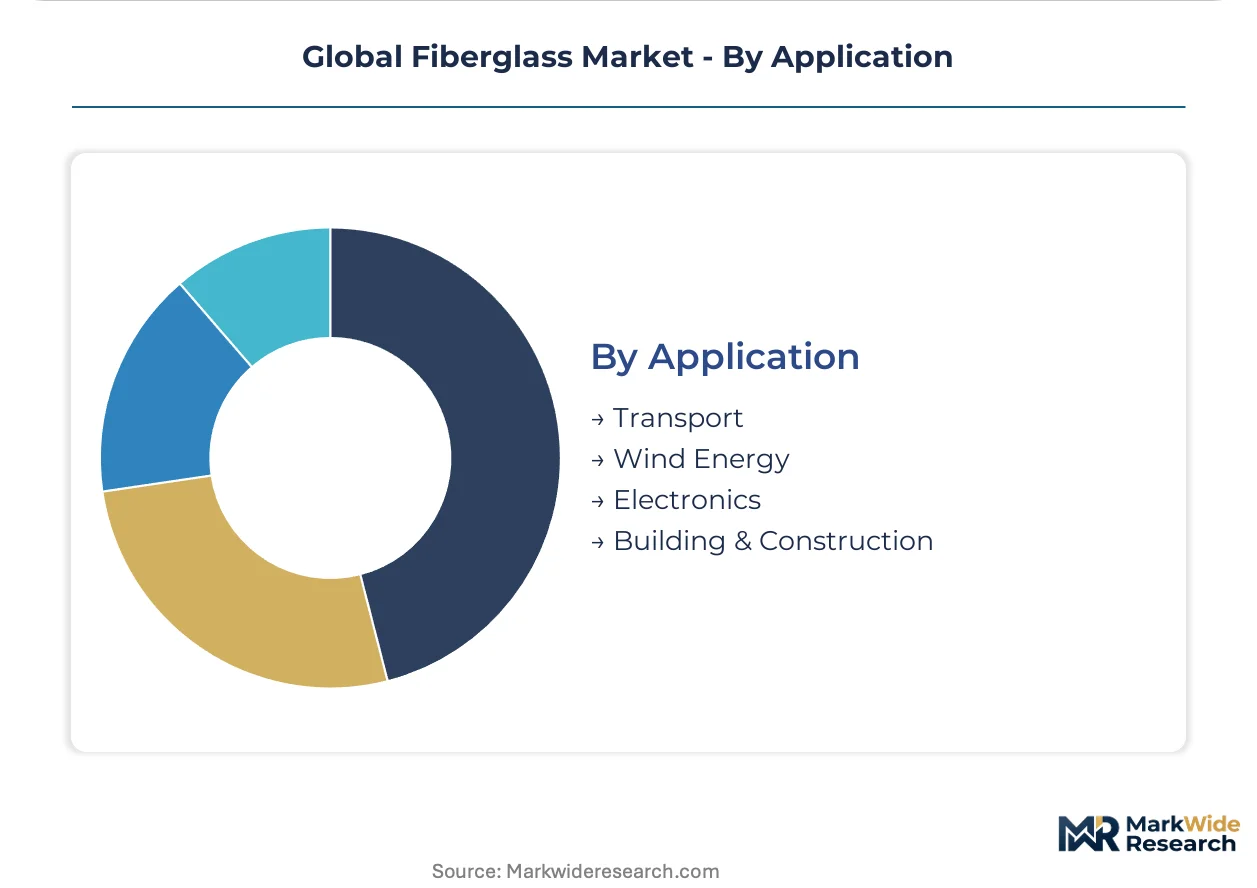
Application:
Customer type separation distinguishes project-driven wind energy procurement from recurring electronics substrate purchasing, with transport and building construction occupying hybrid positions.
- Wind Energy:Blade fabrication consumes unidirectional rovings and multiaxial fabrics in the largest single-application volume globally. Direct mill-to-factory contracts between Zhejiang suppliers and Denmark-based OEMs are displacing traditional distributor channels.
- Building & Construction:Encompasses insulation, roofing, and facade applications with fragmented buyer structures and price-sensitive procurement. REACH registration constraints on binder chemistries are extending material approval timelines for European projects.
- Transport:Rail interior panels, truck fairings, and shipping containers specify fire-retardant formulations meeting EN 45545 and FMVSS 302 standards. Certification burden concentrates sourcing among qualified compounders.
- Electronics:Printed circuit board substrates and antenna housings demand low-dielectric constant E-glass with tight dimensional tolerance. Japan's METI supply chain resilience initiatives are diversifying sourcing beyond Zhejiang concentration.
Building & construction holds the largest share; wind energy is gaining share fastest on rotor diameter expansion and offshore installation acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deepwater ports and integrated rail-water intermodal terminals underwrite China's dominance in fiberglass feedstock logistics, while Denmark's Esbjerg offshore wind assembly hub anchors European blade fabrication demand.
China
Jushi and Taishan Fiberglass operate massive furnace clusters in Zhejiang and Jiangsu provinces serving wind turbine OEMs. MIIT enforces GB 31572 emissions standards that consolidate supply around compliant producers. The Ningbo-Zhoushan port complex handles boron-free glass batch imports for domestic boron-free E-glass formulation.
United States
Texas and Iowa wind corridors drive roving demand for 80-meter-plus rotor blades. EPA Clean Air Act permits regulate binder curing oven emissions at Kansas and Ohio furnace operations. Owens Corning leverages its North American footprint to secure long-term supply agreements with Vestas and Siemens Gamesa blade factories.
Germany
KBA type-approval processes for automotive composite components sustain chopped fiberglass demand from Bavarian tier-one suppliers. ECHA REACH registration timelines extend material approval cycles for novel sizing chemistries. The Leipzig-Halle logistics cluster concentrates converter operations serving Czech and Polish blade fabrication plants.
India
Gujarat and Tamil Nadu wind installations remain undersupplied with domestic fiberglass conversion capacity. BIS standards on industrial glass fiber quality constrain import substitution timelines. The Mundra port zone hosts emerging roving-chopping operations targeting renewable energy corridor demand.
Japan
METI supply chain resilience initiatives diversify electronics-grade E-glass sourcing beyond Zhejiang concentration. Low-dielectric constant specifications for 5G antenna substrates sustain premium pricing for dimensional-tolerant formats. The Nagoya industrial zone concentrates printed circuit board laminate fabricators.
Global Fiberglass Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in furnace operations and downstream in conversion. The market exhibits tiered consolidation, with three Chinese producers controlling majority E-glass capacity and Western incumbents defending specialty positions. Strategic archetypes separate scale-driven commodity suppliers, premium reinforcement specialists, and integrated wind energy solution providers. Dominant competitive moves center on direct mill-to-blade-factory contract displacement of distributor channels, and AI-driven furnace optimization reducing unplanned downtime.
Among Chinese state-linked furnace operators, China Jushi Co., Ltd. and Taishan Fiberglass exemplify the scale-driven archetype through massive Zhejiang-based production platforms. Owens Corning occupies a position bridging North American manufacturing presence with long-term OEM supply agreements. Saint-Gobain Vetrotex represents the European premium tier through specialized reinforcement products.
| Leading Market Players |
|---|
| China Jushi Co., Ltd. |
| Owens Corning |
| Saint-Gobain Vetrotex |
| Nippon Electric Glass |
| Taishan Fiberglass |
| PPG Industries |
| 3B - The Fiberglass Company |
| Johns Manville |
| LANXESS |
| Others |
Supply Flow & Price Mechanics
The Ningbo-Zhoushan port complex channels boron-free glass batch imports into Zhejiang furnace clusters, where freight cost differentials between deepwater and feeder ports amplify pricing power for coastal producers while inland buyers absorb logistics premiums that stratify end-product pricing across construction and wind energy segments.
Pricing Analysis
Volume-discount tiering structures separate direct mill-to-factory contracts from distributor-mediated procurement, with unidirectional roving agreements indexed to installed capacity forecasts commanding premium stability while chopped strand spot purchases fluctuate with precious metal bushing cost volatility. Price differentiation hinges on furnace scale economies and REACH-compliant sizing chemistry certification tiers. Cost compression in automotive-grade chopped formats is intensifying because German tier ones are dual-qualifying vinyl ester-compatible suppliers. Construction gypsum facing buyers exhibit highest price sensitivity; aerospace S-glass qualification programs show least.
Supply Chain Analysis
Contract-manufacturing concentration sits with Jushi and Taishan Fiberglass operating captive furnace networks, while Owens Corning and Saint-Gobain Vetrotex maintain integrated roving-conversion capabilities. Geographic supply concentration centers on China, the United States, and Germany, with Egyptian and Turkish operations serving Mediterranean marine builders. Raw material dependencies draw from platinum-rhodium alloy bushings, boron-free silica batch formulations, and styrene-based polyester resin systems. Single-source vulnerability around Zhejiang E-glass capacity creates geographic risk exposure for European and North American buyers. Distribution runs through direct OEM contracts displacing traditional reinforcement distributors in wind energy clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Fiberglass Market is exiting a capital expenditure trough as wind turbine installation cycles recover, with rotor diameter expansion driving sustained furnace utilization rates across Zhejiang and North American production hubs.
For Market Incumbents: Build switching-cost moats through embedded digital thread traceability in every roving package, making sensor-ready connectivity a baseline qualification criterion that locks in Vestas and Siemens Gamesa blade factory relationships. Deepen backward integration into boron-free glass batch formulation to capture IRA domestic content bonuses. Defend against carbon fiber substitution in primary load-bearing structures by accelerating S-glass modulus improvements and qualifying hybrid roving-carbon architectures. For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu wind corridors represent the most penetrable entry point, where domestic fiberglass conversion capacity remains structurally undersupplied against renewable energy installation targets. Recycled fiberglass reinforcement via pyrolysis-based fiber recovery from decommissioned turbine blades offers a second white-space avenue, converging with chopped strand mat production for closed-loop raw material sourcing. A go-to-market angle anchored in BIS quality certification compliance and Mundra port zone logistics access can bypass incumbent Zhejiang supply chain dominance. For Investors and Strategic Acquirers: AI-driven furnace optimization specialists with multi-facility thermal modeling capabilities represent the priority acquisition archetype, as predictive platinum alloy degradation analytics reduce unplanned downtime and virtualize capital allocation decisions. Long-term viability over the next decade hinges on thermoplastic resin system compatibility and bio-based binder chemistry portfolios that align with EU F-Gas Regulation phasedown timelines. The signal to watch is ECHA restriction proposal updates on residual styrene monomer content, which will accelerate vinyl ester and epoxy alternative adoption curves. Cross-checking against IEA wind energy capacity installation forecasts is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron-Free Batch | Captures US IRA domestic content bonuses for clean energy manufacturing supply chains. |
| AI-Driven Furnace Thermal Optimization | Reduces unplanned downtime by predicting platinum-rhodium bushing degradation before filament quality drifts. |
| Direct Mill-to-Blade-Factory Contracts | Displaces distributor channels and locks in volume commitments indexed to OEM installed capacity forecasts. |
| Pyrolysis-Based Fiber Recovery Operations | Enables closed-loop raw material sourcing from decommissioned turbine blades into chopped strand mat production. |
| Thermoplastic Resin System Qualification | Aligns product portfolios with EU F-Gas Regulation phasedown of hydrofluorocarbon curing processes. |
Methodological Framework
Cross-validation between furnace operator production data and wind turbine OEM procurement disclosures anchors the qualitative findings, combining primary interviews with plant managers, blade factory procurement leads, technical R&D directors, and distribution channel partners with secondary validation through customs/trade data, SEC 10-K filings, and ACC industry reports. Bottom-up capacity modeling and top-down end-use demand estimation triangulate volume figures across the analysis window.
Calibration against historical furnace utilization rates and platinum-rhodium price volatility indices shapes the projection framework across product type, end-use industry, and regional production hub segmentation dimensions. CAGRs derive from regression analysis of installed wind capacity forecasts and automotive lightweighting content-per-vehicle trajectories. Forecast inputs include MIIT emissions enforcement timelines and ECHA REACH registration progression for novel sizing chemistries.
Practitioners should monitor platinum-rhodium alloy price spikes, carbon fiber T700-grade cost parity thresholds, and EU carbon border adjustment implementation for early signals of forecast revision. Cross-checking against IEA renewable energy deployment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Carbon Fiber Wrap Market
Fibers
Fiberglass Cloth Market
Fibers
Thermoformed Fiber Market
Fibers
Carbon Fiber Market
Fibers
Keratin Market
Fibers
Ceramic Fiber Market
Fibers
Drug Integrated Polymer Fibers Market
Fibers
Global Bicomponent Fiber Market
Fibers
Triacetate Cellulose Market
Fibers
Short Fiber Thermoplastics Market
Fibers
Continuous Fiber Thermoplastic (CFT) Market
Fibers
PAN-Based Carbon Fibers Market
Fibers
Metal Fiber Felt Market
Fibers
Asia-Pacific Insoluble Dietary Fibers Market
Fibers
Micro-Fibrillated Cellulose Market
Fibers
Global Electronic Fiberglass Market