
 Global High-Performance Insulation Market | 2026-2036
Global High-Performance Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global High-Performance Insulation Market Foresight
Performance-based maintenance contracts and thermal-monitoring subscriptions is recalibrating how insulation value gets captured across project lifecycles. Owens Corning leverages its manufacturing scale to anchor North American supply chains for aerogel composites. Saint-Gobain competes through vertical integration from raw silica to finished vacuum panels. BASF SE specializes in polyurethane chemistry that differentiates its spray foam systems across data center specifications.
High-performance insulation refers to engineered thermal barriers with lambda values below 0.020 W/m·K, manufactured through vacuum-sealing, nano-gelation, or multi-layer reflective deposition to minimize conductive and radiative heat transfer in demanding temperature-control environments. Aerogel segments command premium positioning due to hydrophobic silica matrices that sustain performance in aerospace envelope applications. Vacuum insulation panels occupy the fastest-expanding margin pool within cold storage retrofits where space constraints dominate design priorities. Spray foam leads volume in new commercial construction across temperate climate zones where installation speed outweighs material cost premiums.
The EPA's Significant New Alternatives Policy and OSHA's Permissible Exposure Limits for isocyanates are tightening formulation standards and installer certification requirements across the United States. The EU F-Gas Regulation and REACH restrict blowing agents and flame retardants, redirecting R&D toward bio-based polyols and mineral wool alternatives. Japan's METI energy efficiency standards for commercial buildings are accelerating specification upgrades in Tokyo's dense retrofit market. Stakeholders must monitor evolving chemical compliance thresholds to preserve market access and anticipate material substitution cycles.
Market Dynamics
EU F-Gas Regulation enforcement is compressing blowing agent options across polyurethane formulations, forcing material substitution cycles that reshape competitive positioning in spray foam and vacuum panel segments.
Growth Catalysts
- Japan METI efficiency standards:Tokyo's commercial retrofit mandates accelerate specification upgrades for mineral wool and aerogel systems in high-rise envelopes.
- Aerospace thermal barrier demand:Lightweight envelope requirements in next-generation aircraft programs pull hydrophobic silica aerogel into primary insulation specifications.
- German energy retrofit mandates:Industrial corridor building codes drive wholesale replacement of legacy insulation in manufacturing facilities and cold storage infrastructure.
Market Restraints
- Petrochemical input volatility:Polyol and isocyanate feedstock costs fluctuate with crude oil indices, compressing margin stability for polyurethane system houses.
- Silica supply concentration:High-purity silica for aerogel production concentrates among limited specialty chemical suppliers, creating bottleneck risk.
- REACH flame retardant restrictions:Halogenated additive bans limit formulation flexibility in construction-grade panels, forcing expensive reformulation cycles.
Strategic Opportunities
- India building efficiency codes:Bureau of Energy Efficiency mandates for commercial HVAC performance create specification entry points for vacuum insulation in premium developments.
- Data center thermal management:Hyperscale facility operators adopt multi-layer reflective deposition systems for precision cooling containment.
- US IRA efficiency incentives:Tax credits for building envelope upgrades redirect retrofit budgets toward high-lambda material categories.
Industry Challenges
- Isocyanate installer certification:OSHA Permissible Exposure Limits require recertification programs that constrain qualified contractor availability across US commercial construction.
- Fire testing timeline compression:UL and ASTM certification cycles for new mineral wool formulations extend product launch schedules by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High-Performance Insulation Market |
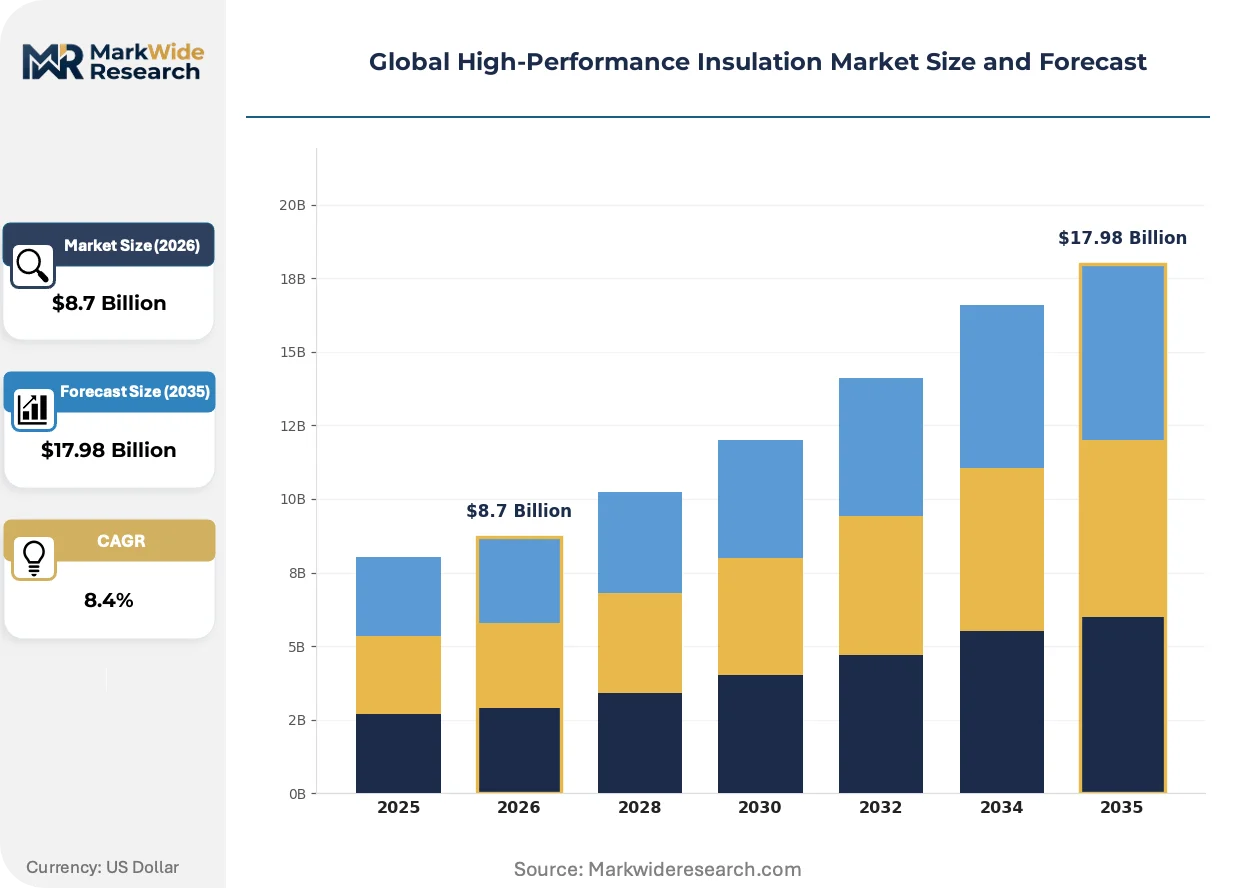
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray Foam, Vacuum Insulation Panels, Aerogel, Reflective Insulation, Fiberglass, Mineral Wool Application: Commercial Buildings, Data Centers, Cold Storage, Refrigeration Units, Aerospace, Marine End User Industry: Construction Firms, Electronics Manufacturers, Food Processing, Aircraft Manufacturers, Shipyards Installation Type: New Construction, Retrofits, Prefabricated Systems, Modular Installations, Onsite Assembly |
| Companies Covered | Owens Corning, Saint-Gobain, BASF SE, Kingspan Group, Rockwool International, 3M, Johns Manville, Armacell International, Knauf Insulation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High-Performance Insulation Market Shifts & Advancements
Material science advances and regulatory chemistry constraints are converging to redefine how thermal performance gets engineered, manufactured, and specified across temperature-control applications.
Aerogel composites are expanding into cold chain logistics infrastructure where space-constrained reefers and pharmaceutical transport containers demand maximum R-value per inch. Food distributors and vaccine logistics operators in Germany and the Netherlands specify silica-based blankets for trailer retrofits. The technology is expanding into adjacent mobility applications including electric vehicle battery thermal management.
REACH restrictions on hydrofluorocarbon blowing agents are eliminating incumbent chemistries from European polyurethane production. Formulators pivot toward bio-based polyols and water-blown systems that sacrifice some lambda performance for compliance certainty. Cold storage OEMs in France and Belgium absorb higher material costs while awaiting next-generation low-GWP alternatives from chemical suppliers.
Performance-based maintenance contracts now bundle thermal monitoring subscriptions with initial insulation installation. Data center operators in Singapore and Sydney subscribe to continuous envelope performance verification rather than accepting static warranty terms. Facility managers reallocate capital from upfront material procurement to lifecycle thermal assurance, compressing traditional distribution margins on commodity insulation categories.
Global High-Performance Insulation Market Segmentation
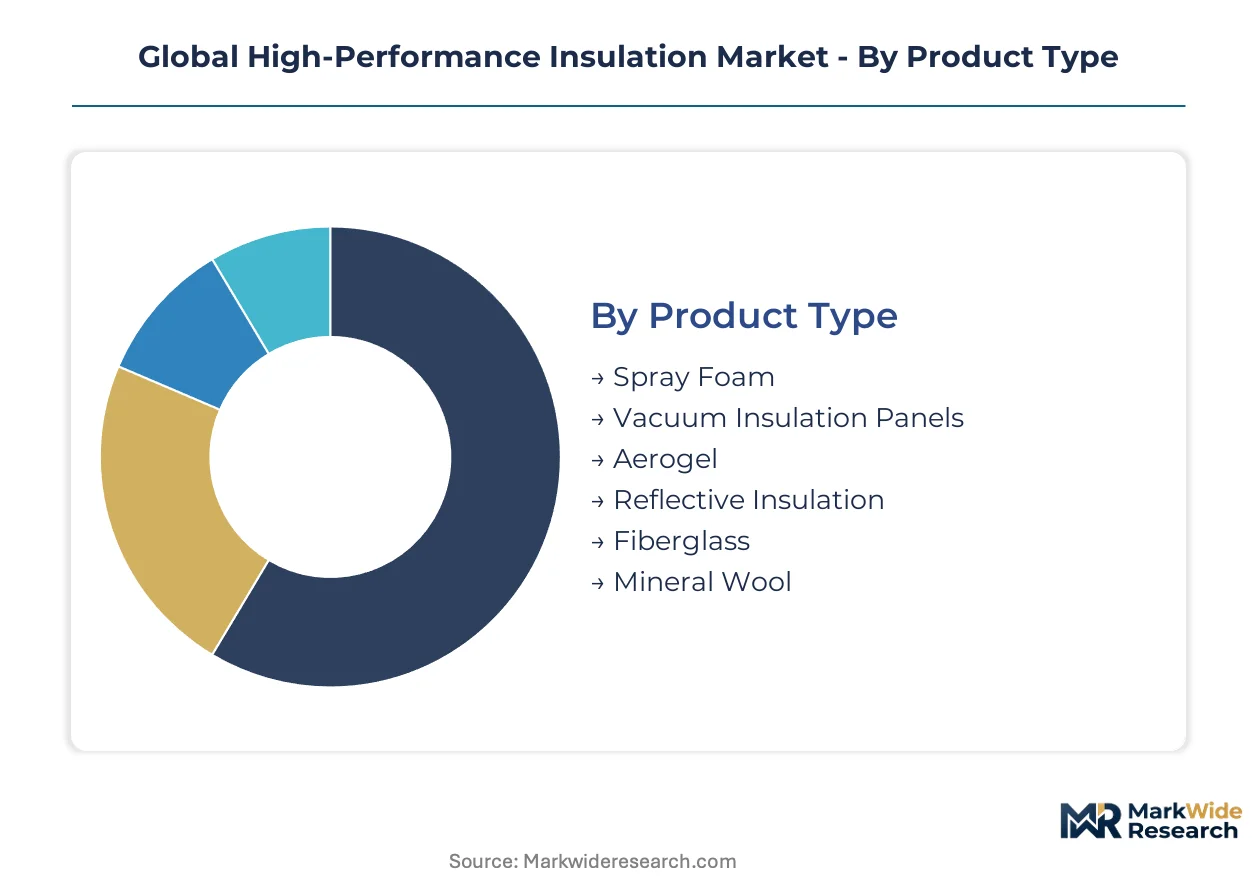
Material composition and installation method determine thermal performance thresholds, regulatory compliance pathways, and lifecycle cost structures across high-performance insulation procurement. Specification engineers weight lambda values against space constraints, fire ratings, and chemical exposure limits when mapping segments to project requirements.
Product Type:
Specialty chemical suppliers concentrate feedstock access for nano-structured materials, while commodity polymer houses dominate blown foam production.
- Spray Foam:Polyurethane systems combine polyols with isocyanate catalysts to form closed-cell barriers with lambda values near 0.020 W/m·K. Commercial construction in the United States absorbs volume for speed-critical envelope sealing, though OSHA exposure limits constrain qualified installer pools.
- Vacuum Insulation Panels:Fumed silica cores sealed in metallized polymer films achieve lambda values below 0.007 W/m·K. Cold storage retrofits in Germany's industrial corridor specify these panels where floor space constraints dominate design priorities.
- Aerogel:Hydrophobic silica matrices sustain performance across aerospace thermal barriers and electric vehicle battery enclosures.
- Reflective Insulation:Multi-layer aluminum deposition systems serve data center precision cooling containment in Singapore and Sydney.
- Fiberglass:Melt-spun glass wool dominates volume in temperate climate new construction where cost minimization outweighs space efficiency.
- Mineral Wool:Stone or slag fibers provide fire resistance for commercial high-rises under Japan METI efficiency standards.
Spray foam absorbs the bulk of installed capacity; vacuum insulation panels are expanding most quickly.
Application:
End-use thermal requirements range from steady-state envelope performance to transient cryogenic protection, reshaping material selection criteria.
- Commercial Buildings:Multi-story envelopes specify mineral wool and aerogel composites to satisfy energy retrofit mandates. Tokyo's dense urban fabric accelerates specification upgrades under METI standards.
- Data Centers:Hyperscale operators deploy reflective insulation and vacuum panels for precision cooling containment zones. Thermal monitoring subscriptions now bundle with installation contracts in Singapore facilities.
- Cold Storage:Space-constrained reefers and pharmaceutical transport containers in Germany and the Netherlands specify aerogel blankets for trailer retrofits.
- Refrigeration Units:OEMs in France and Belgium absorb higher material costs while awaiting REACH-compliant low-GWP blowing agent alternatives.
- Aerospace:Next-generation aircraft programs pull hydrophobic silica aerogel into primary thermal barrier specifications.
- Marine:Shipbuilders specify fire-rated mineral wool for engine compartment and accommodation block separation.
Commercial buildings absorb the bulk of installed capacity; data centers are climbing the fastest.
End User Industry:
Procurement sophistication varies from commodity volume purchasing to performance-based lifecycle contracting.
- Construction Firms:General contractors balance installation speed against material cost premiums across temperate climate zones.
- Electronics Manufacturers:Semiconductor fabs specify ultra-low lambda materials for cleanroom thermal stability.
- Food Processing:Cold chain operators prioritize R-value per inch for refrigerated transport fleet efficiency.
- Aircraft Manufacturers:Airframers demand lightweight envelope solutions with hydrophobic durability.
- Shipyards:Naval and commercial builders specify fire-rated systems for SOLAS compliance.
Construction firms absorb the bulk of installed capacity; aircraft manufacturers are gaining share fastest.
Installation Type:
Project delivery method determines labor skill requirements, quality assurance protocols, and warranty structure terms.
- New Construction:Design-build teams integrate spray foam and fiberglass during framing phases for speed optimization.
- Retrofits:Building envelope upgrades redirect budgets toward high-lambda categories under US IRA efficiency incentives.
- Prefabricated Systems:Panelized wall assemblies factory-integrate vacuum insulation for quality control.
- Modular Installations:Skid-mounted data center units ship with pre-installed reflective insulation layers.
- Onsite Assembly:Complex aerogel applications require specialized contractor certification for aerospace and marine programs.
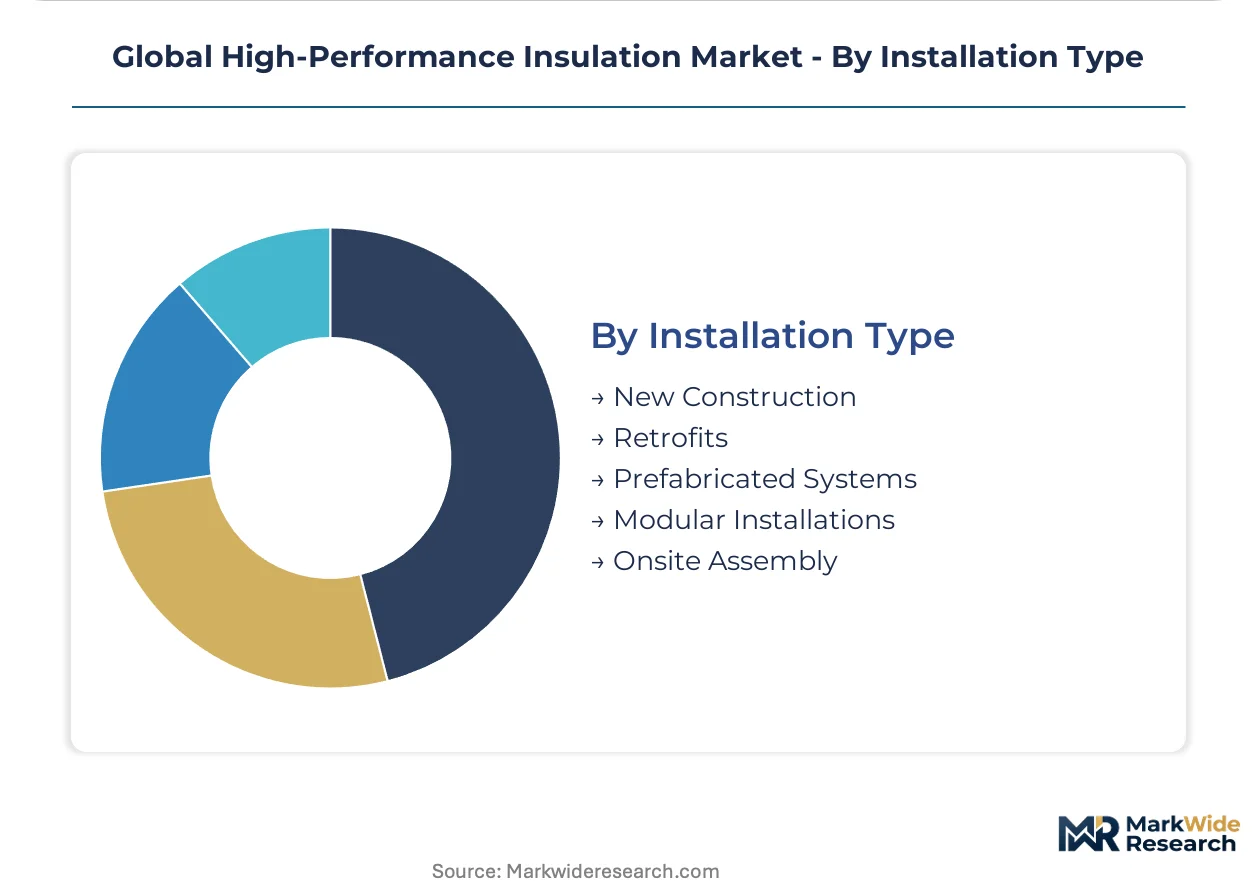
New construction absorbs the bulk of installed capacity; retrofits are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing scale concentrates in Germany and the United States while specification demand clusters in Japan's dense urban corridors. Raw material access and retrofit incentive structures determine regional competitive positioning across the forecast window.
United States
Data center construction in Northern Virginia and Phoenix drives specification upgrades for multi-layer reflective systems. OSHA Permissible Exposure Limits constrain qualified installer pools for polyurethane applications. Tax credits under the Inflation Reduction Act redirect commercial retrofit budgets toward high-lambda material categories in Texas and California industrial zones.
Germany
Energy retrofit mandates across the industrial corridor drive wholesale replacement of legacy insulation in manufacturing facilities and cold storage infrastructure. EU F-Gas Regulation enforcement compresses blowing agent options for polyurethane formulations. Cologne and Hamburg cold storage operators specify vacuum insulation panels where floor space constraints dominate design priorities.
Japan
Tokyo's dense commercial retrofit market accelerates specification upgrades for mineral wool and aerogel systems in high-rise envelopes. METI energy efficiency standards mandate thermal performance thresholds for commercial buildings. Osaka and Nagoya facility managers subscribe to thermal monitoring services bundled with envelope installations.
China
Hyperscale data center operators in the Yangtze River Delta adopt precision cooling containment systems. National dual carbon goals pressure industrial facility operators toward envelope efficiency upgrades. Beijing-Tianjin-Hebei corridor construction firms balance installation speed against material cost premiums in temperate climate zones.
India
Bureau of Energy Efficiency mandates for commercial HVAC performance create specification entry points for vacuum insulation in premium developments. CDSCO and BIS compliance frameworks reshape material import and testing protocols. Mumbai and Bangalore developers specify high-performance barriers in Grade A office construction.
Global High-Performance Insulation Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct value capture models. Specialty chemical suppliers concentrate feedstock access for nano-structured materials while commodity polymer houses dominate blown foam production. Three archetypes define competitive positioning: integrated material-science conglomerates controlling raw silica to finished panel production; regional system houses optimizing installation speed and contractor relationships; and technology licensors monetizing formulation IP across licensed manufacturing networks. Capacity expansion and backward integration into captive silica supply represent the dominant competitive moves.
Within the integrated-materials tier, Owens Corning and Saint-Gobain exemplify divergent scale strategies. Owens Corning leverages North American manufacturing footprint to anchor regional aerogel composite supply chains. Saint-Gobain occupies a position emphasizing upstream control over raw silica through finished vacuum panel production. BASF SE represents the chemistry-specialist archetype, differentiating through polyurethane formulation expertise rather than vertical manufacturing scope.
| Leading Market Players |
|---|
| Owens Corning |
| Saint-Gobain |
| BASF SE |
| Kingspan Group |
| Rockwool International |
| 3M |
| Johns Manville |
| Armacell International |
| Knauf Insulation |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation enforcement gates both qualified supply and premium-tier pricing access for polyurethane system houses, as REACH-compliant blowing agent alternatives command material cost premiums that only backward-integrated producers can absorb without margin erosion.
Pricing Analysis
Margin tightening in spray foam reflects petrochemical input volatility, as polyol and isocyanate feedstock costs fluctuate with crude oil indices. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade aerogel specifications from construction-grade mineral wool, with certification tier and volume scale as primary differentiation drivers. Cost-down pressure on vacuum insulation panels accelerates because cold storage OEMs in France and Belgium absorb higher material costs while awaiting next-generation low-GWP alternatives. General contractors in temperate climate zones exhibit highest price sensitivity, while data center operators prioritize thermal performance over unit economics.
Supply Chain Analysis
Domestic-content mandates in India's Bureau of Energy Efficiency compliance frameworks reshape sourcing for premium commercial developments in Mumbai and Bangalore. High-purity silica concentrates among limited specialty chemical suppliers in Germany and the United States, while polyurethane system houses draw from petrochemical feedstock networks anchored in the US Gulf Coast and Rotterdam. Single-source vulnerability in aerogel precursor supply creates bottleneck risk for aerospace and electric vehicle battery applications. Distribution runs through regional system houses that optimize contractor relationships and installation speed.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around REACH and EPA chemistry constraints that force smaller formulators into expensive reformulation cycles or exit. Regulatory compliance thresholds serve as the primary filter eliminating sub-scale competitors.
For Market Incumbents: Anchor North American manufacturing footprint to secure aerogel composite supply chains against silica supply concentration. Invest in captive silica production or long-term offtake agreements with specialty chemical suppliers to defend margin position against feedstock volatility. Pursue UL and ASTM certification for mineral wool formulations ahead of fire testing timeline compression. For New Entrants and Emerging Players: Capture specification entry points in India's Bureau of Energy Efficiency mandates for commercial HVAC performance, where vacuum insulation penetration remains nascent in Grade A office construction. Target data center thermal management in Singapore and Sydney through performance-based maintenance contracts bundled with thermal monitoring subscriptions. Lead with subscription-based thermal assurance rather than commodity material procurement. For Investors and Strategic Acquirers: EU F-Gas Regulation enforcement accelerating material substitution cycles is the leading indicator that backward-integrated producers will capture disproportionate value across the projection horizon. Focus acquisition screening on specialty chemical suppliers with captive silica access and formulation IP for low-GWP blowing agents. Watch for OSHA isocyanate exposure limit tightening as signal for contractor availability constraints that favor scaled system houses.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Supply | Captive high-purity silica production insulates Owens Corning and Saint-Gobain from feedstock bottleneck risk. |
| Performance-Based Maintenance Contracts | Thermal monitoring subscriptions redirect data center procurement from upfront material to lifecycle assurance. |
| REACH-Compliant Formulation Pivot | Bio-based polyol and water-blown system development preserves EU market access for polyurethane houses. |
| Data Center Specification Capture | Multi-layer reflective deposition systems penetrate hyperscale cooling containment in Northern Virginia and Phoenix. |
| Installer Certification Programs | OSHA-compliant isocyanate training expands qualified contractor pools for US commercial construction. |
Research Methodology
Document review covered customs and trade data, SEC filings from insulation system houses, EU F-Gas Regulation enforcement records, and METI efficiency standard filings, complemented by interviews with plant managers at polyurethane formulation facilities, procurement leads at cold storage OEMs, distribution channel partners in Germany's industrial corridor, and technical R&D directors at aerogel composite producers. Bottom-up volume modeling triangulated against top-down value estimates derived from specification-grade pricing benchmarks.
Historical production and import data cross-referenced against panel input from specification engineers and facility managers informed the analytical framework across the modeling period. Segmentation dimensions included material composition, installation method, end-use application, and regional regulatory cluster. CAGRs derived from slope analysis of fitted trend lines applied to volume and value trajectories, with specific adjustment for EU blowing agent phase-out schedules and US IRA incentive uptake curves.
The model holds under stable petrochemical feedstock pricing and gradual regulatory enforcement timelines; deviation in crude oil volatility or accelerated REACH restriction timelines would shift volume trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
Protective Building Materials Market
Insulation Materials
Mineral Wool Insulation Market
Insulation Materials
Italy Industrial Insulation Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Industrial Insulation Market
Insulation Materials
Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Flame-Retardant Foams and Insulation Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
Expanded Perlite Market
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
Insulation Products Market
Insulation Materials
Global Glass Insulation Market
Insulation Materials
Thermal Tapes Market
Insulation Materials
France Foam Insulation Market