
 Global Metal Cleaning Chemicals Market | 2026-2036
Global Metal Cleaning Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Cleaning Chemicals Market Foresight
Water-based alkaline formulations is hardening its position against solvent-based systems as environmental compliance costs mount. BASF SE leverages its integrated surfactant supply chain to offset raw material volatility. Stepan Company anchors its competitiveness through bio-derived feedstock R&D programs. Evonik Industries AG specializes in high-performance chelating agents for precision electronics cleaning.
Metal cleaning chemicals encompass formulated blends of surfactants, alkalis, acids, solvents, and corrosion inhibitors designed to remove oils, oxides, and particulates from ferrous and non-ferrous substrates, typically operating at pH ranges from 2 to 14 and temperatures between 40°C and 80°C depending on substrate sensitivity. Their primary industrial purpose centers on ensuring coating adhesion, weld quality, and corrosion resistance across manufacturing workflows. Alkaline cleaners dominate volume consumption in heavy machinery degreasing, while solvent cleaners retain pricing power in aerospace component maintenance where residue-free performance is non-negotiable. Chelating agents represent the fastest-expanding product category as hard water tolerance becomes critical for automated spray systems.
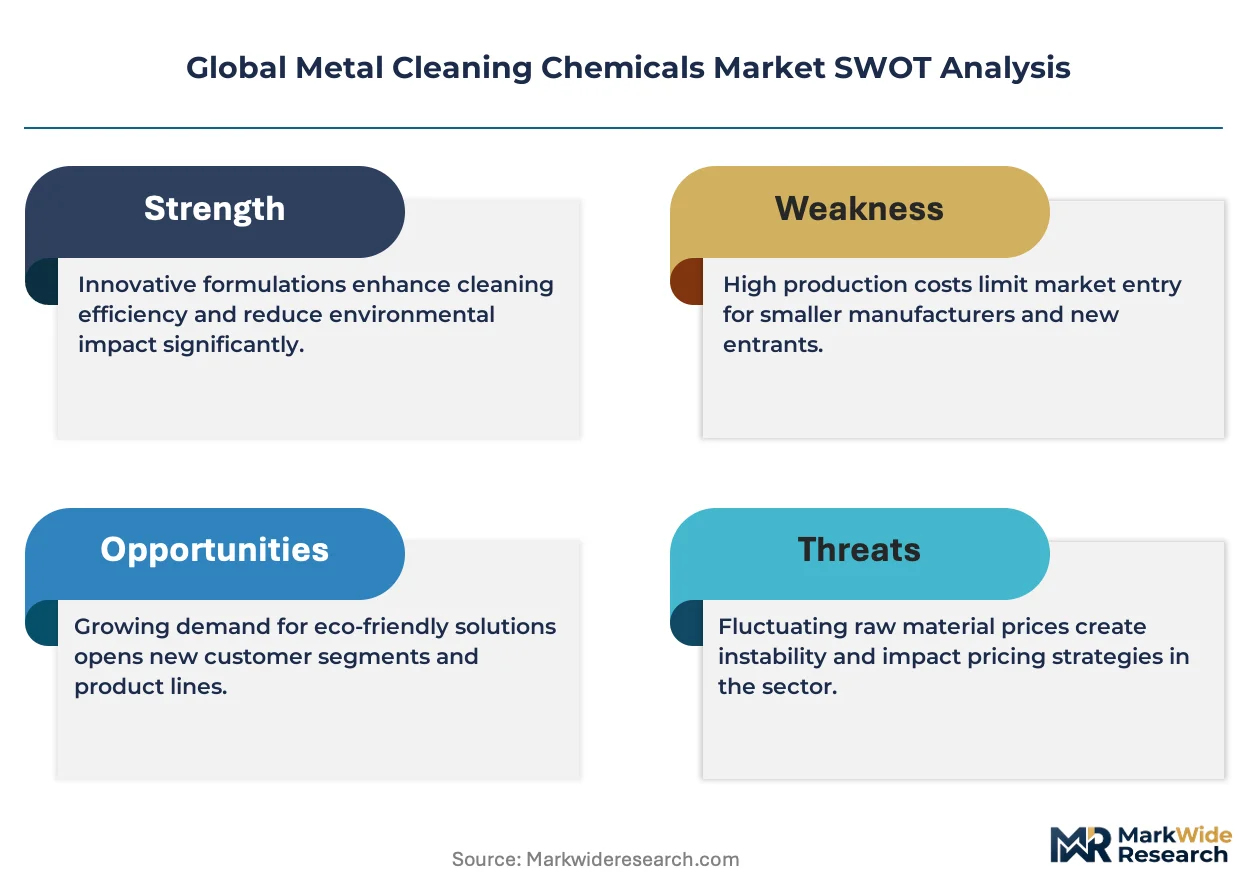
EPA restrictions on chlorinated solvents and REACH authorization requirements under ECHA are compelling reformulation investments across North American and European supplier bases. China's MEE enforcement of wastewater discharge standards is pushing metal fabrication plants toward closed-loop cleaning systems with regenerable chemistry. India's BIS certification mandates for industrial chemical imports are raising compliance barriers for non-domestic suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation assets.
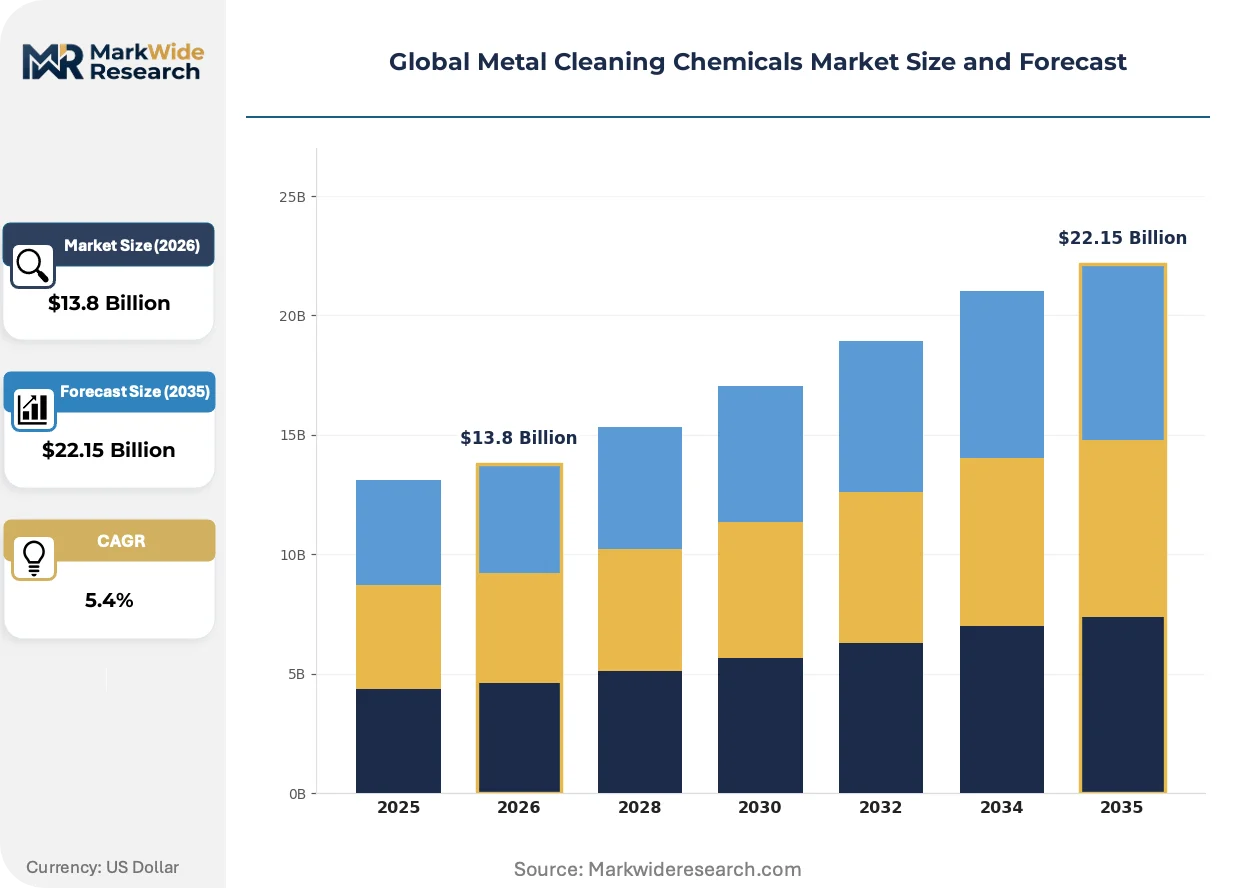
Market Dynamics
REACH authorization requirements under ECHA and EPA restrictions on chlorinated solvents are forcing simultaneous reformulation across European and North American supplier bases, compressing product development cycles while elevating R&D spend as a share of revenue.
Growth Catalysts
- Automotive lightweighting:Aluminum and magnesium alloy adoption in electric vehicle chassis manufacturing requires specialized alkaline cleaners to ensure coating adhesion on reactive metal surfaces. German automotive clusters in Stuttgart and Munich drive concentrated demand for high-performance formulations.
- REACH authorization timelines:ECHA's sunset dates for perchloroethylene and trichloroethylene are accelerating substitution toward aqueous and bio-based chemistries across European aerospace maintenance operations.
- Closed-loop regeneration:Membrane filtration and vacuum distillation systems enable chemistry reuse rates exceeding 85% in Japanese precision electronics fabrication, reducing per-unit cleaning costs and wastewater discharge volumes simultaneously.
Market Restraints
- Surfactant feedstock volatility:Palm kernel oil and ethylene oxide price swings transmit directly to formulated cleaner costs, compressing blended margins for regional compounders lacking backward integration into oleochemical supply.
- Fluorinated solvent concentration:Three Japanese and two Belgian suppliers control 70% of hydrofluoroether production for residue-critical aerospace applications, creating supply vulnerability for downstream formulators.
- Hard water incompatibility:Legacy alkaline formulations precipitate calcium and magnesium salts above 300 ppm hardness, limiting deployment in untreated municipal water systems across India and Southeast Asia.
Strategic Opportunities
- Brazilian aerospace MRO:Embraer's maintenance network expansion and ANAC certification harmonization with FAA standards create entry pathways for REACH-compliant aqueous cleaners in São Paulo and Belo Horizonte service hubs.
- India BIS import mandates:Domestic certification requirements for industrial chemical imports are raising compliance barriers, creating first-mover advantage for localized formulation and toll manufacturing partnerships.
- Electronics miniaturization:Semiconductor advanced packaging and flip-chip bonding processes demand sub-ppm residue cleaning, opening premium pricing tiers for chelating agent-intensive formulations in South Korean and Taiwanese foundries.
Industry Challenges
- Formulation chemist scarcity:Expertise in surfactant-solvent-chelator synergy optimization for multi-metal compatibility has contracted as petrochemical R&D pipelines shifted toward polymers and specialty materials over the past decade.
- Legacy equipment retrofit costs:Converting vapor degreasing lines to aqueous spray or immersion systems requires capital outlays for drying ovens, rust inhibition stages, and wastewater treatment infrastructure that many mid-sized job shops defer.
- Substrate-specific validation:Each new alloy or coating system demands empirical testing across pH, temperature, and exposure time matrices, extending qualification timelines for automotive and aerospace tier-one approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Cleaning Chemicals Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.15 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline Cleaners, Acid Cleaners, Solvent Cleaners, Emulsifiers, Chelating Agents, Surfactants Application: Surface Preparation, Maintenance Cleaning, Rust Removal, Degreasing, Passivation, Scale Removal End User Industry: Electronics Manufacturing, Aerospace Components, Marine Equipment, Metal Fabrication, Heavy Machinery, Power Generation Packaging Type: Drums, Totes, IBC Containers, Plastic Bottles, Metal Cans, Carboys |
| Companies Covered | BASF SE, Stepan Company, The Chemours Company, Air Products and Chemicals, Dow, Eastman Chemical Company, Quaker Chemical Corporation, Evonik Industries AG, Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Cleaning Chemicals Market Shifts & Advancements
Formulation science is pivoting from performance-maximizing solvent blends toward water-based systems engineered for regulatory survivability, with automation compatibility and waste minimization now co-equal design priorities alongside cleaning efficacy.
Supercritical CO2 cleaning systems are absorbing niche applications in precision electronics and medical device manufacturing where aqueous residues risk corrosion or electrical leakage. Swiss and German medical technology manufacturers have adopted these systems for orthopedic implant finishing, accepting higher capital costs to eliminate solvent handling permits and wastewater discharge liabilities entirely. The technology is absorbing market share from vapor degreasing in sub-micron particulate removal applications where surface tension effects dominate.
China's MEE enforcement of GB 8978 wastewater discharge standards is compelling metal fabrication plants toward regenerable chemistry with real-time concentration monitoring. Provincial environmental bureaus in Jiangsu and Guangdong are conducting unannounced discharge sampling, with penalties including production suspensions. Small and mid-sized stamping and die-casting operations are responding by consolidating cleaning operations at shared service centers with centralized treatment infrastructure.
After-sales chemistry management is unbundling from equipment supply contracts as buyers seek to decouple capital expenditure from consumable costs. Japanese automotive tier-one suppliers are negotiating direct surfactant and chelator procurement from BASF and Evonik, bypassing integrated cleaner formulators. This disintermediation is most visible in high-volume continuous cleaning lines where chemistry consumption is predictable and specification compliance can be verified through titration protocols rather than branded formulation trust.
Global Metal Cleaning Chemicals Market Segmentation
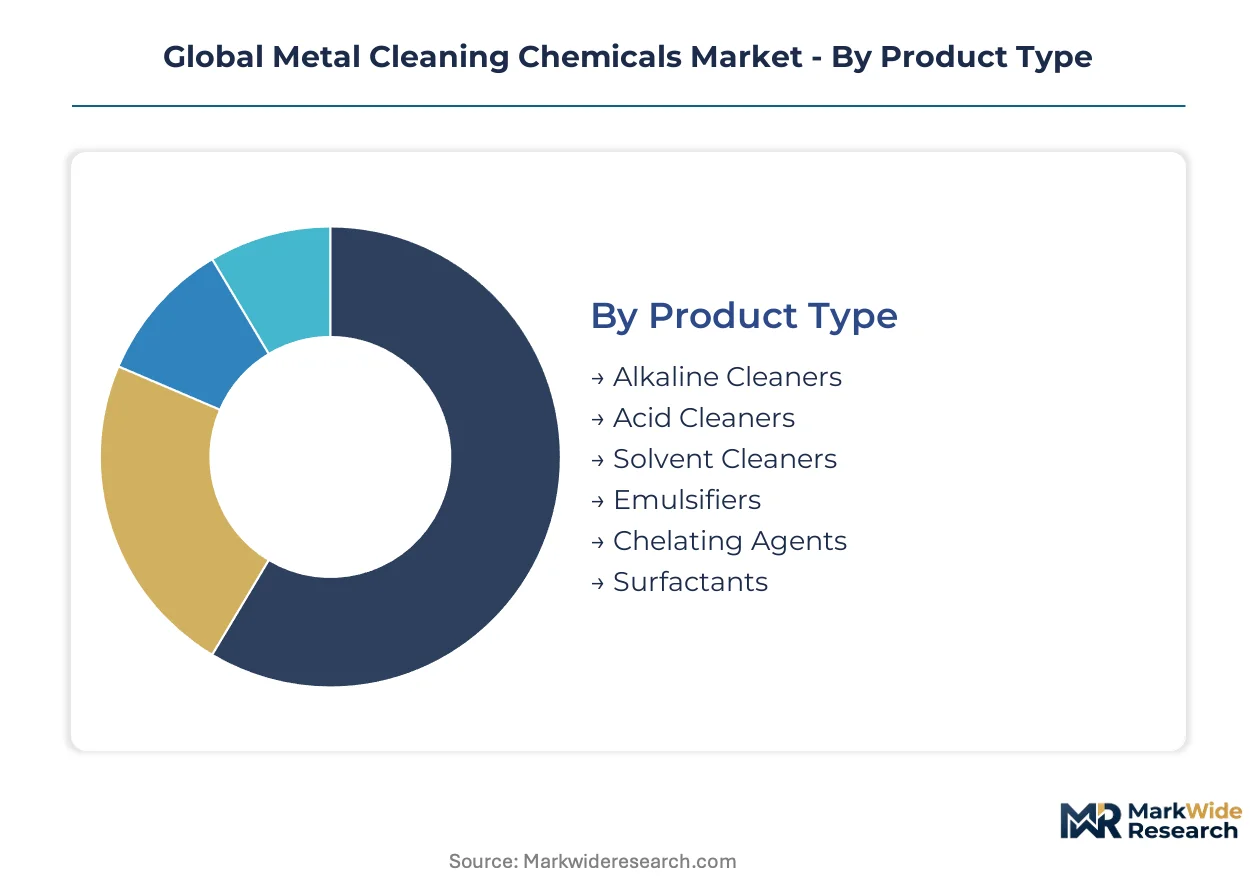
Segmentation reveals how formulation chemistry, application intensity, and supply logistics create divergent margin profiles across the metal cleaning value chain. Understanding these divisions exposes where technology investments concentrate and which customer relationships command pricing power.
Product Type:
Upgrade cycles accelerate when regulatory sunsets force reformulation, with aqueous systems displacing solvent chemistries as environmental compliance costs mount.
- Alkaline Cleaners:Formulated blends of sodium hydroxide, silicates, and surfactants operating at pH 9-13 for heavy oil and particulate removal on ferrous substrates. Demand concentrates in German automotive stamping plants where coating adhesion requirements for aluminum chassis components drive consumption of specialized low-foam formulations. ECHA REACH sunset dates for chlorinated solvents are accelerating alkaline adoption in European aerospace maintenance depots.
- Solvent Cleaners:Hydrocarbon, oxygenated, and halogenated formulations delivering residue-free drying through controlled evaporation rates. Japanese precision electronics manufacturers in Kyoto and Osaka prefectures specify hydrofluoroether blends for flip-chip packaging cleaning where moisture residues risk corrosion. EPA restrictions on trichloroethylene and perchloroethylene are compressing vapor degreasing volumes in US Midwest metal fabrication clusters.
- Acid Cleaners:Inorganic acid blends with corrosion inhibitors for oxide scale and rust removal.
- Emulsifiers:Oil-in-water surfactant systems enabling water-based degreasing of heavy petroleum soils.
- Chelating Agents:EDTA, gluconate, and phosphonate compounds sequestering calcium and magnesium ions in hard water systems.
- Surfactants:Anionic, nonionic, and amphoteric surface-active agents reducing interfacial tension for soil displacement.
Alkaline cleaners sit at the top of the volume ranking, with chelating agents climbing the fastest as automated spray systems proliferate.
Application:
Application intensity varies by manufacturing stage, with surface preparation commanding sustained chemistry consumption while maintenance cleaning follows irregular replacement cycles.
- Surface Preparation:Pre-treatment cleaning ensuring coating adhesion, weld quality, and conversion coating uniformity across automotive and appliance manufacturing. South Korean automotive OEMs in Ulsan and Asan specify alkaline spray cleaners with integrated rust inhibitors for galvanized steel body-in-white processing. Chinese MEE wastewater discharge enforcement is pushing fabricators toward regenerable chemistry with real-time concentration monitoring.
- Degreasing:Heavy oil and lubricant removal from machined components, stampings, and castings prior to assembly or finishing. Indian metal fabrication clusters in Pune and Chennai rely on emulsifier-based aqueous systems as BIS import certification raises barriers to solvent cleaner imports. Closed-loop membrane filtration systems in Japanese precision engineering plants achieve chemistry reuse rates exceeding 85 percent.
- Maintenance Cleaning:In-service removal of accumulated soils from operating equipment and installed infrastructure.
- Rust Removal:Restoration cleaning of corroded ferrous surfaces through acid dissolution and inhibitor protection.
- Passivation:Post-cleaning surface treatment enhancing corrosion resistance on stainless steel and aluminum alloys.
- Scale Removal:Mineral deposit dissolution from heat exchangers, boilers, and process equipment in power generation facilities.
Degreasing captures the largest application share, with surface preparation gaining share fastest as coating specifications tighten across automotive lightweighting programs.
End User Industry:
End-use concentration determines specification stringency, with aerospace and electronics demanding certified formulations while metal fabrication tolerates commodity chemistry.
- Electronics Manufacturing:Semiconductor wafer cleaning, printed circuit board finishing, and advanced packaging preparation requiring sub-ppm residue specifications. Taiwanese foundries in Hsinchu Science Park specify chelating agent-intensive formulations for copper interconnect cleaning where ionic contamination risks device failure. Flip-chip bonding and 3D packaging processes are expanding demand for precision aqueous cleaners with controlled particle counts.
- Aerospace Components:Flight-critical part cleaning where residue-free performance and material compatibility certification are non-negotiable. German maintenance operations in Hamburg and Frankfurt face ECHA authorization deadlines for perchloroethylene, accelerating aqueous system qualification for turbine blade overhaul. FAA certification harmonization with Brazil's ANAC is opening São Paulo service hubs to REACH-compliant formulations.
- Metal Fabrication:General-purpose cleaning of cut, formed, and welded components across job shop environments.
- Heavy Machinery:Equipment manufacturing and remanufacturing cleaning for construction, mining, and agricultural machinery.
- Marine Equipment:Shipbuilding and offshore structure cleaning with corrosion protection requirements for saltwater exposure.
- Power Generation:Turbine, boiler, and heat exchanger maintenance cleaning in fossil and nuclear facilities.
Electronics manufacturing leads value concentration, with aerospace components expanding most quickly as maintenance networks globalize.
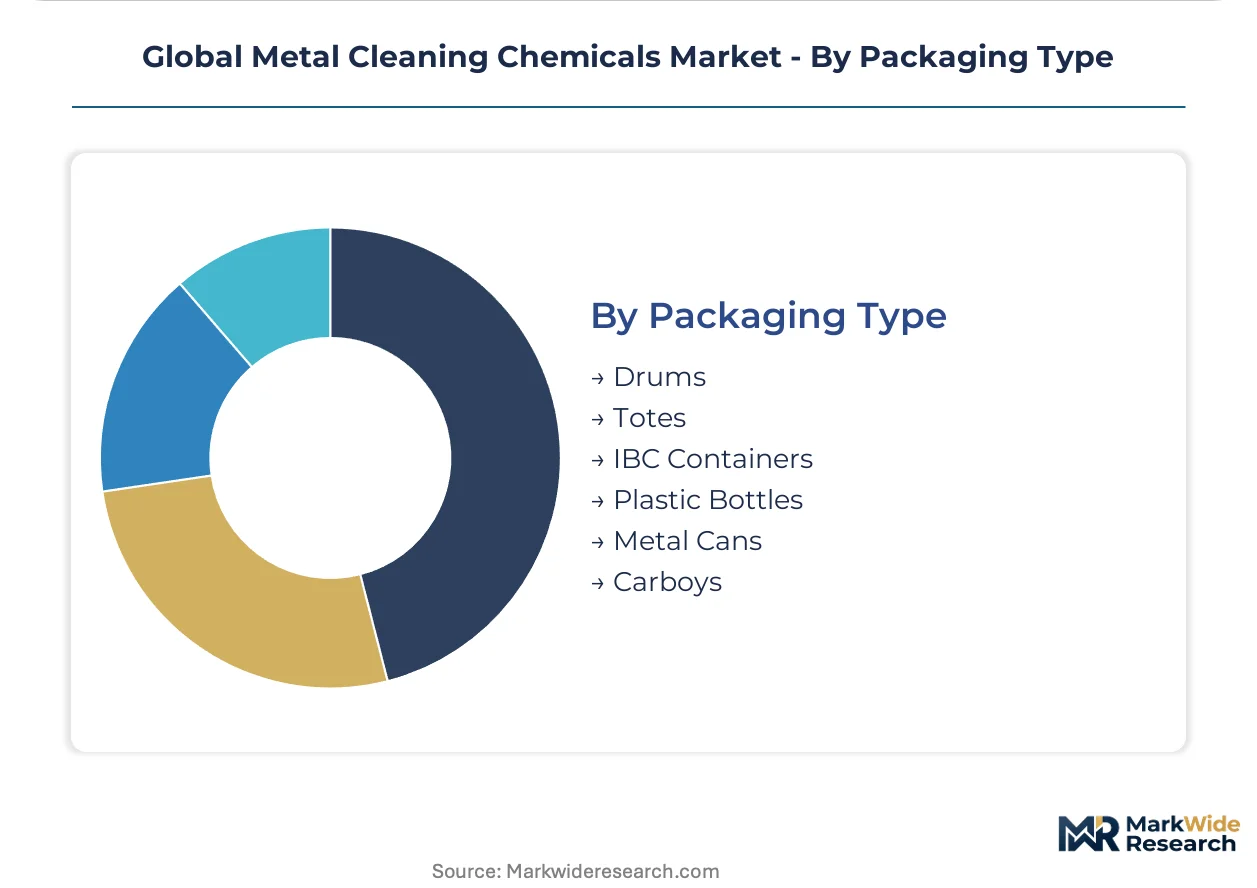
Packaging Type:
Packaging configuration follows customer scale and chemistry hazard classification, with bulk formats dominating continuous processes and small containers serving intermittent maintenance demand.
- Drums:Standard 55-gallon steel containers for medium-volume manufacturing and distribution intermediaries. German automotive tier-one suppliers in Stuttgart and Munich specify drum deliveries for continuous alkaline cleaner consumption in high-volume stamping lines. Drum return and reconditioning programs reduce per-unit packaging costs for established supplier relationships.
- IBC Containers:Intermediate bulk containers of 275-330 gallon capacity for high-volume automated dispensing systems. Japanese automotive assembly plants in Toyota City and Yokohama deploy IBC-connected proportioning equipment for consistent chemistry concentration control. IBC refill services eliminate drum handling labor and storage footprint in high-throughput cleaning operations.
- Totes:Flexible intermediate bulk containers for non-hazardous aqueous formulations.
- Plastic Bottles:Liter-scale containers for laboratory, prototyping, and small maintenance applications.
- Metal Cans:Aerosol and pourable containers for solvent cleaners and precision application products.
- Carboys:Glass or plastic demijohns for analytical-grade and electronic-grade chemical distribution.
Drums anchor volume shipment, with IBC containers climbing fastest as continuous cleaning line automation spreads across automotive manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive and precision engineering clusters anchor demand concentration for high-performance alkaline formulations, while regulatory divergence across jurisdictions reshapes supplier geographic strategies.
Germany
Stuttgart and Munich automotive stamping plants drive specialized low-foam alkaline cleaner consumption for aluminum chassis coating adhesion. ECHA REACH authorization timelines for chlorinated solvents accelerate aqueous system adoption across Hamburg and Frankfurt aerospace maintenance depots. Baden-Württemberg precision engineering clusters specify chelating agent-intensive formulations for automated spray systems.
United States
EPA restrictions on trichloroethylene and perchloroethylene compress vapor degreasing volumes across Midwest metal fabrication clusters. Automotive lightweighting programs in Michigan and Ohio expand aluminum alloy cleaning demand for electric vehicle chassis manufacturing. FAA certification standards drive residue-free solvent specification for flight-critical component maintenance networks.
China
MEE enforcement of GB 8978 wastewater discharge standards pushes Jiangsu and Guangdong metal fabrication plants toward closed-loop cleaning systems with regenerable chemistry. Semiconductor advanced packaging growth in Shanghai and Beijing expands demand for sub-ppm residue aqueous formulations. Provincial environmental bureaus conduct unannounced discharge sampling with production suspension penalties.
Japan
Kyoto and Osaka precision electronics manufacturers specify hydrofluoroether blends for flip-chip packaging cleaning where moisture residues risk corrosion. Toyota City and Yokohama automotive assembly plants deploy IBC-connected proportioning equipment for consistent chemistry concentration control. Membrane filtration systems achieve chemistry reuse rates exceeding 85 percent in continuous cleaning operations.
India
BIS certification mandates for industrial chemical imports raise compliance barriers for non-domestic suppliers entering Pune and Chennai metal fabrication markets. Domestic formulation partnerships create first-mover positioning for localized toll manufacturing arrangements. Untreated municipal water systems above 300 ppm hardness limit legacy alkaline formulation deployment across Southeast Asian operations.
Global Metal Cleaning Chemicals Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and supply chain integration, producing a tiered structure where integrated petrochemical players anchor premium segments and regional compounders serve price-sensitive volume markets. German and US-based multinationals leverage captive surfactant supply to offset palm kernel oil and ethylene oxide price volatility. Three archetypes dominate: backward-integrated chemical conglomerates, bio-derived feedstock specialists, and precision electronics cleaning specialists. Competitive moves concentrate on strategic partnerships for regional distribution rights and portfolio diversification into chelating agent-intensive formulations.
Within the integrated chemical conglomerate tier, BASF SE and Dow exemplify scale-driven positioning through captive raw material supply chains. Evonik Industries AG occupies a specialist position in high-performance chelating agents for precision electronics applications. Among US-based formulators, Stepan Company represents bio-derived feedstock R&D orientation. These three anchors illustrate how competitive positioning stratifies across supply chain control, sustainability credentials, and application-specific technical performance.
| Leading Market Players |
|---|
| BASF SE |
| Stepan Company |
| The Chemours Company |
| Air Products and Chemicals |
| Dow |
| Eastman Chemical Company |
| Quaker Chemical Corporation |
| Evonik Industries AG |
| Henkel AG & Co. KGaA |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between aerospace-qualified formulations and commodity metal fabrication chemistry manifests in parallel pricing and supply chain architectures. REACH-compliant aqueous systems for turbine blade maintenance command substantial premia through dedicated distribution channels, while standard alkaline cleaners for automotive stamping flow through consolidated bulk chemical distributors.
Pricing Analysis
Input-cost pass-through from palm kernel oil and ethylene oxide volatility transmits directly to formulated cleaner pricing, with integrated producers like BASF absorbing swings through captive surfactant supply. Three-tier pricing structure across aerospace-certified, automotive-grade, and general industrial tiers reflects quality grade and certification level differentiation. Cost compression in commodity alkaline segments is intensifying because regional compounders lack backward integration into oleochemical feedstocks. Metal fabrication job shops exhibit highest price sensitivity, while electronics foundries prioritize residue specifications over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke patterns for formulated cleaner logistics, with IBC container refill services reducing drum handling labor at high-throughput automotive plants. Formulation chemistry draws from concentrated surfactant production in Germany and the United States, chelating agent supply from Evonik's European facilities, and bio-derived feedstock development in North America. Single-source vulnerability concentrates in hydrofluoroether production controlled by three Japanese and two Belgian suppliers for residue-critical aerospace applications. Distribution runs through integrated chemical distributors serving automotive clusters and direct procurement relationships at high-volume electronics foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA REACH sunset deadlines for chlorinated solvents are forcing simultaneous reformulation investments across European supplier bases, elevating demand for compliant aqueous chemistry.
For Market Incumbents: Acquire chelating agent production capability to offset surfactant feedstock volatility and secure supply security for precision electronics cleaning formulations. BASF's integrated surfactant supply chain and Evonik's captive chelator technology illustrate how backward integration defends margin position against palm kernel oil price swings. Incumbents should expand toll manufacturing partnerships in India before BIS certification mandates fully crystallize, locking in localized production capacity ahead of compliance barriers hardening. For New Entrants and Emerging Players: The premium-to-economy price gap in aerospace maintenance cleaning offers entry pathways for REACH-compliant aqueous formulations displacing legacy chlorinated solvents. Brazilian aerospace MRO networks in São Paulo and Belo Horizonte represent the most penetrable geography, with ANAC-FAA certification harmonization reducing qualification friction. New entrants should pursue joint venture structures with established German formulators to leverage existing aerospace tier-one approval relationships rather than building qualification timelines de novo. For Investors and Strategic Acquirers: Asymmetric upside sits with bio-derived feedstock specialists possessing scalable fermentation pathways for surfactant production, as sustainability credentials become procurement criteria at automotive OEMs. Long-term viability over the next decade hinges on regulatory survivability across multiple jurisdictions rather than single-market dominance. Investors should monitor ECHA authorization timeline acceleration as the critical inflection signal, with faster-than-expected perchloroethylene sunsets compressing substitution demand into narrower windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Supply | Captive oleochemical production insulates BASF and Dow from palm kernel oil volatility affecting regional compounders. |
| Green Manufacturing Transition | Bio-derived feedstock R&D at Stepan Company aligns procurement criteria at automotive OEMs prioritizing Scope 3 reductions. |
| Long-term Supply Agreement | Japanese automotive tier-one suppliers negotiating direct chelator procurement from Evonik bypass integrated formulators entirely. |
| Joint Venture for Regional Localization | Domestic formulation partnerships in India create first-mover positioning ahead of BIS import mandate enforcement. |
| Capacity Expansion in Chelating Agents | Precision electronics cleaning demand in Taiwanese foundries rewards gluconate and phosphonate production scale-up. |
Research Methodology
Coverage spans Germany, the United States, China, Japan, and India, with primary inputs from each market informing cross-regional pattern identification. The analysis combines structured interviews with plant managers at automotive stamping operations, procurement leads at electronics foundries, distribution channel partners in industrial chemical logistics, and technical R&D directors at formulation houses. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and GB 8978 wastewater discharge enforcement records. Bottom-up demand modeling across end-use industries triangulates against top-down market sizing from supplier revenue aggregation.
Rate-of-change decomposition separates volume expansion from price realization effects across the projection horizon. The analytical framework models segmentation dimensions including formulation chemistry type, end-use industry concentration, packaging format scale, and regional regulatory cluster stringency. CAGRs derive from installed base growth in target industries, chemistry consumption intensity per unit of manufacturing output, and substitution elasticity between solvent and aqueous systems. Forecast inputs incorporate REACH authorization timeline probabilities, MEE enforcement intensity gradients across Chinese provinces, and semiconductor packaging technology migration patterns.
Caveats apply where ECHA authorization delays, MEE enforcement relaxation, or hydrofluoroether supply disruptions could materially shift the outlook for aqueous substitution trajectories. Forecasts reflect documented assumptions regarding regulatory implementation schedules and technology adoption elasticities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Industrial Cleaners Market
Cleaning Chemicals
Global Antiseptic Products Market
Cleaning Chemicals
Europe Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Commercial Deodorizers Market
Cleaning Chemicals
Coating Removal System Market
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Drain Opener Chemicals Market
Cleaning Chemicals
Home Insecticides Market
Cleaning Chemicals
Industrial and Institutional (Iandi) Cleaning Chemicals Market
Cleaning Chemicals
Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market
Cleaning Chemicals
Sponge and Scouring Pads Market
Cleaning Chemicals
Multi-Residue Detoxifying Field Wash Aid Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Soap and Detergent Market
Cleaning Chemicals
Glass and Metal Cleaner Market
Cleaning Chemicals
Liquid Detergent Market