
 Mineral Wool Insulation Market | 2026-2036
Mineral Wool Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Wool Insulation Market Outlook
Project finance tied to green building certification is narrowing the competitive field for mineral wool insulation contracts. ROCKWOOL International A/S leverages its vertical integration from basalt sourcing to finished board production across multiple continents. Johns Manville sustains broad specification reach through its parent Berkshire Hathaway's balance sheet capacity for large commercial project bonding. Saint-Gobain anchors European renovation demand through its ISOVER brand's deep contractor relationships and specification heritage.
Mineral wool insulation comprises fibers manufactured from molten rock, blast furnace slag, or glass, formed through spinning or blowing processes to achieve thermal conductivity values typically ranging from 0.030 to 0.045 W/mK. The material functions primarily as a fire-resistant thermal and acoustic barrier in building envelopes and industrial equipment. Board products command the strongest margin pools in commercial and industrial applications where compressive strength and dimensional stability justify premium positioning. Batts dominate residential new construction volumes but face substitution pressure from spray foam in premium housing segments. The HVAC application channel shows the fastest specification growth as district heating networks and data center cooling systems expand across Northern Europe and East Asia.
The EU Green Deal's renovation wave targets and the US Department of Energy's building performance standards create dual regulatory engines pulling mineral wool specifications toward higher R-values and lower embodied carbon. ECHA's ongoing review of formaldehyde-based binders under REACH pushes manufacturers toward bio-based alternative chemistries that alter product cost structures. China's GB standards for building energy efficiency, enforced by provincial construction quality inspectors, mandate mineral wool in all new public buildings above certain floor areas. Stakeholders must monitor binder chemistry transitions and carbon accounting methodologies as these become decisive factors in public procurement scoring across the three largest demand centers.
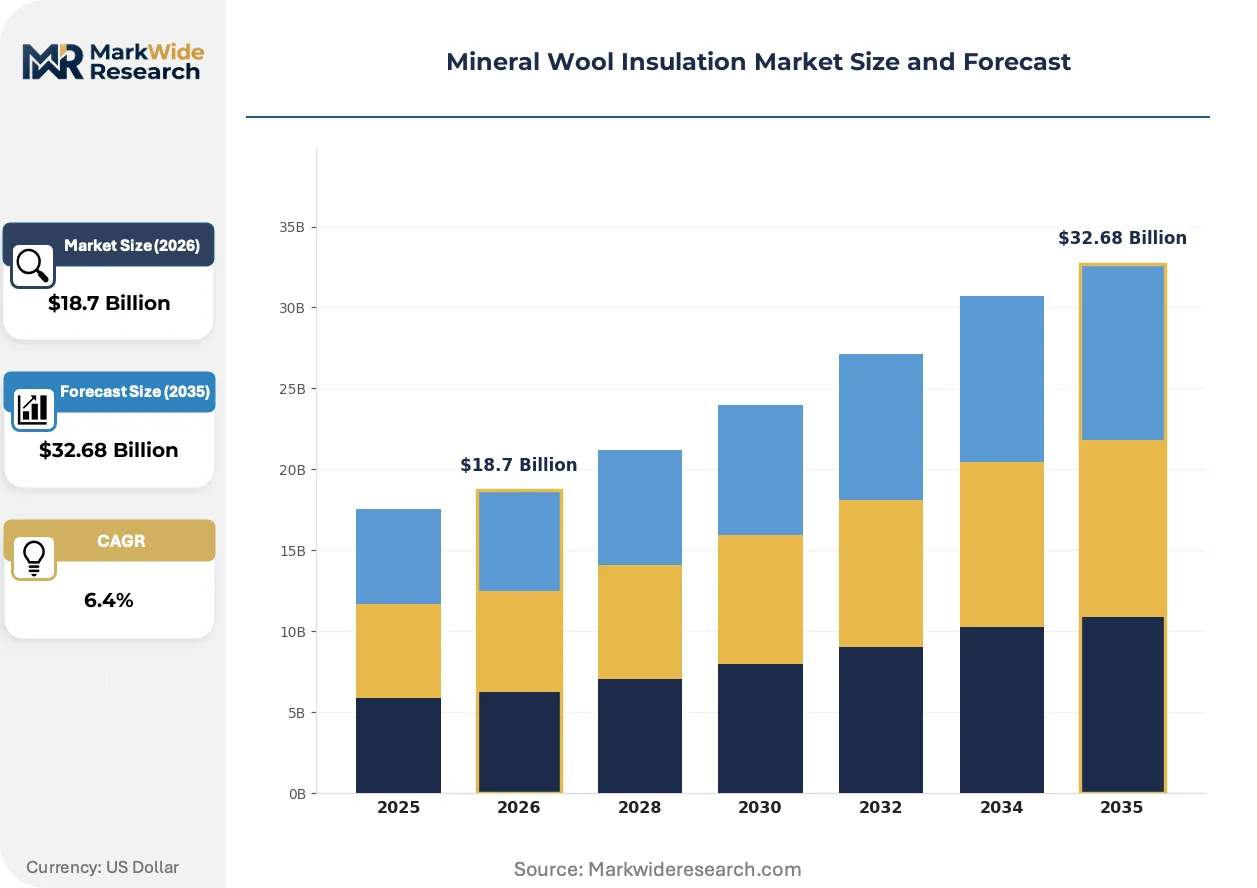
Market Dynamics
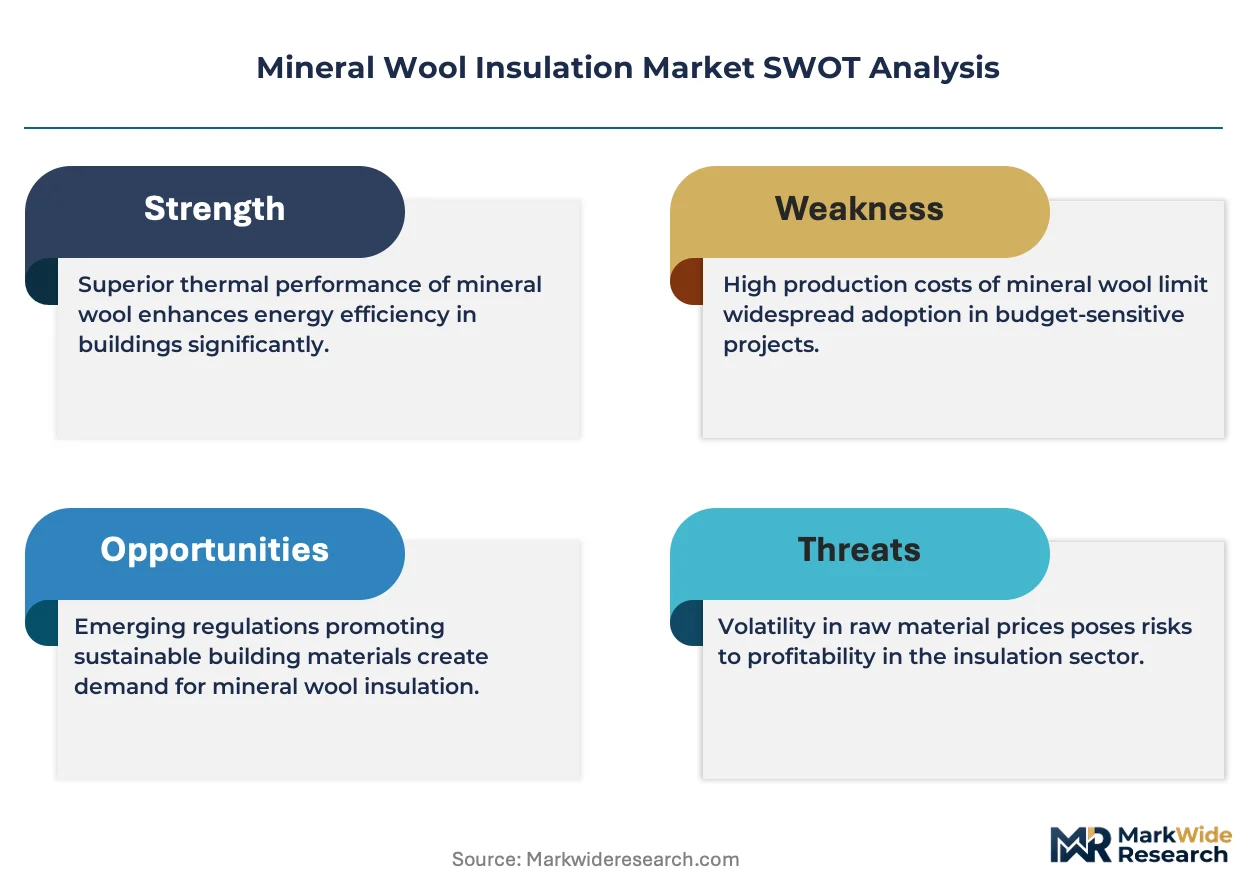
Building energy codes across Germany, the United States, and China are compressing thermal conductivity requirements faster than incumbent supply chains can reformulate binder chemistries and densification processes.
Growth Catalysts
- EU Green Deal renovation mandates:The European Commission's binding targets for building envelope retrofits pull specification volumes toward higher-density mineral wool board products in commercial and multi-family housing.
- Data center cooling infrastructure:Hyperscale facility operators in Northern Europe and East Asia specify mineral wool for thermal and acoustic management in district cooling networks serving server farms.
- Blast furnace slag availability:Steel production clusters in China and Germany provide captive raw material streams that lower input costs for slag-wool manufacturing relative to virgin rock alternatives.
Market Restraints
- Binder chemistry transition costs:ECHA's REACH review of formaldehyde-based binders forces manufacturers to reformulate around bio-based alternatives that raise unit production costs.
- Slag supply geographic concentration:Dependence on integrated steel mill proximity in China's Hebei province and Germany's Ruhr region creates raw material access disparities for non-integrated producers.
- Spray foam substitution in premium residential:Polyurethane spray systems capture specification share in custom home construction where air-sealing performance outweighs fire-resistance priorities.
Strategic Opportunities
- Industrial HVAC aftermarket:District heating network expansions across Poland and the Czech Republic create specification entry points for pipe and equipment insulation in legacy system upgrades.
- US Inflation Reduction Act commercial rebates:Federal tax incentives for building envelope improvements accelerate retrofit project pipelines in Class B and C office stock.
- Digital specification platforms:Building information modeling libraries and automated submittal tools compress the design-to-procurement cycle for contractor customers.
Industry Challenges
- Bio-based binder scale-up:Laboratory-validated alternative chemistries face multi-year validation timelines for fire-performance certification under EN 13501 and ASTM E84 protocols.
- Embodied carbon accounting standardization:Inconsistent methodologies across EPD programs and national building codes complicate low-carbon product positioning in public procurement scoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Wool Insulation Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batts, Blankets, Boards, Loose Fill Application: Residential, Commercial, Industrial, HVAC Installation Method: New Construction, Renovation, Retrofitting, Direct Installation End User: Contractors, Builders, Architects, Homeowners |
| Companies Covered | Knauf Insulation, Kingspan Group, ROCKWOOL International A/S, URSA Insulation, Paroc Group Oy, Saint-Gobain, Johns Manville, Armacell International, Owens Corning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Wool Insulation Market Strategic Shifts
Digital tools are compressing the specification-to-installation cycle while regulatory pressure on embodied carbon forces material transparency upstream into raw material sourcing.
Computational fluid dynamics modeling is virtualizing thermal bridge analysis in building envelope design. Engineering firms serving commercial retrofit clients adopt these simulation tools to demonstrate code compliance before material procurement. The technology is virtualizing the traditional physical mock-up and field-testing phases that previously extended project timelines by weeks.
Germany's amended Building Energy Act tightens permissible U-values for exterior walls and roofs in both new construction and major renovations. The regulation compresses the viable product set to higher-density mineral wool boards with thermal conductivity below 0.035 W/mK. German facade contractors report specification shifts toward multi-layer systems combining insulation with integrated weather barriers.
General contractors increasingly bundle insulation procurement into turnkey envelope packages rather than sourcing materials separately. This consolidation compresses direct manufacturer relationships and elevates the influence of regional distributors with bonding capacity and logistics integration. The shift is most visible in US commercial construction where project delivery methods favor design-build and integrated project delivery structures.
Mineral Wool Insulation Market Segmentation
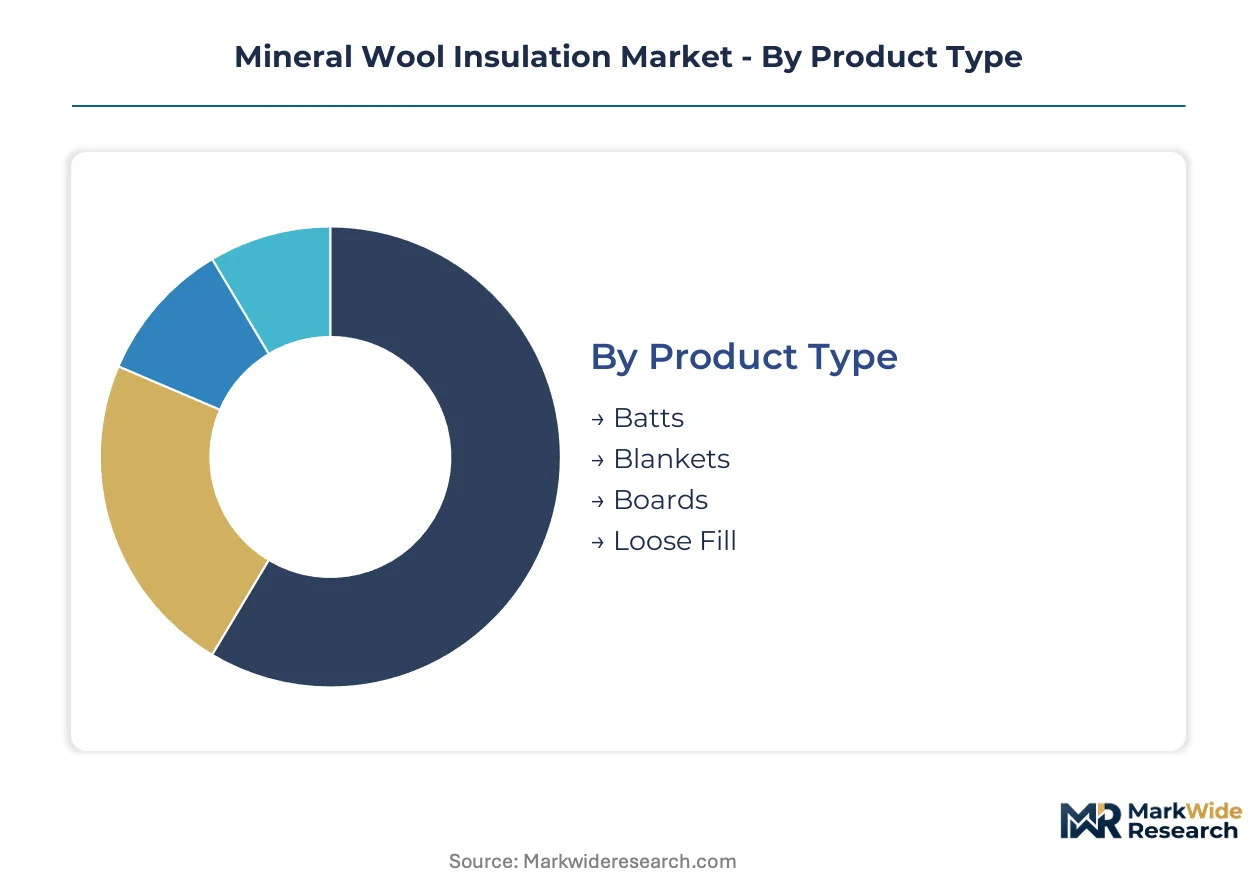
Product form factor determines thermal performance specifications and margin structure across mineral wool applications. Installation context and specifier relationships further fragment competitive positioning within each product category.
Product Type:
Cost tier separates commodity batts from engineered board products with premium positioning.
- Boards:Rigid panels manufactured through controlled densification achieve compressive strength above 50 kPa for facade and roof applications. German facade contractors specify multi-layer systems with integrated weather barriers under amended Building Energy Act requirements. Higher-density formulations with thermal conductivity below 0.035 W/mK command specification in commercial retrofits.
- Batts:Pre-cut fibrous mats sized for standard framing cavities dominate residential new construction volumes. United States production scales through automated slitting lines serving national homebuilder procurement programs. Substitution pressure from polyurethane spray foam intensifies in premium custom home segments.
- Blankets:Continuous rolls suit industrial equipment and pipe insulation with irregular surface geometries.
- Loose Fill:Blown-in material accesses confined attic spaces and irregular cavities in legacy building stock.
Boards command the established base. The steepest expansion runs through batts as residential code adoption accelerates.
Application:
End-use maturity varies sharply across building stock age and regulatory enforcement intensity.
- Commercial:Envelope retrofits in Class B and C office buildings concentrate specification volume as US Inflation Reduction Act rebates accelerate project pipelines. Multi-layer board systems with integrated air barriers dominate facade renovation specifications. EU Green Deal renovation mandates pull demand toward higher R-value assemblies.
- HVAC:District heating network expansions across Poland and the Czech Republic create specification entry points for pipe and equipment insulation. Hyperscale data center operators in Northern Europe specify mineral wool for thermal and acoustic management in district cooling infrastructure.
- Residential:New construction volumes flow through national homebuilder procurement programs with standardized cavity dimensions.
- Industrial:Process equipment and storage tank insulation follows capital expenditure cycles in steel and petrochemical sectors.
Commercial applications anchor current revenue. HVAC infrastructure shows the fastest specification velocity.
Installation Method:
Project delivery structure determines manufacturer access to decision-makers and margin capture.
- Renovation:Major envelope upgrades in Germany trigger mandatory compliance with tightened U-value limits under amended Building Energy Act. Turnkey procurement through regional envelope contractors compresses direct manufacturer relationships. Specification shifts toward higher-density board products with integrated weather barriers.
- New Construction:National homebuilder procurement programs standardize batts through volume contracts with distribution intermediaries. Design-build and integrated project delivery structures in US commercial construction favor bundled envelope packages.
- Retrofitting:Legacy building stock upgrades access confined spaces through loose fill and specialized board cutting.
- Direct Installation:Homeowner-driven attic upgrades bypass contractor channels in residential aftermarket segments.
Renovation work carries the volume concentration. New construction offers the most predictable procurement cadence.
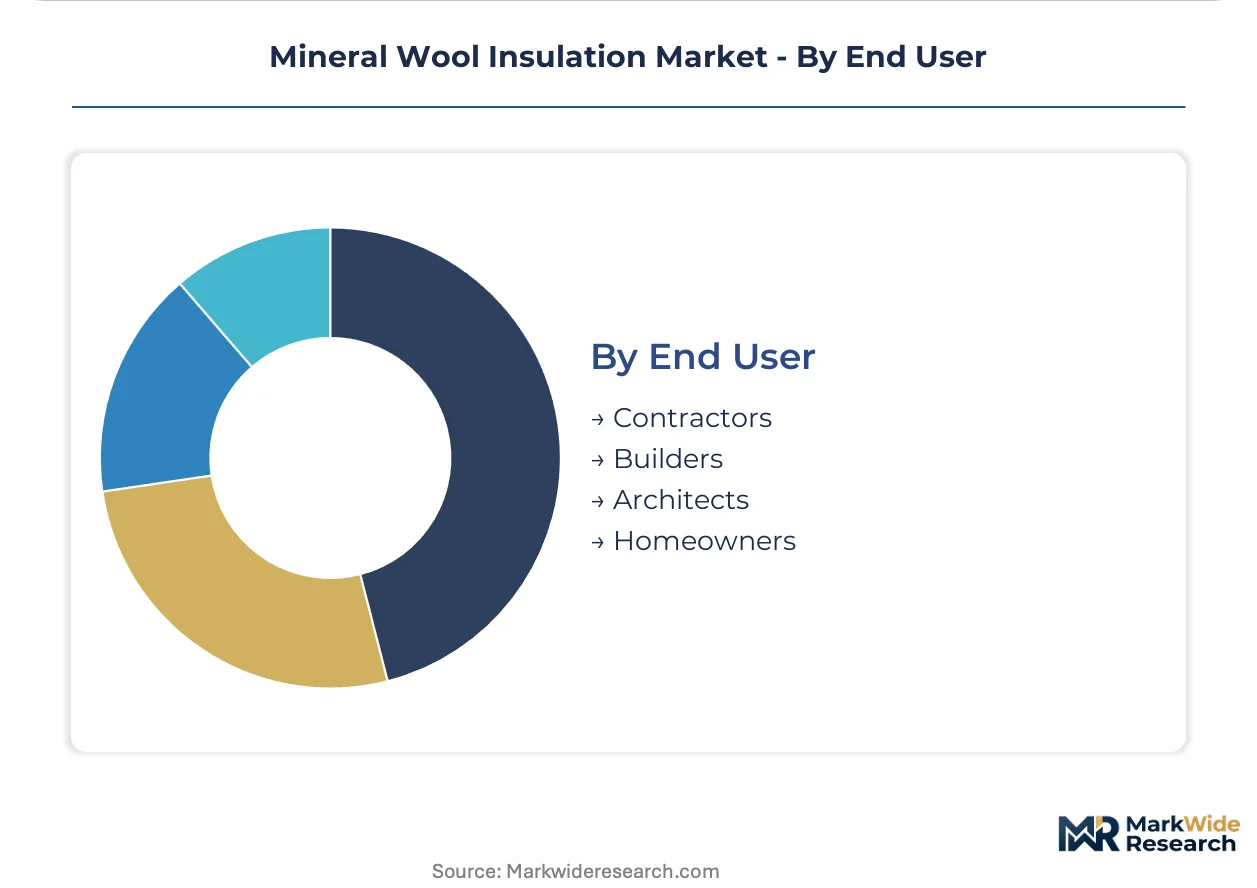
End User:
Specifier influence cascades through distinct professional relationships with material manufacturers.
- Architects:Building information modeling libraries and automated submittal tools compress design-to-procurement cycles for commercial clients. Computational fluid dynamics modeling virtualizes thermal bridge analysis before material specification. EN 13501 and ASTM E84 fire-performance certification requirements filter product selection.
- Contractors:Regional distributors with bonding capacity and logistics integration capture procurement consolidation in US commercial construction. General contractor envelope bundling elevates distributor influence over direct manufacturer relationships.
- Builders:National production homebuilders standardize batts through volume procurement programs with cost-tier pricing.
- Homeowners:Retail channel access and utility rebate programs drive attic upgrade decisions in residential aftermarket.
Architects control specification in commercial segments. Contractors capture procurement volume in execution-phase decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in mineral wool insulation tilt toward regional self-sufficiency, with integrated producers in Germany, the United States, and China serving captive demand clusters while cross-border trade concentrates in specialty board grades.
United States
Commercial building retrofits in Class B and C office stock drive specification volume as the Inflation Reduction Act channels federal tax incentives toward envelope improvements. The Department of Energy's building performance standards compress thermal conductivity requirements faster than incumbent supply chains can reformulate binder chemistries. Production scales through automated slitting lines serving national homebuilder procurement programs in the Southeast and Midwest.
Germany
The amended Building Energy Act tightens permissible U-values for exterior walls and roofs, compressing the viable product set to higher-density mineral wool boards. ECHA's REACH review of formaldehyde-based binders pushes manufacturers toward bio-based alternative chemistries that alter product cost structures. The Ruhr region's integrated steel mills provide captive blast furnace slag streams that lower input costs for slag-wool manufacturing.
China
GB standards for building energy efficiency, enforced by provincial construction quality inspectors, mandate mineral wool in all new public buildings above certain floor areas. Steel production clusters in Hebei province supply raw material streams that lower input costs for slag-wool manufacturing relative to virgin rock alternatives. District heating network expansions across Northern China create specification entry points for pipe and equipment insulation.
Poland
District heating network expansions across Poland and the Czech Republic create specification entry points for pipe and equipment insulation in legacy system upgrades. EU Green Deal renovation mandates pull demand toward higher R-value assemblies in multi-family housing. Warsaw and Krakow contractors report specification shifts toward multi-layer systems combining insulation with integrated weather barriers.
Japan
Hyperscale data center operators specify mineral wool for thermal and acoustic management in district cooling infrastructure serving server farms. METI efficiency standards for commercial buildings accelerate thermal envelope upgrade cycles in Tokyo and Osaka. Kanto region engineering firms adopt computational fluid dynamics modeling to virtualize thermal bridge analysis before material procurement.
Mineral Wool Insulation Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated producers with captive raw material access and multi-continent manufacturing footprints. Three strategic archetypes dominate: integrated rock-wool specialists with basalt sourcing control, diversified building materials conglomerates leveraging distribution scale, and regional slag-wool producers anchored to steel mill proximity. Competitive moves center on backward integration into binder chemistry development and capacity expansion in high-growth HVAC specification channels.
Within the integrated specialist tier, ROCKWOOL International A/S and Paroc Group Oy exemplify producers with upstream control over mineral feedstocks and multi-continent production networks. Among diversified building materials conglomerates, Saint-Gobain and Owens Corning occupy positions that leverage broad distribution infrastructure and cross-product bundling in commercial construction procurement. Johns Manville sits within the mid-scale integrated tier, representing producers with parent-company balance sheet capacity for large commercial project bonding.
| Leading Market Players |
|---|
| Knauf Insulation |
| Kingspan Group |
| ROCKWOOL International A/S |
| URSA Insulation |
| Paroc Group Oy |
| Saint-Gobain |
| Johns Manville |
| Armacell International |
| Owens Corning |
| Others |
Value Chain & Pricing Dynamics
REACH binder chemistry restrictions function as a dual chokepoint that widens pricing spreads between formaldehyde-based and bio-based product tiers while forcing supply chain reconfiguration around certified alternative feedstocks. ECHA's phased compliance timelines compress reformulation investment returns and concentrate bargaining power with integrated producers possessing in-house binder R&D.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in mineral wool procurement. Price differentiation rests on EN 13501 fire-performance certification tier and blast furnace slag integration depth. Pricing pressure stems from bio-based binder scale-up costs that manufacturers struggle to pass through in public tender contexts. National homebuilders exhibit highest price sensitivity through volume contract negotiations, while data center operators accept premium positioning for acoustic-thermal bundled specifications.
Supply Chain Analysis
Export-control regimes on formaldehyde-based binder technologies limit technology transfer flows and fragment global supply coordination. Raw material sourcing concentrates in China's Hebei province, Germany's Ruhr region, and the United States Southeast. Manufacturing draws from basalt deposits, blast furnace slag streams, and phenolic resin alternatives. Single-source vulnerability runs through Hebei slag-wool capacity exposed to steel production curtailments. Distribution runs through regional envelope contractors bundling insulation into turnkey procurement packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mineral wool insulation market functions as a regulatory-entrenchment defensive moat where building code adoption creates switching costs that cement incumbent positions. Certification timelines and specification heritage embed producer relationships that resist displacement.
For Market Incumbents: Harden specification lock-in through accelerated bio-based binder certification under EN 13501 protocols before REACH compliance deadlines compress competitive windows. Expand captive slag supply arrangements in Germany's Ruhr and China's Hebei to defend margin position against virgin rock input volatility. Deepen contractor training programs that embed product-specific installation expertise and elevate switching costs for procurement decision-makers. For New Entrants and Emerging Players: Build out district heating aftermarket specialization in Poland and Czech Republic where legacy system upgrades lack established supplier relationships and specification inertia remains weakest. Target HVAC pipe insulation segments with technical sales teams fluent in computational fluid dynamics modeling tools that architects increasingly require. Penetrate through digital specification platform partnerships that compress traditional distributor gatekeeper roles. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated specialists with captive raw material access and multi-continent production footprints. Long-term viability hinges on carbon accounting methodology standardization that will separate EPD-verified low-carbon producers from commodity competitors. Watch for ECHA REACH enforcement intensity as the inflection signal that accelerates bio-based binder transition timelines and rewards early movers with certification headroom.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Binder Chemistry | ECHA REACH compliance timelines reward captive bio-based formulation R&D with specification priority in EU public tenders. |
| Capacity Expansion in HVAC Specification Channels | Data center cooling infrastructure buildouts in Northern Europe and East Asia pull premium thermal-acoustic product demand. |
| Green Certification Program Investment | EPD verification under evolving carbon accounting methodologies secures procurement scoring advantage in Germany and US federal projects. |
| Long-term Slag Supply Agreement | Steel mill proximity in Hebei and Ruhr regions locks in input cost advantage over virgin rock-dependent competitors. |
| Digital Specification Platform Partnership | Building information modeling library integration compresses design-to-procurement cycles and displaces traditional distributor influence. |
Study Parameters
Desk research of building energy code databases, ECHA regulatory filings, and steel industry production statistics preceded structured interviews with facade contractors, HVAC specification engineers, and thermal envelope procurement managers. Primary fieldwork with German facade contractors, US commercial general contractors, and Chinese provincial construction quality inspectors validated secondary trade flow estimates. Analysis combined bottom-up project pipeline tracking with top-down regulatory mandate quantification across the three largest demand centers.
Forecast assumptions held EU Green Deal renovation targets, US Inflation Reduction Act rebate structures, and China GB standard enforcement intensity at announced policy levels across the projection horizon. Segmentation modeling incorporated product form factor, application end-use, installation method, and specifier professional role as demand dimensions. CAGRs derived from regression analysis of building permit volumes against code adoption curves, with mineral wool specification share assumptions calibrated to energy efficiency tier requirements. District heating network expansion timelines and data center cooling capacity buildouts served as industry-specific demand inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by slag-wool specialists or accelerated bio-based binder breakthroughs by chemical entrants would shift outcomes. Material shifts in ECHA REACH enforcement timelines or carbon accounting methodology standardization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Expanded Perlite Market
Insulation Materials
Global Low Smoke Halogen-Free Cable Materials Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
North America Phase Change Materials Market
Insulation Materials
Global Microporous Insulation Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Carbon Foam Market
Insulation Materials
Technical Foam Market
Insulation Materials
Phase Change Thermal Interface Materials Market
Insulation Materials
Radiation Shielding Materials Market
Insulation Materials
Phase Change Materials Market
Insulation Materials
Microporous Insulation Material Market
Insulation Materials
Thermal Tapes Market
Insulation Materials
Multi-Layer Cryogenic Insulation Market