
 Global Acoustic Insulation Material Market | 2026-2036
Global Acoustic Insulation Material Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acoustic Insulation Material Market Foresight
ISO 11654 sound absorption certification is redrawing competitive boundaries for material suppliers seeking specification in premium commercial projects. Saint-Gobain leverages its integrated glass wool manufacturing footprint across multiple continents to sustain cost-advantaged supply to major infrastructure programs. Rockwool International A/S anchors its position through specialized stone wool formulations engineered for fire-resistant acoustic performance in transportation tunnels and rail systems. Owens Corning competes by extending its building science portfolio into spray-applied solutions that reduce labor hours during high-rise construction.
Acoustic insulation material encompasses engineered substances designed to attenuate sound energy transmission through porous absorption, mass-barrier reflection, or damping dissipation, typically quantified by noise reduction coefficient values between 0.70 and 1.05 for high-performance products. These materials serve primarily to achieve mandated sound transmission class ratings in built environments where occupant comfort, worker safety, or regulatory compliance depends on controlled decibel levels. Mineral wool and fiberglass categories dominate current volume flows due to established supply chains and broad code acceptance, while foam segments capture expanding share in transportation infrastructure where weight reduction intersects with acoustic performance requirements. Spray-on product forms represent the fastest-growing configuration as mechanical contractors prioritize speed of installation in complex architectural geometries.
The US EPA and OSHA frameworks govern occupational noise exposure limits that directly mandate industrial acoustic treatment investments, while REACH and the EU F-Gas Regulation constrain blowing agent chemistries available to European foam manufacturers. China's GB standards and MEE enforcement protocols set progressively tighter building acoustic benchmarks that reshape import qualification requirements for foreign suppliers. Stakeholders must monitor evolving multi-jurisdiction chemical restrictions and decarbonization mandates that threaten to disqualify incumbent formulations before next-generation bio-based alternatives achieve cost parity.
Market Dynamics
Construction contractors across Germany, France, and China are mandating ISO 11654-certified acoustic systems as building codes tighten and metro expansion accelerates urban density requirements.
Growth Catalysts
- EU Green Deal mandates:Stricter sound transmission class ratings in Germany, France, and Italy are forcing retrofit specifications across existing commercial building stock.
- China metro expansion:Mixed-use zoning along urban corridors in Beijing and Shanghai is driving bulk procurement of mineral wool for rail-adjacent developments.
- Spray-applied foam adoption:Mechanical contractors are specifying spray-on configurations to compress installation timelines in complex high-rise geometries.
Market Restraints
- REACH chemical constraints:The EU F-Gas Regulation is restricting blowing agent chemistries available to European foam manufacturers, compressing formulation flexibility.
- Mineral wool supply concentration:Production gravity centers on a limited number of integrated glass wool and stone wool facilities across continental Europe.
- Bio-based cost gap:Next-generation bio-based acoustic alternatives remain priced above cost parity with incumbent mineral wool and fiberglass systems.
Strategic Opportunities
- India building code modernization:BIS acoustic benchmarks are tightening across Mumbai and Delhi commercial developments, opening specification windows for certified imports.
- Transportation tunnel fire-acoustic convergence:Stone wool formulations engineered for simultaneous fire resistance and noise attenuation are capturing specification in rail infrastructure.
- US OSHA enforcement expansion:Industrial noise exposure mandates are extending acoustic treatment requirements into manufacturing facilities previously exempt from retrofit obligations.
Industry Challenges
- ISO 11654 certification timelines:Third-party testing protocols for sound absorption coefficients are creating 4-6 month qualification delays for new product launches.
- Multi-jurisdiction chemical compliance:Formulation teams must simultaneously satisfy REACH restrictions, US EPA frameworks, and China's MEE enforcement protocols.
- Spray-application skill scarcity:Certified applicator pools for complex spray-on acoustic systems remain thin relative to installation demand in high-rise construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acoustic Insulation Material Market |
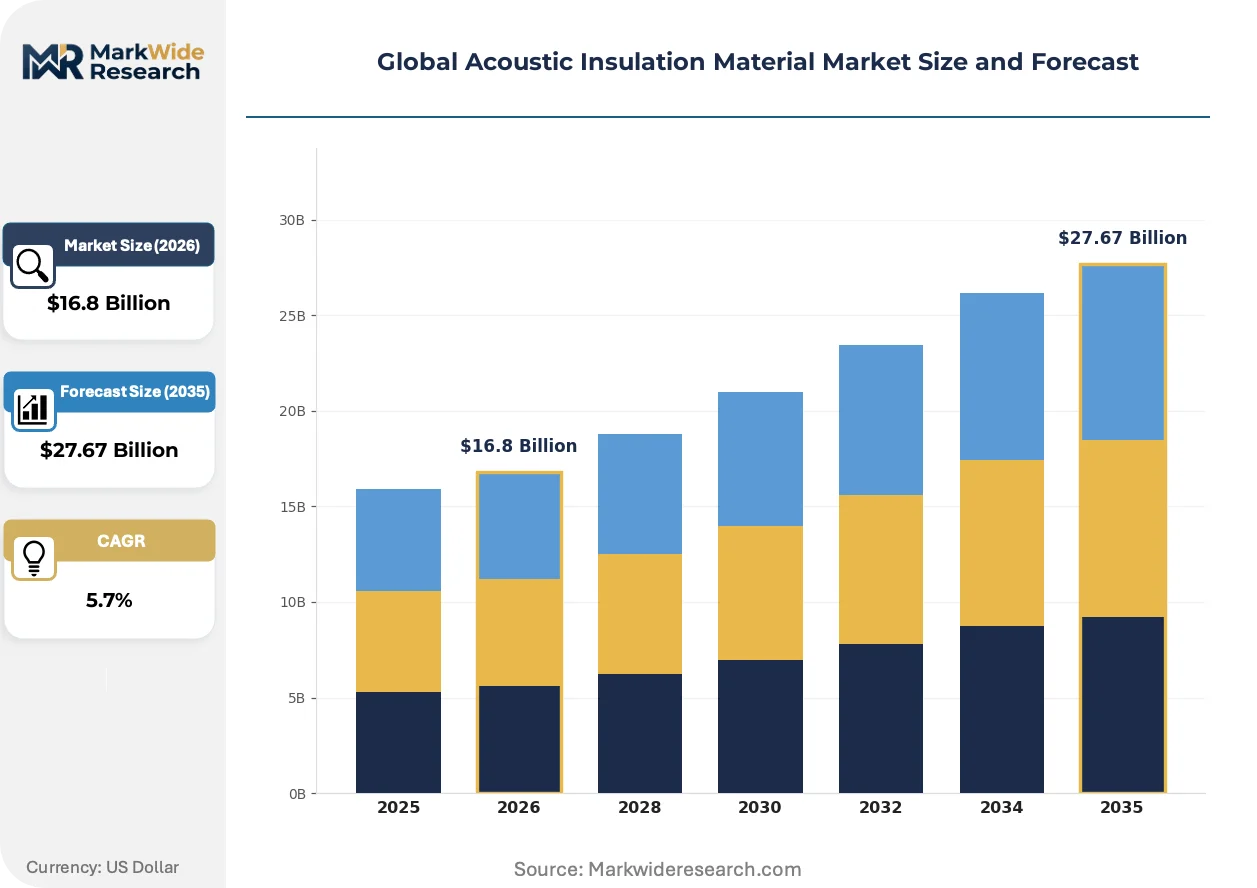
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $27.67 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fiberglass, Mineral Wool, Foam, Cellulose, Cotton Application: Residential Buildings, Commercial Complexes, Industrial Plants, Transportation Infrastructure, Entertainment Venues Product Form: Batts & Rolls, Sheets & Panels, Loose Fill, Spray-On, Boards End User: Construction Contractors, Architectural Firms, Soundproofing Specialists, Vehicle Manufacturers, Event Management Companies |
| Companies Covered | Saint-Gobain, Rockwool International A/S, Knauf Insulation, Owens Corning, BASF SE, Kingspan Group, Johns Manville, Armacell International, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acoustic Insulation Material Market Shifts & Advancements
Acoustic insulation is pivoting from commodity batts toward engineered systems where certification grade and installation speed determine specification outcomes.
Aerogel-composite acoustic panels are miniaturizing thermal-acoustic dual-function systems into sub-10mm thicknesses. Aerospace and electric vehicle manufacturers are adopting these configurations for weight-critical envelope applications. The technology is miniaturizing the trade-off between acoustic performance and spatial volume that previously constrained transportation design.
REACH and the EU F-Gas Regulation are progressively disqualifying hydrofluorocarbon blowing agents from polyurethane foam production. European foam manufacturers are reformulating around pentane and hydrofluoroolefin alternatives at accelerated R&D spend. The regulatory pressure is compressing margins for mid-tier suppliers lacking captive chemical engineering capabilities.
General contractors are unbundling acoustic installation from general trades and awarding direct contracts to certified mechanical specialists. This disintermediation is displacing traditional distributor-led specification in premium commercial projects across Germany and France. The channel shift is most visible in high-rise residential towers where speed-to-enclosure drives procurement decisions.
Global Acoustic Insulation Material Market Segmentation
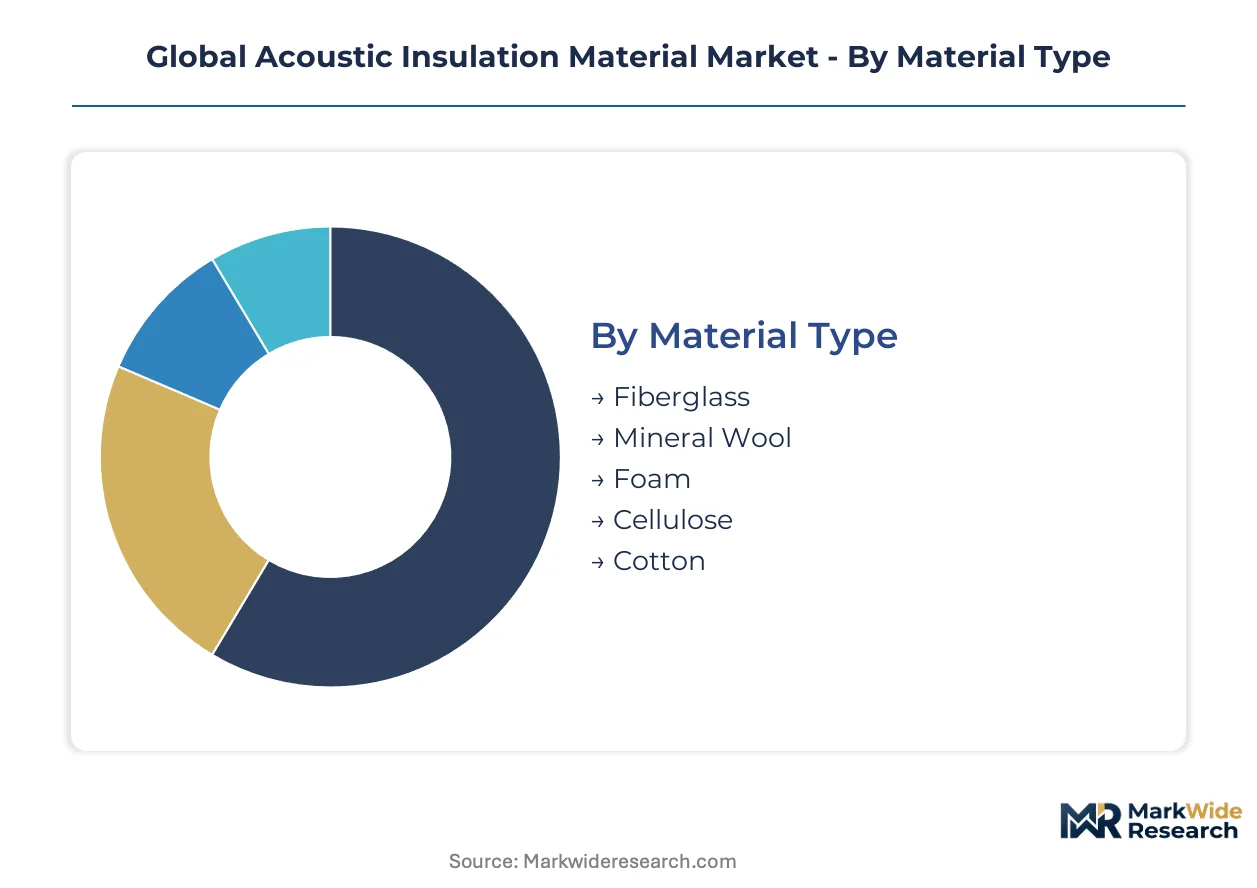
Acoustic insulation procurement splits across material chemistry, installation geometry, and end-use performance requirements. Specification decisions cascade from building code mandates through contractor workflow preferences to final acoustic certification thresholds.
Material Type:
Mineral wool and fiberglass face intensifying substitution pressure from bio-based alternatives as REACH chemical constraints tighten formulation flexibility for conventional systems.
- Fiberglass:Glass wool manufactured from recycled cullet and silica sand delivers consistent NRC 0.85-1.00 performance at moderate density. Demand concentrates in US multi-family residential towers where OSHA-compliant installation protocols favor familiar handling characteristics.
- Mineral Wool:Stone wool spun from basalt or diabase rock achieves simultaneous fire resistance and acoustic attenuation. German and French rail tunnel specifications are driving premium-grade procurement for transportation infrastructure where dual-certification requirements apply.
- Foam:Polyurethane and melamine systems capture specification where weight reduction intersects with complex geometric coverage.
- Cellulose:Recycled paper fiber treated with boric acid serves retrofit markets seeking lower embodied carbon.
- Cotton:Denim and textile waste streams appeal to niche commercial projects targeting LEED v4.1 materials credits.
Mineral wool anchors the volume base while spray-compatible foam formulations gain share at the steepest rate.
Application:
Cost tier stratification separates specification-grade commercial projects from commodity residential batts, with transportation infrastructure commanding premium pricing for fire-acoustic convergence.
- Residential Buildings:Multi-family towers in Beijing and Shanghai specify mineral wool batts to meet GB standard sound transmission class ratings for rail-adjacent units.
- Commercial Complexes:ISO 11654-certified systems dominate premium office and hospitality specifications across Germany and France.
- Industrial Plants:OSHA-mandated noise exposure limits are extending acoustic treatment into manufacturing facilities previously exempt from retrofit obligations.
- Transportation Infrastructure:Stone wool formulations engineered for tunnel fire resistance capture specification in European and Chinese metro expansion programs.
- Entertainment Venues:Concert halls and cinema complexes demand precision-tuned absorption coefficients across octave bands.
Commercial complexes generate the highest value per square meter while transportation infrastructure expands most quickly.
Product Form:
Installation speed is displacing material cost as the primary contractor selection criterion across high-rise construction markets.
- Batts & Rolls:Pre-cut mineral wool and fiberglass configurations dominate established residential workflows with predictable labor estimation.
- Spray-On:Polyurethane and acoustic plaster systems compress enclosure timelines in complex architectural geometries. Mechanical contractors across Germany and France are awarding direct contracts to certified applicators, bypassing traditional distribution channels.
- Sheets & Panels:Rigid boards serve retrofit applications where dimensional stability matters.
- Loose Fill:Blown cellulose and fiberglass occupy attic and cavity applications with limited access constraints.
- Boards:High-density stone wool panels anchor industrial and transportation specifications requiring structural integrity.
Batts and rolls retain the installed volume base while spray-on configurations climb the fastest.
End User:
Customer type determines channel structure, with construction contractors consolidating procurement authority and architectural firms influencing upstream specification.
- Construction Contractors:General contractors across high-rise residential towers are unbundling acoustic installation from general trades. Direct contracting to mechanical specialists is displacing distributor-led specification in Germany and France.
- Soundproofing Specialists:Certified applicator pools for complex spray-on systems remain thin relative to installation demand, creating margin expansion for qualified technicians.
- Architectural Firms:Design-phase specification of ISO 11654-certified materials locks in downstream procurement decisions for premium commercial projects.
- Vehicle Manufacturers:Electric vehicle producers are adopting aerogel-composite panels for weight-critical envelope applications.
- Event Management Companies:Temporary venue operators prioritize rapid-deploy acoustic treatments with reusable configurations.
Construction contractors control the dominant procurement volume while soundproofing specialists capture the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal mandates and China's dual carbon goals are redirecting procurement flows toward certified low-carbon acoustic systems. National building code tightening across multiple jurisdictions is compressing specification windows for uncertified materials. Urban rail expansion programs in Beijing, Berlin, and Mumbai are concentrating bulk demand for fire-acoustic dual-function products.
United States
OSHA enforcement expansion is mandating acoustic retrofits in manufacturing facilities previously exempt from noise exposure limits. The EPA maintains oversight of industrial emissions frameworks that intersect with plant modification timelines. Industrial corridors across Ohio and Michigan are absorbing mineral wool batts for factory wall assemblies.
Germany
The KBA and federal building authorities are enforcing stricter sound transmission class ratings for rail-adjacent residential towers. REACH and the EU F-Gas Regulation are constraining blowing agent chemistries available to domestic foam manufacturers. The Rhine-Ruhr metropolitan zone is specifying stone wool formulations for tunnel fire-acoustic convergence in metro expansion segments.
China
GB standard tightening and MEE enforcement protocols are reshaping import qualification requirements for foreign acoustic suppliers. Dual carbon goals are accelerating specification of lower-embodied-carbon insulation in state-backed infrastructure. Beijing and Shanghai mixed-use corridors are driving bulk procurement of mineral wool for rail-adjacent high-rise developments.
India
BIS acoustic benchmark modernization is opening specification windows for certified imports in Mumbai and Delhi commercial towers. The national building code revision process is elevating sound transmission class requirements for premium office developments. The Delhi-NCR corridor is concentrating demand for ISO 11654-certified systems in new hospitality and corporate projects.
France
ANSM and national construction regulators are mandating ISO 11654 certification for premium commercial specifications. The EU Green Deal is forcing retrofit specifications across existing Parisian office stock. The Île-de-France region is unbundling acoustic installation from general trades and awarding direct contracts to certified mechanical specialists.
Global Acoustic Insulation Material Market Competitive Landscape
Player mix skews toward integrated material science conglomerates with captive mineral wool supply chains. Tiered specialization separates volume-driven batt manufacturers from premium spray-application specialists. Three archetypes dominate: integrated glass wool producers with multi-continent manufacturing footprints, stone wool specialists engineering fire-acoustic dual performance, and chemical conglomerates supplying foam blowing agent formulations. Competitive moves concentrate on backward integration into raw material sourcing and geographic expansion through specification-grade certification acquisition.
Among European-anchored material science groups, Saint-Gobain, Rockwool International A/S, and Knauf Insulation occupy positions across distinct chemistry verticals. Saint-Gobain exemplifies the integrated glass wool archetype with manufacturing footprints spanning multiple continents. Rockwool International A/S anchors the stone wool specialization vector for transportation tunnel applications. Knauf Insulation represents the family-owned, construction-systems-integrated model with broad code acceptance across residential and commercial workflows.
| Leading Market Players |
|---|
| Saint-Gobain |
| Rockwool International A/S |
| Knauf Insulation |
| Owens Corning |
| BASF SE |
| Kingspan Group |
| Johns Manville |
| Armacell International |
| 3M Company |
| Others |
Supply & Pricing Matrix
Capacity utilization at integrated glass wool facilities across Germany and France anchors price floors for mineral wool batts, compressing margins for mid-tier foam converters lacking backward integration into silica sand or basalt sourcing. Scale advantages at Saint-Gobain and Rockwool manufacturing clusters translate into procurement leverage that smaller spray-application specialists cannot replicate without volume commitments from rail infrastructure programs.
Pricing Analysis
Certification level creates the primary spread between premium ISO 11654-grade systems and commodity residential batts. Three-tier pricing structure across premium, standard, and economy levels reflects testing investment amortization and fire-resistance bundling. Cost compression in European foam segments is intensifying because REACH and F-Gas Regulation constraints are forcing reformulation around pentane alternatives. Industrial contractors in US manufacturing corridors exhibit highest price sensitivity, while transportation infrastructure procurement in Chinese metro expansion shows lowest sensitivity due to dual-certification mandates.
Supply Chain Analysis
Baltic Sea port congestion for stone wool slab shipments to German rail tunnel projects concentrates delivery risk in Q3 construction windows. Supply draws from basalt quarries in Denmark, recycled cullet streams in the United States, and petrochemical feedstocks in Belgium and the Netherlands. Raw material dependencies span boron for fire resistance, isocyanates for polyurethane systems, and aluminum sulfate for cellulose treatment. Single-source vulnerability sits with certified applicator pools for complex spray-on geometries. Distribution runs through mechanical contractor direct contracts in high-rise residential, bypassing traditional distributor networks in premium commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acoustic insulation market is shifting toward platform economics where ISO 11654 certification databases and contractor-applicator matching platforms are consolidating specification authority. Interoperability between building information modeling systems and acoustic performance libraries is redrawing competitive moats around data assets rather than raw material access alone.
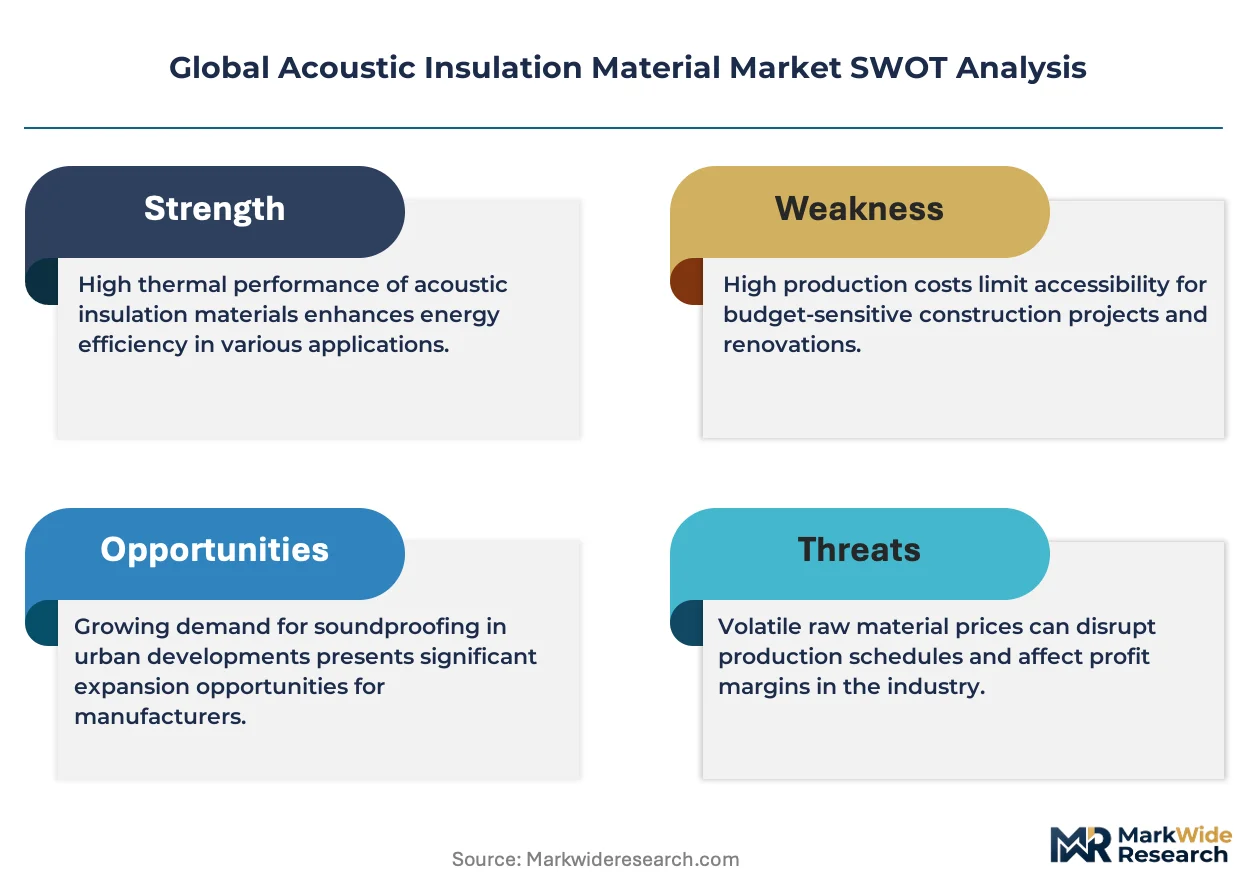
For Market Incumbents: Fortify backward integration into boron and basalt sourcing to insulate margins from REACH-constrained foam competitors. Expand certified applicator training capacity in Chinese urban corridors before metro expansion peaks absorb available technician pools. Prioritize captive supply of stone wool formulations for fire-acoustic convergence in transportation tunnels, where dual-certification requirements lock out reformulation-lagged rivals. For New Entrants and Emerging Players: Differentiate on bio-based cellulose and cotton formulations targeting LEED v4.1 materials credits in Mumbai and Delhi commercial towers. Penetrate the India building code modernization window before BIS acoustic benchmarks harden import qualification barriers. Pursue direct contracting relationships with soundproofing specialists in France's Île-de-France region, where general contractor unbundling creates channel access without distributor incumbent relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among spray-application service providers with certified technician networks and long-term maintenance contracts for transportation infrastructure. Five-to-ten year viability favors stone wool specialists with rail tunnel specification lock-in over foam manufacturers facing progressive F-Gas disqualification. Target acquisition archetype: regional spray-applicator platforms with ISO 11654 certification scope expansion capability. Watch REACH chemical restriction timelines as the inflection signal for bio-based alternative cost parity achievement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basalt Sourcing | Captive supply of stone wool raw materials insulates margins from REACH-constrained competitors in European foam segments. |
| ISO 11654 Certification Database Development | Digital specification platforms lock in downstream procurement decisions for premium commercial projects across Germany and France. |
| Certified Applicator Training Expansion | Technician pool scarcity in Chinese metro corridors creates margin expansion for qualified spray-on installation providers. |
| Bio-Based Formulation R&D Investment | Cellulose and cotton alternatives capture LEED v4.1 demand as mineral wool faces embodied carbon scrutiny under EU Green Deal mandates. |
| Direct Contractor Channel Bypass | Mechanical specialist contracting in high-rise residential displaces distributor-led specification, compressing channel margin capture. |
Research Methodology
Desk research of customs trade data, EU ECHA regulatory filings, and SEC 10-K disclosures preceded structured interviews with construction contractor procurement directors, acoustic applicator technicians, and building code enforcement officials. Primary fieldwork with mineral wool plant managers and foam formulation chemists validated secondary volume estimates. Bottom-up project pipeline analysis across Beijing, Shanghai, Berlin, and Mumbai rail expansion programs was triangulated against top-down building code mandate impact assessments.
Variance decomposition across material chemistry, application geometry, and end-use performance requirements shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product form, certification tier, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle acceleration under tightening sound transmission class mandates. Forecast inputs incorporated MEE enforcement protocol intensity in China and OSHA expansion trajectory in US industrial corridors.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal implementation or China dual carbon policy continuity would require recalibration. Forecasts reflect assumptions around REACH chemical restriction timelines and certified applicator training throughput capacity. Practitioners should keep alternative scenarios live as F-Gas Regulation amendment cycles and BIS acoustic benchmark revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Multi-Layer Cryogenic Insulation Market
Insulation Materials
Asia-Pacific Insulation Materials Market
Insulation Materials
Carbon Foam Market
Insulation Materials
Italy Industrial Insulation Market
Insulation Materials
France Foam Insulation Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Global Pipe Insulation Market
Insulation Materials
Flexible Insulation Market
Insulation Materials
Flame-Retardant Foams and Insulation Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Thermal Conductive Polymer Materials Market
Insulation Materials
Silver Ion Antibacterial Insulation Cup Market
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
High Temperature Insulation Market