
 Global Fire Protection Materials Market | 2026-2036
Global Fire Protection Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fire Protection Materials Market Foresight
Modular fire protection systems is shifting buyer preference away from site-mixed applications toward pre-engineered kits with faster installation protocols. 3M leverages its adhesive science portfolio to bundle intumescent coatings with compatible primers and sealants for streamlined specification. Sika anchors its position through direct channel control with construction firms across Europe and Asia-Pacific. Morgan Advanced Materials specializes in high-temperature insulation boards that compete on tested fire resistance duration rather than cost alone.
Fire protection materials encompass chemically formulated substances and engineered assemblies designed to inhibit flame propagation, maintain structural integrity during thermal exposure, or seal penetrations against smoke and gas passage; intumescent coatings expand up to fifty times their original thickness when heated, forming an insulating char layer that protects steel substrates from reaching critical failure temperatures. Intumescent coatings lead product type demand due to their versatility across steel geometries and established performance certification under UL 263 and EN 13381-8 test protocols. Fireproof insulation captures expanding margin pools as energy efficiency codes increasingly bundle thermal and fire performance requirements in single-product specifications. Data centers represent the fastest-growing application segment, driven by insurer mandates for battery storage room protection and hot-aisle containment fire barriers.
NFPA 101 life safety codes in the United States, the EU Construction Products Regulation with its harmonized EN fire classification standards, and China's GB 8624 combustion performance grading collectively shape product formulation requirements and testing burdens for market access. Japan's Ministry of Economy, Trade and Industry (METI) enforces building material flame retardancy standards that influence export-oriented manufacturers' R&D priorities. Stakeholders must monitor evolving electric vehicle battery facility codes and hydrogen infrastructure fire safety guidelines, as these emerging asset classes will redirect specification standards and certification investments across the supply base.
Market Dynamics
Modular fire protection systems are compressing specification cycles as data center operators and industrial facility managers prioritize pre-engineered kits over site-mixed applications. This shift concentrates purchasing power with manufacturers capable of bundling coatings, primers, and sealants into certified assembly packages.
Growth Catalysts
- EU Construction Products Regulation:Harmonized EN fire classification standards mandate stricter fire resistance ratings for high-rise structures across member states, forcing specification upgrades for intumescent coatings and fire-resistant boards.
- Lithium-ion battery storage rooms:Data centers in the United States and Germany are expanding fire safety specifications for battery storage facilities under insurer mandates, creating dedicated demand for hot-aisle containment fire barriers.
- Urban densification in China:Industrial facility upgrades and high-rise construction in Shanghai and Shenzhen drive specification of certified fire protection materials meeting GB 8624 combustion performance grading.
Market Restraints
- Petrochemical input volatility:Epoxy resins and phosphorus-based flame retardants face price instability tied to crude oil derivatives, compressing margins for coating formulators.
- Testing laboratory concentration:UL 263 and EN 13381-8 certification capacity concentrates in Germany and the United States, creating bottlenecks for Asian manufacturers seeking market access.
- Cementitious coating substitution:Spray-applied cementitious materials compete on installed cost for simple steel geometries, limiting intumescent coating penetration in budget-constrained projects.
Strategic Opportunities
- Hydrogen infrastructure codes:Emerging fire safety guidelines for hydrogen production and storage facilities in Japan and South Korea will redirect certification investments toward high-temperature insulation systems.
- Electric vehicle battery plants:Gigafactory construction in Hungary and the United States creates demand for fire-resistant boards and penetration sealing systems in cell production areas.
- Energy efficiency bundling:Thermal and fire performance requirements are merging in single-product specifications, rewarding manufacturers with dual-certified insulation portfolios.
Industry Challenges
- Fire testing engineer scarcity:Qualified personnel capable of interpreting UL 263 and EN 1363-1 test protocols are concentrated in Western Europe and North America, slowing Asian product development cycles.
- Legacy substrate compatibility:Intumescent coatings must demonstrate adhesion to weathered steel and existing paint systems, complicating retrofit specifications for industrial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fire Protection Materials Market |
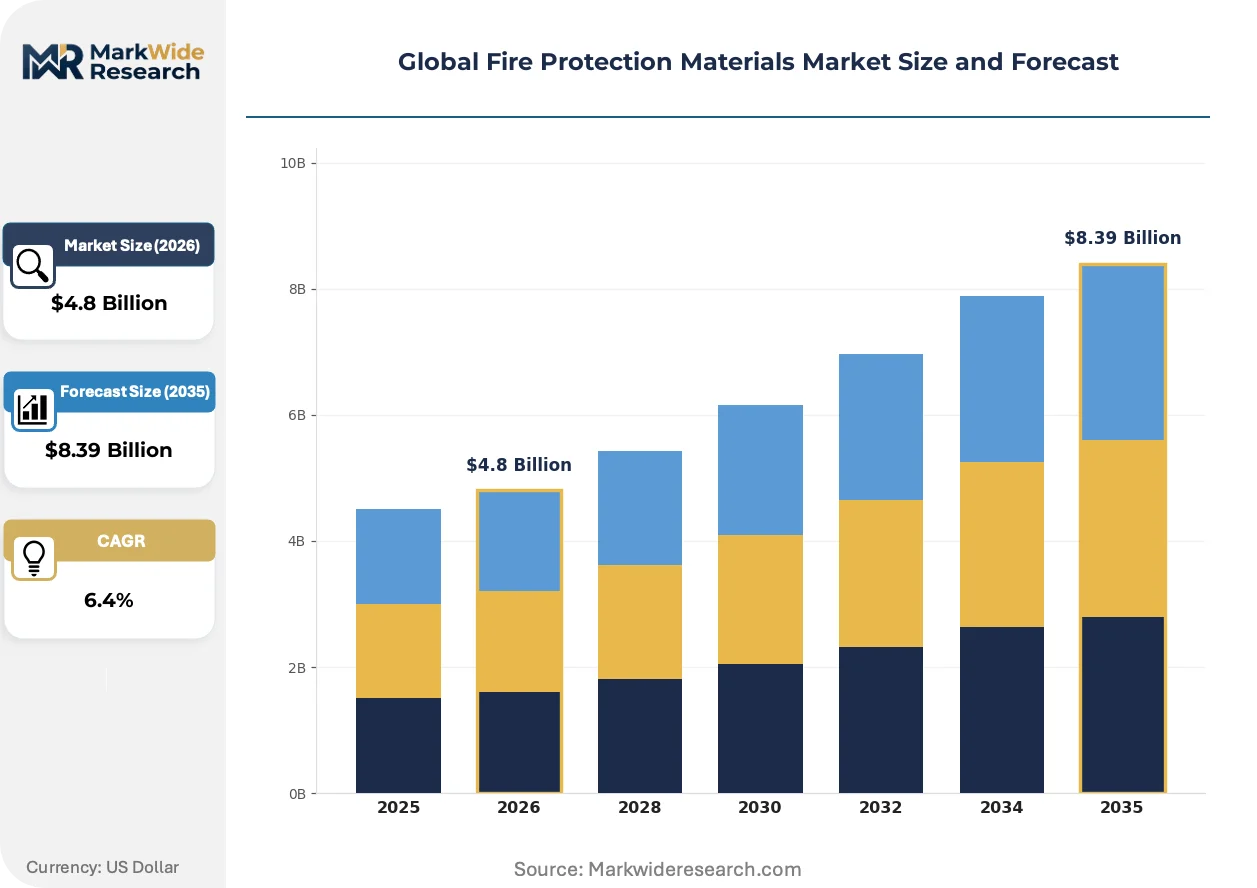
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intumescent Coatings, Fire-Resistant Boards, Fireproof Insulation, Fire Retardant Fabrics, Firestop Sealants Application: Commercial Buildings, Transportation Vehicles, Oil & Gas Facilities, Power Plants, Data Centers Installation Type: New Construction, Renovation Projects, Industrial Plants, Public Infrastructure, Energy Facilities End User: Construction Companies, Manufacturing Units, Facility Management, Government Agencies, Research Laboratories |
| Companies Covered | 3M, Akzo Nobel, BASF, Sika, Hilti, Morgan Advanced Materials, PPG Industries, Hempel, Etex Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fire Protection Materials Market Shifts & Advancements
Fire protection materials are undergoing formulation and delivery model transformation as thermal performance requirements merge with fire safety mandates. Manufacturers are repositioning around bundled certification packages and digital specification tools.
Intumescent coating chemistry is converging with nanotechnology-enhanced char formers to achieve thinner film builds on complex steel geometries. Data center contractors in Virginia and Frankfurt are specifying these advanced formulations to reduce material volume in cable tray and beam applications. The technology is converging with 3D laser scanning for automated thickness verification, compressing installation quality assurance timelines.
REACH regulation amendments are restricting halogenated flame retardants in construction products, forcing reformulation of sealants and coatings across EU member states. Manufacturers with pre-registered alternative chemistries capture specification share as importers face registration deadlines. The restriction most affects penetration sealing systems in high-rise residential towers, where German and French contractors are accelerating substitution timelines.
Buyer specification behavior is fragmenting as facility owners internalize fire engineering capabilities previously outsourced to general contractors. Singapore and Australian mining companies now direct material selection through captive engineering teams, disintermediating traditional distributor influence. This concentration of technical decision-making compresses supplier qualification to manufacturers with in-house fire testing documentation and localized technical service presence.
Global Fire Protection Materials Market Segmentation
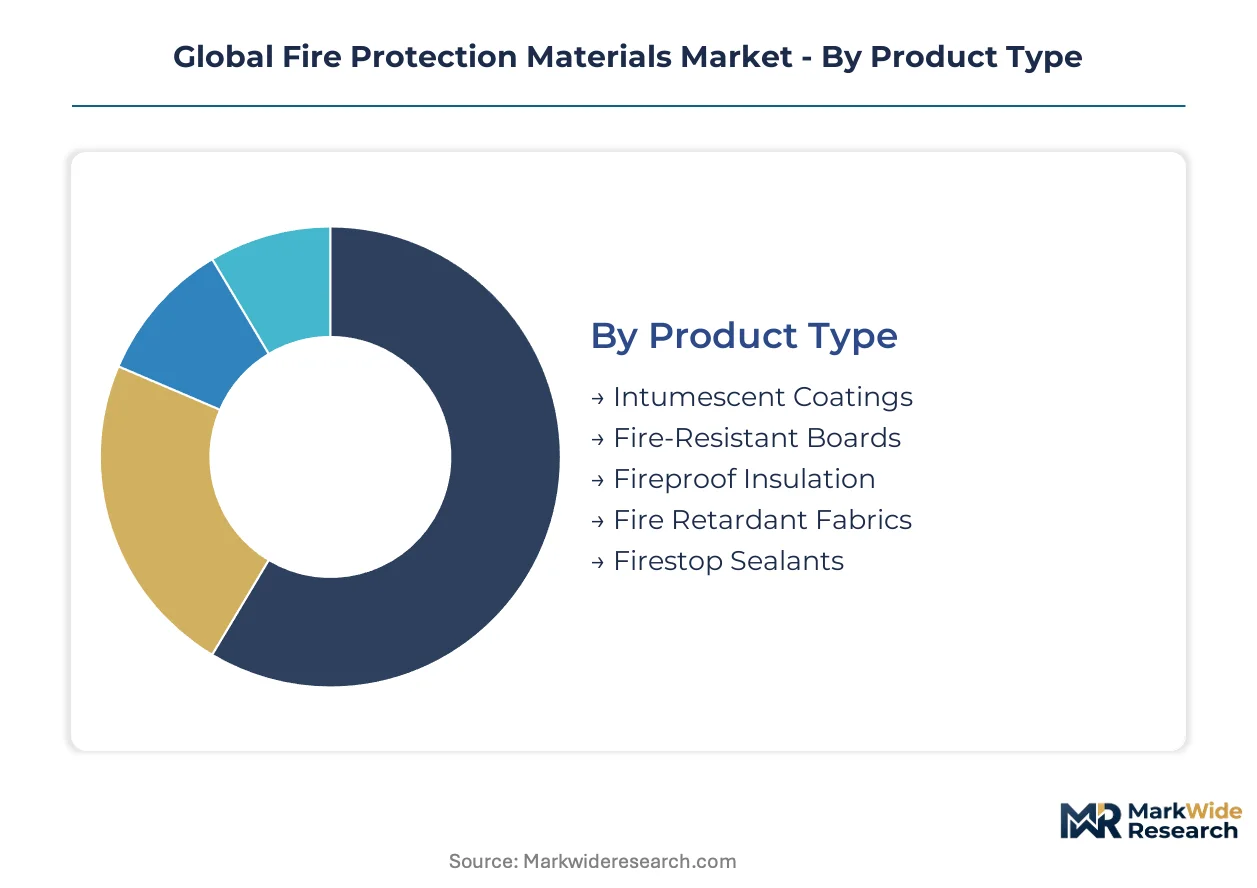
Fire protection materials fragment across four distinct classification axes that shape procurement behavior and technical specification. Product chemistry determines performance certification requirements. Application context dictates fire resistance duration and testing protocols. Installation type influences delivery model preferences between site-applied and pre-engineered systems.
Product Type:
Customization intensity varies sharply across this category, from specification-heavy intumescent formulations to commodity-grade fire retardant textiles.
- Intumescent Coatings:These formulations expand up to fifty times original thickness when heated, creating insulating char layers that protect steel substrates from critical failure temperatures. Demand concentrates in data center construction across Virginia and Frankfurt, where complex beam geometries and cable tray configurations require thin-film builds with automated thickness verification.
- Fire-Resistant Boards:Engineered mineral fiber or calcium silicate assemblies provide passive fire protection for compartmentation and structural encasement. High-rise construction in Shanghai and Shenzhen drives specification of certified boards meeting GB 8624 combustion performance grading, with contractors prioritizing pre-cut dimensional accuracy over field fabrication.
- Fireproof Insulation:Dual-certified thermal and fire performance materials capture expanding specification share as energy codes merge requirements. European contractors bundle these into single-product specifications for high-rise residential towers.
- Fire Retardant Fabrics:Chemically treated textiles inhibit flame propagation in temporary structures and transportation interiors. Mass transit operators in Japan specify these for rolling stock refurbishment programs.
- Firestop Sealants:Elastomeric compounds seal penetrations against smoke and gas passage in compartmentation systems. REACH amendments restricting halogenated chemistries are forcing reformulation across EU member states.
Leading the category by volume: Intumescent Coatings. Growing fastest: Fireproof Insulation.
Application:
Risk-adjusted specification intensity separates high-consequence industrial facilities from standardized commercial construction.
- Commercial Buildings:Office and retail structures drive baseline demand for intumescent steel protection and compartmentation boards. German contractors specify EN-certified systems under harmonized EU Construction Products Regulation mandates.
- Data Centers:Battery storage room protection and hot-aisle containment fire barriers create dedicated demand for advanced formulations. Insurer mandates in the United States and Germany are accelerating specification cycles for this segment, which is expanding most quickly across the analysis window.
- Oil & Gas Facilities:Offshore platforms and refineries require high-temperature insulation systems with tested hydrocarbon fire resistance. North Sea operators specify Morgan Advanced Materials boards for extended duration protection.
- Power Plants:Conventional and renewable generation facilities need cable tray protection and turbine hall compartmentation. Utility procurement concentrates with manufacturers holding in-house fire testing documentation.
- Transportation Vehicles:Rail rolling stock and aerospace interiors demand lightweight fire retardant materials. Japanese METI flame retardancy standards influence export-oriented manufacturer R&D priorities.
Dominant by project count: Commercial Buildings. Steepest specification upgrade trajectory: Data Centers.
Installation Type:
Delivery model preferences split between speed-critical new construction and retrofit-constrained renovation environments.
- New Construction:Greenfield projects favor pre-engineered modular kits with faster installation protocols. 3M bundles coatings with compatible primers and sealants for streamlined specification in data center builds.
- Renovation Projects:Existing building upgrades face legacy substrate compatibility challenges. Intumescent coatings must demonstrate adhesion to weathered steel and existing paint systems, complicating industrial facility retrofit specifications.
- Industrial Plants:Manufacturing facility upgrades prioritize tested fire resistance duration over installed cost. Sika anchors position through direct channel control with construction firms.
- Public Infrastructure:Government-funded projects require extensive certification documentation and localized technical service presence. Singapore and Australian mining companies now direct material selection through captive engineering teams.
- Energy Facilities:Hydrogen production and storage facilities in Japan and South Korea are redirecting certification investments toward high-temperature insulation systems.
Largest volume channel: New Construction. Procurement complexity highest: Renovation Projects.
End User:
Technical decision-making authority concentrates with facility owners possessing captive fire engineering capabilities.
- Construction Companies:General contractors balance installed cost against specification risk in competitive bidding. Cementitious coating substitution limits intumescent penetration in budget-constrained projects.
- Facility Management:Industrial facility managers prioritize pre-engineered kits over site-mixed applications, compressing specification cycles and concentrating purchasing power with bundling-capable manufacturers.
- Government Agencies:Public sector procurement mandates extensive testing documentation. UL 263 and EN 13381-8 certification capacity concentration in Germany and the United States creates bottlenecks for Asian manufacturers seeking access.
- Manufacturing Units:Gigafactory construction in Hungary and the United States creates demand for fire-resistant boards and penetration sealing systems in electric vehicle battery cell production areas.
- Research Laboratories:Specialized facilities require custom-engineered solutions with extended fire resistance ratings. Qualified fire testing engineer scarcity in Western Europe and North America slows product development cycles.
Primary volume purchaser: Construction Companies. Technical specification authority shifting toward: Facility Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the largest share of fire protection materials globally, yet Germany and the United States concentrate certified testing capacity and formulation R&D. This production-consumption asymmetry shapes trade flows and certification bottlenecks across the industry.
United States
Data center construction in Virginia and Texas drives specification of intumescent coatings for battery storage room protection. NFPA 101 life safety codes mandate fire resistance ratings for high-rise structures, forcing upgrades across commercial portfolios. Insurer mandates in Northern Virginia accelerate procurement cycles for hot-aisle containment fire barriers.
Germany
Industrial facility managers in the Ruhr region prioritize pre-engineered fire protection kits over site-mixed applications. The EU Construction Products Regulation enforces harmonized EN fire classification standards for high-rise residential towers. Frankfurt data center operators specify advanced intumescent formulations with automated thickness verification protocols.
China
Urban densification in Shanghai and Shenzhen propels demand for certified fire-resistant boards meeting GB 8624 combustion performance grading. The Ministry of Emergency Management enforces stricter fire safety codes for industrial facility upgrades. High-rise construction clusters in the Pearl River Delta specify intumescent coatings for complex steel geometries.
Japan
Hydrogen infrastructure development in Kansai and Kyushu redirects certification investments toward high-temperature insulation systems. METI enforces building material flame retardancy standards that influence export-oriented manufacturer R&D priorities. Osaka-based contractors specify fire retardant fabrics for rolling stock refurbishment programs.
Singapore
Mining companies and government agencies direct material selection through captive engineering teams, disintermediating traditional distributor influence. The Building and Construction Authority mandates fire resistance ratings for high-rise commercial structures. Marina Bay financial district projects prioritize pre-cut fire-resistant boards with certified dimensional accuracy.
Global Fire Protection Materials Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with adhesive science portfolios and specialized high-temperature insulation manufacturers. Market access concentrates with players bundling coatings, primers, and sealants into certified assembly packages. Two strategic archetypes dominate: diversified materials science conglomerates leveraging cross-product bundling, and focused thermal protection specialists competing on tested fire resistance duration. Capacity expansion and direct channel control with construction firms represent the dominant competitive moves across both archetypes.
Within the diversified conglomerate tier, 3M and BASF occupy positions anchored by adhesive science capabilities and construction chemical portfolios respectively. Sika exemplifies the direct channel control archetype through its engagement with construction firms across European and Asia-Pacific markets. Morgan Advanced Materials represents the specialized high-temperature insulation vector, competing on certified fire resistance performance rather than installed cost alone.
| Leading Market Players |
|---|
| 3M |
| Akzo Nobel |
| BASF |
| Sika |
| Hilti |
| Morgan Advanced Materials |
| PPG Industries |
| Hempel |
| Etex Group |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between UL 263-tested intumescent systems and uncertified commodity alternatives manifests in divergent pricing architectures and procurement channel structures. Premium formulations command project-based pricing with bundled technical service, while commodity-grade cementitious coatings flow through distributor networks on per-unit transactional terms. This tier divergence concentrates margin capture with manufacturers maintaining captive testing relationships in Germany and the United States, while Asian suppliers face certification bottlenecks that compress their pricing power.
Pricing Analysis
Cost-down pressure on standard-grade intumescent coatings accelerates because cementitious alternatives compete aggressively for simple steel geometries in budget-constrained commercial projects. Three-tier pricing structure across premium, standard, and economy levels differentiates primarily by certification tier—UL 263 and EN 13381-8 tested products versus self-declared performance claims—and by after-sales bundling of technical specification support. Margin tightening in the economy tier reflects petrochemical input volatility, particularly epoxy resins and phosphorus-based flame retardants. Facility management buyers demonstrate highest price sensitivity, prioritizing pre-engineered kit costs over lifecycle performance, while data center operators show lowest sensitivity due to insurer mandate compliance requirements.
Supply Chain Analysis
Dual-sourcing requirements from German and U.S. data center operators mandate multi-supplier qualification for intumescent coatings, forcing manufacturers to maintain redundant certification portfolios across UL and EN testing protocols. Geographic supply concentration centers on China for raw material processing, Germany for formulation R&D, and the United States for specification influence. Raw material dependencies rest on epoxy resins from petrochemical feedstocks, phosphorus-based flame retardants, and mineral wool substrates. Single-source vulnerability concentrates in UL 263 testing capacity, where laboratory bottlenecks in Germany and the United States delay Asian manufacturer market access. Distribution runs through direct channel relationships with construction firms for premium tiers and regional distributors for commodity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vertical-integration into raw material processing and captive testing infrastructure as the primary margin-defense mechanism. Players are racing upstream to secure phosphorus-based flame retardant supply and backward into UL/EN certification relationships.
For Market Incumbents: Deepen direct channel control with construction firms by bundling coatings, primers, and sealants into certified assembly packages that cementitious substitutes cannot replicate. Cementitious coating substitution threatens simple-geometry applications, so incumbents must anchor position through specification-engineering relationships with data center operators. Capacity addition in Virginia and Frankfurt data center corridors captures fastest-growing demand, while certification investment in hydrogen infrastructure fire safety guidelines preempts emerging specification standards in Japan and South Korea. For New Entrants and Emerging Players: EU Construction Products Regulation amendments restricting halogenated flame retardants open a window for alternative-chemistry specialists to capture specification share as importers face registration deadlines. Firestop sealant reformulation for high-rise residential towers in Germany and France represents the most penetrable white-space target, given REACH-driven substitution timelines. A go-to-market angle anchored in pre-registered alternative chemistries with documented EN fire classification performance bypasses incumbent formulation lock-in. For Investors and Strategic Acquirers: Re-rating potential sits with specialized high-temperature insulation manufacturers given hydrogen infrastructure code development in Japan and South Korea as a demand catalyst. Long-term viability favors players with dual-certified thermal-fire insulation portfolios that capture energy efficiency bundling trends. Acquisition target archetype: mid-cap specialists with in-house fire testing documentation and localized technical service presence in Asia-Pacific. The signal to watch is electric vehicle battery plant construction permits in Hungary and the United States as inflection indicators for fire-resistant board demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flame Retardant Supply | Captive phosphorus-based feedstock access insulates margin from petrochemical volatility. |
| Long-term Testing Laboratory Partnership | UL 263 and EN 13381-8 certification capacity locks reduce Asian competitor market access timelines. |
| Joint Venture for Hydrogen Infrastructure Certification | METI and South Korean fire safety guideline alignment preempts emerging specification standards. |
| Capacity Expansion in Data Center Corridors | Virginia and Frankfurt proximity captures insurer-mandated battery storage room protection demand. |
| Green Manufacturing Transition for REACH Compliance | Halogen-free formulation platforms capture EU Construction Products Regulation substitution windows. |
Research Methodology
Multi-period observation of certification registration patterns, construction permit flows, and insurer mandate adoption anchored the trend analysis, supplemented by interviews with plant managers at coating formulators, procurement leads at data center developers, technical R&D directors at insulation manufacturers, and distribution channel partners across Europe and Asia-Pacific. Secondary validation drew from customs and trade data, SEC 10-K filings of diversified chemical conglomerates, UL and EN certification databases, and building code amendment tracking. Bottom-up project pipeline assessment triangulated against top-down construction spending forecasts to establish volume baselines.
Segment-weighting across product type, application context, installation method, and end-user decision authority shaped the analytical framework across the projection horizon. Intumescent coatings, fire-resistant boards, fireproof insulation, and firestop sealants were modeled with distinct specification intensity curves. Application segmentation weighted data center construction, commercial buildings, oil and gas facilities, power plants, and transportation vehicles by fire resistance duration requirements. CAGRs derived from regression analysis of historical certification volumes against construction value-added data, with hydrogen infrastructure code development and electric vehicle battery plant construction as industry-specific forecast inputs.
The model assumes a particular technology adoption path for nanotechnology-enhanced char formers; alternative pathways for automated thickness verification integration would alter the outlook for installation labor cost assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity, certification laboratory capacity expansion, and petrochemical input price normalization. Deviation in EU REACH amendment implementation timelines or hydrogen infrastructure fire safety guideline finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Thin Insulation Market
Insulation Materials
Europe MDI-Based PU Technical Insulation Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Hot Insulation Materials Market
Insulation Materials
UK Industrial Insulation Market
Insulation Materials
Fireproofing Materials Market
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
Global Low Smoke Halogen-Free Cable Materials Market
Insulation Materials
Protective Building Materials Market
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
Global Insulation Market