
 USA and Canada Fence Screen Market | 2026-2036
USA and Canada Fence Screen Market Size, Share, and Industry Trends Forecast 2026-2036
USA and Canada Fence Screen Market Analytics
Skilled textile fabrication labor availability is unwinding capacity constraints at domestic mesh converters. FenceScreen, Inc. leverages automated knitting lines to sustain rapid-turn production for stadium windscreen contracts. Tenax Corporation anchors its position through backward integration into virgin polyethylene resin compounding. Midwest Cover Inc. competes on custom dye-matching capabilities for branded construction site wraps.
USA and Canada fence screens are engineered tensioned mesh or solid panels, typically fabricated from UV-stabilized polyethylene, vinyl-coated polyester, or extruded PVC with 70-90% opacity ratings and grommet-reinforced edges for tie-down installation. These products serve primarily as visual barriers, dust containment, and branded signage substrates across active construction zones, sports venues, and residential perimeters. Privacy screen products command the deepest margin pools due to custom sizing and color-matching requirements, while shade cloth volumes dominate in the Sun Belt and Southwest Canada where solar heat mitigation drives specification. Fabric materials lead residential applications for aesthetic flexibility, though vinyl sustains share in commercial and construction segments where chemical resistance and cleanability outweigh first-cost premiums.
OSHA construction site safety standards, EPA stormwater pollution prevention requirements, and Canadian provincial occupational health regulations collectively mandate perimeter containment on active job sites, directly converting compliance obligations into specification demand. Municipal sign ordinances in major metro areas further shape product design by restricting graphic content and imposing wind-load engineering thresholds. Stakeholders must monitor evolving municipal procurement preferences for domestically fabricated content and recycled material minimums as sustainability criteria penetrate public infrastructure spending decisions.
Market Dynamics
OSHA and Canadian provincial workplace safety codes are tightening perimeter containment standards, converting compliance obligations into specification demand across commercial construction corridors from Toronto through the Great Lakes to Chicago.
Growth Catalysts
- EPA Stormwater Pollution Prevention:Active construction sites in California and Ontario must deploy perimeter containment to intercept sediment runoff, directly mandating fence screen installation.
- Solar Heat Mitigation:Shade cloth specifications dominate across the Sun Belt and Southwest Canada as building codes incorporate thermal comfort requirements for outdoor worker protection.
- Stadium Renovation Cycles:Sports venue operators in Texas and Florida are replacing legacy windscreens with branded mesh systems that integrate digital printing for sponsorship revenue.
Market Restraints
- Virgin Polyethylene Resin Volatility:Backward-integrated converters like Tenax Corporation face margin compression when ethylene feedstock prices spike, squeezing non-integrated competitors harder.
- Domestic Knitting Capacity Concentration:Automated textile fabrication lines cluster in the Carolinas and Ontario, creating geographic supply risk during hurricane or winter storm disruptions.
- Vinyl Substitution Threat:Solid PVC panels compete with mesh for chemical-resistant applications, though weight and wind-load engineering limits restrict their deployment.
Strategic Opportunities
- Recycled Content Mandates:Municipal procurement preferences in Chicago and Vancouver are beginning to specify minimum post-consumer polyethylene content, rewarding early movers with reformulated compounds.
- Residential Privacy Segment:Custom dye-matching and sizing capabilities remain underpenetrated in suburban Toronto and Dallas-Fort Worth exurbs where homeowner association aesthetic codes proliferate.
- E-Commerce Channel Expansion:Direct-to-contractor platforms are displacing traditional distribution for standardized construction site wraps, compressing lead times from weeks to days.
Industry Challenges
- Skilled Knitting Technician Shortage:Automated line operation and pattern programming expertise is scarce in the Great Lakes textile corridor, constraining rapid-turn production capacity.
- Municipal Sign Ordinance Fragmentation:Wind-load engineering thresholds and graphic content restrictions vary block-by-block in major metros, forcing custom engineering for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA and Canada Fence Screen Market |
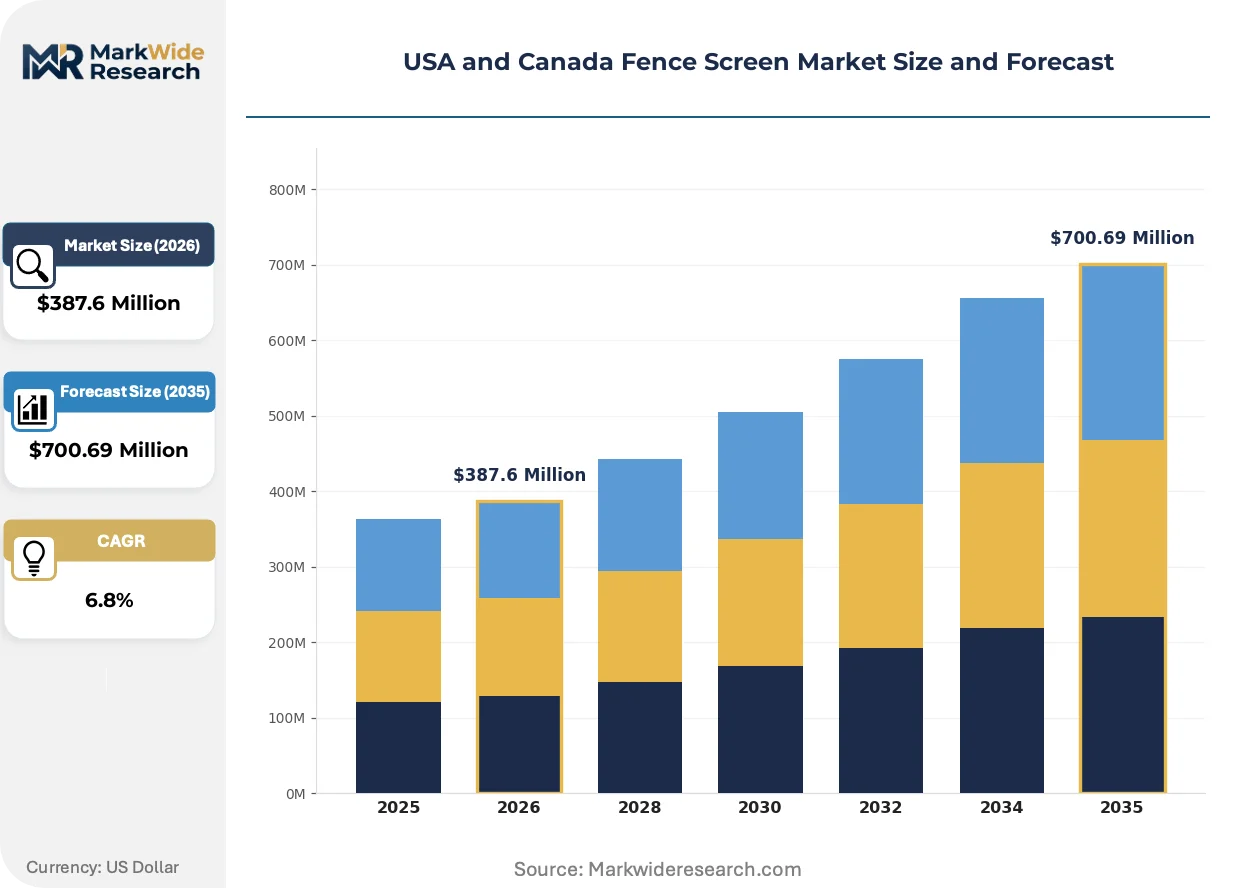
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Privacy Screen, Shade Cloth, Windscreen, Decorative Panel Material: Vinyl, Fabric, Wood, Metal Application: Residential, Commercial, Construction, Sports Facilities Sales Channel: Retail, Online, Wholesale, Distributors |
| Companies Covered | FenceWrap, Ball Fabrics, FenceScreen, Inc., Fence Screen Depot, Tenax Corporation, Midwest Cover Inc., PrivacyScreen.com, Seegars Fence Company, Pexco LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA and Canada Fence Screen Market Evolving Landscape
Digital printing integration and sustainable material formulations are reshaping product specifications, while procurement channels fragment across traditional distribution and direct digital platforms.
Recycled-content polyethylene mesh is fragmenting the specification landscape for construction site containment. Municipal contractors in Vancouver and Chicago are piloting screens with 30-50% post-consumer resin content to meet emerging sustainability procurement criteria. This material shift is fragmenting supplier tiers, separating compounders with captive recycling capabilities from converters dependent on virgin resin supply chains.
OSHA's updated construction site safety standards are mandating higher-visibility perimeter containment with specified opacity ratings and reflective striping. The industrial consequence is a phasing out of legacy burlap and non-rated fabrics that previously served informal barrier roles. California and Ontario job sites are responding fastest, with safety managers specifying UV-stabilized polyethylene with 90% opacity and grommet-reinforced edges as baseline compliance.
Contractor buying patterns are compressing specification cycles from annual planning to just-in-time procurement through mobile-enabled platforms. Traditional distribution relationships in the Sun Belt are being disrupted by direct manufacturer portals that offer real-time dye-matching visualization and 48-hour turnaround. This behavioral shift is most visible in Texas and Florida commercial construction, where project superintendents now source branded wraps via smartphone rather than through established distributor networks.
USA and Canada Fence Screen Market Segmentation
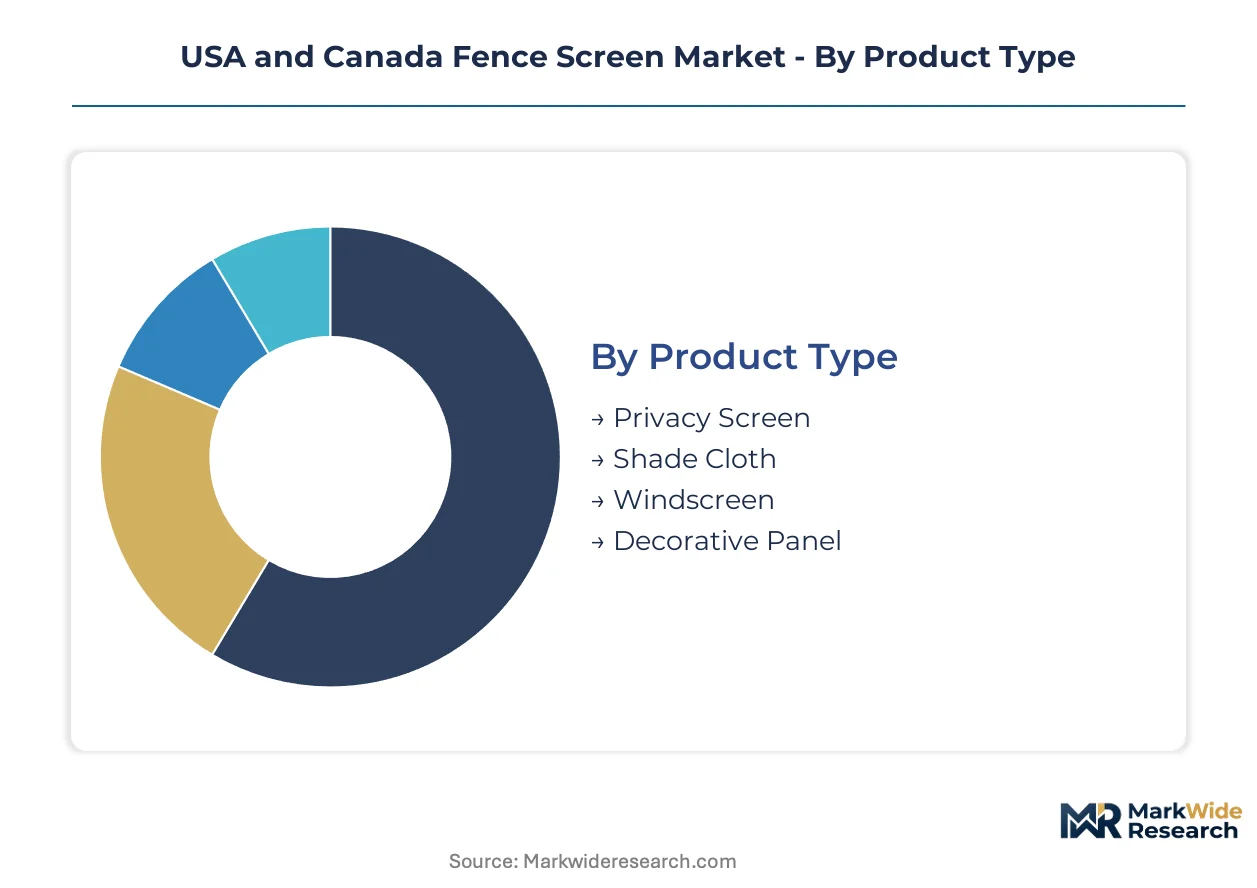
Segmentation in the USA and Canada fence screen market reveals divergent margin structures across material technologies and procurement channels. Specification requirements vary sharply between OSHA-mandated construction containment and aesthetic-driven residential privacy applications.
Product Type:
Margin pools concentrate in custom-fabricated solutions where sizing flexibility and color-matching capabilities command pricing premiums over standardized construction wraps.
- Privacy Screen:UV-stabilized polyethylene or vinyl-coated polyester panels with 90% opacity ratings serve homeowner association-compliant residential perimeters across suburban Toronto and Dallas-Fort Worth exurbs. Custom dye-matching for branded aesthetic requirements generates the deepest margin pools in this segment.
- Shade Cloth:Knitted HDPE mesh with 70-80% UV block specifications dominates procurement across the Sun Belt and Southwest Canada where municipal building codes incorporate thermal comfort mandates for outdoor worker protection.
- Windscreen:Tensioned mesh systems with grommet-reinforced edges serve sports venue perimeter containment across Texas and Florida stadium renovation cycles.
- Decorative Panel:Perforated metal or routed wood substrates address high-end residential architectural screening in coastal California and Vancouver metro markets.
The dominant share belongs to Privacy Screen, while Shade Cloth is closing the gap fastest.
Material:
Cost tier stratification separates commodity polyethylene converters from specialty compounders with captive resin capabilities.
- Vinyl:Extruded PVC and vinyl-coated polyester substrates deliver chemical resistance and cleanability specifications required by California EPA stormwater compliance officers for sediment containment at active construction sites.
- Fabric:Knitted polyethylene mesh fabricated on automated lines in the Carolinas and Ontario textile corridor serves high-volume stadium windscreen and construction barrier contracts with rapid-turn production cycles.
- Wood:Cedar and pressure-treated lumber panels address residential privacy preferences in Pacific Northwest and Northeast markets where natural aesthetic integration commands specification.
- Metal:Aluminum and steel perforated systems serve permanent architectural screening applications with wind-load engineering thresholds exceeding mesh capabilities.
Fabric holds the volume leadership position, though Vinyl sustains share in commercial segments where regulatory compliance outweighs first-cost premiums.
Application:
Customer type determines procurement cycle length and customization depth, with construction superintendents demanding just-in-time delivery versus residential homeowners prioritizing aesthetic consultation.
- Residential:Custom sizing and color-matching requirements proliferate across homeowner association-governed developments in suburban Ontario and Texas exurbs where aesthetic codes mandate perimeter screening compliance.
- Commercial:Branded wraps with digital printing integration serve retail and office property managers in Chicago and Toronto seeking sponsorship revenue from perimeter advertising substrates.
- Construction:OSHA and provincial workplace safety codes mandate 90% opacity perimeter containment with reflective striping across active job sites in California and Ontario, converting compliance obligations into specification demand.
- Sports Facilities:Stadium operators in Texas and Florida are replacing legacy windscreens with mesh systems integrating digital printing for sponsorship revenue generation during renovation cycles.
Construction anchors volume demand, while Residential privacy applications are expanding most quickly.
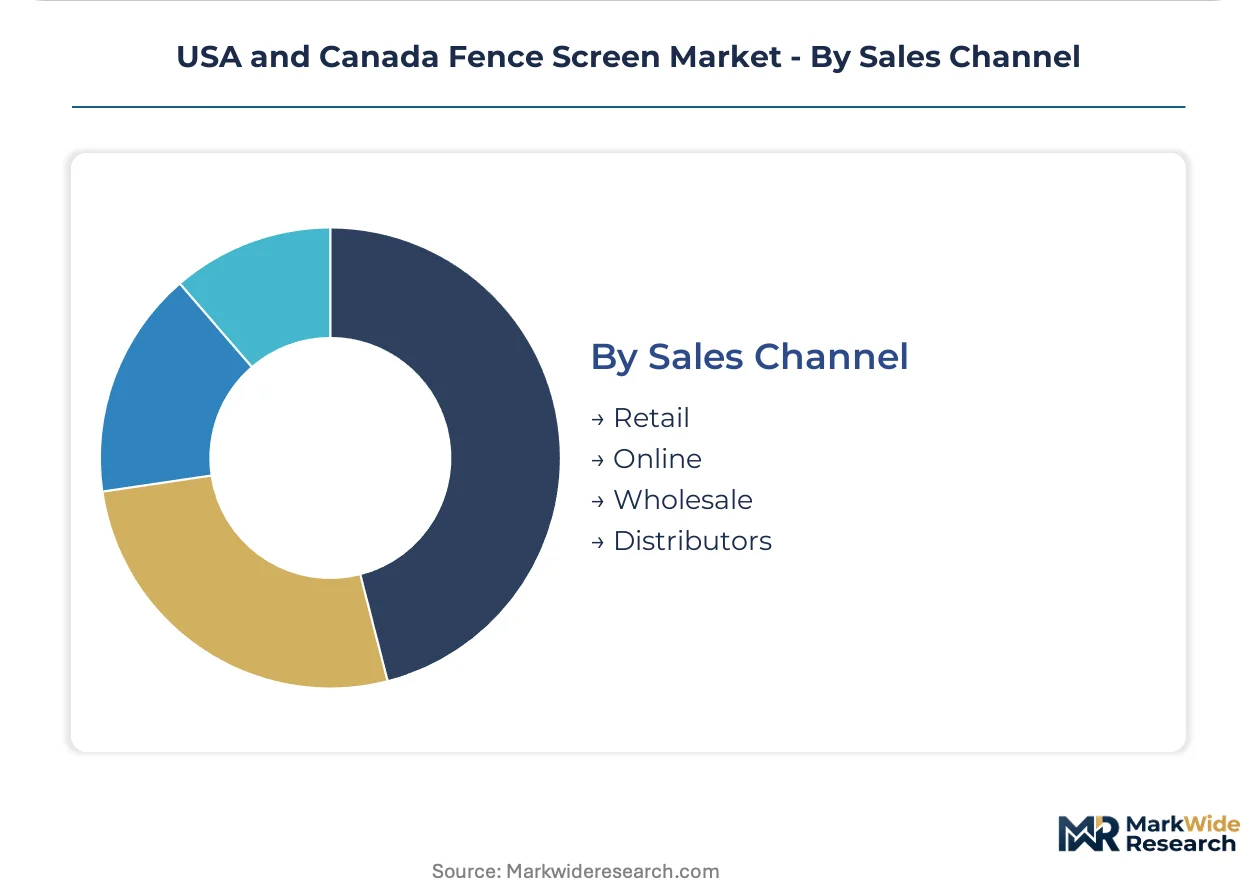
Sales Channel:
Supply concentration in automated knitting corridors shapes distribution economics, with geographic proximity to Carolinas and Ontario production assets influencing lead-time competitiveness.
- Retail:Big-box and specialty hardware chains serve standardized residential privacy screen procurement in Sun Belt markets where immediate availability outweighs customization requirements.
- Online:Direct-to-contractor platforms with real-time dye-matching visualization are displacing traditional distribution for standardized construction wraps across Texas and Florida commercial markets.
- Wholesale:Volume purchasing agreements serve multi-site construction managers across the Great Lakes corridor with consolidated procurement for Toronto-through-Chicago project portfolios.
- Distributors:Established networks retain specification influence in municipal and institutional procurement where established relationships and credit terms sustain channel position.
Distributors retain the largest share in institutional procurement, though Online channels are gaining share fastest in commercial construction segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the bilateral market: Canadian provinces emphasize cold-climate durability specifications while US demand concentrates in OSHA-mandated construction corridors and Sun Belt solar mitigation applications.
Ontario
Provincial workplace safety codes under Ontario's Ministry of Labour mandate high-visibility perimeter containment on Toronto-area construction sites. The Great Lakes textile corridor hosts automated knitting operations serving rapid-turn contracts. Kitchener-Waterloo converters supply custom dye-matched privacy screens for suburban homeowner association developments.
California
EPA stormwater pollution prevention requirements drive sediment interception specifications across active job sites from Los Angeles to the Bay Area. Cal/OSHA enforcement of updated construction safety standards mandates 90% opacity ratings with reflective striping. San Diego fabricators specialize in UV-stabilized polyethylene for coastal wind-load applications.
Texas
Stadium renovation cycles in Dallas-Fort Worth and Houston generate demand for branded mesh windscreens integrating digital printing capabilities. Municipal procurement across the state increasingly specifies thermal comfort requirements for outdoor worker protection. Austin-area distributors compete on just-in-time delivery through mobile-enabled contractor platforms.
British Columbia
Vancouver municipal contractors pilot recycled-content screens with post-consumer resin minimums under emerging sustainability procurement criteria. The province's occupational health regulations align with federal Canadian standards for perimeter containment. Lower Mainland fabricators serve Pacific Northwest aesthetic preferences with natural-tone privacy products.
Florida
Sports venue operators from Miami to Tampa replace legacy windscreens with sponsorship-integrated mesh systems during renovation cycles. Building codes incorporate solar heat mitigation mandates that specify shade cloth for outdoor worker protection. Orlando-area wholesale distributors retain influence in institutional procurement through established credit relationships.
USA and Canada Fence Screen Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward-integrated compounders controlling resin supply chains while regional converters compete on customization velocity. The structure rewards scale in standardized construction wraps and agility in residential privacy applications. Three archetypes dominate: resin-integrated manufacturers, automated knitting specialists, and custom fabrication shops. Competitive moves concentrate on geographic expansion into underserved exurbs and portfolio diversification toward recycled-content formulations.
Among North American fabricators, Tenax Corporation exemplifies the resin-integrated archetype through captive polyethylene compounding capabilities. FenceScreen, Inc. occupies a position within the automated production tier, while Midwest Cover Inc. represents specialists competing on custom dye-matching and sizing flexibility. These three entities anchor the competitive topology without exhausting its diversity.
| Leading Market Players |
|---|
| FenceWrap |
| Ball Fabrics |
| FenceScreen, Inc. |
| Fence Screen Depot |
| Tenax Corporation |
| Midwest Cover Inc. |
| PrivacyScreen.com |
| Seegars Fence Company |
| Pexco LLC |
| Others |
Value Network & Pricing Analysis
Automated knitting line utilization rates in the Carolinas and Ontario textile corridor determine price floors across standardized construction wrap tiers, with excess capacity compressing spot-market quotes while custom dye-matching capabilities sustain premium residential privacy margins.
Pricing Analysis
Long-term offtake agreements dominate procurement for multi-site construction managers across the Toronto-Chicago corridor, while spot purchasing prevails for just-in-time stadium renovation contracts in Texas and Florida. Price differentiation separates OSHA-compliant 90% opacity screens with reflective striping from economy-grade residential privacy products lacking certification documentation. Pricing pressure intensifies in standardized construction wraps as direct-to-contractor platforms disintermediate traditional distributor markups. Municipal contractors in Vancouver and Chicago exhibit lowest price sensitivity due to sustainability procurement mandates specifying recycled-content minimums.
Supply Chain Analysis
The United States and Canada anchor automated textile fabrication, with the Carolinas and Ontario corridor hosting concentrated knitting capacity serving rapid-turn production cycles. Virgin polyethylene resin draws from Gulf Coast petrochemical complexes, while UV stabilizers and colorant masterbatches source from specialty chemical producers in Ohio and New Jersey. Supply chain risk centers on hurricane and winter storm disruptions to the Carolinas-Ontario knitting corridor. Distribution runs through wholesale networks for institutional procurement and direct manufacturer portals for commercial construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multi-site construction managers consolidating procurement across Toronto-through-Chicago project portfolios, fragmenting specification influence away from established distributor relationships.
For Market Incumbents: Shield margin position by securing backward integration into recycled polyethylene compounding capabilities before Vancouver and Chicago municipal mandates harden into binding specifications. Prioritize capacity addition in Ontario to reduce geographic supply risk during winter storm disruptions. Channel control through exclusive distributor relationships retains value in institutional procurement where credit terms sustain loyalty. For New Entrants and Emerging Players: Certification fast-tracks through OSHA-compliant 90% opacity testing protocols open specification access to California and Ontario construction sites where safety managers mandate documented compliance. White-space concentration exists in suburban Dallas-Fort Worth and Toronto exurbs where homeowner association aesthetic codes proliferate unmet custom dye-matching demand. Direct-to-contractor platform deployment with real-time visualization tools captures procurement share from traditional wholesale networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated knitting specialists serving multi-year stadium windscreen contracts with integrated digital printing capabilities. Long-term viability over the projection horizon favors compounders with captive recycling infrastructure positioned for municipal sustainability mandate expansion. The signal to watch is recycled-content specification adoption velocity across Chicago and Vancouver public procurement databases.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Formulation | Captures municipal procurement share in Vancouver and Chicago where sustainability minimums are hardening. |
| Automated Knitting Scale-Up | Reduces unit costs for standardized OSHA-compliant construction wraps across the Great Lakes corridor. |
| Direct-to-Contractor Platform Launch | Compresses lead times from weeks to days in Texas and Florida commercial construction procurement. |
| Custom Dye-Matching Capability Investment | Penetrates suburban Toronto and Dallas-Fort Worth exurbs with homeowner association aesthetic mandates. |
| Backward Integration into Resin Compounding | Insulates margin from ethylene feedstock volatility affecting non-integrated converters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, OSHA regulatory filings, EPA stormwater compliance records, and municipal procurement databases. Primary interviews engaged construction site safety managers, textile fabrication plant engineers, distributor procurement leads, and municipal contracting officers across California, Ontario, Texas, and British Columbia. Secondary validation drew from Canadian provincial workplace safety code updates, SEC 10-K disclosures from resin-integrated manufacturers, and stadium operator capital expenditure plans. Bottom-up volume estimates triangulated against top-down construction spending correlations.
Segmentation dimensions modeled include material technology, opacity rating tier, application type, and procurement channel structure across the projection horizon. CAGRs derived from regression analysis against construction permit volumes, OSHA enforcement trend indices, and municipal sustainability procurement adoption curves. Industry-specific forecast inputs incorporated UV stabilizer cost trajectories and digital printing equipment deployment rates in the Sun Belt.
Underlying assumptions cover sustained OSHA and provincial workplace safety code enforcement, stable ethylene feedstock pricing, and gradual municipal recycled-content mandate adoption, with deviation risk concentrated in hurricane disruption frequency to Carolinas knitting capacity and sudden tariff imposition on polyethylene resin imports. Recalibration cycles align with material shifts in municipal procurement database specifications and OSHA construction safety standard update announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
Europe AAC Blocks and Panels Market
Building & Construction Materials
Barn Door Hardware Market
Building & Construction Materials
US and Canada Corner Beads and Caps Market
Building & Construction Materials
Germany Construction Chemicals Market
Building & Construction Materials
PVC Window Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Roofing Materials Market
Building & Construction Materials
Wood Shingles Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
Acoustic Doors Market
Building & Construction Materials
North America Concrete Conditioner Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
Floor Screeds Market