
 Farm Equipment Rental Market | 2026-2036
Farm Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Farm Equipment Rental Market Intelligence
The gap between premium precision-ag fleets and commodity-grade rental pools is rebalancing across North American farm country. John Deere sustains technology leadership through integrated telemetry and autosteer subscriptions on leased tractors. Mahindra & Mahindra competes on cost-optimized utility tractor rentals for smallholder corridors in South Asia. CNH Industrial anchors its position with Case IH and New Holland dual-brand coverage across Midwestern dealer networks.
Farm equipment rental denotes the temporary provision of agricultural machinery—typically diesel-powered implements rated from 40 to 600 horsepower—through contractual arrangements rather than capital purchase, enabling growers to match machine capacity to seasonal field windows without ownership burdens. Tractor rentals dominate transaction volume given their universal tillage and transport utility, while harvester rentals command premium daily rates tied to narrow grain moisture windows. Short-term rental structures are expanding fastest among contract farming enterprises that require specialized planters for two-week sowing periods, whereas lease financing retains structural importance among dairy cooperatives seeking multi-year milking parlor equipment commitments.
US EPA Tier 4 Final regulations and EU Stage V emissions frameworks are reshaping fleet composition by accelerating retirement of pre-compliant diesel stock and elevating rental premiums for newer machines. India's CEA agricultural electrification directives and BIS safety certification requirements for power-tiller operation are creating parallel compliance layers for rental operators serving smallholder clusters. Stakeholders must weigh residual value risk against rental rate premiums as emissions standards tighten and battery-electric prototypes enter field trials.
Market Dynamics
US EPA Tier 4 Final emissions mandates are accelerating diesel fleet turnover across North American rental pools, forcing operators to retire pre-compliant machines and absorb residual value losses while Brazilian and Indian regulators draft parallel standards.
Growth Catalysts
- Precision Agriculture Telemetry:Integrated autosteer and yield-mapping subscriptions on leased tractors enable growers to access Tier 4 Final-compliant horsepower without capital outlay. Large-scale corn and soybean operations in Iowa and Illinois are expanding rental contracts to cover entire planting windows.
- India's CEA Electrification Directives:Rural grid extension programs are creating rental demand for electric power-tillers and small tractors in Bihar and Uttar Pradesh smallholder corridors. Equipment lessors are adding battery-electric units to capture subsidized deployment opportunities.
- Seasonal Demand Concentration:Brazil's Mato Grosso soybean belt experiences acute machinery shortages during narrow planting and harvest windows. Rental operators are pre-positioning combines and planters to capture premium daily rates when local dealer inventory depletes.
Market Restraints
- Steel and Component Cost Volatility:Hydraulic systems and high-strength chassis materials face input price swings that compress rental fleet margins. Operators struggle to pass through cost spikes via rate adjustments due to fixed seasonal contract structures.
- Dealer Network Concentration:Midwestern US farm equipment distribution remains anchored by legacy Case IH and New Holland dealer territories. Independent rental operators face parts availability delays and service access barriers outside authorized networks.
- Residual Value Collapse Risk:Pre-Tier 4 Final diesel tractors and harvesters face accelerated obsolescence as California CARB and EU Stage V standards tighten. Rental fleet owners holding aged inventory face write-downs that erode balance sheet capacity.
Strategic Opportunities
- Contract Farming Expansion:Enterprise sowing services in Vietnam and Indonesia require specialized precision planters for 10-14 day windows. Rental operators can bundle equipment with agronomic advisory to capture recurring revenue streams.
- EU Green Deal Agricultural Transition:Carbon credit mechanisms and CAP eco-scheme payments are incentivizing lower-emission machinery adoption. Rental fleets positioning battery-electric prototypes for German and French field trials access subsidized pilot funding.
- Telematics-Enabled Usage Pricing:Hourly engine-load metering and GPS-verified acreage tracking allow rental contracts to shift from flat daily rates to performance-based billing. Large grain cooperatives in Kansas and Nebraska prefer this cost allocation model.
Industry Challenges
- Certified Technician Scarcity:EPA Tier 4 Final aftertreatment systems and precision-ag electronics require specialized diagnostic training. Rental operators in rural Texas and Saskatchewan report 90-day lead times for qualified service hires.
- Legacy Fleet Integration Complexity:Older mechanical-drive tractors lack CAN bus connectivity for telemetry overlay. Rental companies maintaining mixed-age fleets face dual inventory and training cost structures.
- Cross-Border Regulatory Friction:Equipment moving between US, Canadian, and Mexican rental pools must satisfy diverging emissions enforcement timelines. Transport logistics and compliance documentation create administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Farm Equipment Rental Market |
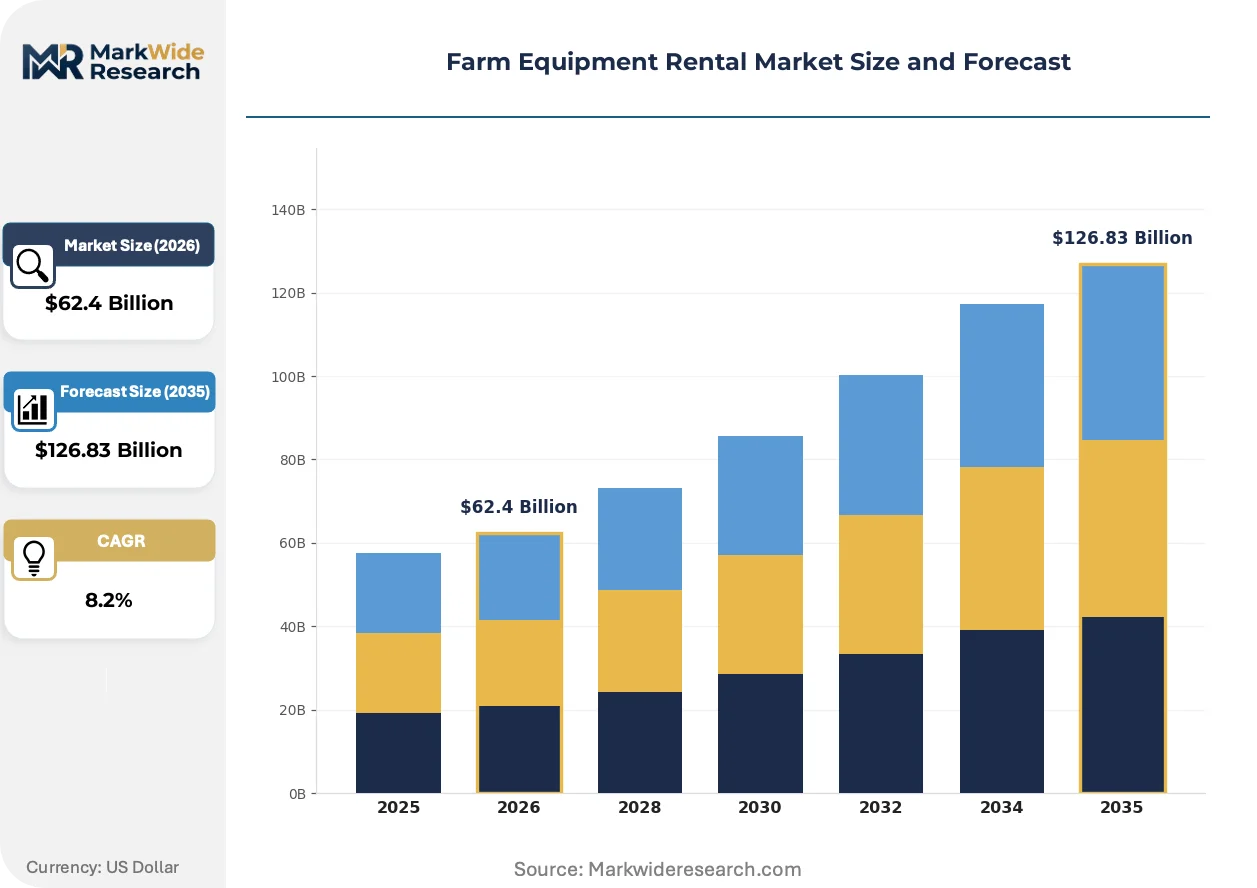
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $126.83 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Tractors, Plows, Harvesters, Seeders Service Type: Short-term Rental, Long-term Rental, Lease Financing, Rent-to-Own Industry Vertical: Agriculture, Horticulture, Landscaping, Forestry Customer Type: Farmers, Small Holders, Agricultural Cooperatives, Contractors |
| Companies Covered | Kubota Corporation, John Deere, Deere & Company, The Pape Group, JCB, CNH Industrial, Mahindra & Mahindra, Premier Equipment Rentals, AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Farm Equipment Rental Market Strategic Shifts & Innovations
Telemetry integration and emissions compliance are converging to reshape fleet economics, with rental operators repositioning around data services rather than pure asset utilization.
Autonomous tractor platforms from John Deere and smaller precision-ag startups are automating field operations previously requiring operator presence. Large-scale wheat and corn growers in North Dakota and Manitoba are piloting supervised autonomy for overnight tillage shifts. This compression of labor dependency is automating the traditional constraint on equipment utilization rates during narrow weather windows.
EU Stage V emissions frameworks and California CARB off-road diesel regulations are mandating diesel particulate filters and selective catalytic reduction across 75-600 horsepower categories. Fleet operators face retrofit-or-retire decisions that favor newer rental machines with factory-installed compliance. German and French cereal producers are prioritizing leased equipment with verified Stage V certification to avoid operational restrictions in low-emission zones.
Flexible rental tenure structures are displacing traditional seasonal fixed contracts across Australian broadacre farming and Argentine soybean operations. Growers now specify equipment access in 48-hour increments tied to soil moisture conditions rather than calendar dates. This behavioral shift is most visible in South Australia's Murray-Darling basin, where irrigation timing unpredictability makes rigid rental commitments uneconomical.
Farm Equipment Rental Market Segmentation
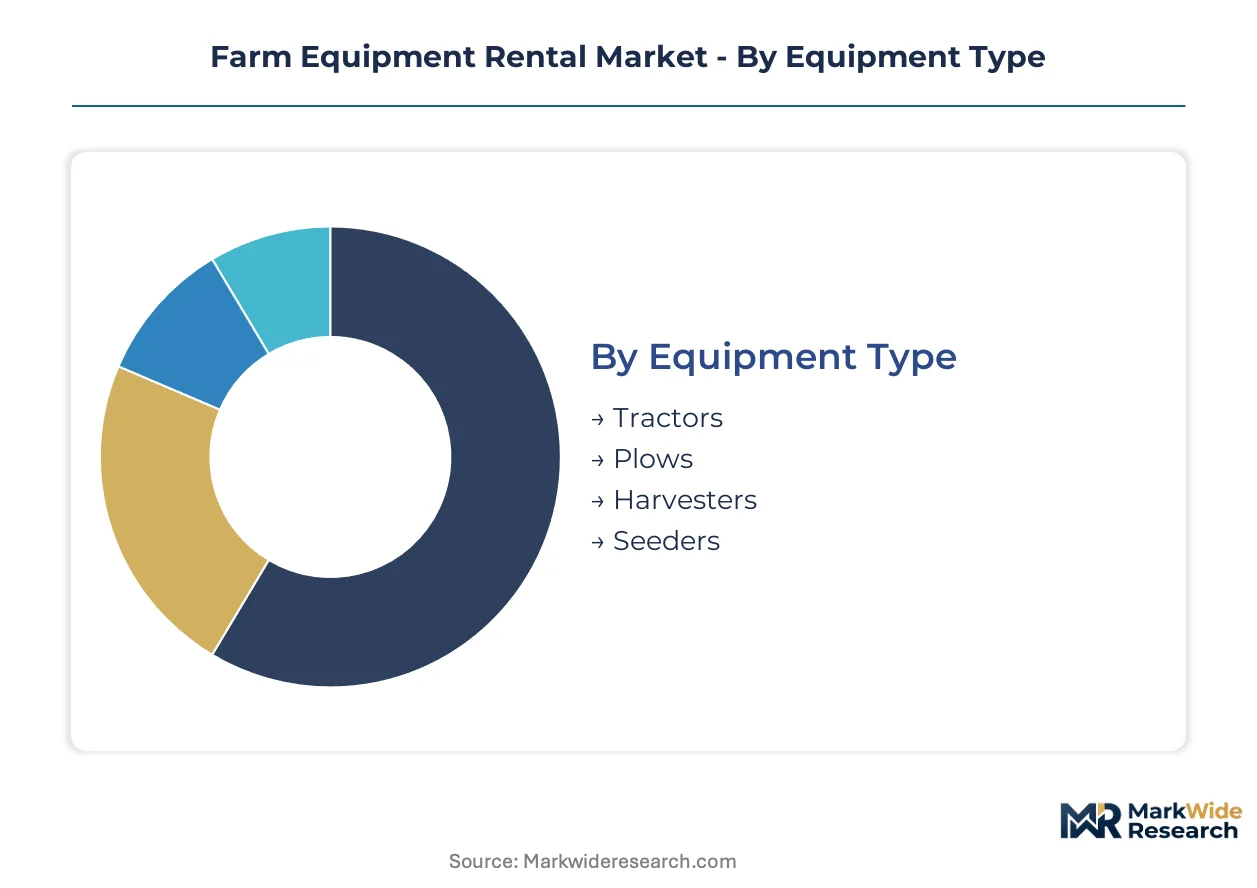
Equipment rental decisions in agriculture hinge on matching machine capability to narrow seasonal windows without absorbing residual value risk. The segmentation structure reflects how growers balance capital constraints against operational flexibility across diverse cropping systems and tenure arrangements.
Equipment Type:
Buyers prioritize horsepower-to-acreage matching and emissions compliance tier when selecting rental machinery for specific field operations.
- Tractors:Diesel-powered units from 40 to 600 horsepower serve universal tillage, planting, and transport functions across grain and specialty crop systems. Iowa and Illinois corn operations dominate rental volume, driven by EPA Tier 4 Final compliance requirements that make newer leased machines preferable to aged owned fleets.
- Harvesters:Combines and forage harvesters command premium daily rates tied to narrow grain moisture windows and perishable crop timing. Brazil's Mato Grosso soybean belt generates acute seasonal demand spikes when local dealer inventory depletes during concentrated harvest periods.
- Plows:Tillage implements attach to rented or owned tractor power units for primary and secondary soil preparation. Demand concentrates in wheat-growing regions of Kansas and Nebraska where conventional tillage persists despite no-till adoption trends.
- Seeders:Precision planters and air seeders enable accurate seed placement at variable rates for optimized plant populations. Contract farming enterprises in Vietnam and Indonesia require specialized units for compressed 10-14 day sowing windows.
Tractors lead on scale; harvesters lead on momentum.
Service Type:
Tenure structure selection reflects working capital availability and equipment utilization predictability across different farm enterprise types.
- Short-term Rental:Daily or weekly contracts spanning 48-hour increments to seasonal windows match equipment to weather-dependent field conditions. Australian broadacre growers in the Murray-Darling basin favor this flexibility given irrigation timing unpredictability.
- Lease Financing:Multi-year contractual arrangements with purchase options at term end suit dairy cooperatives and permanent crop operators seeking milking parlor or orchard equipment stability. Balance sheet treatment as operating leases preserves borrowing capacity for land acquisition.
- Long-term Rental:Seasonal or annual contracts without ownership transfer provide medium-duration equipment access for crop rotation transitions. Mid-sized grain operations in the US Corn Belt use these structures for precision planters during narrow planting windows.
- Rent-to-Own:Rental payments accumulate toward eventual title transfer, bridging growers from rental dependency toward ownership. Smallholder corridors in South Asia apply this structure to utility tractors where capital purchase remains prohibitive.
Short-term rental leads on scale; lease financing leads on momentum.
Industry Vertical:
End-use sector determines equipment specification requirements and seasonal intensity patterns that shape rental demand profiles.
- Agriculture:Row crop and broadacre grain production generates the dominant share of rental transaction volume. Corn, soybean, and wheat operations in North Dakota and Manitoba drive demand for high-horsepower tractors and combines with telemetry integration.
- Horticulture:Specialty crop and vegetable production requires specialized planting, cultivation, and harvesting equipment with precise depth and spacing control. California Central Valley operators rent bed shapers and mechanical harvesters for lettuce and tomato operations.
- Landscaping:Commercial turf maintenance and estate management utilize compact utility tractors and rotary mowers on shorter rental cycles. Municipal and golf course contracts in Florida and Arizona generate recurring seasonal demand.
- Forestry:Logging and land clearing operations rent feller bunchers, skidders, and forwarders for concentrated harvest periods. Pacific Northwest timber operations and Brazilian eucalyptus plantations drive specialized equipment requirements.
Agriculture leads on scale; horticulture leads on momentum.
Customer Type:
Entity scale and organizational structure dictate rental contract terms, service level expectations, and equipment sophistication preferences.
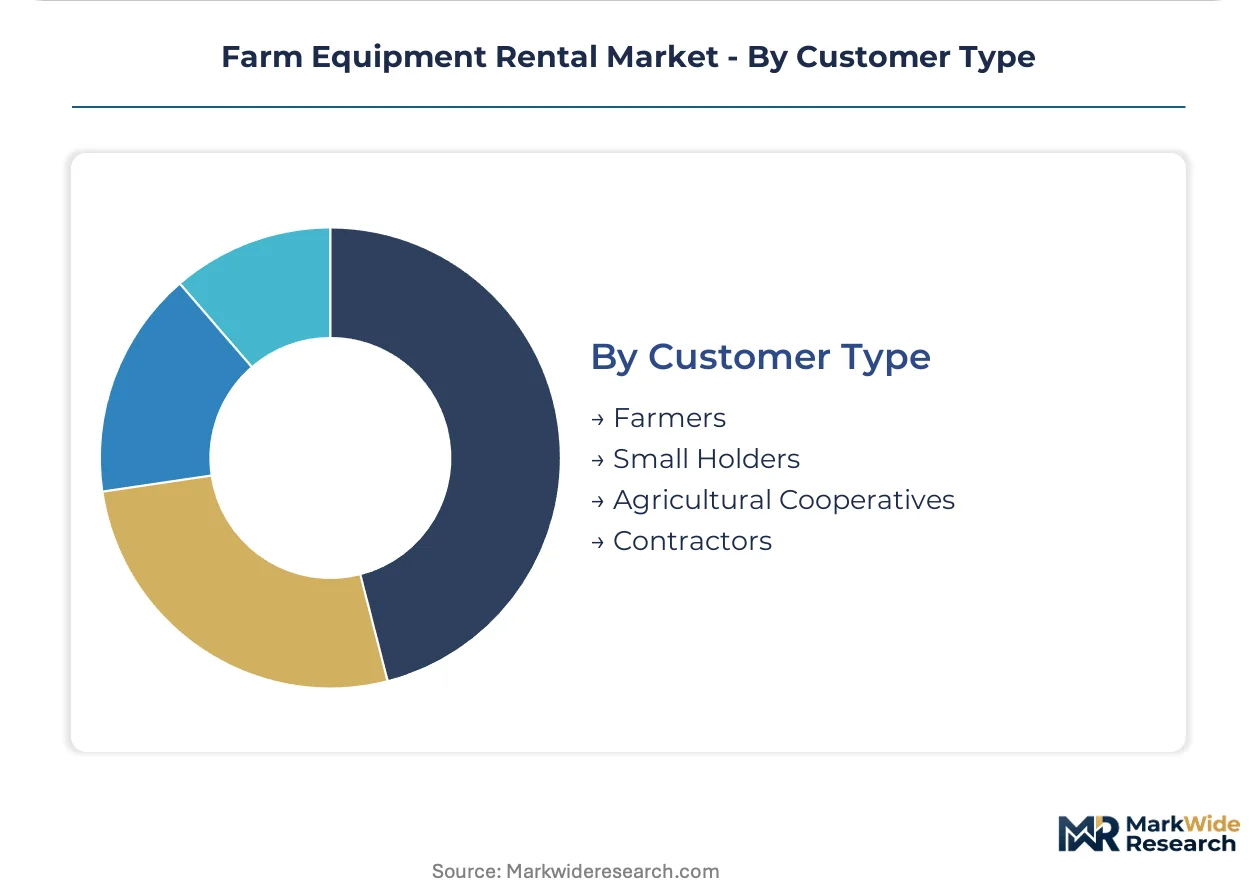
- Farmers:Individual owner-operators managing diversified crop and livestock enterprises represent the foundational rental customer base. German and French cereal producers prioritize leased equipment with verified EU Stage V certification to avoid operational restrictions.
- Agricultural Cooperatives:Member-owned enterprises aggregate equipment demand across multiple growers to negotiate favorable rental rates and service terms. Large grain cooperatives in Kansas and Nebraska prefer telematics-enabled usage pricing over flat daily rates.
- Small Holders:Subsistence and semi-commercial operators with limited land area require small tractors and power-tillers on affordable terms. India's CEA electrification directives are creating rental demand for electric power-tillers in Bihar and Uttar Pradesh.
- Contractors:Custom service providers rent specialized equipment to fulfill sowing, spraying, and harvesting contracts for third-party growers. Enterprise sowing services in Southeast Asia bundle precision planters with agronomic advisory for recurring revenue capture.
Farmers lead on scale; agricultural cooperatives lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's cereal producers prioritize EU Stage V certified leases, while Brazilian operators capture premium rates in Mato Grosso's narrow harvest windows. Regional differentiation concentrates around emissions compliance tiers, seasonal demand intensity, and smallholder electrification programs.
United States
Mid-sized grain operations across Iowa and Illinois dominate rental volume for Tier 4 Final compliant tractors and precision planters. EPA enforcement timelines accelerate pre-compliant diesel retirements across Midwestern dealer networks. Kansas and Nebraska grain cooperatives drive telematics-enabled usage pricing adoption.
Brazil
Mato Grosso soybean belt operators face acute machinery shortages during compressed planting and harvest periods. ANVISA and environmental licensing requirements shape equipment import timelines for rental fleet operators. São Paulo-based logistics hubs pre-position combines to capture premium daily rates when local inventory depletes.
India
Bihar and Uttar Pradesh smallholder corridors generate rental demand for electric power-tillers under CEA rural grid extension programs. BIS safety certification requirements for power-tiller operation create compliance layers for rental operators. Punjab and Haryana tractor rental pools serve wheat-rice rotation systems with multi-year lease structures.
Germany
EU Stage V emissions frameworks mandate diesel particulate filters across 75-600 horsepower categories for cereal producers in Lower Saxony and Bavaria. CAP eco-scheme payments incentivize lower-emission machinery adoption through subsidized pilot funding. Berlin-Brandenburg operators trial battery-electric prototypes in field validation programs.
Australia
Murray-Darling basin broadacre growers favor 48-hour rental increments tied to soil moisture rather than fixed calendar contracts. TGA and state-level agricultural safety regulations govern equipment certification for cross-border fleet movements. South Australian irrigation districts drive flexible tenure adoption given rainfall unpredictability.
Farm Equipment Rental Market Key Industry Players
Top-tier vendors anchor integrated telemetry and emissions-compliant fleet provision, while regional specialists and utility-focused operators occupy mid-market and smallholder tiers. Market structure reflects consolidation around dealer-anchored networks alongside fragmentation among independent rental pools. Strategic archetypes include precision-ag technology integrators, cost-optimized utility providers, and seasonal demand aggregators. Dominant competitive moves encompass telematics subscription bundling and emissions-compliant fleet renewal programs.
Among Japan-based manufacturers, Kubota Corporation occupies a position within compact utility and mid-horsepower tractor archetypes. John Deere and Deere & Company exemplify precision-ag technology integration through telemetry-enabled lease structures. Mahindra & Mahindra represents cost-optimized utility tractor provision for smallholder market penetration. These three anchors illustrate divergent strategic positioning across premium technology, integrated platforms, and emerging market accessibility tiers.
| Leading Market Players |
|---|
| Kubota Corporation |
| John Deere |
| Deere & Company |
| The Pape Group |
| JCB |
| CNH Industrial |
| Mahindra & Mahindra |
| Premier Equipment Rentals |
| AGCO Corporation |
| Others |
Cost & Logistics Intelligence
High-strength steel and hydraulic component costs cascade from foundries in China and Germany through to rental rate floors in Iowa and Mato Grosso, with EPA Tier 4 Final compliance premiums widening the spread between aged mechanical-drive fleets and telemetry-integrated replacements. Fleet operators absorb residual value risk on pre-compliant diesel stock while passing through emissions-certified premiums to growers facing narrow planting windows.
Pricing Analysis
Capacity additions in Brazil's São Paulo logistics corridor are reshaping price floors for combine rentals during Mato Grosso's compressed harvest windows. Three-tier pricing structure across premium telemetry-integrated, standard emissions-compliant, and economy mechanical-drive tiers reflects EPA certification grade and autosteer subscription bundling. Pricing pressure stems from steel input volatility that fleet operators struggle to pass through fixed seasonal contracts. Smallholder corridors in Bihar exhibit highest price sensitivity, while Kansas grain cooperatives accepting telematics-enabled usage pricing show lowest.
Supply Chain Analysis
Regional distribution centers in Des Moines and Campinas anchor hub-and-spoke patterns that pre-position planters and harvesters ahead of soil moisture triggers. Manufacturing concentrates in Germany, Japan, and India for diesel powertrains, precision hydraulics, and cost-optimized utility frames respectively. Component sourcing draws from high-strength steel mills, selective catalytic reduction suppliers, and CAN bus telemetry module producers. Single-source vulnerability sits with Tier 4 Final aftertreatment system suppliers facing certified technician scarcity. Distribution runs through legacy Case IH and New Holland dealer territories that independent rental operators struggle to penetrate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet modernization toward telemetry-integrated, emissions-compliant assets expands margin capture through premium rental tiers and usage-based billing adoption. Cost compression in mechanical-drive residuals accelerates shift toward subscription revenue models.
For Market Incumbents: Anchor defensive positioning through backward integration into certified technician training programs and captive aftertreatment service capacity. Consolidate dealer network access in Midwestern territories where independent operators face parts availability barriers. Threat of autonomous tractor platforms from precision-ag startups demands telemetry subscription bundling to lock in grower relationships. Leverage EPA Tier 4 Final enforcement timelines to accelerate pre-compliant fleet retirements and capture residual value recovery.
For New Entrants and Emerging Players: Begin with electric power-tiller deployment in Bihar and Uttar Pradesh smallholder corridors where CEA grid extension subsidies reduce capital barriers. Target contract farming enterprises in Vietnam and Indonesia requiring precision planters for compressed sowing windows. Go-to-market angle bundles equipment access with agronomic advisory services to capture recurring revenue beyond pure asset rental.
For Investors and Strategic Acquirers: Consolidation pressure builds where independent rental pools lack scale to absorb EPA compliance costs and telemetry platform investments. Long-term viability favors operators with balanced fleet age profiles and geographic diversification across multiple regulatory jurisdictions. Acquisition target archetype: regional specialists with established dealer relationships and undepreciated Tier 4 Final inventory. Signal to watch is California CARB enforcement expansion that would accelerate pre-compliant obsolescence nationwide.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Subscription Bundling | John Deere's autosteer and yield-mapping integrations lock growers into multi-season contractual relationships. |
| Emissions-Compliant Fleet Renewal | EPA Tier 4 Final and EU Stage V certification requirements elevate rental premiums for newer machines. |
| Electric Power-Tiller Deployment | India's CEA grid extension programs create subsidized entry points for battery-electric smallholder equipment. |
| Flexible Tenure Restructuring | Australian Murray-Darling basin growers demand 48-hour increments tied to soil moisture conditions. |
| Certified Technician Pipeline Investment | Rural Texas and Saskatchewan operators report 90-day lead times for EPA aftertreatment-qualified service hires. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary field engagement with fleet operators, dealer network managers, agricultural cooperative procurement leads, and precision-ag technology directors alongside secondary validation through EPA enforcement documentation, EU Stage V regulatory filings, ANVISA import licensing records, and CEA electrification directive implementation reports. Bottom-up equipment transaction modeling and top-down macroeconomic triangulation anchored market sizing across the projection horizon.
Historical reference periods established baseline fleet composition and rental rate structures that informed forward modeling across equipment type, service tenure, industry vertical, and customer entity segmentation dimensions. CAGRs derived from regression analysis against planted acreage trends, emissions compliance phase-in schedules, and telemetry adoption curves. Industry-specific forecast inputs incorporated seasonal demand concentration patterns in Brazil's soybean belt and smallholder electrification subsidy trajectories in South Asia.
Several conditions sit outside the modeled scope, including unannounced regulatory acceleration by California CARB, breakthrough battery-electric range extension in row-crop applications, and autonomous tractor regulatory clearance timelines. Forecasts reflect documented assumptions regarding enforcement consistency and technology cost curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
United States Irrigation Valves Market
Farm Equipment and Irrigations
Watering Cans Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Fertigation Control System Market
Farm Equipment and Irrigations
Irrigation Pumps Market
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market
Farm Equipment and Irrigations
Australia Irrigation Automation Market
Farm Equipment and Irrigations
North America Agricultural Tires Market
Farm Equipment and Irrigations
Rain Barrels Market
Farm Equipment and Irrigations
Hose Reel Irrigation Machine Market
Farm Equipment and Irrigations
Agriculture Logistics Market
Farm Equipment and Irrigations
Irrigation Liner Market