
 Rotary Tiller Market | 2026-2036
Rotary Tiller Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Tiller Market Analysis
Dealer and cooperative procurement networks is rewriting how rotary tillers reach end-users across fragmented agricultural geographies. Kubota Corporation leverages its captive distribution in Southeast Asia to sustain premium positioning among smallholder cooperatives. Deere & Company anchors North American volume through its integrated dealer financing and precision agriculture bundling. Mahindra & Mahindra Ltd. dominates the Indian subcontinent with localized manufacturing and state-level subsidy navigation.
A rotary tiller is a powered agricultural implement employing rotating blades or tines to pulverize, mix, and level soil, typically operating at depths of 10-25 centimeters with PTO-driven shafts at 540 or 1000 RPM. Its primary commercial purpose is seed bed preparation and residue incorporation ahead of planting cycles. Heavy-duty gasoline and diesel configurations still occupy the majority of revenue pools across broadacre farming, though battery-powered walk-behind units represent the fastest-growing margin segment as electrification subsidies expand. Compact tillers for landscape maintenance command stable replacement demand but face pricing pressure from unbranded Asian imports.
EPA Tier 4 Final and EU Stage V emissions frameworks constrain diesel engine certification costs and accelerate OEM investment in electric drivetrains. India's Central Pollution Control Board and BIS efficiency labeling shape import access and domestic manufacturer compliance burdens. Stakeholders must monitor subsidy regime durability in Brazil's Plan Safra and India's SMAM mechanization scheme, as fiscal tightening could abruptly alter equipment replacement cycles.
Market Dynamics
Precision agriculture integration and emissions compliance costs are restructuring competitive economics across rotary tiller manufacturing, forcing OEMs to rebalance R&D portfolios between electrification and conventional drivetrain optimization.
Growth Catalysts
- SMAM Mechanization Subsidies:India's state-level equipment financing schemes reduce capital barriers for smallholder adoption of PTO-driven tillers in Punjab and Haryana.
- EU Stage V Emissions Framework:Certification requirements accelerate battery-electric platform development among European horticulture equipment suppliers.
- Specialty Crop Intensification:North American vegetable and organic farming belts drive demand for precision depth-control tillage in high-value seed bed preparation.
Market Restraints
- Diesel Engine Cost Escalation:EPA Tier 4 Final aftertreatment systems add 15-25% to powertrain costs, compressing margins on mid-horsepower tractor attachments.
- Import Dependence for Lithium Cells:Battery-powered walk-behind tillers rely on East Asian cell suppliers, exposing OEMs to raw material volatility and logistics bottlenecks.
- Subsidized Equipment Depreciation Cycles:Fiscal tightening in Brazil's Plan Safra could abruptly truncate replacement demand in Mato Grosso mechanization corridors.
Strategic Opportunities
- Cooperative Procurement Platforms:Digitally aggregated smallholder buying pools in Southeast Asia enable direct manufacturer-to-farm sales, bypassing traditional dealer markups.
- Telematics-Enabled Rental Models:IoT-hour-meter integration allows pay-per-use tiller access for seasonal operators in India's eastern rice belts.
- Biodegradable Hydraulic Fluids Mandate:Anticipated EU environmental product declarations create first-mover advantage for bio-based lubricant system suppliers.
Industry Challenges
- Cross-Platform PTO Compatibility:Variability in 540/1000 RPM shaft specifications across Japanese, European, and Indian tractor brands complicates universal attachment design.
- Electric Drivetrain Thermal Management:High-torque tillage loads in compact battery-powered units demand novel cooling architectures absent from established mower or blower platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Tiller Market |
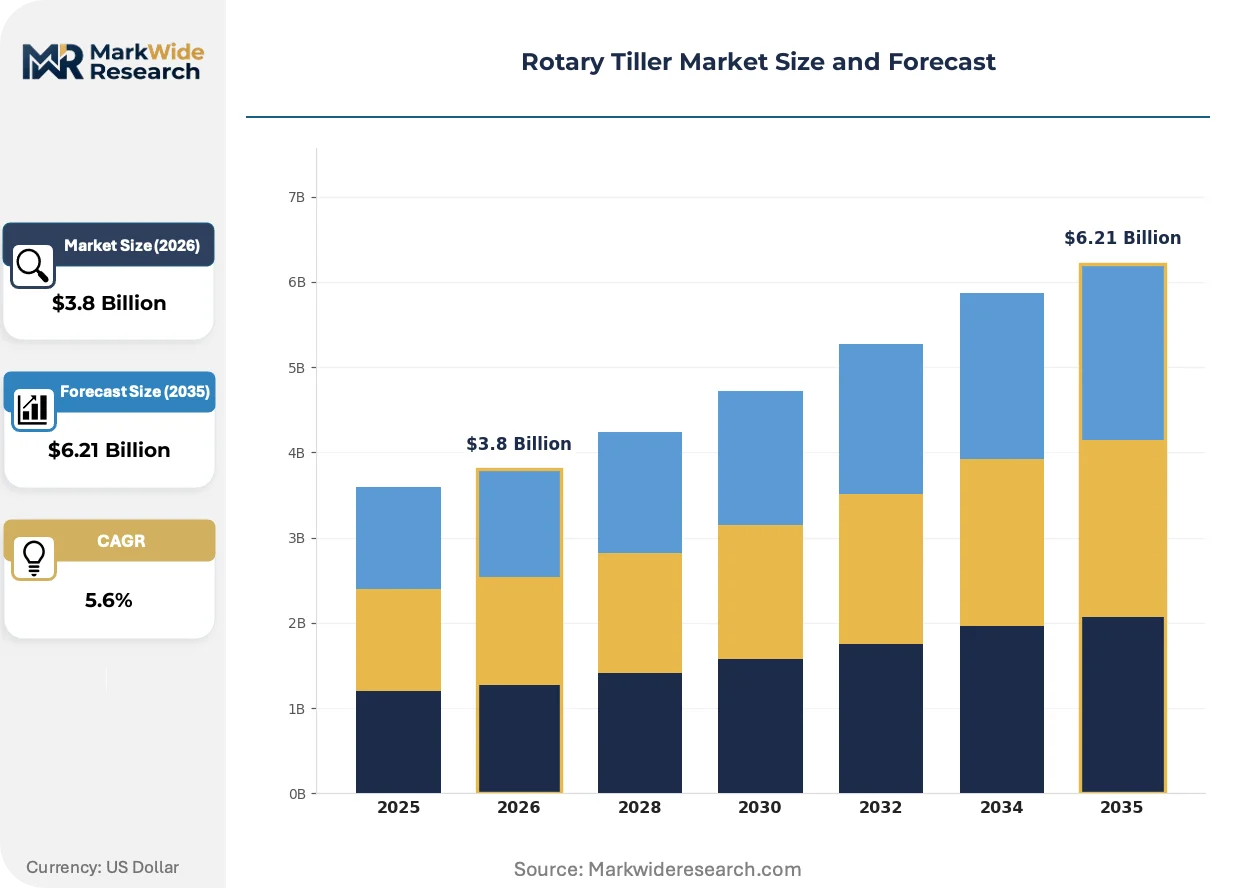
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-Behind, Garden, Heavy-Duty, Compact Power Source: Gasoline, Diesel, Electric, Battery Size: Small, Medium, Large, Extra Large Application: Farming, Landscape Maintenance, Soil Preparation, Seed Bed Preparation |
| Companies Covered | CNH Industrial N.V., Mahindra & Mahindra Ltd., Kubota Corporation, CLAAS Group, Foton Lovol Heavy Industry Co., Ltd., Yanmar Co., Ltd., AGCO Corporation, Iseki & Co., Ltd., Deere & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Tiller Market Emerging Trajectories
Electrification and digital integration are reconfiguring product architectures faster than supply chains can adapt, compressing development cycles and redrawing competitive boundaries between agricultural machinery incumbents and battery-system specialists.
Brushless DC motor controllers with integrated regenerative braking are migrating from premium European walk-behind units into mid-range Asian export configurations. Italian and German vineyard operators now specify these systems for reduced noise compliance in protected zones. The technology is migrating from niche horticulture applications toward broadacre rice paddy preparation in Vietnam and Thailand.
EPA Tier 4 Final and EU Stage V emissions frameworks are forcing diesel engine suppliers to consolidate certification programs across sub-40 horsepower categories. This concentration eliminates marginal engine builders and restricts tiller OEM sourcing to three surviving powertrain platforms. Indian manufacturers face parallel pressure from BIS efficiency labeling requirements for domestic diesel engines.
Equipment-as-a-service contracts are displacing outright purchase in Brazilian soybean expansion zones where credit access fluctuates with harvest futures. Dealer networks in Mato Grosso now bundle tillers with precision planting packages under seasonal rental terms. This restructuring concentrates volume with integrated agricultural solution providers and marginalizes standalone implement distributors.
Rotary Tiller Market Segmentation
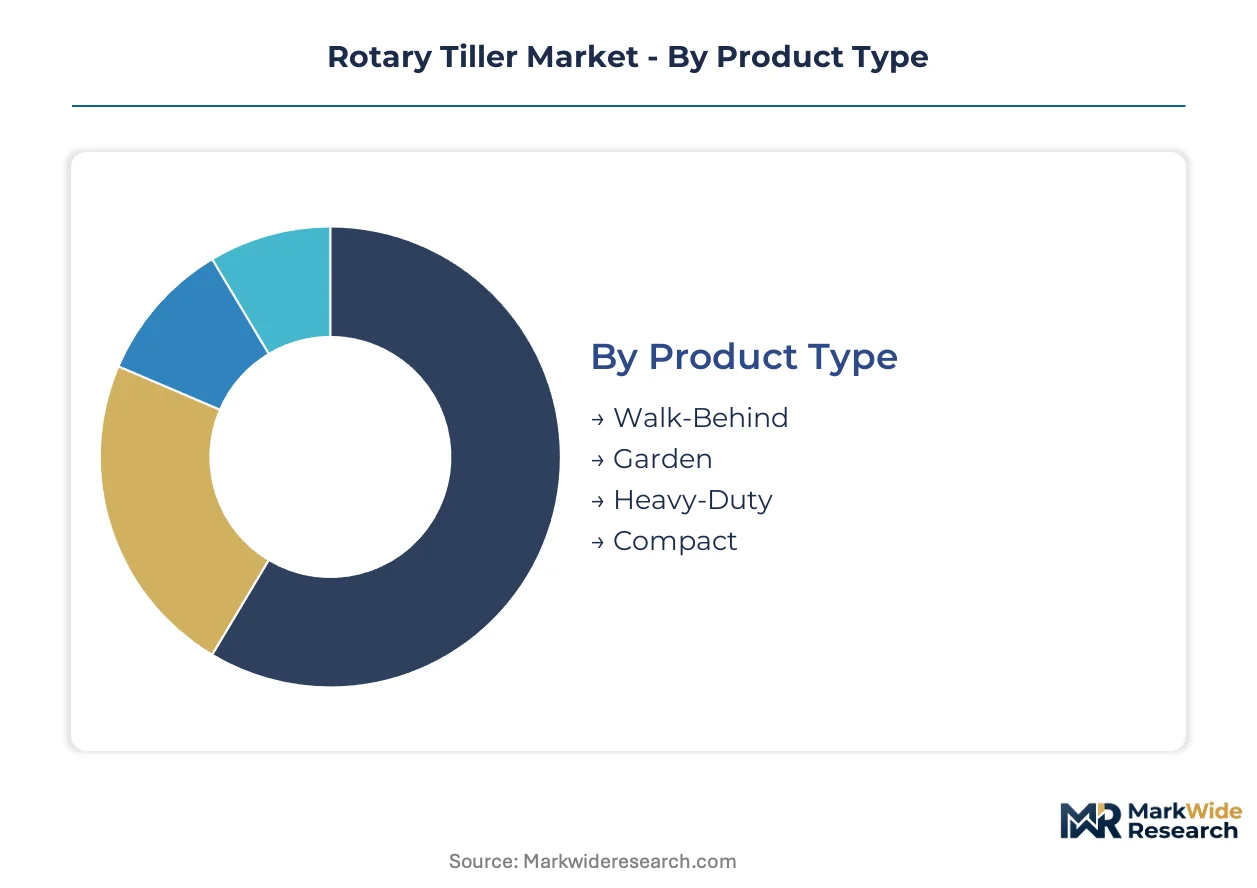
Product architecture in rotary tillers follows distinct usage intensity and power requirements. Segmentation reveals where electrification subsidies reshape procurement economics versus where diesel retention persists.
Product Type:
Cost tier stratification separates hobbyist purchases from commercial fleet deployments.
- Heavy-Duty:Reinforced gearbox assemblies and heat-treated tine configurations withstand continuous operation in Brazil's Mato Grosso soybean preparation corridors. Demand concentrates among contractor fleets serving expansion zones where credit access fluctuates with harvest futures.
- Walk-Behind:Compact frame designs with direct-drive PTO shafts target smallholder cooperatives in India's Punjab-Haryana belt. Subsidy navigation through state-level SMAM schemes determines manufacturer channel strategy.
- Garden:Lighter gauge steel construction serves residential soil amendment with seasonal replacement cycles.
- Compact:Narrow working widths fit vineyard inter-row operations in Italian protected zones.
Heavy-Duty commands the established base. The steepest expansion runs through Walk-Behind.
Power Source:
Application intensity dictates fuel choice, with emissions compliance costs accelerating platform shifts.
- Diesel:Water-cooled indirect injection engines above 25 horsepower incorporate EPA Tier 4 Final aftertreatment systems that add certification burden. Broadacre farming in North American grain belts retains this configuration for torque density.
- Battery:Lithium iron phosphate cell packs with brushless DC controllers enable regenerative braking in European vineyard zones. Noise compliance requirements in German protected areas drive specification.
- Gasoline:Air-cooled single-cylinder designs dominate mid-range walk-behind export configurations from Southeast Asian manufacturing hubs.
- Electric:Corded AC motor systems persist in fixed-location nursery operations with grid access.
Diesel retains the volume base. Battery configurations are climbing the fastest.
Size:
Working width and tractor matching requirements segment demand by farm scale.
- Large:2.5-3.5 meter working widths pair with 80+ horsepower tractors in Brazilian mechanization corridors. Equipment-as-a-service bundling with precision planting packages concentrates procurement with integrated agricultural solution providers.
- Small:Sub-1.2 meter configurations attach to compact tractors in Japanese rice paddy operations. Telematics-enabled rental models with IoT-hour-meter integration serve seasonal operators in India's eastern rice belts.
- Medium:1.2-2.0 meter spans dominate European horticulture belt vegetable operations.
- Extra Large:4+ meter folding frame designs serve Black Sea region broadacre wheat preparation.
Large formats anchor commercial fleet procurement. Small units are gaining share fastest through cooperative aggregation platforms.
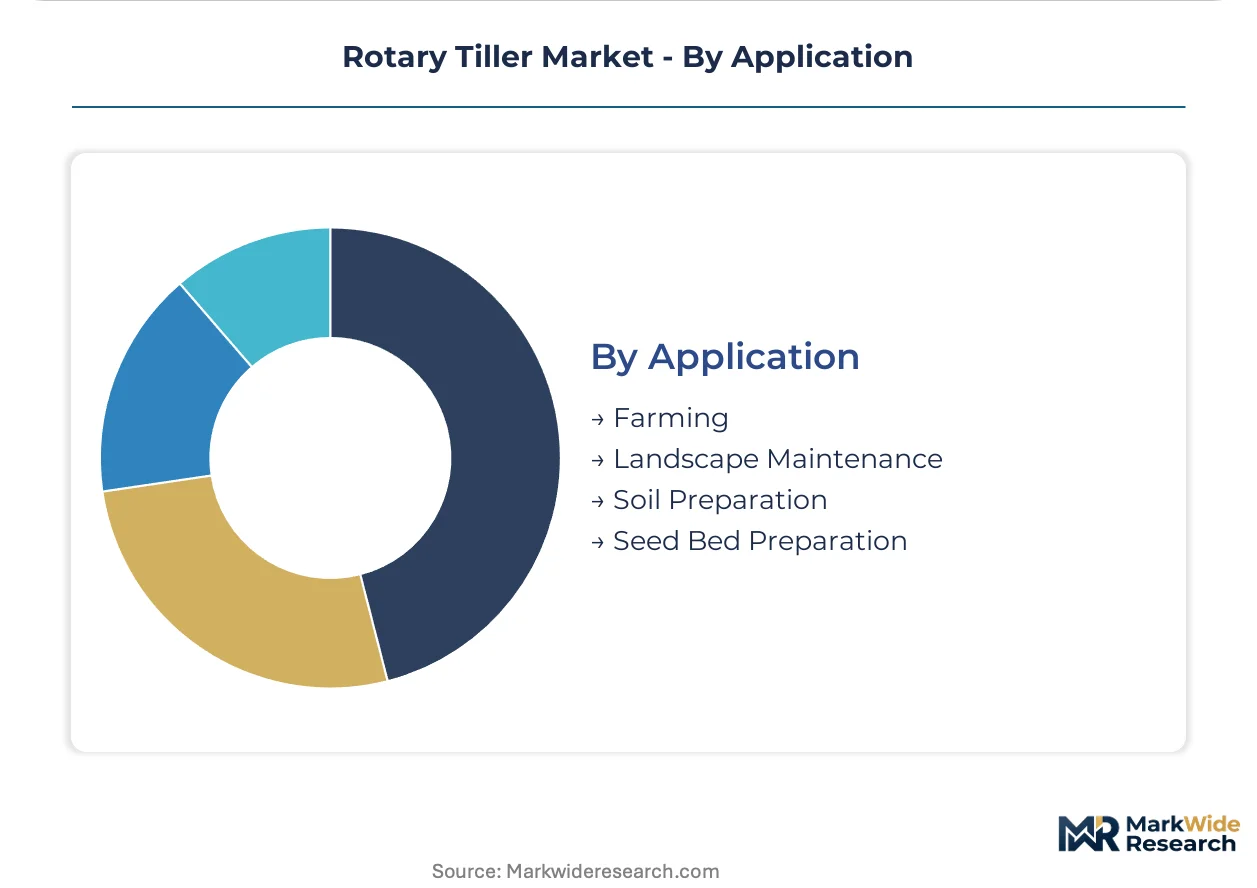
Application:
End-use intensity determines durability specifications and replacement frequency.
- Soil Preparation:Deep tillage to 25 centimeters with residue incorporation requirements shapes blade metallurgy and tine angle geometry. North American organic farming belts specify these units for carbon sequestration compliance.
- Seed Bed Preparation:Precision depth control within 2 centimeter tolerances drives demand for hydraulic float systems in high-value vegetable operations. Specialty crop intensification in California's Central Valley concentrates premium procurement.
- Farming:General purpose tillage spans commodity grain and forage operations with standardized PTO interfaces.
- Landscape Maintenance:Lower duty cycles in municipal and golf course applications favor compact configurations with quick-hitch compatibility.
Soil Preparation anchors equipment fleet investment. Seed Bed Preparation shows the steepest trajectory as precision agriculture bundling expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in European horticulture belts where Stage V compliance costs filter marginal suppliers, while Indian manufacturers compete on state-level subsidy capture across Punjab and Haryana. This asymmetry shapes divergent investment patterns across major agricultural economies.
United States
Precision agriculture bundling with dealer financing networks drives procurement in California's Central Valley vegetable operations. EPA Tier 4 Final certification requirements constrain diesel engine sourcing to consolidated powertrain platforms. Iowa and Illinois grain belt contractors anchor heavy-duty fleet replacement cycles through integrated equipment-as-a-service contracts.
Germany
Vineyard inter-row tillage in protected zones mandates battery-electric noise compliance specifications. EU Stage V emissions frameworks accelerate OEM investment in brushless DC motor architectures. Baden-Württemberg's machinery clusters concentrate development of regenerative braking systems for premium horticulture exports.
India
SMAM mechanization subsidies reduce capital barriers for smallholder cooperatives across Punjab and Haryana. BIS efficiency labeling requirements reshape domestic diesel engine compliance burdens for manufacturers. Tamil Nadu and Karnataka assembly hubs serve eastern rice belt telematics-enabled rental models with IoT-hour-meter integration.
Brazil
Plan Safra fiscal cycles dictate equipment replacement timing in Mato Grosso soybean expansion corridors. ANVISA agricultural equipment standards intersect with state-level environmental licensing for broadacre mechanization. São Paulo-based dealer networks bundle tillers with precision planting packages under seasonal rental terms.
China
Dual carbon goals accelerate lithium iron phosphate cell pack adoption in Yangtze River Delta manufacturing bases. GB standards for agricultural machinery efficiency reshape export competitiveness for Southeast Asian markets. Shandong Province fabrication clusters supply mid-range gasoline walk-behind configurations for cooperative procurement platforms.
Rotary Tiller Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying gearboxes, tine assemblies, and powertrain modules. The vendor base stratifies across three tiers: multinational agricultural machinery conglomerates with captive distribution, regional manufacturers leveraging localized subsidy navigation, and unbranded Asian fabricators competing on export pricing. Two dominant competitive moves define current positioning: backward integration into precision control electronics and geographic expansion through cooperative procurement platform partnerships.
Among Japanese machinery conglomerates, Kubota Corporation and Yanmar Co., Ltd. exemplify platform integrators with established captive distribution networks. Mahindra & Mahindra Ltd. occupies a position representing regional manufacturers with localized state-level subsidy expertise. Deere & Company anchors the premium system tier through integrated precision agriculture bundling. These three archetypes illustrate how competitive positioning diverges across subsidy-dependent versus technology-differentiated market segments.
| Leading Market Players |
|---|
| CNH Industrial N.V. |
| Mahindra & Mahindra Ltd. |
| Kubota Corporation |
| CLAAS Group |
| Foton Lovol Heavy Industry Co., Ltd. |
| Yanmar Co., Ltd. |
| AGCO Corporation |
| Iseki & Co., Ltd. |
| Deere & Company |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on East Asian lithium cell suppliers compresses margin buffers across battery-powered walk-behind tiers while amplifying pricing tier spreads between premium European vineyard configurations and mid-range Asian export units. This concentration dynamic simultaneously shapes procurement economics for OEMs and determines accessibility thresholds for smallholder cooperatives navigating India's SMAM subsidy schemes.
Pricing Analysis
Configured-to-order pricing for precision depth-control hydraulic float systems in California's Central Valley vegetable operations commands substantial premiums over standard PTO-driven configurations. Three-tier pricing structure across premium, standard, and economy levels separates German vineyard noise-compliant battery units from Indian subsidy-optimized walk-behind models from unbranded Asian fabricators. Cost compression in mid-range gasoline configurations is intensifying because of East Asian manufacturing hub competition. Smallholder cooperatives in India's Punjab-Haryana belt exhibit highest price sensitivity; integrated contractor fleets in Brazil's Mato Grosso corridors show lowest sensitivity due to equipment-as-a-service bundling.
Supply Chain Analysis
Export-control restrictions on advanced brushless DC motor controllers and precision sensor technology limit flows from German Baden-Württemberg clusters to Southeast Asian assembly operations. Manufacturing gravity centers on China's Shandong Province for mid-range gasoline walk-behind frames, India's Tamil Nadu and Karnataka for diesel PTO-driven assemblies, and Italy for premium vineyard inter-row configurations. Critical inputs encompass heat-treated tine steel from European foundries, lithium iron phosphate cells from East Asian suppliers, and EPA Tier 4 Final-certified diesel powertrains from consolidated Japanese and American platforms. Single-source vulnerability in battery cell supply exposes OEMs to raw material volatility. Distribution runs through captive dealer networks for multinational conglomerates and cooperative procurement platforms for smallholder aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-enabled rental models with IoT-hour-meter integration represent a service-attach layer expanding faster than hardware sales across India's eastern rice belts, transforming capital expenditure into recurring revenue streams for fleet operators and manufacturers alike.
For Market Incumbents: Harden captive distribution control through backward integration into precision control electronics and deepen aftermarket service bundling to offset margin compression from unbranded Asian import pressure. Consolidate EPA Tier 4 Final and EU Stage V certification programs across sub-40 horsepower categories to eliminate marginal engine builder competition. Prioritize state-level subsidy navigation expertise in India's SMAM mechanization corridors to defend procurement volume against regional manufacturers. For New Entrants and Emerging Players: Build out cooperative procurement platform partnerships in Vietnam and Thailand where digitally aggregated smallholder buying pools enable direct manufacturer-to-farm sales bypassing traditional dealer markups. Target telematics-enabled rental penetration in India's eastern rice belts where seasonal operators lack credit access for outright purchase. Pursue biodegradable hydraulic fluids certification ahead of anticipated EU environmental product declarations to capture first-mover premium positioning. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors battery-system specialists with thermal management capabilities over legacy diesel-powertrain incumbents. Long-term viability over the next decade hinges on electrification subsidy durability and precision agriculture integration depth. Monitor Brazil's Plan Safra fiscal tightening as an inflection indicator for equipment replacement cycle truncation in Mato Grosso mechanization corridors. Acquisition focus should center on brushless DC motor controller developers and IoT-hour-meter platform operators serving emerging market rental models.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Electronics | Captive control over brushless DC motor controllers reduces dependency on restricted-technology suppliers and protects margin structure. |
| Cooperative Procurement Platform Partnership | Direct manufacturer-to-farm sales in Southeast Asia bypass dealer markups and capture smallholder volume aggregation. |
| Telematics-Enabled Rental Model Deployment | IoT-hour-meter integration transforms seasonal operators in India's eastern rice belts into recurring revenue accounts. |
| Bio-Based Lubricant System Certification | Anticipated EU environmental product declarations create first-mover positioning for biodegradable hydraulic fluids compliance. |
| State-Level Subsidy Navigation Investment | SMAM scheme expertise in Punjab and Haryana determines manufacturer channel access and procurement volume capture. |
Methodological Framework
A spread of perspectives from OEM product managers, dealer network operators, smallholder cooperative leaders, and state agricultural department officials converged on the working assumptions driving segmentation and forecast calibration. Primary fieldwork encompassed structured interviews with maintenance directors at Brazilian contractor fleets, plant engineers at Indian assembly hubs, and aftermarket service heads at European horticulture equipment suppliers. Secondary validation drew from customs and trade data on agricultural machinery imports, EPA and EU Stage V certification filings, SEC 10-K disclosures from listed machinery conglomerates, and state-level SMAM scheme procurement records. Bottom-up equipment shipment tracking and top-down agricultural mechanization intensity modeling were triangulated against subsidy regime durability assessments.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with equipment replacement cycles modeled against credit access fluctuations and emissions compliance cost trajectories. Segmentation dimensions encompassed product architecture intensity, power source platform, working width scale, and application-specific durability requirements. CAGRs were derived from equipment shipment trajectories weighted by subsidy regime probability and electrification adoption curves. Industry-specific forecast inputs included PTO compatibility standardization patterns across Japanese, European, and Indian tractor brands, and thermal management innovation diffusion from premium European units to mid-range Asian exports.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-system specialists or unbranded Asian fabricators would shift outcomes beyond modeled ranges. Material shifts in Brazil's Plan Safra fiscal commitment, India's SMAM subsidy allocation, or EU Stage V enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
Crop Sprayers Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
North America Agricultural Tractors Market
Agricultural Machinery
India Agricultural Machinery Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
Autonomous Agricultural Machinery Market
Agricultural Machinery
Agricultural Tractor Robots Market
Agricultural Machinery
Farm Tractor Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
Tractor Implements Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
Brazil Tractors Market