
 Potato Planter Market | 2026-2036
Potato Planter Market Size, Share, and Industry Trends Forecast 2026-2036
Potato Planter Market Insights
ISO 12100 machinery safety certification is collapsing the supplier base for European-bound potato planters, forcing smaller fabricators to either upgrade guarding systems or exit export channels. Grimme Landmaschinenfabrik leverages in-house foundry capacity to control critical component costs across its planter lines. AVR bvba anchors its position through specialized hill-planting expertise in Belgium and adjacent markets. John Deere extends its precision agriculture ecosystem by integrating planter telemetry with fleet management platforms.
A potato planter is a mechanized agricultural implement designed to deposit seed tubers at controlled depth and spacing, typically achieving row widths of 75 to 90 centimeters and planting depths of 10 to 15 centimeters depending on soil conditions and cultivar requirements. Its primary commercial purpose is to replace manual planting labor while optimizing plant population density for yield maximization in commercial potato production. Multi-row pneumatic planters now dominate volume sales where field sizes exceed 50 hectares, while precision planter configurations command margin premiums through GPS-guided seed placement and variable-rate capabilities. Mechanical technology persists in small-scale segments across developing markets due to lower capital requirements and simpler maintenance protocols.
CE marking under EU Machinery Directive 2006/42/EC and EPA Tier 4 emissions compliance in the United States shape product development roadmaps, with manufacturers redesigning powertrains and hydraulic systems to satisfy both frameworks. The EU F-Gas Regulation additionally constrains pneumatic system refrigerant choices for climate-controlled storage-integrated planters. Stakeholders must monitor how emerging national farm mechanization subsidy programs in India and Brazil alter competitive access rules for imported planter equipment.
Market Dynamics
Farm consolidation across Germany, the Netherlands, and the United States is compressing equipment replacement cycles while ISO 12100 safety mandates force capital-intensive redesigns of pneumatic and mechanical planter systems.
Growth Catalysts
- EU Green Deal subsidy alignment:Precision planter configurations with GPS-guided seed placement qualify for accelerated depreciation and direct equipment grants in Germany and the Netherlands.
- Commercial grower mechanization:Field sizes exceeding 50 hectares in North America drive multi-row pneumatic planter fleet expansion to reduce manual labor dependency.
- Seed spacing uniformity technology:Variable-rate pneumatic systems optimize plant population density for yield maximization in high-input potato production regions.
Market Restraints
- CE marking compliance costs:ISO 12100 machinery safety certification requirements force smaller fabricators to upgrade guarding systems or abandon European export channels entirely.
- EPA Tier 4 powertrain redesigns:Emissions compliance in the United States necessitates costly hydraulic and engine system reconfigurations that compress margins on mid-range planter models.
- Manual planting persistence:Mechanical technology dominates small-scale segments across developing markets due to lower capital barriers and maintenance simplicity.
Strategic Opportunities
- India farm mechanization subsidies:Emerging national equipment subsidy programs alter competitive access rules for imported planter equipment in high-volume potato production states.
- Brazil import tariff restructuring:Shifting duty frameworks on agricultural machinery create openings for European and North American manufacturers to establish localized assembly.
- Climate-controlled storage integration:EU F-Gas Regulation constraints on pneumatic system refrigerants drive innovation in closed-loop climate management for seed conditioning planters.
Industry Challenges
- Precision agriculture technician scarcity:GPS-guided planter calibration and telemetry integration require specialized skill sets that agricultural equipment dealerships struggle to staff.
- Legacy fleet interoperability:Planter telemetry integration with existing fleet management platforms demands costly retrofit kits for growers with mixed-manufacturer equipment bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potato Planter Market |
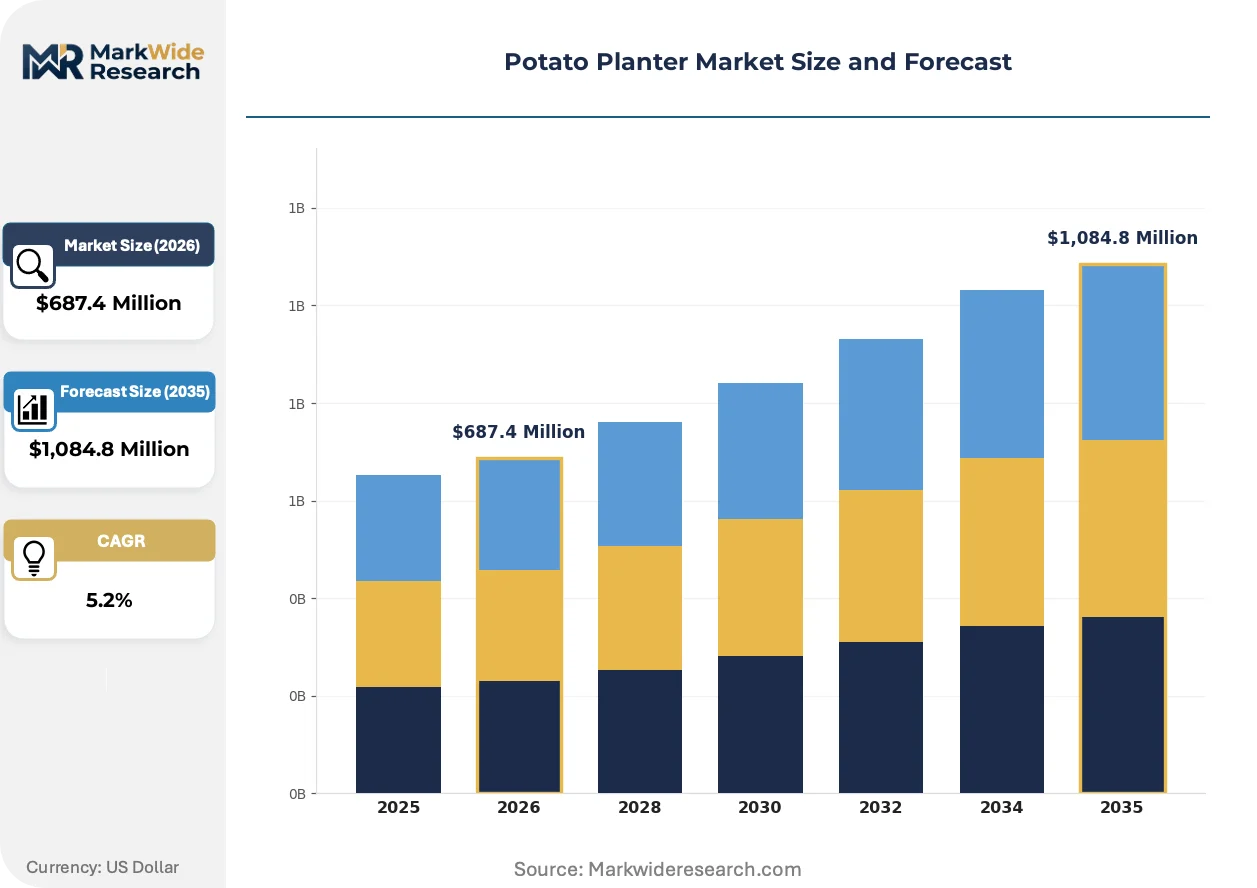
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,084.8 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Row, Multi Row, Hill Planting, Precision Planters Technology: Mechanical, Hydraulic, Pneumatic, Electromechanical End User: Farmers, Agricultural Cooperatives, Commercial Growers, Research Institutions Size: Small Scale, Medium Scale, Large Scale, Custom |
| Companies Covered | Grimme Landmaschinenfabrik, AVR bvba, Kverneland Group, John Deere, CNH Industrial, Kubota Corporation, Dewulf Group, AGCO Corporation, Kuhn Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potato Planter Market Trends and Innovations
Pneumatic seed handling architectures are fragmenting competitive positioning while regulatory pressure on refrigerants and emissions accelerates powertrain diversification. Equipment buyers now prioritize connectivity ecosystems over standalone mechanical performance.
Electro-pneumatic seed cup designs with individual row shutoff are fragmenting the traditional mechanical finger pickup market. Large-scale commercial growers in the United States and Germany are retrofitting existing frames with these modules to reduce seed waste on headlands. The technology is fragmenting supplier hierarchies by enabling hydraulic component specialists to enter planter subassembly markets previously controlled by integrated manufacturers.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants are forcing redesigns of climate-controlled storage-integrated planters sold in Germany, the Netherlands, and Belgium. Manufacturers must validate alternative refrigerant chemistries or abandon pneumatic cooling architectures entirely. German fabricators with captive refrigeration engineering capabilities are capturing specification advantages in premium planter segments.
After-sales service unbundling is compressing traditional dealer revenue models in North America. Commercial growers in Idaho and North Dakota now procure planter telemetry subscriptions directly from platform providers rather than through equipment dealers. This behavioral shift is most visible among precision agriculture early adopters operating fleets exceeding 20 implements who prioritize data portability across mixed-manufacturer environments.
Potato Planter Market Segmentation
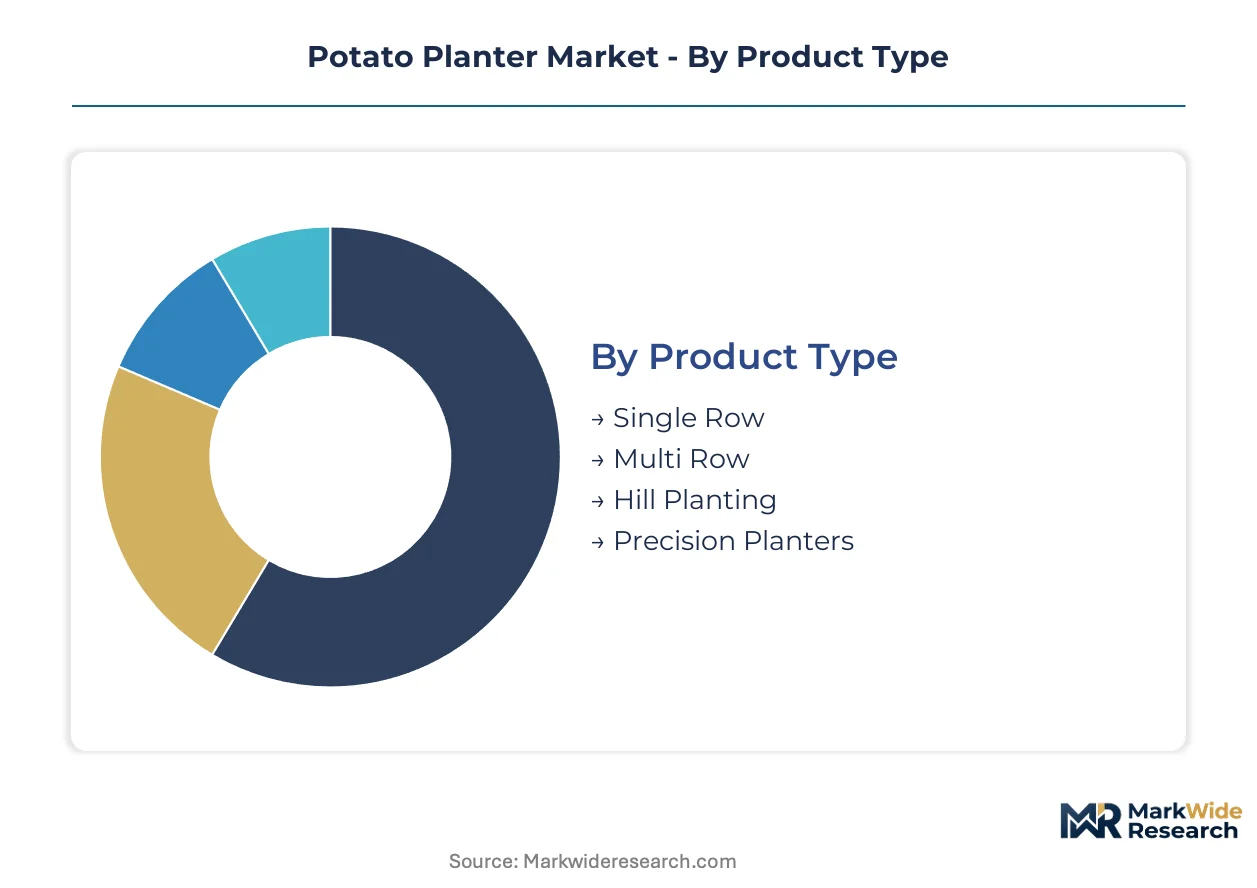
Potato planter procurement patterns diverge sharply across operational scales and regulatory environments. Segmentation reveals where capital intensity barriers protect incumbent suppliers from substitution threats.
Product Type:
Multi Row planters face acute substitution pressure from precision-guided alternatives in subsidy-rich European markets, while single-row mechanical units defend share through capital accessibility in emerging economies.
- Single Row:Mechanical finger-pickup architectures dominate smallholder operations across India and Brazil. Manual planting labor in Bihar and Uttar Pradesh states limits mechanization penetration to demonstration farms and cooperative equipment pools.
- Multi Row:Pneumatic seed handling with 4-to-8-row configurations commands fleet procurement by commercial growers in Germany and the Netherlands. CE marking compliance and GPS-ready frame designs align with EU Green Deal equipment depreciation schedules.
- Hill Planting:Specialized ridge-forming and tuber placement systems anchor demand in Belgium's sandy-loam potato belt. AVR bvba's concentrated expertise in this configuration creates specification stickiness among regional processing contract growers.
- Precision Planters:Variable-rate pneumatic systems with individual row shutoff capture margin premiums in Idaho and North Dakota. Telemetry integration with John Deere Operations Center and Climate FieldView platforms drives replacement cycles among data-centric operators.
Multi Row planters retain volume leadership; Precision Planters hold the steepest expansion curve.
Technology:
Cost tier stratification separates pneumatic and electromechanical systems from legacy mechanical alternatives, with hydraulic architectures occupying a narrowing middle ground.
- Mechanical:Finger-pickup and cup-feed systems persist across small-scale segments in developing markets. Lower capital barriers and village-level repair capability sustain demand despite seed spacing uniformity limitations.
- Hydraulic:Row-unit lift and depth-control systems face displacement by electro-hydraulic actuators in premium planter configurations. EPA Tier 4 powertrain integration costs compress margins on mid-range hydraulic models.
- Pneumatic:Vacuum-assisted seed cup designs with individual metering dominate commercial grower procurement in the United States and Germany. EU F-Gas Regulation refrigerant constraints are forcing closed-loop pneumatic architecture redesigns.
- Electromechanical:Servo-driven seed cup actuation with real-time population sensing is gaining specification share in precision agriculture early adopter segments. Direct platform provider subscription models are bypassing traditional dealer channels for telemetry-enabled units.
Pneumatic systems anchor current revenue concentration; electromechanical architectures are climbing the fastest through retrofit module penetration.
End User:
Customer type determines service bundling expectations and financing structure acceptance, with cooperatives and commercial growers diverging on data ownership terms.
- Farmers:Owner-operators below 50 hectares prioritize mechanical simplicity and third-party repair accessibility. India's PLI scheme for farm machinery is altering import competitive dynamics for this price-sensitive segment.
- Agricultural Cooperatives:Shared equipment pools in Germany and the Netherlands concentrate demand for ISOBUS-compatible multi-row configurations. Collective procurement power extracts extended warranty and seasonal uptime guarantees from suppliers.
- Commercial Growers:Corporate farming operations in Idaho and North Dakota drive telemetry subscription adoption and fleet standardization. Mixed-manufacturer environments create retrofit interoperability demand for legacy planter telemetry integration.
- Research Institutions:Plot-scale precision requirements in Wageningen and Fargo breeding programs sustain niche demand for single-row electromechanical units with programmable spacing protocols.
Commercial Growers dominate capital deployment; Agricultural Cooperatives are expanding most quickly through EU subsidy aggregation.
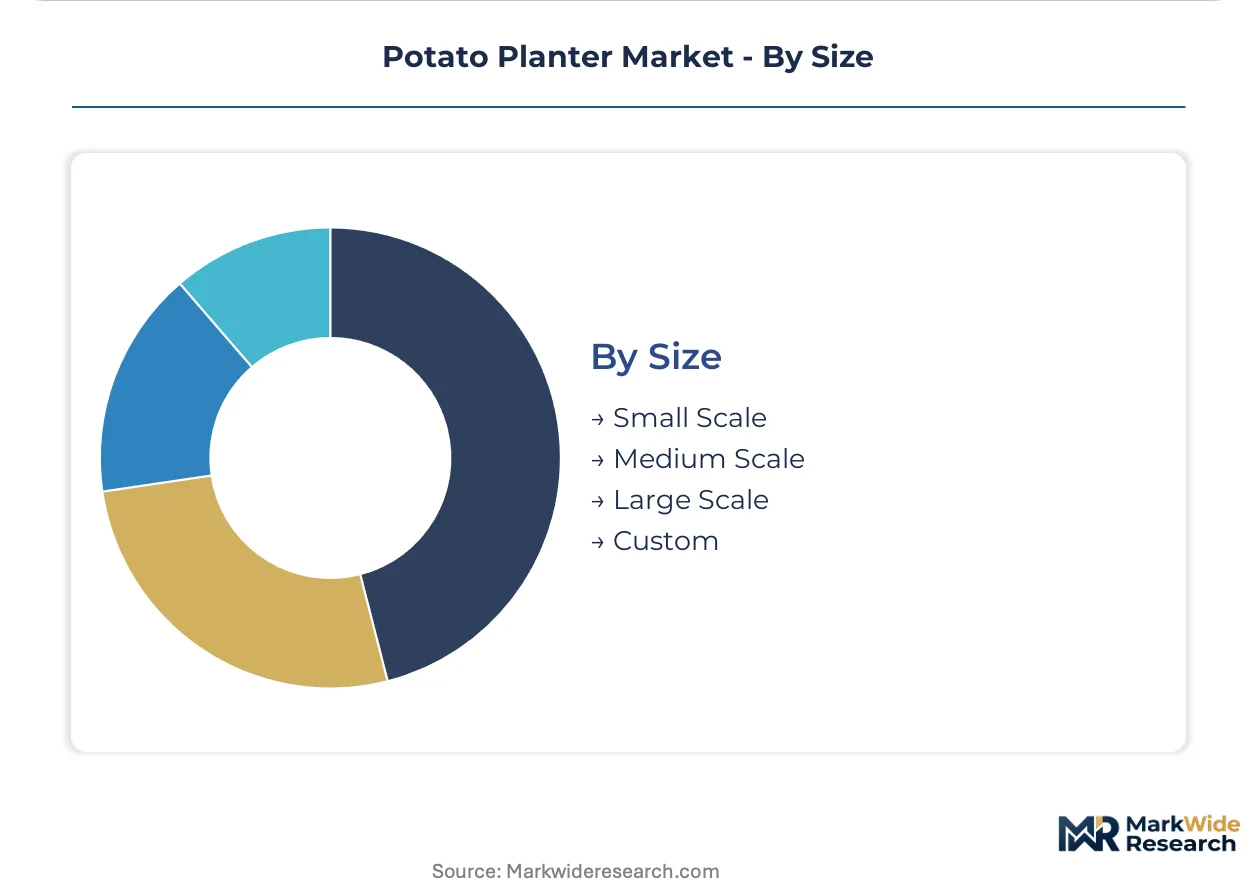
Size:
Operational scale alignment with field geometry and labor availability dictates frame configuration selection across regional production systems.
- Small Scale:Two-row and three-row mechanical planters serve fragmented landholdings in India and Eastern European subsistence-transition zones. DGFT import duty structures shape competitive access for foreign manufacturers.
- Medium Scale:Four-row pneumatic configurations with basic GPS guidance capture farm consolidation transitions in Germany's Lower Saxony and the Netherlands' Flevoland polders.
- Large Scale:Eight-row and twelve-row pneumatic systems with integrated fertilizer placement dominate Red River Valley and Columbia Basin operations. Row widths of 75 to 90 centimeters match regional cultivation equipment interoperability standards.
- Custom:Modified hill-planting and bed-forming configurations serve Belgian processing contract specifications and organic certification requirements in specific soil type clusters.
Large Scale configurations retain volume leadership; Medium Scale units hold the steepest expansion curve through farm consolidation acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial growers in the United States, Germany, and the Netherlands dominate equipment procurement, while mechanization subsidies reshape competitive access in India and Brazil.
United States
Idaho and North Dakota commercial operators drive eight-row pneumatic fleet standardization. EPA Tier 4 emissions compliance forces powertrain redesigns that compress margins on mid-range models. The Red River Valley concentration anchors telemetry subscription adoption among data-centric growers.
Germany
Lower Saxony farm consolidation accelerates four-to-six-row replacement cycles. EU Green Deal equipment depreciation schedules align with CE marking and ISO 12100 safety mandates. Foundry-integrated fabricators in Lower Saxony control critical component costs through captive casting capacity.
Netherlands
Flevoland polder operations concentrate demand for ISOBUS-compatible multi-row configurations. EU F-Gas Regulation refrigerant constraints force closed-loop pneumatic architecture redesigns. Wageningen research institutions sustain niche demand for programmable single-row electromechanical units.
India
Bihar and Uttar Pradesh smallholders limit mechanization to cooperative equipment pools. PLI scheme for farm machinery and DGFT import duty structures alter competitive dynamics for foreign manufacturers. Punjab and Haryana demonstration farms anchor subsidy-driven precision planter trials.
Brazil
Minas Gerais and Paraná potato belts face labor availability constraints that favor mechanization. Shifting agricultural machinery duty frameworks create openings for European and North American assembly localization. São Paulo-based processing contract growers drive specification requirements for imported equipment.
Potato Planter Market Competitive Landscape
Player mix skews toward integrated agricultural machinery conglomerates with captive distribution networks. Tiered supplier concentration separates foundry-integrated European specialists from Asian volume manufacturers. Strategic archetypes include precision agriculture platform integrators, hill-planting regional specialists, and pneumatic component subsystem suppliers. Dominant competitive moves center on telemetry ecosystem lock-in through platform subscription models and in-house foundry capacity acquisition for casting cost control.
Within the integrated machinery tier, John Deere exemplifies platform-centric positioning through precision agriculture ecosystem extension. Grimme Landmaschinenfabrik anchors German fabrication concentration with foundry-integrated cost structures. AVR bvba occupies a specialist position rooted in Belgian hill-planting expertise and adjacent market specification stickiness.
| Leading Market Players |
|---|
| Grimme Landmaschinenfabrik |
| AVR bvba |
| Kverneland Group |
| John Deere |
| CNH Industrial |
| Kubota Corporation |
| Dewulf Group |
| AGCO Corporation |
| Kuhn Group |
| Others |
Pricing and Supply Chain Analysis
Long-term equipment procurement contracts with indexed steel and hydraulic component pricing lock in supply access for German and Dutch commercial growers while insulating against foundry cost volatility. These arrangements concentrate pricing power among foundry-integrated fabricators in Lower Saxony who control captive casting capacity for planter frames and row units.
Pricing Analysis
Cost-plus contracts with steel indexation anchor precision planter transactions between German fabricators and cooperative buyers in the Netherlands. Three-tier pricing structure across premium electromechanical, standard pneumatic, and economy mechanical levels separates telemetry-enabled configurations from basic GPS-ready models. Pricing pressure stems from EPA Tier 4 powertrain redesign costs compressing margins on mid-range hydraulic units. Smallholder farmers across India exhibit highest price sensitivity, while commercial growers in Idaho prioritize telemetry ecosystem value over unit cost.
Supply Chain Analysis
Inventory cycles stretching across planting seasons force pneumatic component stockpiling in German fabrication hubs before North American spring demand windows. Supply concentration centers on Germany, the Netherlands, and the United States for precision frame manufacturing, with hydraulic systems sourcing from Italian and Japanese specialists. Raw material dependencies include high-grade steel for frames, specialized polymers for seed cups, and precision bearings for metering systems. Tariff exposure on Chinese-sourced electro-hydraulic actuators creates single-source vulnerability for electromechanical retrofit modules. Distribution runs through OEM captive dealer networks in developed markets and cooperative equipment pools in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Farm consolidation across Germany and the Netherlands represents an early-cycle expansion story, with subsidy alignment under EU Green Deal depreciation schedules accelerating precision planter replacement waves.
For Market Incumbents: Compound defensive positioning by acquiring captive foundry capacity in Lower Saxony to control critical casting costs against Asian volume manufacturers. Invest in ISOBUS certification and telemetry platform integration to lock out hydraulic component specialists entering planter subassembly markets through electro-pneumatic retrofit modules. Priority lever rests on backward integration into seed cup manufacturing. For New Entrants and Emerging Players: Differentiate on climate-controlled storage integration for EU F-Gas Regulation compliance, targeting Belgian and Dutch processing contract growers with closed-loop refrigerant architectures. White-space targets include single-row electromechanical units for Wageningen and Fargo research institutions, plus hill-planting configurations for Belgian sandy-loam potato belts. Go-to-market angle emphasizes direct telemetry subscription models bypassing traditional dealer channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telemetry platform providers serving commercial growers with fleets exceeding twenty implements. Long-term viability over a five-to-ten year horizon favors electromechanical architecture specialists with servo-driven seed cup capabilities. Acquisition target archetype includes hydraulic component manufacturers with pneumatic subsystem engineering depth. Signal to watch is telemetry subscription attach rates among precision agriculture early adopters.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Acquisition | Captive casting control in Lower Saxony insulates Grimme Landmaschinenfabrik from steel cost volatility. |
| Telemetry Platform Integration | John Deere Operations Center connectivity locks in commercial grower fleet standardization across mixed-manufacturer environments. |
| EU F-Gas Regulation Compliance | Alternative refrigerant validation opens premium specification share in German and Dutch climate-controlled storage segments. |
| Electro-Pneumatic Retrofit Module Development | Individual row shutoff technology fragments traditional mechanical finger pickup markets in Idaho and North Dakota. |
| India PLI Scheme Localization | Domestic assembly qualification under DGFT structures alters competitive access rules for foreign manufacturers in Bihar and Uttar Pradesh. |
Research Methodology
A spread of perspectives from equipment procurement managers at commercial growing operations, agricultural cooperative fleet directors, OEM aftermarket service heads, and precision agriculture platform engineers converged on the working assumptions. Primary interview insights combined with secondary validation from EU Machinery Directive implementation records, EPA Tier 4 compliance filings, and agricultural equipment trade customs data. Bottom-up planter shipment analysis triangulated against top-down farm consolidation metrics across Germany, the Netherlands, and the United States.
Segmentation dimensions modeled include product type architecture, technology tier, operational scale category, and end-user procurement structure across the analysis window. CAGRs derived from equipment replacement cycle compression rates and subsidy program uptake curves. Industry-specific forecast inputs incorporate EU Green Deal equipment depreciation schedules and India PLI scheme mechanization penetration assumptions.
The analysis sits within stated boundaries; outcomes outside sustained farm consolidation trajectories or abrupt subsidy program suspension would require recalibration. Forecasts reflect documented assumptions regarding pneumatic technology displacement rates and electromechanical retrofit adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
Zero Turn Mowers Market
Farm Equipment and Irrigations
Global Irrigation Automation Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market
Farm Equipment and Irrigations
Watering Cans Market
Farm Equipment and Irrigations
Irrigation Pumps Market
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
North America Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Global Fruit Picker Market
Farm Equipment and Irrigations
Rain Barrels Market
Farm Equipment and Irrigations
United States Irrigation Valves Market
Farm Equipment and Irrigations
India Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Lawn Edge Trimmer Market
Farm Equipment and Irrigations
Irrigation Controllers Market