
 Agricultural Solar Pumps Market | 2026-2036
Agricultural Solar Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Solar Pumps Market Insights
IEC 62253 certification for photovoltaic pumping systems is bifurcating the competitive landscape into qualified suppliers and marginal participants. Grundfos leverages its vertical integration across motor and controller manufacturing to sustain premium positioning in submersible systems. Shakti Pumps anchors its India dominance through deep rural distribution networks and localized service infrastructure.
Agricultural solar pumps convert photovoltaic energy into mechanical lift for groundwater extraction, typically achieving 3-8 cubic meters per hour flow rates at 20-100 meter total dynamic heads depending on solar irradiance and pump configuration. The equipment serves primarily as a diesel displacement technology for irrigation in off-grid or unreliable-grid agricultural regions. Submersible pumps capture the largest margin pool due to higher technical barriers and longer service intervals, while surface pumps occupy volume leadership in shallow-well applications across South Asia and Sub-Saharan Africa. Photovoltaic technology leads installed base but hybrid systems represent the fastest structural expansion as farmers seek dispatchable water delivery beyond peak sun hours.
FDA regulates materials contacting potable water in livestock watering applications, while India's BIS mandates performance testing under MNRE specifications for subsidy eligibility, and REACH restricts hazardous substances in European-sourced electronic components. These frameworks collectively raise compliance costs for new entrants while locking incumbents into certification maintenance cycles. Stakeholders must monitor how evolving carbon border mechanisms and irrigation water-use regulations reshape total cost-of-ownership calculations for farm-level pumping decisions.
Market Dynamics
The Agricultural Solar Pumps Market is undergoing a fundamental reconfiguration as photovoltaic module cost deflation intersects with diesel price volatility, forcing irrigation equipment economics toward renewable displacement across arid agricultural belts.
Growth Catalysts
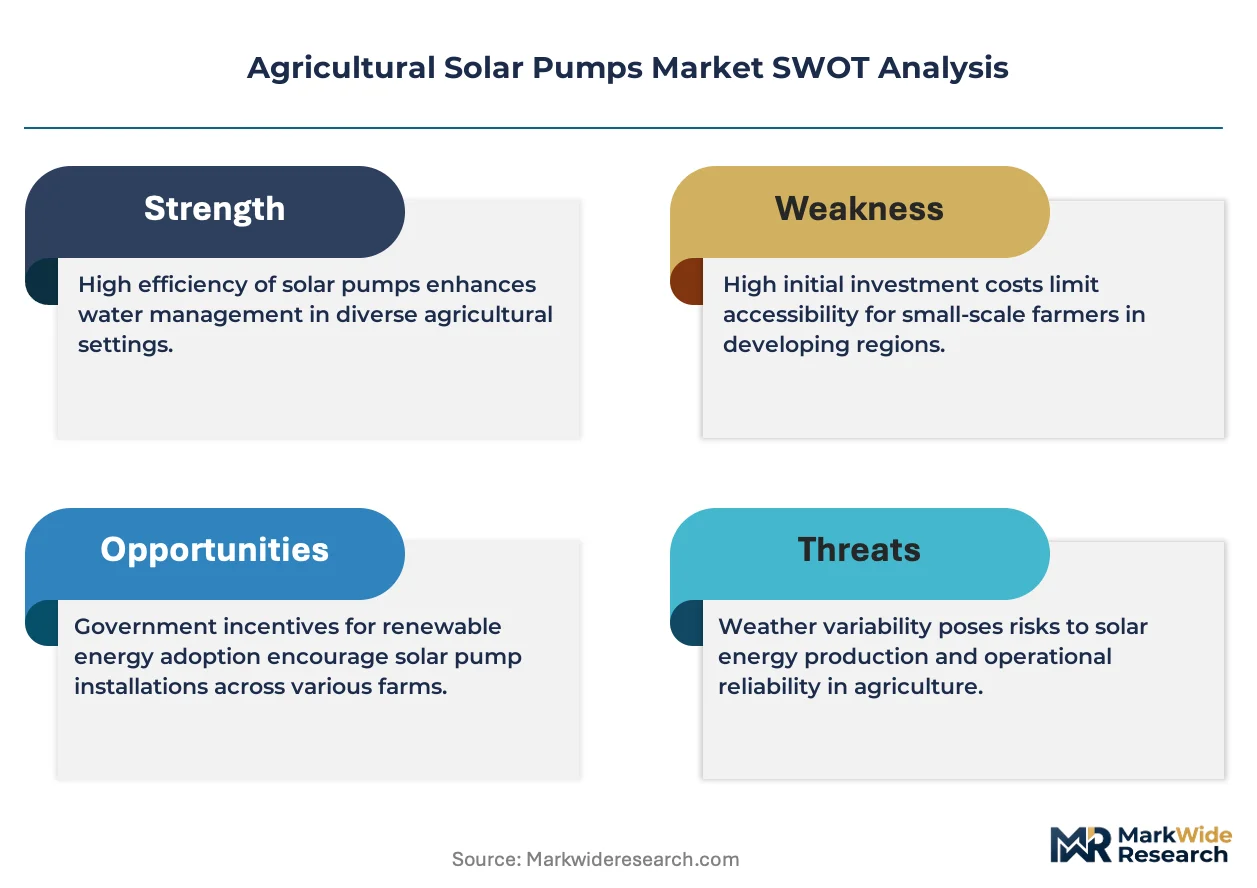
- India's PM-KUSUM scheme:Subsidy structures covering up to 60 percent of system costs are accelerating smallholder adoption in Rajasthan, Gujarat, and Maharashtra, with state nodal agencies streamlining disbursement timelines.
- Photovoltaic efficiency gains:PERC and TOPCon cell architectures are lifting pump output per installed watt, reducing array footprint requirements for marginal farmers with limited land availability.
- Groundwater stress mandates:China's Ministry of Water Resources restrictions on diesel-powered tube wells in North China Plain provinces are redirecting irrigation investment toward solar-powered extraction systems.
Market Restraints
- Polysilicon price volatility:Supply concentration among Chinese ingot and wafer producers creates input cost uncertainty that compresses margin visibility for downstream pump assemblers.
- Battery storage integration costs:Lithium-ion pack pricing and replacement cycles extend payback periods for hybrid systems, limiting adoption among credit-constrained smallholders.
- Technical service scarcity:Rural areas in Sub-Saharan Africa lack trained technicians for inverter and MPPT controller diagnostics, elevating downtime risk and total cost of ownership.
Strategic Opportunities
- Pay-as-you-go financing models:Mobile-money-enabled metered water access is unlocking adoption among East African smallholders excluded from traditional agricultural credit channels.
- Agrivoltaic co-location:Elevated panel arrays enabling simultaneous crop cultivation beneath solar infrastructure are expanding addressable land area in land-scarce South Asian markets.
- EU Carbon Border Adjustment Mechanism:Embedded emissions accounting for imported agricultural goods is incentivizing European food retailers to source from farms with verified renewable irrigation credentials.
Industry Challenges
- IEC 62253 certification complexity:Third-party testing timelines for photovoltaic pumping system validation extend 8-14 months, delaying subsidy access and freezing working capital for product launches.
- Groundwater governance fragmentation:State-level water rights regimes in India create permitting unpredictability that complicates project finance structuring and equipment deployment planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Solar Pumps Market |
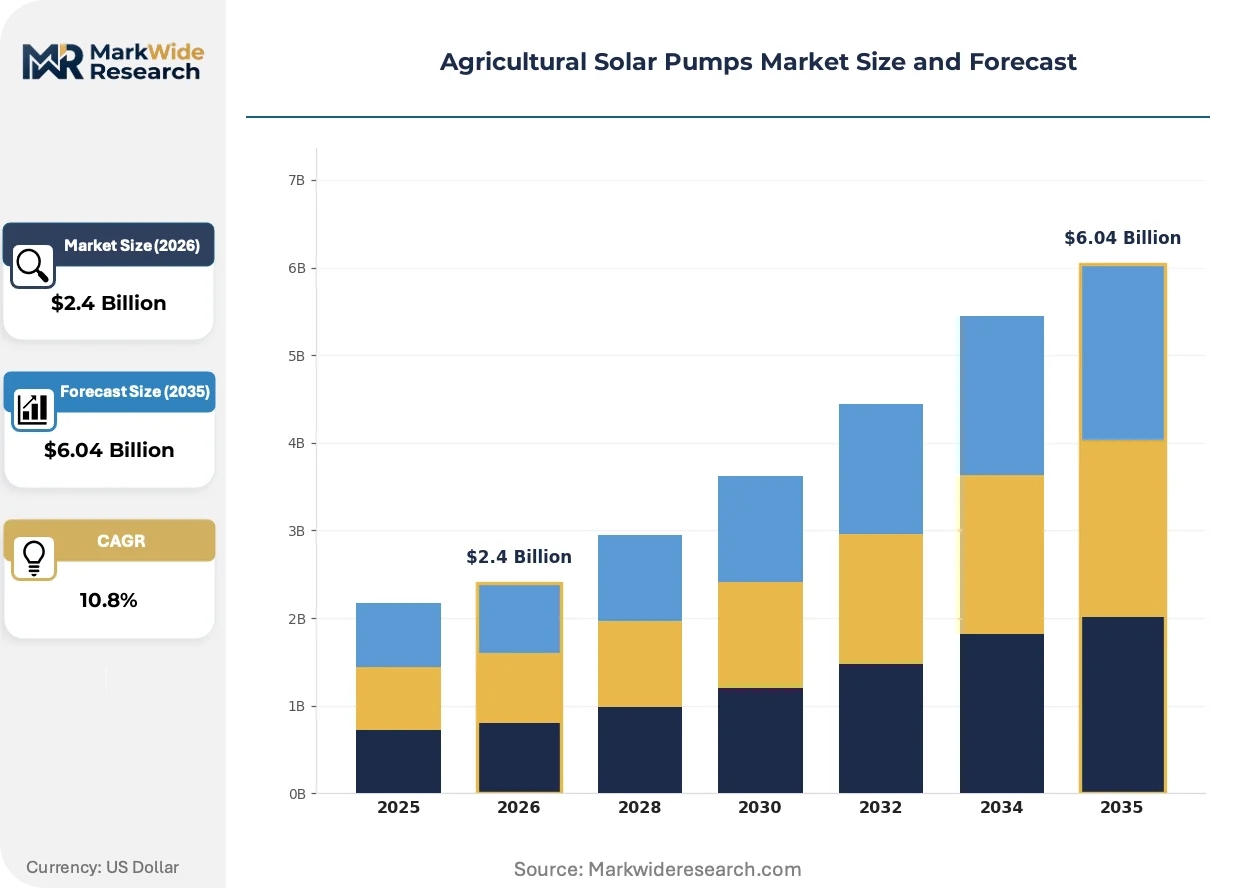
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.04 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
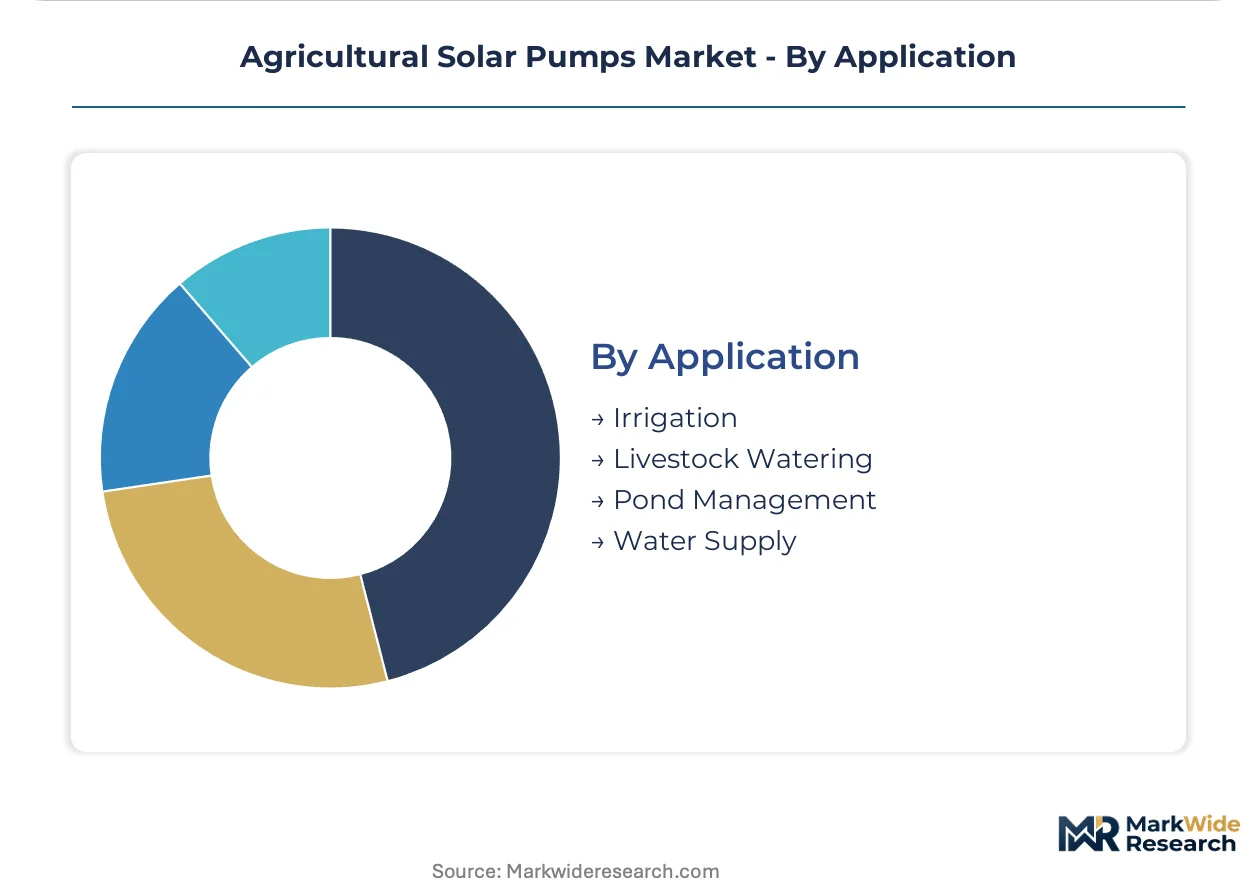
| Segmentation | Product Type: Surface Pumps, Submersible Pumps, Centrifugal Pumps, Diaphragm Pumps End User: Farmers, Agricultural Cooperatives, Commercial Growers, Research Institutions Technology: Photovoltaic, Hybrid Systems, Wind-Solar Hybrid, Off-Grid Solutions Application: Irrigation, Livestock Watering, Pond Management, Water Supply |
| Companies Covered | Grundfos, Lorentz, Shakti Pumps, Franklin Electric, Rafsun, RPS Solar Pumps, Xylem, KSB SE & Co, Jakson Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Solar Pumps Market Trends and Innovations
Equipment intelligence and service model reinvention are restructuring how agricultural solar pumps deliver value, shifting competitive advantage from hardware specification toward operational reliability guarantees and financing accessibility.
Brushless DC motor architectures paired with permanent magnet synchronous designs are bifurcating the submersible pump category. Large horticulture operations in Spain and Italy are specifying these systems for high-head, variable-flow applications. The technology is bifurcating supplier tiers into those with in-house magnet and winding capabilities versus assemblers dependent on imported motor kits.
China's dual carbon goals and MIIT efficiency mandates are accelerating domestic pump motor efficiency standards. Manufacturers must now certify products under revised GB 18613-2020 specifications to access state procurement channels. Export-oriented suppliers are dual-certifying under IEC and GB regimes to maintain access to both Belt and Road project pipelines and European distribution.
Service unbundling is restructuring buyer-supplier relationships across South Asian markets. Farmers are purchasing hardware through dealer networks while contracting maintenance separately through regional technician cooperatives. This pattern is most visible in Tamil Nadu and Karnataka, where irrigation equipment dealers now compete primarily on financing terms rather than after-sales coverage.
Agricultural Solar Pumps Market Segmentation
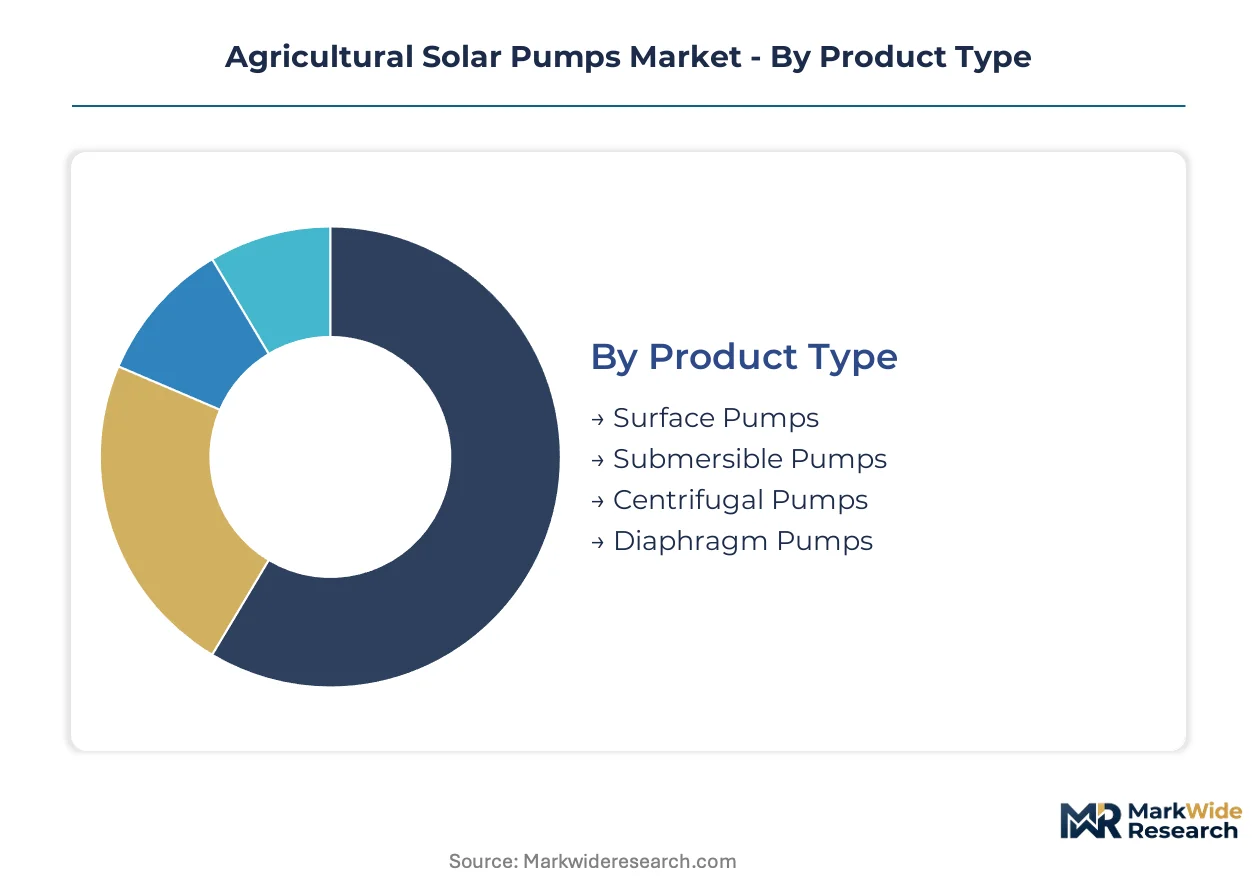
Segmentation in agricultural solar pumps reveals how equipment specifications, user economics, and regulatory frameworks intersect to determine commercial viability across disparate farming contexts. Understanding these divisions exposes where margin pools concentrate and which technology configurations align with subsidy eligibility requirements.
Product Type:
BIS mandates under India's MNRE specifications create divergent compliance pathways for surface versus submersible configurations, with IEC 62253 certification timelines extending 8-14 months for systems targeting subsidy access.
- Surface Pumps:These units mount above water level and operate via suction lift, typically serving shallow wells under 7 meters depth. Demand clusters across South Asian smallholdings where groundwater tables remain accessible and capital constraints favor lower first-cost equipment. India's PM-KUSUM scheme disbursement timelines favor these configurations for marginal farmers in Gujarat and Rajasthan.
- Submersible Pumps:Designed for deep-well deployment with motor and pump sealed in a single housing, these systems achieve 20-100 meter total dynamic heads. Commercial growers in Spain and Italy specify brushless DC variants for high-head horticulture applications. Higher technical barriers and extended service intervals sustain premium positioning for qualified suppliers with in-house motor manufacturing.
- Centrifugal Pumps:Impeller-based designs convert rotational energy into hydraulic pressure for medium-head irrigation networks. Agricultural cooperatives in Brazil deploy these for collective distribution systems serving multiple smallholders.
- Diaphragm Pumps:Positive displacement mechanisms handle viscous fluids and suspended solids in livestock watering applications. FDA material requirements for potable water contact elevate compliance costs in US dairy operations.
Submersible pumps handle the majority of throughput; hybrid-ready configurations are gaining share fastest as farmers seek dispatchable water delivery beyond peak sun hours.
End User:
Credit access and land tenure patterns stratify adoption economics across user categories, with mobile-money-enabled financing unlocking segments excluded from traditional agricultural lending.
- Farmers:Individual smallholders dominate unit volume, typically deploying 1-3 kW systems for supplemental irrigation on holdings under 5 hectares. Pay-as-you-go models in East Africa are penetrating this segment through metered water access rather than equipment ownership.
- Agricultural Cooperatives:Collective purchasing entities aggregate demand for shared infrastructure, achieving scale economies in installation and maintenance. Tamil Nadu and Karnataka dealer networks now compete primarily on financing terms for cooperative procurement.
- Commercial Growers:Large horticulture and viticulture operations specify high-head, variable-flow systems with intelligence-enabled remote monitoring. EU Carbon Border Adjustment Mechanism pressures are incentivizing renewable irrigation credentials for European export compliance.
- Research Institutions:Demonstration and pilot deployments test agrivoltaic co-location and efficiency-optimized configurations. China's Ministry of Water Resources restrictions on diesel-powered tube wells redirect institutional investment toward solar validation projects in North China Plain provinces.
Farmers account for the greatest installed base; commercial growers are expanding most quickly as carbon accounting reshapes procurement specifications.
Technology:
PERC and TOPCon cell architectures are lifting output per installed watt, reducing array footprint requirements and enabling deployment on land-constrained holdings.
- Photovoltaic:Pure solar configurations represent the dominant installed base, converting direct irradiance into mechanical lift without storage intermediation. Peak sun hour limitations constrain water delivery timing, restricting adoption in crops requiring consistent soil moisture.
- Hybrid Systems:Battery-coupled architectures enable dispatchable pumping across dawn and dusk periods, extending operational windows for high-value horticulture. Lithium-ion pack pricing and replacement cycles currently limit penetration among credit-constrained smallholders.
- Wind-Solar Hybrid:Complementary generation profiles smooth output variability in regions with correlated diurnal wind patterns. Coastal Maharashtra and Gujarat installations are testing these configurations for groundwater extraction.
- Off-Grid Solutions:Standalone systems without grid fallback serve areas with unreliable or nonexistent electrical infrastructure. Sub-Saharan Africa's technical service scarcity elevates downtime risk and total cost of ownership for these deployments.
Photovoltaic technology commands the largest installed base; hybrid systems are climbing the fastest as battery economics gradually improve.
Application:
Water-use regulations and livestock welfare standards are segmenting compliance requirements, with irrigation facing the most stringent groundwater governance constraints.
- Irrigation:Groundwater extraction for crop production represents the primary demand driver, with state-level water rights regimes in India creating permitting unpredictability. China's dual carbon goals and MIIT efficiency mandates are accelerating displacement of diesel-powered tube wells.
- Livestock Watering:Remote pasture applications favor solar autonomy where grid extension proves uneconomical. FDA regulates materials contacting potable water in US applications, while REACH restricts hazardous substances in European-sourced electronic components.
- Pond Management:Aeration and circulation systems maintain water quality in aquaculture and recreational applications. Southeast Asian shrimp farming operations are adopting these configurations for off-grid coastal sites.
- Water Supply:Community-scale distribution systems serve rural settlements without centralized infrastructure. Brazil's semi-arid northeast deploys solar pumping for human consumption alongside agricultural use.
Irrigation handles the majority of throughput; livestock watering is expanding most quickly as pastoral intensification spreads across arid zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PM-KUSUM scheme and China's dual carbon goals are redirecting agricultural irrigation investment toward photovoltaic extraction systems across arid cultivation belts.
India
Rajasthan, Gujarat, and Maharashtra smallholders drive volume demand as state nodal agencies streamline subsidy disbursement timelines under MNRE specifications. BIS mandates performance testing for subsidy eligibility, locking qualified suppliers into certification maintenance cycles. Tamil Nadu and Karnataka dealer networks now compete primarily on financing terms for cooperative procurement.
China
North China Plain groundwater stress mandates are redirecting tube well investment toward solar-powered extraction systems. MIIT efficiency mandates under revised GB 18613-2020 specifications require domestic motor efficiency certification for state procurement access. Yangtze River Delta manufacturers are dual-certifying under IEC and GB regimes to maintain Belt and Road and European distribution channels.
Brazil
Semi-arid northeast smallholders and agricultural cooperatives deploy collective distribution systems serving multiple users. ANVISA regulates materials for potable water contact in livestock applications. Ceará and Pernambuco installations are expanding from human consumption into supplemental irrigation for drought-resistant crops.
United States
California and Arizona commercial growers specify high-head systems for horticulture and viticulture with remote monitoring capabilities. FDA regulates materials contacting potable water in livestock watering applications. Central Valley operations are adopting renewable irrigation credentials to satisfy EU Carbon Border Adjustment Mechanism pressures on embedded emissions accounting.
Germany
Bavaria and Baden-Württemberg precision agriculture operations integrate photovoltaic pumping into renewable energy portfolios. REACH restricts hazardous substances in electronic components, elevating compliance costs for new entrants. ECHA enforcement is locking incumbents into supply chain documentation cycles for European-sourced controller assemblies.
Agricultural Solar Pumps Market Competitive Landscape
Listed leaders compete with private specialists across certification-qualified and marginal participant tiers. The vendor base stratifies into IEC 62253-certified suppliers with in-house motor manufacturing and regional assemblers dependent on imported component kits. Three archetypes dominate: vertically integrated pump specialists with captive motor production, solar module manufacturers extending into downstream pumping equipment, and regional distributors bundling hardware with localized service infrastructure. Competitive moves concentrate on certification maintenance cycles and pay-as-you-go financing model deployment.
Within the premium-tier vector, Grundfos and Franklin Electric exemplify in-house motor and controller manufacturing capabilities that sustain positioning in submersible systems. Shakti Pumps anchors the India-focused archetype through deep rural distribution networks. Lorentz and RPS Solar Pumps occupy positions among specialists emphasizing off-grid and hybrid system configurations for Sub-Saharan African and South Asian markets.
| Leading Market Players |
|---|
| Grundfos |
| Lorentz |
| Shakti Pumps |
| Franklin Electric |
| Rafsun |
| RPS Solar Pumps |
| Xylem |
| KSB SE & Co |
| Jakson Group |
| Others |
Pricing and Supply Chain Analysis
Polysilicon substitution for conventional silicon feedstocks is redrawing manufacturing geography toward Chinese ingot and wafer producers while compressing margin visibility for downstream pump assemblers exposed to input cost volatility.
Pricing Analysis
Certification level under IEC 62253 creates the primary spread between qualified suppliers and marginal participants. Three-tier pricing structure across premium, standard, and economy levels reflects in-house motor manufacturing depth versus kit-dependent assembly. Cost compression in economy tiers is intensifying because subsidy disbursement timelines reward faster certification pathways. Smallholder farmers in South Asia exhibit highest price sensitivity, while commercial growers in Southern Europe prioritize reliability guarantees over unit economics.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe and Asia-East Africa trade lanes are elevating inbound logistics costs for controller and inverter assemblies. Manufacturing concentrates in China, India, and Germany, with permanent magnet motors drawing from rare earth processing clusters in Jiangxi and Inner Mongolia. Single-source vulnerability in MPPT controller semiconductors poses structural risk. Distribution runs through rural dealer networks in India and cooperative procurement channels in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across state-level subsidy regimes and groundwater governance systems is creating niche opportunities for regionally specialized suppliers.
For Market Incumbents: Secure certification maintenance cycles ahead of evolving MNRE and MIIT efficiency mandates to lock out marginal competitors. Deepen backward integration into permanent magnet motor manufacturing to defend margin position against kit-dependent assemblers. Prioritize captive service infrastructure in Tamil Nadu and Karnataka where dealer competition has shifted to financing terms. For New Entrants and Emerging Players: IEC 62253 fast-track partnerships with accredited testing laboratories in India and China compress subsidy access timelines against incumbent certification pipelines. Target pay-as-you-go financing models in East Africa where mobile-money penetration outpaces traditional agricultural credit. Lead with agrivoltaic co-location configurations in land-scarce South Asian markets. For Investors and Strategic Acquirers: The market sits at a subsidy-dependency phase that favors vertically integrated pump specialists with captive motor production and established certification portfolios. Long-term viability centers on manufacturers capable of dual-certifying under IEC and GB regimes for Belt and Road and European access. Watch lithium-ion pack pricing trajectories as the inflection signal for hybrid system penetration among credit-constrained smallholders.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62253 Certification Fast-Track | Accelerates subsidy eligibility timelines under India's MNRE specifications for qualified suppliers. |
| Permanent Magnet Motor Manufacturing Scale-Up | Captures margin pool in submersible systems through in-house magnet and winding capabilities. |
| Pay-as-you-Go Financing Platform Launch | Unlocks East African smallholder segments excluded from traditional agricultural credit channels. |
| Agrivoltaic Co-Location Deployment | Expands addressable land area beneath elevated panel arrays in South Asian markets. |
| Dual-Certification Under IEC and GB Regimes | Maintains access to Belt and Road pipelines and European distribution for export-oriented suppliers. |
Research Methodology
A standing panel of pump system engineers, rural dealer network managers, state nodal agency procurement officers, and agricultural cooperative purchasing leads provided ongoing calibration across primary fieldwork. Secondary validation drew from MNRE subsidy disbursement records, BIS certification databases, MIIT efficiency mandate filings, and customs data on photovoltaic module and controller imports. Bottom-up installation forecasts triangulated against top-down irrigation equipment expenditure estimates.
Consistency checks validated volume and value outputs against state-level PM-KUSUM deployment targets and North China Plain groundwater stress mandate implementation rates. Segmentation modeling spanned product type, end user category, technology configuration, and application across the projection horizon. CAGRs derived from fitted growth curves incorporating solar module cost deflation trajectories and diesel price volatility assumptions.
Decision-makers should treat outputs as directional under stable subsidy regime continuity and lithium-ion pricing gradualism; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
Fertigation Control System Market
Farm Equipment and Irrigations
Watering Cans Market
Farm Equipment and Irrigations
Global Irrigation Machinery Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market
Farm Equipment and Irrigations
Grass Trimmer Market
Farm Equipment and Irrigations
Drip Irrigation Systems Market
Farm Equipment and Irrigations
Golf Irrigation Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market
Farm Equipment and Irrigations
Global Fruit Picker Market
Farm Equipment and Irrigations
Irrigation Liner Market
Farm Equipment and Irrigations
Hose Reel Irrigation Machine Market
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Asia-Pacific Irrigation Machinery Market
Farm Equipment and Irrigations
India Agricultural Irrigation Machinery Market