
 Mini Tractors Market | 2026-2036
Mini Tractors Market Size, Share, and Industry Trends Forecast 2026-2036
Mini Tractors Market Foresight
India's Gujarat manufacturing corridor is narrowing the cost gap between domestic and imported compact powertrain assemblies. John Deere leverages its anchored dealer network across Punjab and Haryana to sustain parts availability. Kubota dominates hydrostatic transmission integration for sub-compact lines. Mahindra competes on vertical integration into cast-iron engine blocks and forged axles.
Mini tractors are self-propelled agricultural machines typically rated below 40 HP, featuring three-point hitch systems and power-take-off shafts rated at 540 or 1000 RPM for implement drive. These machines serve primary tillage, mowing, loader work, and precision planting on plots under 10 hectares where full-size equipment lacks maneuverability. Compact mini tractors lead volume shipments across European vineyard and hobby-farm channels, while four-wheel-drive configurations capture the fastest expansion in Asian wet-paddy applications. The 20-30 HP power band anchors margin pools through higher attachment sales density and replacement-part throughput.
EPA Tier 4 Final standards in the United States and India's CEA emission norms for agricultural engines are forcing particulate-filter and common-rail retrofit investments across supplier bases. CE marking requirements under the EU Machinery Directive restrict market access for non-certified Asian OEMs seeking European vineyard and landscaping contracts. Stakeholders must monitor how India's BIS certification timelines and evolving F-Gas Regulation scope for refrigerant-based cab cooling reshape product development roadmaps and factory certification budgets.
Market Dynamics
Engine downsizing and emissions compliance are compressing powertrain architectures across the Mini Tractors Market, forcing manufacturers to redesign cooling packages and after-treatment systems for sub-40 HP platforms.
Growth Catalysts
- India's PLI scheme for farm mechanization:Production-linked incentives for component localization are pulling assembly capacity into Gujarat and Maharashtra, shortening lead times for domestic powertrain sourcing.
- Orchard mechanization in Southeast Asia:Smallholders in Vietnam and Thailand are retrofitting three-point hitch implements for inter-row cultivation, expanding addressable machine hours per hectare.
- Hydrostatic transmission maturation:Continuously variable drive systems are eliminating clutch maintenance burdens for rental fleet operators, improving uptime in wet-paddy field cycles.
Market Restraints
- Cast-iron foundry concentration:Engine block and axle housing supply clusters in eastern China create single-source vulnerability for non-integrated assemblers.
- EPA Tier 4 Final retrofit costs:Particulate filter and selective catalytic reduction hardware add fixed cost layers that compress margins on sub-25 HP price-sensitive segments.
- Used equipment import flows:Refurbished Japanese compact tractors displace new-unit demand in Bangladesh and Sri Lankan coastal districts.
Strategic Opportunities
- Electric powertrain pilot zones:Battery-swappable sub-compact platforms align with India's CEA zero-emission agricultural equipment trials in Punjab canal-irrigated belts.
- Telematics-enabled rental pools:Hourly usage tracking and remote diagnostic integration allow cooperative lending programs to underwrite equipment loans against actual utilization data.
- CE marking pathway for Asian OEMs:EU Machinery Directive certification opens vineyard and landscaping contract channels in France, Italy, and Spain currently served by established European brands.
Industry Challenges
- After-treatment calibration expertise:Common-rail injection and EGR valve tuning require technician training programs that rural dealer networks lack.
- BIS certification timeline uncertainty:Bureau of Indian Standards approval delays for new engine families freeze product launch windows during critical planting-season demand peaks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini Tractors Market |
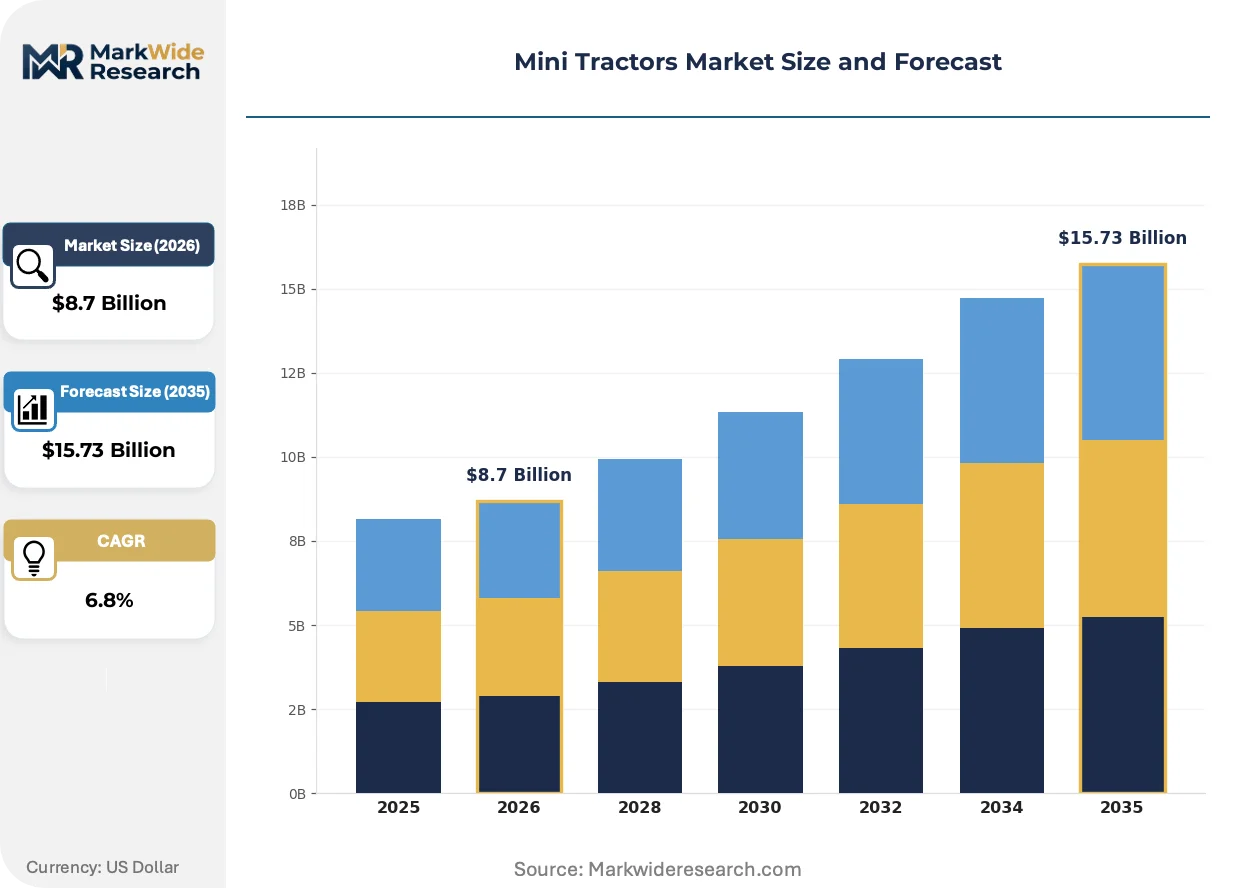
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Mini Tractors, Compact Mini Tractors, Garden Tractors, Sub-Compact Tractors End Use: Agricultural Use, Residential Landscaping, Commercial Landscaping, Construction Power Rating: Less than 20 HP, 20-30 HP, 30-40 HP, More than 40 HP Drive Type: Two-Wheel Drive, Four-Wheel Drive, All-Terrain Drive, Hydrostatic Drive |
| Companies Covered | New Holland, TYM, John Deere, VST, Swaraj, Kubota, Massey Ferguson, Sonalika, Mahindra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini Tractors Market Shifts & Advancements
Powertrain electrification and precision agriculture integration are redefining machine architecture, shifting competitive advantage from mechanical durability to sensor fusion and data interoperability.
Diesel-electric hybrid architectures are hybridizing conventional mechanical PTO systems with onboard battery buffers, enabling torque-assist for high-draft tillage without engine upsizing. European vineyard operators in Burgundy and Tuscany are piloting these platforms for slope stability. The technology is hybridizing the historical trade-off between horsepower rating and fuel economy, allowing 25 HP-rated machines to deliver 35 HP-equivalent drawbar pull during transient load spikes.
EPA Tier 4 Final and India's CEA emission norms are forcing synchronized particulate-filter regeneration cycles and urea dosing strategies across supplier development programs. Engine calibration teams must now coordinate with exhaust after-treatment specialists earlier in the design phase. Sub-25 HP equipment sold into California's San Joaquin Valley faces additional CARB verification steps that extend homologation calendars by four to six months.
Cooperative procurement consortia are consolidating equipment orders across fifty-plus member farms, extracting volume discounts previously reserved for municipal fleet purchasers. These buying pools compress dealer margin structures while demanding standardized attachment interfaces and shared spare-parts inventories. The model is most developed in Gujarat's Anand and Mehsana districts, where dairy cooperatives have extended their collective purchasing infrastructure into mechanization assets.
Mini Tractors Market Segmentation
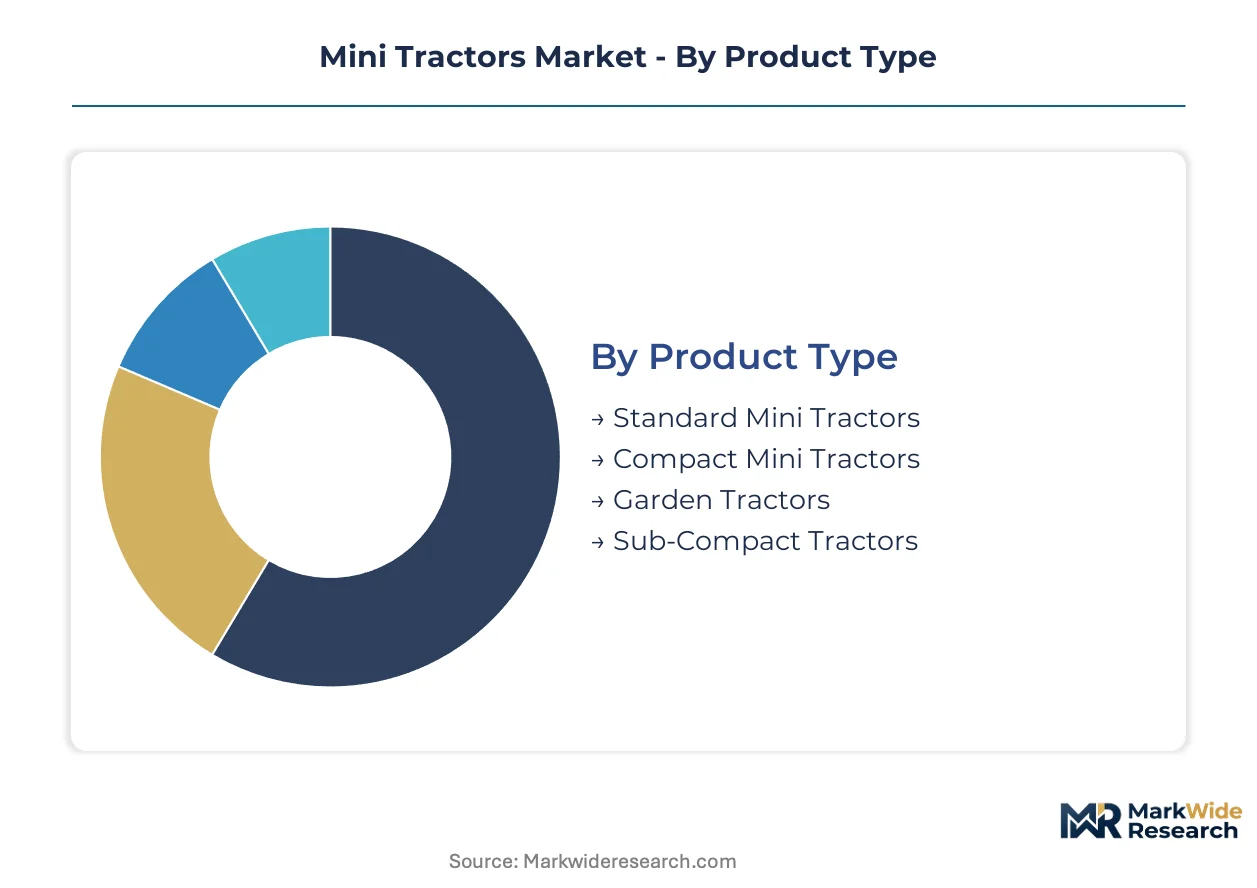
Mini tractor segmentation reveals distinct equipment architectures optimized for plot size, soil conditions, and attachment versatility. Powertrain configuration and chassis dimensions determine addressable applications, from precision vineyard work to commercial loader operations.
Product Type:
Equipment architecture separates by chassis scale and three-point hitch capacity, with frame geometry dictating implement compatibility and maneuverability envelopes.
- Standard Mini Tractors:Three-point hitch systems rated at 540 RPM PTO with Category I implement mounting serve primary tillage and mowing on holdings of 5-15 hectares. Demand clusters in India's Maharashtra cooperative networks where mid-scale farmers prioritize attachment interchangeability over premium hydrostatic controls.
- Compact Mini Tractors:Narrow-track configurations with sub-48-inch wheel widths navigate European vineyard rows and Southeast Asian orchard interstices. French Burgundy operators specify these platforms for slope-stability ballast packages and precision spraying booms.
- Garden Tractors:Rear-engine layouts with belt-driven mower decks target residential turf maintenance on plots under 2 hectares.
- Sub-Compact Tractors:Front-loader-ready chassis with hydrostatic transmissions dominate US hobby-farm channels and Japanese terraced rice operations.
Compact Mini Tractors commands the established base. The steepest expansion runs through Sub-Compact Tractors.
End Use:
Application intensity varies by annual machine-hour utilization, with commercial operators demanding durability warranties that residential users rarely activate.
- Agricultural Use:Primary tillage, seedbed preparation, and crop transport on smallholder plots drive attachment sales density. Indian Punjab canal-irrigated belts concentrate demand for 540 RPM PTO-driven rotavators and laser-guided land levelers.
- Residential Landscaping:Mowing and material handling on estate properties and hobby farms rarely exceed 200 annual operating hours.
- Commercial Landscaping:Municipal parks departments and golf course maintenance crews specify quick-attach loader buckets and backhoe configurations for multi-implement daily cycles.
- Construction:Skid-steer alternatives for light grading and trenching on confined job sites favor four-wheel-drive traction and rear remote hydraulic circuits.
Agricultural Use anchors volume shipments. Commercial Landscaping shows the steepest expansion trajectory.
Power Rating:
Engine displacement bands align with implement draft requirements and emissions compliance thresholds, with regulatory breakpoints at 19 HP and 26 HP in key markets.
- Less than 20 HP:Single-cylinder diesel engines below EPA Tier 4 Final thresholds avoid after-treatment hardware in US markets. Indian Gujarat horticulture belts specify these platforms for inter-row cultivators and portable sprayer pumps.
- 20-30 HP:Three-cylinder common-rail architectures balance fuel efficiency with sufficient PTO output for rotary tillers and small square balers. This band captures replacement-part throughput and attachment upsell margins.
- 30-40 HP:Turbocharged intercooled engines with 1000 RPM PTO options serve round-baler and flail-mower applications on dairy operations.
- More than 40 HP:Approaching utility-tractor territory, these platforms face competition from full-size equipment on cost-per-horsepower metrics.
20-30 HP commands the established base. Less than 20 HP gains share fastest in emission-sensitive regulatory environments.
Drive Type:
Power transmission architecture determines operator skill requirements, maintenance intervals, and traction performance in saturated soil conditions.
- Two-Wheel Drive:Mechanical gearboxes with clutch-based shuttle shifting minimize acquisition cost for dry-land row-crop applications. Indian Gujarat groundnut and cotton belts specify these configurations for flat terrain with minimal seasonal mud.
- Four-Wheel Drive:Front-axle engagement via mechanical or electro-hydraulic couplers delivers drawbar pull in wet-paddy and sloped vineyard terrain. Vietnamese Mekong Delta smallholders retrofit these platforms for dual-crop rice and vegetable rotations.
- All-Terrain Drive:Articulated steering and oscillating frames navigate undulating topography with minimal soil compaction.
- Hydrostatic Drive:Continuously variable transmission pedals eliminate clutch operation, reducing operator fatigue in loader-intensive commercial applications.
Four-Wheel Drive commands the established base. Hydrostatic Drive climbs the fastest as rental fleets prioritize uptime over acquisition cost.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Mumbai anchors India's agricultural machinery import corridor, while the Port of Hamburg serves as Europe's primary entry point for Asian compact equipment. These maritime gateways determine regional inventory cycles and dealer stocking patterns.
India
Maharashtra and Gujarat states drive domestic absorption through cooperative lending infrastructure. The PLI scheme for farm mechanization pulls assembly capacity into the Gujarat manufacturing corridor, shortening powertrain lead times. Anand and Mehsana districts concentrate dairy cooperative procurement consortia that aggregate equipment orders across fifty-plus member farms.
United States
California's San Joaquin Valley imposes additional CARB verification steps that extend homologation calendars by four to six months for sub-25 HP equipment. EPA Tier 4 Final standards force particulate-filter and selective catalytic reduction hardware investments that compress margins on price-sensitive segments. Hobby-farm channels in the Pacific Northwest prioritize hydrostatic transmission configurations for loader-intensive operations.
China
Eastern China foundry clusters supply cast-iron engine blocks and axle housings to non-integrated assemblers across Asia. The concentration creates single-source vulnerability for manufacturers lacking captive casting capacity. MIIT emission standards for agricultural engines are tightening in parallel with India's CEA norms, forcing synchronized supplier development programs.
Germany
Bavaria and Baden-Württemberg host precision agriculture technology clusters that integrate sensor fusion into compact tractor architectures. CE marking requirements under the EU Machinery Directive restrict market access for non-certified Asian OEMs seeking vineyard and landscaping contracts. The KBA oversees type approval for diesel-electric hybrid platforms piloted in slope-stability applications.
Vietnam
Mekong Delta smallholders retrofit four-wheel-drive platforms for dual-crop rice and vegetable rotations, expanding addressable machine hours per hectare. Orchard mechanization in the Central Highlands drives inter-row cultivation implement sales. The country's national agricultural equipment regulator aligns emission testing protocols with ASEAN harmonization frameworks.
Mini Tractors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in powertrain and transmission supply. The vendor base organizes around three strategic archetypes: full-line agricultural equipment multinationals with anchored dealer networks, regional assemblers competing on vertical integration into cast-iron engine blocks, and transmission technology specialists dominating hydrostatic integration. Competitive moves concentrate on backward integration into captive foundry capacity and telematics-enabled rental pool partnerships.
Among full-line integrators, John Deere and New Holland occupy positions defined by dealer infrastructure depth rather than product differentiation alone. Kubota exemplifies the transmission-technology archetype through hydrostatic system integration. Mahindra represents the vertically integrated regional model with in-house casting and forging capabilities. These three anchors illustrate how competitive advantage in the Mini Tractors Market derives from supply-chain configuration rather than standalone engineering.
| Leading Market Players |
|---|
| New Holland |
| TYM |
| John Deere |
| VST |
| Swaraj |
| Kubota |
| Massey Ferguson |
| Sonalika |
| Mahindra |
| Others |
Supply & Pricing Matrix
Eastern China foundry clusters for cast-iron engine blocks and axle housings concentrate upstream bargaining power, anchoring margin pools with assemblers who lack captive casting capacity while forcing price discipline on non-integrated competitors across India and Southeast Asia.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure across the Mini Tractors Market, separating California CARB-verified premiums from baseline federal-compliant equipment and sub-25 HP segments that avoid after-treatment hardware entirely. Price differentiation rests on certification grade and geographic delivery cost, with Indian cooperative buyers exhibiting highest sensitivity to acquisition price while European vineyard operators absorb premiums for slope-stability ballast packages. Cost compression in sub-25 HP segments is intensifying because particulate-filter and selective-catalytic-reduction hardware adds fixed cost layers that manufacturers cannot fully pass through.
Supply Chain Analysis
Contract manufacturing for powertrain assemblies concentrates with Mahindra's captive foundries in Gujarat, Kubota's hydrostatic transmission specialists, and John Deere's anchored component suppliers across Punjab and Haryana. Geographic supply concentration centers on China for cast-iron castings, India for forged axles and engine blocks, and Germany for precision agriculture sensor packages. Raw material dependencies include high-grade pig iron, alloy steel forgings, and common-rail injection systems. Single-source vulnerability runs through eastern China foundry clusters. Distribution runs through cooperative procurement consortia in Gujarat's Anand district and anchored dealer networks across Maharashtra.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mini Tractors Market functions as a defensive-moat story where regulatory entrenchment around EPA Tier 4 Final and India's CEA emission norms creates high barriers to homologation that protect incumbents with established certification timelines.
For Market Incumbents: Insulate margin pools by deepening backward integration into captive foundry capacity for engine blocks and axle housings, eliminating single-source exposure to eastern China clusters. Anchor dealer network density in Maharashtra and Gujarat cooperative belts to preempt rental-fleet telematics partnerships that threaten parts-availability advantages. The threat of electric powertrain pilots in Punjab canal belts demands calibration expertise investments that rural networks currently lack. For New Entrants and Emerging Players: Build out CE marking certification pathways to access European vineyard and landscaping contracts in France, Italy, and Spain currently served by established brands. Target Bangladesh and Sri Lankan coastal districts where refurbished Japanese compact tractor flows have created price-conditioned demand for new-unit alternatives at economy positioning. A telematics-enabled rental pool partnership with Indian dairy cooperatives offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated regional assemblers with in-house casting and forging capabilities that compress cost structures against non-integrated competitors. Long-term viability across the analysis window hinges on regulatory compliance infrastructure rather than standalone engineering differentiation. Monitor BIS certification timeline delays as the critical signal for product launch window risk in India's peak planting-season demand cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Foundry Capacity | Mahindra's Gujarat casting facilities eliminate single-source dependence on eastern China clusters. |
| Telematics-Enabled Rental Pool Partnership | Cooperative lending programs in Anand district underwrite loans against actual utilization data. |
| CE Marking Certification Pathway Investment | EU Machinery Directive compliance opens vineyard contracts in Burgundy and Tuscany. |
| Hydrostatic Transmission Platform Expansion | Kubota's continuously variable systems reduce clutch maintenance burdens for Vietnamese rental fleets. |
| Electric Powertrain Pilot Zone Deployment | Battery-swappable platforms align with India's CEA zero-emission trials in Punjab canal belts. |
Research Methodology
Desk research of customs and trade data, agricultural machinery registration databases, and EPA certification filings preceded structured interviews with OEM procurement directors, cooperative lending program managers, and aftermarket service heads. Primary fieldwork with dealer network operators in Maharashtra and Gujarat validated secondary estimates of equipment turnover rates. Bottom-up triangulation across powertrain component sourcing and top-down reconciliation against cooperative procurement consortium order flows anchored volume estimates.
Assumptions held fixed include current EPA Tier 4 Final and India CEA emission norm stringency levels, while variables tested included PLI scheme extension timelines and electric powertrain adoption curves. The analytical framework modeled segmentation across power rating bands, drive type architectures, and end-use intensity tiers. CAGRs were derived from equipment replacement cycles and attachment sales density correlations. Forecast inputs incorporated cooperative lending penetration rates and foundry capacity utilization across eastern China clusters.
Sensitivities concentrate around BIS certification timeline delays, PLI scheme modification, and used Japanese equipment import flow volumes into South Asian markets. Quarterly review of homologation calendar extensions and cooperative procurement consortium formation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Global Crop Harvesting Robots Market
Agricultural Machinery
Brazil Agricultural Machinery Market
Agricultural Machinery
Electric Farm Tractor Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Rotary Tiller Market
Agricultural Machinery
Brazil Tractors Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
Utility Tractor Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
Agricultural Machinery Market
Agricultural Machinery
Canada Robotic Fruit Picker Market
Agricultural Machinery
Two Wheel Walking Tractor Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
South America Agricultural Tractors Market