
 Watering Cans Market | 2026-2036
Watering Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Watering Cans Market Analytics
Multi-source resin procurement is pivoting toward recycled-content mandates as brand owners face mounting compliance costs. Fiskars Corporation leverages its Nordic manufacturing footprint to sustain premium pricing across European garden centers. Haws Company, Inc. anchors its British heritage positioning through brass-and-copper specialist craftsmanship. Elho Group competes on injection-molding scale at its Netherlands facilities, serving mass-market retailers with color-customizable plastic lines.
A watering can is a portable vessel, typically fabricated from galvanized steel, blow-molded polyethylene, or terracotta ceramic, featuring a handle, fill opening, and perforated rose attachment to disperse water in controlled droplet patterns for soil hydration without root disturbance. Plastic variants dominate unit volume due to low per-unit cost and weather resistance, though metal watering cans command margin pools in heritage and professional horticulture channels. Decorative type segments are expanding fastest as consumers treat watering cans as visible patio accessories rather than concealed tools. Handheld form factors lead absolute sales, while electric variants remain nascent outside Japanese balcony-farming applications.
The EPA regulates phthalate content in polypropylene garden products under TSCA Section 6, compelling U.S. manufacturers to reformulate resins or absorb testing costs. REACH restrictions on cadmium and lead in metal alloys directly affect European zinc-coated watering can production, with ECHA enforcement tightening since the SCIP database launch. ISO 9001 certification has become a baseline threshold for accessing German and Dutch retail chains. Stakeholders must decide whether to absorb compliance premiums or accelerate backward integration into recycled resin compounding before regulatory thresholds tighten further.
Market Dynamics
REACH compliance in the European Union is tightening material specifications for plastic watering cans, forcing manufacturers to reformulate resins or absorb testing costs while residential gardening adoption accelerates among urban millennials across Germany and North America.
Growth Catalysts
- Balcony-farming culture:China's expanding urban agriculture movement drives demand for compact, precision-dispersion watering tools in high-density residential settings.
- REACH material mandates:European Union restrictions on cadmium and lead in metal alloys compel zinc-coated watering can producers to adopt compliant alloy formulations.
- Recycled-content procurement:Brand owners face mounting compliance costs that accelerate multi-source resin procurement toward post-consumer polyethylene feedstocks.
Market Restraints
- Petroleum-based resin volatility:Blow-molded polyethylene production faces input cost swings tied to crude oil price fluctuations.
- Asian supply concentration:Injection-molding capacity clusters in China's Guangdong and Zhejiang provinces, creating geographic dependency risk.
- Substitution by drip irrigation:Automated micro-irrigation systems threaten handheld watering can volumes in professional horticulture channels.
Strategic Opportunities
- Japanese electric variants:Battery-powered watering systems remain nascent outside Tokyo and Osaka balcony-farming applications, presenting first-mover white space.
- EU Green Deal tailwinds:Circular economy action plan incentives reward manufacturers with verified recycled-content supply chains.
- Direct-to-consumer channels:Specialty gardening platforms bypass mass-market retail gatekeepers for heritage brass-and-copper product lines.
Industry Challenges
- ISO 9001 certification timelines:German and Dutch retail chains demand quality management documentation that extends supplier onboarding cycles.
- SCIP database integration:ECHA enforcement of substance of concern reporting creates data management burdens for zinc alloy and plastic compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Watering Cans Market |
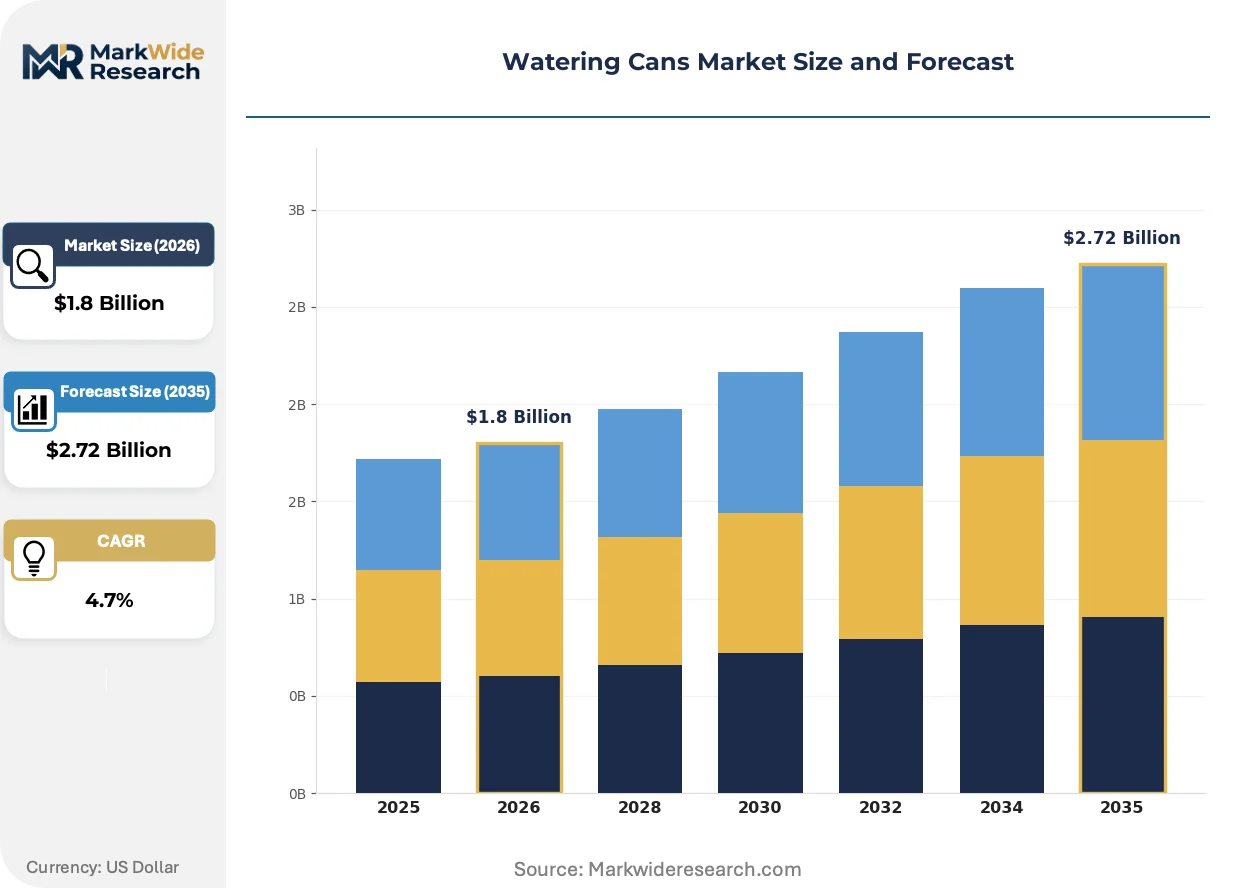
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Metal, Wood, Ceramic Type: Traditional, Retractable, Decorative, Functional Capacity: Small, Medium, Large, Extra Large Form Factor: Handheld, Wheelbarrow, Hanging, Electric |
| Companies Covered | Algreen Products Inc., Emsa GmbH, Fiskars Corporation, Hozelock Ltd., Haws Company, Inc., Behrens Manufacturing, LLC, Elho Group, Novelty Manufacturing Co., Bloem Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Watering Cans Market Evolving Landscape
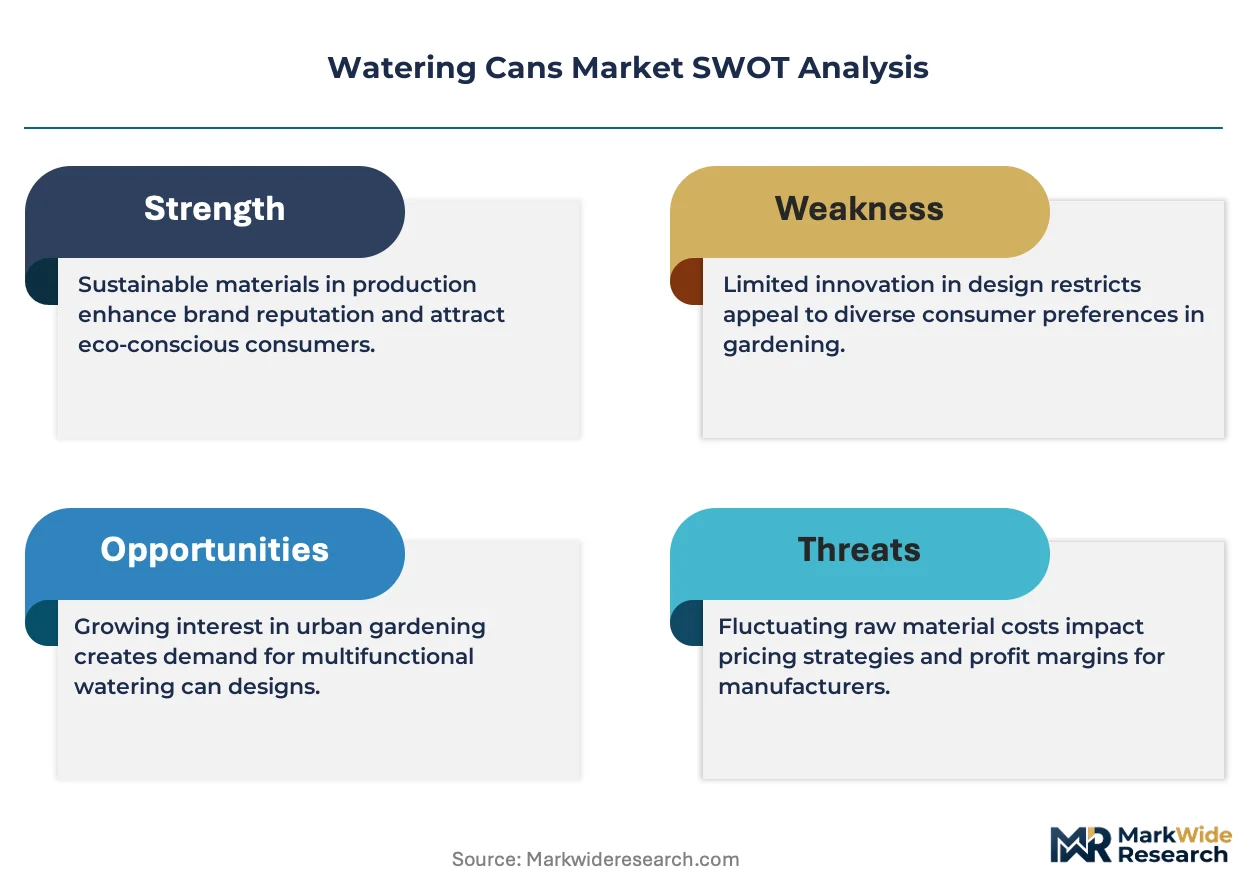
Product evolution in watering cans is bifurcating between heritage craftsmanship positioning and injection-molding scale efficiency, with regulatory pressure on material composition acting as the forcing mechanism for technical change.
Electrification of handheld watering tools is electrifying the Japanese residential segment. Battery-powered variants with programmable flow rates now penetrate Tokyo and Osaka balcony-farming households. This technology is compressing demand for traditional gravity-fed cans in space-constrained urban applications.
REACH restrictions on cadmium and lead in metal alloys now govern European zinc-coated watering can production. ECHA enforcement tightened following the SCIP database launch, compelling foundries to certify alloy compositions. Heritage metal specialists in Britain and Germany absorb premium testing costs to maintain brass-and-copper positioning.
Buyer procurement now favors visible patio accessories over concealed tools, elevating decorative type segments. Mass-market retailers in the Netherlands and Germany expand color-customizable plastic lines to capture this aesthetic shift. Urban millennial gardeners in North American cities treat watering cans as design objects, not utilitarian equipment.
Watering Cans Market Segmentation
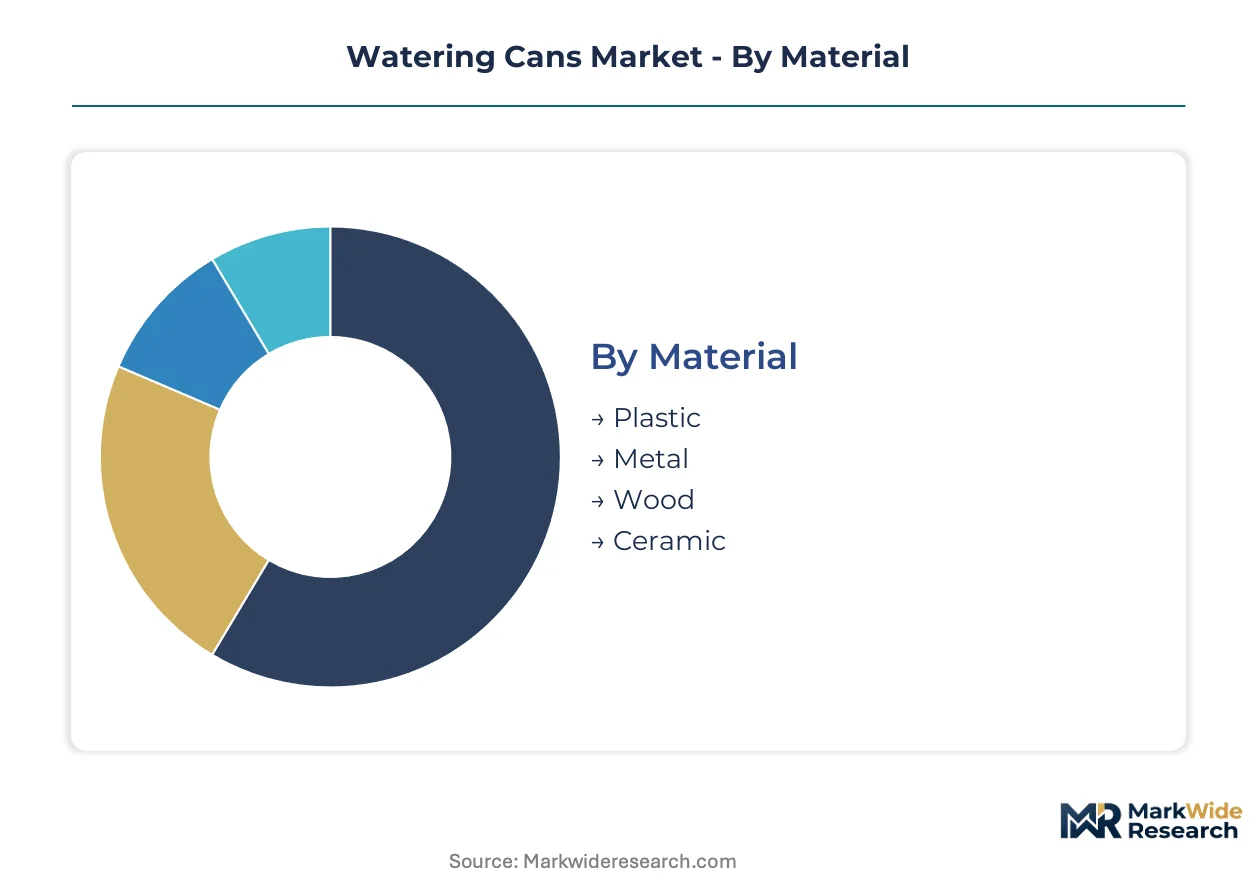
Watering can segmentation reveals divergent manufacturing economics across material classes and divergent user behaviors across capacity tiers. Producers must align tooling investments with whether demand flows through mass-market retail, specialty garden centers, or direct-to-consumer channels.
Material:
Customization versus standardization splits sharply across material categories, with blow-molded plastics permitting color and geometry flexibility while metal alloys demand fixed tooling for heritage forms.
- Plastic:Blow-molded polyethylene and polypropylene variants dominate unit economics through weather resistance and sub-dollar per-unit manufacturing cost. Dutch injection-molding clusters supply mass-market retailers across Germany and the Netherlands with color-customizable lines, though REACH compliance on phthalate content is forcing resin reformulation.
- Metal:Galvanized steel and zinc-coated alloys command margin pools in professional horticulture and heritage channels. British brass-and-copper specialists absorb ECHA-mandated testing costs to maintain artisan positioning, while REACH restrictions on cadmium and lead compel foundry certification.
- Wood:Cedar and teak constructions serve boutique garden center channels with biodegradable positioning. Scandinavian suppliers leverage FSC certification to access premium shelf space.
- Ceramic:Terracotta and glazed stoneware variants target decorative patio applications where visible aesthetics override portability concerns. Italian and Portuguese kiln operations feed Mediterranean retail demand.
Most installed capacity flows through plastic. Expansion is steepest in metal heritage positioning as urban millennials treat watering tools as design objects.
Type:
Cost tier stratification separates commoditized functional designs from premium decorative positioning that commands 3-4x retail markup.
- Traditional:Classic long-spout gravity-fed designs with perforated rose attachments remain the volume baseline for general soil hydration. German precision gardening specialists specify calibrated flow rates for seedling applications.
- Retractable:Collapsible silicone or accordion-fold constructions compress for balcony storage in Tokyo and Osaka high-density housing. Japanese battery-powered variants integrate programmable flow within this form factor.
- Decorative:Visible patio accessory positioning elevates hand-painted, sculptural, or vintage-reproduction designs. North American urban gardeners treat these as outdoor décor investments rather than concealed tools.
- Functional:Ergonomic grip engineering and precision-dispersion roses target repetitive-use professional horticulturists. Dutch greenhouse operators specify ISO 9001-certified suppliers for procurement compliance.
Traditional types absorb the largest production runs. Decorative types are climbing the fastest as consumer willingness-to-pay shifts toward aesthetic visibility.
Capacity:
Volume tiering maps directly to user physical constraints and task frequency, with small-capacity designs capturing balcony farmers and extra-large units serving commercial nursery operations.
- Small:Under-2-liter vessels suit indoor houseplant maintenance and seedling trays. China's expanding balcony-farming culture in Guangzhou and Shenzhen drives concentrated demand for single-hand maneuverability.
- Medium:2-5 liter workhorses balance portability and coverage for suburban container gardening. North American home improvement retailers stock this tier as the default recommendation.
- Large:5-10 liter constructions reduce refill frequency for raised-bed vegetable plots. German allotment gardeners specify these for weekend-intensive cultivation patterns.
- Extra Large:10+ liter wheelbarrow-integrated or shoulder-strap designs serve commercial landscapers and municipal parks departments. British heritage manufacturers maintain foundry capacity for this low-volume, high-margin tier.
Medium capacity moves the most units through retail. Small capacity is gaining share fastest as urban density rises and balcony agriculture normalizes.
Form Factor:
Customer type bifurcation separates handheld gravity-fed tools for casual gardeners from powered systems for precision agriculture and mobility-limited users.
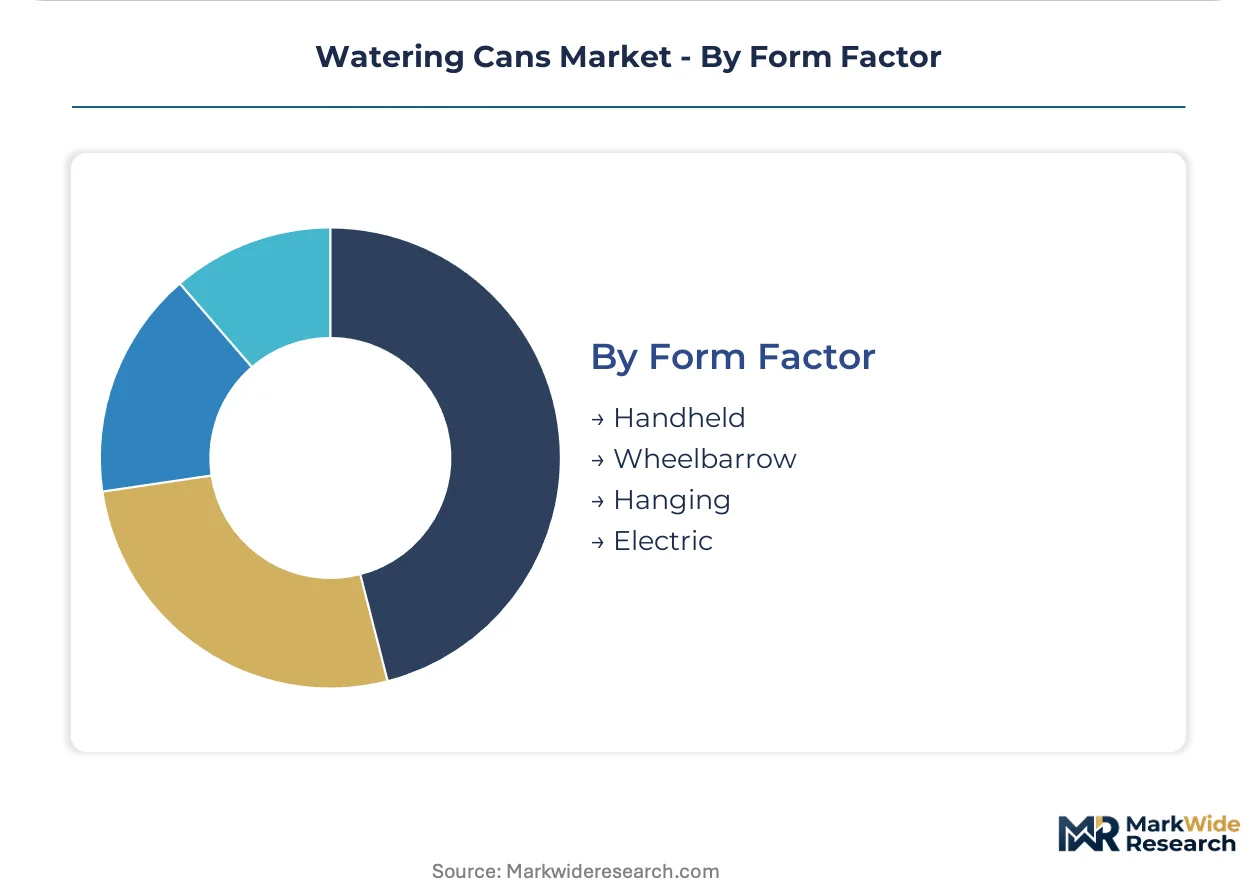
- Handheld:Single or double-handle portable designs constitute the absolute sales majority across all retail channels. Injection-molding scale at Netherlands and Guangdong facilities feeds this dominant form factor.
- Wheelbarrow:Trolley-mounted tanks with hose wands extend reach for large-property maintenance without repeated refilling. French and Italian estate gardening suppliers specialize in this commercial-grade tier.
- Hanging:Wall-mounted or greenhouse-rail systems enable gravity-fed drip for vertical growing installations. Dutch horticulture technology integrators specify these for controlled-environment agriculture.
- Electric:Battery-powered pumps with programmable flow rates penetrate Japanese balcony-farming households in Tokyo and Osaka. This technology remains nascent outside these dense urban applications.
Handheld form factors absorb nearly all production tooling. Electric variants hold the steepest expansion trajectory as battery density improves and urban space constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province anchors injection-molding capacity for plastic watering can production, supplying mass-market retailers across Germany, the Netherlands, and North America while REACH compliance costs reshape European sourcing patterns.
United States
Urban millennial gardeners in Brooklyn and Portland treat decorative watering cans as patio design objects rather than concealed tools. The EPA regulates phthalate content in polypropylene garden products under TSCA Section 6, compelling manufacturers to reformulate resins. Injection-molding operations in Ohio and Pennsylvania serve home improvement retailers with color-customizable plastic lines.
Germany
Precision gardening specialists in Bavaria specify calibrated flow rates for seedling applications, driving demand for ISO 9001-certified suppliers. REACH restrictions on cadmium and lead in metal alloys govern zinc-coated watering can production, with ECHA enforcement tightening since the SCIP database launch. Foundries in North Rhine-Westphalia absorb premium testing costs to maintain access to Dutch and German retail chains.
China
Balcony-farming culture in Guangzhou and Shenzhen concentrates demand for compact, single-hand maneuverable vessels under 2 liters. The country's national environmental regulator enforces dual carbon goals that pressure manufacturers toward recycled-content feedstocks. Injection-molding clusters in Zhejiang Province export blow-molded polyethylene variants to European mass-market retailers facing compliance cost pressures.
United Kingdom
Heritage brass-and-copper craftsmanship anchors British positioning in premium garden center channels, with urban gardeners in London treating vintage-reproduction designs as outdoor décor investments. REACH compliance on metal alloy compositions extends supplier onboarding cycles for foundries in the Midlands. Direct-to-consumer specialty platforms bypass mass-market retail gatekeepers for artisan product lines.
Netherlands
Greenhouse operators in the Randstad region specify ISO 9001-certified suppliers for procurement compliance in professional horticulture channels. The EU Green Deal circular economy action plan rewards manufacturers with verified recycled-content supply chains. Elho Group leverages injection-molding scale at its domestic facilities to serve mass-market retailers with color-customizable plastic lines.
Watering Cans Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electrification and recycled-material positioning as differentiation vectors. The vendor base spans Nordic manufacturing footprints, British heritage specialists, and Dutch injection-molding scale operations. Three archetypes dominate: heritage craftsmanship anchors, mass-market plastic molders, and precision horticulture suppliers. Competitive moves concentrate on backward integration into recycled resin compounding and direct-to-consumer channel development to bypass retail gatekeepers.
Among heritage specialists, Haws Company, Inc. and Fiskars Corporation exemplify contrasting geographic anchoring strategies, with the former representing British artisan positioning and the latter leveraging Nordic manufacturing footprints for premium pricing across European garden centers. Elho Group occupies the mass-market plastic tier, serving retailers through injection-molding scale. These three names illustrate how competitive positioning fragments across craftsmanship, scale efficiency, and regional manufacturing concentration.
| Leading Market Players |
|---|
| Algreen Products Inc. |
| Emsa GmbH |
| Fiskars Corporation |
| Hozelock Ltd. |
| Haws Company, Inc. |
| Behrens Manufacturing, LLC |
| Elho Group |
| Novelty Manufacturing Co. |
| Bloem Company |
| Others |
Value Network & Pricing Analysis
German and Dutch retail chain procurement concentrates demand among ISO 9001-certified suppliers, anchoring a contract-based long-term offtake model where volume commitments lock in preferential resin pricing and compliance documentation. This buyer archetype clustering transfers pricing power upstream to compounders with verified recycled-content supply chains, compressing margins for uncertified molders.
Pricing Analysis
Petroleum-based resin volatility passes through to blow-molded polyethylene unit costs, with crude oil price swings compressing margins at Netherlands and Guangdong injection-molding facilities. Three-tier pricing structure across premium, standard, and economy levels separates heritage brass-and-copper specialists from mass-market plastic molders and commodity zinc-coated producers. Cost compression in the plastic tier is intensifying because REACH phthalate reformulation adds testing overhead. Mass-market retailers exhibit highest price sensitivity; heritage garden centers accept 3-4x markups for artisan positioning.
Supply Chain Analysis
Direct-to-specialty-garden-center channels handle heritage brass-and-copper demand, while mass-market retail distribution runs through Dutch and German distribution hubs serving European garden centers. Injection-molding capacity clusters in China, the Netherlands, and Germany, with blow-molded polyethylene production drawing from petrochemical feedstocks in Guangdong and Zhejiang provinces. Raw material dependencies center on high-density polyethylene resin, zinc alloy ingots, and FSC-certified cedar. Single-source vulnerability in Guangdong Province creates geographic concentration risk for European retailers facing REACH compliance deadlines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Watering can production economics favor manufacturing footprint arbitrage between REACH-regulated European facilities and China's dual carbon goal jurisdictions, where recycled-content mandates accelerate faster than compliance cost absorption in the EU.
For Market Incumbents: Anchor certification investments in ISO 9001 and ECHA SCIP database integration to defend Dutch and German retail shelf access against emerging recycled-resin compounders. Backward integration into post-consumer polyethylene feedstock sourcing offsets petroleum-based resin volatility. Electrification of Japanese balcony-farming applications threatens handheld gravity-fed volumes; battery-powered R&D partnerships with Tokyo horticulture technology integrators secure positioning in the fastest-expanding form factor. For New Entrants and Emerging Players: Battery-powered programmable flow systems offer a technology-first wedge into underserved North American and European balcony-farming households where electric variants remain nascent outside Tokyo and Osaka. Target direct-to-consumer specialty platforms for heritage brass-and-copper positioning, bypassing mass-market retail gatekeepers that demand ISO 9001 documentation extending onboarding cycles. Recycled-content resin compounding with ECHA-compliant formulations captures EU Green Deal circular economy incentives. For Investors and Strategic Acquirers: Private equity firms with consumer goods manufacturing portfolios are the most active acquirer in this space, targeting mid-cap injection-molders with Netherlands or Germany facilities and established retail relationships. Long-term viability over the coming decade hinges on recycled-content supply chain verification and electrification R&D capabilities. Watch for SCIP database enforcement tightening as the inflection signal that separates compliant from stranded capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin Compounding | ECHA REACH compliance and EU Green Deal incentives reward verified post-consumer polyethylene feedstocks. |
| Direct-to-Consumer Channel Development | Specialty gardening platforms bypass Dutch and German retail gatekeepers demanding ISO 9001 documentation. |
| Battery-Powered Product Line Launch | Tokyo and Osaka balcony-farming households already adopt programmable flow electric variants. |
| Heritage Craftsmanship Brand Extension | London and Brooklyn urban gardeners treat brass-and-copper designs as outdoor décor investments. |
| SCIP Database Compliance Investment | ECHA enforcement of substance of concern reporting creates data management barriers for zinc alloy foundries. |
Research Methodology
Coverage spans Germany, the Netherlands, China, the United States, and the United Kingdom, with primary inputs from each region triangulated against secondary validation. Primary interviews engaged injection-molding plant managers, retail category buyers at German garden centers, zinc alloy foundry technical directors, balcony-farming technology integrators in Tokyo, and ECHA regulatory affairs specialists. Secondary sources included customs and trade data for polyethylene resin flows, SEC filings for listed garden products manufacturers, EPA TSCA Section 6 enforcement documentation, and EU SCIP database publication records. Bottom-up unit economics from manufacturing cost structures and top-down retail channel value flows were reconciled through iterative triangulation.
Rate-of-change decomposition across the analysis window isolated volume drivers by material class, capacity tier, and form factor evolution. The modeling framework segmented by plastic-metal-ceramic-wood material categories, traditional-retractable-decorative-functional type positioning, small-medium-large-extra large capacity tiers, and handheld-wheelbarrow-hanging-electric form factors. CAGRs were derived from installed capacity utilization rates, retail inventory turnover at Dutch and German chains, and balcony-farming household penetration curves in Guangzhou and Shenzhen. Forecast inputs incorporated REACH compliance cost trajectories and battery energy density improvement curves for electric variant adoption.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petroleum price volatility, ECHA enforcement intensity, and substitution by drip irrigation in professional horticulture channels. The analysis reflects assumptions on recycled-content mandate acceleration and electrification technology transfer from Japanese to European and North American markets. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Africa Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Weed Trimmer Market
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Golf Irrigation Market
Farm Equipment and Irrigations
Asia-Pacific Irrigation Machinery Market
Farm Equipment and Irrigations
Global Irrigation Automation Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
Agriculture Logistics Market
Farm Equipment and Irrigations
Lawn Edge Trimmer Market
Farm Equipment and Irrigations
Irrigation Controllers Market
Farm Equipment and Irrigations
Farm Equipment Rental Market
Farm Equipment and Irrigations
North America Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market