
 Fertigation Control System Market | 2026-2036
Fertigation Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Fertigation Control System Market Analysis
Consolidation among large-scale agricultural producers is recalibrating procurement patterns across the fertigation control system supply base. Lindsay Corporation leverages its pivot irrigation heritage to extend into integrated nutrient management platforms for broadacre operators. Netafim Limited anchors drip-fertigation hybrid systems through dense technical service networks in arid growing regions. Jain Irrigation Systems Ltd. competes on manufacturing scale across South Asian and African markets with locally assembled control units.
A fertigation control system combines irrigation infrastructure with precision nutrient delivery mechanisms, typically operating through injector pumps, mixing chambers, and sensor feedback loops that maintain electrical conductivity between 1.5 and 3.0 mS/cm depending on crop stage. Its primary commercial purpose is to synchronize water and fertilizer application with root-zone uptake patterns, minimizing leaching losses. Drip irrigation control hardware captures the dominant share of product-type value as perennial crop operators prioritize emitter-specific flow regulation. IoT-based solutions represent the fastest-expanding technology segment as cloud-connected soil probes enable remote pH and EC adjustment. Software platforms concentrate margin pools through recurring subscription models tied to agronomic analytics.
The EPA enforces Clean Water Act discharge limits that push US growers toward closed-loop fertigation with catchment monitoring. California's State Water Resources Control Board mandates groundwater sustainability plans that directly incentivize precision nutrient application in affected basins. Israel's Ministry of Agriculture and Rural Development maintains strict water-use efficiency standards that shape export-ready system specifications from domestic manufacturers. Stakeholders must weigh regulatory compliance timelines against the capital intensity of retrofitting legacy flood-irrigation blocks with sensor-driven fertigation networks.
Market Dynamics
Groundwater sustainability mandates across major agricultural basins are forcing capital reallocation toward sensor-driven nutrient management infrastructure, compressing payback period expectations from five years to under three.
Growth Catalysts
- California's SGMA implementation:The Sustainable Groundwater Management Act requires agricultural water districts in the Central Valley to meter and report nutrient loading, driving wholesale replacement of flood irrigation with closed-loop drip-fertigation networks.
- Controlled-environment agriculture:Greenhouse operators in the Netherlands and Spain deploy multi-zone fertigation controllers to optimize electrical conductivity gradients across tomato and pepper production cycles.
- Edge computing architectures:On-farm sensor hubs now process soil-moisture and pH data locally, enabling sub-minute nutrient adjustment without cloud latency.
Market Restraints
- Stainless steel price volatility:Injector pump housings and mixing chamber components face input cost swings tied to nickel supply disruptions from Indonesian export quotas.
- Technical interoperability gaps:Proprietary communication protocols between soil probes and central controllers force growers into single-vendor lock-in, raising total cost of ownership.
- Skilled technician scarcity:Calibration of EC/pH sensor arrays requires agronomic engineering expertise concentrated in Israel and California, limiting deployment velocity in emerging markets.
Strategic Opportunities
- Mexico's protected agriculture expansion:Sinaloa and Jalisco greenhouse clusters lack integrated fertigation expertise, creating service-attach revenue pools for controller vendors with Spanish-language technical support.
- EU Farm-to-Fork Strategy:The 50% nutrient reduction target by 2030 positions precision fertigation as compliance infrastructure, opening subsidy-funded procurement channels across Spain, Italy, and Greece.
- Subscription analytics convergence:Controller hardware vendors bundle cloud-based yield prediction models, converting one-time equipment sales into recurring agronomic software revenue.
Industry Challenges
- Legacy irrigation retrofit complexity:Flood-irrigated almond and pistachio orchards in California's San Joaquin Valley require trenched lateral installation and root-zone sensor placement, extending project timelines.
- Calibration drift management:Ion-selective electrodes in continuous-flow systems degrade under high-salinity conditions, demanding quarterly maintenance protocols that strain remote operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fertigation Control System Market |
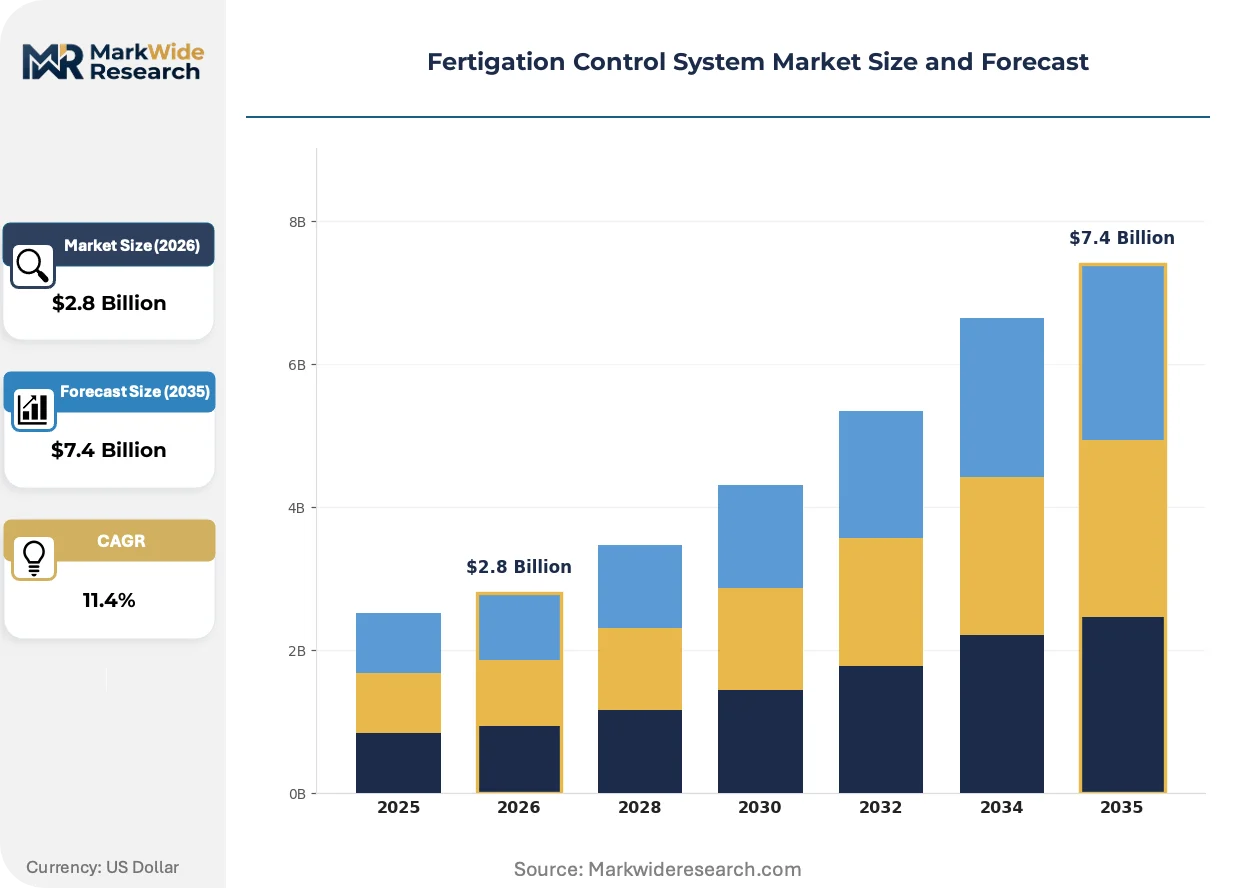
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Irrigation, Nutrient Dosing, Pressure Regulators, Sensors Technology: Automated Systems, IoT-Based Solutions, Manual Controls, Software Platforms End User: Agricultural Producers, Greenhouses, Landscape Professionals, Nurseries Application: Crop Production, Turf Management, Horticulture, Hydroponics |
| Companies Covered | Lindsay Corporation, Rivulis Irrigation, Netafim Limited, Galcon Ltd., Rain Bird Corporation, The Toro Company, Valmont Industries, Sentek Pty Ltd, Jain Irrigation Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fertigation Control System Market Emerging Trajectories
Real-time nutrient modulation is displacing scheduled batch application across high-value cropping systems. Three interconnected developments are compressing technology adoption cycles and reshaping vendor competitive requirements.
Hyperspectral imaging is integrating with fertigation control loops to enable non-destructive leaf-tissue nutrient mapping. Strawberry and blueberry growers in California and Florida deploy tractor-mounted sensors that feed nitrogen demand signals directly to injector pump variable-frequency drives. This convergence is integrating agronomic sensing with actuation hardware into unified feedback architectures that bypass manual tissue sampling entirely.
Israel's Ministry of Agriculture and Rural Development tightened water-use efficiency certification standards for exported irrigation equipment in 2023. Domestic manufacturers must now demonstrate 95% distribution uniformity and sub-5% coefficient of variation in emitter flow rates to qualify for government R&D grants. Drip-fertigation system vendors serving Middle Eastern and North African markets are redesigning pressure-compensating emitters to meet these specifications preemptively.
Buyer consolidation among berry cooperatives and vegetable marketing associations is concentrating procurement authority. Large-scale strawberry producers in California's Monterey County now negotiate enterprise-wide controller deployments across multiple ranches, displacing decentralized grower-level purchasing. This concentration is forcing smaller fertigation vendors to demonstrate multi-site remote management capabilities or exit the segment entirely.
Fertigation Control System Market Segmentation
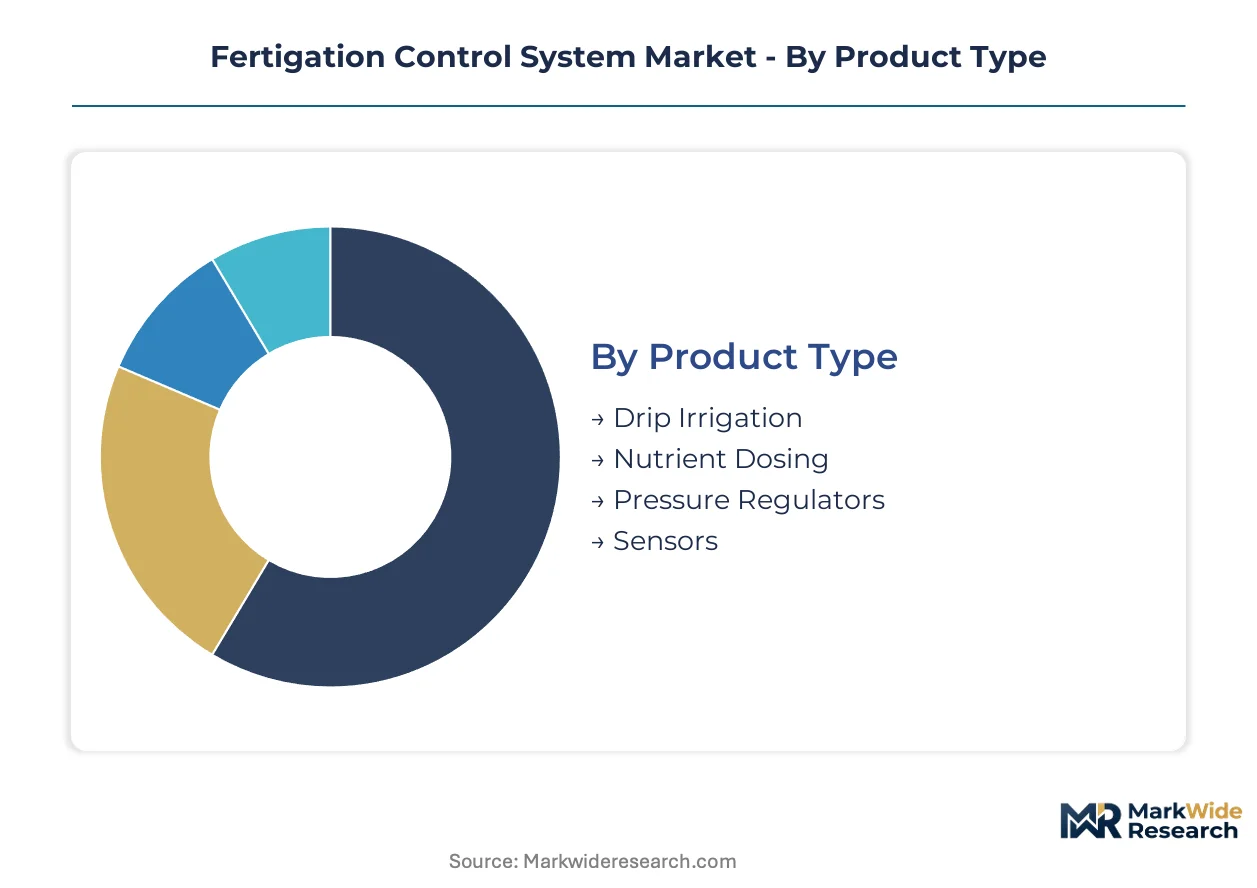
Fertigation control system procurement varies sharply by operational scale and regulatory exposure. Segmentation reveals which technology tiers command premium pricing and which face commoditization pressure from open-source alternatives.
Product Type:
EPA discharge permits and California State Water Resources Control Board groundwater mandates drive certification requirements for closed-loop systems, while basic drip components face lighter regulatory burden.
- Drip Irrigation:Emitter networks with pressure-compensating flow regulation dominate perennial crop installations. California almond and pistachio operators in the San Joaquin Valley prioritize this hardware to meet SGMA compliance timelines.
- Nutrient Dosing:Injector pump assemblies with variable-frequency drives enable real-time nitrogen adjustment based on soil-moisture feedback. Greenhouse clusters in the Netherlands and Spain specify these for multi-zone electrical conductivity management.
- Pressure Regulators:Diaphragm and piston-type units maintain distribution uniformity across elevation changes in undulating terrain.
- Sensors:Ion-selective electrode arrays for continuous pH and EC monitoring require quarterly calibration protocols.
Drip Irrigation sits at the top of the volume ranking, with Nutrient Dosing climbing the fastest.
Technology:
Cost stratification separates subscription-backed platforms from capital-intensive hardware, with mid-tier automation facing margin compression from both directions.
- Automated Systems:Programmable logic controllers with preset fertigation schedules reduce labor inputs for broadacre operators. Israel's Ministry of Agriculture and Rural Development efficiency certification requirements shape specifications for Middle Eastern and North African export markets.
- IoT-Based Solutions:Cloud-connected soil probes with edge computing architectures process data locally for sub-minute nutrient adjustment. Strawberry cooperatives in California's Monterey County deploy these for enterprise-wide multi-site coordination.
- Manual Controls:Basic timer-based injector systems serve price-sensitive nursery operations with limited technical staffing.
- Software Platforms:Agronomic analytics subscriptions convert equipment sales into recurring revenue through yield prediction bundling.
Automated Systems hold the largest installed base, though IoT-Based Solutions are expanding most quickly through greenhouse procurement channels.
End User:
Customer type determines service-attach potential and technical support intensity, with consolidated agricultural producers extracting steeper volume discounts than fragmented nursery operators.
- Agricultural Producers:Large-scale operators in California's Central Valley negotiate enterprise-wide deployments across multiple ranches. SGMA groundwater sustainability plans directly incentivize precision nutrient application infrastructure.
- Greenhouses:Controlled-environment agriculture facilities in Mexico's Sinaloa and Jalisco clusters lack integrated expertise, creating service revenue pools for vendors with Spanish-language technical support.
- Landscape Professionals:Turf management contractors prioritize portable dosing equipment for municipal and commercial contracts.
- Nurseries:Containerized plant operations favor entry-level timer systems with minimal calibration requirements.
Agricultural Producers generate the highest absolute demand, while Greenhouses show the steepest expansion trajectory as protected agriculture scales.
Application:
Application scope dictates sensor density and controller complexity, with hydroponic systems requiring the most intensive monitoring arrays.
- Crop Production:Row crop and orchard operators deploy zone-specific EC management to minimize nitrogen leaching. California's Central Valley dominates deployment volume under state groundwater mandates.
- Horticulture:High-value ornamental and vegetable operations invest in hyperspectral imaging integration for non-destructive leaf-tissue nutrient mapping.
- Turf Management:Golf course and sports field operators prioritize uniform coverage across large irregular areas.
- Hydroponics:Soilless cultivation systems demand continuous recirculation monitoring with sub-5% coefficient of variation in nutrient delivery.
Crop Production accounts for the greatest unit volume, with Horticulture gaining share fastest through precision agriculture adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel commands export-ready system specifications through stringent efficiency mandates, while the United States drives deployment volume through groundwater sustainability enforcement. Mexico's protected agriculture expansion creates service-attach opportunities for vendors with localized technical support.
United States
California's Central Valley dominates procurement as large-scale almond and pistachio operators retrofit flood-irrigated blocks with closed-loop drip-fertigation networks. The EPA enforces Clean Water Act discharge limits that push growers toward catchment monitoring. Strawberry cooperatives in Monterey County negotiate enterprise-wide controller deployments across multiple ranches.
Israel
Domestic manufacturers face 95% distribution uniformity certification requirements for exported irrigation equipment under tightened Ministry of Agriculture and Rural Development standards. These specifications shape product designs for Middle Eastern and North African markets. Technical service networks concentrate in arid growing regions where drip-fertigation hybrid systems anchor market presence.
Netherlands
Greenhouse operators deploy multi-zone fertigation controllers to optimize electrical conductivity gradients across tomato and pepper production cycles. EU Farm-to-Fork Strategy nutrient reduction targets position precision fertigation as compliance infrastructure. Controlled-environment agriculture facilities in the Westland region drive premium-tier hardware procurement.
Spain
Almería's greenhouse clusters integrate IoT-based soil-moisture feedback loops for real-time nutrient adjustment. The country's agricultural water districts prioritize emitter-specific flow regulation under EU environmental directives. Andalusian protected agriculture expansion concentrates demand for Spanish-language technical support capabilities.
Mexico
Sinaloa and Jalisco greenhouse clusters lack integrated fertigation expertise, creating service revenue pools for controller vendors. Protected agriculture scaling across the Bajío Region drives demand for automated nutrient dosing systems. Local procurement favors vendors with established technical training programs and regional spare parts distribution.
Fertigation Control System Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base spans irrigation heritage companies extending into nutrient management, drip-fertigation hybrid specialists, and manufacturing-scale operators serving emerging markets. Three strategic archetypes dominate: pivot-to-platform diversifiers, technical-service-intensive specialists, and volume-driven local assemblers. M&A activity concentrates on sensor technology tuck-ins, while geographic expansion targets Mexico's protected agriculture corridors.
Among heritage irrigation diversifiers, Lindsay Corporation and Valmont Industries occupy positions leveraging pivot infrastructure into integrated nutrient platforms. Netafim Limited anchors the specialist tier through dense technical service networks in arid growing regions. Jain Irrigation Systems Ltd. exemplifies the manufacturing-scale archetype with locally assembled control units across South Asian and African markets.
| Leading Market Players |
|---|
| Lindsay Corporation |
| Rivulis Irrigation |
| Netafim Limited |
| Galcon Ltd. |
| Rain Bird Corporation |
| The Toro Company |
| Valmont Industries |
| Sentek Pty Ltd |
| Jain Irrigation Systems Ltd. |
| Others |
Supply Flow & Price Mechanics
California's Sustainable Groundwater Management Act gates qualified supply and premium-tier pricing access by mandating closed-loop drip-fertigation networks with catchment monitoring, forcing buyers toward certified systems and compressing price floors for uncertified alternatives.
Pricing Analysis
Capacity additions in South Asia are reshaping price floors for entry-level timer-based systems while premium IoT platforms maintain subscription-backed pricing power. Three-tier pricing structure across premium, standard, and economy levels separates cloud-connected multi-zone controllers from programmable logic units and basic injector timers. Price differentiation hinges on Israel's Ministry of Agriculture efficiency certification and after-sales service bundling. Cost compression in economy tiers is intensifying because local assembly in India and Mexico reduces landed costs, though agricultural producers in California's Central Valley show lowest price sensitivity due to SGMA compliance deadlines.
Supply Chain Analysis
Freight costs from Israeli and Dutch manufacturing hubs to Mexico's Sinaloa and Jalisco greenhouse clusters elevate landed pricing for premium controllers. Supply concentrates in Israel, the Netherlands, and India, with injector pump housings and ion-selective electrode arrays drawing from stainless steel and specialized ceramic feedstock. Single-source vulnerability in nickel supply from Indonesian export quotas threatens input cost stability. Distribution runs through technical service networks that bundle installation and calibration, particularly in arid growing regions where drip-fertigation hybrid systems require dense field support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where buyer consolidation among California strawberry cooperatives and Dutch greenhouse operators shifts procurement toward premium specifications with multi-site remote management capabilities.
For Market Incumbents: Lock in enterprise-wide deployments across California's Monterey County berry cooperatives before SGMA compliance deadlines concentrate buyer power further. Deepen backward integration into ion-selective electrode manufacturing to offset nickel price volatility and sensor calibration drift costs. Acquire Spanish-language technical service capabilities to defend position in Mexico's protected agriculture expansion against emerging local assemblers. For New Entrants and Emerging Players: Begin with service-attach revenue models in Mexico's Sinaloa and Jalisco greenhouse clusters where integrated fertigation expertise is scarce and procurement favors vendors with regional spare parts distribution. Target nursery operations with simplified timer-based systems as the most penetrable segment, then ladder toward automated nutrient dosing through yield prediction software bundling. For Investors and Strategic Acquirers: Roll-up economics work for technical-service-intensive specialists because buyer consolidation demands multi-site remote management capabilities that fragmented local vendors cannot deliver. Five-to-ten-year viability hinges on recurring agronomic software revenue conversion. Target sensor technology tuck-ins with edge computing architectures. Watch California State Water Resources Control Board enforcement intensity as the inflection signal for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive supply of ion-selective electrodes reduces exposure to nickel price volatility from Indonesian quotas. |
| Multi-Site Remote Management Platform Launch | Monterey County strawberry cooperatives negotiate enterprise-wide deployments requiring centralized oversight capabilities. |
| Spanish-Language Technical Service Expansion | Sinaloa and Jalisco greenhouse clusters lack integrated fertigation expertise and favor vendors with localized training. |
| Subscription Analytics Convergence | Yield prediction bundling converts one-time controller sales into recurring revenue through cloud-based agronomic platforms. |
| Israeli Efficiency Certification Pre-Compliance | 95% distribution uniformity standards shape export-ready specifications for Middle Eastern and North African markets. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with irrigation infrastructure procurement managers, greenhouse operations directors, agronomic engineers, and aftermarket service heads with secondary validation through EPA discharge permit filings, California State Water Resources Control Board groundwater sustainability plan databases, Israeli Ministry of Agriculture efficiency certification records, and EU Farm-to-Fork Strategy implementation documents. Bottom-up controller shipment tallies by product type and technology tier were triangulated against top-down agricultural water district capital expenditure surveys.
Historical reference periods anchored the projection horizon through year-over-year installation tracking across California's Central Valley, Netherlands Westland region, and Almería greenhouse clusters. Segmentation dimensions modeled include product type, technology tier, end-user scale, and application intensity. CAGRs were derived from regression analysis against regulatory compliance timelines and protected agriculture expansion curves, with forecast inputs incorporating stainless steel price indices and skilled technician availability by region.
Caveats apply where nickel export quota enforcement, California groundwater basin prioritization schedules, or EU subsidy disbursement timing could materially shift the outlook. Forecasts reflect assumptions about regulatory compliance velocity and technology adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Asia-Pacific Irrigation Machinery Market
Farm Equipment and Irrigations
Global Fruit Picker Market
Farm Equipment and Irrigations
Lawn Edge Trimmer Market
Farm Equipment and Irrigations
Irrigation Liner Market
Farm Equipment and Irrigations
Ride-On Mower Market
Farm Equipment and Irrigations
Global Irrigation Automation Market
Farm Equipment and Irrigations
North America Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Irrigation Pumps Market
Farm Equipment and Irrigations
Rain Barrels Market
Farm Equipment and Irrigations
Grass Trimmer Market
Farm Equipment and Irrigations
Hose Reel Irrigation Machine Market
Farm Equipment and Irrigations
South America Irrigation Machinery Market
Farm Equipment and Irrigations
Tractor Rental Market
Farm Equipment and Irrigations
Agriculture Logistics Market
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market