
 Agriculture Logistics Market | 2026-2036
Agriculture Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Logistics Market Outlook
Modular cold chain bundling is expanding buyer choice across perishable agriculture corridors. CEVA Logistics leverages integrated temperature-controlled networks to sustain service consistency in Latin American fruit exports. Cargill anchors its advantage through backward integration into grain origination and port terminal control. CHS Inc. differentiates via farmer cooperative ownership structures that tighten input-to-export capture across the US Midwest.
Agriculture logistics encompasses the specialized movement, storage, and handling of crops, livestock inputs, and food products from farm gate to processing or retail destination, requiring controlled atmosphere specifications, moisture management protocols, and contamination prevention systems to preserve commodity grade and food safety. The cold chain segment leads margin capture due to pharmaceutical-grade temperature precision requirements and spoilage cost exposure, while freight forwarding occupies the broadest volume base across bulk grain and oilseed movements. Road transport dominates last-mile flexibility for time-sensitive dairy and fresh vegetable delivery, though rail transport sustains cost efficiency on high-volume soybean and corn routes from interior production belts to coastal export terminals.
The US Department of Transportation enforces hours-of-service rules and electronic logging mandates that reshape fleet utilization and driver availability across interstate agricultural hauls. The EU Green Deal's Fit for 55 framework tightens emissions standards for refrigerated transport units, forcing carrier investment in alternative-fuel cold chain assets. Stakeholders must monitor how California's CARB regulations and Brazil's CONAMA resolutions on transport emissions create divergent compliance cost structures across the hemisphere's dominant export corridors.
Market Dynamics
The EU Green Deal's Fit for 55 framework is forcing refrigerated fleet operators to retire diesel assets prematurely and accelerate alternative-fuel adoption across European agricultural corridors. This regulatory compression cascades through cold chain economics, reshaping carrier investment cycles and equipment depreciation schedules.
Growth Catalysts
- EU Green Deal mandates:The Fit for 55 framework tightens emissions standards for refrigerated transport units, compelling fleet renewal and creating demand for electric and hydrogen-powered cold chain assets across member states.
- Brazil soybean corridor concentration:Interior-to-port grain movements are scaling intermodal investments, with rail terminal expansions at Santos and Paranaguá reducing road dependency for oilseed exports.
- Pharmaceutical-grade cold chain protocols:Fresh produce distributors are adopting temperature precision standards originally developed for biologics, reducing spoilage exposure in berry and stone fruit segments.
Market Restraints
- Refrigerant cost volatility:F-Gas Regulation phase-down schedules in Europe are constraining hydrofluorocarbon supply, inflating reefer unit maintenance costs for independent carriers.
- Driver pool contraction:US hours-of-service enforcement through electronic logging devices has tightened long-haul capacity for interstate agricultural movements.
- Port terminal concentration:Grain export infrastructure ownership clusters among three major terminal operators in Brazil's southern corridor, elevating handling fee leverage.
Strategic Opportunities
- India's integrated cold chain gaps:Post-harvest losses exceeding thirty percent in horticulture create white space for controlled-atmosphere storage networks linking Punjab and Maharashtra production belts to Mumbai and Chennai ports.
- Blockchain-IoT convergence:Real-time temperature logging combined with distributed ledger verification is enabling premium pricing for traceable organic produce in European retail channels.
- California CARB incentives:The state's clean truck funding programs subsidize zero-emission refrigerated vehicle deployment, lowering entry barriers for electric fleet conversion in the Central Valley dairy corridor.
Industry Challenges
- Refrigeration technician scarcity:Alternative-fuel cold chain assets require specialized maintenance protocols that existing diesel-focused workforces lack certification to perform.
- Multi-jurisdiction compliance layering:Carriers operating across US, Mexican, and Brazilian territories must reconcile divergent emissions testing regimes and driver qualification standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Logistics Market |
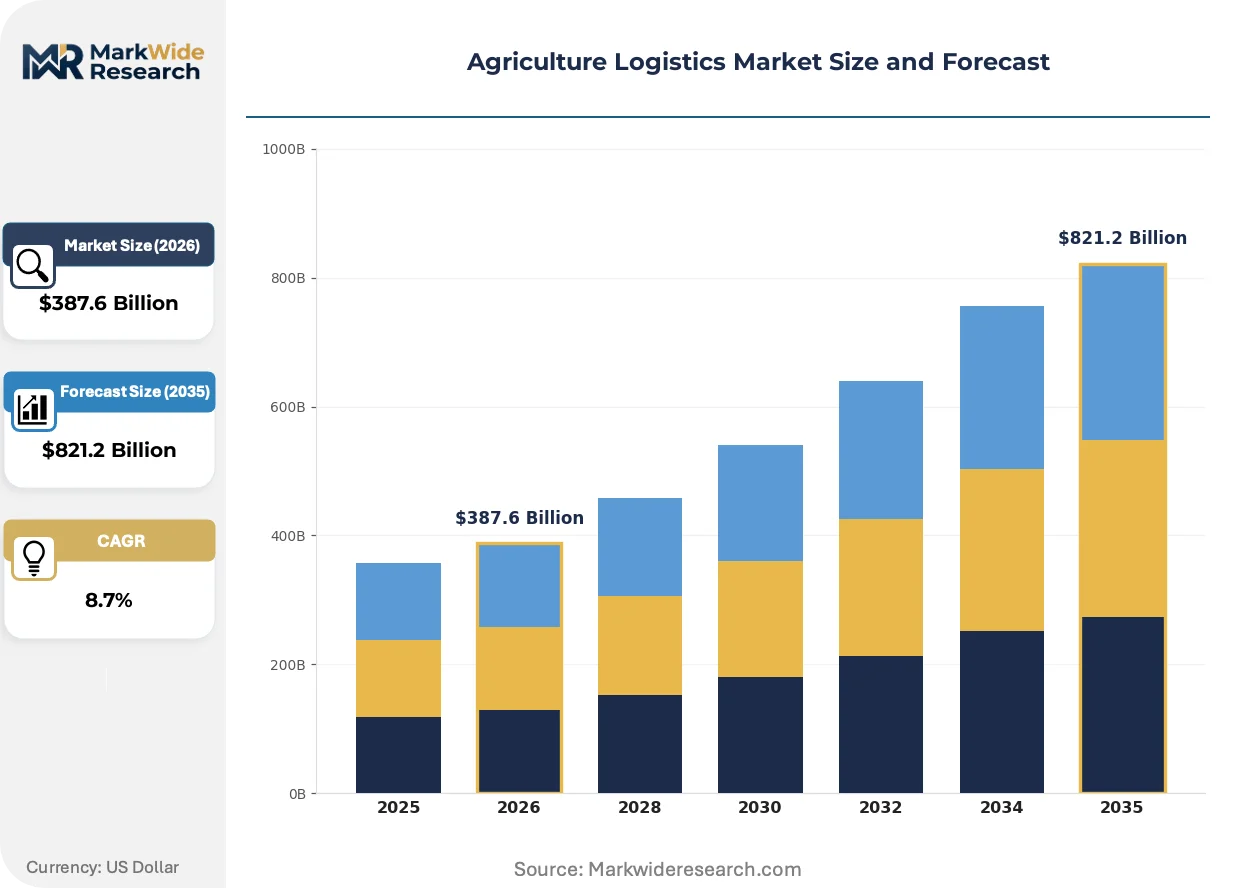
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Forwarding, Warehousing, Cold Chain, Transportation End Use Application: Crop Production, Livestock, Aquaculture, Organic Farming Delivery Mode: Road Transport, Rail Transport, Air Freight, Sea Freight Packaging Type: Bulk Packaging, Retail Packaging, Reusable Containers, Flexible Packaging |
| Companies Covered | CEVA Logistics, Bollore Logistics, Cargill, CHS Inc., FedEx, Archer Daniels Midland, Kuehne+Nagel, C.H. Robinson, DHL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Logistics Market Strategic Shifts
Digital infrastructure is modularizing physical assets across agricultural logistics, compressing the traditional separation between freight forwarding and controlled-atmosphere operations. Three interconnected developments are restructuring how perishables and bulk commodities move from origin to destination.
Containerized cold chain technology is modularizing temperature-controlled storage, allowing fresh produce distributors to lease plug-and-play refrigeration units rather than committing to fixed warehouse infrastructure. Latin American fruit exporters are adopting these units fastest, deploying them at origin packing houses to pre-cool berries before ocean transit. The technology is modularizing capital deployment, shifting cost structures from capex-heavy asset ownership toward operational expenditure models that scale with harvest cycles.
The EU F-Gas Regulation is accelerating refrigerant transition timelines, banning new hydrofluorocarbon-based systems in transport refrigeration from 2030. European fleet operators are responding with pilot deployments of CO2 transcritical systems and cryogenic nitrogen units for long-haul dairy movements. The regulation hits independent carriers hardest, as asset replacement cycles compress from fifteen years to eight under compliance pressure.
Consolidated buying among European supermarket chains is compressing supplier lists and demanding integrated farm-to-shelf logistics accountability. German and Dutch retail procurement teams now require single-contract temperature integrity from Latin American origin through final-mile delivery. This concentration is visible most acutely in Chilean cherry and blueberry exports, where forwarders must bundle ocean, port, and road cold chain liability under unified service agreements.
Agriculture Logistics Market Segmentation
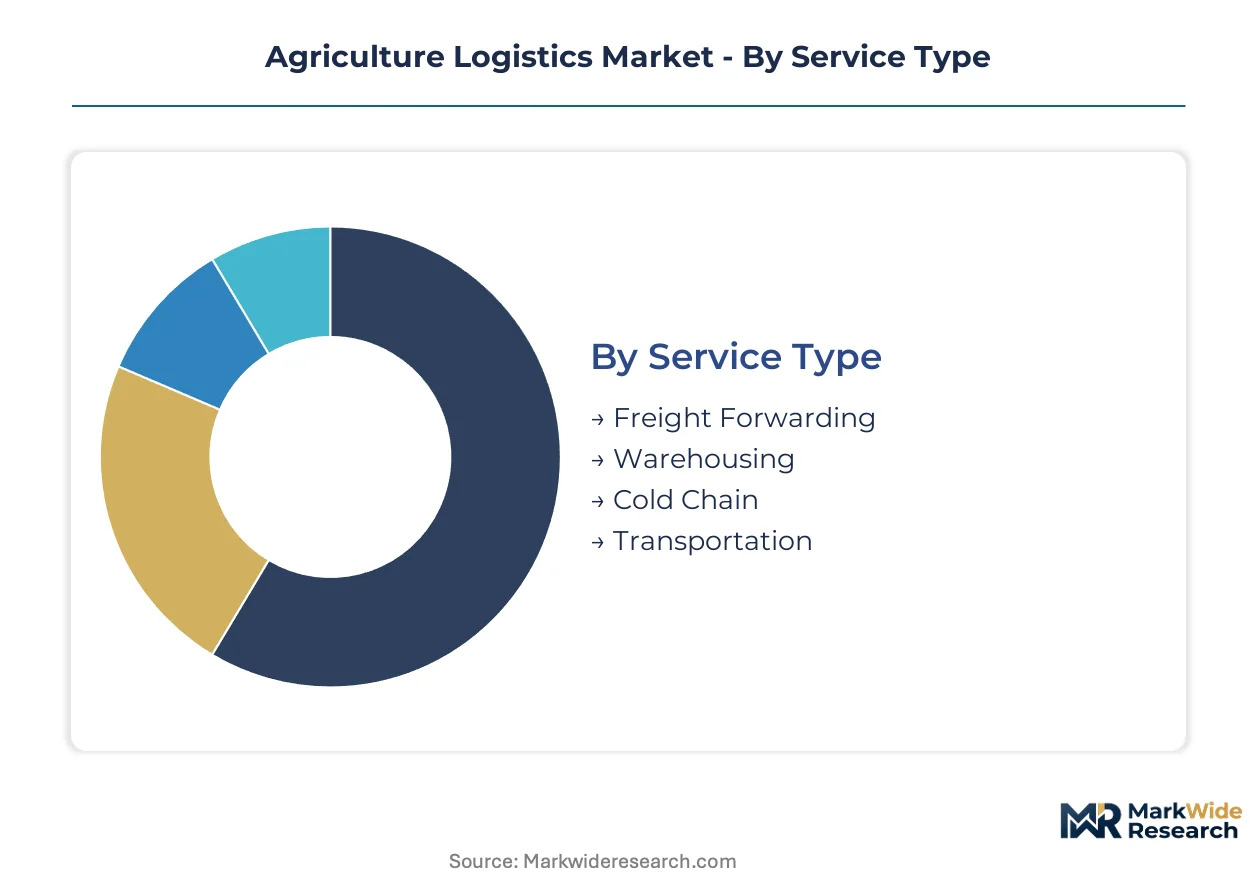
Agriculture logistics demands precise matching of service capabilities to commodity preservation requirements. Segmentation reveals where margin capture concentrates across temperature-sensitive and bulk-handling workflows.
Service Type:
Standardization dominates freight forwarding and warehousing, while cold chain operations require intensive customization to commodity-specific atmosphere protocols.
- Cold Chain:Temperature-controlled networks maintain pharmaceutical-grade precision for berries, stone fruits, and dairy products. EU F-Gas Regulation compliance costs are compressing independent carrier fleets and accelerating consolidation among temperature-controlled specialists serving Latin American fruit corridors.
- Freight Forwarding:Coordination of multimodal documentation, customs clearance, and carrier procurement for bulk grain and oilseed movements. Demand clusters in Brazil's soybean corridor where interior-to-port coordination determines export timing and price realization.
- Transportation:Direct asset operation across road, rail, and port drayage for agricultural commodities. US hours-of-service enforcement through electronic logging devices has tightened long-haul driver availability for interstate grain movements.
- Warehousing:Storage facilities with moisture management and contamination prevention systems for commodity grade preservation.
Most installed capacity flows through freight forwarding. Expansion is steepest in cold chain.
End Use Application:
Volume scale differentiates commodity crops from specialized segments where certification premiums justify logistics investment.
- Crop Production:Grain, oilseed, and specialty crop movements from farm gate to processing or export terminal. Brazil's Mato Grosso-to-Santos corridor exemplifies the rail-terminal investments reducing road dependency for soybean exports.
- Livestock:Feed input delivery, live animal transport, and chilled meat distribution requiring biosecurity protocols. EU Green Deal emissions mandates are forcing refrigerated fleet renewal for dairy movements across member states.
- Organic Farming:Certified organic produce requiring segregated handling and blockchain-traceable documentation for European retail premium capture.
- Aquaculture:Temperature-controlled distribution of fresh and frozen seafood products with rapid spoilage windows.
Most installed capacity flows through crop production. Expansion is steepest in organic farming.
Delivery Mode:
Cost efficiency versus speed flexibility determines modal selection across distance and commodity value gradients.
- Road Transport:Door-to-door flexibility for time-sensitive dairy, fresh vegetables, and last-mile distribution. California CARB clean truck incentives are subsidizing zero-emission refrigerated vehicle deployment in the Central Valley dairy corridor.
- Rail Transport:Unit train economics for high-volume soybean and corn movements from US Midwest and Brazilian interior to coastal export terminals. Paranaguá terminal expansions are absorbing growing oilseed volumes.
- Sea Freight:Containerized and bulk ocean movements for intercontinental grain and perishable exports. Reefer container adoption is climbing fastest among Chilean cherry exporters serving Chinese New Year demand windows.
- Air Freight:Premium velocity for high-value perishables with extreme spoilage sensitivity such as fresh-cut flowers and seed stock.
Most installed capacity flows through road transport. Expansion is steepest in rail transport.
Packaging Type:
Capital intensity separates reusable infrastructure from single-use alternatives across harvest cycle economics.
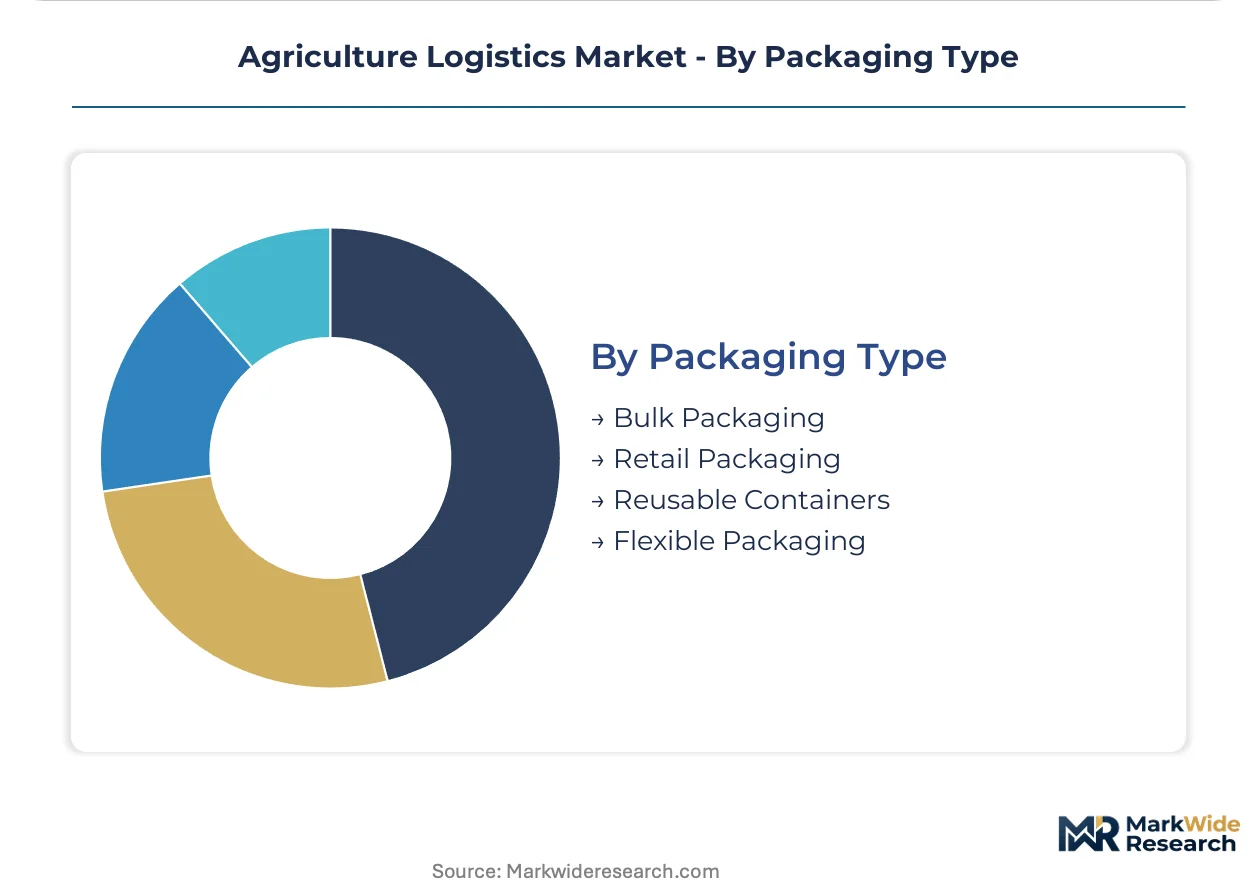
- Reusable Containers:Modular cold chain units that shift capital deployment from fixed warehouse infrastructure to operational expenditure models scaling with harvest cycles. Latin American berry exporters are deploying plug-and-play refrigeration at origin packing houses.
- Bulk Packaging:Grain hopper cars, flexitanks, and bulk containers for oilseed and cereal movements where commodity density maximizes load efficiency. Santos port grain terminals handle the densest concentration.
- Flexible Packaging:Modified atmosphere films and vacuum-sealed barriers for retail-ready produce extending shelf life.
- Retail Packaging:Consumer-unit formats requiring final-mile consolidation and store-ready presentation.
Most installed capacity flows through bulk packaging. Expansion is steepest in reusable containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern agriculture logistics traces its industrial lineage to the US Midwest grain elevators of the late nineteenth century, where standardized handling protocols first enabled mass commodity export. Today's network spans five critical production and export geographies where infrastructure investment and regulatory pressure are reshaping corridor economics.
United States
The US Department of Transportation enforces hours-of-service rules through electronic logging mandates that compress fleet utilization across interstate grain hauls. California CARB clean truck funding programs subsidize zero-emission refrigerated vehicle deployment in the Central Valley dairy corridor. Chicago and Minneapolis anchor grain rail terminal concentration where unit train economics sustain cost efficiency on high-volume corn and soybean routes.
Brazil
Interior-to-port grain movements are scaling intermodal investments as soybean export volumes strain existing road capacity. Brazil's CONAMA resolutions on transport emissions create compliance cost structures diverging from US and European standards. Santos and Paranaguá port terminals are absorbing expanded oilseed volumes as rail terminal investments reduce road dependency across the Mato Grosso production belt.
Germany
The EU Green Deal's Fit for 55 framework tightens emissions standards for refrigerated transport units, forcing premature diesel asset retirement. ECHA oversight of refrigerant phase-down schedules constrains hydrofluorocarbon supply and inflates reefer maintenance costs. Hamburg and Rotterdam corridor concentration demands integrated cold chain accountability from Eastern European produce suppliers.
India
Post-harvest losses exceeding thirty percent in horticulture create white space for controlled-atmosphere storage networks linking production belts to export ports. FSSAI food safety mandates and DGFT export facilitation schemes are accelerating cold chain infrastructure recognition. Mumbai and Chennai port zones are concentrating private investment in modular refrigeration units serving Punjab and Maharashtra farm clusters.
China
Dual carbon goals and MEE emissions enforcement are redirecting agricultural transport investment toward rail electrification and port automation. SAMR standardization of cold chain protocols is harmonizing previously fragmented regional requirements. Yangtze River Delta logistics zones are consolidating temperature-controlled warehousing capacity for high-value fruit and seafood distribution.
Agriculture Logistics Market Competitive Environment
Premium-margin players sit above commodity-margin players across temperature-control precision and traceability certification tiers. The vendor base stratifies between integrated conglomerates with captive origination assets, specialized cold chain operators with pharmaceutical-grade protocols, and digital-forward freight brokers optimizing multimodal coordination. Three archetypes dominate: grain-origination integrators controlling upstream supply, temperature-controlled specialists serving perishable corridors, and platform-based intermediaries aggregating fragmented carrier capacity. Consolidation pressure is accelerating through equipment replacement cycles and regulatory compliance cost layering.
Within the integrated conglomerate tier, Cargill and Archer Daniels Midland represent upstream-anchored archetypes with grain origination and port terminal control. CEVA Logistics and Kuehne+Nagel occupy positions as temperature-controlled network specialists bundling ocean, port, and final-mile cold chain liability. These players exemplify how service integration and asset control separate premium-capture competitors from commodity-margin freight forwarders.
| Leading Market Players |
|---|
| CEVA Logistics |
| Bollore Logistics |
| Cargill |
| CHS Inc. |
| FedEx |
| Archer Daniels Midland |
| Kuehne+Nagel |
| C.H. Robinson |
| DHL |
| Others |
Value Chain & Pricing Dynamics
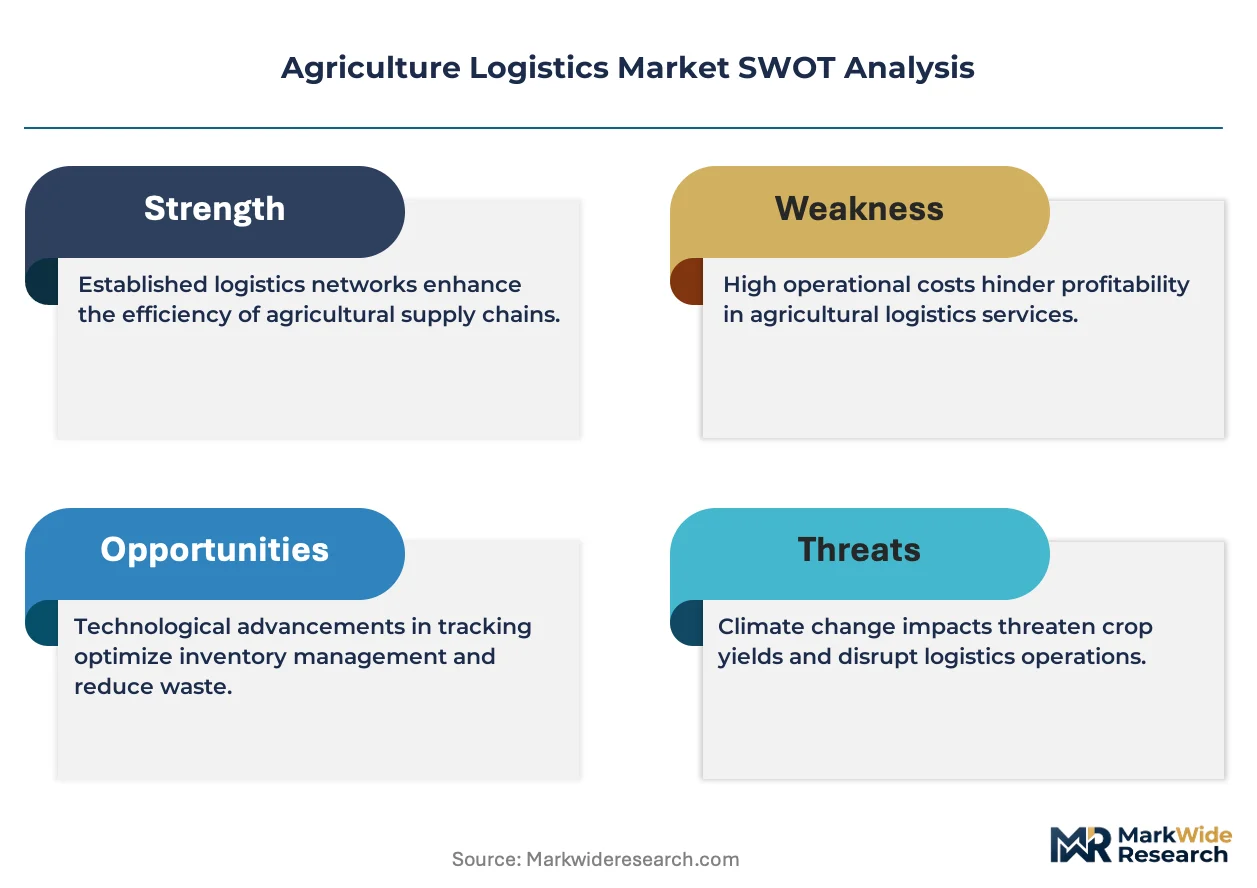
Consolidated procurement by German and Dutch supermarket chains is compressing supplier lists and demanding integrated farm-to-shelf logistics accountability, forcing carriers to bundle ocean, port, and road cold chain liability under unified service agreements that elevate pricing for compliant operators while squeezing non-integrated independents.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates agriculture logistics, with pharmaceutical-grade temperature precision commanding the highest tier for berry and stone fruit movements. Price differentiation rests on certification grade and geographic delivery cost, with EU F-Gas Regulation compliance adding a certification premium for alternative-fuel cold chain assets. Cost compression in the standard tier is intensifying because independent carriers face compressed asset replacement cycles. Smallholder-dependent corridors in India exhibit the highest price sensitivity, while integrated Latin American fruit exporters serving European retail chains show the least.
Supply Chain Analysis
Dual-sourcing requirements from European retail procurement teams are mandating multi-carrier qualification for Latin American fruit corridors, spreading contract volumes across integrated networks. Geographic supply concentration centers on Brazil for soybean and oilseed exports, the United States for Midwest grain movements, and India for horticulture post-harvest infrastructure. Raw material dependencies draw from specialized refrigerants, refrigerated container units, and rail terminal capacity. Single-source vulnerability runs through Brazil's Santos and Paranaguá port terminal concentration. Distribution runs through multimodal corridors anchored by coastal export gateways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agriculture logistics functions as a geographic-arbitrage play where EU Green Deal compliance costs in Europe diverge sharply from Brazil's CONAMA emission standards, creating cost-advantaged positioning for South American operators serving European demand.
For Market Incumbents: Deploy backward integration into grain origination and port terminal control to anchor upstream supply security against emerging digital freight brokers. CEVA Logistics and Cargill exemplify how captive infrastructure defends margin position when electronic logging mandates tighten driver availability. Capacity addition in Brazil's Mato Grosso-to-Santos corridor captures rail-terminal expansion benefits. For New Entrants and Emerging Players: Launch via modular cold chain bundling targeting India's post-harvest loss gaps exceeding thirty percent in Punjab and Maharashtra horticulture belts. Blockchain-IoT convergence for organic produce traceability offers the most penetrable wedge into European premium retail channels. Direct partnerships with farmer cooperatives bypass established grain-origination integrators. For Investors and Strategic Acquirers: Asymmetric upside sits with temperature-controlled specialists holding pharmaceutical-grade certification and Latin American corridor density. Long-term viability hinges on regulatory compliance cost absorption capacity across divergent EU, US, and Brazilian emission frameworks. Watch for F-Gas Regulation refrigerant phase-down acceleration as inflection indicator for carrier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative-Fuel Fleet Conversion | EU Green Deal Fit for 55 compliance forces premature diesel retirement and hydrogen pilot deployment. |
| Rail Terminal Expansion | Santos and Paranaguá capacity additions reduce road dependency for Brazil soybean corridor volumes. |
| Blockchain-IoT Integration | Distributed ledger verification enables premium pricing for traceable organic produce in German retail. |
| Farmer Cooperative Partnership | CHS Inc. ownership structures tighten input-to-export capture across US Midwest grain movements. |
| Modular Cold Chain Deployment | Plug-and-play refrigeration units shift capital from fixed warehouses to harvest-scaled operational expenditure. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cold chain operations directors, grain elevator managers, retail procurement leads, and refrigerated fleet operators alongside secondary validation. Customs data, USDA grain movement reports, EU transport emission filings, and port authority throughput statistics anchored supply-side modeling. Bottom-up carrier capacity assessments and top-down commodity flow analysis triangulated market sizing.
Comparable historical periods anchored the projection horizon to established trend baselines in refrigerated transport adoption and intermodal grain corridor development. Segmentation dimensions modeled include service type, end-use application, delivery mode, and packaging format across temperature-controlled and bulk-handling workflows. CAGRs derived from logistic curve fitting to technology diffusion patterns in alternative-fuel fleet deployment and modular cold chain adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under refrigerant supply disruption or accelerated EU F-Gas phase-down schedules. Forecasts reflect documented assumptions about regulatory enforcement timelines and commodity price volatility corridors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market
Farm Equipment and Irrigations
Irrigation Liner Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market
Farm Equipment and Irrigations
Australia Irrigation Automation Market
Farm Equipment and Irrigations
Farm Equipment Rental Market
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Rain Barrels Market
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
Brazil Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Lawn Edge Trimmer Market