
 Hose Reel Irrigation Machine Market | 2026-2036
Hose Reel Irrigation Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Hose Reel Irrigation Machine Market Insights
Modular bundling of hose reel units with GPS-guided control systems and variable-rate nozzles is recalibrating how farm equipment dealers structure purchase options. Lindsay Corporation leverages its vertical integration into tower manufacturing to sustain margin control across North American distribution channels. Valmont Industries anchors its competitive stance through advanced remote-monitoring platforms that integrate soil-moisture telemetry. Reinke Manufacturing differentiates via specialized corrosion-resistant coatings engineered for high-salinity water sources.
A hose reel irrigation machine consists of a rotating drum mounted on a mobile chassis, wound with high-density polyethylene or PVC hose typically spanning 100 to 500 meters, driven by a turbine, piston, or electric motor that retracts the hose at calibrated speeds to distribute water through an attached sprinkler cart. The apparatus serves agricultural and commercial operators requiring portable, self-propelled water application across irregular field geometries without fixed infrastructure. Automatic systems lead product-type configurations where labor scarcity elevates total cost of ownership calculations for manual alternatives. Sprinkler technology dominates the technology dimension due to its compatibility with reel-mounted traversal mechanisms, while drip integration remains nascent. Agricultural producers represent the deepest end-user pool, though sports facilities command premium pricing for precision-turf applications.
The EPA enforces water-efficiency standards under the WaterSense program that shape equipment specifications for federal procurement eligibility. USDA conservation programs subsidize precision irrigation adoption, while ISO 15886-3 governs sprinkler performance uniformity testing that manufacturers must satisfy for CE marking access to European markets. Stakeholders must weigh capital allocation between automation upgrades and water-rights compliance investments as regulatory thresholds tighten.
Market Dynamics
Water-stressed agricultural zones are forcing capital rotation from flood irrigation toward precision reel systems, with EU Green Deal compliance deadlines compressing replacement cycles for vineyard and orchard operators across Mediterranean Europe.
Growth Catalysts
- EU Green Deal water efficiency mandates:Replacement deadlines for flood systems are accelerating mechanized irrigation adoption in Spain, Italy, and France.
- High-density polyethylene hose durability:Extended service life in abrasive field conditions is reducing total cost of ownership calculations for large-scale producers.
- Vineyard and orchard concentration:Recurring summer drought cycles in Mediterranean growing regions are elevating reel irrigation to essential infrastructure status.
Market Restraints
- Steel and polymer input cost volatility:Drum chassis and hose materials face commodity price swings that compress manufacturer margins.
- CE marking compliance friction:ISO 15886-3 sprinkler uniformity testing creates certification bottlenecks for European market entry.
- Fixed pivot system substitution:Center-pivot alternatives capture regular-field geometries at lower per-hectare capital intensity.
Strategic Opportunities
- GPS-guided control convergence:Integration with variable-rate nozzle systems opens precision agriculture service revenue streams.
- Sports turf premium applications:Stadium and golf course operators command pricing multiples above agricultural benchmarks for precision coverage.
- USDA conservation program subsidies:Federal cost-share mechanisms reduce capital barriers for precision irrigation adoption among mid-scale operators.
Industry Challenges
- Telemetry integration complexity:Soil-moisture sensor calibration with reel retraction speeds demands specialized agronomic-technical hybrid staffing.
- Corrosion-resistant coating certification:High-salinity water compatibility testing extends product development timelines for coastal and brackish-source deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hose Reel Irrigation Machine Market |
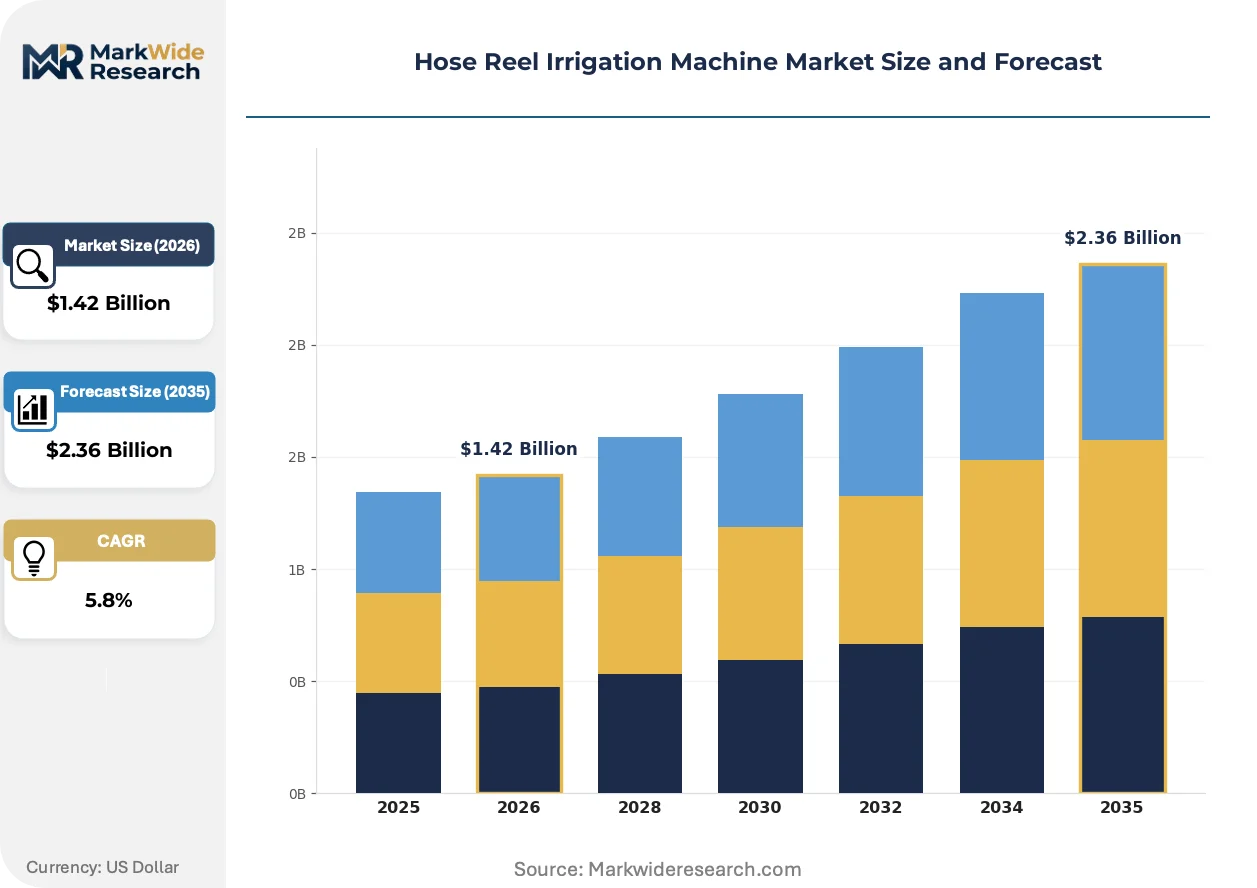
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Semi-Automatic, Portable End User: Agricultural Producers, Landscaping Companies, Sports Facilities, Municipalities Technology: Drip Irrigation, Sprinkler Systems, Surface Irrigation, Subsurface Irrigation Application: Crops, Lawns, Golf Courses, Greenhouses |
| Companies Covered | Lindsay Corporation, Valmont Industries, Reinke Manufacturing, ABI Irrigation, Netafim, T-L Irrigation, OCMIS, Zeno Farm Machinery, Rain Bird, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hose Reel Irrigation Machine Market Trends and Innovations
Reel irrigation architecture is fragmenting into configurable subsystems, with control electronics and nozzle packages decoupling from chassis hardware to enable upgrade pathways and service-based revenue models.
Variable-rate nozzle technology is modularizing around GPS-enabled sprinkler carts that adjust flow patterns in real time. Large-scale vineyard operators in Spain and Italy are adopting these configurations fastest. The technology is modularizing dealer inventory structures from bundled equipment sales toward component upgrade programs.
EPA WaterSense efficiency standards are reshaping federal procurement eligibility criteria for irrigation equipment. Manufacturers must satisfy flow-rate uniformity thresholds to access USDA-subsidized conservation program channels. Agricultural producers in water-stressed western US states face compressed equipment replacement timelines to maintain subsidy access.
Equipment-as-a-service contracting is displacing outright purchase for mid-scale orchard operators facing capital constraints. Farm equipment dealers in France and Italy are piloting subscription models bundling maintenance with seasonal deployment. Turf management facilities represent the most advanced adoption geography for outcome-based irrigation service agreements.
Hose Reel Irrigation Machine Market Segmentation
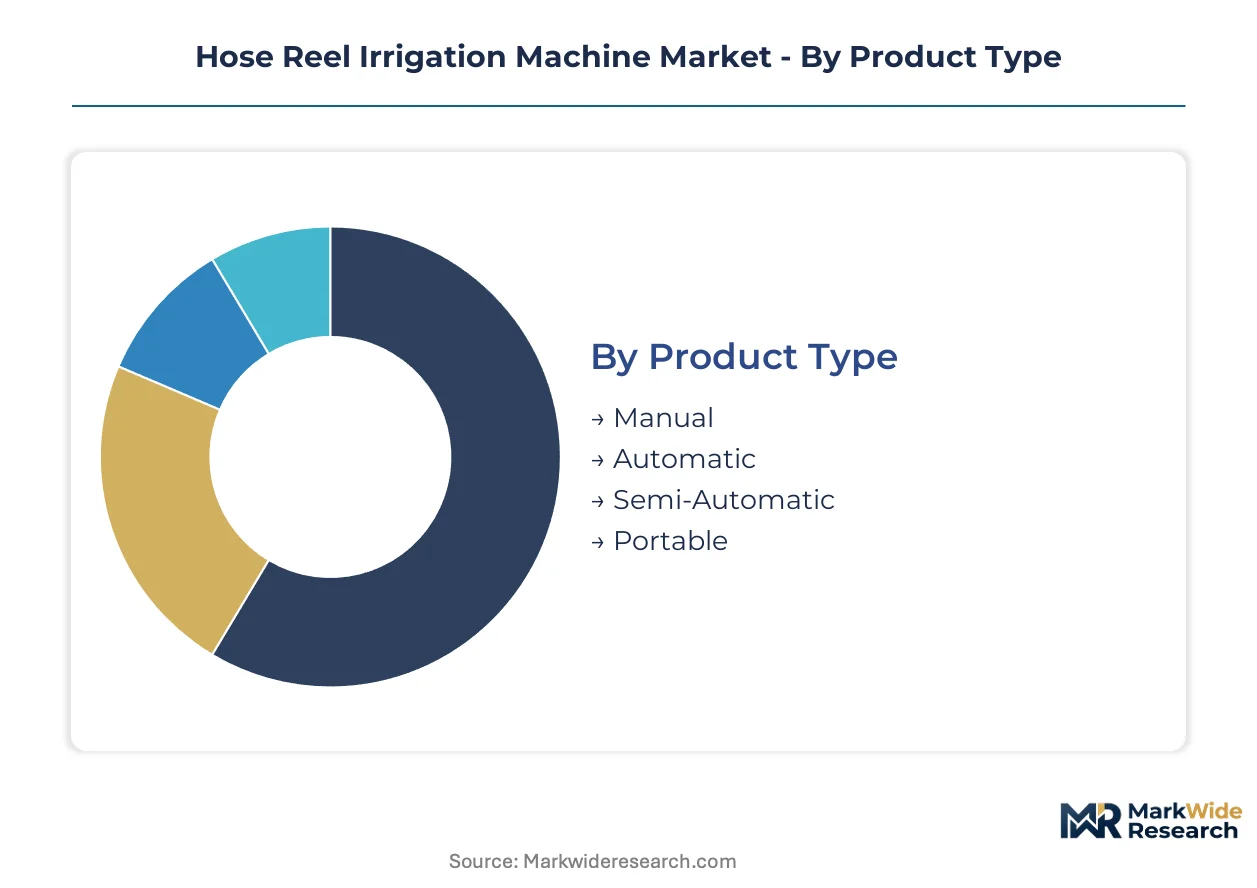
Segmentation in hose reel irrigation machines reveals how equipment specifications align with water source constraints, field geometries, and labor availability across distinct operational contexts. Purchase patterns diverge sharply between capital-rich vineyard operators seeking automation and municipal buyers prioritizing acquisition cost over precision features.
Product Type:
Supply concentration tilts toward automatic configurations as turbine-driven retraction mechanisms displace manual alternatives in distributor inventories across water-stressed agricultural zones.
- Automatic:Turbine or electric motor drives calibrated hose retraction at variable speeds matched to soil infiltration rates. Large-scale vineyard operators in Spain and Italy specify these systems to satisfy EU Green Deal water efficiency mandates while reducing labor dependency during peak irrigation windows.
- Manual:Hand-cranked drum operation suits smallholder plots and emergency backup deployment where capital constraints override labor cost considerations. Demand clusters in Eastern European orchard operations and developing agricultural regions with surplus seasonal labor availability.
- Semi-Automatic:Hybrid configurations blend motorized retraction with operator-controlled speed adjustment, appealing to mid-scale producers transitioning from flood irrigation.
- Portable:Lightweight chassis and quick-connect couplings enable multi-field deployment without permanent infrastructure, serving rental equipment fleets and specialty crop rotation systems.
Today's leader: Automatic. Tomorrow's challenger: Portable.
End User:
Cost tier stratification separates agricultural volume purchasers from premium-seeking turf managers, with pricing multiples expanding across the customer spectrum.
- Agricultural Producers:Vineyard and orchard operators in Mediterranean Europe constitute the deepest demand pool, deploying reel systems across irregular field geometries unsuited to center-pivot alternatives. USDA conservation program subsidies compress capital barriers for US-based row-crop adopters.
- Sports Facilities:Stadium and golf course operators command premium pricing for precision-turf applications requiring uniform coverage across undulating surfaces. Telemetry integration with soil-moisture sensors distinguishes procurement specifications in this segment.
- Landscaping Companies:Commercial grounds maintenance contractors prioritize equipment mobility and rapid deployment for municipal and corporate contracts.
- Municipalities:Public parks and roadway verge irrigation programs emphasize acquisition cost minimization and standardized maintenance protocols over precision features.
Volume concentrates with Agricultural Producers. Margin expansion sits with Sports Facilities.
Technology:
Application compatibility determines technology adoption, with reel-mounted traversal mechanisms favoring specific water distribution architectures over others.
- Sprinkler Systems:Impact and gear-driven heads mounted on traveling carts distribute water through pressurized spray patterns compatible with hose retraction dynamics. This configuration dominates vineyard and orchard applications across France, Spain, and Italy due to adaptability to varying row spacing.
- Drip Irrigation:Emitters and micro-tubes deliver targeted root-zone application with minimal evaporative loss, though integration with mobile reel systems remains technically constrained and commercially nascent.
- Surface Irrigation:Gravity-fed furrow and border strip methods persist in rice and forage production where topography permits, though reel system compatibility is limited.
- Subsurface Irrigation:Buried drip lines and porous tubing reduce surface wetting and disease pressure, requiring specialized reel configurations for hose protection during deployment and retrieval.
Commercial dominance belongs to Sprinkler Systems. Technical innovation targets Drip Irrigation integration.
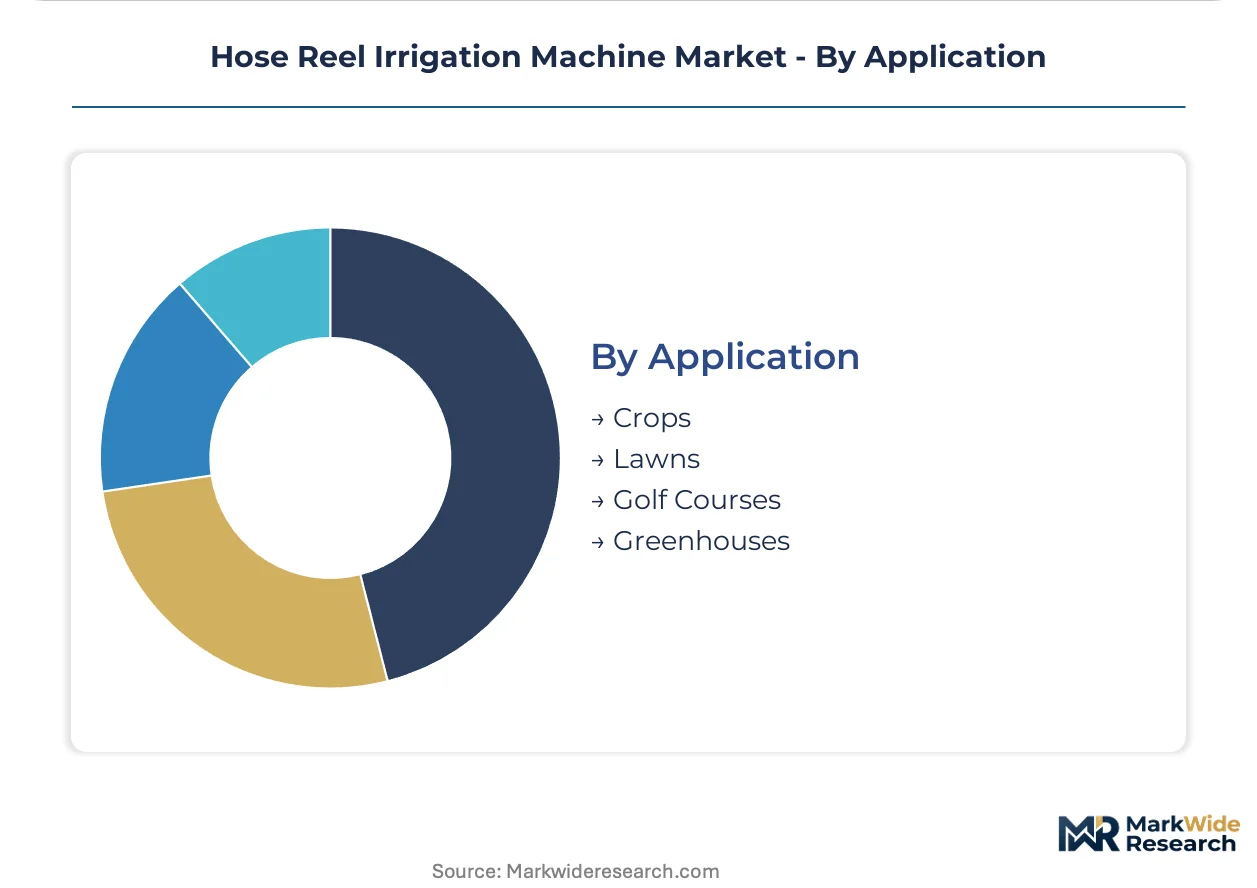
Application:
Customer maturity separates established agricultural deployment from emerging precision-turf segments, with greenhouse applications representing a distinct technical specification cluster.
- Crops:Row and specialty crop irrigation across cereals, vegetables, and permanent plantings constitutes the foundational application segment. Field geometries and water source variability drive specification diversity in this category.
- Golf Courses:Precision coverage requirements for fairway and green maintenance elevate equipment specifications toward GPS-guided control and variable-rate nozzle integration.
- Lawns:Commercial and residential turf irrigation emphasizes coverage uniformity and operational simplicity over precision agriculture features.
- Greenhouses:Controlled-environment agriculture demands compact reel configurations with chemical-resistant hose materials and low-pressure distribution compatibility.
Established scale resides in Crops. Steepest expansion trajectory emerges in Golf Courses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reel irrigation technology first achieved commercial scale in Italian vineyards during the 1970s, spreading northward through French orchard country and westward into Iberian growing regions. Today's deployment patterns still trace these historical diffusion pathways.
United States
USDA conservation programs subsidize precision irrigation adoption across California's Central Valley and the Pacific Northwest, compressing capital barriers for mid-scale operators. The EPA's WaterSense program enforces flow-rate uniformity thresholds that shape federal procurement eligibility. Equipment dealers in Fresno County and Yakima Valley report fastest inventory turnover for GPS-guided automatic configurations.
Spain
Vineyard operators in La Mancha and Catalonia face recurring summer drought cycles that elevate reel systems to essential infrastructure status. EU Green Deal water efficiency mandates accelerate replacement of flood irrigation with mechanized alternatives. Manufacturing clusters around Zaragoza specialize in corrosion-resistant chassis for high-salinity water sources.
Italy
Orchard and vineyard concentration in Emilia-Romagna and Apulia drives demand for portable systems serving irregular field geometries. CE marking compliance under ISO 15886-3 sprinkler uniformity testing creates certification bottlenecks for imported equipment. Bologna-based equipment distributors pioneered modular bundling with variable-rate nozzle packages.
France
Bordeaux wine producers and Provence orchard operators deploy automatic systems to satisfy tightening water abstraction limits. The country's national agricultural regulator enforces efficiency standards that privilege precision application technologies. Dealer networks in Montpellier test subscription-based equipment-as-a-service models for capital-constrained growers.
Australia
Murray-Darling Basin water trading schemes incentivize efficiency investments among broadacre cereal producers. The country's national agricultural regulator monitors extraction compliance through telemetry integration requirements. Manufacturing activity clusters in South Australia around specialized high-density polyethylene hose production for abrasive field conditions.
Hose Reel Irrigation Machine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across automation sophistication and telemetry integration capabilities. The vendor base organizes into three tiers: integrated tower manufacturers controlling upstream chassis production, precision agriculture specialists bundling GPS-guided control systems, and regional fabricators competing on acquisition cost. Strategic moves concentrate on backward integration into hose manufacturing and service-based revenue model development.
Within the integrated manufacturing tier, Lindsay Corporation and Valmont Industries occupy positions exemplifying vertical control over tower and chassis production. Reinke Manufacturing represents the specialization archetype, with company naming suggesting corrosion-resistant engineering focus. These three entities anchor the competitive structure while mid-scale regional fabricators compete on price-accessible configurations for developing agricultural markets.
| Leading Market Players |
|---|
| Lindsay Corporation |
| Valmont Industries |
| Reinke Manufacturing |
| ABI Irrigation |
| Netafim |
| T-L Irrigation |
| OCMIS |
| Zeno Farm Machinery |
| Rain Bird |
| Others |
Pricing and Supply Chain Analysis
High-density polyethylene resin costs cascade through three pricing tiers as drum chassis manufacturers in Italy and Spain pass commodity volatility to vineyard operators and municipal buyers with divergent bargaining positions. Steel drum fabrication and corrosion-resistant coating inputs concentrate margin pressure on mid-scale fabricators competing against vertically integrated tower producers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates GPS-guided automatic systems from semi-automatic configurations and manual drum units. Certification grade under ISO 15886-3 sprinkler uniformity testing and after-sales telemetry bundling drive price differentiation between EU-market-compliant and developing-market equipment. Cost compression in economy tiers intensifies because steel and polymer input volatility compresses regional fabricator margins. Municipal buyers exhibit highest price sensitivity, while sports facilities accepting precision-turf specifications show least elasticity.
Supply Chain Analysis
Direct-to-farm-equipment-dealer channels handle agricultural volume demand across Mediterranean Europe, while specialized turf distributors serve sports facility buyers in France and Italy. Manufacturing concentrates in Italy, Spain, and Australia, with Zaragoza-area producers specializing in corrosion-resistant chassis and South Australian facilities feeding high-density polyethylene hose production. Raw material dependencies rest on steel coil imports, polymer resin supply, and specialized coating chemicals. Single-source vulnerability around turbine drive components from German suppliers creates procurement risk. Distribution runs through dealer networks with seasonal inventory build ahead of Mediterranean irrigation windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal compliance deadlines in Mediterranean Europe run ahead of USDA conservation program windows in the western United States, creating a twelve-to-eighteen-month arbitrage window for equipment redeployment from subsidy-saturated Spanish markets to emerging Californian demand.
For Market Incumbents: Extend telemetry integration capabilities to defend against precision-agriculture specialists bundling GPS-guided control systems. Backward integration into high-density polyethylene hose manufacturing secures margin control against polymer price volatility. Reinke Manufacturing's corrosion-resistant coating specialization demonstrates how technical differentiation resists commodity-tier competition from Asian fabricators. For New Entrants and Emerging Players: E-commerce direct-to-vineyard platforms bypass established dealer networks in Italian and French regions with fragmented equipment distribution. Portable system configurations for mid-scale orchard operators transitioning from flood irrigation represent the most penetrable white-space segment. Subscription-based equipment-as-a-service contracting, piloted by Montpellier dealers, offers a service-revenue go-to-market angle distinct from capital-sale competition. For Investors and Strategic Acquirers: Consolidation pressure builds where telemetry integration complexity demands agronomic-technical hybrid staffing that mid-scale regional fabricators cannot sustain independently. Long-term viability favors acquirers of specialized coating technology and GPS control module developers over commodity chassis producers. The signal to watch is USDA conservation program subsidy expansion timelines, which would accelerate capital rotation and equipment replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hose Manufacturing | Captive polyethylene supply insulates Lindsay Corporation against polymer commodity cycles. |
| GPS-Guided Control Platform Development | Variable-rate nozzle convergence opens precision-agriculture service revenue for Valmont Industries. |
| Corrosion-Resistant Coating Certification | High-salinity compatibility testing extends Reinke Manufacturing's coastal market access. |
| Equipment-as-a-Service Pilot Programs | Subscription bundling reduces capital barriers for French and Italian mid-scale vineyard operators. |
| CE Marking Compliance Investment | ISO 15886-3 sprinkler uniformity testing clears certification bottlenecks for European market entry. |
Research Methodology
Bottom-up agricultural producer modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with farm equipment dealers, vineyard operations managers, municipal irrigation procurement officers, and precision-agriculture technology integrators combined with secondary validation against EU agricultural machinery trade data, USDA conservation program disbursement records, EPA WaterSense certification databases, and ISO standard implementation filings. Triangulation between demand-side adoption patterns and supply-side production clustering ensures cross-verified volume and value estimates.
Input-output matrices map hose reel unit shipments against irrigation coverage expansion, water-stress indices, and regulatory compliance deadlines across the projection horizon. Segmentation dimensions include product type configuration, end-user category, sprinkler technology tier, and regional regulatory cluster. CAGRs derive from fitted adoption curves calibrated to EU Green Deal implementation phases and USDA subsidy program renewal cycles. Forecast inputs incorporate drought frequency projections for Mediterranean growing regions and water-rights trading scheme developments in Australia's Murray-Darling Basin.
The model assumes a particular technology adoption path; alternative pathways for drip-irrigation integration with mobile reel systems would alter the outlook. Forecasts reflect base-case assumptions regarding polymer price stabilization and CE marking compliance timeline continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Tractor Rental Market
Farm Equipment and Irrigations
Watering Cans Market
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
North America Agricultural Tires Market
Farm Equipment and Irrigations
Irrigation Controllers Market
Farm Equipment and Irrigations
Grass Trimmer Market
Farm Equipment and Irrigations
Global Irrigation Automation Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Australia Irrigation Automation Market
Farm Equipment and Irrigations
Weed Trimmer Market
Farm Equipment and Irrigations
Zero Turn Mowers Market
Farm Equipment and Irrigations
Golf Irrigation Market
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market