
 Electric Tractors Market | 2026-2036
Electric Tractors Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Tractors Market Analytics
ISO 11783 certification for agricultural electronics and precision farming interfaces is collapsing the competitive field to manufacturers with embedded software competency. John Deere leverages its proprietary operations center platform to lock in fleet management contracts across North American row-crop operations. Monarch Tractor competes through integrated autonomy stacks that eliminate operator labor in specialty crop vineyards. Kubota Corporation anchors its position in compact electric tractors through dense dealer networks across Japan and Southeast Asian rice-growing prefectures.
An electric tractor is a self-propelled agricultural vehicle powered by rechargeable battery packs or fuel cell systems, typically delivering 40–300 horsepower through electric drivetrains with instant torque delivery and regenerative braking capability, designed primarily for tillage, planting, harvesting, and material handling without tailpipe emissions. Battery Electric technology leads unit shipments due to mature lithium-ion supply chains and falling pack costs per kilowatt-hour, while Autonomous Electric commands premium pricing through labor substitution in high-value perennial crops. Utility Tractors occupy the broadest addressable base across mid-sized farms, whereas Specialty Tractors concentrate margin pools in narrow-profile vineyard and orchard configurations where diesel alternatives face operational constraints.
EPA Tier 4 Final emissions standards and California Air Resources Board zero-emission equipment mandates are forcing diesel tractor obsolescence timelines in regulated air basins, while EU Green Deal farm-to-fork sustainability targets and F-Gas Regulation phase-downs reshape European procurement specifications toward electrified fleets. India's PLI scheme for automotive and auto component manufacturing subsidizes domestic battery assembly capacity, lowering import dependency for electric tractor powertrains. Stakeholders must monitor battery raw material sourcing agreements and charging infrastructure deployment rates in agricultural corridors as the primary determinants of fleet electrification velocity.
Market Dynamics
Diesel cost volatility and EPA emissions standards are compressing operational budgets for large-scale crop producers, accelerating procurement timelines for battery-electric units in regulated air basins.
Growth Catalysts
- EPA Tier 4 Final standards:These emissions regulations are forcing diesel tractor obsolescence timelines in US regulated air basins, compelling fleet turnover toward zero-emission machinery.
- California Air Resources Board mandates:Zero-emission equipment requirements in California's Central Valley are concentrating demand for battery-electric tractors where air basin regulations are most stringent.
- Falling lithium-ion pack costs:Mature battery supply chains are reducing powertrain costs per kilowatt-hour, expanding the addressable base for mid-sized farm electrification.
Market Restraints
- Battery raw material concentration:Cobalt and lithium processing capacity concentrates in limited geographies, exposing supply chains to geopolitical disruption and price volatility.
- Charging infrastructure gaps:Rural agricultural corridors lack high-capacity grid connections necessary for fleet-scale electric tractor deployment, delaying adoption in remote growing regions.
- Energy density limitations:Current lithium-ion chemistry restricts continuous field operation duration compared to diesel refueling cycles, constraining applicability in large-acreage row-crop applications.
Strategic Opportunities
- India PLI scheme subsidies:Production-linked incentives for automotive and auto component manufacturing are building domestic battery assembly capacity, lowering import dependency for electric tractor powertrains in South Asian markets.
- Autonomy-tractor convergence:Integrated autonomy stacks eliminating operator labor are opening premium pricing pools in high-value perennial crops such as vineyards and orchards.
- EU Green Deal procurement:Farm-to-fork sustainability targets and F-Gas Regulation phase-downs are reshaping European procurement specifications toward electrified fleets.
Industry Challenges
- ISO 11783 certification complexity:Agricultural electronics and precision farming interface standards require embedded software competency, collapsing the competitive field to manufacturers with substantial R&D resources.
- Dealer network reconfiguration:Traditional service infrastructure designed around internal combustion powertrains requires capital-intensive retooling for high-voltage systems and battery diagnostics.
- Integration with legacy fleet management:Proprietary operations center platforms create switching costs that complicate multi-brand fleet electrification strategies for large agricultural enterprises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Tractors Market |
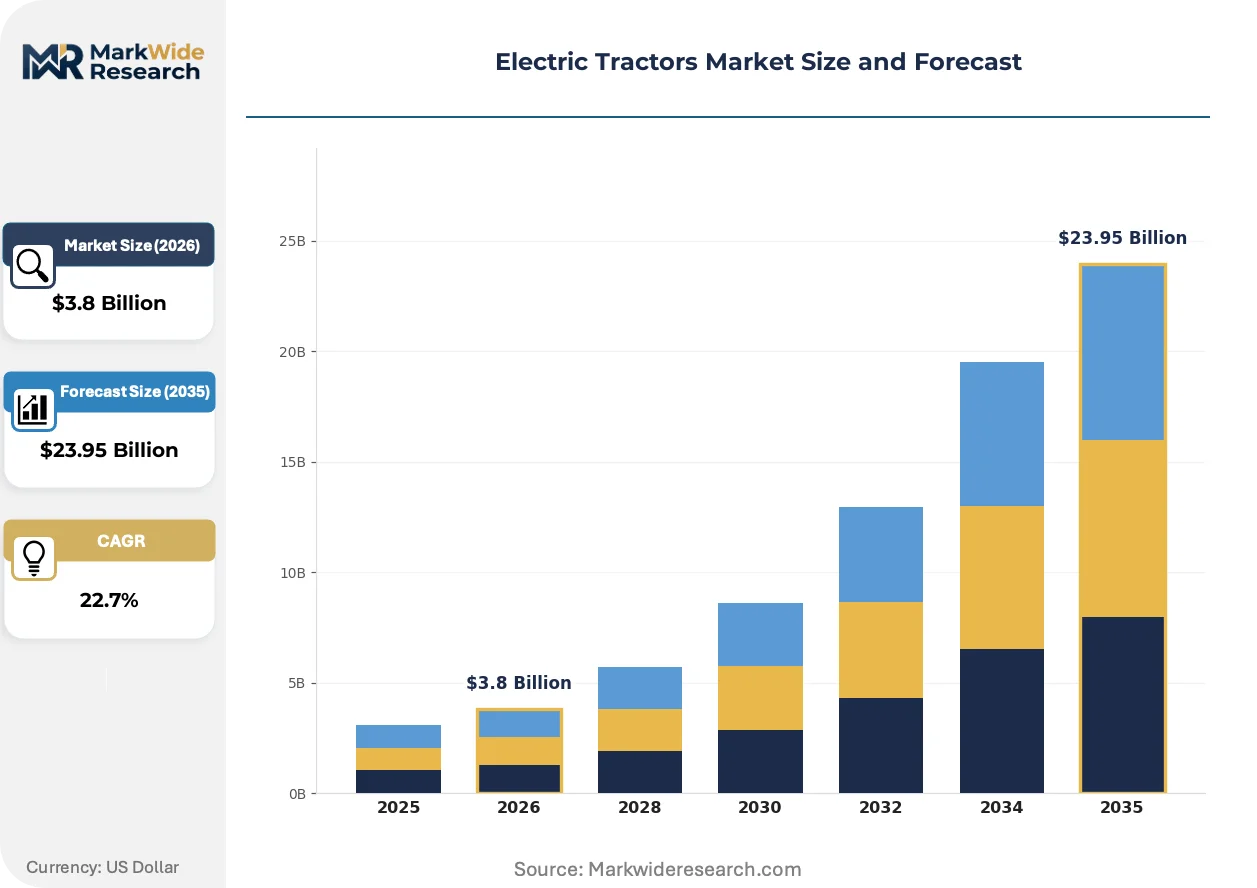
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Utility Tractors, Agricultural Tractors, Specialty Tractors Application: Crop Production, Livestock Farming, Landscaping, Soil Cultivation End User: Farmers, Agricultural Cooperatives, Landscaping Companies, Government Agencies Technology: Battery Electric, Fuel Cell Electric, Hybrid Electric, Autonomous Electric |
| Companies Covered | John Deere, CNH Industrial, Kubota Corporation, AGCO Corporation, Monarch Tractor, Solectrac, Fendt, Mahindra, Yanmar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Tractors Market Evolving Landscape
Electrification is fragmenting established competitive positions in agricultural machinery, with software competency and battery supply chain control replacing horsepower ratings as the primary basis of differentiation.
Solid-state battery chemistry is fragmenting the powertrain landscape by promising higher energy density and faster charging cycles than conventional lithium-ion architectures. Specialty crop operators in narrow-profile vineyard configurations are piloting these systems to eliminate diesel alternatives facing operational constraints in confined row spacing. The technology is fragmenting R&D investment patterns, diverting capital from mechanical transmission improvements toward electrochemical innovation and thermal management systems.
California Air Resources Board zero-emission mandates are compressing diesel equipment residual values in regulated air basins, forcing accelerated depreciation schedules for fleet managers. Large-scale crop production operations in the Central Valley are responding by front-loading procurement of battery-electric units ahead of compliance deadlines. This regulatory pressure is concentrating manufacturer attention on California certification pathways, creating a geographic lead market that shapes product development priorities for North American deployment.
Service contract unbundling is disrupting traditional dealer revenue models that bundled equipment sales with maintenance packages. Fleet management platforms are displacing transactional sales relationships with subscription-based uptime guarantees and predictive maintenance analytics. This shift is most visible in North American row-crop operations where John Deere's proprietary operations center has locked in multi-year fleet management contracts through integrated telematics and remote diagnostics capabilities.
Electric Tractors Market Segmentation
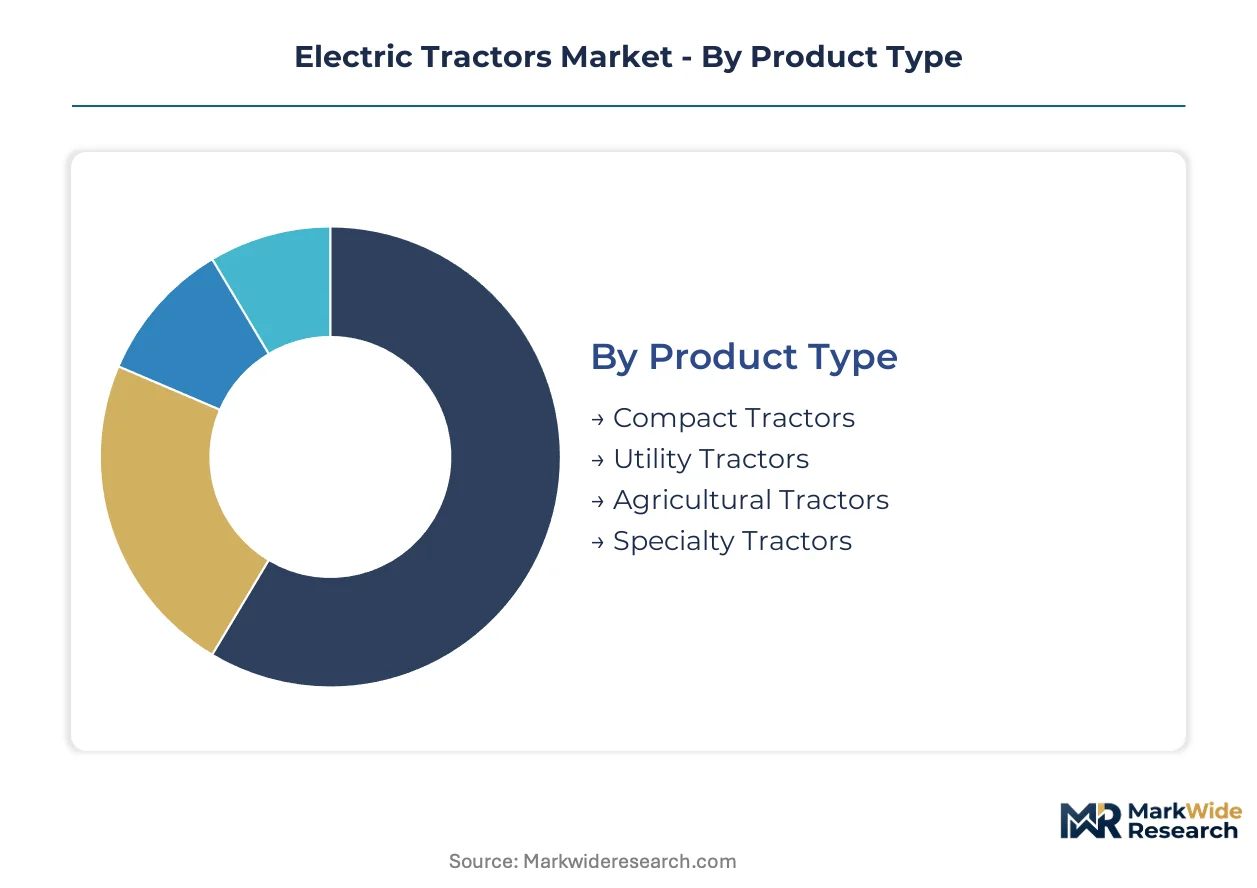
Segmentation in electric tractors reveals how powertrain architecture and farm scale reshape procurement patterns. Understanding these divides exposes where battery economics overcome diesel incumbency and where autonomy commands premium positioning.
Product Type:
Margin pools concentrate in configurations that balance horsepower range with battery pack scalability across diverse farm operations.
- Utility Tractors:These mid-sized units deliver 40–100 horsepower through standardized battery architectures, dominating procurement from mixed-crop operations in the US Corn Belt where diesel cost volatility compresses operating budgets most acutely.
- Specialty Tractors:Narrow-profile designs with sub-60-inch wheelbases enable zero-emission operation in vineyard and orchard row spacing where diesel alternatives face physical constraints; California's Central Valley mandates accelerate fleet turnover here.
- Compact Tractors:Sub-40 horsepower machines serve smallholder and hobby farm segments with lower capital barriers.
- Agricultural Tractors:High-horsepower row-crop configurations above 150 horsepower remain supply-constrained by energy density limitations in current lithium-ion chemistry.
The dominant share belongs to Utility Tractors, while Specialty Tractors are closing the gap fastest.
Application:
Volume concentration tracks where continuous field duty cycles align with battery swap or fast-charge logistics.
- Crop Production:Large-acreage grain and oilseed operations deploy battery-electric units for tillage and planting where EPA Tier 4 Final standards have forced diesel obsolescence timelines in regulated US air basins.
- Soil Cultivation:Tillage applications benefit from regenerative braking on downhill passes and lower continuous power draw compared to harvest operations, concentrating adoption in rolling terrain farms.
- Livestock Farming:Manure handling and feed distribution tasks favor compact electric units for indoor air quality compliance.
- Landscaping:Municipal and commercial grounds maintenance drives demand for low-noise, zero-emission equipment in noise-restricted zones.
Crop Production commands the largest installed base, though Soil Cultivation applications are expanding most quickly as charging infrastructure penetrates agricultural corridors.
End User:
Procurement scale determines whether fleet management platforms or transactional sales dominate the purchasing relationship.
- Farmers:Individual owner-operators below 500 acres represent fragmented demand sensitive to upfront capital cost and residual value risk in transitioning diesel fleets.
- Agricultural Cooperatives:Pooled procurement entities across the US Midwest and European grain belts aggregate volume sufficient to justify dedicated charging infrastructure and negotiate service contract unbundling.
- Landscaping Companies:Commercial operators prioritize equipment uptime guarantees and predictive maintenance analytics through subscription-based fleet management platforms.
- Government Agencies:Federal and state entities drive standard-setting through zero-emission procurement mandates and demonstration program funding.
Agricultural Cooperatives hold the dominant procurement volume position, while Landscaping Companies are adopting electric units at the steepest rate as municipal contracts mandate emission reductions.
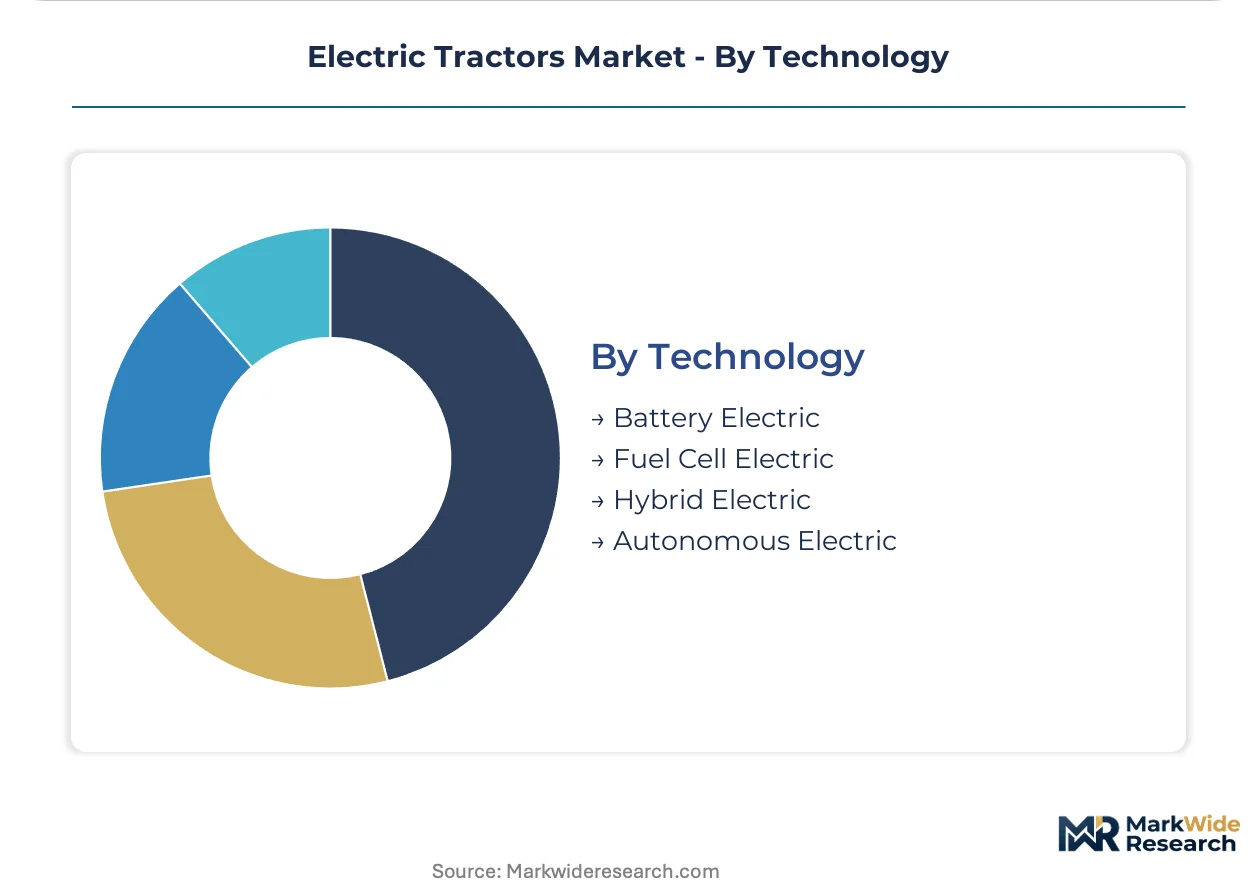
Technology:
Powertrain architecture separates markets by energy storage chemistry maturity and labor substitution capability.
- Battery Electric:Lithium-ion pack architectures with 40–300 kWh capacity leverage mature supply chains and falling per-kilowatt-hour costs, anchoring unit shipment leadership across all farm scales and geographies.
- Autonomous Electric:Integrated autonomy stacks eliminating operator labor command premium pricing in high-value perennial crops; Monarch Tractor and John Deere operations center platforms compete through remote monitoring and fleet optimization contracts.
- Hybrid Electric:Range-extender configurations with small diesel generators bridge charging infrastructure gaps in remote growing regions.
- Fuel Cell Electric:Hydrogen proton-exchange membrane systems remain pre-commercial for agricultural applications due to fueling infrastructure absence and green hydrogen cost premiums.
Battery Electric technology anchors unit shipment leadership, while Autonomous Electric configurations are climbing the fastest as labor costs rise in specialty crop regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Central Valley's high-voltage agricultural grid interconnections and California Aqueduct water infrastructure anchor North American electric tractor deployment, underwriting charging networks that stretch from Fresno to Bakersfield.
United States
EPA Tier 4 Final standards and CARB zero-emission mandates compress diesel residual values in the San Joaquin Valley, where almond and pistachio growers front-load battery-electric procurement ahead of compliance deadlines. The California Air Resources Board's FARMER program subsidizes charging infrastructure at cooperative depots across Tulare and Kern counties.
Germany
EU Green Deal farm-to-fork targets and F-Gas Regulation phase-downs reshape procurement specifications toward electrified fleets in Lower Saxony's intensive livestock regions. The Federal Ministry of Food and Agriculture funds demonstration programs for autonomous electric units in precision crop operations near Oldenburg.
India
PLI scheme subsidies for automotive component manufacturing build domestic lithium-ion assembly capacity, reducing import dependency for electric tractor powertrains in Punjab's rice-wheat belt. The Bureau of Indian Standards certifies battery safety protocols as Haryana's cooperative networks pilot fleet-scale charging at grain mandis.
Japan
METI decarbonization roadmaps and JIS standards for agricultural machinery accelerate compact electric tractor deployment in Kyushu's greenhouse vegetable clusters. Dense Kubota dealer networks across Fukuoka prefecture service high-voltage systems for smallholder rice operations transitioning from diesel tillers.
Australia
Grid reliability constraints and remote station distances slow fleet electrification in Queensland's sugar cane districts, though Victoria's dairy cooperatives adopt compact units for indoor air quality compliance. The Clean Energy Finance Corporation underwrites charging infrastructure at Gippsland agricultural hubs.
Electric Tractors Market Competitive Landscape
Listed leaders compete with private specialists across embedded software competency, collapsing the competitive field to manufacturers with substantial R&D resources. The market structure concentrates around three strategic archetypes: diversified agricultural machinery conglomerates with proprietary fleet management platforms, autonomy-focused specialists eliminating operator labor, and compact equipment manufacturers leveraging dense service networks. Dominant competitive moves include strategic partnerships for battery supply chain security and geographic expansion through dealer network reconfiguration for high-voltage service capabilities.
Within the diversified machinery tier, John Deere and CNH Industrial occupy positions defined by integrated operations center platforms and multi-brand portfolio breadth. Monarch Tractor exemplifies the autonomy-specialist archetype, while Kubota Corporation anchors the compact equipment segment through established distribution infrastructure. These three represent distinct strategic vectors—software-locked fleet contracts, labor-substitution premium pricing, and service-network density—rather than direct product competition.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| Kubota Corporation |
| AGCO Corporation |
| Monarch Tractor |
| Solectrac |
| Fendt |
| Mahindra |
| Yanmar |
| Others |
Value Network & Pricing Analysis
ISO 11783 certification for agricultural electronics gates both supplier qualification and price tiering simultaneously, forcing manufacturers to absorb embedded software development costs or surrender premium positioning to certified competitors. This regulatory threshold compresses margins for uncertified entrants while amplifying pricing power for incumbents with validated precision farming interfaces.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 11783-validated units commanding substantial premiums over uncertified alternatives. Battery pack capacity and autonomy integration serve as secondary differentiation levers, with autonomous electric configurations extracting labor-substitution value in specialty crop applications. Pricing pressure stems from lithium-ion commodity volatility and cobalt supply uncertainty, which compresses margins in mid-tier utility tractor segments. Agricultural cooperatives exhibit highest price sensitivity due to pooled procurement leverage, while vineyard operators in California's Central Valley demonstrate lowest sensitivity given compliance-driven replacement mandates.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell manufacturing, with Japan controlling specialty cathode chemistry production for high-energy-density agricultural applications. The electric tractor supply chain draws from these three nations for battery cells, power electronics, and precision motor controllers, with final assembly concentrating in the United States, Germany, and Japan. Single-source vulnerability in cobalt processing exposes procurement timelines to geopolitical disruption in Central African supply corridors. Distribution runs through established agricultural equipment dealer networks requiring capital-intensive retooling for high-voltage diagnostics and battery service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent diesel tractor manufacturers face substitution pressure from battery-electric architectures that eliminate legacy powertrain competencies, demanding defensive repositioning around software-locked fleet management platforms.
For Market Incumbents: Shield installed base relationships by accelerating proprietary operations center deployment across North American row-crop operations before autonomy specialists capture vineyard and orchard segments. Vertical integration into battery pack assembly mitigates lithium supply volatility, while ISO 11783 certification investment preserves pricing tier access against emerging software-native competitors.
For New Entrants and Emerging Players: California Air Resources Board fast-track certification offers regulatory arbitrage for zero-emission equipment mandates compressing diesel residual values in the Central Valley. Specialty tractor configurations for narrow-profile vineyards represent the most penetrable white space, with autonomy-integrated units commanding premium positioning through labor substitution value propositions absent in commodity utility segments.
For Investors and Strategic Acquirers: EPA Tier 4 Final enforcement timelines reshape the acquisition landscape by accelerating fleet turnover velocity in regulated US air basins. Long-term viability centers on software-embedded fleet management platforms rather than transactional equipment sales, with autonomous electric specialists representing priority acquisition archetypes. Battery raw material sourcing agreements serve as the critical inflection signal for manufacturing scale sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation from South Korean suppliers for California Central Valley deployment. |
| Autonomy Stack Integration | Enables labor-substitution pricing premiums in high-value perennial crop operations. |
| Dealer Network Reconfiguration | Retools service infrastructure for high-voltage diagnostics across Midwest agricultural corridors. |
| ISO 11783 Certification Pathway | Validates precision farming interfaces for fleet management platform lock-in. |
| Charging Infrastructure Partnership | Deploys high-capacity grid interconnections at cooperative depots in regulated air basins. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, EU Green Deal implementation documents, and agricultural equipment trade data. Primary interviews engaged fleet managers at agricultural cooperatives, precision farming technology directors, dealer network operations heads, and battery supply chain procurement leads. Secondary validation incorporated CARB enforcement timelines, PLI scheme disbursement records, and lithium carbonate price indices. Bottom-up unit shipment estimates triangulated against top-down addressable farm acreage analysis.
Segmentation dimensions modeled span powertrain architecture, farm scale tier, application intensity, and regional regulatory cluster across the projection horizon. CAGRs derive from installed base turnover velocity, diesel-to-electric substitution elasticities, and charging infrastructure penetration curves. Forecast inputs incorporate battery pack cost trajectories, autonomy adoption rates in specialty crops, and compliance deadline clustering effects.
Decision-makers should treat outputs as directional under sustained lithium supply expansion and stable grid interconnection permitting timelines; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in battery chemistry cost curves and zero-emission mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Brazil Agricultural Machinery Market
Agricultural Machinery
Agricultural Drum Mowers Market
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
Sickle Bar Mower Market
Agricultural Machinery
India Tractor Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Driverless Tractor Market
Agricultural Machinery
Europe Utility Tractor Market
Agricultural Machinery
Orchard Tractor Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
North America Agricultural Sprayers Market
Agricultural Machinery
Italy Agricultural Machinery Market
Agricultural Machinery
Vietnam Combine Harvester Market
Agricultural Machinery
Agricultural Spray Drone Market
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
North America Agricultural Machinery Market