
 Compost Turning Machine Market | 2026-2036
Compost Turning Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Compost Turning Machine Market Analysis
China's industrial composting belt is reshaping equipment sourcing patterns for large-scale turner systems. Vermeer Corporation leverages its North American dealer network to sustain aftermarket parts revenue across Midwest agricultural markets. SCARAB International anchors its position through specialized windrow turner designs for high-throughput municipal operations. Eggersmann Anlagenbau GmbH competes on integrated plant engineering, bundling turners with screening and aeration subsystems.
A compost turning machine mechanically agitates and aerates organic material piles to accelerate decomposition, typically processing windrows two to four meters wide with drum speeds calibrated to material density and moisture content. The equipment serves commercial composting facilities, agricultural operations, and municipal organic waste programs requiring pathogen reduction and stabilized humus output. Mechanical technology dominates installed base economics due to simpler maintenance protocols and lower capital outlay, while electric systems capture planning interest in European urban facilities facing noise ordinances and emissions restrictions. Agricultural waste applications generate the steadiest replacement cycle demand, whereas municipal solid waste contracts concentrate margin pools through multi-year service agreements and technology upgrade clauses.
The US EPA's organic waste landfill diversion guidelines and EU F-Gas Regulation on equipment emissions shape product certification requirements and cross-border market access protocols for manufacturers. Germany's KBA and France's ANSM enforce machinery safety standards that influence turner guarding, emergency stop configurations, and operator certification programs. India's BIS adoption of ISO compost quality standards creates equipment specification pathways for export-oriented suppliers. Stakeholders must monitor how carbon accounting rules for soil amendment credits reshape facility scale decisions and turner sizing requirements.
Market Dynamics
Electric and hybrid turner technologies are compressing the installed base of diesel-powered units as European urban facilities face tightening noise ordinances and emissions ceilings. Municipal procurement offices now weight lifecycle carbon metrics above upfront capital cost in tender evaluations.
Growth Catalysts
- EU F-Gas Regulation:Equipment emissions standards are accelerating replacement cycles in Germany, France, and Italy as municipalities retrofit existing composting infrastructure to maintain operating permits.
- Windrow aeration automation:Sensor-integrated drum systems are reducing labor intensity at high-throughput municipal facilities, cutting operator headcount per shift by half.
- Rhine-Ruhr corridor investment:Federal climate adaptation funding is channeling capital into district-level composting infrastructure, concentrating equipment demand in Germany's industrial heartland.
Market Restraints
- Steel and hydraulic component volatility:Input cost swings for fabricated drum assemblies and drive systems are compressing margin visibility for equipment fabricators on fixed-price municipal contracts.
- Specialized foundry concentration:Heat-treated alloy drum manufacturing concentrates in Central European supplier networks, creating vulnerability to energy price shocks and logistics disruptions.
- Electric drivetrain technical ceiling:Battery energy density limitations restrict continuous operation duration for fully electric turners in large-scale agricultural windrow applications.
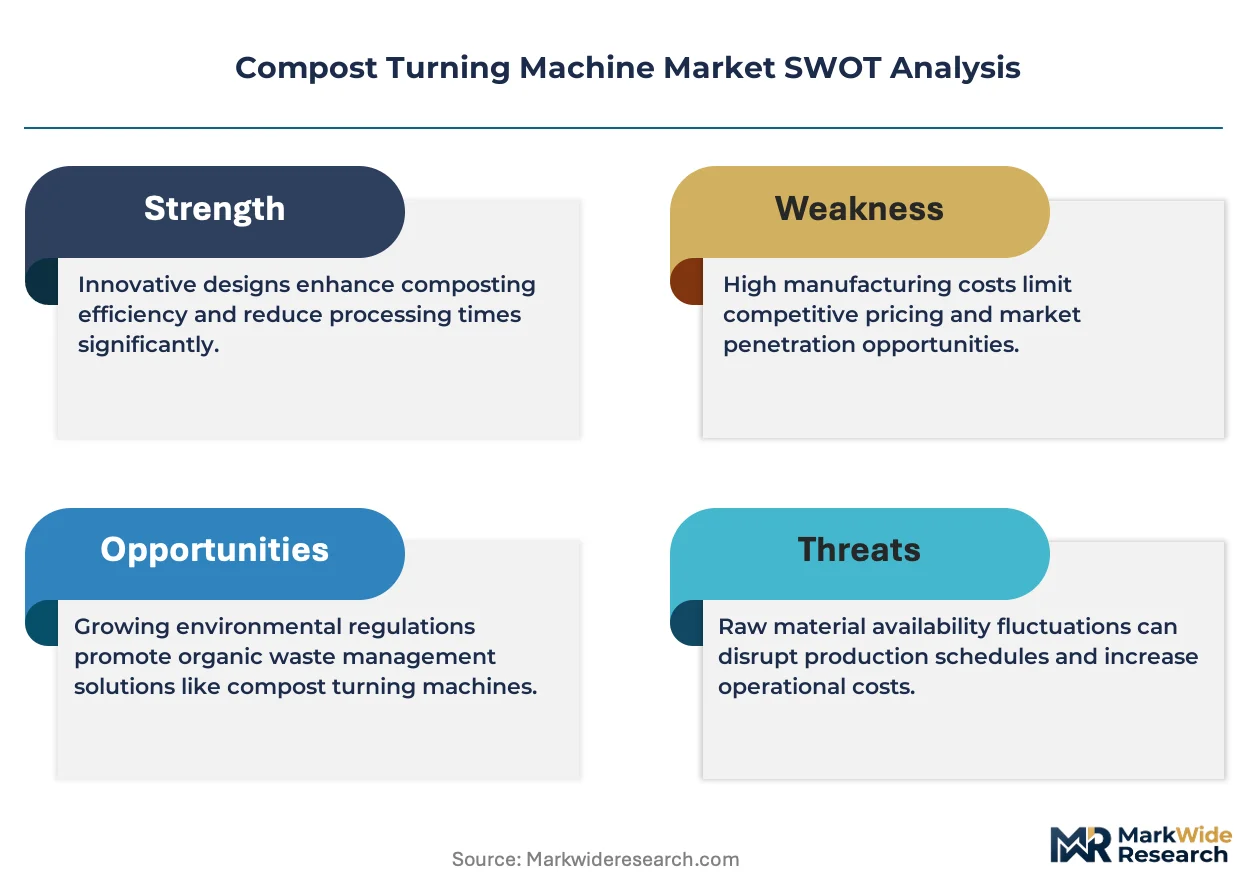
Strategic Opportunities
- India BIS certification pathway:Adoption of ISO compost quality standards is opening equipment specification channels for export-oriented suppliers targeting subcontinental municipal waste programs.
- Carbon credit monetization:Soil amendment credit accounting rules are reshaping facility scale decisions, creating demand for larger turner configurations that maximize throughput per labor hour.
- Telematics-augmented service contracts:Predictive maintenance platforms bundled with equipment leases are capturing multi-year revenue streams from risk-averse municipal procurement offices.
Industry Challenges
- Certified technician scarcity:Hydraulic system diagnostics and electric drivetrain repair require specialized training that outpaces vocational program output in Midwest agricultural markets.
- Legacy diesel fleet integration:Hybrid procurement strategies force facilities to maintain dual spare parts inventories and cross-train maintenance crews on incompatible system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compost Turning Machine Market |
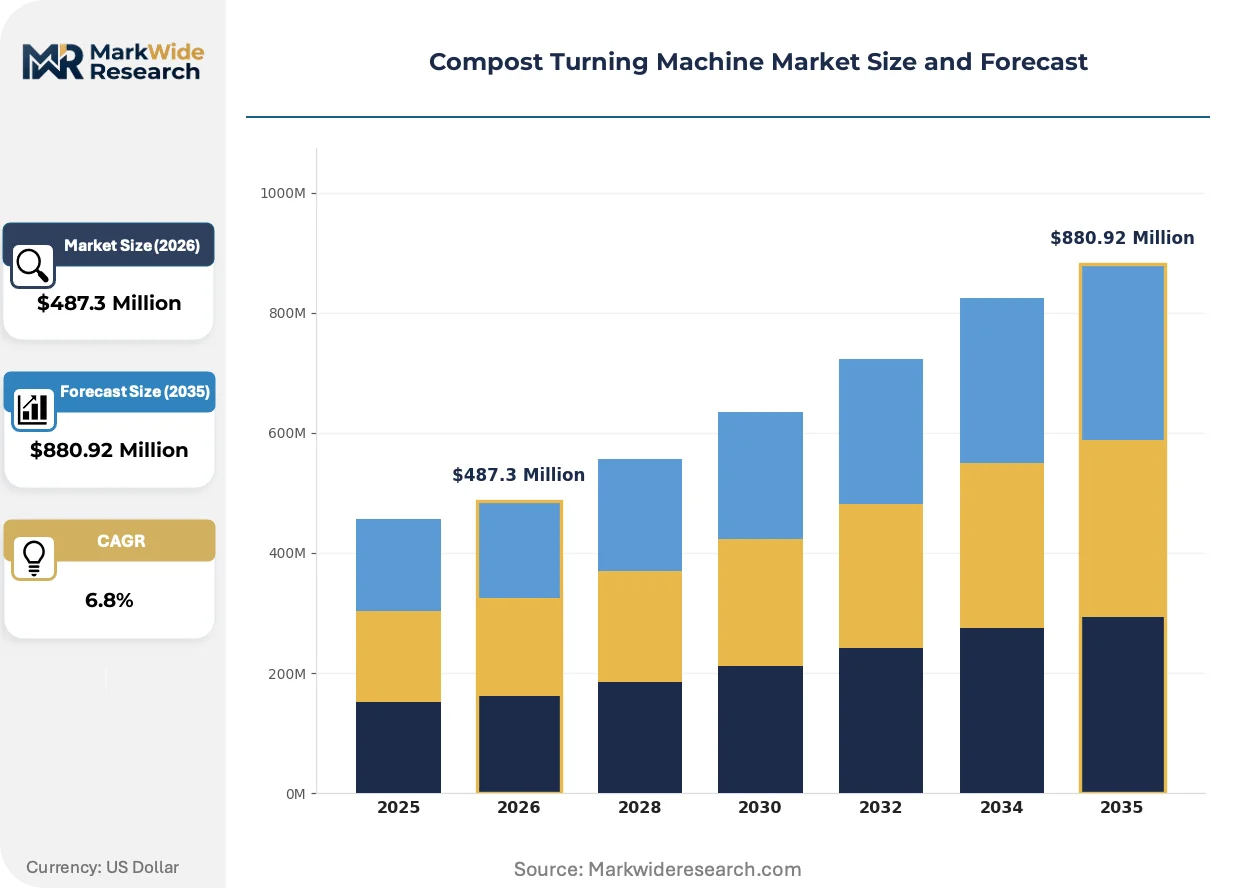
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static, Turners, Aerators, Shredders Technology: Mechanical, Hydraulic, Manual, Electric Application: Agricultural Waste, Municipal Solid Waste, Garden Waste, Industrial Waste End User: Farmers, Landscapers, Municipalities, Waste Management Firms |
| Companies Covered | Eggersmann Anlagenbau GmbH, Brown Bear Corporation, SCARAB International, Backhus (Eggersmann Group), ALLU Finland Oy, Terex Corporation, Midwest Bio-Systems Inc., Patz Corporation, Vermeer Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compost Turning Machine Market Emerging Trajectories
Equipment intelligence layers are redefining competitive differentiation as buyers prioritize uptime guarantees over hardware specifications. Automation, emissions compliance, and service unbundling are converging to reshape vendor-customer relationships.
Drum speed and moisture calibration systems are migrating from manual operator adjustment to automated closed-loop control. Municipal facilities in Germany and the Netherlands are adopting these configurations fastest, driven by labor cost pressures and consistency mandates for pathogen reduction. The technology is migrating from premium tier positioning toward mid-range equipment specifications, compressing price premiums for basic mechanical turners.
France's ANSM and Germany's KBA machinery safety standards are tightening emergency stop and guarding requirements for windrow turners. Equipment manufacturers must redesign operator platforms and drum enclosures to satisfy type-approval protocols before market entry. Urban composting facilities in Paris and Berlin metropolitan zones are accelerating replacement schedules to preempt compliance deadlines.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance bundles. Agricultural cooperatives and municipal authorities are separately sourcing spare parts through third-party channels and performing maintenance in-house. This pattern concentrates in North American Midwest markets where dealer network density supports competitive parts distribution.
Compost Turning Machine Market Segmentation
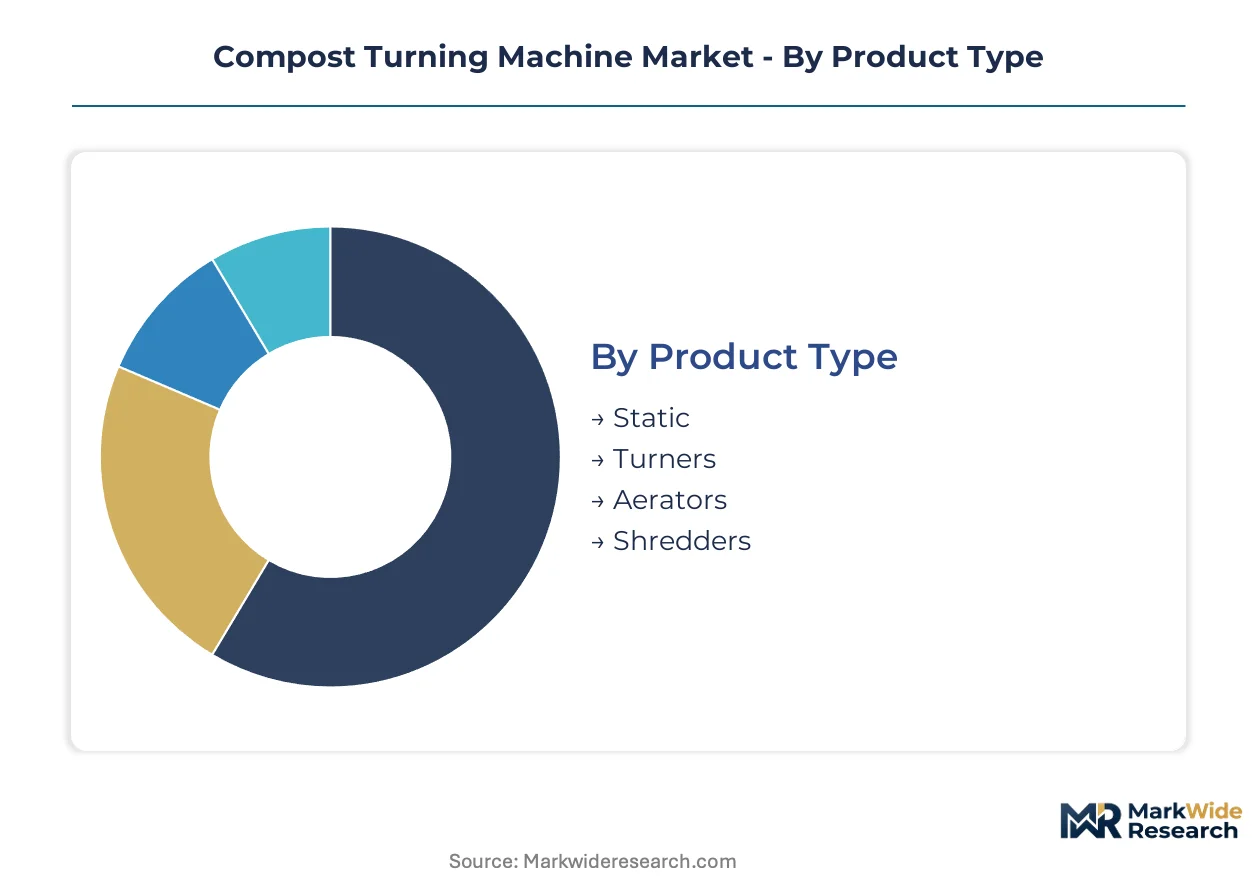
Compost turning equipment exhibits divergent specification requirements across facility scales and material streams. Understanding how product configurations, power systems, and customer procurement patterns segment reveals where margin pools concentrate and technology substitution accelerates.
Product Type:
Facility operators select equipment based on throughput volume, material heterogeneity, and labor availability across commercial and municipal composting operations.
- Turners:Self-propelled windrow turners dominate municipal procurement specifications, with drum widths spanning two to four meters calibrated to organic waste tonnage. Rhine-Ruhr corridor municipalities specify these units under federal climate adaptation funding programs prioritizing throughput per labor hour.
- Aerators:Static aeration systems integrate with blower subsystems for enclosed tunnel composting, reducing operator exposure in high-pathogen municipal solid waste streams. German and French urban facilities specify these configurations to satisfy EU F-Gas Regulation emissions ceilings and noise ordinances.
- Static:Stationary in-vessel systems serve small-scale agricultural operations with limited windrow space and seasonal processing windows.
- Shredders:Pre-processing size reduction equipment handles contaminated municipal feedstocks requiring homogenization before windrow formation.
The dominant share belongs to Turners, while Aerators is closing the gap fastest as enclosed composting gains regulatory preference in European urban zones.
Technology:
Power system selection reflects capital budget constraints, operational cost structures, and emissions compliance timelines facing facility operators.
- Mechanical:Simpler drive trains and maintenance protocols sustain installed base economics across Midwest agricultural markets where dealer network density supports aftermarket parts availability.
- Electric:Battery-powered and grid-connected systems capture planning interest in Paris and Berlin metropolitan facilities facing tightening emissions restrictions and carbon accounting requirements for soil amendment credits.
- Hydraulic:High-torque hydraulic drive systems persist in large-scale agricultural windrow applications where continuous operation duration exceeds current battery energy density limitations.
- Manual:Small-scale tractor-pulled units serve landscaping contractors and farm operations with seasonal, low-volume processing requirements.
Mechanical systems retain the largest installed base, though Electric configurations are expanding most quickly as municipal procurement offices weight lifecycle carbon metrics above upfront capital cost.
Application:
Feedstock characteristics dictate equipment sizing, contamination tolerance, and pathogen reduction certification requirements across end-use segments.
- Municipal Solid Waste:Heterogeneous organic fractions from household collection require robust drum construction and integrated screening subsystems. Multi-year service agreements with technology upgrade clauses concentrate margin pools for equipment suppliers in Germany, France, and Italy under EU landfill diversion mandates.
- Agricultural Waste:Manure and crop residue applications generate steadiest replacement cycle demand through agricultural cooperatives and independent farm operators across North American Midwest markets.
- Industrial Waste:Food processing and biofuel byproduct streams require specialized corrosion-resistant drum materials and accelerated aeration protocols.
- Garden Waste:Lower-contamination green waste from landscaping operations suits smaller turner configurations with reduced guarding and emergency stop complexity.
Agricultural Waste commands the highest replacement frequency, while Municipal Solid Waste is gaining share fastest as district-level composting infrastructure expands under regulatory pressure.
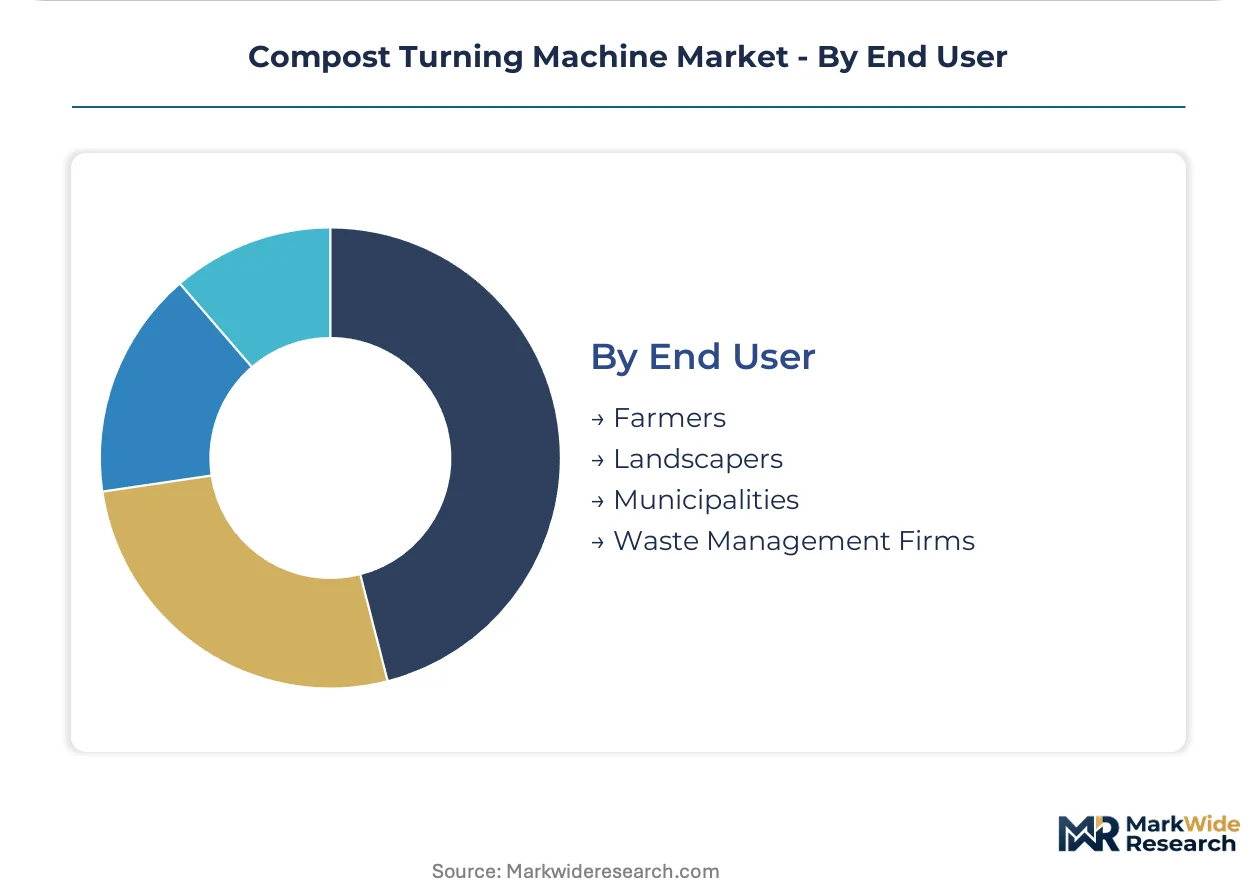
End User:
Procurement authority and technical sophistication vary sharply across customer categories, shaping sales channel configuration and service bundling strategies.
- Municipalities:District and city-level waste authorities issue tender specifications emphasizing lifecycle cost, emissions compliance, and uptime guarantees. Germany's KBA and France's ANSM machinery safety standards influence operator platform and guarding requirements in procurement documents.
- Waste Management Firms:National and regional contractors operating multiple facilities prioritize fleet standardization and predictive maintenance platforms to minimize cross-site spare parts inventories.
- Farmers:Agricultural cooperatives and independent operators exhibit strongest price sensitivity and highest propensity for third-party parts sourcing and in-house maintenance.
- Landscapers:Seasonal demand patterns and limited capital budgets favor rental and lease arrangements over equipment ownership.
Municipalities represent the largest contract value per transaction, while Waste Management Firms are scaling fastest through consolidation and multi-facility fleet standardization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heat-treated alloy drum fabrication concentrates in Central European supplier networks, creating geographic vulnerability to energy price shocks while Rhine-Ruhr corridor municipalities channel federal climate adaptation funding into district-level composting infrastructure.
Germany
The KBA enforces machinery safety standards for windrow turner guarding and emergency stop configurations. Federal climate adaptation funding flows into the Rhine-Ruhr corridor, concentrating equipment demand in district-level composting infrastructure across North Rhine-Westphalia and Hesse.
France
Paris and Berlin metropolitan zones accelerate replacement schedules to preempt ANSM compliance deadlines on operator platform redesign. The EU F-Gas Regulation drives retrofit cycles in urban composting facilities facing tightening emissions ceilings and noise ordinances.
United States
Midwest agricultural markets sustain replacement cycle demand through agricultural cooperatives and independent farm operators. The EPA's organic waste landfill diversion guidelines shape product certification requirements for cross-border market access protocols.
India
BIS adoption of ISO compost quality standards creates equipment specification pathways for export-oriented suppliers. Subcontinental municipal waste programs expand procurement specifications as district-level composting infrastructure scales under central government organic waste mandates.
Italy
Municipalities retrofit existing composting infrastructure to maintain operating permits under EU landfill diversion mandates. Northern industrial districts concentrate demand for high-throughput municipal operations with integrated screening and aeration subsystems.
Compost Turning Machine Market Vendor Landscape
Integrated plant engineering specialists and agricultural equipment fabricators split the market across municipal and farm-segment procurement channels. The vendor base organizes around three strategic archetypes: European turnkey system integrators bundling turners with screening and aeration subsystems, North American agricultural machinery houses leveraging dealer network density for aftermarket parts revenue, and specialized windrow equipment designers focused on high-throughput municipal specifications. Competitive moves concentrate on geographic expansion through distributor partnerships and portfolio diversification into electric drivetrain configurations.
Among German-based engineering firms, Eggersmann Anlagenbau GmbH occupies a position exemplifying the integrated plant engineering archetype. SCARAB International and Vermeer Corporation represent distinct geographic anchors within the specialized equipment and agricultural machinery tiers respectively. These three entities illustrate how vendor positioning fragments across municipal procurement offices weighting lifecycle carbon metrics and agricultural cooperatives exhibiting price sensitivity toward third-party parts sourcing.
| Leading Market Players |
|---|
| Eggersmann Anlagenbau GmbH |
| Brown Bear Corporation |
| SCARAB International |
| Backhus (Eggersmann Group) |
| ALLU Finland Oy |
| Terex Corporation |
| Midwest Bio-Systems Inc. |
| Patz Corporation |
| Vermeer Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Central European heat-treated alloy drum fabrication is compressing supplier margins and amplifying pricing power for foundries serving German and Italian equipment fabricators. This utilization squeeze forces municipal procurement offices to accept longer lead times and weakened negotiation leverage on fixed-price contracts.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure by mandating emissions-compliant configurations that separate premium electric-hybrid units from standard mechanical systems and economy-grade manual equipment. Price differentiation rests on certification grade for pathogen reduction and after-sales service bundling rather than hardware specifications alone. Cost compression in the economy tier is intensifying because agricultural cooperatives source third-party spare parts and perform maintenance in-house. Municipalities exhibit lowest price sensitivity due to multi-year service agreements with technology upgrade clauses, while farmers remain most responsive to upfront capital outlay.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard as fabricators push financing burden onto Central European foundries and hydraulic component suppliers. Heat-treated alloy drum manufacturing concentrates in Germany, Italy, and Poland, while electric drivetrain subsystems draw from South Korean and Japanese battery suppliers. Raw material dependencies span heat-treated steel alloys, hydraulic drive systems, and lithium-ion battery cells. Single-source vulnerability in specialized foundry capacity creates exposure to energy price shocks. Distribution runs through authorized dealer networks in North American agricultural markets and direct municipal tender channels in European urban zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as EU landfill diversion mandates force replacement cycles across German, French, and Italian municipal infrastructure. Federal climate adaptation funding in Germany's Rhine-Ruhr corridor provides the cyclical anchor.
For Market Incumbents: Pre-empt electric drivetrain substitution by securing captive supply of battery subsystems through backward integration into South Korean cell partnerships. Lock in multi-year municipal service contracts with predictive maintenance platforms before competitor telematics offerings mature. Defend against specialized windrow equipment designers by bundling turners with screening and aeration subsystems under integrated plant engineering contracts. For New Entrants and Emerging Players: Build out India BIS certification capabilities to capture subcontinental municipal waste program specifications as district-level composting infrastructure scales. Target agricultural cooperatives in North American Midwest markets with rental-lease arrangements that sidestep incumbent dealer network density. Enter through telematics-augmented service contracts that municipal procurement offices increasingly favor over equipment ownership. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated plant engineering specialists bundling equipment with multi-year maintenance obligations. Long-term viability over a 5-10 year window favors vendors with captive aftermarket parts revenue streams and municipal contract backlogs. Acquisition targets should display vertical integration into heat-treated alloy drum fabrication or exclusive distribution control in high-replacement-frequency agricultural zones. Watch for carbon credit monetization rules as the inflection signal that reshapes facility scale decisions and turner sizing requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Drivetrain Transition | Battery-powered configurations satisfy Paris and Berlin emissions ceilings while commanding service contract premiums. |
| Backward Integration into Foundry Capacity | Captive heat-treated alloy drum production insulates margin visibility from Central European energy price volatility. |
| Telematics Platform Development | Predictive maintenance offerings capture multi-year revenue streams from risk-averse German municipal procurement offices. |
| India BIS Certification Investment | ISO compost quality alignment opens equipment specification channels for subcontinental municipal waste programs. |
| Carbon Credit Monetization Structuring | Soil amendment credit accounting expertise differentiates vendors as facility scale decisions shift toward larger configurations. |
Methodological Framework
Initial hypotheses were tested against primary input from municipal procurement directors, agricultural cooperative equipment managers, aftermarket service heads, and plant engineering specialists at integrated system providers and refined through secondary validation. Primary fieldwork combined structured interviews with maintenance directors at composting facilities and OEM procurement teams with trade data analysis. Secondary sources encompassed EU F-Gas Regulation compliance filings, KBA and ANSM machinery safety standards documentation, BIS certification registries, and customs records for heat-treated alloy drum imports. Bottom-up facility-level demand estimates were triangulated against top-down regional infrastructure spending projections.
Demand-supply balance modeling across the projection horizon incorporated municipal organic waste tonnage forecasts, agricultural windrow replacement cycles, and foundry capacity utilization rates. Segmentation dimensions spanned product type, power system technology, feedstock application, and end-user procurement authority. CAGRs were derived from fitted growth curves calibrated to historical equipment shipment data and regulatory compliance deadline schedules. Industry-specific forecast inputs included federal climate adaptation funding disbursement trajectories in Germany and central government organic waste mandate implementation pacing in India.
Stress conditions across steel and hydraulic component price volatility, battery energy density improvement rates, and municipal budget austerity scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and infrastructure funding continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Soil Aerators Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Cotton Picker Market
Agricultural Equipment
Global Drip Emitters Market
Agricultural Equipment
Stock Tanks Market
Agricultural Equipment
Plow Folding System Market
Agricultural Equipment
Australia Bird Feeder Market
Agricultural Equipment
Livestock Grow Lights Market
Agricultural Equipment
Wheelbarrow Market
Agricultural Equipment
Billhook Market
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
Commercial Grain Mill Market
Agricultural Equipment
Lawn Shredder Market
Agricultural Equipment
Irrigation Syringe Market
Agricultural Equipment
North America Electric Zero Turn Mower Market
Agricultural Equipment
Global Infrared Heater for Agriculture Market