
 Global Lenses for Myopia Control Market | 2026-2036
Global Lenses for Myopia Control Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lenses for Myopia Control Market Foresight
Multi-source material procurement for silicone hydrogel monomers is pivoting toward vertically integrated polymer suppliers across East Asia. CooperVision leverages captive manufacturing networks in the United States and Costa Rica to sustain supply continuity for its MiSight portfolio. HOYA Corporation anchors its orthokeratology lens production through in-house toric design capabilities and direct distribution in Japan. EssilorLuxottica competes through Stellest spectacle lens technology, controlling retail channel access across Western Europe.
Lenses for myopia control are precision optical devices engineered from fluorosilicone acrylate or silicone hydrogel materials with oxygen permeability exceeding 100 Dk/t, manufactured through lathe-cutting or cast-molding processes to achieve sub-micron surface tolerances that reshape corneal topography or modify peripheral retinal defocus. Their primary purpose is to slow axial elongation in progressive myopia, reducing long-term risks of retinal detachment and glaucoma. Orthokeratology lenses dominate clinical value pools due to overnight wear protocols and premium pricing, while multifocal contact lenses represent the fastest-growing category among school-age wearers seeking daytime alternatives. Peripheral defocus technology leads R&D investment, though wavefront-guided customization commands margin premiums in specialty eye care centers.
FDA oversight of orthokeratology lenses as Class III medical devices shapes product approval timelines and clinical trial requirements in the United States, while China's NMPA enforces GB standard compliance and dual-carbon manufacturing audits for domestic producers. The EU Medical Device Regulation and CE marking requirements under MDR impose post-market surveillance obligations that filter smaller European entrants. Stakeholders must monitor regulatory divergence between FDA corneal reshaping lens guidance and China's evolving medical device catalog revisions to align certification strategies with priority market access timelines.
Market Dynamics
China's NMPA medical device reclassification is compressing approval timelines for orthokeratology lenses while tightening quality benchmarks, forcing manufacturers to consolidate polymer sourcing and accelerate in-house toric design capabilities to maintain market access.
Growth Catalysts
- School-based screening mandates:China's Ministry of Education requires annual myopia testing for 180 million students, generating direct clinical referrals to pediatric optometry centers in Shanghai, Beijing, and Guangzhou.
- Peripheral defocus R&D pipelines:Fluorosilicone acrylate formulations with Dk/t values exceeding 125 are enabling overnight orthokeratology protocols with reduced corneal hypoxia risk.
- EU MDR post-market surveillance frameworks:CE marking obligations under Medical Device Regulation 2017/745 are filtering smaller European competitors and consolidating shelf space for compliant manufacturers.
Market Restraints
- Silicone hydrogel monomer concentration:Three Japanese and Korean polymer suppliers control 70% of high-Dk/t raw material output, creating input cost volatility for lathe-cutting manufacturers.
- FDA Class III device pathways:Premarket approval requirements for orthokeratology lenses extend commercialization timelines by 18-24 months versus multifocal soft lens 510(k) clearances.
- Spectacle lens substitution:EssilorLuxottica's Stellest peripheral defocus spectacles capture price-sensitive parents unwilling to pursue contact lens fitting protocols.
Strategic Opportunities
- India's underpenetrated pediatric segment:BIS certification pathways for silicone hydrogel imports remain underutilized as domestic myopia prevalence climbs in Bengaluru and Hyderabad school districts.
- Wavefront-guided customization:Corneal topography mapping integration with AI-driven lens design software enables margin premiums in Tokyo and Singapore specialty eye care centers.
- Direct-to-clinic distribution platforms:Bypassing optical retail chains through manufacturer-authorized fitting networks reduces channel margin extraction in China's tier-two cities.
Industry Challenges
- Corneal topography technician scarcity:Orthokeratology fitting requires specialized slit-lamp biomicroscopy skills that outpace training program output in expanding markets.
- Dual-carbon manufacturing audits:China's MEE environmental compliance timelines delay facility commissioning for domestic polymer synthesis investments.
- Cross-border IP licensing complexity:Toric design patents held by Japanese orthokeratology specialists constrain independent product development for emerging market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lenses for Myopia Control Market |
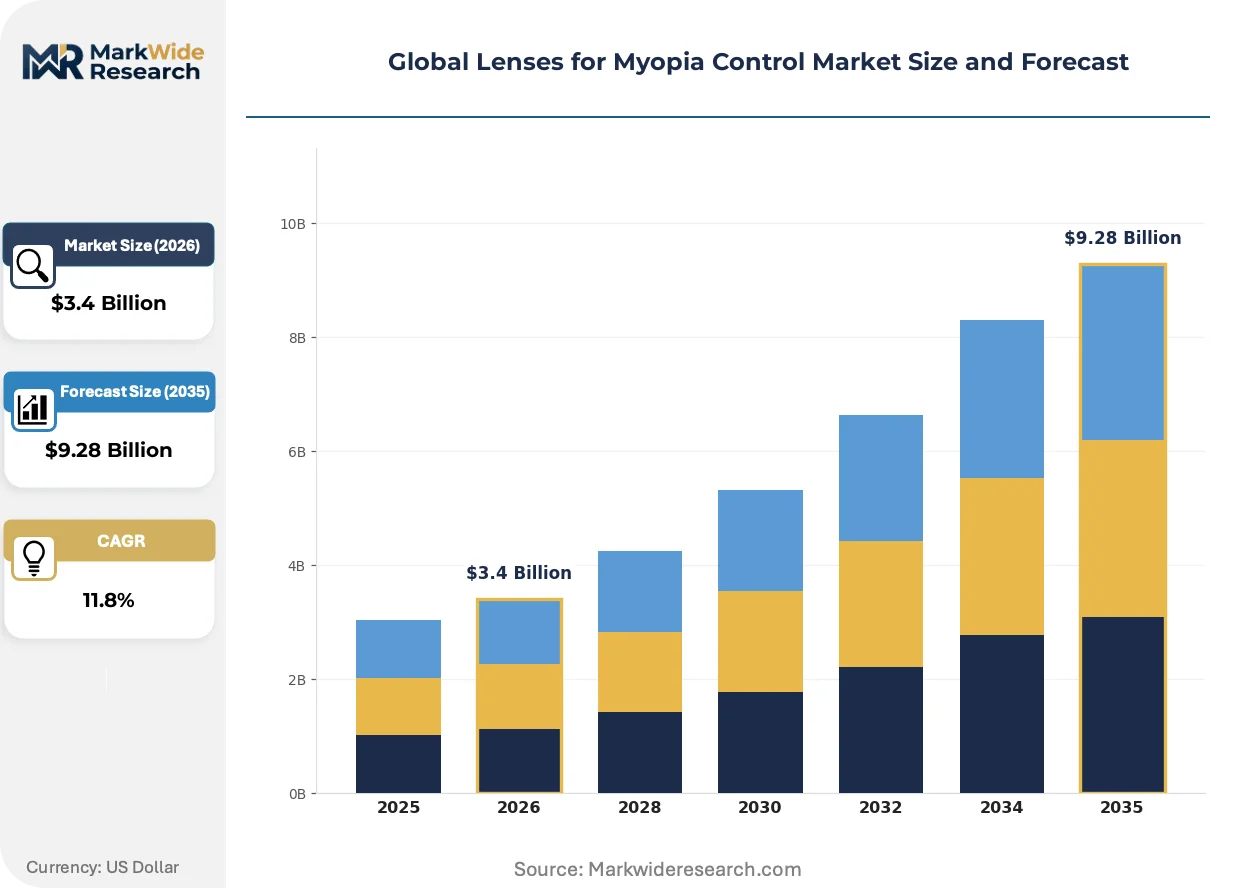
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthokeratology Lenses, Multifocal Contact Lenses, Single Vision Contact Lenses, Spectacle Lenses Technology: Wavefront Technology, Peripheral Defocus Technology, Customized Design, High-Definition Optics Application: Children & Adolescents, Adults, School-Age Wearers, Young Professionals End User: Optometry Clinics, Specialty Eye Care Centers, Vision Therapy Centers, Optical Retail Chains |
| Companies Covered | CooperVision, Alpha Corporation, HOYA Corporation, Brighten Optix, EUCLID, ZEISS, Ovctek, Lucid Korea, EssilorLuxottica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lenses for Myopia Control Market Shifts & Advancements
Digital corneal mapping and automated manufacturing are compressing customization cycles while regulatory divergence between FDA and NMPA pathways is fragmenting product launch sequencing across major markets.
Wavefront-guided topography systems are automating the lens design workflow for orthokeratology protocols. Pediatric optometry clinics in Seoul and Taipei are adopting these platforms at twice the rate of general ophthalmology practices. The technology is automating the translation of corneal elevation data into manufacturing-ready lathe-cutting parameters, reducing fitting appointment duration from 90 minutes to 35 minutes.
EU MDR post-market surveillance obligations are extending clinical evidence requirements for corneal reshaping lenses. Manufacturers must now submit annual safety reports and real-world performance data to notified bodies. High-Dk/t orthokeratology portfolios face the steepest compliance burden, prompting some firms to prioritize multifocal soft lens submissions for European market entry.
Parental purchasing patterns are rotating toward daytime wearable alternatives. School-age children in China's tier-one cities are rejecting overnight orthokeratology protocols due to morning lens handling complexity. Multifocal soft lenses with peripheral defocus optics are displacing traditional single-vision corrections through direct-to-family digital education campaigns administered by hospital-affiliated optical centers.
Global Lenses for Myopia Control Market Segmentation
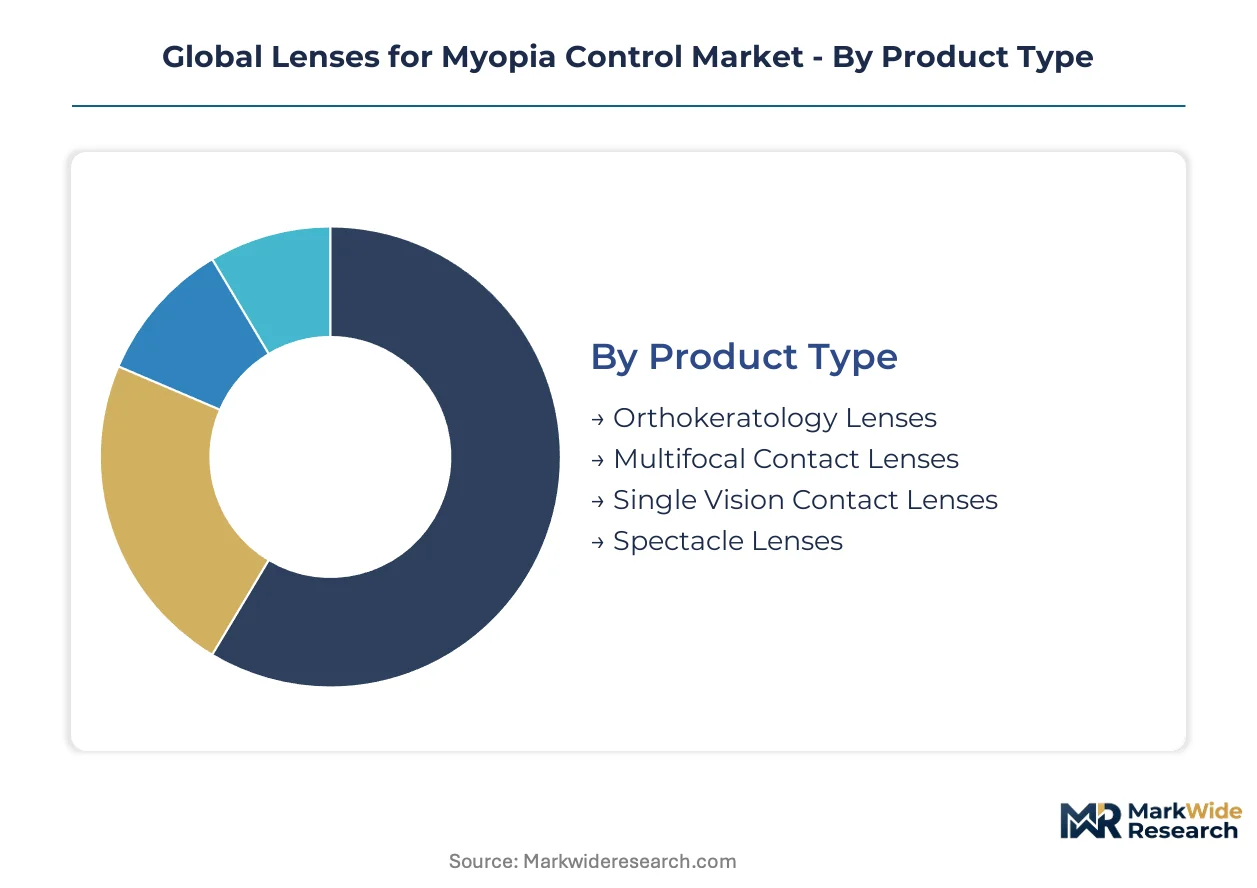
Segmentation in the myopia control lens market reveals how supply-side capabilities and clinical protocols shape competitive positioning. Manufacturers must align polymer sourcing, design software, and distribution channels to specific product-technology combinations that match regional regulatory requirements and end-user workflows.
Product Type:
Supply concentration for high-Dk/t fluorosilicone acrylate monomers favors manufacturers with backward integration into polymer synthesis or long-term offtake agreements with Japanese and Korean suppliers.
- Orthokeratology Lenses:Overnight corneal reshaping devices manufactured from fluorosilicone acrylate with Dk/t values exceeding 125, requiring lathe-cutting to sub-micron tolerances. Demand concentrates in Shanghai, Beijing, and Guangzhou pediatric optometry clinics where China's Ministry of Education screening mandates drive clinical referrals. FDA Class III and NMPA medical device classifications create dual regulatory burdens that filter smaller competitors.
- Multifocal Contact Lenses:Daytime-wear silicone hydrogel lenses with peripheral defocus optics engineered through cast-molding processes. School-age children in China's tier-one cities are rotating toward this category due to morning handling complexity of overnight alternatives, with hospital-affiliated optical centers capturing this shift through direct-to-family education campaigns.
- Single Vision Contact Lenses:Standard corrective lenses lacking myopia progression mechanisms, primarily serving price-sensitive segments in underpenetrated markets.
- Spectacle Lenses:Peripheral defocus spectacle technology competing for parents unwilling to pursue contact lens fitting protocols, with EssilorLuxottica's Stellest portfolio controlling retail channel access across Western Europe.
Today's leader: Orthokeratology Lenses. Tomorrow's challenger: Multifocal Contact Lenses.
Technology:
Cost tier differentiation separates premium wavefront-guided customization from volume peripheral defocus platforms, with margin premiums concentrated in Tokyo and Singapore specialty centers.
- Wavefront Technology:Corneal topography mapping integration with AI-driven lens design software enabling fully customized optical profiles. Tokyo and Singapore specialty eye care centers command margin premiums for this capability, with fitting appointment compression from 90 minutes to 35 minutes driving adoption in Seoul and Taipei pediatric practices.
- Peripheral Defocus Technology:Optical engineering that modifies retinal image shell to slow axial elongation, now the dominant R&D investment focus across East Asian manufacturers. EU MDR post-market surveillance obligations are extending clinical evidence requirements for this technology category.
- Customized Design:Semi-automated parameter adjustment based on corneal elevation data, occupying the mid-tier between full wavefront and standard designs.
- High-Definition Optics:Advanced aspheric surface treatments reducing higher-order aberrations, primarily deployed in premium orthokeratology portfolios.
Volume concentrates in Peripheral Defocus. Margin accumulates in Wavefront-guided platforms.
Application:
Customer type stratification reflects divergent compliance capabilities, with school-age wearers requiring parental mediation and young professionals self-directing purchasing decisions.
- Children & Adolescents:Primary target population for myopia intervention, with China's 180 million student screening pool generating direct clinical referrals. Parental purchasing authority and morning lens handling supervision requirements favor spectacle or multifocal soft lens alternatives in urban Chinese households.
- School-Age Wearers:Distinct segment with autonomous compliance capacity and daytime wear preference, expanding most quickly in China's tier-one cities through hospital-affiliated optical center channels.
- Adults:Late-intervention candidates with established myopia progression, typically presenting at specialty centers in Seoul and Taipei.
- Young Professionals:Digitally native segment with screen-time exposure concerns, self-directing toward daytime wearable alternatives through direct-to-clinic platforms.
Regulatory focus centers on Children & Adolescents. Commercial momentum favors School-Age Wearers.
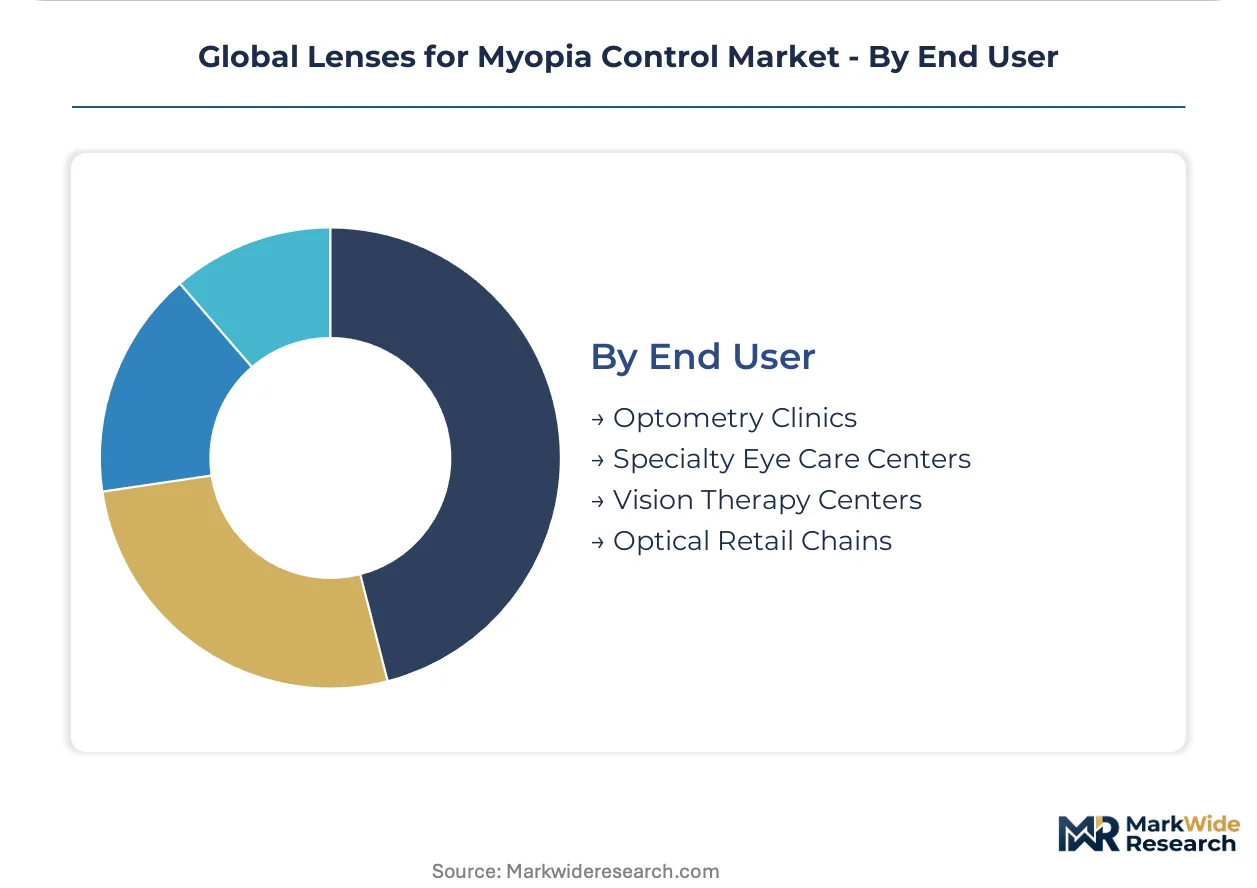
End User:
Distribution channel configuration determines margin extraction, with manufacturer-authorized fitting networks bypassing optical retail markups in China's tier-two cities.
- Optometry Clinics:Primary fitting sites for orthokeratology protocols, concentrated in Shanghai, Beijing, and Guangzhou where China's school-based screening programs direct referrals. Corneal topography technician scarcity constrains expansion pace in emerging markets.
- Specialty Eye Care Centers:Premium service tier with wavefront-guided customization capabilities and AI-integrated design workflows, commanding highest margins in Tokyo and Singapore.
- Vision Therapy Centers:Rehabilitation-focused facilities with limited myopia control lens penetration, primarily serving post-surgical or amblyopia cases.
- Optical Retail Chains:Mass-market channel for spectacle lens substitution and entry-level multifocal soft lenses, with EssilorLuxottica controlling access across Western Europe.
Clinical value pools concentrate in Optometry Clinics. Margin premiums accumulate in Specialty Eye Care Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors global manufacturing capacity for fluorosilicone acrylate monomers and orthokeratology lens finishing, with Shanghai pediatric optometry clinics processing referrals from school-based screening programs covering 180 million students nationwide.
China
China's Ministry of Education mandates annual myopia testing for students, generating direct clinical referrals to Shanghai, Beijing, and Guangzhou optometry centers. NMPA medical device reclassification tightens quality benchmarks while compressing approval timelines for orthokeratology lenses. Yangtze River Delta polymer suppliers are consolidating to meet dual-carbon manufacturing audits under MEE environmental compliance timelines.
United States
FDA Class III device pathways for orthokeratology lenses extend commercialization timelines versus multifocal soft lens 510(k) clearances, filtering market entry for foreign manufacturers. Pediatric optometry practices in California and Texas concentrate fitting volume for overnight corneal reshaping protocols. CooperVision leverages captive manufacturing networks across Costa Rica and domestic facilities to sustain MiSight portfolio supply continuity.
Japan
HOYA Corporation anchors orthokeratology lens production through in-house toric design capabilities and direct distribution channels serving Tokyo specialty eye care centers. METI industrial policy supports precision optical manufacturing clusters in the Chubu region. Osaka and Nagoya pediatric practices adopt wavefront-guided topography systems at twice the rate of general ophthalmology clinics.
South Korea
Seoul pediatric optometry clinics drive adoption of automated corneal mapping platforms that compress fitting appointment duration from 90 minutes to 35 minutes. MFDS medical device regulations align with international standards while maintaining stringent post-market surveillance for high-Dk/t contact lenses. Busan-Ulsan industrial corridors host polymer synthesis facilities supplying regional lathe-cutting manufacturers.
Germany
EU MDR post-market surveillance obligations under Medical Device Regulation 2017/745 filter smaller European competitors and consolidate shelf space for compliant manufacturers. ZEISS and EssilorLuxottica control retail channel access across Western Europe through spectacle lens substitution strategies. Bavarian precision optics clusters support R&D investment in peripheral defocus technology for myopia progression management.
Global Lenses for Myopia Control Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue wavefront-guided customization and direct-to-clinic distribution platforms. Market structure reflects consolidation around vertically integrated polymer suppliers and specialized toric design capabilities, with three strategic archetypes dominating: captive manufacturers with backward integration into monomer synthesis, licensed distributors of imported orthokeratology portfolios, and spectacle lens incumbents leveraging retail channel control. Competitive moves concentrate on M&A activity targeting AI-driven lens design software and strategic partnerships with hospital-affiliated optical centers.
Within the captive manufacturing tier, CooperVision and HOYA Corporation exemplify archetypes built on in-house production networks and direct distribution control. EssilorLuxottica occupies a position representing spectacle lens substitution strategies that compete for price-sensitive parents unwilling to pursue contact lens fitting protocols. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning without requiring equivalent strategic moves across all market participants.
| Leading Market Players |
|---|
| CooperVision |
| Alpha Corporation |
| HOYA Corporation |
| Brighten Optix |
| EUCLID |
| ZEISS |
| Ovctek |
| Lucid Korea |
| EssilorLuxottica |
| Others |
Supply & Pricing Matrix
Captive manufacturing networks across Costa Rica and the United States anchor CooperVision's supply position and pricing power for silicone hydrogel multifocal portfolios, while HOYA Corporation's in-house toric design capabilities in Japan command premium positioning for orthokeratology lenses. This integration choice separates volume-accessible tiers from margin-rich customization segments.
Pricing Analysis
Fluorosilicone acrylate monomer costs pass through directly to orthokeratology lens pricing, with three Japanese and Korean polymer suppliers controlling high-Dk/t raw material output. Pricing stratifies across premium wavefront-guided customization, standard peripheral defocus platforms, and economy single-vision corrections based on certification tier and customization level. Cost compression in the standard tier intensifies because spectacle lens substitution from EssilorLuxottica's Stellest portfolio captures price-sensitive parents. School-age wearers in China's tier-one cities show least price sensitivity for daytime wearable alternatives, while tier-two city households exhibit highest elasticity.
Supply Chain Analysis
Corneal topography technician scarcity in Shanghai, Beijing, and Guangzhou constrains lathe-cutting capacity expansion despite polymer feedstock availability from Yangtze River Delta suppliers. Manufacturing concentrates in China, Japan, and South Korea, with Busan-Ulsan industrial corridors hosting polymer synthesis facilities and Chubu region precision optics clusters supporting finishing operations. Supply chains draw from fluorosilicone acrylate monomers, silicone hydrogel polymers, and AI-driven lens design software. Single-source vulnerability runs through Japanese toric design patent holders constraining independent product development. Distribution runs through manufacturer-authorized fitting networks bypassing optical retail markups in China's tier-two cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory momentum into demand generation, with China's Ministry of Education screening mandates for 180 million students creating structural referral volume to pediatric optometry clinics.
For Market Incumbents: Deploy backward integration into polymer synthesis to secure fluorosilicone acrylate supply continuity against Japanese and Korean supplier concentration. Accelerate in-house toric design capabilities to meet NMPA quality benchmark tightening. Spectacle lens substitution from EssilorLuxottica's retail channel control threatens contact lens fitting protocol adoption among price-sensitive parents. For New Entrants and Emerging Players: Hospital-affiliated optical centers in China's tier-two cities represent the most penetrable channel partner type for direct-to-clinic distribution platforms. India's underpenetrated pediatric segment offers white-space access through BIS certification pathways as domestic myopia prevalence climbs in Bengaluru and Hyderabad school districts. Wavefront-guided customization software partnerships with Seoul and Taipei pediatric practices enable margin-premium positioning without captive manufacturing investment. For Investors and Strategic Acquirers: Roll-up economics work for AI-driven lens design software specialists because corneal topography automation compresses fitting appointment duration and expands addressable clinic throughput. Five-to-ten year viability hinges on regulatory divergence between FDA Class III pathways and NMPA medical device catalog revisions consolidating compliant manufacturer market share. Monitor EU MDR post-market surveillance obligation compliance rates as inflection indicator for European shelf space consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Captive supply of high-Dk/t fluorosilicone acrylate monomers reduces input cost volatility from Japanese and Korean supplier concentration. |
| AI-Driven Lens Design Software Acquisition | Corneal topography automation platforms compress fitting appointment duration from 90 minutes to 35 minutes in Seoul and Taipei clinics. |
| Direct-to-Clinic Distribution Platform Launch | Manufacturer-authorized fitting networks bypass optical retail markups and capture margin in China's tier-two cities. |
| NMPA Dual-Carbon Manufacturing Compliance Investment | MEE environmental audit readiness accelerates facility commissioning for domestic orthokeratology lens production. |
| Wavefront-Guided Customization Capability Buildout | Tokyo and Singapore specialty eye care centers command margin premiums for fully customized optical profiles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pediatric optometrists, polymer procurement leads at lens manufacturers, regulatory affairs specialists at notified bodies, and hospital purchasing committee members with secondary validation. FDA 510(k) and PMA filings, NMPA medical device registration databases, EU MDR notified body certificates, and customs records for fluorosilicone acrylate monomer trade flows anchored supply-side modeling. Bottom-up clinic referral volume estimates from China's Ministry of Education screening mandates triangulated against top-down manufacturer shipment data.
Historical reference periods spanning pre-pandemic baseline through post-regulatory-reclassification intervals anchored the forecast window across the analysis window. Segmentation dimensions modeled include product type, technology tier, application age group, and end-user channel configuration. CAGRs derived from fitted growth curves applied to addressable screening population expansion and lens replacement frequency assumptions. Industry-specific inputs incorporated NMPA approval timeline compression effects and EU MDR post-market surveillance cost burdens.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to corneal topography technician training program output and dual-carbon manufacturing audit enforcement intensity. Forecasts reflect documented assumptions about screening mandate continuity and polymer supplier concentration stability. Practitioners should monitor NMPA medical device catalog revision timing and EU MDR annual safety report submission rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cerebral Somatic Oximeters Market
Medical Devices
Surgical Display Market
Medical Devices
Global on-Body Injectors Market
Medical Devices
Global Centesis Catheters Market
Medical Devices
Power Smart Bed Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Zygomatic and Pterygoid Implants Market
Medical Devices
Cochlear Implant Systems Market
Medical Devices
Silastic Implant Market
Medical Devices
Self-Destructing Syringe Market
Medical Devices
Global Electronic Drug Delivery Systems Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
Morcellators Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
IV Equipment Market