
 Ophthalmic Suspension Market | 2026-2036
Ophthalmic Suspension Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Suspension Market Outlook
Single-use vial-to-multidose bottle conversion is consolidating as the dominant packaging configuration shift, reshaping how hospitals and retail pharmacies evaluate unit economics and sterility assurance. Novartis leverages its manufacturing scale to supply preservative-free multidose systems across European and North American distribution channels. Bausch Health anchors its position through vertical control over active pharmaceutical ingredient sourcing for corticosteroid suspensions. Alcon competes by extending its reach into combination antibiotic-steroid formulations that reduce patient drop burden.
Ophthalmic suspension denotes a liquid dosage form wherein insoluble drug particles remain dispersed in an aqueous or oil-based vehicle, typically requiring particle size control below 10 micrometers to ensure uniform dosing and minimize ocular irritation; these formulations serve primarily to deliver anti-infective, anti-inflammatory, or hypotensive agents to the anterior segment or vitreous cavity. Corticosteroid suspensions command the deepest margin pools due to chronic demand from post-surgical inflammation management and uveitis protocols, while topical delivery dominates volume because of patient familiarity and minimal invasiveness despite lower per-dose reimbursement. Intravitreal administration represents the fastest-growing delivery mode as sustained-release suspensions for macular edema and retinal vascular disease gain specialist adoption.
The FDA enforces bioequivalence standards for generic ophthalmic suspensions through rigorous in vitro and clinical endpoint studies, while the EMA's MDR framework imposes stricter device-drug combination scrutiny on preservative delivery systems. India's CDSCO has tightened import registration requirements for ophthalmic formulations, redirecting multinational supply chain investments toward local contract manufacturing. Stakeholders must monitor how evolving preservative safety thresholds and reimbursement compression on generic corticosteroids reshape portfolio prioritization decisions across developed and emerging markets.
Market Dynamics
Preservative-free multidose delivery systems are compressing unit economics for hospital formularies while tightening sterility assurance protocols across ophthalmology clinics. This packaging transition is forcing API suppliers and contract manufacturers to revalidate production lines around particle size control below 10 micrometers.
Growth Catalysts
- MDR Device-Drug Scrutiny:The EMA's Medical Device Regulation framework is accelerating compliance investments in preservative delivery systems, pushing European manufacturers toward integrated quality management systems that streamline cross-border distribution.
- Post-Surgical Inflammation Protocols:Chronic corticosteroid demand from cataract and vitreoretinal surgery recovery is expanding hospital pharmacy procurement of suspension formulations with extended dosing intervals.
- Intravitreal Delivery Mode:Sustained-release suspensions for macular edema are displacing frequent intravitreal injections in retinal specialist practices, concentrating adoption among academic medical centers with compounding pharmacy capabilities.
Market Restraints
- API Supply Concentration:Corticosteroid active pharmaceutical ingredient production concentrates among Indian and Chinese bulk manufacturers, exposing finished dose formulators to import registration delays under CDSCO's tightened foreign supplier verification requirements.
- Bioequivalence Submission Burden:The FDA's updated guidance on generic ophthalmic suspensions mandates rigorous in vitro and clinical endpoint studies, extending ANDA review timelines and elevating development costs for new entrants.
- Preservative Safety Threshold Compression:Benzalkonium chloride concentration limits in multidose formulations are forcing reformulation investments that erode margin structures on established generic products.
Strategic Opportunities
- Medicare Outpatient Reimbursement Tailwind:United States reimbursement policies favoring office-based ophthalmic procedures are expanding addressable volume for preservative-free multidose systems in ambulatory surgery centers.
- Combination Formulation White Space:Antibiotic-steroid combination suspensions that reduce patient drop burden represent an underdeveloped category with limited generic competition in European markets.
- Local Contract Manufacturing Pivot:CDSCO's import registration redirection is creating partnership opportunities for multinational sponsors with Indian CMOs possessing sterile suspension filling capabilities and WHO-GMP certification.
Industry Challenges
- Sterile Manufacturing Skill Scarcity:Aseptic processing technicians with ophthalmic suspension-specific particle size validation experience command premium compensation, constraining capacity expansion timelines for mid-scale CMOs.
- Legacy Equipment Integration:Converting single-use vial lines to multidose bottle configurations requires substantial capital redeployment and process revalidation, delaying portfolio transitions for manufacturers with depreciated filling assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Suspension Market |
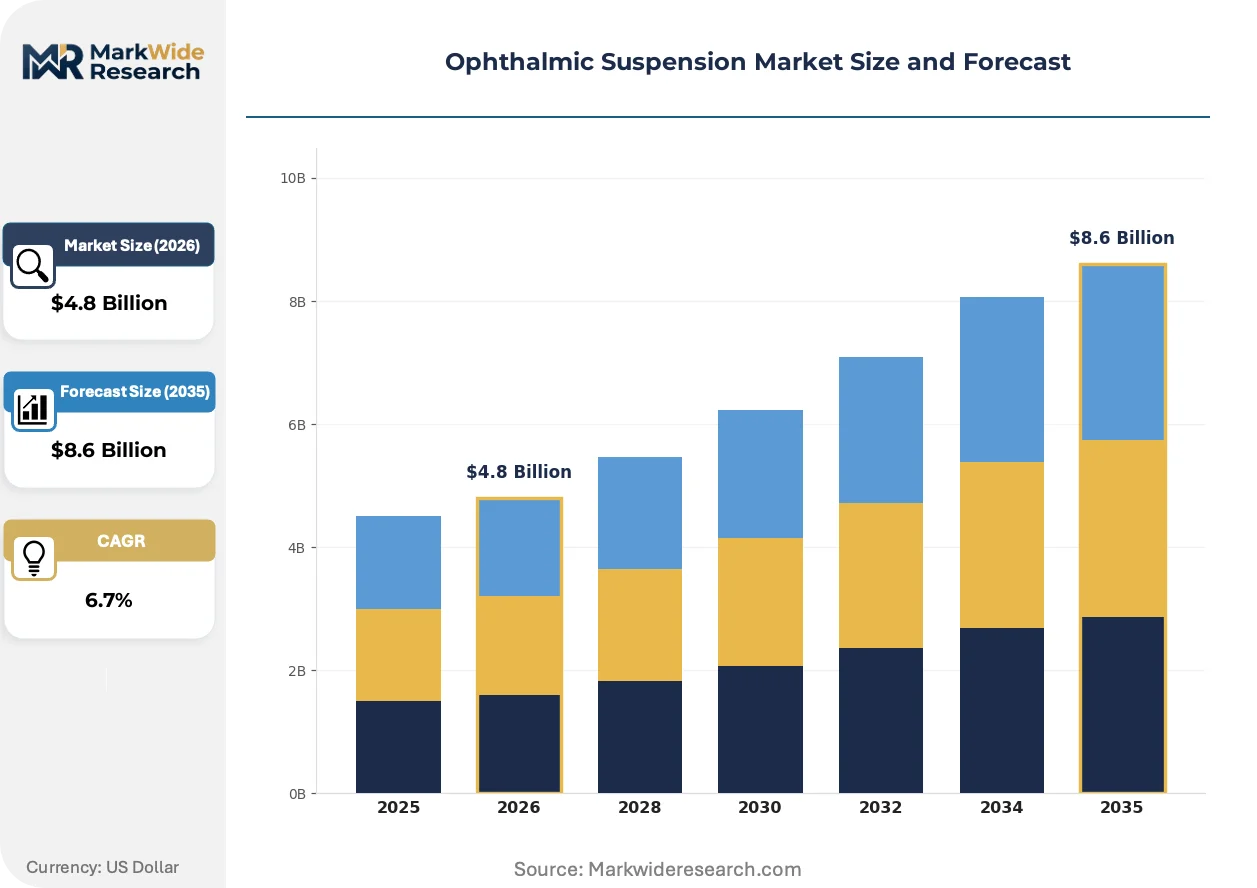
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotic, Antiviral, Corticosteroid, Non-Steroidal Anti-Inflammatory Therapy Area: Glaucoma, Allergies, Infections, Inflammation Delivery Mode: Topical, Intravitreal, Periocular, Subconjunctival End User: Hospitals, Clinics, Ophthalmology Centers, Homecare |
| Companies Covered | Allergan, Bausch Health, Novartis, Santen Pharmaceutical, Alcon, Pfizer, Merck, AbbVie, Ocular Therapeutix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Suspension Market Strategic Shifts
Novel excipient technologies are enabling thermosensitive gelation systems that extend ocular surface residence time without compromising visual clarity. These advances are compressing dosing frequency requirements and reshaping competitive positioning around patient adherence metrics.
Nanocrystal suspension technology is modularizing drug delivery architecture by enabling high-concentration, low-volume formulations that reduce particle aggregation risk during shelf storage. Retinal specialists in German and French academic hospitals are adopting these systems for sustained-release intravitreal applications. The structural consequence is compressing development timelines for follow-on biologics while elevating barrier-to-entry for conventional micronized suspension generic sponsors.
The FDA's tightened bioequivalence guidance for ophthalmic suspensions is forcing generic sponsors toward clinical endpoint studies rather than pharmacokinetic substitution. This regulatory friction is extending ANDA approval timelines and compressing first-mover advantage windows for Paragraph IV challengers. Complex corticosteroid suspensions with particle size distributions below 5 micrometers face the steepest compliance elevation, concentrating development resources among sponsors with in-house sterility assurance expertise.
Hospital pharmacy procurement committees are consolidating supplier relationships around vendors offering integrated sterility testing and stability validation documentation. This concentration is displacing fragmented multi-source purchasing patterns that predominated in retail pharmacy channels. The shift is most visible in United States integrated delivery networks where formulary standardization across ambulatory and inpatient settings drives volume commitments to single manufacturing platforms.
Ophthalmic Suspension Market Segmentation
Ophthalmic suspension formulations fragment across therapeutic intent, anatomical target, and care setting. Supply concentration in corticosteroid APIs and sterility-assured multidose packaging creates divergent margin structures across these categories.
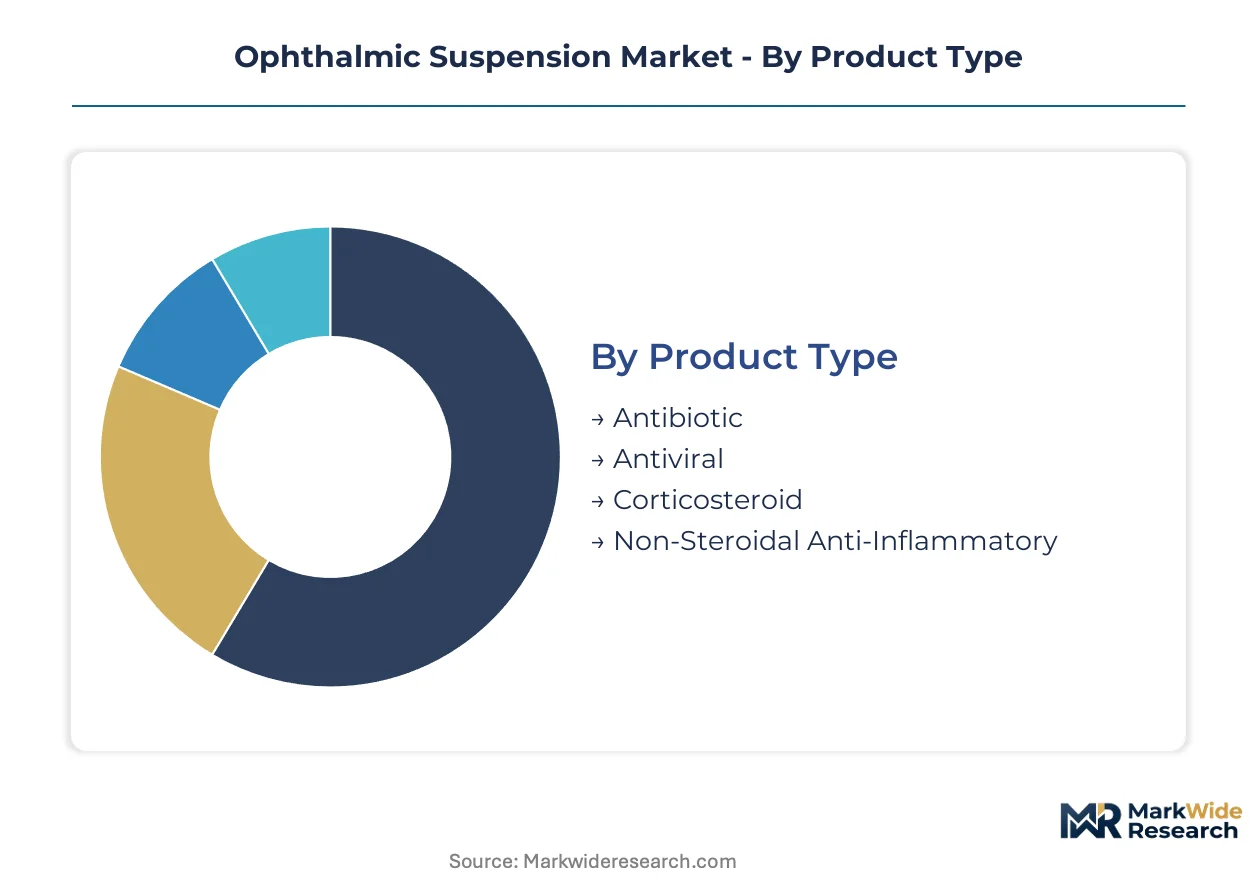
Product Type:
API sourcing geography and formulation complexity concentrate manufacturing capability among distinct supplier tiers.
- Corticosteroid:Suspensions of prednisolone acetate and dexamethasone require particle size distributions below 10 micrometers to prevent ocular irritation. Hospital pharmacies in the United States prioritize these formulations for post-surgical inflammation protocols, though benzalkonium chloride reformulation costs are compressing generic margins.
- Antibiotic:Tobramycin and ciprofloxacin suspensions dominate infection management in ambulatory settings. European EMA MDR compliance investments are pushing preservative-free multidose adoption faster here than in other categories, concentrating procurement among integrated delivery networks with formulary standardization mandates.
- Non-Steroidal Anti-Inflammatory:Ketorolac tromethamine suspensions serve acute pain management following refractive surgery.
- Antiviral:Ganciclovir and foscarnet suspensions address herpetic keratitis in immunocompromised patient populations.
Today's leader: Corticosteroid. Tomorrow's challenger: Antibiotic.
Therapy Area:
Reimbursement intensity and procedure volume create tiered addressable markets across anterior and posterior segment indications.
- Inflammation:Uveitis and post-operative protocols drive chronic dosing regimens. Medicare outpatient reimbursement policies in the United States favor office-based administration, expanding volume for preservative-free multidose systems in academic medical centers and ambulatory surgery centers.
- Infections:Bacterial keratitis and conjunctivitis demand rapid therapeutic onset. India's CDSCO tightened import registration requirements are redirecting multinational supply chains toward local contract manufacturing partnerships with WHO-GMP certified facilities.
- Glaucoma:Intraocular pressure management via suspensions competes with solution and implant alternatives.
- Allergies:Seasonal allergic conjunctivitis applications concentrate in retail pharmacy channels with lower per-dose reimbursement.
Inflammation commands the deepest margin pools. Infections present the steepest regulatory friction for new entrants.
Delivery Mode:
Technical sophistication and sterility assurance requirements stratify manufacturing capability across administration routes.
- Intravitreal:Sustained-release suspensions for macular edema and retinal vascular disease displace frequent injections in German and French academic hospitals. These formulations demand compounding pharmacy partnerships and particle aggregation controls that elevate barrier-to-entry for conventional generic sponsors.
- Topical:Eye drop suspensions dominate patient familiarity and prescription volume. The FDA's tightened bioequivalence guidance mandates clinical endpoint studies rather than pharmacokinetic substitution, extending ANDA timelines for new topical entrants.
- Periocular:Orbital floor and retrobulbar injections serve posterior segment access without vitreous cavity penetration.
- Subconjunctival:Depot formulations beneath the conjunctival sac enable prolonged anti-inflammatory effect.
Topical delivery anchors current volume. Intravitreal administration is climbing the fastest as sustained-release technology matures.
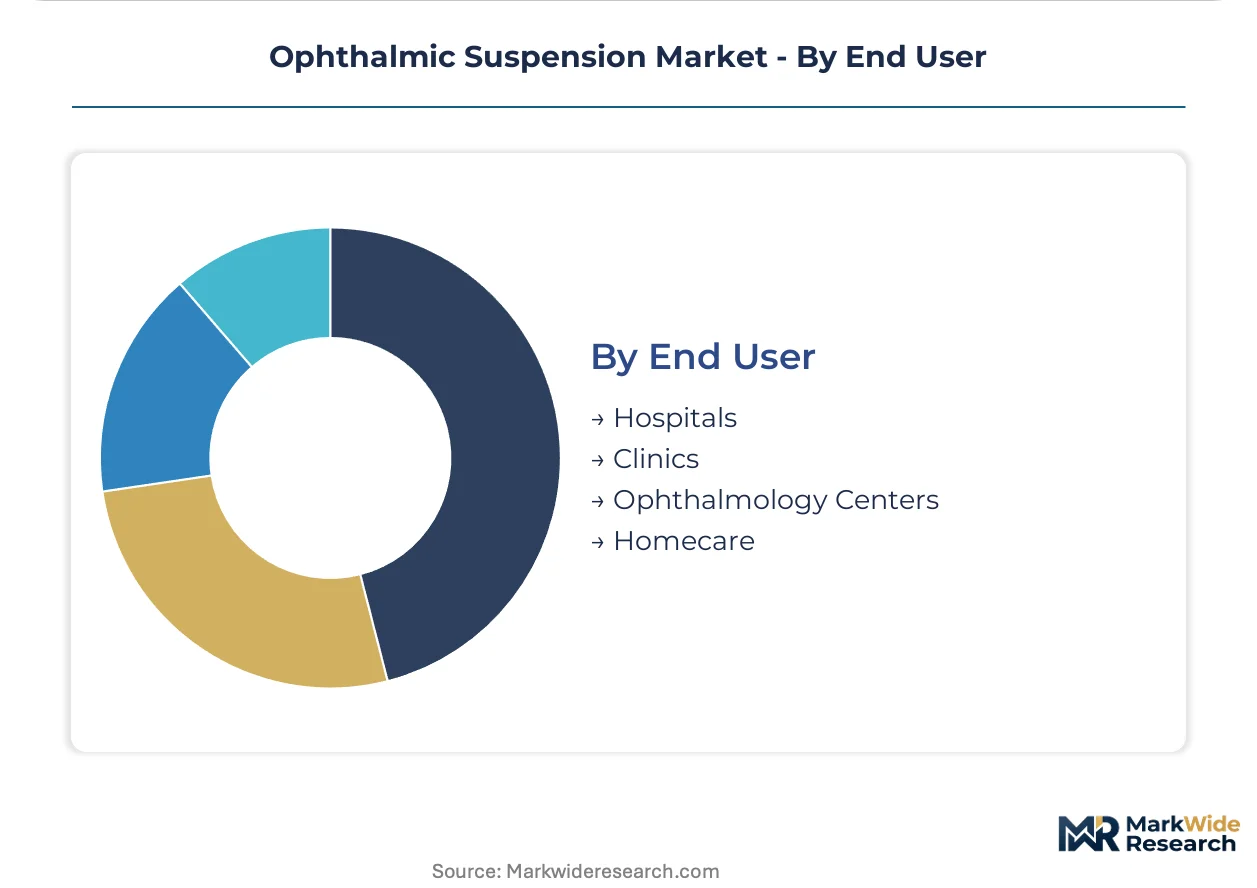
End User:
Procurement centralization and sterility documentation requirements are consolidating supplier relationships across care settings.
- Hospitals:Integrated delivery networks in the United States are standardizing formularies across inpatient and ambulatory settings, driving volume commitments to single manufacturing platforms with bundled sterility testing and stability validation documentation.
- Ophthalmology Centers:Specialized retinal and cataract practices concentrate adoption of intravitreal sustained-release suspensions. These facilities prioritize vendors offering preservative-free multidose systems with extended dosing intervals to reduce patient visit frequency.
- Clinics:General ophthalmology and optometry practices represent fragmented demand with price-sensitive procurement.
- Homecare:Self-administered topical suspensions for chronic conditions require patient-friendly packaging and adherence support.
Hospitals concentrate purchasing power through formulary consolidation. Ophthalmology centers drive adoption of highest-margin delivery innovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ophthalmic suspension manufacturing traces its commercial scale to post-war pharmaceutical development in the United States and Switzerland, where sterile formulation expertise first consolidated around corticosteroid chemistry. That foundation now distributes across distinct national regulatory environments.
United States
Medicare outpatient reimbursement policies favor office-based ophthalmic procedures, expanding procurement of preservative-free multidose systems in ambulatory surgery centers. The FDA's tightened bioequivalence guidance for generic suspensions extends ANDA review timelines and elevates development costs. Boston and Research Triangle Park host specialist CMOs with particle size validation capabilities for intravitreal formulations.
Germany
Academic medical centers in Berlin and Munich drive adoption of sustained-release intravitreal suspensions for macular edema, displacing frequent injection protocols. The EMA's MDR framework imposes stricter device-drug combination scrutiny on preservative delivery systems. Heidelberg and Freiburg concentrate sterile compounding pharmacy partnerships serving retinal specialist practices.
India
CDSCO tightened import registration requirements redirect multinational supply chains toward local contract manufacturing partnerships with WHO-GMP certified facilities. Mumbai and Hyderabad anchor bulk API production for corticosteroid suspensions, though foreign supplier verification delays now constrain finished dose formulators. Ahmedabad and Bengaluru expand sterile suspension filling capacity for export markets.
Japan
PMDA oversight of ophthalmic combination products maintains elevated barrier-to-entry for generic sponsors, preserving margin structures for originator formulations. Tokyo and Osaka metropolitan areas concentrate demand for preservative-free multidose systems in aging patient populations. Nagoya hosts specialist manufacturers with thermosensitive gelation excipient capabilities.
Switzerland
Swissmedic's precision around sterile manufacturing standards attracts sponsors seeking regulatory credibility for European market entry. Basel and Zurich anchor formulation development for high-value corticosteroid suspensions with particle distributions below 5 micrometers. The Lake Geneva region concentrates quality management system consultancies serving MDR compliance investments.
Ophthalmic Suspension Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation complexity and sterility assurance capabilities. The market structures around three tiers: multinational pharmaceutical conglomerates with integrated API-to-dose vertical control, mid-scale specialists with CMO partnerships for sterile filling, and regional generic sponsors concentrated on topical antibiotic suspensions. Competitive moves center on preservative-free multidose technology licensing and backward integration into particle size reduction equipment.
Within the conglomerate tier, Novartis and Alcon exemplify scale-driven positions spanning European and North American distribution, while Bausch Health occupies a distinct archetype through upstream control over corticosteroid API sourcing. These anchors demonstrate how manufacturing depth and regulatory navigation capability separate sustainable margin capture from commodity pricing pressure.
| Leading Market Players |
|---|
| Allergan |
| Bausch Health |
| Novartis |
| Santen Pharmaceutical |
| Alcon |
| Pfizer |
| Merck |
| AbbVie |
| Ocular Therapeutix |
| Others |
Value Chain & Pricing Dynamics
Hospital pharmacy procurement committees in United States integrated delivery networks concentrate purchasing volume around single manufacturing platforms, compressing price negotiation leverage for mid-scale generic sponsors and elevating contract-based pricing with bundled sterility documentation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates preservative-free multidose corticosteroid suspensions from benzalkonium chloride-containing generics and commodity antibiotic formulations. Price differentiation rests on FDA bioequivalence certification tier and particle size validation documentation, with premium tiers commanding advantage from in-house sterility assurance capabilities. Cost compression in generic corticosteroid segments is intensifying because benzalkonium chloride reformulation investments erode margin structures. Retail pharmacy channels exhibit highest price sensitivity, while academic medical centers prioritize sterility documentation over per-unit cost.
Supply Chain Analysis
Aseptic processing technicians with ophthalmic suspension-specific particle size validation experience command premium compensation in Mumbai and Hyderabad, constraining capacity expansion timelines for sterile filling operations. Bulk API production for corticosteroid suspensions concentrates in India and China, with finished dose formulators drawing from Chinese chemical intermediates and Indian bulk manufacturing. Single-source vulnerability runs through concentrated corticosteroid API supply from Indian bulk manufacturers facing CDSCO foreign supplier verification delays. Distribution runs through hospital pharmacy procurement committees consolidating supplier relationships around integrated sterility testing platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ophthalmic suspension markets compound steadily through chronic post-surgical inflammation protocols that generate recurring corticosteroid demand across aging patient populations.
For Market Incumbents: Extend manufacturing scale advantages into preservative-free multidose technology licensing partnerships with European and North American distribution channels. Backward integration into particle size reduction equipment anchors margin capture against emerging generic sponsors facing FDA bioequivalence submission burdens. Prioritize sterility assurance expertise accumulation to defend positioning as hospital procurement committees consolidate supplier relationships. For New Entrants and Emerging Players: CDSCO's tightened import registration requirements in India open a window for local contract manufacturing partnerships with WHO-GMP certified facilities serving multinational supply chain redirection. Target antibiotic-steroid combination suspensions in European markets where EMA MDR compliance investments have limited generic competition penetration. Lead with preservative-free multidose formulation capabilities to differentiate from commodity topical antibiotic sponsors. For Investors and Strategic Acquirers: Specialist pharmaceutical conglomerates with integrated API-to-dose vertical control are the most active acquirer in this space, seeking sterile manufacturing capability additions. Five-to-ten year viability hinges on sustained-release intravitreal suspension technology maturation and Medicare outpatient reimbursement policy stability. Monitor FDA ANDA approval timeline extensions for generic ophthalmic suspensions as inflection indicator for competitive intensity shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Multidose Technology Licensing | EMA MDR compliance investments accelerate European hospital pharmacy adoption of integrated delivery systems. |
| Particle Size Validation Capability Expansion | FDA bioequivalence guidance tightens submission standards below 10 micrometer control thresholds. |
| Local Contract Manufacturing Partnerships | CDSCO import registration redirection creates WHO-GMP certified capacity access in Indian pharmaceutical clusters. |
| Combination Formulation Pipeline Development | Antibiotic-steroid suspensions reduce patient drop burden in post-surgical protocols with limited generic competition. |
| Sustained-Release Intravitreal Platform Investment | German and French academic medical centers displace frequent injection protocols with extended dosing interval systems. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors alongside secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up prescription volume modeling and top-down manufacturer revenue triangulation anchor analytical integrity.
Granularity-level framing applies across product type, therapy area, delivery mode, and end user dimensions with regional regulatory cluster differentiation. CAGRs derive from prescription volume trajectory analysis and pricing evolution assumptions across the projection horizon. Forecast inputs incorporate Medicare reimbursement policy stability assumptions and CDSCO import registration timeline projections.
Revisions become necessary when FDA bioequivalence guidance enforcement intensity shifts, EMA MDR compliance timeline extensions materialize, or CDSCO foreign supplier verification delays exceed baseline assumptions. Forecasts reflect documented assumptions around sterility assurance capability scarcity and preservative safety threshold evolution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Eye Infections Treatment Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Vitreous Detachment Treatment Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Ophthalmic Femtosecond Lasers Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Non-Infectious Macular Edema Treatment Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
North America Vision Care Market
Ophthalmology
Age Related Vision Dysfunction Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Vernal Keratoconjunctivitis Treatment Market
Ophthalmology
Global Ophthalmology PACS Market
Ophthalmology
Age-Related Macular Degeneration Market