
 Choroidal Neovascularization Market | 2026-2036
Choroidal Neovascularization Market Size, Share, and Industry Trends Forecast 2026-2036
Choroidal Neovascularization Market Intelligence
Buyer concentration among retinal specialty clinics is realigning as hospital ophthalmology departments fragment into standalone ambulatory surgical centers. F. Hoffmann-La Roche anchors its position through sustained dominance in ranibizumab supply chains across European markets. Regeneron Pharmaceuticals differentiates via Eylea manufacturing scale and channel control in North American distribution networks. Novartis competes through geographic diversification and leverages its bevacizumab portfolio for off-label CNV applications.
Choroidal neovascularization describes the pathological growth of new blood vessels from the choroid through Bruch's membrane into the subretinal space, typically triggered by vascular endothelial growth factor dysregulation in age-related macular degeneration and pathological myopia. Anti-VEGF agents represent the dominant therapeutic class where margin pools concentrate due to recurring intravitreal injection protocols and chronic disease management requirements. Gene therapy within the technology dimension shows the fastest structural expansion as sustained expression platforms promise reduced injection frequency compared to monoclonal antibody maintenance regimens. Ophthalmology clinics capture the largest end-user share while home care delivery remains nascent pending formulation stability advances.
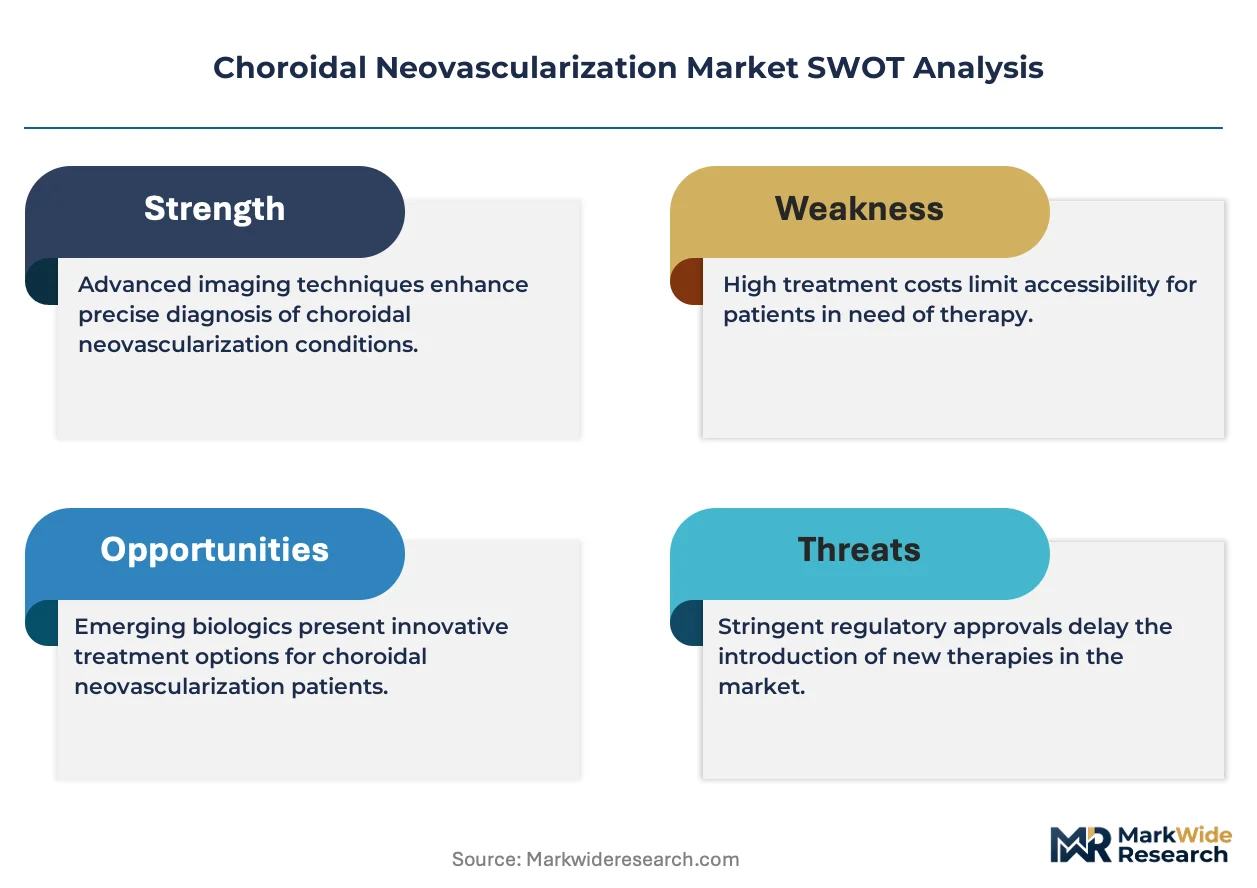
FDA ophthalmic biologics guidance and EMA MDR requirements shape product standards for intravitreal delivery systems and sterility assurance. The EU AI Act and HIPAA compliance frameworks increasingly govern diagnostic imaging workflows that identify CNV progression and trigger treatment authorization. Stakeholders must monitor reimbursement policy shifts for combination therapy protocols and gene therapy platforms as payors reassess value-based contracting models for chronic retinal diseases.
Market Dynamics
The transition from monthly intravitreal injection regimens toward sustained-release and gene therapy platforms is compressing treatment frequency expectations and forcing reinvention of clinic workflows and reimbursement structures across ophthalmology practices.
Growth Catalysts
- EMA Accelerated Assessment Pathway:The European regulator's fast-track designation for ophthalmic biologics shortens time-to-market for novel anti-VEGF agents, incentivizing pipeline investment from biotech developers targeting retinal diseases.
- Retinal Specialty Clinic Expansion:Standalone ambulatory surgical centers are proliferating in Germany, Japan, and the United States, creating dedicated infrastructure for high-volume intravitreal injection protocols and chronic disease management.
- Gene Therapy Manufacturing Scale-Up:Viral vector production capacity expansion by contract development organizations is reducing cost-per-dose for sustained-expression platforms, enabling clinical trial enrollment beyond academic medical centers.
Market Restraints
- Reimbursement Compression:Medicare's 2024 physician fee schedule adjustments for intravitreal injections in the United States are narrowing per-procedure margins for retina specialists, constraining clinic expansion plans.
- Supply Concentration in Viral Vectors:AAV manufacturing capacity concentrates among three contract manufacturers globally, creating queue risk for gene therapy developers awaiting GMP batch release.
- Technical Limitation of Subretinal Delivery:Vitrectomy-dependent administration of gene therapies limits addressable patient populations to surgical centers with specialized equipment, excluding general ophthalmology practices.
Strategic Opportunities
- Underpenetrated Pathological Myopia Segment:Japan's high prevalence of high myopia creates a concentrated addressable population for anti-VEGF protocols beyond age-related macular degeneration, with PMDA approval pathways increasingly accommodating Asian epidemiology data.
- Home Care Formulation Innovation:Stable anti-VEGF formulations suitable for subconjunctival or topical administration would unlock pharmacy channel distribution, bypassing clinic-based injection requirements entirely.
- EU AI Act Diagnostic Integration:Regulatory clarity on machine-learning algorithms for CNV detection in optical coherence tomography workflows enables automated treatment authorization systems, reducing specialist bottleneck constraints.
Industry Challenges
- Vitreoretinal Surgeon Training Pipeline:Fellowship positions in the United States and Germany are failing to keep pace with clinic expansion, extending patient wait times for initial consultation and treatment initiation.
- Cold Chain Integrity for Biologics:Intravitreal agents require uninterrupted temperature control from manufacturing through compounding pharmacy to point-of-care, with excursion events triggering batch discard and supply disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Choroidal Neovascularization Market |
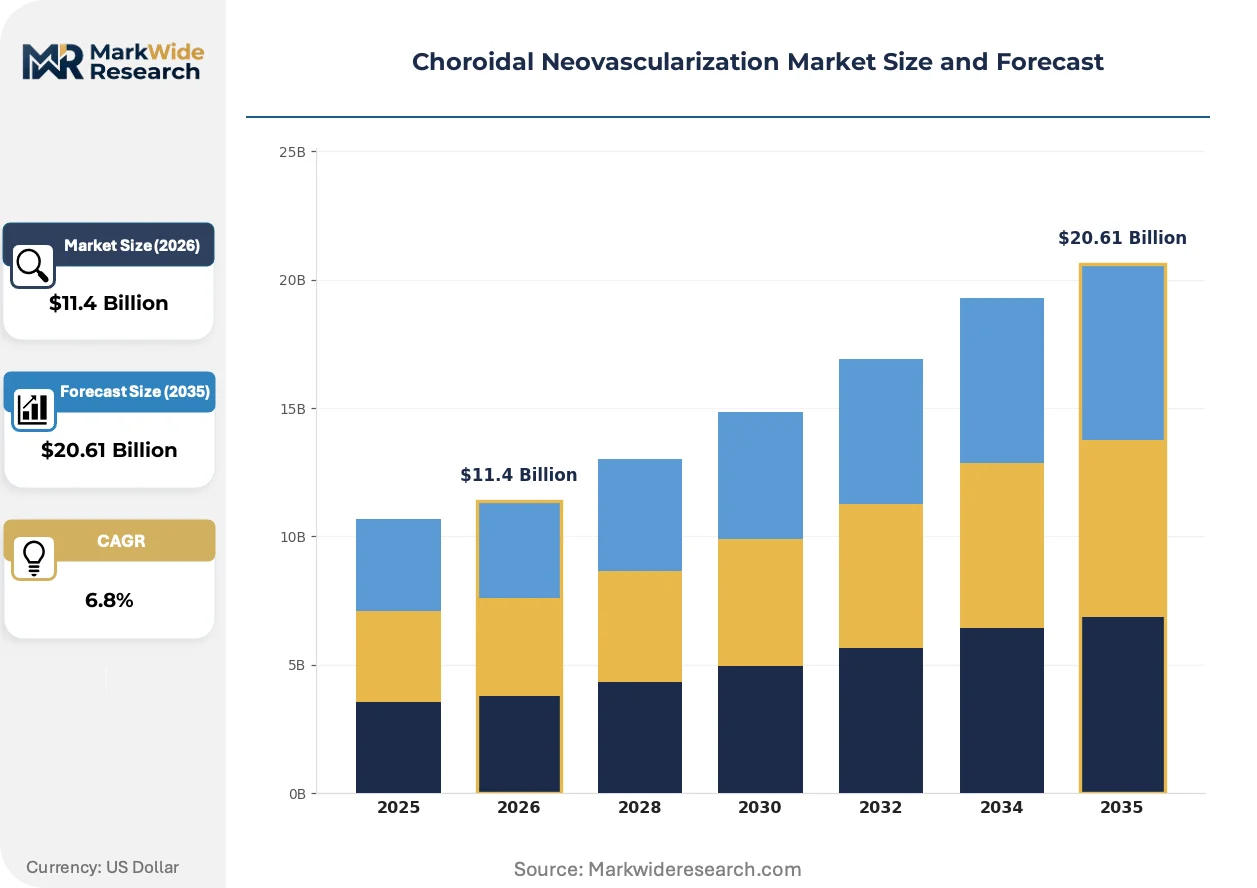
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-VEGF Agents, Corticosteroids, Laser Therapy, Combination Therapy Technology: Monoclonal Antibodies, Gene Therapy, Photodynamic Therapy, Surgery End User: Ophthalmology Clinics, Hospitals, Home Care, Research Institutes Delivery Mode: Intravitreal Injection, Oral, Topical, Dose-Dependent |
| Companies Covered | Pfizer, F. Hoffmann-La Roche, Novartis, Bayer, Regeneron Pharmaceuticals, Gilead Sciences, AstraZeneca, Sanwa Kagaku Kenkyusho, Bausch Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Choroidal Neovascularization Market Strategic Shifts & Innovations
Gene therapy platforms and AI-augmented diagnostic workflows are converging to redefine treatment protocols, shifting value capture from recurring pharmaceutical sales toward upfront intervention models and software-enabled care coordination.
Sustained-expression gene therapies using AAV5 and AAV8 vectors are decentralizing the economics of chronic retinal disease management by promising multi-year therapeutic effect from single administration. Retina specialists in the United States and Germany are prioritizing clinical trial site qualification for these platforms, anticipating patient volume migration from maintenance injection regimens. The structural consequence is compression of recurring revenue pools for conventional anti-VEGF agents and reallocation of clinic capacity toward surgical intervention and post-gene-therapy monitoring.
The EU AI Act's risk classification framework for medical device software is mandating conformity assessment procedures for OCT-based CNV detection algorithms before market deployment. European ophthalmology equipment manufacturers are restructuring quality management systems to accommodate notified body oversight of machine-learning components. Germany and France are experiencing the most pronounced implementation friction, as their national competent authorities interpret algorithm transparency requirements most stringently, delaying product registration timelines.
Retinal specialty clinics are consolidating purchasing authority through group purchasing organizations, unbundling device procurement from pharmaceutical supply agreements that historically bundled diagnostic equipment with drug volume commitments. Independent practice associations in the United States are negotiating directly with anti-VEGF manufacturers, bypassing hospital system intermediaries. This behavior is most visible in Texas and Florida, where regulatory environments favor standalone ambulatory facility licensing and certificate-of-need restrictions are absent.
Choroidal Neovascularization Market Segmentation
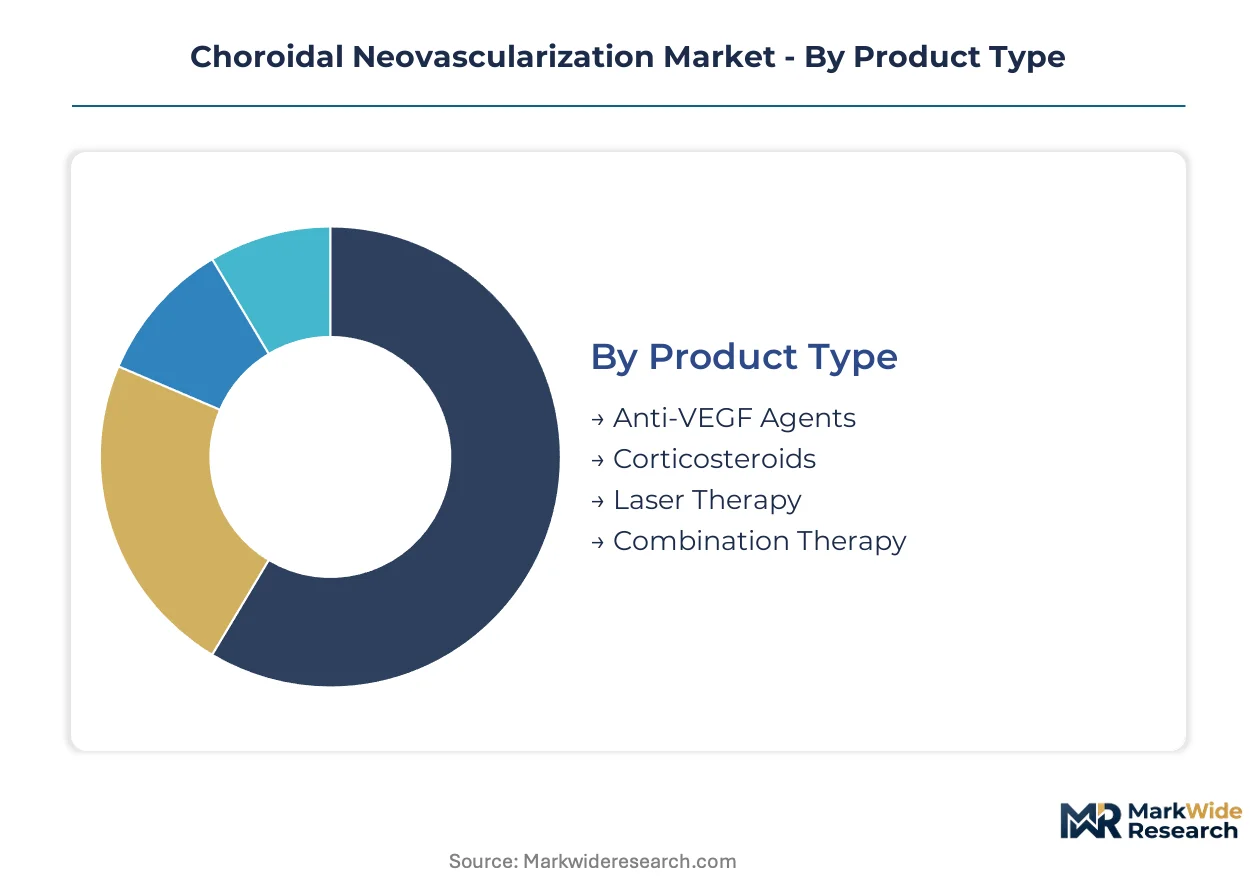
Segmentation in the choroidal neovascularization market reveals how treatment economics fragment across chronic maintenance models versus curative intervention platforms. Understanding these divisions exposes where margin pools concentrate and which delivery innovations threaten incumbent revenue structures.
Product Type:
Volume leadership sits with recurring administration agents, while premium capture gravitates toward one-time intervention platforms promising sustained efficacy.
- Anti-VEGF Agents:Intravitreal monoclonal antibodies and fusion proteins constitute the therapeutic backbone, administered via recurring injection protocols in retina specialist offices across the United States, Germany, and Japan. Medicare reimbursement compression and EMA parallel pathway pricing are narrowing per-procedure margins, forcing clinic consolidation and volume concentration among high-throughput ambulatory surgical centers.
- Gene Therapy:AAV-mediated sustained-expression platforms promise multi-year therapeutic effect from single subretinal administration, commanding premium pricing justified by reduced injection burden. Manufacturing scale constraints and vitrectomy-dependent delivery limit addressable populations to academic medical centers with surgical infrastructure in the United States and European university hospitals.
- Corticosteroids:Intravitreal steroid implants address inflammatory components in selected CNV subtypes, positioned as second-line options where anti-VEGF monotherapy proves insufficient.
- Laser Therapy:Photocoagulation and thermal ablation techniques retain niche application for extrafoveal lesions, declining in share as pharmacologic alternatives improve foveal safety profiles.
- Combination Therapy:Sequential or concurrent anti-VEGF and photodynamic protocols target refractory cases, requiring complex authorization workflows that concentrate in tertiary referral networks.
Today's leader: Anti-VEGF Agents. Tomorrow's challenger: Gene Therapy.
Technology:
Platform maturity separates established manufacturing processes from emerging modalities still navigating regulatory validation and reimbursement negotiation.
- Monoclonal Antibodies:Ranibizumab and aflibercept biosimilars are commoditizing the injection-maintenance segment, with F. Hoffmann-La Roche and Regeneron Pharmaceuticals defending position through manufacturing scale and channel control. FDA ophthalmic biologics guidance and EMA MDR sterility requirements elevate barriers for new entrants.
- Photodynamic Therapy:Verteporfin-based photochemical activation of vascular occlusion retains limited application for polypoidal choroidal vasculopathy subtypes prevalent in Asian populations.
- Surgery:Vitrectomy-dependent subretinal delivery systems enable gene therapy administration but restrict addressable sites to specialized surgical centers with microincision equipment.
- Gene Therapy:Viral vector platforms using AAV5 and AAV8 serotypes are climbing the fastest, with contract manufacturing organization capacity expansion reducing cost-per-dose and enabling clinical trial enrollment beyond academic medical centers.
Established platforms dominate procedure volume. Gene vector technologies are gaining share fastest.
End User:
Care setting determines reimbursement pathway complexity and patient access speed, with fragmentation between institutional and ambulatory models reshaping purchasing authority.
- Ophthalmology Clinics:Standalone retina specialty practices and ambulatory surgical centers in Texas and Florida are consolidating purchasing through independent practice associations, bypassing hospital system intermediaries. Group purchasing organizations are unbundling device procurement from pharmaceutical supply agreements.
- Hospitals:Academic medical centers in the United States and university hospitals in Germany retain gene therapy trial site qualification and complex case referral concentration, though ophthalmology department fragmentation into standalone facilities is eroding historical volume.
- Home Care:Subconjunctival and topical anti-VEGF formulations remain preclinical, with formulation stability challenges blocking pharmacy channel distribution and self-administration models.
- Research Institutes:Contract research organizations and academic laboratories drive early-phase pipeline activity, particularly for sustained-release depot formulations and non-viral gene delivery platforms.
Institutional sites anchor complex intervention revenue. Ambulatory clinics are capturing maintenance regimen volume.
Delivery Mode:
Route of administration dictates supply chain configuration, from cold-chain biologics requiring compounding pharmacy intermediaries to theoretical self-administration models that would bypass clinical infrastructure entirely.
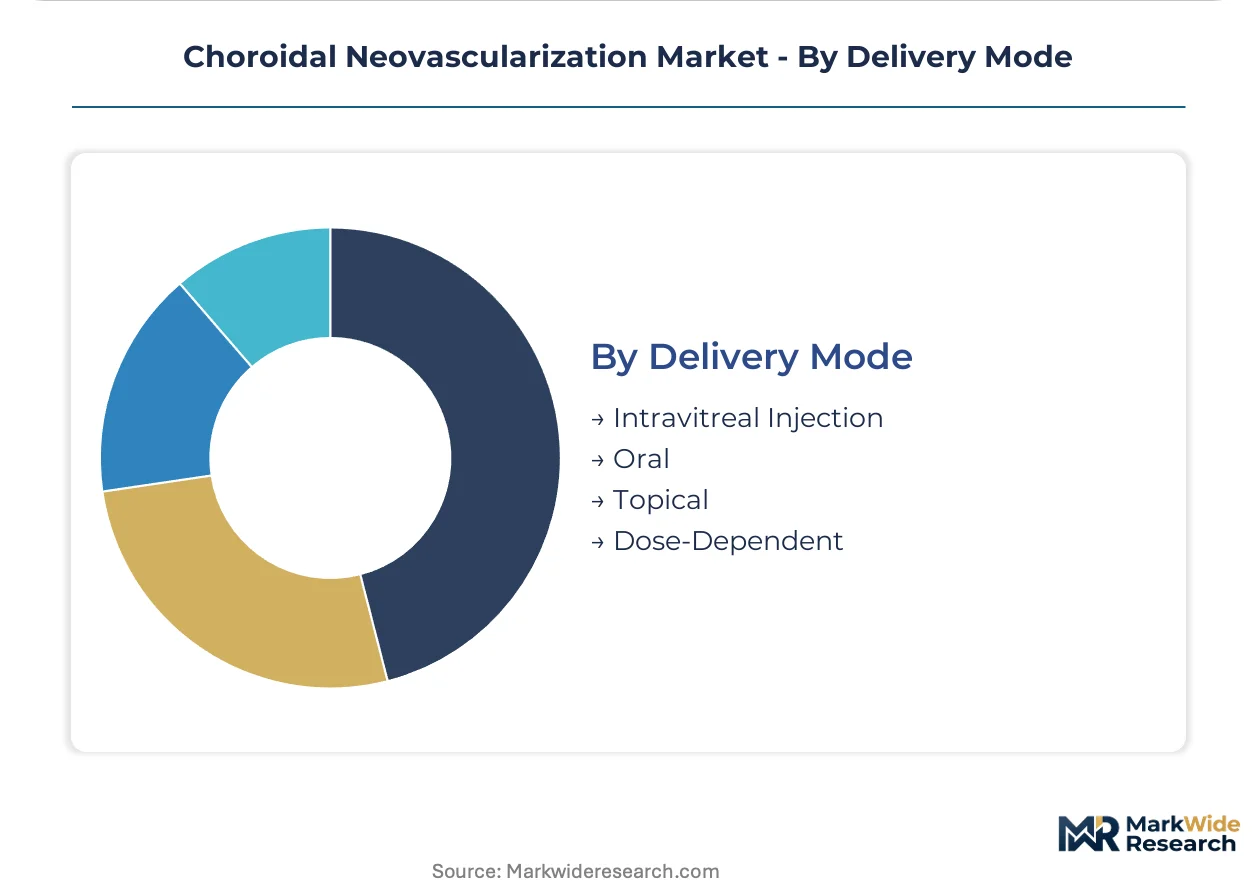
- Intravitreal Injection:Direct vitreous cavity administration via microincision techniques dominates current practice, requiring sterile compounding, temperature-controlled logistics, and specialist operator presence. Medicare physician fee schedule adjustments are compressing per-procedure margins.
- Dose-Dependent:Extended-interval and treat-and-extend protocols are displacing fixed monthly regimens, reducing injection frequency but complicating inventory forecasting and clinic scheduling optimization.
- Oral:Systemic VEGF inhibition remains investigational, with toxicity profiles blocking regulatory advancement despite patient preference for non-invasive administration.
- Topical:Penetrating formulations targeting transscleral or transcorneal drug transfer are in preclinical development, with stability and bioavailability challenges unresolved.
Invasive delivery maintains clinical control. Non-invasive alternatives remain speculative.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates more retina specialist capacity than any other single country, while Japan's pathological myopia prevalence creates a distinct epidemiological profile for CNV treatment protocols.
United States
Medicare reimbursement for intravitreal injections and an aging demographic base sustain high procedure volumes across retina specialty practices. FDA ophthalmic biologics guidance streamlines approval pathways for sustained-release formulations. Texas and Florida host the fastest-growing concentrations of standalone ambulatory surgical centers, where independent practice associations negotiate directly with manufacturers.
Germany
EMA accelerated assessment pathways and statutory health insurance coverage for anti-VEGF therapies support treatment access across the federal system. The EU AI Act and MDR requirements impose conformity assessments on OCT-based diagnostic algorithms. Bavaria and Baden-Württemberg concentrate university hospital infrastructure where gene therapy trial sites qualify for subretinal delivery protocols.
Japan
High myopia prevalence generates substantial addressable populations for CNV interventions beyond age-related macular degeneration. PMDA approval pathways increasingly incorporate Asian epidemiology data for anti-VEGF submissions. The Kanto region around Tokyo anchors retinal specialty clinic density, with Kansai emerging as a secondary concentration for clinical trial enrollment.
United Kingdom
NHS specialized commissioning frameworks govern access to intravitreal therapies, with NICE technology appraisals determining formulary placement for novel agents. MHRA post-Brexit regulatory autonomy enables accelerated access partnerships for ophthalmic biologics. London and the Southeast concentrate both private retina practices and NHS foundation trust ophthalmology departments.
Switzerland
Swissmedic regulatory efficiency and high private insurance penetration support early adoption of premium-priced sustained-expression platforms. The country's compact geography enables rapid distribution of cold-chain biologics from central compounding facilities. Basel and Zurich host the primary clusters of retinal specialty practices serving cross-border populations from neighboring EU markets.
Choroidal Neovascularization Market Key Industry Players
United States producers anchor one tier; Swiss and German specialists hold differentiated positions in biologics manufacturing and ophthalmic device integration. The market structure concentrates around three to four integrated pharmaceutical developers with vertically controlled supply chains, supplemented by mid-scale biotech specialists pursuing gene therapy platforms. Dominant competitive moves include capacity expansion in viral vector manufacturing and strategic partnerships between diagnostic equipment manufacturers and therapy developers.
Within the integrated pharmaceutical tier, F. Hoffmann-La Roche, Novartis, and Regeneron Pharmaceuticals exemplify distinct strategic positions. The Basel-based Roche entity represents sustained dominance in established anti-VEGF supply chains across European markets. Novartis occupies a position emphasizing geographic diversification and portfolio breadth. Regeneron Pharmaceuticals anchors North American channel control through manufacturing scale advantages. Each serves as an archetype for how incumbents defend position against gene therapy displacement.
| Leading Market Players |
|---|
| Pfizer |
| F. Hoffmann-La Roche |
| Novartis |
| Bayer |
| Regeneron Pharmaceuticals |
| Gilead Sciences |
| AstraZeneca |
| Sanwa Kagaku Kenkyusho |
| Bausch Health |
| Others |
Cost & Logistics Intelligence
Viral vector manufacturing costs cascade through gene therapy pricing tiers, compressing margin structures for AAV5 and AAV8 platforms while cold-chain logistics expenses anchor anti-VEGF injection reimbursement floors across United States, German, and Japanese markets.
Pricing Analysis
Capacity additions in contract manufacturing organizations are reshaping price floors for sustained-expression platforms, though three-tier pricing structure across premium gene therapy, standard anti-VEGF maintenance, and economy biosimilar tiers persists. Price differentiation hinges on injection frequency reduction and surgical delivery complexity. Cost compression in the maintenance segment intensifies because Medicare physician fee schedule adjustments narrow per-procedure margins. Retina specialty clinics in Texas and Florida exhibit highest price sensitivity, while academic medical centers in Germany and Japan absorb premium pricing for trial-site qualification.
Supply Chain Analysis
Return flows for temperature-compromised biologics and expired viral vector batches create reverse-logistics complexity, with batch discard protocols triggering supply disruption alerts. Manufacturing concentrates in the United States, Switzerland, and Germany for sterile compounding and GMP viral vector production. Raw material dependencies include AAV plasmid DNA, HEK293 cell lines, and specialized vitrectomy instrumentation. Single-source vulnerability in AAV contract manufacturing creates queue risk for gene therapy developers. Distribution runs through hospital-affiliated compounding pharmacies and standalone ambulatory surgical center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in choroidal neovascularization therapies stems from gene therapy platform economics displacing recurring injection burdens, while cold-chain cost reductions and biosimilar competition reshape tier profitability.
For Market Incumbents: Cement manufacturing scale advantages in ranibizumab and aflibercept supply chains through captive AAV production capacity in Basel and North American hubs. Defend against gene therapy displacement by securing exclusive trial-site partnerships with academic medical centers in Germany and Japan. Channel control through direct contracting with independent practice associations in Texas and Florida preserves volume against hospital system intermediaries. For New Entrants and Emerging Players: Contract development organizations with viral vector surplus capacity offer partnership entry points for sustained-expression platform developers targeting pathological myopia in Japan. White-space concentration sits with subconjunctival formulation stability research enabling pharmacy channel bypass. Go-to-market leverage through PMDA Asian epidemiology data pathways accelerates approval for high-myopia CNV indications beyond age-related macular degeneration. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale gene therapy developers because AAV manufacturing queue bottlenecks concentrate value in sites with secured GMP batch release. Long-term viability favors platforms demonstrating multi-year expression durability. Acquisition targets include viral vector CDMOs with ophthalmic biologics track record. Monitor EMA accelerated assessment pathway queue depth as inflection signal for competitive timing.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | AAV5 and AAV8 capacity expansion reduces cost-per-dose and enables trial enrollment beyond academic centers. |
| Retina Specialty Clinic Partnership | Direct contracting with Texas and Florida independent practice associations bypasses hospital system intermediaries. |
| EMA Accelerated Assessment Pathway | Fast-track designation shortens time-to-market for novel anti-VEGF agents targeting European markets. |
| AI-Augmented Diagnostic Integration | EU AI Act compliance for OCT-based CNV detection algorithms enables automated treatment authorization systems. |
| Pathological Myopia Portfolio Expansion | PMDA Asian epidemiology data incorporation unlocks Japan's high-myopia addressable population beyond AMD. |
Research Approach
Coverage spans the United States, Germany, Japan, and Switzerland, with primary inputs from each market's regulatory and clinical stakeholder base. Drug development executives, regulatory affairs leads at FDA and EMA, formulary directors, hospital procurement managers, and payer access specialists provided qualitative inputs. Secondary validation drew from FDA ophthalmic biologics guidance documents, EMA accelerated assessment pathway decisions, ClinicalTrials.gov enrollment data, and CMS Medicare physician fee schedule filings. Bottom-up procedure volume modeling and top-down market sizing triangulated across these sources.
Rate-of-change decomposition structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user setting, and regional regulatory cluster. CAGRs derived from procedure volume trends, pricing trajectory assumptions, and gene therapy adoption curve modeling. Forecast inputs incorporated vitreoretinal surgeon training pipeline constraints and viral vector manufacturing capacity expansion schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gene therapy durability data and reimbursement policy shifts for combination protocols. Forecasts reflect documented assumptions regarding injection frequency reduction and clinic capacity expansion. Practitioners should monitor EMA accelerated assessment queue depth, PMDA Asian epidemiology data acceptance rates, and Medicare physician fee schedule revision timing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Aesthetic Ophthalmology Device Market
Ophthalmology
Eye Allergy Treatment Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Global Ophthalmic Sutures Market
Ophthalmology
Europe Dry Eye Syndrome Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Blepharitis Treatment Market
Ophthalmology
Ophthalmic Femtosecond Lasers Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Global Hemianopsia Market
Ophthalmology
Ophthalmic Drugs and Devices Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Macular Edema Market