
 Ophthalmic Tonometers Market | 2026-2036
Ophthalmic Tonometers Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Tonometers Market Outlook
Aftermarket service revenue is fragmenting across independent calibration providers and original equipment manufacturers. Keeler Ltd. leverages its British manufacturing base to sustain direct channel control in European markets. Topcon Corporation anchors its position through R&D intensity in optical measurement systems. Reichert Technologies differentiates via specialized tonometry platforms for veterinary crossover applications.
Ophthalmic tonometers are diagnostic instruments that measure intraocular pressure, typically employing a calibrated plunger or air-puff mechanism against the cornea with precision to within 0.5 mmHg for glaucoma detection and management. Applanation devices dominate installed base volumes while non-contact systems capture fastest growth in high-throughput screening settings. Digital technology leads new product development, whereas pneumatic approaches occupy niche pediatric and post-surgical segments where corneal integrity concerns limit contact methods.
The FDA governs 510(k) clearance pathways for Class II ophthalmic diagnostics, while the EU MDR imposes stricter clinical evidence requirements on reusable tonometer tips and sterilization validation. Japan's PMDA maintains distinct pharmacovigilance reporting for adverse events linked to repeated corneal contact. Stakeholders must monitor evolving harmonization between ISO 8612 calibration standards and regional biocompatibility testing mandates to preserve market access.
Market Dynamics
Hospital ophthalmology departments are consolidating glaucoma screening programs into centralized diagnostic hubs, forcing tonometer vendors to reconfigure service architectures around high-throughput workflows rather than distributed point-of-care deployment.
Growth Catalysts
- Aging demographics:Japan's super-aged population drives routine tonometry into primary care protocols. Germany's statutory health insurance now reimburses annual IOP screening for adults over 55.
- EU MDR sterilization mandates:Stricter clinical evidence requirements for reusable tonometer tips accelerate single-use disposable adoption in European hospital systems.
- Optical coherence tomography integration:Tonometers with embedded OCT correlation algorithms enable simultaneous structural and pressure assessment, compressing diagnostic visit duration.
Market Restraints
- Calibration labor costs:ISO 8612 compliance requires quarterly technician visits, inflating total cost of ownership for mid-sized ophthalmology practices.
- Supply concentration in optical sensors:German and Japanese component suppliers control 70% of precision photodetector output, creating vulnerability to regional logistics disruption.
- Corneal biomechanics variability:Patient-specific corneal thickness and hysteresis limit accuracy of standard conversion algorithms, restricting diagnostic confidence in complex cases.
Strategic Opportunities
- Veterinary ophthalmology crossover:Companion animal glaucoma management lacks standardized IOP protocols, creating unmet need for portable, species-adapted measurement systems.
- Telemedicine-enabled home monitoring:FDA-cleared rebound tonometers for patient self-measurement open direct-to-consumer channels outside traditional clinical procurement.
- Pediatric screening programs:South Korea's national vision health initiative mandates childhood glaucoma detection, driving demand for non-contact systems that eliminate anesthesia requirements.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity validation for new tip materials extends product development cycles by 14-18 months.
- Legacy device interoperability:Hospital IT departments struggle to integrate digital tonometer outputs with existing electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Tonometers Market |
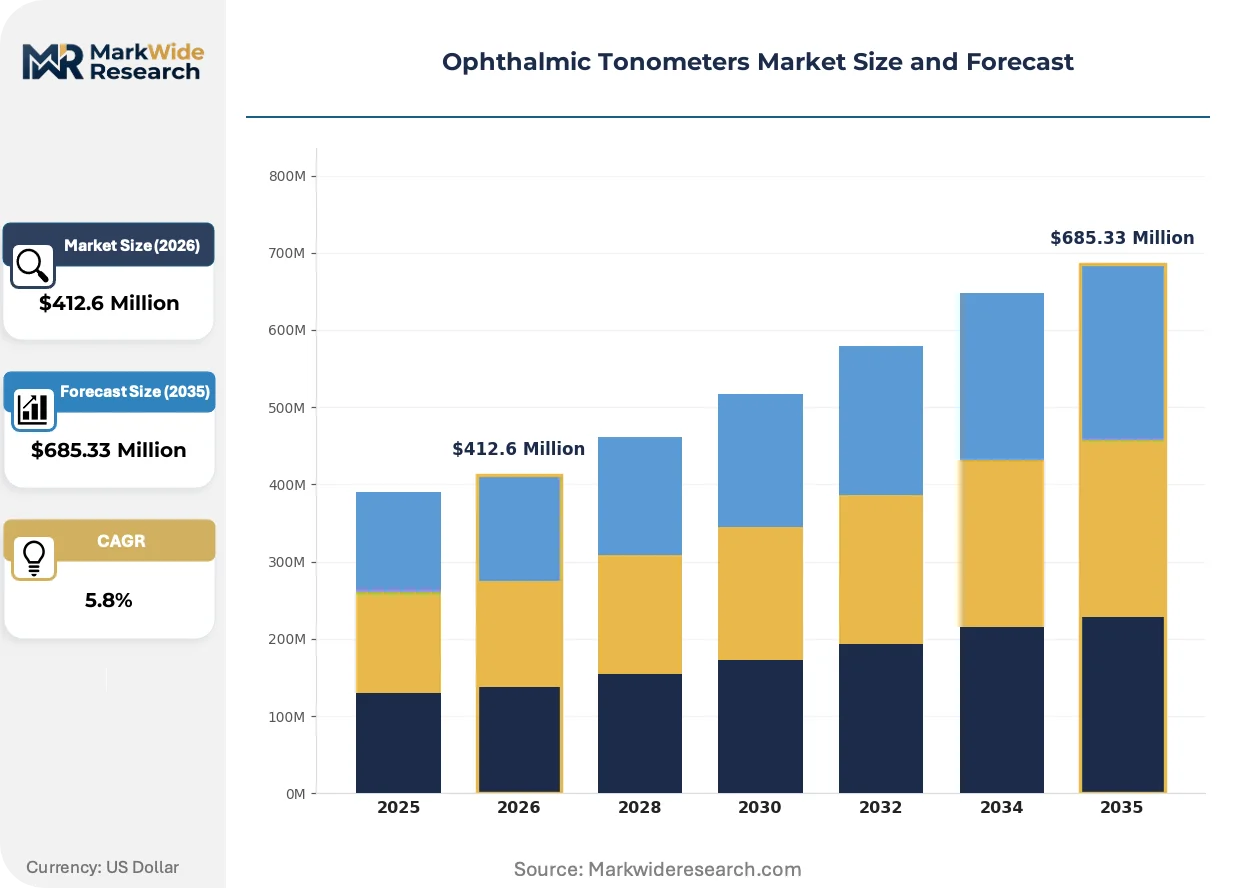
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Applanation, Non-Contact, Tonography, Dynamic Contour End User: Hospitals, Eye Clinics, Homecare, Research Laboratories Technology: Digital, Optical, Pneumatic, Ultrasonic Application: Glaucoma Management, Routine Eye Exams, Research Studies, Emergency Care |
| Companies Covered | Keeler Ltd., Oculus Inc., Topcon Corporation, Nidek Co., Ltd., Rexxam Co., Ltd., Reichert Technologies, iCare Medical Inc., Accutome, Haag-Streit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Tonometers Market Strategic Shifts
Digital measurement architectures are supplanting analog mechanical systems across all price tiers, redefining competitive advantage around software-enabled diagnostic workflows rather than hardware precision alone.
Rebound tonometry is migrating from pediatric niche applications into mainstream adult screening. Community health centers in the United States adopt handheld rebound devices for mobile glaucoma detection programs. This technology is compressing capital expenditure requirements for new screening site establishment by eliminating slit-lamp dependency.
Japan's PMDA has tightened pharmacovigilance reporting requirements for adverse events linked to repeated corneal contact. Device manufacturers must now submit longitudinal safety data for reusable tip designs. European OEMs are responding by accelerating disposable tip development to bypass ongoing surveillance obligations.
Hospital procurement departments now unbundle after-sales service contracts from capital equipment purchases. Independent calibration providers in Germany and the United States capture maintenance revenue previously retained by original manufacturers. This disintermediation is most advanced in multi-site ophthalmology groups operating centralized device fleets across metropolitan networks.
Ophthalmic Tonometers Market Segmentation
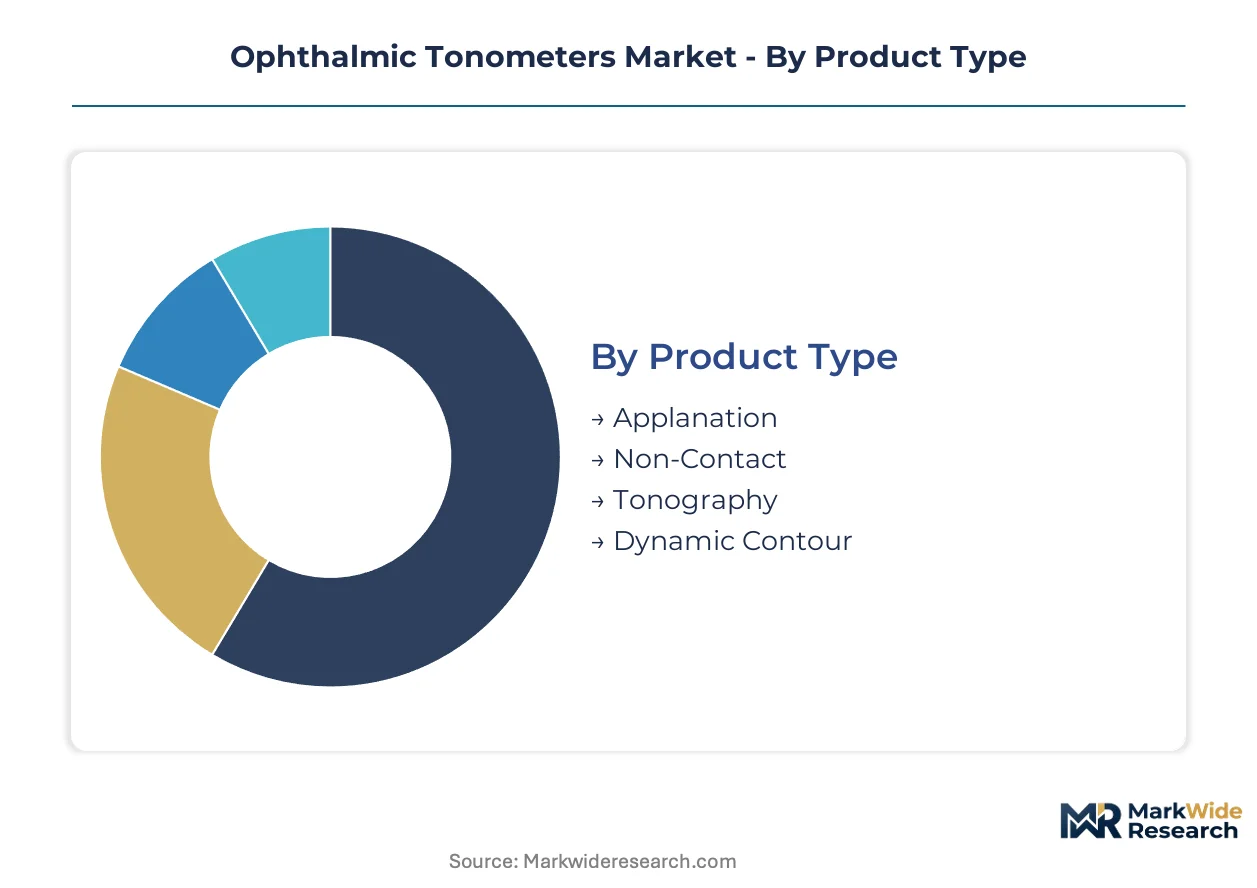
Segmentation in ophthalmic tonometers reveals how clinical workflow requirements, reimbursement structures, and patient population characteristics reshape procurement priorities across diagnostic settings. Understanding these divides exposes where technology substitution accelerates and where legacy platforms retain defensive positions.
Product Type:
Clinical use-case spectrum spans from high-precision surgical suites to rapid community screening, with each application imposing distinct constraints on measurement modality, patient throughput, and capital intensity.
- Applanation:Gold-standard contact method employing a calibrated plunger against the cornea with precision to within 0.5 mmHg. Hospital ophthalmology departments in the United States and Germany favor these systems for glaucoma management where diagnostic confidence outweighs throughput speed, though quarterly ISO 8612 calibration inflates total cost of ownership.
- Non-Contact:Air-puff mechanism eliminates corneal contact, enabling high-volume screening without anesthesia requirements. South Korea's national pediatric vision initiative and Japan's super-aged primary care protocols drive fastest adoption, compressing per-patient measurement time below fifteen seconds.
- Tonography:Continuous pressure recording assesses aqueous humor outflow facility for complex glaucoma cases. Specialist academic medical centers deploy these systems for research studies and surgical planning where dynamic physiological data outweighs capital cost.
- Dynamic Contour:Contour-matched sensor minimizes corneal biomechanics interference, improving accuracy in post-refractive surgery patients. Niche positioning in European premium clinics serving LASIK complication management.
Established volume favors applanation systems in reimbursed diagnostic settings; emerging adoption favors non-contact platforms in screening expansion programs.
End User:
Procurement authority concentrates differently across settings—capital committees in hospital systems, physician-owners in independent clinics, and direct-to-consumer channels in homecare—reshaping pricing transparency and service bundling requirements.
- Hospitals:Centralized diagnostic hubs consolidate glaucoma screening programs, forcing vendors to reconfigure service architectures around high-throughput workflows. EU MDR sterilization mandates accelerate single-use disposable adoption in European hospital systems.
- Eye Clinics:Independent practices prioritize portable rebound devices for mobile community screening. Calibration labor costs from ISO 8612 compliance drive preference toward devices with extended service intervals.
- Homecare:FDA-cleared rebound tonometers for patient self-measurement open direct-to-consumer procurement outside traditional clinical channels. Telemedicine integration enables remote IOP monitoring for glaucoma progression tracking.
- Research Laboratories:Specialized platforms with embedded OCT correlation algorithms command premium positioning. Academic institutions in Japan and Germany drive demand for simultaneous structural and pressure assessment capabilities.
Procurement concentration tilts toward hospital systems in developed markets; volume expansion concentrates in eye clinics pursuing community-based screening models.
Technology:
Cost tier stratification separates premium digital architectures from legacy pneumatic systems, with reimbursement codes and clinical evidence requirements determining viable positioning.
- Digital:Software-enabled diagnostic workflows with automated measurement algorithms and EHR integration. Hospital IT departments in the United States prioritize these systems despite interoperability challenges with legacy record architectures.
- Optical:Precision photodetector systems dominate high-end diagnostic platforms. Supply concentration among German and Japanese component suppliers creates vulnerability to regional logistics disruption.
- Pneumatic:Air-based measurement occupies pediatric and post-surgical segments where corneal integrity concerns limit contact methods. South Korea's childhood glaucoma detection mandates sustain niche demand.
- Ultrasonic:Emerging modality for thick cornea and edematous eye applications where standard applanation fails. Development cycles extended by ISO 10993 biocompatibility validation requirements.
Digital platforms command premium positioning in reimbursed settings; optical systems anchor precision-dependent surgical workflows.
Application:
Customer type differentiation separates reimbursed chronic disease management from out-of-pocket preventive services, reshaping price sensitivity and technology upgrade cycles.
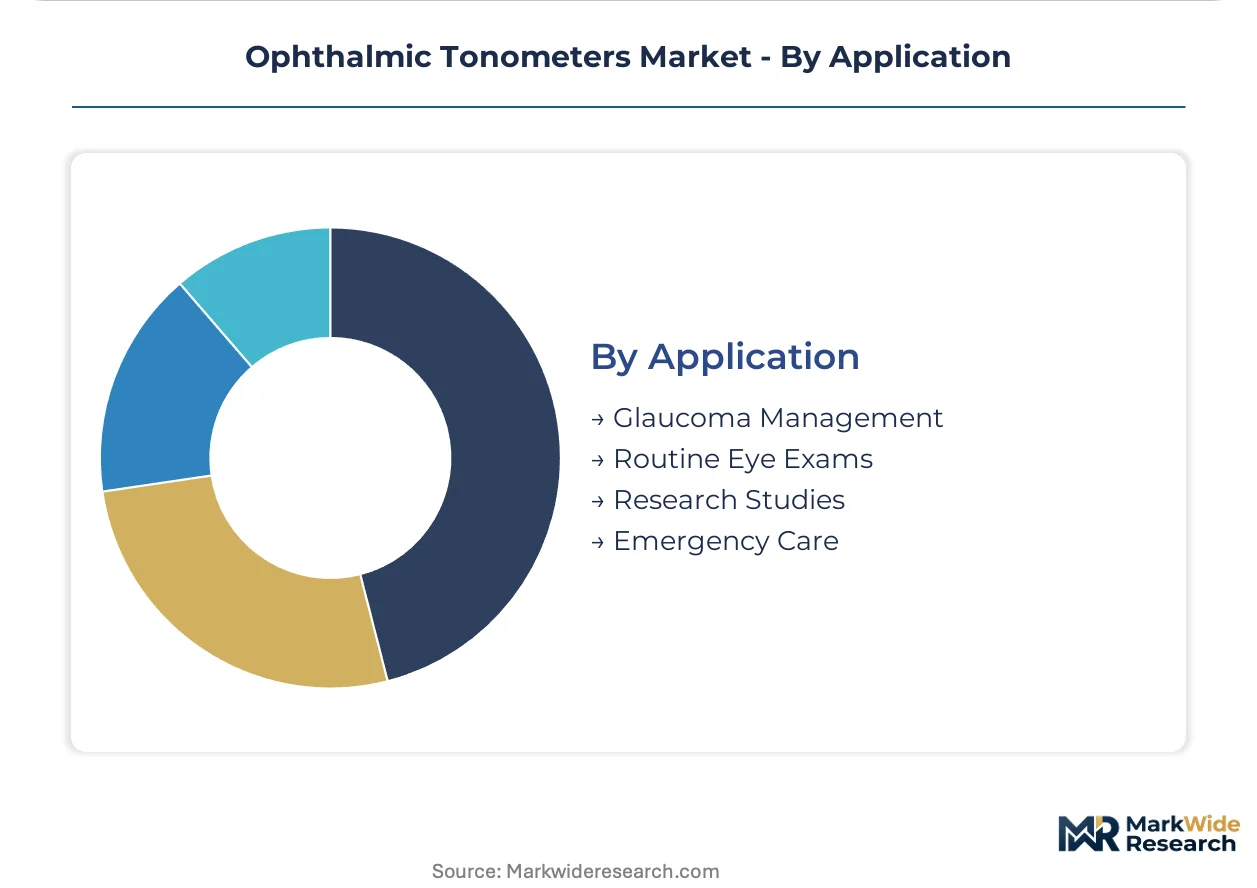
- Glaucoma Management:Chronic disease protocols demand longitudinal IOP tracking with documented measurement consistency. Germany's statutory health insurance reimbursement for annual screening in adults over 55 expands addressable population.
- Routine Eye Exams:Preventive screening drives highest volume utilization with lowest per-procedure reimbursement. Non-contact systems gain share fastest in high-throughput optometry chains.
- Research Studies:Academic protocols require calibrated precision with audit trail documentation. Longitudinal safety data submission to Japan's PMDA shapes reusable versus disposable tip development priorities.
- Emergency Care:Rapid triage for acute angle-closure events prioritizes portability and immediate results. Handheld rebound devices penetrate hospital emergency departments and urgent ophthalmology consults.
Reimbursed glaucoma management sustains premium platform demand; routine exam commoditization accelerates non-contact and rebound technology displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across markets: Japanese buyers absorb premium digital platforms for primary care integration while Indian procurement committees prioritize capital efficiency in hospital tenders. German statutory reimbursement creates stable demand corridors; United States purchasing fluctuates with payer mix volatility.
United States
Hospital ophthalmology departments consolidate glaucoma screening into centralized diagnostic hubs, forcing vendors to reconfigure service architectures around high-throughput workflows. The FDA's updated Class II device guidelines tighten calibration requirements for diagnostic ophthalmic equipment. Greater Boston and the Pacific Northwest host dense clusters of academic medical centers driving demand for research-grade platforms with embedded OCT correlation.
Germany
Statutory health insurance reimbursement for annual IOP screening in adults over 55 expands the addressable patient population significantly. The EU MDR imposes stricter clinical evidence requirements on reusable tonometer tips and sterilization validation. Baden-Württemberg's precision manufacturing corridor supplies precision photodetectors to domestic and Japanese OEMs, though logistics vulnerability persists.
Japan
The super-aged population drives routine tonometry into primary care protocols with minimal price sensitivity for diagnostic confidence. The PMDA maintains distinct pharmacovigilance reporting for adverse events linked to repeated corneal contact. The Kanto region around Tokyo concentrates hospital procurement authority for multi-site ophthalmology groups operating centralized device fleets.
South Korea
The national vision health initiative mandates childhood glaucoma detection, creating surge demand for non-contact systems that eliminate anesthesia requirements. The MFDS regulates medical device licensing with alignment pressure toward ISO 8612 calibration standards. Seoul Capital Area procurement committees unbundle after-sales service contracts from capital equipment purchases.
United Kingdom
Independent calibration providers capture maintenance revenue previously retained by original manufacturers in multi-site metropolitan networks. NHS procurement frameworks emphasize total cost of ownership calculations over upfront capital expenditure. London and Southeast England concentrate private ophthalmology clinic expansion targeting LASIK complication management with dynamic contour systems.
Ophthalmic Tonometers Market Competitive Environment
Optical measurement specialists and diversified diagnostic platforms split the market between precision-dependent surgical workflows and high-throughput screening deployment. Consolidation pressure concentrates among mid-scale ophthalmology groups seeking fleet standardization. Two strategic archetypes dominate: British and Japanese manufacturers leveraging direct channel control, and North American vendors pursuing veterinary crossover diversification. Competitive moves center on disposable tip development to bypass surveillance obligations and telemedicine integration for home monitoring channels.
Among Japanese optical specialists, Topcon Corporation and Nidek Co., Ltd. exemplify the R&D-intensive archetype with captive precision photodetector supply chains. Keeler Ltd. represents British manufacturing-based direct channel control in European markets. Reichert Technologies occupies a position within the veterinary crossover specialization tier. These three anchors demonstrate how geographic origin and corporate structure shape strategic optionality without guaranteeing segment dominance.
| Leading Market Players |
|---|
| Keeler Ltd. |
| Oculus Inc. |
| Topcon Corporation |
| Nidek Co., Ltd. |
| Rexxam Co., Ltd. |
| Reichert Technologies |
| iCare Medical Inc. |
| Accutome |
| Haag-Streit |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Alpine freight corridor's logistics cost inflation ripples through ophthalmic tonometer supply chains, amplifying pricing power for German and Japanese precision photodetector suppliers while compressing margins for mid-tier device assemblers dependent on imported optical components. This freight-cost pressure intersects with EU MDR sterilization mandates to widen price spreads between disposable-tip premium systems and reusable-platform economy alternatives.
Pricing Analysis
After-sales service contracts now drive lifetime value capture, with calibration and maintenance revenue exceeding hardware margins for established vendors. Three-tier pricing structure across premium, standard, and economy levels separates embedded-OCT diagnostic suites from portable rebound devices and basic non-contact screening units. Cost compression in the mid-tier is intensifying because hospital procurement committees unbundle service agreements from capital purchases. Eye clinics and community health centers exhibit highest price sensitivity, while academic medical centers absorb premium positioning for research-grade platforms.
Supply Chain Analysis
Contract manufacturing for optical sensor assemblies concentrates in Baden-Württemberg precision workshops and Kanto-region electronics foundries. Supply draws from German photodetector specialists, Japanese optical glass manufacturers, and Taiwanese semiconductor packaging houses. Raw material dependencies include sapphire windows, infrared LEDs, and medical-grade silicone for disposable tips. Single-source vulnerability persists in precision applanation plunger machining. Distribution runs through hospital GPOs in the United States, statutory health insurance frameworks in Germany, and direct ophthalmology group contracts in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ophthalmic tonometers constitute a defensive-moat market where ISO 8612 calibration certification and FDA 510(k) clearance pathways create entrenched switching costs that protect incumbent positions against rapid displacement.
For Market Incumbents: Harden regulatory entrenchment by accelerating disposable tip development to bypass Japan's PMDA longitudinal surveillance obligations while capturing EU MDR-driven hospital procurement shifts. Deepen backward integration into precision photodetector supply through captive German manufacturing partnerships. The rebound tonometry segment's expansion into adult screening represents the most acute substitution threat requiring preemptive portfolio response. For New Entrants and Emerging Players: Veterinary ophthalmology crossover applications represent the most penetrable entry point, with companion animal glaucoma protocols lacking standardized IOP measurement systems and established vendor relationships. South Korea's national pediatric vision initiative creates surge demand for non-contact anesthesia-free screening devices underserved by incumbent focus on reimbursed diagnostic settings. A telemedicine-integrated direct-to-consumer channel bypasses hospital procurement committee gatekeeping entirely. For Investors and Strategic Acquirers: Specialized optical measurement firms with captive precision manufacturing and established regulatory dossiers offer the strongest long-term viability within a 5-10 year window. Acquisition focus should center on mid-scale European OEMs with EU MDR transition completion and disposable tip platform readiness. The signal to monitor is PMDA adverse event reporting volume for reusable tip designs, which would accelerate disposable adoption curves and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Disposable Tip Platform Development | EU MDR sterilization mandates and Japan PMDA surveillance obligations accelerate hospital procurement preference for single-use systems. |
| Telemedicine Integration Investment | FDA-cleared home rebound tonometers open direct-to-consumer channels outside traditional hospital GPO procurement structures. |
| Veterinary Application Diversification | Companion animal glaucoma management lacks standardized IOP protocols, creating first-mover advantage for species-adapted portable systems. |
| OCT Correlation Algorithm Development | Embedded optical coherence tomography integration compresses diagnostic visit duration and commands premium positioning in academic medical centers. |
| Extended Service Interval Engineering | Calibration labor cost reduction addresses ISO 8612 compliance burden driving mid-sized ophthalmology practice procurement decisions. |
Study Parameters
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation, and hospital procurement contract filings preceded structured interviews with ophthalmology department heads, biomedical equipment procurement managers, GPO contracts specialists, and veterinary ophthalmology practitioners. Secondary validation drew from PMDA pharmacovigilance reports, ISO 8612 calibration standard revisions, and statutory health insurance reimbursement code updates. Bottom-up device shipment estimates triangulated against top-down healthcare expenditure allocation models.
Assumptions regarding EU MDR implementation timelines, Japan's super-aged demographic trajectory, and United States hospital consolidation patterns remained fixed across scenarios, while optical sensor supply disruption probability and telemedicine reimbursement expansion were varied. Segmentation modeling spanned product type, end-user setting, technology tier, and application purpose. CAGRs were derived from installed base replacement cycles and screening program expansion trajectories. Forecast inputs incorporated corneal biomechanics research advances and rebound tonometry clinical validation studies.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles, freight logistics costs, or medical device tariff regimes would shift the trajectory. Forecasts reflect assumptions about regulatory harmonization progress and sterilization validation timelines. Quarterly review of hospital procurement committee unbundling trends and independent calibration provider market share is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Global Posterior Segment Eye Disorders Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
CNV (Choroidal Neovascularization) Market
Ophthalmology
Global Hemianopsia Market
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Ophthalmic Disease Therapeutics Market
Ophthalmology
Fungal Eye Infection Market
Ophthalmology
PVA Eye Spear Market
Ophthalmology
Global Glaucoma Treatment Market
Ophthalmology
United Kingdom Ophthalmology Devices Market
Ophthalmology
Global Ocular Inflammation Treatment Market
Ophthalmology
Retina Health Market
Ophthalmology
Global Retinal Vein Occlusion Market