
 Global Optic Nerve Disorders Treatment Market | 2026-2036
Global Optic Nerve Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optic Nerve Disorders Treatment Market Foresight
Project finance for late-stage ophthalmology trials is narrowing the field of viable competitors, favoring firms with balance-sheet depth or risk-sharing partnerships. Novartis AG leverages its integrated eye-care platform to sustain pipeline momentum across glaucoma and optic neuropathy indications. F. Hoffmann-La Roche Ltd. anchors its position through biomarker-driven patient stratification in neuro-ophthalmology. Pfizer Inc. competes by extending its rare-disease infrastructure into Leber's hereditary optic neuropathy programs.
Optic nerve disorders treatment encompasses pharmacological and interventional modalities targeting axonal degeneration, retinal ganglion cell loss, and elevated intraocular pressure, with functional parameters including visual field preservation and optic disc perfusion metrics. The primary purpose spans halting progressive vision loss and restoring neural conductivity in conditions ranging from ischemic insult to hereditary mitochondrial dysfunction. Glaucoma medications occupy the largest revenue pool given chronic administration requirements, while neuroprotective agents represent the fastest-expanding category as mechanism-specific therapies advance through clinical validation. Intravitreal injection delivery commands premium positioning due to precision dosing and sustained-release formulations, though topical eye drops retain volume leadership in first-line management.
The FDA's orphan drug framework and EMA's accelerated assessment pathway shape development incentives, while Japan's PMDA Sakigake designation compresses review timelines for novel neuroprotective mechanisms. These regulatory architectures determine which innovators gain early market access and pricing flexibility across North America, Europe, and Asia-Pacific. Stakeholders must monitor reimbursement negotiations for sustained-release implants versus conventional injection regimens, as payor categorization will determine commercial viability of next-generation delivery platforms.
Market Dynamics
Neuroprotective drug development is consolidating around sustained-release intravitreal delivery platforms, compressing development timelines and raising capital barriers for entrants lacking integrated manufacturing capabilities or risk-sharing partnerships with specialized eye hospitals.
Growth Catalysts
- FDA Orphan Drug Designation:The pathway accelerates clinical trial timelines and grants seven-year market exclusivity for therapies targeting Leber's hereditary optic neuropathy and other rare optic nerve conditions.
- Japan's PMDA Sakigake Framework:Early approval designation compresses regulatory review for novel neuroprotective mechanisms, enabling first-in-class therapies to reach Japanese patients ahead of other markets.
- Intravitreal Injection Platforms:Sustained-release formulations from biodegradable polymers extend dosing intervals from monthly to quarterly, improving adherence in chronic glaucoma management.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Over 60% of specialized neuroprotective compounds rely on single-source contract manufacturers in Switzerland and Germany, creating supply vulnerability.
- EMA Accelerated Assessment Thresholds:Stringent benefit-risk requirements for novel mechanisms delay European market entry even after FDA approval, fragmenting launch sequencing.
- Topical Drop Substitution:Fixed-dose combination drops for early-stage glaucoma limit uptake of injection therapies in price-sensitive markets and primary care settings.
Strategic Opportunities
- Underpenetrated German Outpatient Networks:Specialized neuro-ophthalmology centers in Bavaria and North Rhine-Westphalia remain underserved by sustained-release implant therapies.
- Biomarker-Guided Patient Stratification:Integration of OCT-based ganglion cell analysis with genetic screening enables precision dosing and expands addressable populations.
- EMA Priority Medicines Scheme:Enhanced scientific advice and accelerated assessment for neuroprotective agents targeting ischemic optic neuropathy reduce regulatory capital requirements.
Industry Challenges
- Retinal Specialist Training Bottlenecks:Intravitreal injection competence requires fellowship-level surgical training, constraining administration capacity in community ophthalmology practices.
- Multinational Trial Harmonization:Divergent visual field endpoints between FDA and PMDA protocols force duplicate study arms, inflating Phase III costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optic Nerve Disorders Treatment Market |
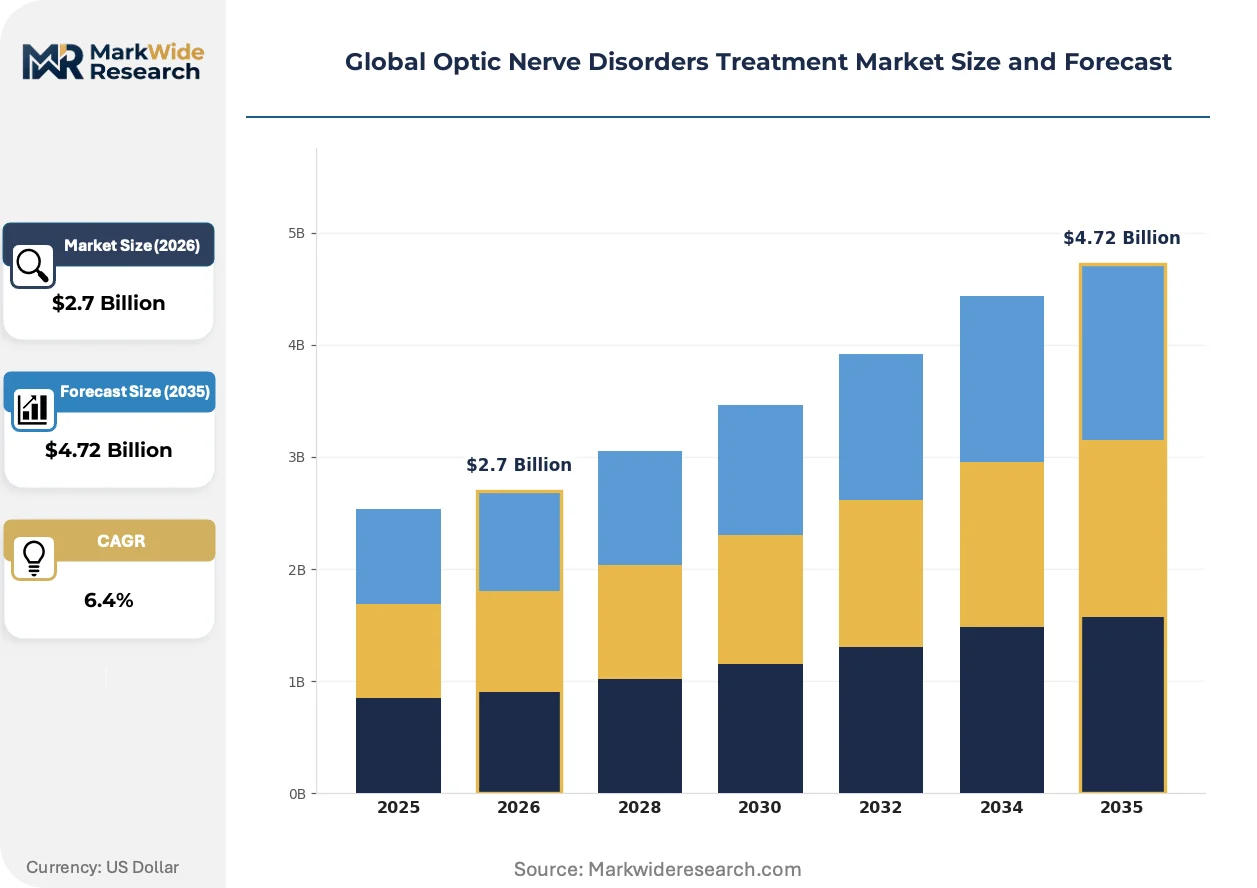
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glaucoma Medications, Neuroprotective Agents, Anti-inflammatory Drugs, Dietary Supplements, Surgical Devices Therapy Area: Optic Neuritis, Ischemic Optic Neuropathy, Traumatic Optic Neuropathy, Leber's Hereditary Optic Neuropathy, Papilledema End User: Ophthalmology Clinics, Specialized Eye Hospitals, Neurology Centers, Research Institutes, Rehabilitation Facilities Delivery Mode: Oral, Intravitreal Injection, Topical Eye Drops, Implanted Devices, Intravenous Therapy |
| Companies Covered | Novartis AG, F. Hoffmann-La Roche Ltd., Pfizer Inc., Teva Pharmaceutical Industries Ltd., Santen Pharmaceutical Co., Ltd., Allergan plc, GlaxoSmithKline plc, Bausch Health Companies, Inc., Mallinckrodt Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optic Nerve Disorders Treatment Market Shifts & Advancements
Delivery technology convergence is redefining competitive boundaries in optic nerve therapeutics, with sustained-release platforms absorbing functions previously split across device and drug manufacturers.
Gene therapy vectors incorporating tissue-specific promoters are hybridizing with biodegradable scleral implants, enabling localized, long-duration expression of neuroprotective proteins. Academic medical centers in the United States and Japan are piloting these systems in mitochondrial optic neuropathies. The technology is hybridizing drug and device regulatory pathways, forcing sponsors to build dual expertise or cede control to platform specialists.
EMA's Medical Device Regulation (MDR) reclassification of drug-eluting implants as combination products imposes notified body involvement alongside centralized drug assessment. Manufacturers must now submit technical documentation on polymer degradation kinetics alongside clinical efficacy data. German and French notified bodies are experiencing backlogs exceeding 18 months, delaying European launches for implant-based therapies.
Hospital procurement committees are consolidating purchasing authority for ophthalmology biologics, displacing individual physician preference in favor of formulary contracts tied to volume commitments. United States academic medical centers and Japanese university hospitals are leading this consolidation. The shift compresses commercial access for mid-tier manufacturers lacking dedicated hospital contracting teams.
Global Optic Nerve Disorders Treatment Market Segmentation
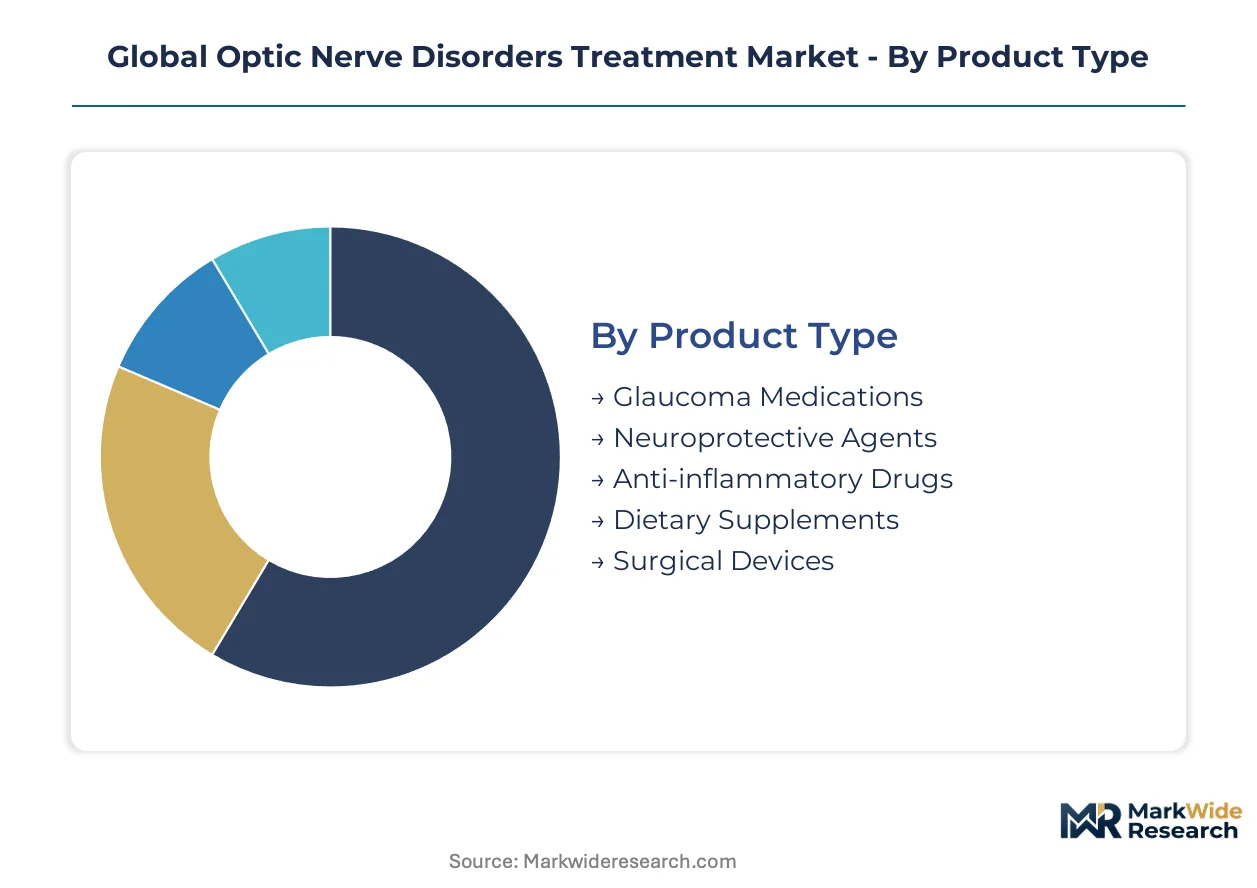
Treatment modality selection in optic nerve disorders hinges on disease etiology, progression velocity, and anatomical accessibility. Segmentation reveals how chronic versus acute conditions dictate channel strategy and pricing architecture across institutional purchasers.
Product Type:
The use-case spectrum spans chronic pressure management to acute axonal rescue, with formulation science determining reimbursement tiers and administration site requirements.
- Glaucoma Medications:Prostaglandin analogs and beta-blockers dominate first-line protocols through once-daily dosing regimens. Demand concentrates in United States Medicare Part D formularies and Japanese national health insurance listings, constrained by generic erosion in established markets.
- Neuroprotective Agents:Mechanism-specific therapies targeting retinal ganglion cell apoptosis include brimonidine derivatives and NMDA receptor modulators. German outpatient networks and academic medical centers in Massachusetts drive adoption, fueled by orphan drug incentives for mitochondrial optic neuropathies.
- Anti-inflammatory Drugs:Corticosteroid protocols for optic neuritis associated with multiple sclerosis.
- Dietary Supplements:Antioxidant formulations targeting oxidative stress in ischemic insults.
- Surgical Devices:Micro-invasive glaucoma shunts and neurostimulation implants.
The dominant share belongs to Glaucoma Medications, while Neuroprotective Agents is closing the gap fastest.
Therapy Area:
Cost tier stratification separates chronic maintenance indications from acute intervention scenarios, with diagnostic complexity determining specialist referral patterns.
- Optic Neuritis:Demyelinating inflammation requiring urgent high-dose corticosteroid protocols. United States multiple sclerosis centers and United Kingdom neurology trusts generate volume, pressured by biosimilar competition in established markets.
- Ischemic Optic Neuropathy:Acute vascular compromise demanding immediate neuro-ophthalmology consultation. Japanese university hospitals and Swiss emergency networks concentrate demand, driven by aging population incidence and cardiovascular comorbidity protocols.
- Traumatic Optic Neuropathy:Compression or transection injuries from craniofacial trauma.
- Leber's Hereditary Optic Neuropathy:Maternally inherited mitochondrial DNA mutation with gene therapy pipeline activity.
- Papilledema:Intracranial pressure elevation requiring neurosurgical or endovascular intervention.
Optic Neuritis commands the largest addressable population, though Ischemic Optic Neuropathy shows the steepest expansion trajectory from demographic shifts.
End User:
Customer type segmentation reflects procedure complexity gradients, with capital equipment requirements filtering access by institutional scale.
- Specialized Eye Hospitals:Tertiary referral centers equipped for intravitreal surgery and sustained-release implant administration. Bavaria's university-affiliated networks and Tokyo's Juntendo University Hospital anchor demand, shaped by bundled payment pilots for chronic glaucoma management.
- Ophthalmology Clinics:Community-based practices handling topical therapy initiation and monitoring. French mutualist clinics and California independent practice associations concentrate volume, constrained by specialist training bottlenecks in injection competence.
- Neurology Centers:Integrated multiple sclerosis and neuro-ophthalmology services.
- Research Institutes:Academic medical centers conducting gene therapy and neuroprotection trials.
- Rehabilitation Facilities:Low-vision services for end-stage optic nerve damage.
Specialized Eye Hospitals capture the premium procedure segment, while Ophthalmology Clinics are expanding their share through practice consolidation.
Delivery Mode:
Maturity gradients separate decades-old topical administration from implant technologies navigating combination product regulatory pathways.
- Intravitreal Injection:Precision dosing of anti-VEGF agents and sustained-release corticosteroids via pars plana access. Adoption clusters in United States retinal specialist practices and South Korean high-volume centers, accelerated by quarterly dosing formulations improving adherence.
- Topical Eye Drops:Prostaglandin and carbonic anhydrase inhibitor formulations for intraocular pressure reduction. German statutory health insurance formularies and Indian government procurement programs sustain volume, limited by patient compliance failures in chronic regimens.
- Oral:Systemic neuroprotective and anti-inflammatory agents.
- Implanted Devices:Biodegradable scleral implants and glaucoma drainage hardware.
- Intravenous Therapy:Acute high-dose protocols for inflammatory and ischemic indications.
Topical Eye Drops retain volume leadership, yet Intravitreal Injection is gaining share fastest through sustained-release innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and German tertiary centers, where bundled reimbursement for sustained-release implants exceeds United States Medicare rates by margins that reflect procedure complexity and specialist scarcity.
United States
Medicare Part D formularies drive volume for prostaglandin analogs, while academic medical centers in Massachusetts and California pilot gene-surgery hybrid protocols. The FDA's orphan drug designation compresses timelines for Leber's hereditary optic neuropathy therapies. Retinal specialist practices in the Northeast corridor absorb the majority of intravitreal injection procedures.
Germany
Statutory health insurance maintains premium reimbursement tiers for neuroprotective agents, with Bavarian university hospitals leading sustained-release implant adoption. EMA accelerated assessment pathways for combination products create regulatory bottlenecks at German notified bodies. The North Rhine-Westphalia outpatient network remains underserved by advanced delivery platforms.
Japan
PMDA Sakigake designation enables first-in-class neuroprotective agents to reach Tokyo's Juntendo University Hospital ahead of other markets. Aging demographics expand ischemic optic neuropathy diagnostic volumes at university-affiliated centers. METI funding for mitochondrial disease research accelerates local gene therapy vector development.
Switzerland
Swissmedic's proximity to contract manufacturing clusters in Basel supports over 60% of specialized neuroprotective API production for European markets. Zurich and Geneva emergency networks concentrate demand for acute ischemic protocols. The country's reimbursement authority favors high-cost implant therapies in cantonal hospital formularies.
United Kingdom
NHS England's specialized commissioning framework restricts neuro-ophthalmology biologics to designated multiple sclerosis centers in London and the Midlands. NICE technology appraisals impose cost-effectiveness thresholds that delay access to sustained-release formulations. Scottish neurology trusts generate volume for optic neuritis corticosteroid protocols.
Global Optic Nerve Disorders Treatment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying API and polymer substrates to finished-dose manufacturers. The vendor base stratifies across three tiers: multinational pharmas with integrated eye-care divisions, mid-cap firms with risk-sharing partnerships for late-stage trials, and single-product biotechs dependent on contract manufacturing. Dominant competitive moves include strategic partnerships with specialized eye hospitals for real-world evidence generation, and backward integration into biodegradable polymer production to secure implant supply chains.
Within the integrated platform tier, Novartis AG and F. Hoffmann-La Roche Ltd. exemplify archetypes of balance-sheet depth and biomarker-driven stratification respectively. Pfizer Inc. occupies a position extending rare-disease infrastructure into hereditary optic neuropathy programs. These three entities represent the concentration of project finance capacity that narrows viable competition in late-stage ophthalmology trials.
| Leading Market Players |
|---|
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Santen Pharmaceutical Co., Ltd. |
| Allergan plc |
| GlaxoSmithKline plc |
| Bausch Health Companies, Inc. |
| Mallinckrodt Pharmaceuticals |
| Others |
Supply & Pricing Matrix
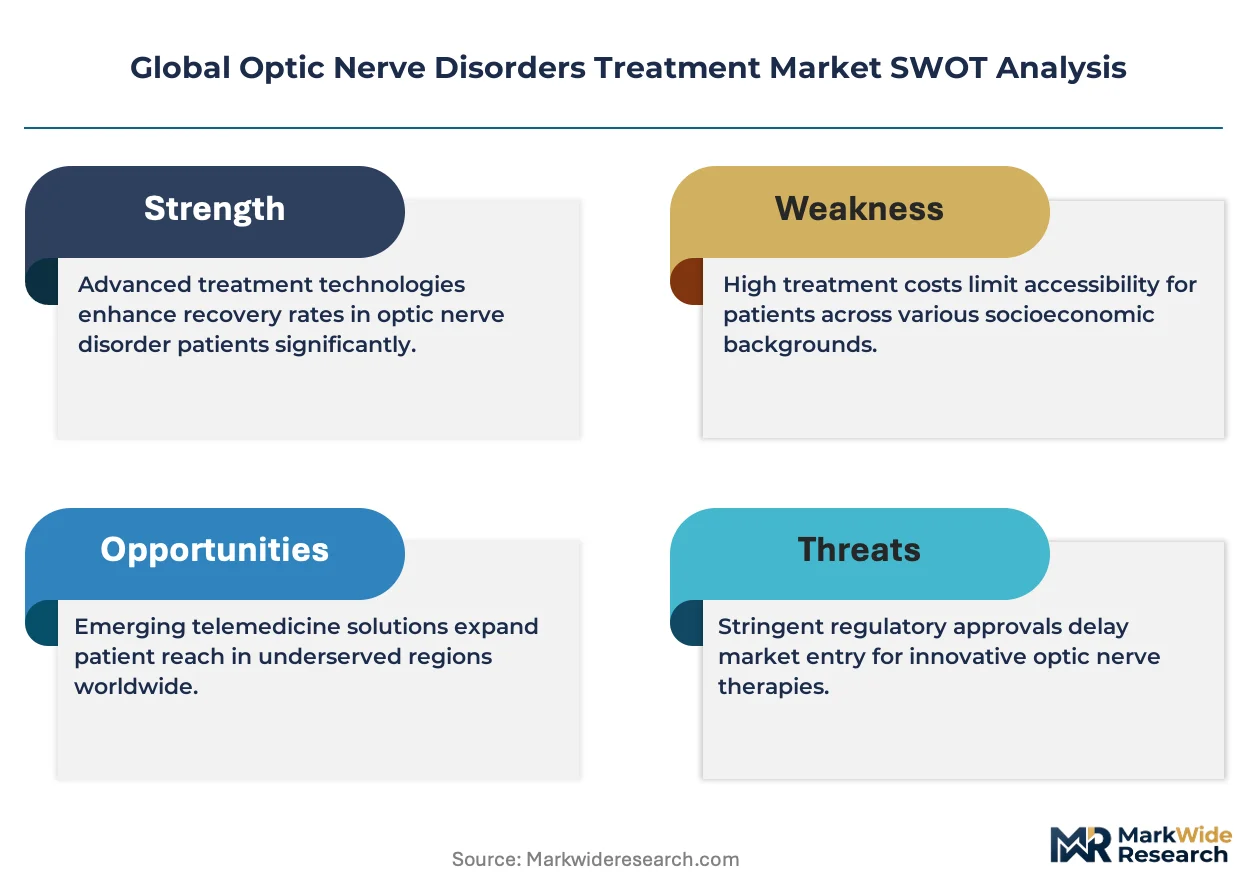
Swiss and German contract manufacturers control over sixty percent of specialized neuroprotective API output, anchoring margin capture upstream while finished-dose manufacturers in the United States and Japan compete on formulation differentiation and delivery platform innovation. This concentration forces downstream players to absorb polymer substrate volatility or cede pricing power to integrated platform holders with captive supply.
Pricing Analysis
The customization-premium spread between standard prostaglandin analog drops and configured-to-order sustained-release implants exceeds threefold in Japanese and German tertiary centers. Pricing stratifies across premium neuroprotective agents, standard glaucoma medications, and economy-tier generic drops, with differentiation driven by FDA orphan drug exclusivity and biodegradable polymer certification tiers. Cost compression in the standard drop segment intensifies as Indian and Chinese generic manufacturers expand formulary access, while hospital procurement committees in the United States exhibit lowest price sensitivity for implant therapies bundled with specialist surgical fees.
Supply Chain Analysis
Tariff exposure between Switzerland and the European Union dominates supply chain risk planning for implant-based therapies navigating German notified body backlogs. Manufacturing concentrates in Switzerland, Germany, and the United States, with polymer substrate production drawing from Basel-area chemical clusters and biodegradable scaffold fabrication resting on South Korean precision molding capacity. Single-source vulnerability pervades the retinal specialist training pipeline, constraining administration capacity regardless of drug availability. Distribution runs through hospital procurement committees consolidating ophthalmology biologics purchasing authority ahead of individual physician preference.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as diagnostic complexity fragments patient flows across neuro-ophthalmology, retina, and glaucoma specialist silos, creating niche entry points for mechanism-specific therapies and regional delivery platforms.
For Market Incumbents: Harden position through backward integration into biodegradable polymer production and exclusive formulary contracts with Bavarian and North Rhine-Westphalia hospital networks. The EMA Medical Device Regulation reclassification of drug-eluting implants as combination products threatens margin structure for non-integrated manufacturers. Capacity addition in Swiss polymer substrate production secures supply continuity against German notified body delays.
For New Entrants and Emerging Players: German outpatient ophthalmology clinics in underserved North Rhine-Westphalia networks represent the most penetrable entry point for sustained-release implant therapies bypassing saturated academic medical center competition. Gene-surgery hybrid protocols in mitochondrial optic neuropathies offer whitespace for platform specialists with dual regulatory expertise. Go-to-market execution should prioritize risk-sharing partnerships with specialized eye hospitals for real-world evidence generation ahead of payer negotiations.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap firms with validated neuroprotective mechanisms and risk-sharing partnerships compressing late-stage trial timelines. Long-term viability hinges on regulatory navigation capabilities across FDA orphan drug, EMA accelerated assessment, and PMDA Sakigake pathways. The signal to watch is Japanese university hospital adoption rates for first-in-class therapies, which predict reimbursement traction in other premium markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer Backward Integration | Captive supply of implant substrates insulates margin from Swiss-German API concentration. |
| PMDA Sakigake Pathway Navigation | Early approval designation compresses review timelines for novel neuroprotective mechanisms in Tokyo. |
| Hospital Procurement Committee Partnership | Exclusive formulary contracts displace physician preference in United States academic medical centers. |
| Gene-Surgery Hybrid Platform Development | Dual regulatory expertise captures mitochondrial optic neuropathy whitespace ahead of device-drug convergence. |
| Real-World Evidence Generation Consortium | Specialized eye hospital partnerships accelerate payer access for sustained-release formulations. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists and refined through secondary validation against FDA orphan drug filings, EMA accelerated assessment submissions, PMDA Sakigake designations, and ClinicalTrials.gov protocol endpoints. Bottom-up patient flow modeling across glaucoma, optic neuritis, and ischemic optic neuropathy indications triangulated with top-down pharmaceutical revenue segmentation.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning treatment modality, therapy area, end-user institution type, and delivery mode. CAGRs were derived from epidemiological incidence projections, pricing elasticity estimates for sustained-release versus conventional formulations, and regulatory approval probability-weighted revenue recognition timelines. Forecast inputs incorporated retinal specialist training pipeline constraints and polymer substrate production capacity utilization.
Macroeconomic conditions sit as an overlay; deviation in statutory health insurance reimbursement rates, Medicare Part D formulary placement timelines, or yen-euro exchange rate volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway success probabilities and hospital procurement consolidation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Keratoconus Treatment Market
Ophthalmology
Eye Care Surgical Market
Ophthalmology
Aesthetic Ophthalmology Device Market
Ophthalmology
Global Ophthalmic Perimeters Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Global Ophthalmology PACS Market
Ophthalmology
Epidemic Keratoconjunctivitis Treatment Market
Ophthalmology
Diabetic Retinopathy Treatment Market
Ophthalmology
Ophthalmic Femtosecond Lasers Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Ophthalmic Eye Shield Market
Ophthalmology
Superficial Punctate Keratitis Treatment Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Global Advanced Ophthalmology Technologies Market
Ophthalmology
India Ophthalmic Clinical Trials Market
Ophthalmology
South Africa Ophthalmic Devices Market