
 Ophthalmology Devices Market | 2026-2036
Ophthalmology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmology Devices Market Intelligence
Consolidation among large hospital networks and specialized surgical centers as primary buyers is hardening procurement channels for ophthalmology devices. This trend favors large-scale manufacturers with extensive distribution networks. Alcon leverages its comprehensive portfolio in surgical and vision care to serve these consolidated buyers. Carl Zeiss Meditec differentiates through its leadership in advanced diagnostic and surgical imaging systems, while Johnson & Johnson Vision Care sustains its market presence through strong brand recognition and extensive reach in vision care products.
Ophthalmology devices encompass a range of medical instruments used for diagnosing, treating, and correcting eye disorders. These devices often incorporate high-precision optics, with resolutions capable of imaging retinal layers at the micron level. Their primary purpose is to enable practitioners to perform procedures from routine eye exams to complex surgeries. Within the product landscape, diagnostic devices form a foundational segment, while surgical instruments for cataract surgery applications represent a major value pool. The laser systems technology segment is expanding due to its use in refractive procedures.
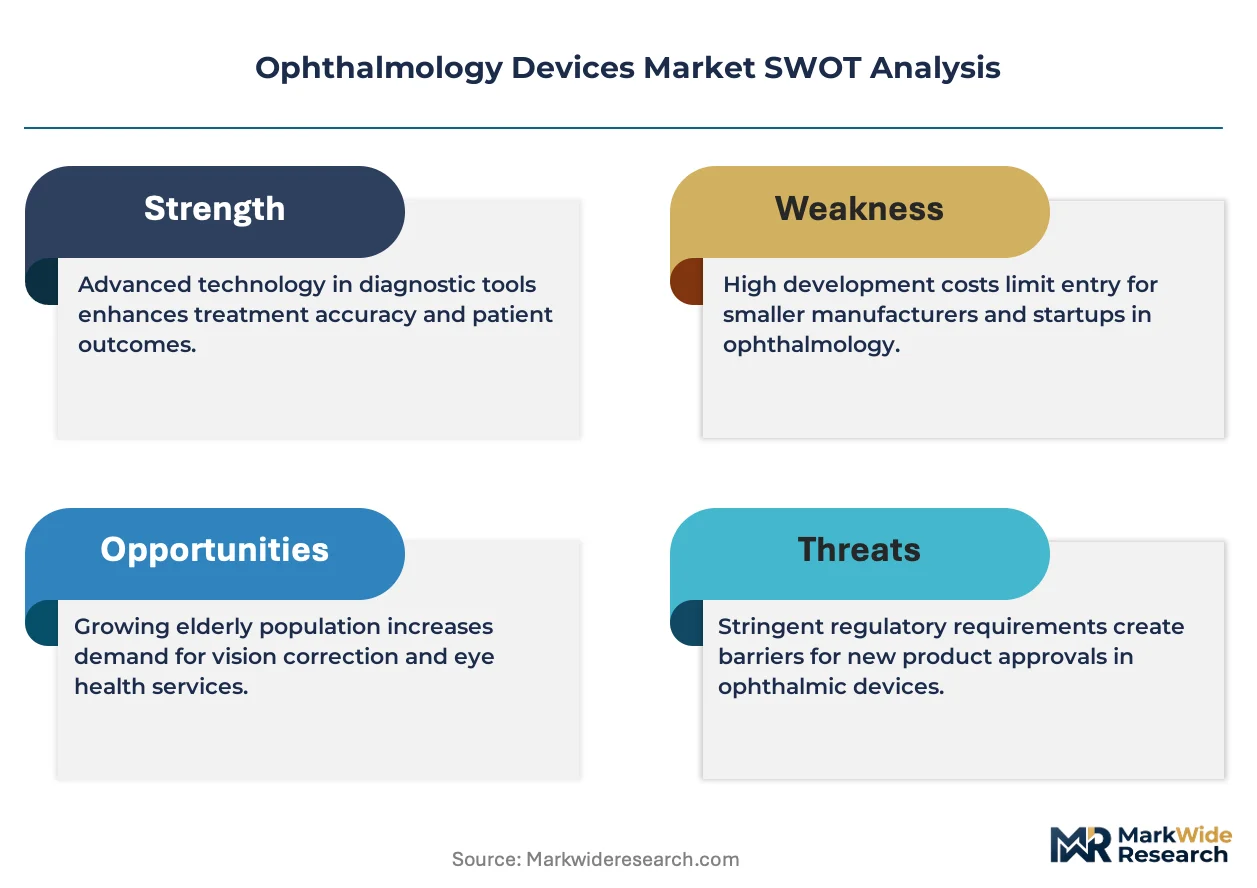
Market access for ophthalmology devices is governed by stringent regulatory approvals. The U.S. FDA's Premarket Approval (PMA) process sets a high bar for safety and efficacy data for Class III devices. In parallel, the EU's Medical Device Regulation (MDR) and China's NMPA requirements mandate rigorous clinical evidence and post-market surveillance. Navigating these varied and evolving compliance pathways remains a critical challenge for manufacturers seeking market entry and sustained access.
Market Dynamics
The integration of advanced diagnostic imaging like Optical Coherence Tomography directly into surgical platforms is the central force shaping the market. This convergence enables real-time, high-resolution guidance during procedures, meeting demand for greater precision in minimally invasive ophthalmic surgery.
Growth Catalysts
- Demographic Shifts:Expanding elderly populations in Japan and China are increasing the patient pool for cataracts and age-related macular degeneration, fueling procedural volume.
- Surgical Technology Evolution:Innovations in femtosecond laser systems enhance precision in cataract surgeries, encouraging adoption by surgical centers seeking superior patient outcomes.
- Public Health Mandates:National blindness prevention programs in India and Brazil are increasing access to diagnostic screening and surgical interventions through public health systems.
Market Restraints
- High Capital Expenditure:The significant investment for advanced systems like femtosecond lasers restricts adoption by smaller clinics and hospitals, particularly in price-sensitive regions.
- Regulatory Compliance Burden:Navigating disparate approval processes, including the EU's MDR and China's NMPA requirements, imposes substantial costs and delays on manufacturers.
- Reimbursement Pressure:Declining reimbursement rates for ophthalmic procedures in markets like the United States constrain the capital budgets of healthcare providers, slowing equipment upgrades.
Strategic Opportunities
- Emerging Market Penetration:Demand in Southeast Asia and Latin America offers growth, driven by rising incomes and expanding private healthcare infrastructure for vision care.
- AI-Powered Diagnostics:Developing AI algorithms for OCT and fundus cameras enables automated disease detection, creating value in large-scale screening programs and primary care.
- Connected Surgical Ecosystems:Building digital platforms that connect diagnostic and surgical devices improves workflow efficiency and data management for consolidated hospital networks.
Industry Challenges
- Skilled Personnel Shortage:A lack of technicians proficient with advanced laser-assisted surgical systems hinders the full utilization of new capital equipment in many regions.
- System Interoperability:Ensuring seamless data flow between new devices and existing hospital electronic health record (EHR) systems is a persistent technical hurdle.
- Component Supply Volatility:The supply of critical components like high-grade optics and semiconductors is vulnerable to logistical bottlenecks and geopolitical trade tensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmology Devices Market |
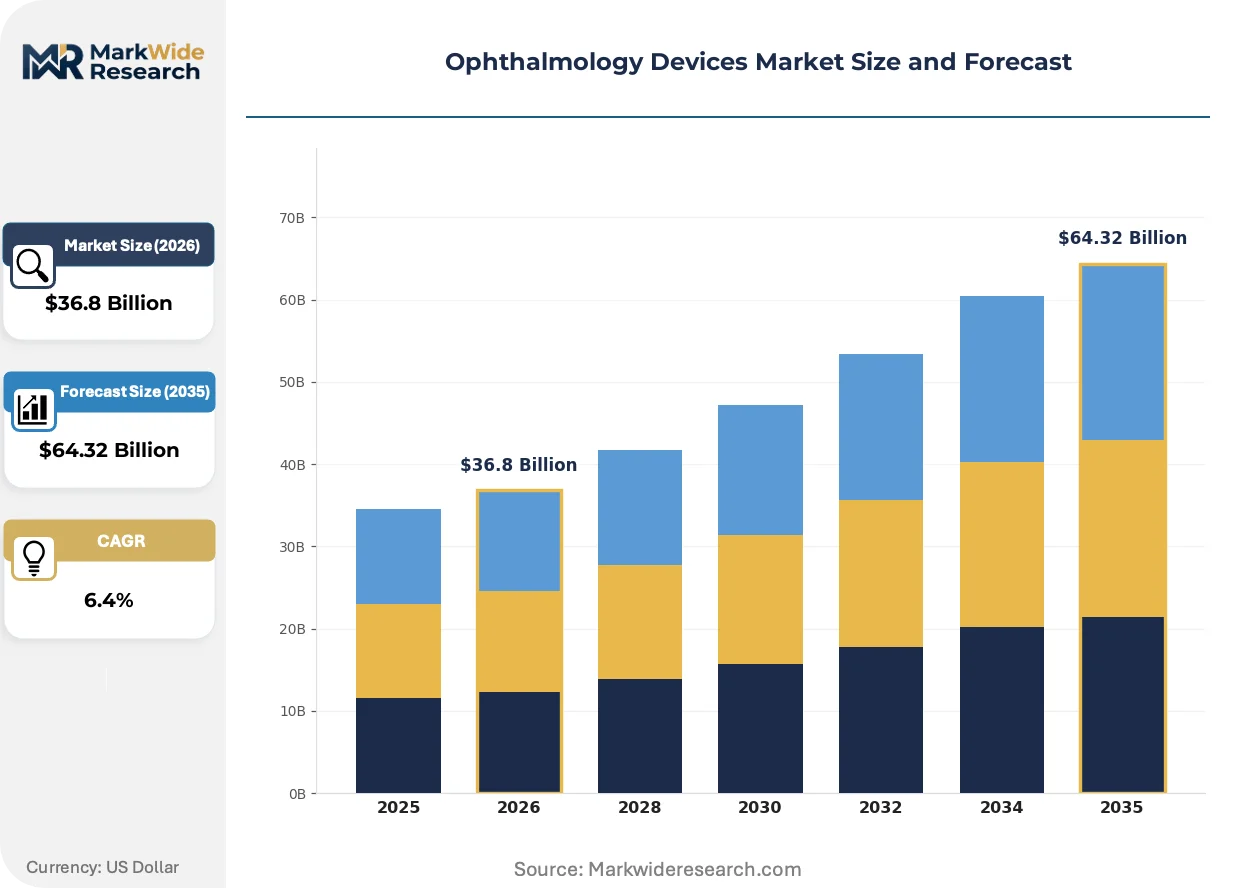
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $64.32 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Devices, Surgical Instruments, Vision Care Equipment, Imaging Systems, Monitoring Tools Application: Cataract Surgery, Glaucoma Management, Retinal Treatment, Refractive Procedures, Corneal Therapy End User: Eye Clinics, Specialized Surgical Centers, Optical Laboratories, Private Practices, Research Institutions Technology: Laser Systems, Optical Coherence Tomography, Ultrasound Imaging, Digital Refraction, Biometry Devices |
| Companies Covered | Alcon, Johnson & Johnson Vision Care, Carl Zeiss Meditec, Bausch & Lomb, Essilor International, Hoya Corporation, Topcon Corporation, Nidek Co., Ltd., Haag-Streit Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmology Devices Market Strategic Shifts & Innovations
The market's evolution is defined by the fusion of software intelligence with high-precision hardware. This shift is turning standalone diagnostic and surgical instruments into interconnected nodes within a broader clinical data ecosystem, enhancing both precision and workflow efficiency.
Portable and handheld diagnostic instruments, such as smartphone-based fundus cameras and portable OCTs, are gaining traction. Optometrists and even primary care physicians are adopting these tools for preliminary screenings outside of traditional hospital settings. This trend is decentralizing the point of initial diagnosis, enabling earlier disease detection in community-based and remote care environments.
The European Union's Medical Device Regulation (MDR) imposes more stringent requirements for clinical evidence and life-cycle management. This regulation forces manufacturers to conduct more rigorous pre-market clinical investigations and continuous post-market surveillance. Class IIb and III devices, including many surgical implants and active therapeutic devices, face the highest scrutiny, compelling firms to reinvest in clinical data generation to maintain market access.
Large hospital networks are moving away from outright capital purchases toward more flexible, consumption-based acquisition models. This shift favors arrangements where providers pay on a per-procedure basis for surgical packs and the use of associated capital equipment like phacoemulsification systems. This model is most prominent among large, multi-site surgical center chains in the United States seeking to align capital costs with procedural volume.
Ophthalmology Devices Market Segmentation
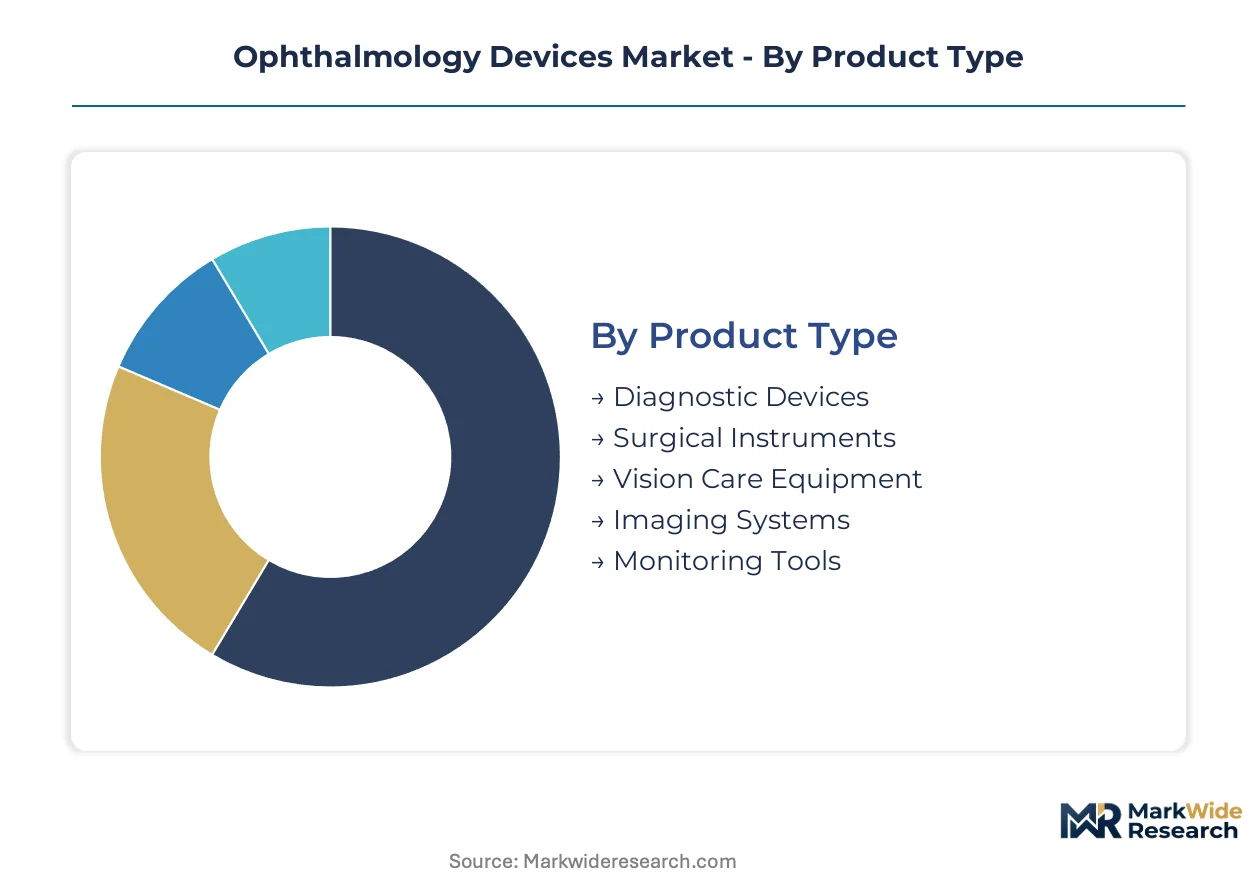
Segmentation within the ophthalmology devices market clarifies distinct product functionalities and end-user requirements. Understanding these granular divisions helps manufacturers tailor product development and market access strategies. It also highlights specific areas of high growth and evolving technological priorities across the industry.
Product Type:
The product type segmentation highlights the spectrum from highly standardized diagnostic tools to custom-configured surgical platforms.
- Surgical Instruments:These tools facilitate invasive ophthalmic procedures, ranging from micro-forceps to phacoemulsification systems. Demand is concentrating in specialized surgical centers in countries like the United States, driven by the increasing volume of cataract surgeries.
- Diagnostic Devices:This segment includes slit lamps, tonometers, and perimeters used for routine eye examinations and disease detection. Their demand is high in developing economies, particularly India, due to national blindness prevention programs expanding access to basic screenings.
- Vision Care Equipment:This category covers devices like autorefractors and lensmeters, primarily used in optical shops for prescription eyewear.
- Imaging Systems:These advanced devices, including fundus cameras and OCTs, provide detailed ocular structure visualization for disease monitoring.
- Monitoring Tools:This segment encompasses devices for continuous measurement of parameters like intraocular pressure, crucial for glaucoma management.
Leading the category by volume: Diagnostic Devices. Growing fastest: Surgical Instruments.
Application:
Application segmentation illustrates where the highest procedural volumes and associated device utilization occur across ophthalmic care.
- Cataract Surgery:This application involves the removal of a clouded lens and implantation of an intraocular lens, representing the most common ophthalmic procedure globally. Expanding elderly populations in China are fueling a significant increase in demand for related surgical instruments and consumables.
- Retinal Treatment:Devices for this application address conditions like age-related macular degeneration and diabetic retinopathy, often involving lasers or intravitreal injections. Innovations in real-time imaging during procedures are driving adoption among specialized retinal surgeons.
- Glaucoma Management:This includes devices for diagnosing and monitoring intraocular pressure, as well as surgical systems for outflow enhancement.
- Refractive Procedures:Laser systems are central to this application, correcting vision impairments like myopia through corneal reshaping.
- Corneal Therapy:Devices here range from diagnostic pachymeters to surgical tools for corneal transplants and cross-linking procedures.
Cataract Surgery applications consistently generate the largest revenue pool. Refractive Procedures are currently expanding most quickly due to technological advancements.
End User:
The end-user segmentation delineates the primary institutional and individual buyers of ophthalmology devices.
- Specialized Surgical Centers:These facilities focus exclusively on ophthalmic surgeries, requiring high-precision capital equipment like femtosecond lasers and advanced phacoemulsification systems. Procurement channels are hardening for these centers, favoring manufacturers with extensive distribution networks and strong service capabilities.
- Eye Clinics:General ophthalmology clinics provide comprehensive eye care, from routine exams to minor procedures, utilizing a broad range of diagnostic and basic surgical tools. Their demand is widespread, particularly in urban centers across Europe, serving a large patient base.
- Optical Laboratories:These entities primarily use vision care equipment for crafting and fitting prescription lenses and contact lenses.
- Private Practices:Independent ophthalmologists and optometrists operate these smaller settings, focusing on patient consultations and preliminary diagnostics.
- Research Institutions:Universities and dedicated research centers employ highly specialized imaging and experimental devices for ophthalmic studies.
Specialized Surgical Centers drive demand for high-end capital equipment. Eye Clinics represent the largest volume of device procurement across the market.
Technology:
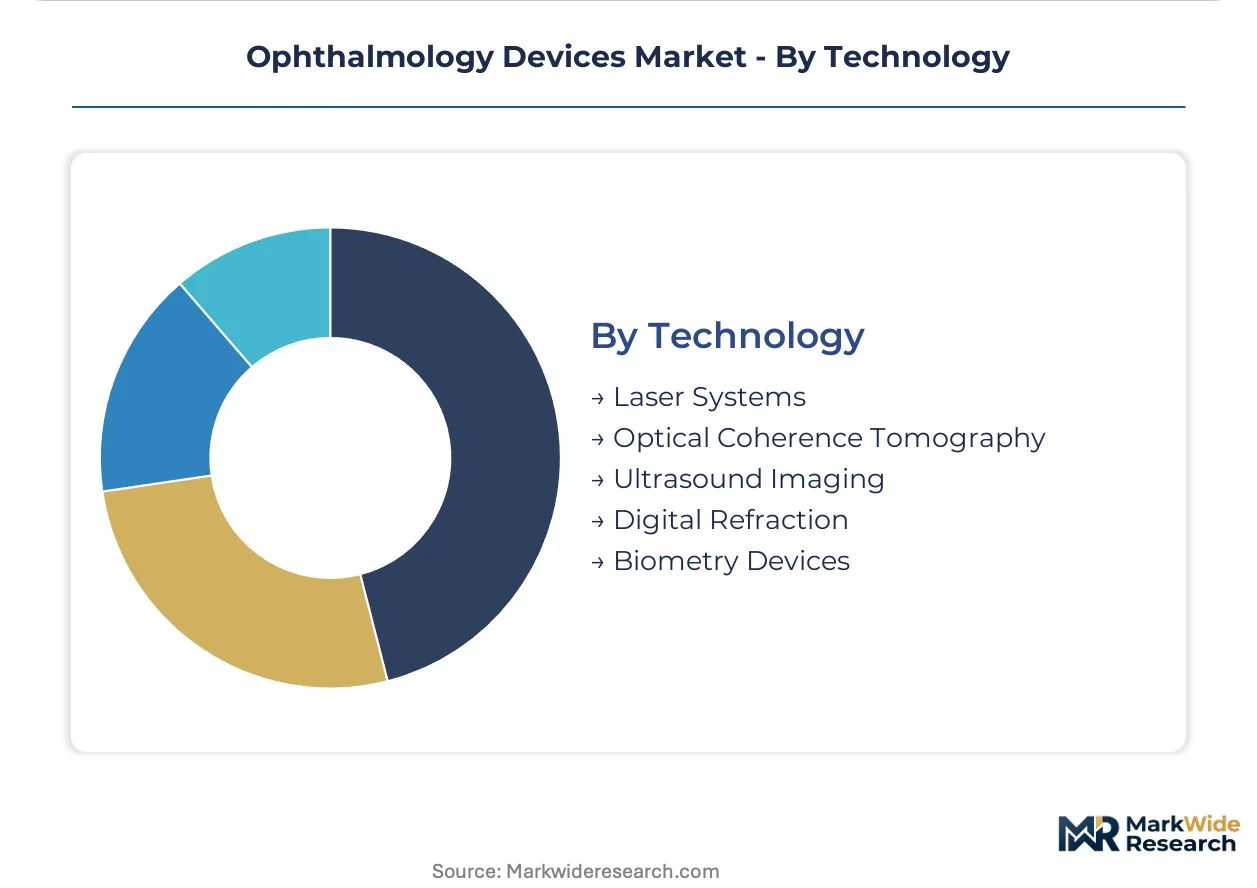
Technology segmentation reveals the maturity and innovation cycles driving device development within ophthalmology.
- Optical Coherence Tomography:OCT technology provides cross-sectional imaging of ocular tissues with micron-level resolution, crucial for early disease detection and monitoring. Advances in integrating OCT directly into surgical platforms are meeting demand for real-time guidance during complex procedures.
- Laser Systems:This segment includes femtosecond lasers and excimer lasers, used extensively in refractive surgery and advanced cataract removal. Innovations in these systems enhance precision and patient outcomes, encouraging adoption by major surgical centers in developed markets like Germany.
- Ultrasound Imaging:These devices use high-frequency sound waves to visualize ocular structures, particularly useful when optical clarity is compromised.
- Digital Refraction:Automated systems for measuring refractive errors offer efficiency and accuracy in prescribing corrective lenses.
- Biometry Devices:These instruments precisely measure eye dimensions, essential for calculating intraocular lens power before cataract surgery.
Optical Coherence Tomography solutions are exhibiting the steepest expansion trajectory. Laser Systems maintain a dominant share in high-value surgical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for ophthalmology devices concentrates significantly in regions experiencing demographic shifts and expanding healthcare infrastructure. Aging populations globally require more cataract and macular degeneration treatments. Public health initiatives in developing nations also drive increased diagnostic screenings.
China
China's expanding elderly population fuels a substantial increase in demand for cataract surgery and age-related macular degeneration treatments. The NMPA requirements for medical devices ensure safety and efficacy for domestic market entry. Major ophthalmic device manufacturing clusters are emerging in the Yangtze River Delta, supporting local production and distribution.
Japan
Japan's rapidly aging demographic creates a consistent demand for advanced diagnostic and surgical ophthalmology devices. The Ministry of Health, Labour and Welfare (MHLW) oversees medical device approvals, emphasizing product quality. Tokyo remains a central hub for research and development in ophthalmic imaging systems, attracting significant investment.
United States
The United States market demonstrates robust demand for high-end surgical instruments, driven by advanced specialized surgical centers. The U.S. FDA's PMA process sets a high bar for Class III device approvals, influencing market access. Boston's biotech cluster attracts significant innovation in ophthalmic diagnostics and laser systems development.
Germany
Germany exhibits strong demand for innovative laser systems and precision surgical equipment, particularly for refractive procedures. The EU's Medical Device Regulation (MDR) mandates rigorous clinical evidence for market entry across the European Union. Southern Germany, around cities like Jena and Munich, hosts clusters of optical technology manufacturers.
India
India's national blindness prevention programs significantly boost demand for diagnostic devices and basic surgical instruments in primary care. The Central Drugs Standard Control Organization (CDSCO) regulates medical device approvals within the country, expanding access. Major cities like Chennai and Hyderabad are developing as centers for affordable ophthalmic care delivery.
Ophthalmology Devices Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized niches in advanced imaging and AI-powered diagnostics, seeking to disrupt traditional segments. The market structure features a mix of large, diversified healthcare conglomerates and specialized optical technology firms that focus on specific device categories. Strategic archetypes include comprehensive portfolio providers, technology innovators, and regional specialists. Companies pursue portfolio diversification and strategic partnerships to strengthen their market presence and expand into new geographic territories.
Within the comprehensive portfolio provider archetype, Alcon exemplifies broad reach across surgical and vision care segments, serving consolidated buyers with a wide product offering. Carl Zeiss Meditec, a German-based company, anchors the advanced diagnostic and surgical imaging systems category, differentiating through its technological leadership. Johnson & Johnson Vision Care maintains a significant market presence through strong brand recognition and extensive global distribution channels for its vision care products, particularly in the consumer-facing segments.
| Leading Market Players |
|---|
| Alcon |
| Johnson & Johnson Vision Care |
| Carl Zeiss Meditec |
| Bausch & Lomb |
| Essilor International |
| Hoya Corporation |
| Topcon Corporation |
| Nidek Co., Ltd. |
| Haag-Streit Group |
Cost & Logistics Intelligence
The European Union's Medical Device Regulation (MDR) significantly gates qualified supply and influences premium-tier pricing access for ophthalmology devices. This stringent regulatory framework mandates extensive clinical evidence, impacting development costs and market entry.
Pricing Analysis
Volume-based segments often face tighter margins, while specialized surgical instruments command premium pricing due to their advanced capabilities. The dominant pricing model for capital equipment involves contract-based long-term agreements, increasingly shifting towards consumption-based per-procedure models for consumables. Price differentiation stems from precision engineering, brand recognition from companies like Carl Zeiss Meditec, and comprehensive after-sales service. Pricing softness is evident in markets like the United States, driven by declining reimbursement rates for ophthalmic procedures. Smaller clinics and hospitals exhibit higher price sensitivity, particularly in developing regions.
Supply Chain Analysis
Critical component supply for high-grade optics and semiconductors primarily relies on manufacturing hubs in China and Germany. These essential inputs are susceptible to logistical bottlenecks and geopolitical trade tensions, posing a structural risk to the supply chain. Distribution runs through extensive networks managed by large manufacturers like Alcon, serving consolidated hospital networks and specialized surgical centers. Boston's biotech cluster also contributes to specialized component innovation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is currently engaged in a vertical-integration race, driven by players pursuing the seamless integration of diagnostic imaging into surgical platforms. This convergence aims to create connected surgical ecosystems, enhancing precision and workflow efficiency.
For Market Incumbents: Cement market leadership by deepening vertical integration into advanced diagnostic and surgical imaging systems. Invest significantly in clinical data generation to navigate the EU's MDR compliance burden, countering the threat of regulatory delays. Expand comprehensive service capabilities and distribution networks to serve hardening procurement channels among consolidated buyers. Develop integrated digital platforms to enhance workflow efficiency across their broad portfolios.
For New Entrants and Emerging Players: Optometrists and primary care physicians represent penetrable channel partners for innovative diagnostic solutions. Target underpenetrated emerging markets like Southeast Asia and Latin America with portable, cost-effective diagnostic devices. Focus on developing AI algorithms for automated disease detection in OCT and fundus cameras, creating value in large-scale screening programs. Leverage smartphone-based technologies for preliminary screenings in community-based settings.
For Investors and Strategic Acquirers: The expanding elderly populations and technological advancements are the leading indicators that signal sustained long-term growth in ophthalmic procedures. Seek acquisition targets among specialized optical technology firms and emerging entrants focused on AI-powered diagnostics. Monitor the adoption rates of integrated diagnostic-surgical platforms, as this will signify the market's readiness for advanced, connected ecosystems.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Evidence Generation | Ensures compliance with stringent regulations like the EU MDR for market access. |
| AI-Powered Diagnostic Development | Automates disease detection, creating value in large-scale screening programs. |
| Integrated Surgical Platform Launch | Enhances precision and workflow efficiency during complex ophthalmic procedures. |
| Emerging Market Entry | Captures new patient populations in regions with rising incomes and expanding healthcare. |
| Hospital Network Partnerships | Secures procurement channels and broadens reach among consolidated healthcare buyers. |
Research Approach
Company annual reports, regulatory body publications (FDA, NMPA, MDR), and industry association whitepapers formed the secondary backbone for this analysis. Primary research involved in-depth interviews with ophthalmologists, hospital procurement managers, device engineers, and regulatory affairs specialists. This approach combined qualitative insights with quantitative data, ensuring robust bottom-up and top-down triangulation.
A bottom-up approach, validated by top-down market sizing, structured the forecast framework over the projection horizon. Segmentation dimensions included product type, application, end user, technology, and key regional markets. Compound annual growth rates were derived from historical data analysis and projected market dynamics, incorporating factors like demographic shifts and public health mandates as key inputs.
Several conditions sit outside the modeled scope, including geopolitical trade tensions and unforeseen technological disruptions. Forecasts reflect assumptions regarding regulatory stability and reimbursement policy changes. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Astigmatism Market
Ophthalmology
Extended and Continuous Wear Lenses Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Amblyopia Treatment Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Ischemic Optic Neuropathy Treatment Market
Ophthalmology
Eye Care Surgical Market
Ophthalmology
Exophthalmos Treatment Market
Ophthalmology
Global Uveitis Treatment Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Uveal Melanoma Market
Ophthalmology
Vernal Keratoconjunctivitis Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market