
 Global Photochromic Lenses Market | 2026-2036
Global Photochromic Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Global Photochromic Lenses Market Foresight
Japanese optical resin producers is restructuring supply chains to reduce dependence on imported photochromic dye precursors. EssilorLuxottica leverages its captive retail network across France and Italy to control distribution depth. Transitions Optical sustains technology leadership through proprietary imbibition processes for plastic substrates. Hoya Corporation anchors high-index photochromic output from its Tokyo-area manufacturing complex.
Photochromic lenses incorporate silver halide or organic naphthopyran molecules that reversibly darken upon UV exposure, typically achieving 75-85% visible light transmittance in the activated state, and serve the dual purpose of correcting refractive errors while eliminating the need for separate prescription sunglasses. Progressive lenses command premium positioning as aging populations require multifocal correction with adaptive tint, while polycarbonate material segments expand fastest in sports and protective eyewear due to impact resistance mandates. Single vision applications retain volume dominance through standard optical retail channels.
FDA ophthalmic device regulations govern lens biocompatibility and optical power accuracy in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substances in coating chemistries, and Japan's PMDA enforces quality management systems for imported optical devices. Stakeholders must monitor evolving blue-light filtration standards and photochromic activation speed benchmarks as purchasing criteria across vision clinics and online retailers.
Market Dynamics
Japanese optical resin producers are restructuring supply chains to reduce dependence on imported photochromic dye precursors, while polycarbonate lens demand concentrates in Germany, Japan, and the United States where optical retail chains prioritize lightweight durability.
Growth Catalysts
- REACH compliance mandates:European ECHA disclosure requirements for hazardous substances in coating chemistries accelerate material transparency investments across lens manufacturers supplying EU markets.
- Aging demographic pull:Progressive lenses command premium positioning as populations require multifocal correction with adaptive tint functionality in vision correction products.
- Polycarbonate sports adoption:Impact resistance mandates in protective eyewear drive material substitution toward lightweight, durable substrates for athletic and industrial applications.
Market Restraints
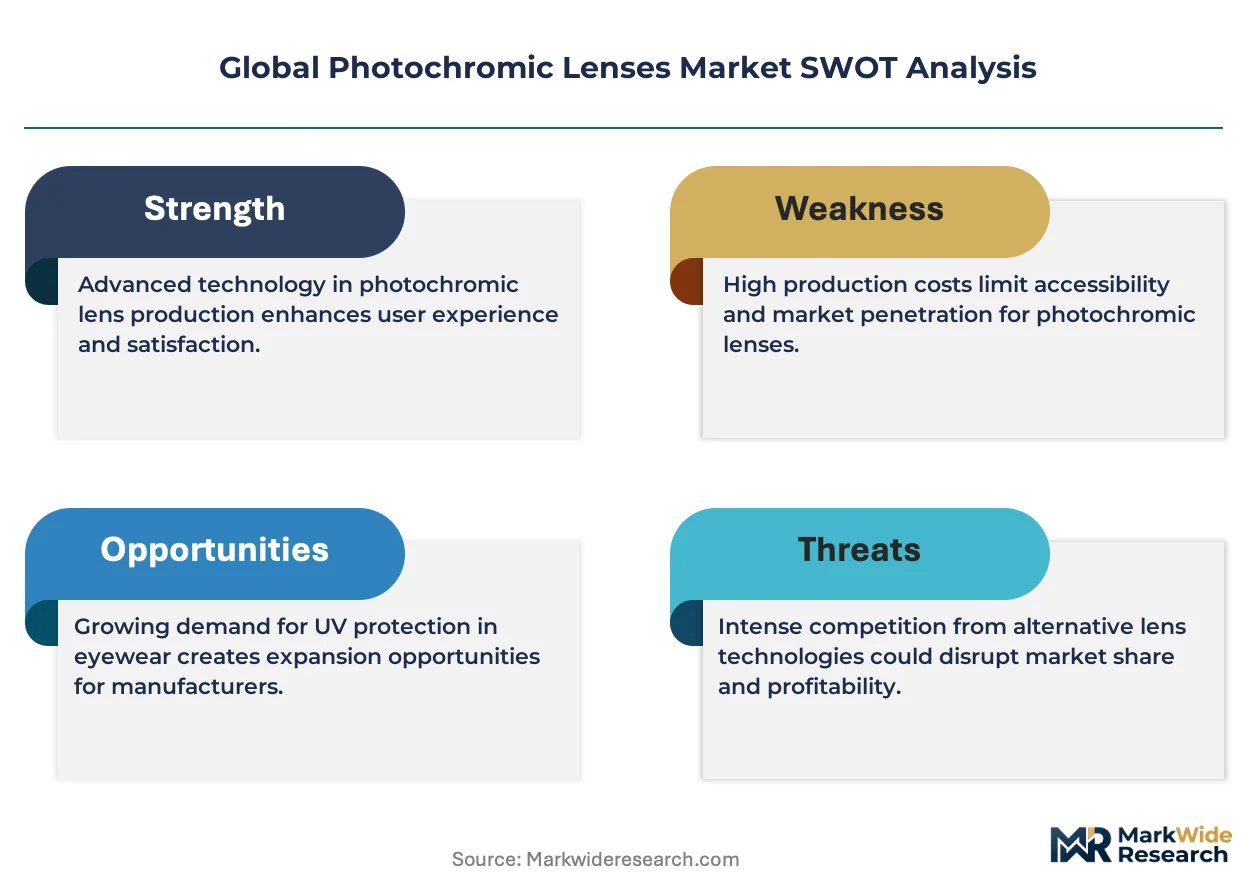
- Silver halide supply concentration:Photochromic dye precursor production clusters in limited chemical manufacturing regions, exposing lens producers to input cost volatility and geopolitical disruption.
- Activation speed limitations:Current organic naphthopyran molecules require 30-60 seconds for full darkening transition, creating performance gaps against consumer expectations for instantaneous adaptation.
- FDA ophthalmic device friction:Biocompatibility testing and optical power accuracy certification timelines extend product development cycles for US market entry.
Strategic Opportunities
- Blue-light filtration convergence:Integration of photochromic activation with digital eye strain mitigation creates dual-function value propositions for screen-intensive professional segments.
- Online retail channel expansion:Direct-to-consumer prescription platforms bypass traditional optical retail markups, capturing price-sensitive single-vision purchasers.
- India PLI scheme alignment:Domestic manufacturing incentives for medical devices attract lens fabrication investment to serve South Asian vision correction demand.
Industry Challenges
- Imbibition process expertise scarcity:Proprietary dye infusion techniques for plastic substrates require specialized polymer chemistry talent concentrated among legacy Japanese and European producers.
- ISO 8980-3 certification complexity:Transmittance uniformity and fatigue resistance testing protocols demand capital-intensive metrology equipment for batch compliance verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Photochromic Lenses Market |
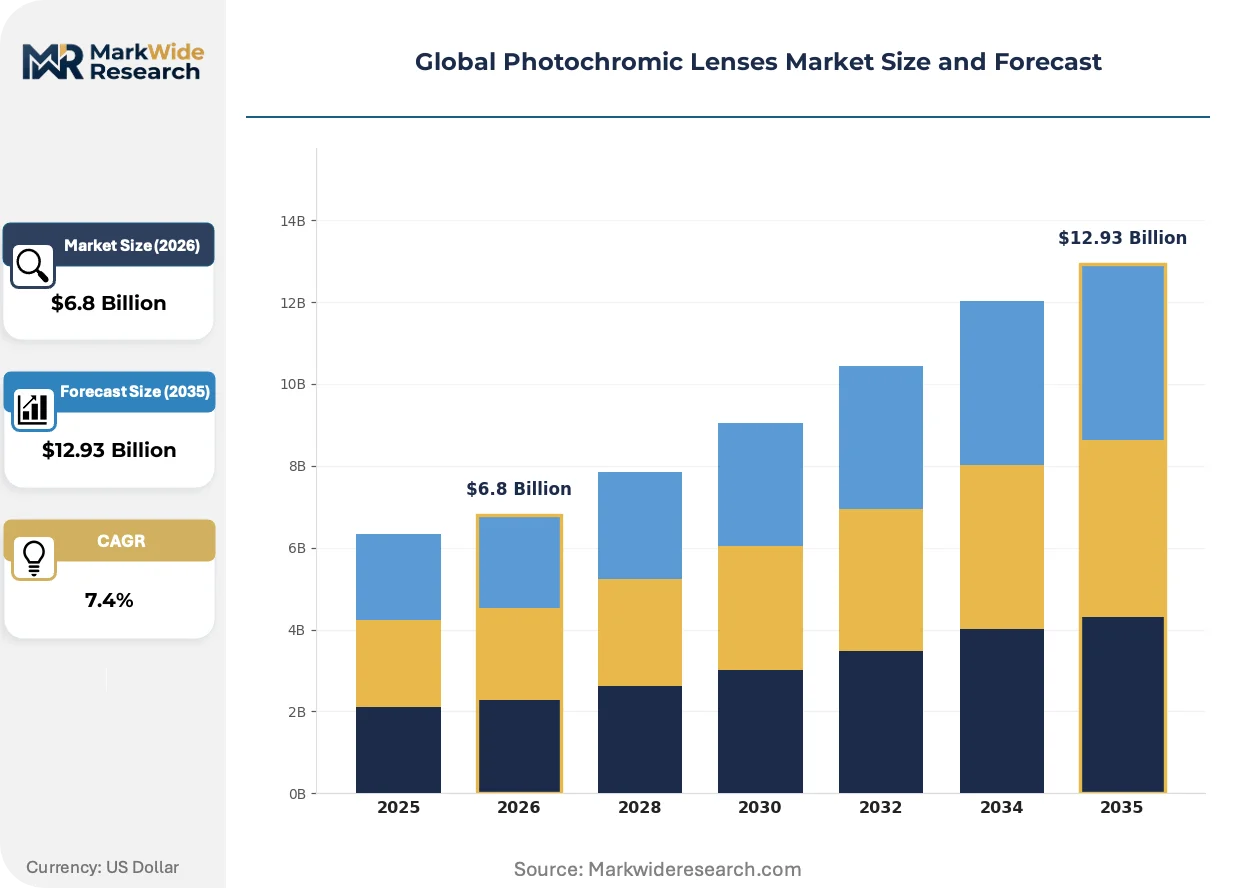
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Vision, Progressive, Bifocal, Trifocal, Reading, Safety Lens Material: Plastic, Polycarbonate, Trivex, Glass, High-Index, Nylon End User: Eyewear Retailers, Optometrists, Optical Laboratories, Vision Clinics, Specialty Stores, Online Retailers Application: Sunglasses, Prescription Glasses, Sports Eyewear, Fashion Eyewear, Protective Eyewear, Driving Glasses |
| Companies Covered | Transitions Optical, Corning Incorporated, EssilorLuxottica, Younger Optics, PPG Industries, Carl Zeiss AG, Rodenstock GmbH, Seiko Optical Products, Hoya Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Photochromic Lenses Market Shifts & Advancements
Organic naphthopyran chemistry is displacing silver halide formulations in plastic substrates, while regulatory frameworks in Europe and Asia-Pacific tighten material disclosure requirements beyond traditional ophthalmic safety standards.
Photochromic lens manufacturing is modularizing around substrate-agnostic dye application systems. Optical laboratories in Germany and Japan are adopting flexible imbibition equipment capable of switching between polycarbonate, high-index resin, and Trivex materials within single production runs. This equipment flexibility is modularizing supplier relationships, allowing mid-size labs to source dyes from multiple chemical producers without process revalidation.
Japan's PMDA quality management system requirements for imported optical devices now mandate ISO 13485 certification for all foreign manufacturing facilities. European lens exporters face expanded technical documentation demands including supply chain traceability for photochromic dye precursors. Small-batch specialty producers in Switzerland and South Korea are responding by establishing captive Tokyo-area warehousing to accelerate customs clearance.
Vision clinics are unbundling after-sales tint verification services from initial prescription fulfillment. Independent optometrists in France and Italy now charge separately for photochromic activation speed testing and transmittance certification, while retail chains bundle these services into premium warranty packages. This service bifurcation is most visible in Mediterranean markets where consumer protection regulations require explicit performance disclosures at point of sale.
Global Photochromic Lenses Market Segmentation
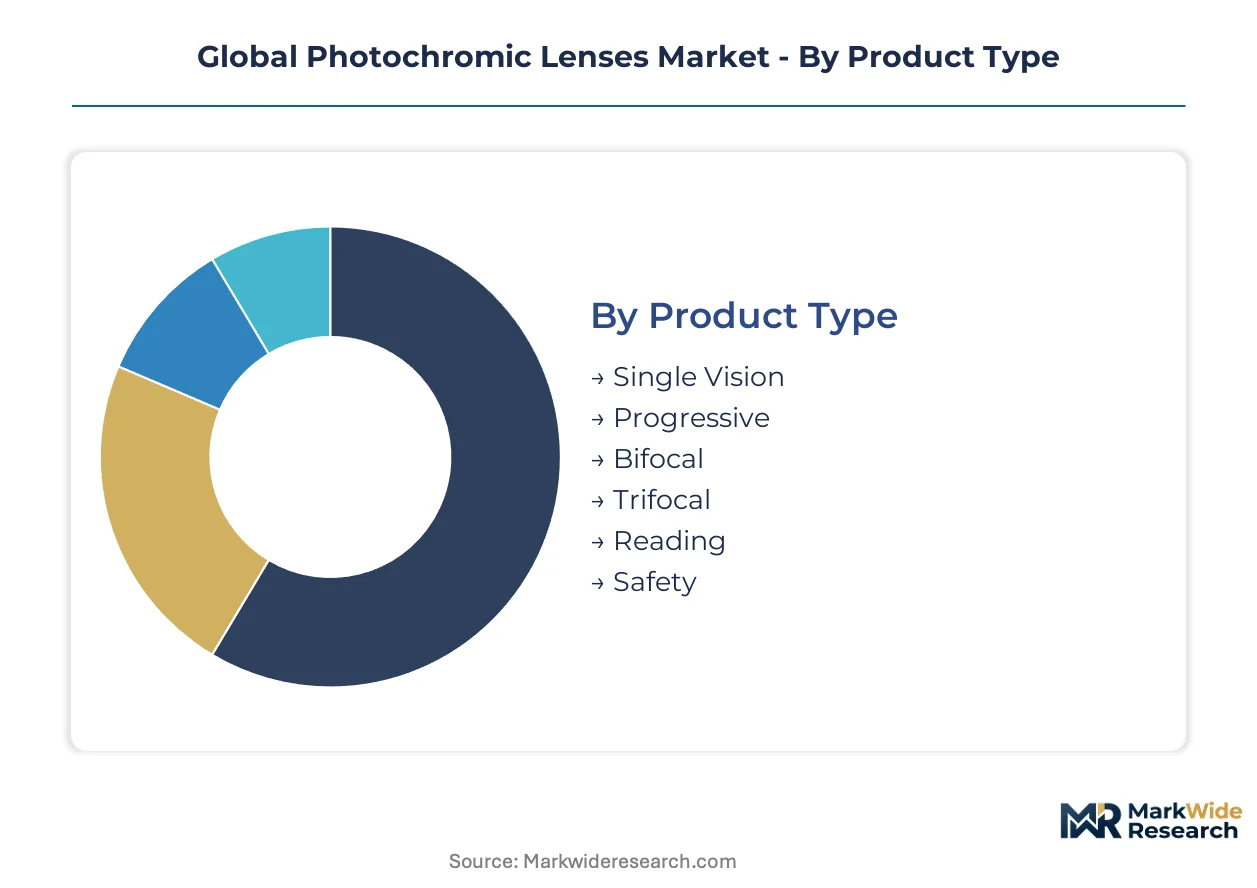
Photochromic lens purchasing decisions hinge on prescription complexity, material durability requirements, and distribution channel accessibility. Upgrade cycles vary dramatically across vision correction needs—from annual single-vision replacements to multi-year progressive lens investments—creating distinct margin profiles and customer lifetime value calculations for manufacturers.
Product Type:
Replacement frequency and prescription complexity drive upgrade-cycle differentiation across vision correction formats.
- Single Vision:Standard spherical or cylindrical correction for myopia, hyperopia, or astigmatism without multifocal elements. Mass-market optical retail chains in the United States and Germany prioritize inventory depth here due to highest turnover velocity and price-sensitive consumer segments.
- Progressive:Gradient multifocal design integrating distance, intermediate, and near correction zones without visible lines. Aging demographics in Japan and France pull premium positioning as presbyopia incidence rises among professionals requiring seamless focal transition for digital and physical tasks.
- Bifocal:Dual-segment design with distinct distance and reading zones separated by a visible line. Remains relevant in budget-conscious markets and occupational safety programs requiring simple near-distance alternation.
- Trifocal:Triple-segment construction adding dedicated intermediate correction for computer work. Niche adoption persists among specific industrial and administrative worker populations.
- Reading:Single-power magnification for near-vision tasks without distance correction. Over-the-counter availability and low price points concentrate volume in pharmacy and convenience retail channels.
- Safety:Impact-rated photochromic construction meeting ANSI Z87.1 or EN 166 standards. Industrial procurement programs in manufacturing-heavy German regions and US Midwestern states specify these for compliance-driven replacement schedules.
Single Vision sits at the top of the volume ranking, with Progressive climbing the fastest.
Lens Material:
Weight, impact resistance, and refractive index requirements stratify material selection across end-use applications and cost tiers.
- Plastic:Standard CR-39 resin offering optical clarity and easy tintability at moderate weight. Dominates entry-to-mid-tier prescription fulfillment through independent optometrists and value-oriented retail chains.
- Polycarbonate:Thermoplastic polymer delivering superior impact resistance at half the weight of standard plastic. Sports and protective eyewear mandates in the United States, Germany, and Japan accelerate substitution here, with pediatric and industrial safety applications leading specification.
- Trivex:Urethane-based material combining polycarbonate-level impact resistance with superior optical clarity and lower density. Premium sports and rimless frame applications in Japanese and Swiss markets favor this for its drilling durability and chromatic aberration control.
- Glass:Mineral substrate with exceptional scratch resistance and optical precision. Declining share persists only in specialty high-power prescriptions and heritage luxury frames where weight tolerance exists.
- High-Index:Dense resin formulations enabling thinner profiles for strong prescriptions. Hoya Corporation's Tokyo-area complex anchors supply for severe myopia corrections across East Asian markets.
- Nylon:Flexible, shatter-resistant polymer dominant in wraparound sports frame designs. Brazilian and Australian outdoor recreation markets specify this for extreme-flexure durability.
Polycarbonate captures the steepest expansion trajectory as safety mandates proliferate, while Glass contracts toward specialty niches.
End User:
Channel control and service bundling determine margin capture and customer data access across the value chain.
- Eyewear Retailers:Chains like EssilorLuxottica's captive network in France and Italy control distribution depth through exclusive brand access and in-store optometric services. Volume concentration here enables manufacturer promotional programming and inventory financing leverage.
- Optometrists:Independent eye care professionals prescribing and dispensing with personalized fitting services. Patient relationship longevity supports premium progressive lens attachment rates and warranty attachment.
- Optical Laboratories:Wholesale surfacing and coating facilities serving retail accounts without captive manufacturing. German and Japanese labs are adopting flexible imbibition equipment for substrate-agnostic production.
- Vision Clinics:Medical-model practices emphasizing clinical outcomes over retail margin. Separate photochromic activation speed testing and transmittance certification services now generate ancillary revenue in Mediterranean markets.
- Specialty Stores:Niche retailers focusing on sports, fashion, or occupational segments. Curated assortment and technical expertise command price premiums for performance-oriented materials.
- Online Retailers:Direct-to-consumer platforms bypassing traditional optical retail markups. Price-sensitive single-vision purchasers and repeat buyers with stable prescriptions concentrate here, though progressive lens complexity limits penetration.
Eyewear Retailers hold the largest volume position, with Online Retailers expanding most quickly through prescription platform technology.
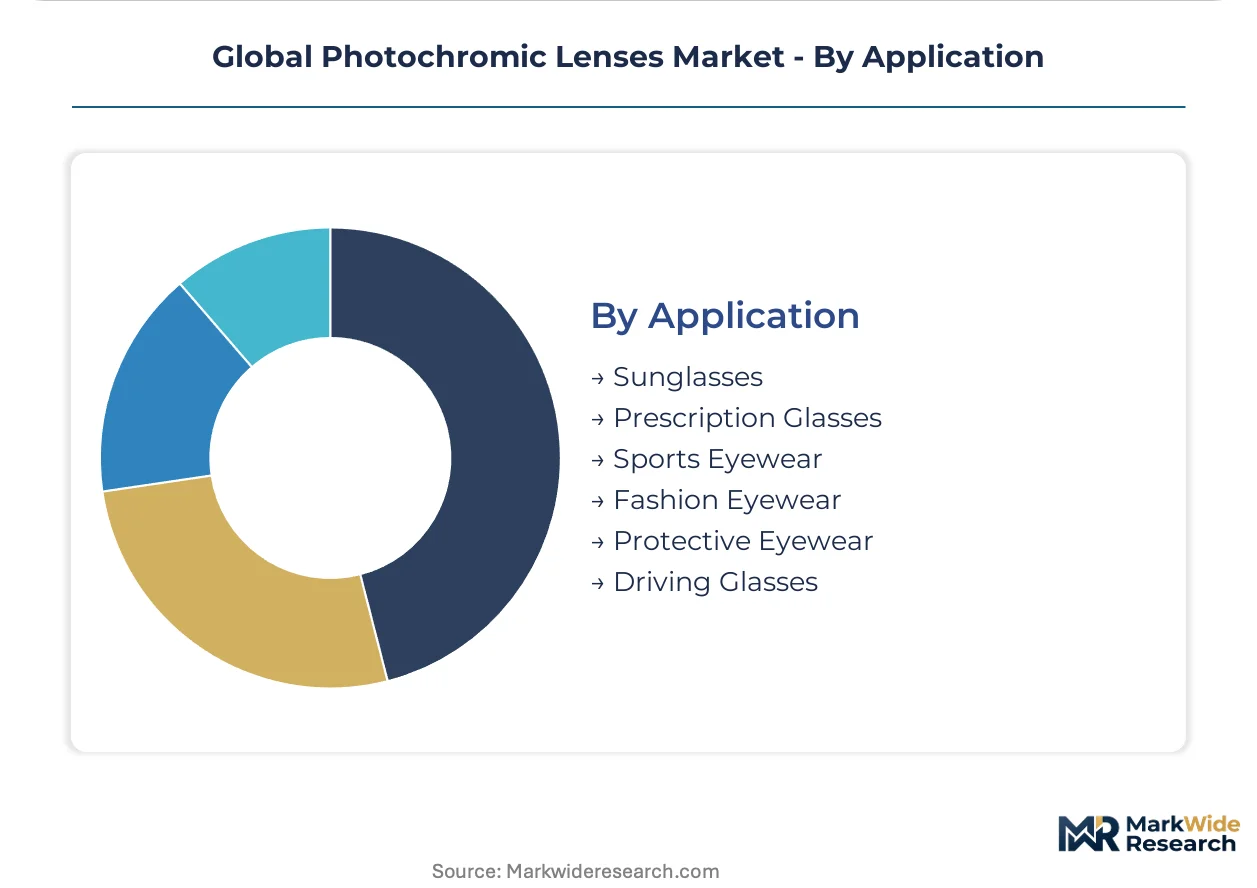
Application:
Functional use case dictates performance specifications, regulatory requirements, and replacement cycle timing.
- Prescription Glasses:Dual-purpose vision correction with adaptive tint for daily wear. Dominant application channel as consumers consolidate sunglass and corrective lens purchases; REACH compliance in Europe and FDA ophthalmic device standards govern material disclosure and biocompatibility.
- Sunglasses:Non-corrective photochromic designs for fashion and recreational use. Competes against fixed-tint alternatives on convenience and UV protection versatility.
- Sports Eyewear:Impact-rated construction for athletic activity with secure retention and ventilation features. Polycarbonate and Trivex concentration here aligns with ASTM F803 and EN 174 standards for ball and racquet sports.
- Fashion Eyewear:Style-driven frames prioritizing aesthetic tint behavior and brand positioning. Seasonal collection cycles accelerate replacement compared to functional categories.
- Protective Eyewear:Industrial and occupational compliance products meeting specific hazard ratings. Mandatory replacement programs in manufacturing and construction create predictable demand patterns.
- Driving Glasses:Optimized activation range for automotive windscreen UV filtration conditions. Specialized naphthopyran formulations address the reduced UV transmission through laminated glass that slows standard photochromic response.
Prescription Glasses leads absolute volume, with Sports Eyewear gaining share fastest through protective mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting photochromic lens fabrication toward jurisdictions with streamlined chemical disclosure frameworks. Manufacturers now optimize production footprints across compliance-cost gradients rather than raw material proximity alone.
United States
FDA ophthalmic device standards govern biocompatibility testing and optical power accuracy certification. Pediatric polycarbonate mandates and sports protective eyewear regulations accelerate material substitution in industrial Midwestern states. EssilorLuxottica's captive retail network concentrates distribution control through metropolitan optical chains.
Germany
REACH compliance and ECHA hazardous substance disclosure requirements impose stringent coating chemistry documentation. Optical laboratories in Bavaria and Baden-Württemberg deploy flexible imbibition equipment for substrate-agnostic production runs. Carl Zeiss AG and Rodenstock GmbH anchor high-precision manufacturing clusters around Stuttgart and Munich.
Japan
PMDA quality management system requirements and ISO 13485 certification mandates govern imported optical device clearance. Hoya Corporation's Tokyo-area complex dominates high-index photochromic output for severe myopia corrections. Japanese optical resin producers restructure supply chains to reduce dependence on imported dye precursors.
France
ANSM clinical device oversight and evolving EU MDR frameworks tighten material traceability requirements. Mediterranean consumer protection regulations mandate explicit photochromic performance disclosures at point of sale. Independent optometrists in Paris and Lyon unbundle after-sales tint verification services from initial prescription fulfillment.
India
PLI scheme incentives for medical device manufacturing attract lens fabrication investment toward domestic production. CDSCO quality standards and BIS optical product specifications govern market entry for imported substrates. Vision correction demand concentrates in Maharashtra and Karnataka urban corridors.
Global Photochromic Lenses Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty substrate and direct-to-consumer prescription platforms. The vendor base stratifies across captive retail networks, independent laboratory suppliers, and chemical technology licensors. Three archetypes dominate: integrated optical conglomerates controlling distribution depth; specialized dye chemistry houses licensing imbibition processes; and regional fabrication labs serving fragmented optometrist channels. Competitive moves concentrate on backward integration into dye precursor production and geographic expansion through online prescription platforms.
Among integrated optical conglomerates, EssilorLuxottica and Hoya Corporation exemplify the retail-captive model. Transitions Optical occupies a position as the technology-licensing archetype. Carl Zeiss AG and Rodenstock GmbH represent precision-manufacturing specialists serving premium vision correction segments. These named entities anchor the competitive structure without exhausting the participant universe.
| Leading Market Players |
|---|
| Transitions Optical |
| Corning Incorporated |
| EssilorLuxottica |
| Younger Optics |
| PPG Industries |
| Carl Zeiss AG |
| Rodenstock GmbH |
| Seiko Optical Products |
| Hoya Corporation |
| Others |
Supply & Pricing Matrix
Silver halide spot indices and naphthopyran precursor contract rates cascade through photochromic lens manufacturing into three distinct pricing tiers that separate premium progressive designs from standard single-vision offerings and economy safety-grade volumes. Buyers in Germany and Japan absorb elevated coating chemistry costs driven by REACH disclosure mandates, while US optical retail chains negotiate volume rebates that compress margins for mid-tier polycarbonate substrates.
Pricing Analysis
Retailer markup layers dominate final consumer pricing, with independent optometrists capturing premium attachment rates for progressive lens warranties while online direct-to-consumer platforms strip out fitting service costs to target price-sensitive single-vision repeat purchasers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 8980-3 certification grade, volume scale, and after-sales tint verification bundling. Cost compression in economy safety-grade segments intensifies as Indian PLI-subsidized fabrication capacity enters South Asian procurement channels. Vision clinics in Mediterranean markets exhibit lowest price sensitivity due to unbundled clinical service revenue, while online single-vision purchasers demonstrate highest elasticity.
Supply Chain Analysis
Direct-to-laboratory channels handle substrate-agnostic dye procurement for German and Japanese optical labs running flexible imbibition equipment, while captive retail networks in France and Italy source through exclusive manufacturer arrangements. Production gravity centers on Japan for high-index resin formulations, Germany for precision polycarbonate surfacing, and the United States for pediatric safety mandates. Silver halide crystals, organic naphthopyran dyes, and optical-grade monomers constitute critical input dependencies. Single-source vulnerability in Japanese dye precursor imports exposes East Asian fabricators to geopolitical disruption. Distribution runs through wholesale optical laboratories serving fragmented independent optometrists, integrated retail chains, and emerging direct-to-consumer prescription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photochromic lenses function as a stable compounder anchored by aging demographic pull for progressive multifocal correction across developed economies. Prescription complexity trends and protective eyewear mandate expansion sustain replacement cycle visibility.
For Market Incumbents: Cement technology leadership through proprietary imbibition process patent thickets and captive dye precursor production in Tokyo-area complexes. Backward integration into naphthopyran chemistry reduces exposure to imported precursor volatility. Channel control through exclusive retail network access in France and Italy defends margin position against direct-to-consumer platform erosion. ISO 13485 certification investment accelerates Japanese PMDA clearance timelines for imported substrate lines.
For New Entrants and Emerging Players: Capture white-space in Indian domestic manufacturing under PLI scheme incentives, where CDSCO quality standards and BIS specifications create barrier-filtered growth corridors. Online prescription platforms for stable single-vision corrections offer lowest customer acquisition friction compared to complex progressive fulfillment. Specialty sports eyewear segments in Brazil and Australia present penetrable niches where nylon substrate expertise commands premium positioning outside incumbent strongholds.
For Investors and Strategic Acquirers: Asymmetric upside sits with substrate-agnostic dye application technology licensors and regional fabrication labs serving fragmented optometrist channels in undersupplied South Asian corridors. Long-term viability hinges on regulatory compliance scalability across REACH, FDA, and PMDA frameworks. Acquisition targets should demonstrate captive retail network relationships or proprietary chemistry IP. Blue-light filtration convergence with photochromic activation serves as the signal to watch for technology inflection and premium tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dye Precursors | Captive naphthopyran supply reduces Japanese producers' import dependency and stabilizes input cost volatility. |
| Flexible Imbibition Equipment Deployment | German and Japanese labs switch between polycarbonate, Trivex, and high-index materials within single production runs. |
| Direct-to-Consumer Platform Launch | Online prescription technology bypasses traditional optical retail markups for price-sensitive single-vision purchasers. |
| ISO 13485 Certification Investment | Foreign manufacturers accelerate Japanese PMDA quality management system clearance for imported optical devices. |
| Blue-Light Filtration Convergence | Dual-function value propositions target screen-intensive professional segments with digital eye strain mitigation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with optical laboratory managers, independent optometrists, lens coating R&D directors, retail chain procurement leads, and regulatory affairs specialists at ophthalmic device manufacturers with secondary validation against FDA 510(k) filings, ECHA REACH registration databases, PMDA quality management system notifications, SEC 10-K optical segment disclosures, and customs trade data for photochromic dye precursor flows. Bottom-up prescription volume modeling and top-down ophthalmic device market sizing were cross-checked for triangulation.
Historical reference periods anchored the projection horizon through observed replacement cycle patterns across single-vision, progressive, and safety lens categories. Segmentation dimensions spanned prescription complexity tiers, lens material grades, distribution channel types, and regional regulatory clusters. CAGRs were derived from fitted growth curves calibrated to demographic presbyopia incidence and protective eyewear mandate adoption trajectories. Industry-specific inputs included ISO 8980-3 transmittance uniformity benchmarks and evolving blue-light filtration standard adoption rates.
Regulatory framework shifts, raw material price volatility, and activation speed technology breakthroughs are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding REACH compliance cost pass-through rates and online prescription platform penetration ceilings. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Automated Ophthalmic Perimeters Market
Ophthalmology
Anterior Uveitis Market
Ophthalmology
Ophthalmic Eye Shield Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Tobramycin Eye Drop Market
Ophthalmology
Amblyopia Treatment Market
Ophthalmology
India Ophthalmic Clinical Trials Market
Ophthalmology
Ophthalmic Eye Drops Market
Ophthalmology
Cataract Treatment Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Global Ophthalmic Equipment Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Ophthalmic Femtosecond Lasers Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Non-Infectious Uveitis Treatment Market
Ophthalmology
Synoptophore Market