
 Leber Congenital Amaurosis Market | 2026-2036
Leber Congenital Amaurosis Market Size, Share, and Industry Trends Forecast 2026-2036
Leber Congenital Amaurosis Market Outlook
The divergence between premium gene therapy interventions and commodity supportive care is realigning how stakeholders allocate R&D capital and pricing power across the Leber Congenital Amaurosis landscape. Spark Therapeutics leverages its pioneering FDA-approved gene therapy platform to sustain first-mover advantage in viral vector delivery. Novartis anchors its position through integrated ophthalmology networks, while Editas Medicine competes on CRISPR-based editing precision for inherited retinal diseases.
Leber Congenital Amaurosis constitutes a severe inherited retinal dystrophy caused by mutations in genes such as RPE65, CEP290, or GUCY2D, typically presenting at birth with nystagmus, poor pupillary response, and profoundly reduced vision; its primary clinical purpose centers on preserving or restoring photoreceptor function through targeted genetic intervention. Gene therapy commands the dominant value pool given curative intent and premium pricing dynamics, while diagnostic tools represent the fastest-expanding segment driven by newborn screening expansion and carrier detection programs. Viral vector technology leads current commercialization, though CRISPR platforms attract accelerating development investment for broader mutational coverage.
FDA breakthrough therapy designation and EMA priority medicines pathways shape trial enrollment speed and post-approval monitoring obligations for developers in this space. Reimbursement negotiations with national health technology assessment bodies in Germany, France, and England determine patient access thresholds and manufacturer revenue realization. Stakeholders must monitor evolving gene therapy durability data and competing CRISPR clinical readouts to inform portfolio prioritization and partnership timing.
Market Dynamics
The FDA breakthrough therapy designation is compressing clinical trial timelines for inherited retinal disease programs, forcing developers to accelerate manufacturing scale-up before durability data matures.
Growth Catalysts
- Newborn Screening Expansion:State-level mandates in the United States are expanding RPE65 mutation detection, creating addressable patient pools before photoreceptor degeneration advances.
- EMA Priority Medicines Pathway:European developers gain accelerated assessment timelines, reducing regulatory capital requirements for gene therapy commercialization.
- Adeno-Associated Virus Manufacturing:Contract development organizations are scaling suspension-based production, lowering per-dose viral vector costs for ophthalmology applications.
Market Restraints
- Single-Dose Pricing Architecture:Curative gene therapies require upfront cost recovery without recurring revenue, straining payer budget impact models.
- Vector Immunogenicity:Pre-existing neutralizing antibodies against AAV serotypes exclude substantial patient populations from treatment eligibility.
- Specialized Treatment Center Concentration:Qualified retinal surgery infrastructure clusters in major metropolitan areas, limiting rural and exurban patient access.
Strategic Opportunities
- Japan's Regenerative Medicine Framework:Conditional approval pathways enable earlier commercial entry with post-market efficacy confirmation.
- CRISPR-Base Editing Convergence:Cytosine and adenine base editors enable precise correction of point mutations beyond viral vector packaging limits.
- Teleophthalmology Screening Networks:Remote retinal imaging platforms extend diagnostic reach into underserved regions, accelerating referral to treatment centers.
Industry Challenges
- Retinal Surgeon Training Bottlenecks:Subretinal injection techniques require specialized surgical fellowship programs, constraining treatment throughput.
- Long-Term Durability Monitoring:Decade-long follow-up obligations for gene therapy recipients impose sustained pharmacovigilance infrastructure costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leber Congenital Amaurosis Market |
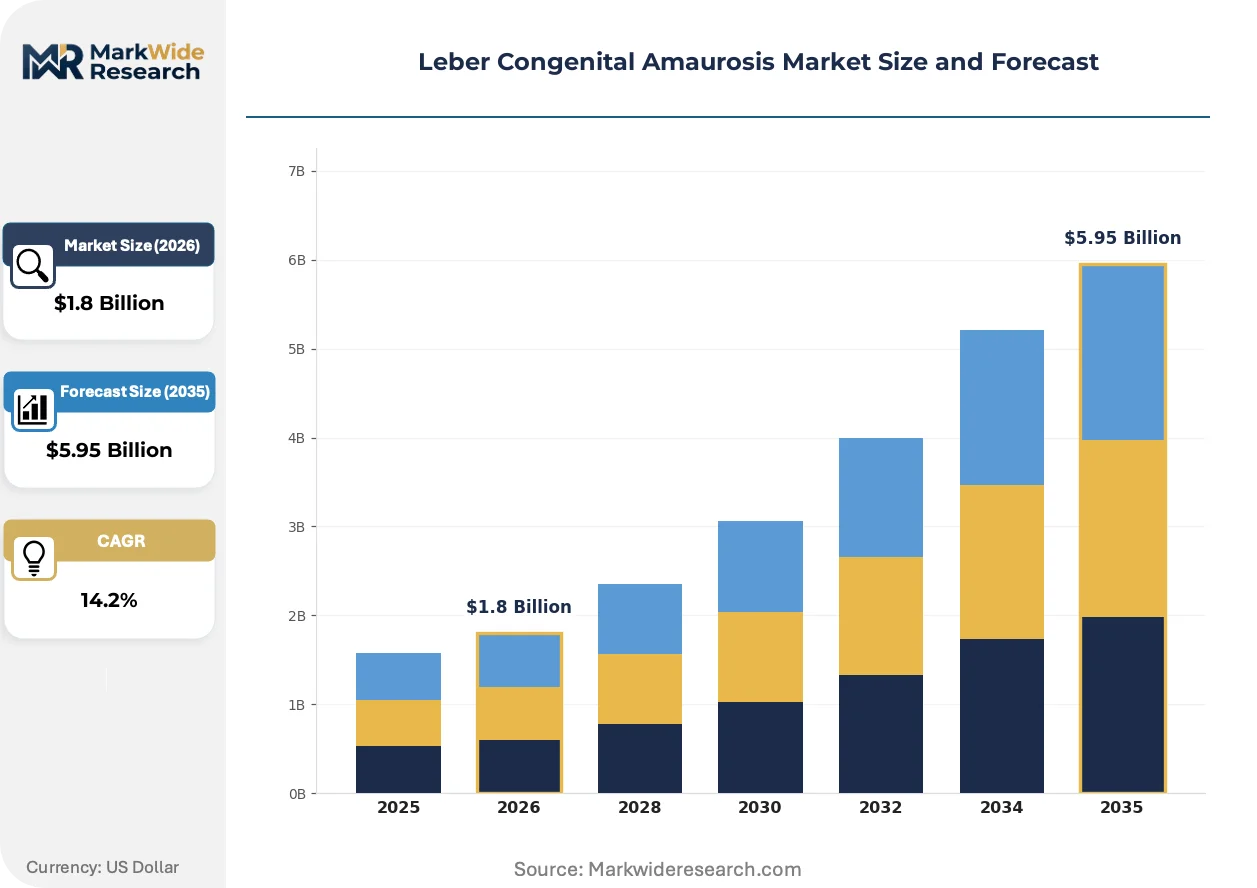
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Surgical Intervention, Diagnostic Tools, Supportive Care Application: Clinical Research, Patient Management, Genetic Testing, Patient Education End User: Hospitals, Specialty Clinics, Research Institutions, Rehabilitation Centers Technology: CRISPR, Viral Vectors, Next-Generation Sequencing, Retinal Implants |
| Companies Covered | Spark Therapeutics, Novartis, Biogen, GenSight Biologics, ProQR Therapeutics, Atsena Therapeutics, Editas Medicine, Ocugen, Regeneron Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leber Congenital Amaurosis Market Strategic Shifts
Gene therapy platforms are absorbing manufacturing innovations from oncology cell therapy, while regulatory frameworks adapt to single-administration curative models. Three developments are restructuring competitive positioning.
Dual-vector systems for oversized transgenes are absorbing split-intein protein engineering approaches, enabling delivery of coding sequences exceeding single AAV capacity. Pediatric ophthalmology centers in Germany and the United States are piloting these systems for CEP290-related ciliopathies. The technology is absorbing prior investment in modular protein design, compressing development timelines for mutations previously deemed undruggable.
EMA's adaptive pathways framework is enabling staggered approval for gene therapies with preliminary efficacy signals, requiring real-world evidence generation post-authorization. Developers must build patient registries and digital health monitoring infrastructure to satisfy continued benefit-risk verification. Ophthalmology programs with European Medicines Agency rapporteur engagement are restructuring phase III endpoints to incorporate functional vision metrics rather than surrogate anatomical measures.
Integrated delivery networks are consolidating procurement authority for high-cost gene therapies, shifting purchasing decisions from individual physicians to pharmacy and therapeutics committees. Children's hospitals in the United States are forming regional buying consortia to negotiate outcome-based reimbursement arrangements. This concentration is most visible in the Northeast corridor, where academic medical centers coordinate prior authorization submissions and patient travel logistics.
Leber Congenital Amaurosis Market Segmentation
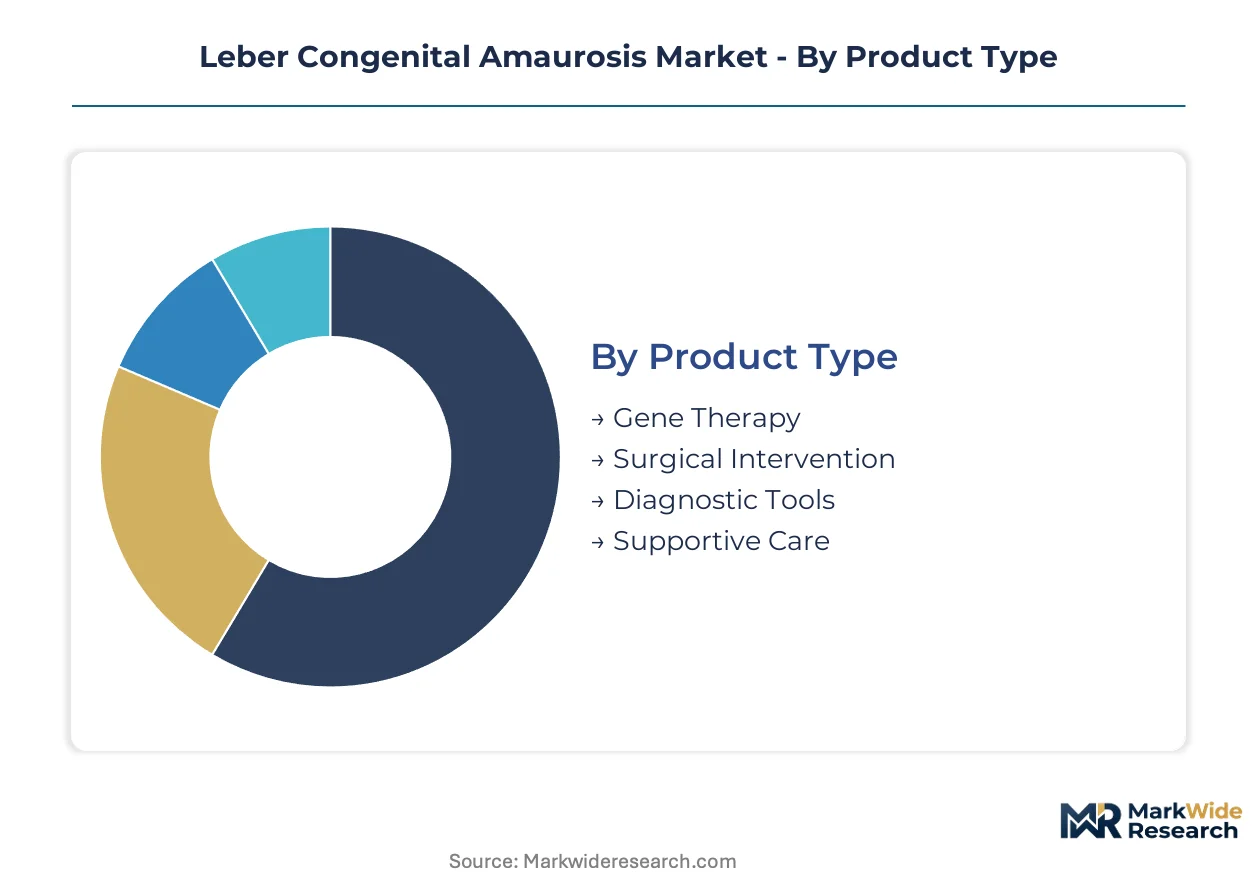
Segmentation in the Leber Congenital Amaurosis market reveals how regulatory pathways, reimbursement structures, and clinical infrastructure concentrate value across distinct product and service categories. Understanding these divisions enables stakeholders to align development resources with segments offering viable commercial entry points.
Product Type:
FDA breakthrough therapy designation and EMA priority medicines pathways impose differentiated certification burdens across therapeutic modalities, with gene therapies facing the most extensive pre-approval manufacturing validation and post-market surveillance obligations.
- Gene Therapy:Adeno-associated viral vectors deliver functional gene copies directly to retinal pigment epithelium. Demand concentrates in pediatric ophthalmology centers across the United States, Germany, and Japan where specialized surgical infrastructure and favorable reimbursement frameworks support single-administration curative interventions.
- Diagnostic Tools:Next-generation sequencing panels and electroretinography systems enable early mutation detection before photoreceptor degeneration advances. Newborn screening mandates in multiple United States states are expanding addressable patient pools for RPE65 and CEP290 mutation identification.
- Surgical Intervention:Subretinal injection procedures and vitrectomy techniques support gene therapy delivery.
- Supportive Care:Low-vision aids and orientation mobility services address functional impairment in non-candidates for genetic intervention.
Leading the category by volume: Gene Therapy. Growing fastest: Diagnostic Tools.
Application:
Cost tier stratification separates capital-intensive clinical research programs from recurring-revenue patient management services, with genetic testing occupying an intermediate position dependent on laboratory throughput scale.
- Clinical Research:Phase I/II trials for novel viral vectors and CRISPR platforms require substantial investigator-initiated funding and specialized retinal imaging endpoints. Academic medical centers in Boston and Philadelphia anchor United States trial enrollment through established inherited retinal disease registries.
- Patient Management:Longitudinal care coordination spans genetic counseling, surgical scheduling, and post-treatment monitoring. Children's hospitals in the Northeast corridor are consolidating procurement authority through regional buying consortia.
- Genetic Testing:Carrier screening and prenatal diagnosis programs.
- Patient Education:Digital health platforms and family support networks.
Clinical Research commands the highest per-patient expenditure. Patient Management delivers the most stable recurring revenue streams.
End User:
Customer type concentration reflects where qualified surgical expertise and gene therapy administration infrastructure actually exist, creating severe access constraints outside major metropolitan academic centers.
- Hospitals:Tertiary care institutions with dedicated ophthalmology departments and subretinal injection capabilities. Demand clusters in urban United States markets where FDA-approved therapies have established reimbursement codes and prior authorization pathways.
- Specialty Clinics:Retina-focused outpatient facilities offering diagnostic screening and referral coordination. Germany's integrated care networks and Japan's conditional approval framework enable earlier commercial access than fragmented United States clinic systems.
- Research Institutions:University-affiliated centers conducting natural history studies and registry development.
- Rehabilitation Centers:Low-vision training and adaptive technology services for irreversible cases.
Hospitals capture the majority of gene therapy revenue. Specialty Clinics are expanding fastest as screening networks decentralize.
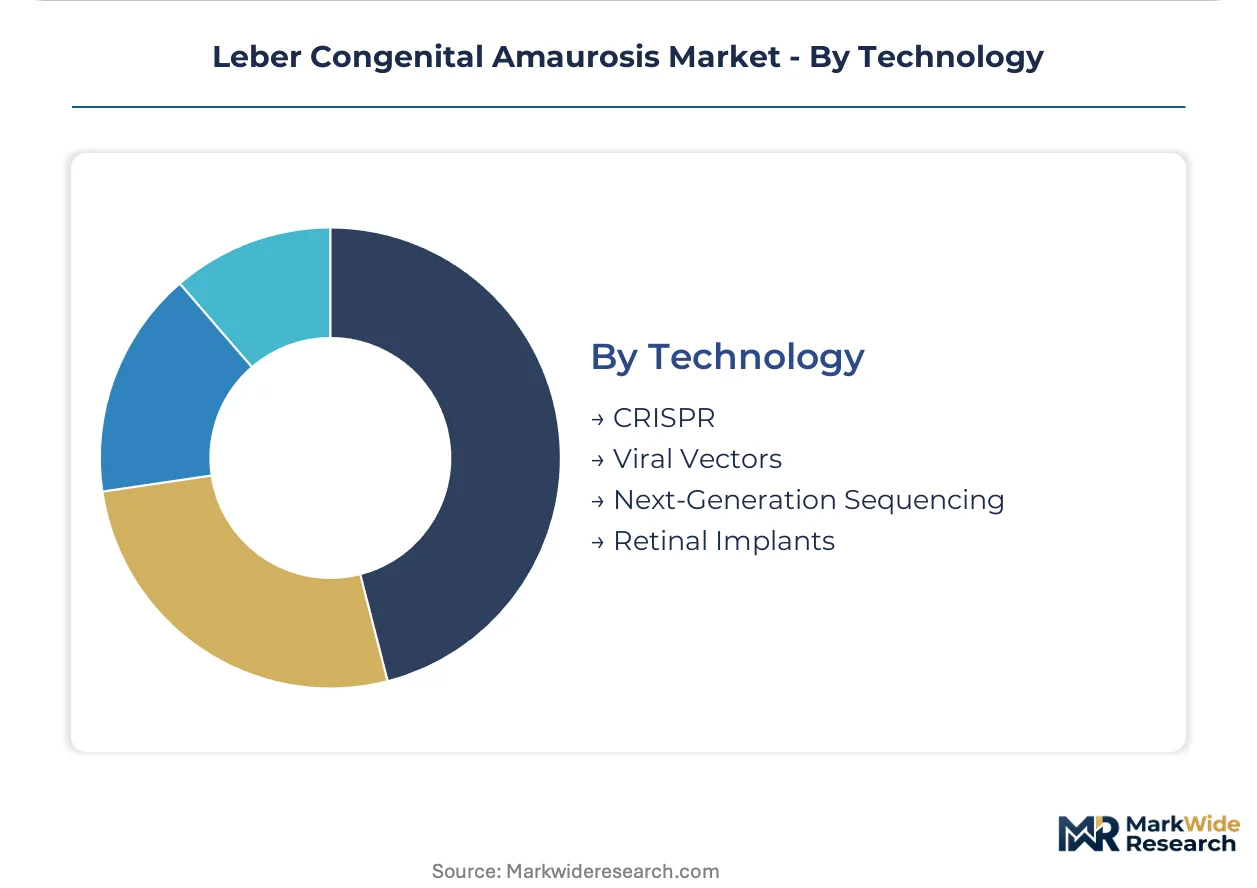
Technology:
Supply concentration in viral vector manufacturing creates bottlenecks for first-generation platforms, while CRISPR-based approaches attract development investment for mutations exceeding single AAV packaging capacity.
- Viral Vectors:Adeno-associated virus serotypes 2 and 5 dominate commercial gene delivery, with suspension-based manufacturing scaling at contract development organizations to reduce per-dose costs. Pre-existing neutralizing antibodies exclude substantial patient populations from eligibility.
- CRISPR:Base editing platforms enable precise correction of point mutations without double-strand breaks. Editas Medicine and similar developers are advancing clinical programs for CEP290-related ciliopathies previously deemed undruggable with conventional gene replacement.
- Next-Generation Sequencing:Panel-based mutation detection for newborn screening expansion.
- Retinal Implants:Prosthetic devices for end-stage photoreceptor degeneration.
Viral Vectors retain dominant commercial position. CRISPR platforms show steepest expansion trajectory in development pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor anchors inherited retinal disease research concentration, with Philadelphia and Baltimore forming contiguous trial enrollment networks. Pediatric ophthalmology centers cluster where FDA breakthrough therapy pathways intersect with established gene therapy manufacturing infrastructure.
United States
Newborn screening mandates in Pennsylvania and Massachusetts expand RPE65 mutation detection pools. FDA breakthrough therapy designation compresses clinical trial timelines for viral vector programs. The Northeast corridor consolidates procurement through children's hospital buying consortia coordinating prior authorization and patient travel logistics.
Germany
EMA priority medicines pathways enable accelerated assessment timelines for gene therapy developers. Germany's national health technology assessment body shapes reimbursement thresholds for single-administration interventions. Heidelberg and Tübingen anchor integrated ophthalmology networks piloting dual-vector systems for CEP290-related ciliopathies.
Japan
Conditional approval frameworks under the regenerative medicine regulatory structure permit earlier commercial entry with post-market efficacy confirmation. PMDA engagement with ophthalmology programs restructures phase III endpoints toward functional vision metrics. Tokyo and Osaka concentrate qualified retinal surgery infrastructure for subretinal injection procedures.
United Kingdom
NICE technology appraisals determine patient access thresholds for premium gene therapies within NHS England. London's Moorfields Eye Hospital anchors inherited retinal disease registries supporting natural history studies. Oxford and Cambridge research institutions advance CRISPR base editing platforms for point mutation correction.
France
ANSM coordinates early access programs for innovative therapies targeting severe ophthalmologic conditions. Parisian academic hospitals concentrate surgical expertise for pediatric retinal interventions. Lyon and Strasbourg expand diagnostic screening networks through teleophthalmology platforms extending reach into underserved regions.
Leber Congenital Amaurosis Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Leber Congenital Amaurosis landscape, with viral vector manufacturers bearing manufacturing facility investments while CRISPR platform developers outsource production. The market structure concentrates around three strategic archetypes: integrated pharmaceutical conglomerates with ophthalmology networks, gene therapy specialists leveraging first-mover viral vector expertise, and genome editing innovators pursuing CRISPR-based precision. Dominant competitive moves include strategic partnerships for AAV manufacturing scale-up and geographic expansion into Japan's conditional approval framework.
Among gene therapy specialists, Spark Therapeutics and Editas Medicine occupy distinct archetype positions. Spark Therapeutics exemplifies the viral vector first-mover model with established FDA-approved platform infrastructure. Editas Medicine represents the CRISPR-based editing precision tier targeting mutations beyond conventional gene replacement capacity. Novartis anchors the integrated pharmaceutical conglomerate archetype through ophthalmology network integration and global commercial infrastructure.
| Leading Market Players |
|---|
| Spark Therapeutics |
| Novartis |
| Biogen |
| GenSight Biologics |
| ProQR Therapeutics |
| Atsena Therapeutics |
| Editas Medicine |
| Ocugen |
| Regeneron Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Viral vector manufacturing costs cascade through three-tier pricing structure across premium, standard, and economy levels, with suspension-based production scale-up at contract development organizations compressing per-dose expenses while FDA breakthrough therapy designation sustains premium capture for first-mover gene therapies. Payer budget impact models strain under single-dose curative architectures, forcing manufacturers to negotiate outcome-based reimbursement with integrated delivery networks.
Pricing Analysis
Value-based pricing anchored to functional vision outcomes dominates gene therapy reimbursement negotiations, with FDA-approved therapies commanding premium tiers against pre-approval CRISPR programs. Price differentiation separates breakthrough-designated viral vectors from diagnostic tools and supportive care, with certification through EMA priority medicines pathways enabling European premium capture. Cost compression in supportive care intensifies because integrated delivery networks consolidate procurement authority through children's hospital buying consortia. Academic medical centers show least price sensitivity due to research funding offsets, while rural specialty clinics face greatest budget constraints.
Supply Chain Analysis
Cold-chain logistics costs for viral vector shipments from United States, Germany, and Japan manufacturing sites elevate downstream pricing for pediatric ophthalmology centers outside major metropolitan clusters. Raw material dependencies center on plasmid DNA, cell culture media, and AAV serotype-specific packaging cell lines. Single-source vulnerability concentrates in contract development organizations with validated suspension-based production capacity. Distribution runs through regional buying consortia coordinating prior authorization and patient travel logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Leber Congenital Amaurosis market functions as a vertical-integration race, with manufacturers pursuing captive AAV production capacity to secure supply continuity and pricing control amid viral vector manufacturing bottlenecks.
For Market Incumbents: Anchor first-mover advantage through backward integration into suspension-based AAV manufacturing capacity in the United States and Germany, while building patient registries to satisfy FDA and EMA post-market surveillance obligations. CRISPR platform developers threaten gene replacement dominance; defend through dual-vector system investments for oversized transgene delivery. For New Entrants and Emerging Players: Capture white-space opportunity in teleophthalmology screening networks extending diagnostic reach into underserved United States rural regions and French exurban territories. Japan's conditional approval framework under PMDA regenerative medicine regulations offers most penetrable commercial entry point; pursue licensing partnerships with established ophthalmology networks rather than direct infrastructure buildout. For Investors and Strategic Acquirers: FDA breakthrough therapy designation awards to CRISPR-based programs are the leading indicator that base editing precision is displacing conventional gene replacement economics. Five-to-ten-year viability favors developers with diversified mutation coverage beyond RPE65. Target acquisition archetype: clinical-stage CRISPR platforms with CEP290 or GUCY2D programs and established PMDA engagement.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Suspension-based AAV production at CDMOs reduces per-dose costs for ophthalmology applications. |
| Regulatory Approval Pathway | EMA adaptive pathways framework enables staggered authorization with real-world evidence generation post-launch. |
| Pipeline Diversification | Dual-vector systems for CEP290 ciliopathies expand addressable mutations beyond single AAV packaging limits. |
| Strategic Partnership | Regional buying consortia in the Northeast corridor coordinate outcome-based reimbursement negotiations. |
| Reimbursement Strategy | NICE technology appraisals determine NHS England patient access thresholds for premium interventions. |
Study Parameters
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, supplemented by formulary database analysis and CMS Medicare reimbursement records. Primary interviews with gene therapy development executives, regulatory affairs leads at ophthalmology-focused biotechs, hospital procurement managers at children's hospitals, and payer access specialists provided operational validation. Bottom-up patient pool modeling across newborn screening expansion states triangulated with top-down market sizing from manufacturer revenue disclosures.
Historical trendline analysis of viral vector manufacturing capacity expansion and gene therapy approval timelines informed projection frameworks across the analysis window. Segmentation dimensions modeled include therapeutic modality, mutation target, pediatric versus adult indication, regional regulatory cluster, and treatment center infrastructure tier. CAGRs derived from slope analysis of comparable rare disease gene therapy adoption curves, adjusted for reimbursement negotiation timelines and surgeon training throughput constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CRISPR clinical readout durability and AAV immunogenicity exclusion rates. Forecasts reflect documented assumptions about newborn screening mandate expansion and conditional approval pathway utilization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Global Ophthalmology Market
Ophthalmology
Usher Syndrome Market
Ophthalmology
Retinoblastoma Treatment Market
Ophthalmology
Retina Health Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
United States Dry Eye Syndrome Market
Ophthalmology
Blepharitis Treatment Market
Ophthalmology
Global Hemianopsia Market
Ophthalmology
Global Anterior Uveitis Treatment Market
Ophthalmology
Vision Care Market
Ophthalmology
Lazy Eye Market
Ophthalmology
Dacryocystitis Market
Ophthalmology
Uveal Melanoma Market
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
Light Therapy Glasses Market