
 Global Continuous Glucose Monitoring Systems Market | 2026-2036
Global Continuous Glucose Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Continuous Glucose Monitoring Systems Market Foresight
The continuous glucose monitoring category is pivoting on a widening performance gap between factory-calibrated premium sensors and calibration-dependent commodity alternatives. Abbott Laboratories leverages its freestyle portfolio to dominate pharmacy and retail channels across North America and Western Europe. Dexcom sustains R&D intensity through iterative transmitter miniaturization and algorithm refinement. Medtronic anchors its position through backward integration into insulin pump ecosystems, creating captive demand for its Guardian sensor platform.
Continuous glucose monitoring systems comprise wearable electrochemical biosensors that interstitial fluid glucose levels via enzymatic glucose oxidase reactions, transmitting data to receivers or smartphones at one- to five-minute intervals for real-time glycemic management. Real-time CGM leads volume shipments due to endocrinologist preference for automated alerts, while intermittent scanning CGM captures price-sensitive Type 2 diabetes segments through lower per-test costs. Mobile integrated technology represents the fastest-expanding technology dimension as Bluetooth-enabled transmitters pair with cloud-connected analytics platforms for remote patient monitoring.
FDA premarket notification pathways and EU MDR technical documentation requirements shape product development timelines and market access barriers for new entrants. The EPA governs disposal frameworks for sensor electronics and battery components, adding compliance costs to hardware manufacturing. Stakeholders must monitor reimbursement parity negotiations between CGM manufacturers and national health technology assessment bodies, as coverage decisions for non-intensive insulin users will determine addressable market expansion beyond current prescribing boundaries.
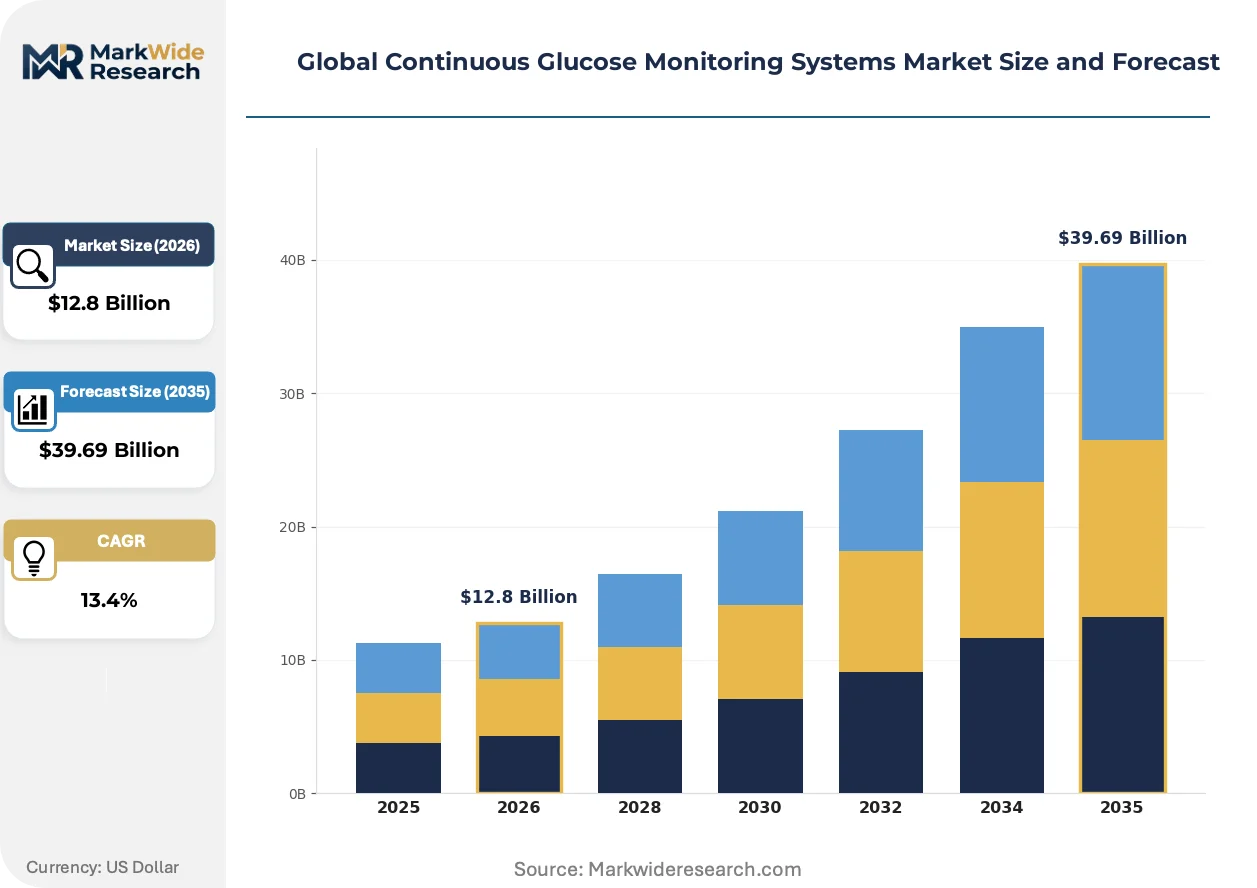
Market Dynamics
Factory-calibrated electrochemical sensor architectures are compressing calibration-dependent alternatives, creating a bifurcation between premium real-time systems and price-accessible intermittent scanning formats. This technical divergence is restructuring reimbursement negotiations and channel access across hospital, pharmacy, and direct-to-consumer pathways.
Growth Catalysts
- EU MDR Compliance Deadlines:Accelerated technical documentation requirements for Class III medical devices are compressing certification timelines for established manufacturers, raising barriers for new entrants and consolidating market access.
- Home Healthcare Provider Expansion:Remote patient monitoring platforms in the United States and Germany are integrating Bluetooth-enabled transmitters with cloud analytics, expanding prescribing boundaries beyond intensive insulin users.
- Enzymatic Glucose Oxidase Miniaturization:Advances in microelectrode fabrication are enabling 14-day wear durations and reduced form factors, improving patient adherence metrics and reducing per-test costs.
Market Restraints
- Platinum Group Metal Input Volatility:Electrochemical sensor electrodes depend on platinum and ruthenium composites, exposing manufacturers to commodity price swings and supply concentration from South African and Russian mining operations.
- FDA Premarket Notification Friction:510(k) pathway requirements for substantial equivalence demonstrations create 12-18 month lead times for algorithm updates and transmitter hardware revisions.
- Intermittent Scanning Substitution:Flash glucose monitoring systems capture price-sensitive Type 2 diabetes segments with lower per-test economics, compressing real-time CGM volume in pharmacy channels.
Strategic Opportunities
- Japan's Aging Demographics:METI reimbursement expansion for non-intensive insulin users in Japan's prefectural health systems represents underpenetrated demand for factory-calibrated sensors.
- Insulin Pump Ecosystem Convergence:Closed-loop algorithm integration between CGM transmitters and automated insulin delivery systems creates captive demand through hardware-software bundling.
- Pharmacy Channel Disintermediation:Direct-to-consumer subscription models in the United States bypass traditional durable medical equipment distributors, capturing margin and patient data assets.
Industry Challenges
- Biocompatibility Engineering Talent Scarcity:Electrochemical sensor development requires specialized expertise in enzymatic stability and interstitial fluid interface design, constraining R&D throughput.
- EU MDR Notified Body Capacity Bottlenecks:Technical documentation review queues for Class III devices extend certification timelines, delaying product launches and freezing pipeline investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Continuous Glucose Monitoring Systems Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $39.69 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Real-Time CGM, Intermittent Scanning CGM, Professional CGM, Implantable CGM Technology: Sensor-Based, Transmitter Technology, Mobile Integrated, Cloud-Connected, Bluetooth Enabled Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes, Hypoglycemia Management End User: Endocrinologists, Diabetologists, Home Healthcare, Ambulatory Care, Long-Term Care Facilities |
| Companies Covered | Abbott Laboratories, Dexcom, Medtronic, F. Hoffmann-La Roche, Senseonics Holdings, Ascensia Diabetes Care Holdings, i-SENS, Medtrum Technologies, Zhejiang POCTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Continuous Glucose Monitoring Systems Market Shifts & Advancements
Algorithmic glucose prediction and disposable sensor miniaturization are converging to compress the performance gap between invasive and non-invasive monitoring paradigms. These technical trajectories are reshaping competitive positioning across hospital, ambulatory, and consumer channels.
Multi-sensor fusion architectures are modularizing glucose monitoring hardware. Wearable platforms now integrate electrochemical biosensors with accelerometry and temperature compensation algorithms to reduce false alert rates. Endocrinology practices in Germany and the United States are adopting these systems for automated insulin dosing protocols. This convergence is modularizing the traditional separation between sensing hardware and decision-support software, enabling third-party algorithm licensing.
FDA breakthrough device designation pathways are compressing review timelines for pediatric and pregnancy-specific glucose monitoring indications. The program's expedited access framework prioritizes real-world evidence collection over traditional pivotal trial designs. Manufacturers targeting Type 1 diabetes management in adolescent populations are restructuring clinical development programs to align with this regulatory channel.
Subscription-based hardware refresh models are displacing durable medical equipment procurement in United States pharmacy benefit structures. Patients receive automated transmitter and sensor shipments without point-of-sale cost exposure, while payers capture adherence data for risk adjustment. This consumption-pattern shift is most visible in employer-sponsored health plans and Medicare Advantage networks seeking remote monitoring quality metrics.
Global Continuous Glucose Monitoring Systems Market Segmentation
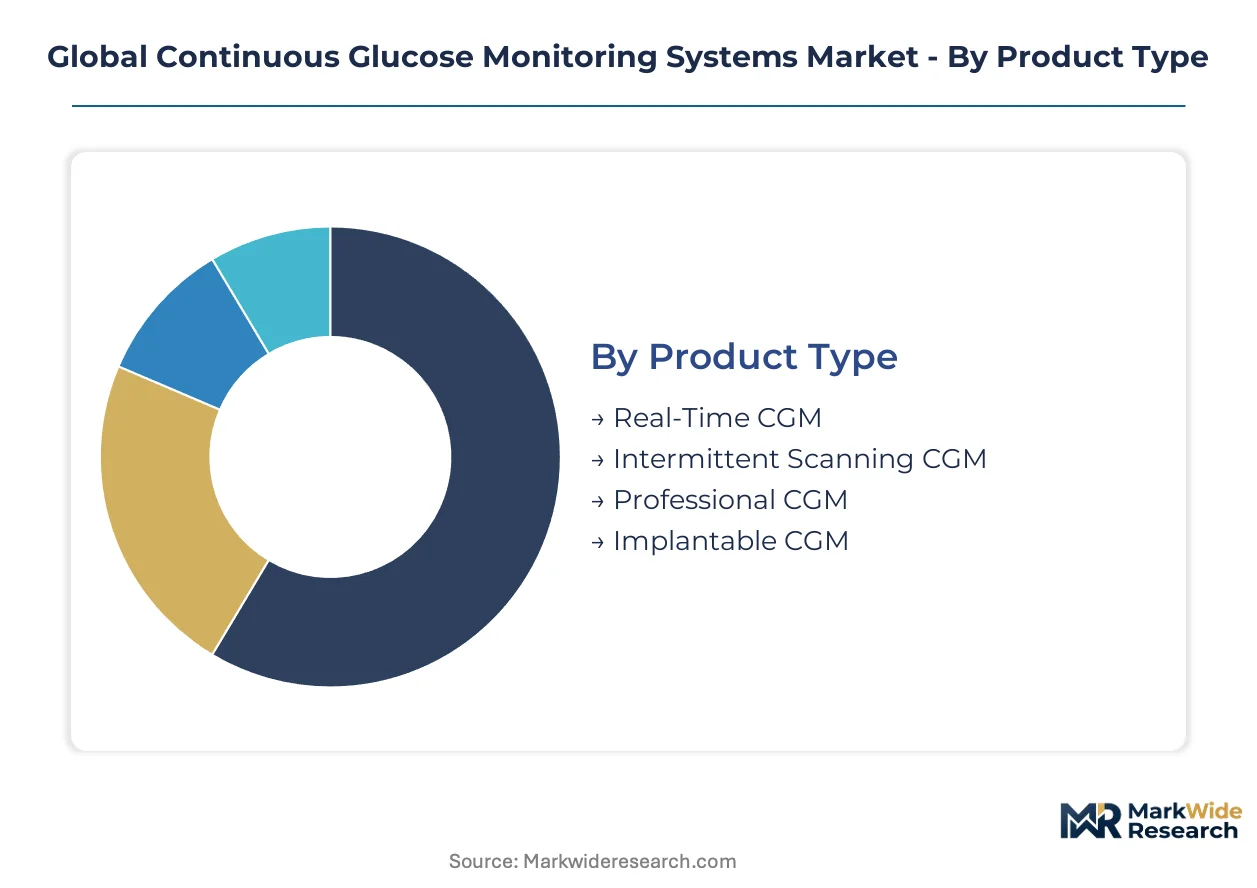
CGM market segmentation reveals divergent technical architectures serving distinct glycemic management intensities. Product format selection determines calibration burden, wear duration, and data transmission protocols that shape reimbursement eligibility and channel economics.
Product Type:
Electrochemical sensor architectures differentiate on real-time versus on-demand data availability, creating distinct cost-accessibility tradeoffs across patient populations.
- Real-Time CGM:Factory-calibrated enzymatic glucose oxidase sensors transmit interstitial glucose readings at one- to five-minute intervals to dedicated receivers or smartphones. Hospital systems in the United States and Germany prioritize these systems for automated insulin dosing protocols due to predictive alert algorithms.
- Intermittent Scanning CGM:Flash monitoring formats require manual sensor scans via handheld readers or NFC-enabled smartphones, trading continuous data streams for reduced per-test economics. Price-sensitive Type 2 diabetes patients in Japan's prefectural health systems drive volume adoption where reimbursement parity remains partial.
- Professional CGM:Clinic-deployed diagnostic sensors capture retrospective glucose profiles over 72- to 144-hour wear periods for treatment optimization.
- Implantable CGM:Long-duration subcutaneous sensors reduce replacement frequency through hermetically sealed optical or enzymatic architectures.
Mature deployment sits with Real-Time CGM. Newer deployment is concentrated in Intermittent Scanning CGM.
Technology:
Hardware-software integration depth determines patient adherence metrics and remote monitoring scalability for payers.
- Sensor-Based:Electrochemical microelectrode arrays with platinum-ruthenium composite catalysts form the core glucose detection layer. Manufacturing scale constraints from South African platinum supply concentration elevate input cost volatility for all downstream formats.
- Transmitter Technology:Miniaturized radiofrequency or Bluetooth Low Energy modules bridge sensor-to-receiver communication. Dexcom and Abbott Laboratories compete through iterative transmitter footprint reduction that extends wear comfort duration.
- Mobile Integrated:Native smartphone applications replace dedicated receivers, collapsing hardware procurement costs. FDA 510(k) clearance for iOS and Android pairing algorithms accelerates pharmacy channel penetration.
- Cloud-Connected:HIPAA-compliant data repositories enable caregiver and clinician remote access to glycemic trends.
- Bluetooth Enabled:Standardized wireless protocols ensure interoperability across receiver hardware generations.
Mature deployment sits with Sensor-Based systems. Newer deployment is concentrated in Mobile Integrated configurations.
Application:
Disease severity and insulin dependency status segment addressable populations by reimbursement eligibility and clinical monitoring intensity.
- Type 1 Diabetes:Absolute insulin deficiency mandates intensive glucose monitoring with automated basal-bolus adjustment. Pediatric endocrinology practices in the United States leverage FDA breakthrough device designations for adolescent-specific indications.
- Type 2 Diabetes:Progressive beta-cell dysfunction creates heterogeneous monitoring needs from oral agent management through intensive insulin therapy. Germany's statutory health insurance expansion for non-intensive insulin users is expanding addressable volume beyond traditional prescribing boundaries.
- Gestational Diabetes:Pregnancy-specific glycemic targets require heightened monitoring frequency without teratogenic pharmacotherapy exposure.
- Prediabetes:Lifestyle intervention monitoring captures emerging glucose dysregulation before pharmacologic threshold.
- Hypoglycemia Management:Alert-priority systems target nocturnal and exercise-induced glucose excursions in insulin-treated populations.
Mature deployment sits with Type 1 Diabetes. Newer deployment is concentrated in Type 2 Diabetes.
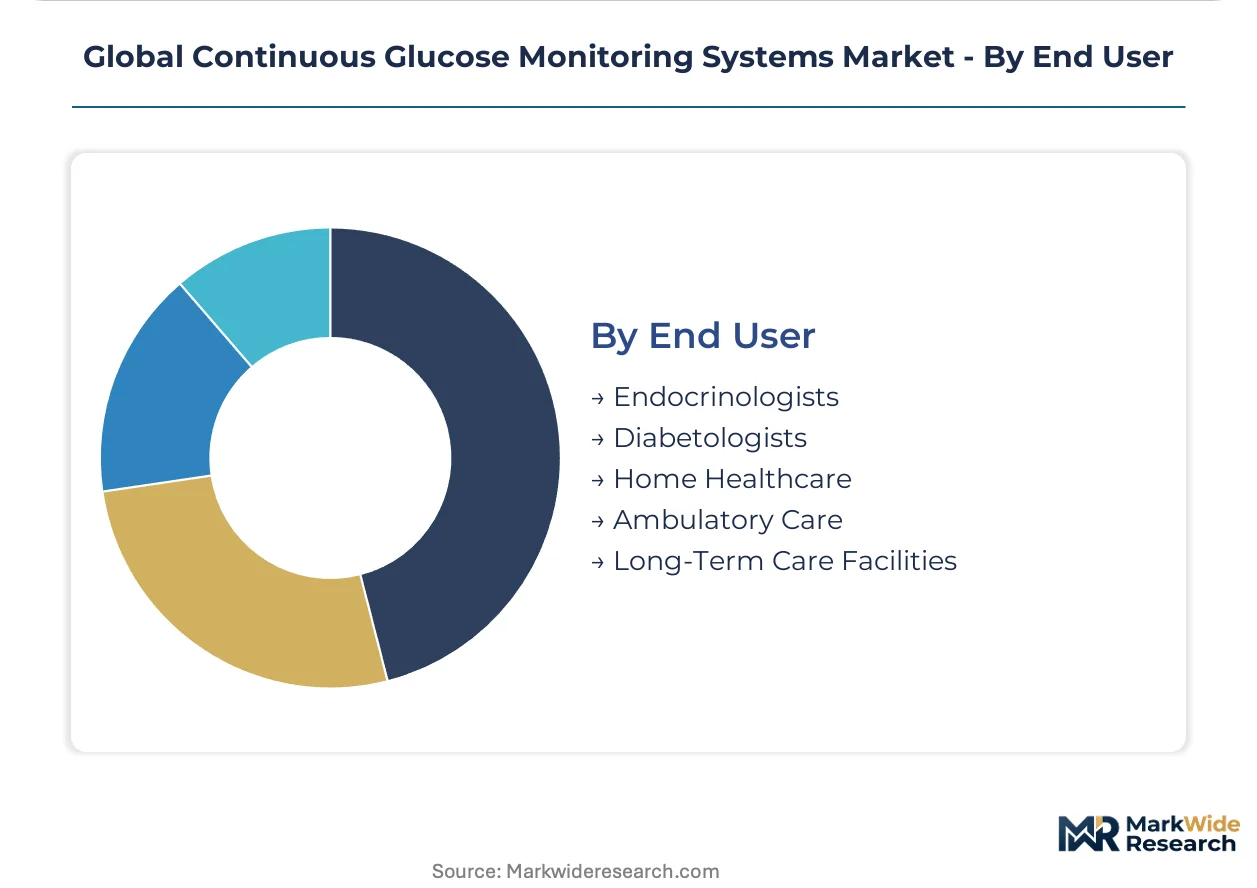
End User:
Prescriber specialty and care setting determine device selection criteria, reimbursement pathway, and patient education burden.
- Endocrinologists:Subspecialty practices drive real-time CGM adoption through closed-loop insulin pump integration and algorithm-driven dosing recommendations. Medicare Advantage networks in the United States capture adherence data for quality metric reporting.
- Diabetologists:Generalist metabolic disease specialists manage broader Type 2 diabetes populations with intermittent scanning preference for cost containment.
- Home Healthcare:Remote patient monitoring platforms pair Bluetooth-enabled transmitters with cloud analytics for post-acute glycemic surveillance.
- Ambulatory Care:Outpatient clinics deploy professional CGM for diagnostic profiling and therapy titration.
- Long-Term Care Facilities:Skilled nursing environments utilize simplified receiver interfaces for cognitively impaired residents.
Mature deployment sits with Endocrinologists. Newer deployment is concentrated in Home Healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Diego anchors sensor manufacturing for North American glucose monitoring systems, with transmitter fabrication clusters extending into Tijuana's medical device corridor. German precision electronics hubs in Freiburg and Munich supply enzymatic electrode substrates across European distribution networks. Japanese semiconductor foundries in Kumamoto prefecture fabricate the platinum-ruthenium composite layers essential for 14-day wear sensors.
United States
Medicare Advantage networks and employer-sponsored health plans drive pharmacy channel volume for factory-calibrated systems. FDA breakthrough device designations compress review timelines for pediatric and pregnancy-specific indications. The Minneapolis-St. Paul corridor concentrates insulin pump ecosystem integration engineering, with closed-loop algorithm development centers expanding in Greater Boston.
Germany
Statutory health insurance reimbursement expansion for non-intensive insulin users widens addressable populations beyond traditional prescribing boundaries. EU MDR technical documentation requirements for Class III devices accelerate certification timelines for established manufacturers. Freiburg's microelectrode fabrication cluster supplies enzymatic glucose oxidase sensor substrates to assembly operations in Baden-Württemberg.
Japan
METI reimbursement expansion for Type 2 diabetes populations in prefectural health systems creates underpenetrated demand for mobile-integrated sensors. PMDA consultation frameworks prioritize real-world evidence collection for software-as-medical-device algorithms. Kumamoto's semiconductor foundries specialize in platinum-ruthenium composite deposition for extended-wear electrochemical architectures.
China
NMPA innovative medical device approval pathways accelerate market access for Bluetooth-enabled transmitter systems. Dual carbon goals drive domestic manufacturing investment in low-energy sensor electronics. Shenzhen's hardware ecosystem concentrates mobile-integrated CGM assembly, with cloud analytics development clusters expanding in Beijing's Zhongguancun technology corridor.
Switzerland
Swissmedic expedited access frameworks align with EU MDR compliance timelines for cross-border market entry. Precision manufacturing heritage in the Jura Arc supports microelectrode fabrication for implantable sensor formats. Basel's pharmaceutical corridor hosts algorithm development centers specializing in predictive glucose forecasting for automated insulin delivery.
Global Continuous Glucose Monitoring Systems Market Competitive Landscape
Capital-heavy electrochemical sensor producers compete with asset-light algorithm developers for margin capture in glucose monitoring value chains. The market structure concentrates around three strategic tiers: vertically integrated pump-sensor ecosystems, standalone sensor specialists, and flash monitoring platform operators. Dominant competitive moves include backward integration into platinum-ruthenium supply chains and strategic partnerships with cloud analytics providers for remote patient monitoring data assets.
Within the integrated ecosystem tier, Medtronic anchors hardware-software bundling strategies through captive insulin pump demand. Abbott Laboratories exemplifies pharmacy channel dominance with factory-calibrated sensor platforms, while Dexcom occupies a position at the algorithm refinement frontier through iterative transmitter miniaturization. These three entities collectively represent the competitive archetypes reshaping reimbursement negotiations and direct-to-consumer subscription model economics across United States and European markets.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom |
| Medtronic |
| F. Hoffmann-La Roche |
| Senseonics Holdings |
| Ascensia Diabetes Care Holdings |
| i-SENS |
| Medtrum Technologies |
| Zhejiang POCTech |
| Others |
Supply & Pricing Matrix
Biocompatibility engineering talent scarcity in Freiburg and Munich widens labor-cost differentials between German precision manufacturing hubs and Asian assembly operations, compressing pricing-tier spreads for factory-calibrated sensors against calibration-dependent alternatives.
Pricing Analysis
Value-based pricing anchored to patient adherence outcomes and reduced hospitalization rates dominates reimbursement negotiations between manufacturers and Medicare Advantage networks. Three-tier pricing structure across premium, standard, and economy levels separates real-time CGM with predictive algorithms from intermittent scanning formats and professional diagnostic sensors. Pricing pressure stems from flash glucose monitoring substitution in Japan's prefectural health systems where reimbursement parity remains partial. Home healthcare providers exhibit highest price sensitivity due to capitated reimbursement structures, while endocrinology practices demonstrate lowest sensitivity given closed-loop insulin pump integration requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from hospital systems and pharmacy benefit managers, bypassing traditional durable medical equipment distributors. Platinum-ruthenium composite deposition draws from South African mining operations and Kumamoto semiconductor foundries, with enzymatic glucose oxidase sensor substrates sourced from Freiburg microelectrode fabrication clusters. Single-source vulnerability in platinum group metal supply concentration exposes manufacturers to commodity price volatility and geopolitical disruption. Distribution runs through pharmacy retail networks in the United States and Western Europe, complemented by direct-to-consumer subscription models capturing patient data assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR certification bottlenecks and platinum input volatility are forcing weaker players toward exit or acquisition, positioning the market as a consolidation play for capitalized incumbents.
For Market Incumbents: Cement algorithm refinement leadership through iterative transmitter miniaturization investments, defending against flash glucose monitoring substitution in price-sensitive Type 2 diabetes segments. Secure backward integration into platinum-ruthenium supply chains to buffer commodity volatility exposure. Prioritize FDA breakthrough device designation pathways for pediatric and pregnancy-specific indications to compress competitor review timelines. For New Entrants and Emerging Players: Begin with mobile-integrated sensor formats targeting Japan's METI reimbursement expansion for non-intensive insulin users, the most penetrable geography given partial real-time CGM adoption. Leverage cloud analytics partnerships with remote patient monitoring platforms to bypass entrenched pharmacy channel gatekeepers. Position on direct-to-consumer subscription economics to capture margin and adherence data assets absent legacy distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with algorithm-development specialists possessing FDA-cleared software-as-medical-device platforms given convergence toward closed-loop insulin delivery systems. Long-term viability favors entities with demonstrated EU MDR Class III certification execution and captive supply arrangements for electrochemical sensor substrates. Watch PMDA consultation framework outcomes for software algorithm reimbursement as the inflection indicator for Asia-Pacific market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review timelines compress competitive windows for pediatric and pregnancy-specific glucose monitoring indications. |
| EU MDR Class III Certification | Technical documentation requirements raise barriers for new entrants and consolidate market access for established manufacturers. |
| Insulin Pump Ecosystem Integration | Closed-loop algorithm convergence creates captive demand through hardware-software bundling and automated delivery protocols. |
| Direct-to-Consumer Subscription Model | Pharmacy channel disintermediation captures margin and patient adherence data assets for risk-adjusted reimbursement. |
| Platinum-Ruthenium Supply Security | Upstream control over electrochemical sensor catalyst inputs buffers commodity price volatility from South African supply concentration. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR certification queues, and METI reimbursement expansion schedules anchored the trend analysis, supplemented by interviews with endocrinologists, biomedical engineers, hospital GPO contracts managers, and pharmacy benefit directors. Secondary validation drew from FDA premarket notification databases, EMA submission records, CMS Medicare coverage determinations, and hospital procurement contract repositories. Bottom-up sensor shipment estimates triangulated against top-down reimbursement expenditure data across the analysis window.
Segment-weighting approaches modeled real-time versus intermittent scanning format splits, technology integration depth, application intensity by diabetes type, and end-user prescribing authority. CAGRs were derived from fitted growth curves applied to manufacturer-reported volume data and payer expenditure trajectories across the projection horizon. Industry-specific forecast inputs included platinum group metal price indices and EU notified body capacity utilization rates.
Underlying measurement precision varies by segment; real-time CGM with established reimbursement codes carries tighter precision than emerging intermittent scanning formats in partial-coverage markets. Forecasts reflect assumptions on regulatory pathway efficiency and reimbursement parity expansion that periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Thailand Diabetes Care Devices Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
Global Insulin Infusion Pumps Market
Diabetes Care
Global Needle Free Diabetes Care Market
Diabetes Care
Indonesia Diabetes Care Devices Market
Diabetes Care
Type-1 Diabetes Treatment Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
Insulin Patch Pumps Market
Diabetes Care
Asia Pacific Continuous Glucose Monitoring (CGM) Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
Brazil Oral Anti-Diabetic Drug Market
Diabetes Care
Asia Pacific Diabetes Pen Market
Diabetes Care
Global Blood Glucose Test Strip Market