
 Europe Wi-Fi Chipset Market | 2026-2036
Europe Wi-Fi Chipset Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wi-Fi Chipset Market Intelligence
Silicon carbide substrate integration is expanding into Wi-Fi power amplifier modules, displacing traditional gallium arsenide in high-efficiency designs. Qualcomm Technologies leverages its modem-RF system architecture to sustain design wins across European smartphone OEMs. Broadcom anchors premium access point shipments with its Wi-Fi 7-ready portfolio, while Infineon Technologies specializes in automotive-grade chipsets for connected vehicle platforms.
A Wi-Fi chipset integrates baseband processors, radio frequency transceivers, and power management circuits onto a single die or package, typically fabricated on 12-inch CMOS wafers at nodes ranging from 28nm to 7nm, enabling wireless local area network connectivity per IEEE 802.11 protocol standards. The 802.11ax segment dominates volume as enterprise refresh cycles accelerate across European office estates, while mesh network configurations capture margin pools in multi-dwelling residential deployments. Dual-band chipsets maintain ubiquity in consumer electronics, though tri-band architectures are gaining traction in premium smart home ecosystems.
The European Telecommunications Standards Institute coordinates spectrum harmonization, while CE marking under the Radio Equipment Directive governs market access for all Wi-Fi devices sold in EU member states. Germany's Federal Network Agency and France's ANFR enforce national frequency allocations that directly determine which Wi-Fi generations achieve commercial scale. Stakeholders must monitor upcoming 6 GHz band expansion decisions across Brussels, Berlin, and Paris, as these rulings will dictate chipset architecture investments for the next protocol transition.
Market Dynamics
The EU Radio Equipment Directive and national spectrum reallocations are compressing design cycles, forcing vendors toward higher-efficiency architectures before 6 GHz band expansion rulings finalize across Brussels, Berlin, and Paris.
Growth Catalysts
- CE marking mandates:The Radio Equipment Directive tightens electromagnetic compatibility requirements, pushing OEMs toward integrated modem-RF systems that reduce certification risk and accelerate time-to-market for Wi-Fi 6E devices.
- Industrial automation corridors:Germany's automotive Tier-1 suppliers and smart manufacturing facilities demand low-latency wireless connectivity, concentrating procurement of Wi-Fi 6 chipsets in Baden-Württemberg and Bavaria production clusters.
- Silicon carbide substrates:Power amplifier modules are migrating from gallium arsenide to silicon carbide for thermal efficiency, enabling denser access point deployments in multi-dwelling residential estates across France.
Market Restraints
- 12-inch CMOS wafer concentration:Foundry capacity for 28nm to 7nm nodes concentrates at Taiwanese and Korean suppliers, exposing European fabless designers to geopolitical supply disruptions and allocation priority shifts.
- 6 GHz licensing friction:France's ANFR and Germany's Federal Network Agency maintain divergent implementation timelines for Wi-Fi 6E standard power rules, fragmenting chipset SKU requirements and inflating inventory carrying costs.
- Legacy 2.4 GHz saturation:Unlicensed spectrum congestion in dense urban deployments degrades effective throughput, limiting price premiums for incremental Wi-Fi 5 to Wi-Fi 6 upgrades in cost-sensitive consumer segments.
Strategic Opportunities
- Polish and Romanian smart home penetration:Eastern European markets show underdeveloped mesh network adoption relative to Western Europe, creating whitespace for tri-band architecture vendors targeting premium residential ecosystems.
- EU Green Deal alignment:Energy efficiency mandates for networked equipment incentivize low-power Wi-Fi 7 designs, rewarding vendors who integrate power management circuits with standby consumption below regulatory thresholds.
- Automotive V2X convergence:Connected vehicle platforms in Stuttgart and Munich require automotive-grade chipsets that bridge IEEE 802.11p and 802.11ax protocols, opening specialized design wins for temperature-hardened suppliers.
Industry Challenges
- RF front-end integration complexity:Baseband processor and transceiver co-design demands scarce millimeter-wave engineering talent, with European universities producing insufficient graduates to staff vendor R&D centers in Dresden and Grenoble.
- CE marking timeline compression:Notified body backlogs for Radio Equipment Directive compliance extend certification cycles to 14-18 months, delaying revenue recognition for Wi-Fi 7 product launches targeting Q4 retail windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wi-Fi Chipset Market |
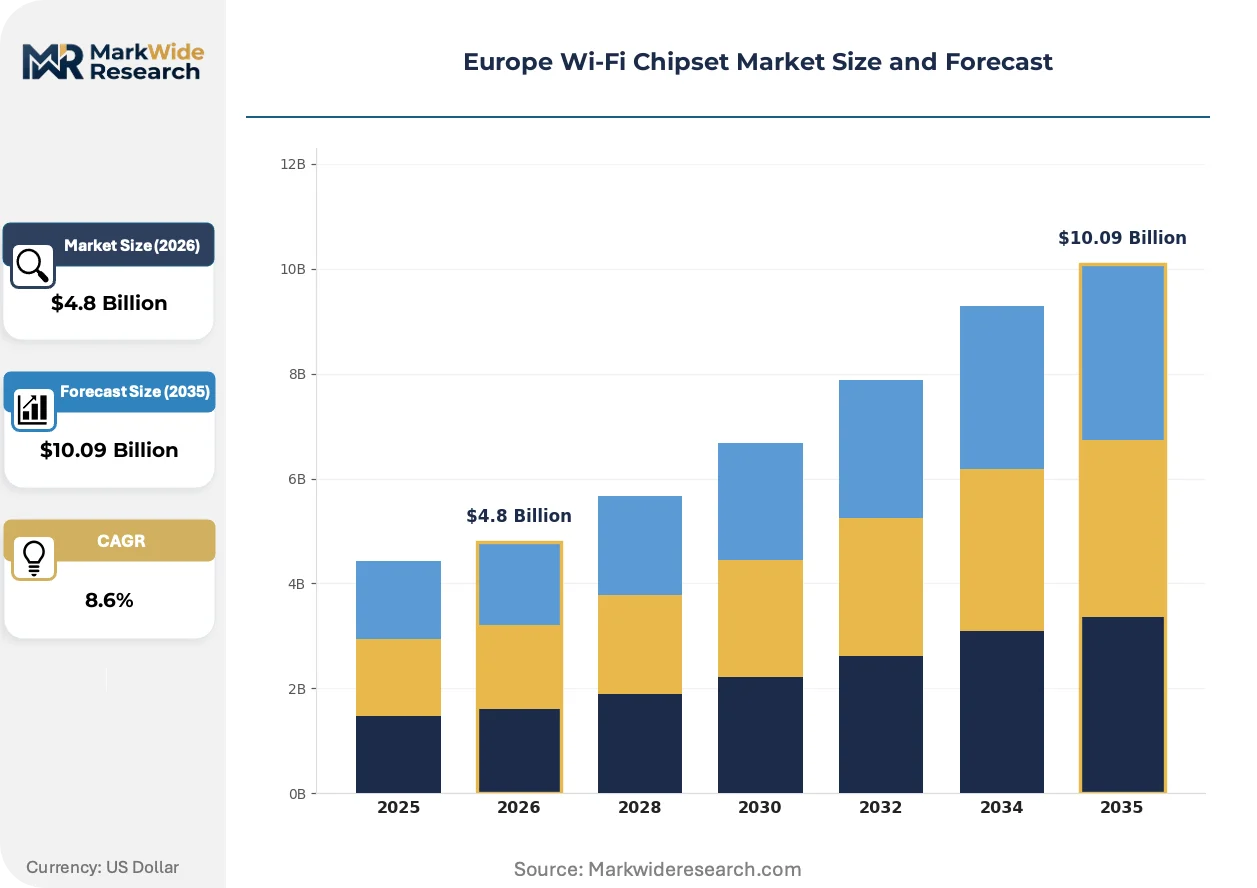
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 802.11n, 802.11ac, 802.11ax, 802.11ad, 802.11ah Device Type: Smartphones, Laptops, Smart Home Devices, Wearable Electronics, Tablets Connectivity Standard: Dual Band, Tri Band, Single Band, Mesh Network, MU-MIMO End User Industry: Consumer Electronics, Telecommunications, Information Technology, Automotive Tier-1 Suppliers, Smart Manufacturing |
| Companies Covered | MediaTek, STMicroelectronics, Qualcomm Technologies, Cisco Systems, Texas Instruments, Broadcom, Infineon Technologies, Espressif Systems, Intel Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wi-Fi Chipset Market Strategic Shifts & Innovations
Protocol generation transitions and substrate material shifts are compressing competitive margins while regulatory harmonization efforts create temporary architecture fragmentation across national boundaries.
Silicon carbide power amplifier modules are consolidating thermal management advantages in high-density access point designs. Enterprise IT procurement teams in Frankfurt and Amsterdam are specifying SiC-based units for new office estate rollouts. This substrate migration is consolidating vendor differentiation around thermal performance rather than raw data rate specifications.
The EU Radio Equipment Directive's 2024 enforcement amendments tighten cybersecurity requirements for wireless network equipment. Manufacturers must now embed hardware security modules and secure boot architectures into chipset designs before CE marking approval. French smart home OEMs are absorbing the highest compliance costs, delaying Wi-Fi 7 product launches by two quarters relative to German competitors.
Enterprise procurement teams are consolidating vendor relationships around modem-RF system suppliers who deliver pre-certified reference designs. Channel partners in London and Milan are displacing component distributors with technical integration services that bundle firmware customization and regulatory filing support. This consolidation is most visible in Germany's industrial automation sector, where automotive buyers demand single-source accountability for wireless connectivity performance.
Europe Wi-Fi Chipset Market Segmentation
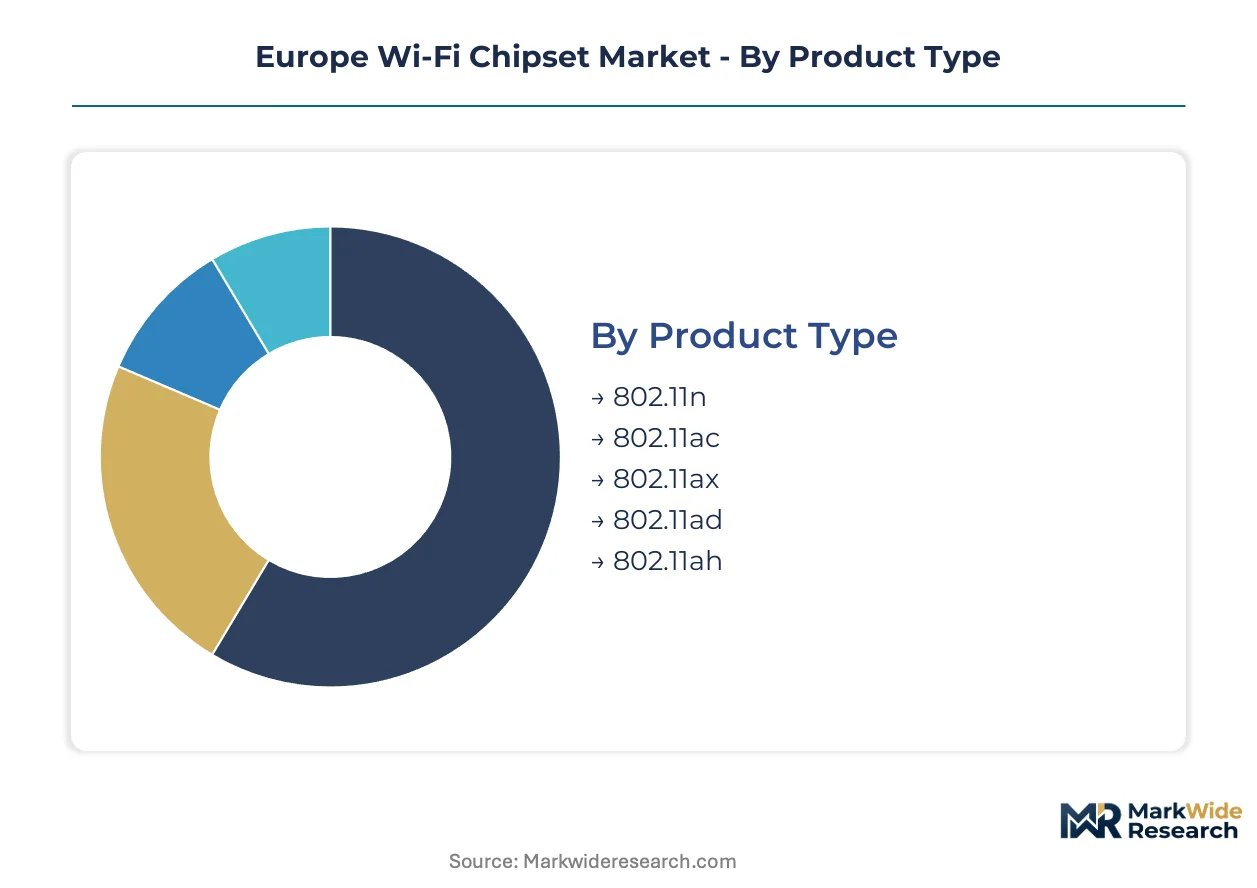
Protocol transitions and device refresh cycles fragment procurement patterns across European markets. Segmentation reveals where design wins concentrate and which architectures command premium positioning.
Product Type:
Upgrade cycles compress as enterprise IT departments accelerate 802.11ax deployments ahead of Wi-Fi 7 availability.
- 802.11n:Legacy silicon persists in industrial sensors and low-bandwidth IoT endpoints where cost minimization outweighs throughput requirements. Demand concentrates in Polish and Romanian manufacturing facilities running legacy SCADA integrations.
- 802.11ac:Wave 2 implementations dominate mid-tier residential routers across Spain and Italy, where consumer price sensitivity delays 802.11ax migration. Volume placements concentrate in retail channel bundles through Madrid and Milan distribution hubs.
- 802.11ax:OFDMA and BSS coloring capabilities enable dense stadium and convention center deployments. German automotive Tier-1 suppliers in Stuttgart specify these chipsets for factory floor wireless backbones requiring deterministic latency.
- 802.11ad:60 GHz millimeter-wave operation supports wireless docking and uncompressed video streaming in conference room installations. Dutch enterprise AV integrators in Eindhoven drive niche procurement for huddle-space deployments.
- 802.11ah:Sub-1 GHz operation extends range for agricultural sensors and smart metering across French rural deployments. ANFR spectrum allocations in the 868 MHz band determine commercial viability.
Volume placements concentrate in 802.11ac; the faster expansion belongs to 802.11ax.
Device Type:
Cost tier stratification separates premium flagship specifications from economy reference designs.
- Smartphones:Modem-RF system integration demands dominate flagship procurement from Munich and Helsinki OEMs. CE marking timelines for 5G-Wi-Fi coexistence certification extend development cycles.
- Laptops:Intel Evo and AMD Ryzen platform certifications mandate Wi-Fi 6 minimum specifications. Enterprise fleet refreshes across London financial services concentrate procurement in Q2-Q3 windows.
- Smart Home Devices:Voice assistant speakers and security cameras drive mesh network chipset demand in Paris and Berlin residential clusters. Matter protocol interoperability requirements reshape silicon selection criteria.
- Wearable Electronics:Ultra-low-power 802.11ah implementations support fitness tracker synchronization. Swiss watchmakers in Geneva specify custom antenna-tuned modules for luxury connected timepieces.
- Tablets:Education sector tenders in Italy and Spain prioritize ruggedized designs with extended thermal envelopes. Regional ministry procurement cycles determine annual volume spikes.
Smartphones absorb the highest silicon value per unit; smart home devices gain share fastest in shipment volume.
Connectivity Standard:
Customer type differentiation separates residential self-install from enterprise managed service deployments.
- Dual Band:2.4 GHz and 5 GHz concurrent operation remains the default for consumer electronics. French retail chains in Lyon and Marseille stock predominantly dual-band SKUs for price-sensitive segments.
- Tri Band:Dedicated backhaul channels enable seamless roaming in multi-story dwellings. Premium smart home ecosystems in Munich and Vienna specify these architectures for whole-home coverage guarantees.
- Single Band:2.4 GHz-only designs persist in cost-optimized IoT sensors and legacy industrial equipment. Eastern European utility smart meter rollouts specify these for maximum range per euro.
- Mesh Network:Self-healing topologies capture margin in multi-dwelling units across Amsterdam and Copenhagen. Property developers bundle these installations in new-build premium residential towers.
- MU-MIMO:Multi-user spatial streaming concentrates in enterprise access points serving open-plan offices. Frankfurt banking headquarters specify 8x8 implementations for trading floor density.
Dual Band maintains ubiquity in unit shipments; Mesh Network commands the steepest expansion trajectory in revenue terms.
End User Industry:
Application-specific certification requirements and margin structures determine vendor targeting priorities.
- Consumer Electronics:Seasonal retail cycles and promotional pricing compress margins. CE marking documentation burdens fall heaviest on small OEMs in Barcelona and Lisbon.
- Telecommunications:Carrier-grade access points and CPE devices demand extended temperature ranges and failure rate guarantees. Deutsche Telekom and Orange specify custom firmware branches.
- Information Technology:Enterprise WLAN infrastructure refresh cycles concentrate procurement through systems integrators. Dutch VARs in Utrecht bundle managed services with hardware deployment.
- Automotive Tier-1 Suppliers:AEC-Q100 qualification and ISO 26262 functional safety requirements gate market entry. Bosch and Continental procurement teams in Stuttgart and Ingolstadt specify automotive-grade temperature ranges.
- Smart Manufacturing:Time-sensitive networking and deterministic latency requirements drive 802.11ax adoption. Bavarian automotive plants in Dingolfing and Regensburg deploy wireless for AGV fleet coordination.
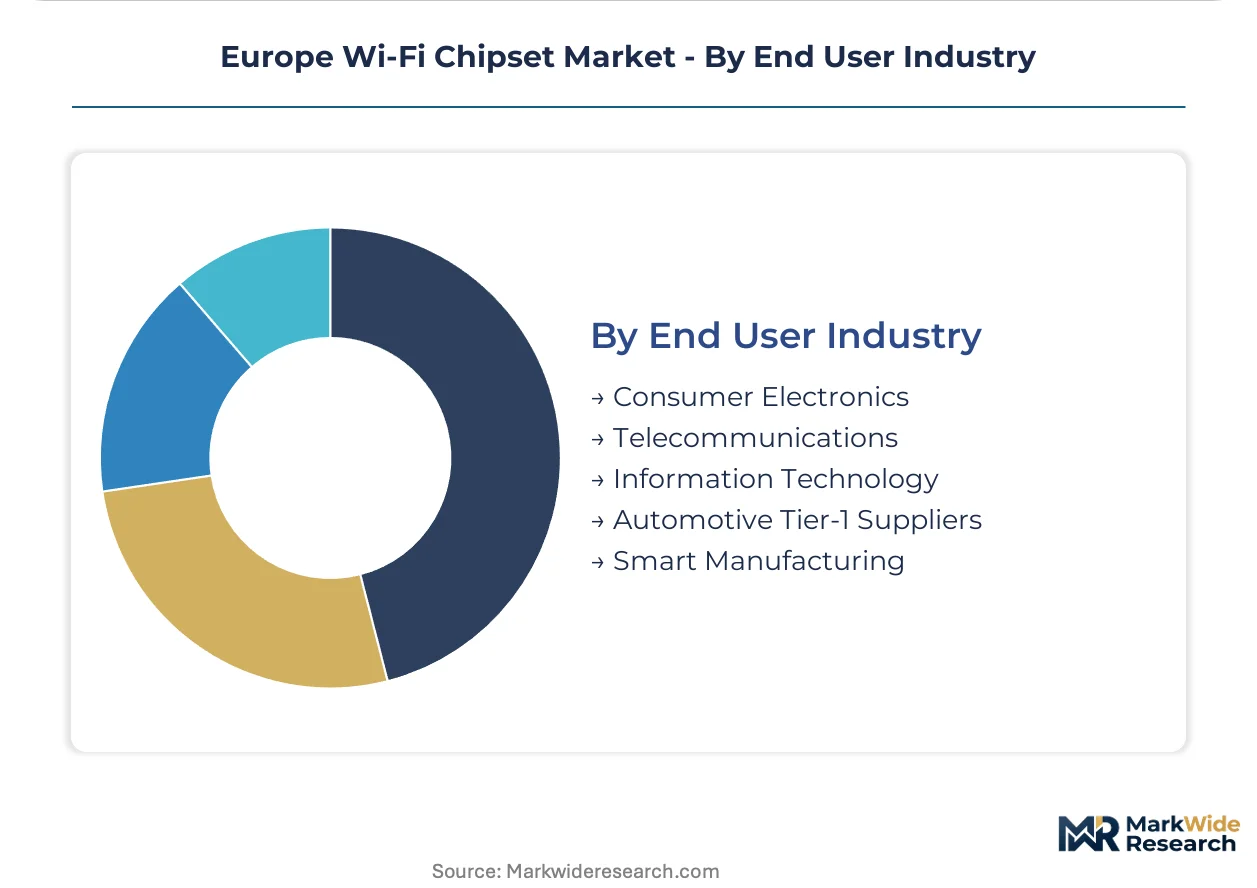
Consumer Electronics dominates absolute volume; Smart Manufacturing climbs fastest in average selling price expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial automation corridors in Germany and automotive manufacturing clusters across Central Europe concentrate procurement of Wi-Fi 6 and Wi-Fi 6E chipsets. Spectrum harmonization efforts by the European Telecommunications Standards Institute shape deployment timelines across member states.
Germany
Automotive Tier-1 suppliers and smart manufacturing facilities in Baden-Württemberg and Bavaria drive demand for low-latency wireless connectivity. The Federal Network Agency governs national frequency allocations that determine Wi-Fi 6E commercial scale. Stuttgart production clusters specify automotive-grade chipsets for connected vehicle platforms requiring deterministic latency.
France
ANFR spectrum management decisions directly impact chipset architecture investments for protocol transitions. CE marking under the Radio Equipment Directive tightens electromagnetic compatibility requirements for Paris-based smart home OEMs. Residential deployments in Lyon and Marseille concentrate procurement of dual-band consumer electronics.
United Kingdom
Enterprise IT procurement teams in London financial services concentrate WLAN infrastructure refresh cycles in Q2-Q3 windows. Channel partners displace component distributors with technical integration services bundling firmware customization. Matter protocol interoperability requirements reshape silicon selection criteria for smart home device manufacturers.
Netherlands
Enterprise AV integrators in Eindhoven drive niche procurement for 60 GHz millimeter-wave conference room installations. Dutch VARs in Utrecht bundle managed services with hardware deployment for information technology end users. Property developers in Amsterdam specify mesh network installations in new-build premium residential towers.
Poland
Eastern European markets show underdeveloped mesh network adoption relative to Western Europe, creating whitespace for tri-band architecture vendors. Legacy 802.11n silicon persists in manufacturing facilities running SCADA integrations. Utility smart meter rollouts specify single-band 2.4 GHz designs for maximum range per euro.
Europe Wi-Fi Chipset Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated modem-RF system suppliers capturing premium positioning in smartphone and enterprise access point categories. The vendor base organizes around three strategic archetypes: fabless semiconductor designers leveraging Taiwanese foundry partnerships, diversified technology conglomerates with captive wireless divisions, and automotive-grade specialists targeting AEC-Q100 qualification requirements. Consolidation pressures intensify as CE marking timelines compress and notified body backlogs extend certification cycles to 14-18 months.
Within the fabless designer tier, MediaTek and Qualcomm Technologies exemplify modem-RF system integration strategies that reduce certification risk for European OEMs. Broadcom anchors premium access point shipments with protocol-forward portfolios, while Infineon Technologies occupies a specialized position serving automotive-grade temperature requirements for Stuttgart and Munich connected vehicle platforms. These three companies represent distinct competitive vectors: volume-scale mobile platforms, enterprise infrastructure dominance, and automotive functional safety compliance.
| Leading Market Players |
|---|
| MediaTek |
| STMicroelectronics |
| Qualcomm Technologies |
| Cisco Systems |
| Texas Instruments |
| Broadcom |
| Infineon Technologies |
| Espressif Systems |
| Intel Corporation |
| Others |
Cost & Logistics Intelligence
Captive foundry partnerships at Taiwanese suppliers anchor both supply security and pricing power for European fabless designers, creating tiered cost structures that ripple through downstream procurement decisions. This integration choice concentrates margin capture at the wafer fabrication stage while exposing buyers to allocation priority shifts during capacity crunches.
Pricing Analysis
Volume placements concentrate in 802.11ac dual-band chipsets; premium margins attach to Wi-Fi 7 tri-band architectures with silicon carbide power amplifiers. Price differentiation separates automotive-grade AEC-Q100 qualified units from consumer electronics SKUs, with CE marking tier and thermal specification as key drivers. Cost compression in consumer segments intensifies as French and German OEMs absorb cybersecurity compliance burdens. Automotive Tier-1 suppliers in Stuttgart show least price sensitivity; Eastern European utility buyers prioritize maximum range per euro.
Supply Chain Analysis
Freight cost volatility from Asian manufacturing hubs compounds lead time uncertainty for 12-inch CMOS wafer shipments. Foundry capacity draws from Taiwan, South Korea, and the United States, with 28nm to 7nm node production resting on gallium arsenide and silicon carbide substrate supply. Single-source vulnerability concentrates at TSMC and Samsung for advanced node allocation. Distribution runs through Munich and Amsterdam technical integration centers that bundle firmware customization with hardware fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where CE marking timeline compression and notified body backlogs force weaker vendors toward exit or acquisition. Regulatory compliance burdens favor scaled players with dedicated certification teams.
For Market Incumbents: Anchor design win retention through automotive-grade qualification investments at AEC-Q100 and ISO 26262 tiers. Threats from MediaTek and Qualcomm modem-RF system integration demand captive foundry capacity commitments in Taiwan. Leverage vertical integration into silicon carbide substrate sourcing to defend thermal performance differentiation. For New Entrants and Emerging Players: Eastern European utility buyers represent an underserved archetype with whitespace for single-band 802.11ah smart meter chipsets. Polish and Romanian manufacturing facilities running legacy SCADA integrations offer penetrable volume placements. Pursue direct utility tender participation rather than distributor channel builds. For Investors and Strategic Acquirers: Exit pathways concentrate in automotive-grade specialists with AEC-Q100 temperature-hardened portfolios. Long-term viability over a multi-year window hinges on Wi-Fi 7 protocol transition timing and 6 GHz band expansion rulings. Watch Federal Network Agency and ANFR spectrum harmonization decisions as inflection indicators for architecture investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-Grade Qualification Investment | AEC-Q100 certification opens procurement at Bosch and Continental in Stuttgart. |
| Silicon Carbide Substrate Integration | Thermal efficiency gains displace gallium arsenide in high-density access points. |
| CE Marking Pre-Certification | Reduced certification risk accelerates time-to-market for Wi-Fi 6E devices. |
| Mesh Network Architecture Development | Tri-band designs capture premium positioning in Munich and Vienna residential clusters. |
| Eastern European Distribution Expansion | Direct utility engagement in Poland and Romania bypasses Western European channel congestion. |
Research Approach
Document review covered ETSI spectrum harmonization filings, Federal Network Agency frequency allocation decisions, and ANFR regulatory notices, complemented by interviews with semiconductor procurement directors at automotive Tier-1 suppliers, smart home OEM product managers, and enterprise IT infrastructure leads. Secondary validation drew from SEC semiconductor filings, foundry capacity utilization reports, and CE marking notified body databases. Bottom-up shipment estimates triangulated against top-down market value reconstructions.
Cross-referencing historical protocol transition patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include protocol generation, device type, connectivity standard, and end-user industry vertical. CAGRs derived from unit shipment trajectories and average selling price evolution, with foundry capacity allocation and spectrum regulatory timing as semiconductor-specific forecast inputs.
Revisions become necessary when Brussels spectrum rulings, foundry geopolitical disruptions, or cybersecurity directive amendments materialize outside baseline assumptions. Forecasts reflect documented judgments about protocol adoption curves and certification timeline compression. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Airbag Chip Market
Chipset and Processors
Global Deep Learning Chipset Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
Tablet Application Processor Market
Chipset and Processors
Global Microcontroller (MCU) Market
Chipset and Processors
Application Processor Market
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
Global Digital Light Processing Chipset Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Power Architecture Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Japan Microprocessor (MPU) Market