
 Application Processor Market | 2026-2036
Application Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Application Processor Market Intelligence
The increasing integration of components into a single System on Chip (SoC) is repositioning buyer choice around power efficiency and miniaturization. Qualcomm Technologies leverages its extensive patent portfolio in 5G and mobile technologies to command a premium. Apple differentiates through its custom silicon designs tightly integrated with its iOS and macOS ecosystems. MediaTek competes aggressively on performance-per-dollar, securing significant volume in mid-range smartphones.
An application processor is a complex semiconductor device that functions as the primary CPU within a mobile or embedded system. These processors execute operating systems and user applications, often integrating multiple cores based on architectures like ARM Cortex. Their primary purpose is to manage the computational workload for everything from user interfaces to complex software. The smartphone segment remains the largest device application, while ARM Cortex architectures dominate the processor type landscape due to their superior power efficiency.
Product compliance is governed by a web of international standards and regional bodies. The US Federal Communications Commission (FCC) sets rules for radio frequency emissions, while the EU's CE marking directive mandates safety and performance criteria. In China, the Ministry of Industry and Information Technology (MIIT) must approve devices before they can connect to public networks. Future success depends on navigating the architectural shift towards open standards like RISC-V and managing supply chain dependencies.
Market Dynamics
The central force shaping the application processor market is the industry-wide migration to advanced 3nm and 5nm semiconductor process nodes. This technological shift directly dictates chip performance, power consumption, and manufacturing cost, creating an intense competitive dynamic among designers and foundries.
Growth Catalysts
- Automotive Integration:The expanding role of processors in automotive infotainment, digital cockpits, and Advanced Driver-Assistance Systems (ADAS) creates a durable, high-value demand stream beyond the mature smartphone market.
- 5G Network Expansion:The continued rollout of 5G infrastructure, particularly in developing economies like India and Brazil, necessitates a device refresh cycle with new handsets featuring compatible, power-efficient application processors.
- National Semiconductor Policies:Government frameworks like the US CHIPS Act and the EU Chips Act are stimulating domestic research, design, and manufacturing capabilities, fostering ecosystem growth and supply chain resilience.
Market Restraints
- Extreme Ultraviolet Lithography Costs:The immense capital investment required for EUV lithography tools, essential for sub-7nm fabrication, concentrates advanced manufacturing capabilities among a few foundries and creates high barriers to entry.
- Foundry Concentration Risk:Heavy reliance on a small number of advanced foundries located primarily in Taiwan and South Korea exposes the entire fabless ecosystem to significant geopolitical and supply chain disruption risks.
- Thermal Management Limits:As processor performance increases within small mobile form factors, dissipating heat becomes a fundamental physical constraint that can throttle performance and impact device reliability.
Strategic Opportunities
- Edge AI Processors:Designing specialized, low-power processors optimized for on-device AI and machine learning workloads in IoT, wearables, and smart home devices opens a major growth area outside of mobile computing.
- RISC-V Architecture:The open-source RISC-V instruction set architecture provides a royalty-free alternative to proprietary cores, enabling companies to develop highly customized processors for specific applications like storage controllers or security modules.
- Industrial Automation:Integrating high-performance application processors into robotics, machine vision systems, and factory automation equipment represents a significant, underpenetrated industrial market.
Industry Challenges
- Complex IP Licensing:Navigating the intricate patent landscape and high licensing costs associated with core technologies like ARM instruction sets and 5G modems remains a significant operational burden for new and smaller designers.
- SoC Verification Talent Gap:A persistent shortage of skilled System on Chip (SoC) verification and physical design engineers creates development bottlenecks, extending project timelines and increasing labor costs across the industry.
- Multi-Regional Compliance:The need to secure certifications from disparate regulatory bodies, such as the FCC in the US, CE marking in the EU, and MIIT in China, adds considerable time and expense to product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Application Processor Market |
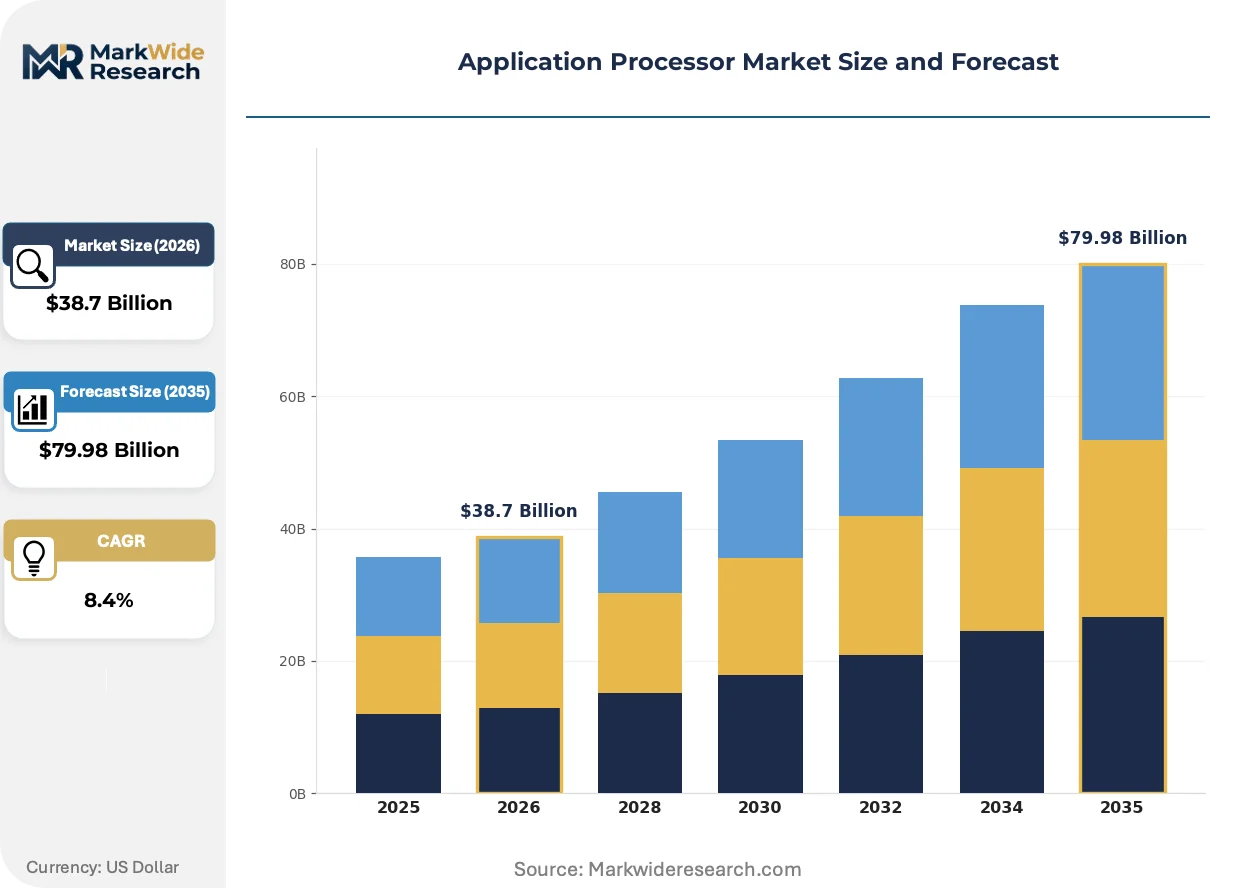
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Processor Type: ARM Cortex, x86, MIPS, RISC-V, Power Architecture Device Application: Smartphones, Tablets, Wearables, Smart TVs, Automotive Infotainment Integration Level: System on Chip, Multi-Chip Module, Discrete Processors, Hybrid Processors End User Segment: Original Equipment Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Tech Startups |
| Companies Covered | Samsung Electronics, NVIDIA Corporation, Qualcomm Technologies, HiSilicon Technologies, NXP Semiconductors, Apple, Intel Corporation, Texas Instruments, MediaTek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Application Processor Market Strategic Shifts & Innovations
Heterogeneous computing is becoming the dominant design paradigm. This approach involves integrating multiple specialized processing cores, such as CPUs, GPUs, and neural processing units (NPUs), into a single SoC to efficiently handle diverse workloads from user interfaces to complex AI tasks.
Advanced Packaging and Chiplets
Chiplet technology enables the assembly of multiple, smaller semiconductor dies, or chiplets, within a single package. High-performance computing segments are the primary adopters, but the technique is now entering the premium mobile processor space. This disaggregation of the monolithic SoC is modularizing system design, allowing for greater customization and improved manufacturing yields for complex processors.
AI-Specific Regulatory Frameworks
The European Union's AI Act establishes a risk-based framework for artificial intelligence, imposing strict requirements on systems deemed high-risk. This regulation forces processor designers to build verifiable safety and transparency features directly into the silicon. Processors designed for automotive ADAS or critical infrastructure control are most affected, demanding new design-for-compliance strategies.
In-House Silicon Design by OEMs
A growing number of large device manufacturers are pursuing custom silicon strategies, designing their own application processors in-house. This trend disrupts the traditional supplier relationship, turning major smartphone and automotive OEMs into direct design entities. The shift is most visible in the premium device tiers where tight hardware and software integration provides a critical competitive advantage.
Application Processor Market Segmentation
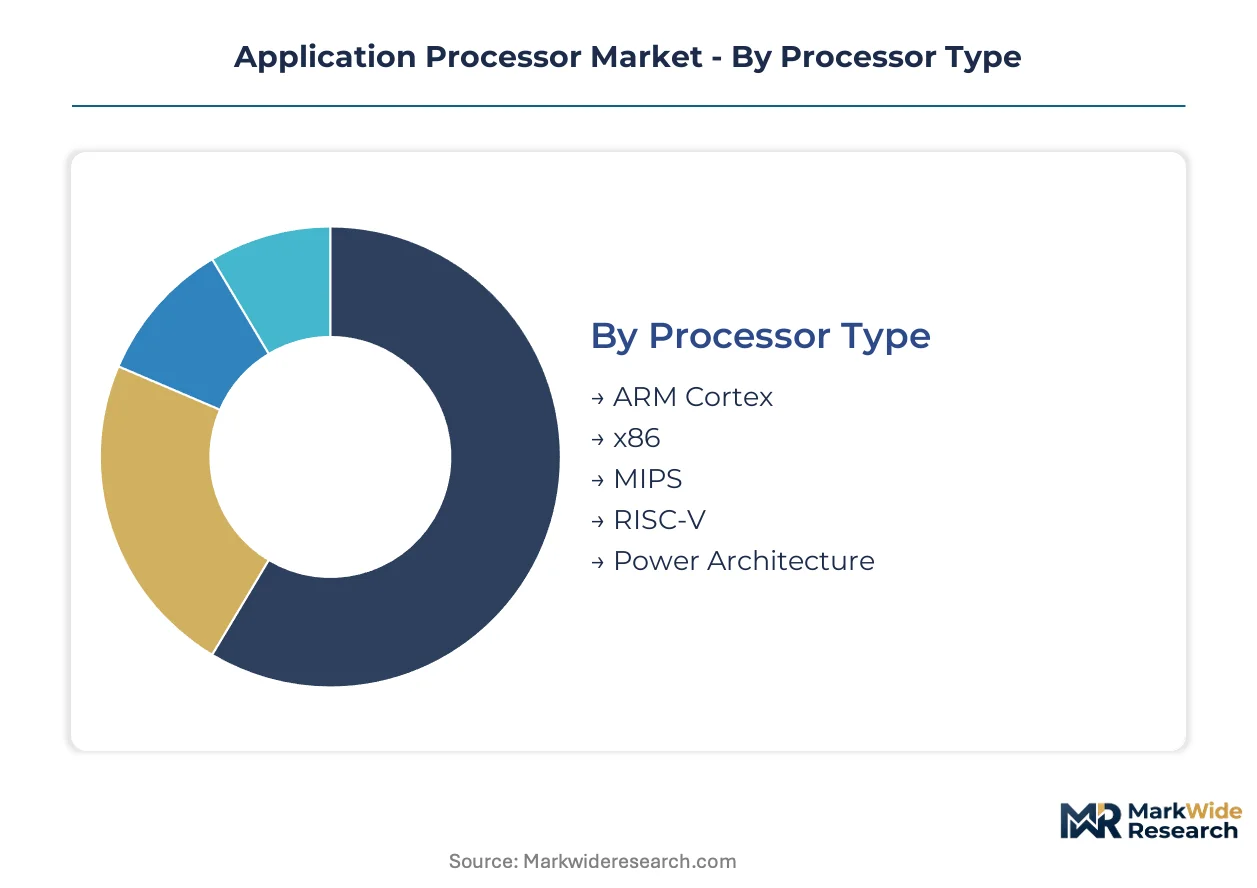
Segmentation of the application processor market clarifies distinct technology preferences, device applications, and supply chain dynamics. Understanding these divisions is crucial for strategic positioning and product development within this complex semiconductor landscape. Each segment exhibits unique demands for performance, power efficiency, and integration.
Processor Type:
Processor type segmentation highlights the volume dominance of certain architectures versus the specialized, high-performance niches occupied by others.
- ARM Cortex:This architecture is optimized for power efficiency and dominates mobile and embedded systems, featuring a wide range of core designs. Demand is pervasive in smartphones and wearables, particularly across consumer electronics manufacturing hubs in China and Vietnam.
- RISC-V:An open-source instruction set architecture, RISC-V offers high customizability and royalty-free licensing, fostering innovation in specialized applications. Demand is rapidly expanding in IoT devices and custom embedded controllers, enabling new market entrants in the US and Europe.
- x86:Known for its high computational power, the x86 architecture is primarily found in traditional personal computing and server environments.
- MIPS:This architecture continues to serve niche markets in embedded systems, networking equipment, and microcontrollers.
- Power Architecture:Utilized in high-reliability applications, including automotive control systems and industrial automation equipment.
Mature deployment sits with ARM Cortex. Newer deployment is concentrated in RISC-V.
Device Application:
Application processors are tailored to specific device environments, optimizing performance and power consumption for diverse user experiences.
- Smartphones:This segment represents the largest volume market, requiring highly integrated and power-efficient processors to support advanced user interfaces and connectivity. Demand remains concentrated in massive consumer markets like China and India, driving continuous innovation in mobile SoC design.
- Automotive Infotainment:Processors in this rapidly expanding segment manage in-vehicle communication, navigation, and entertainment systems, demanding robust performance and reliability. Demand is surging in premium and electric vehicles across Germany and the US, integrating complex ADAS functionalities.
- Tablets:These devices balance screen size and portability, requiring processors that support multimedia consumption and productivity applications.
- Wearables:Characterized by ultra-low power consumption and compact form factors, this segment includes smartwatches and fitness trackers.
- Smart TVs:Processors for Smart TVs handle media decoding, internet connectivity, and advanced user interfaces for home entertainment.
While smartphones maintain market share, automotive infotainment is gaining share fastest due to increasing vehicle digitization.
Integration Level:
The level of integration within an application processor package reflects engineering complexity and performance goals for the target system.
- System on Chip:A single integrated circuit that incorporates all major components of a computer or electronic system, including CPU, GPU, memory, and peripherals. Demand is universal across mobile and embedded devices, driven by miniaturization and power efficiency requirements.
- Multi-Chip Module:This technology combines multiple semiconductor dies within a single package, offering benefits in modularity, yield, and heterogeneous integration. Demand is prevalent in high-performance computing segments and premium mobile processors, particularly from leading foundries in Taiwan.
- Discrete Processors:Individual components like separate CPU and GPU units, offering flexibility but often at the cost of space and power.
- Hybrid Processors:These designs blend different architectures or integration styles to achieve specific performance or efficiency targets.
System on Chip design dominates market share, driving efficiency across most device categories.
End User Segment:
Different end-user segments engage with application processor suppliers based on their position within the broader electronics manufacturing supply chain.
- Original Equipment Manufacturers:These companies directly integrate application processors into their final consumer or industrial products, often developing custom silicon for competitive differentiation. Demand comes from major smartphone OEMs like Apple and Samsung, and automotive giants such as Tesla.
- Tier-1 Suppliers:These firms provide complete sub-assemblies or modules to OEMs, particularly prominent in the automotive and industrial sectors. Demand originates from established suppliers like Bosch and Continental, requiring specialized, high-reliability embedded solutions.
- Aftermarket Providers:This segment offers upgrades, replacement parts, or accessories for existing electronic systems and devices.
- Tech Startups:Emerging companies innovating with new device categories or specialized applications, often seeking flexible and scalable processor solutions.
Original Equipment Manufacturers are critical for market reach, while Tier-1 suppliers enable specialized industry penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The application processor market exhibits a clear divide between regions focused on high-volume manufacturing and those driving advanced design and consumption. Production gravity centers on East Asia, while innovation hubs and significant end-user demand span across multiple continents. This geographic segmentation influences technology adoption and regulatory impacts.
China
Massive consumer electronics manufacturing and expanding 5G infrastructure drive demand for application processors. The Ministry of Industry and Information Technology (MIIT) mandates device approvals before public network connection. Shenzhen's electronics manufacturing clusters continue to innovate in mobile SoC design and integration.
United States
Automotive infotainment systems and Edge AI processors represent significant demand streams for advanced application processors. The US CHIPS Act stimulates domestic research and manufacturing capabilities. Silicon Valley remains a hub for custom silicon design by major OEMs and specialized AI processor developers.
Germany
Robust demand for automotive infotainment and ADAS systems positions Germany as a key market for high-reliability application processors. CE marking directives from the EU mandate safety and performance criteria for electronic components. Munich's automotive industry cluster drives specialized embedded solutions for premium and electric vehicles.
South Korea
Advanced foundry capabilities and a strong consumer electronics industry underpin demand for leading-edge application processors. The country's national semiconductor policies support R&D and manufacturing of advanced process nodes. Seoul's technology ecosystem fosters innovation in mobile SoC design and advanced packaging techniques.
India
Expanding 5G network infrastructure and a large smartphone market fuel substantial demand for power-efficient application processors. The Production Linked Incentive (PLI) scheme encourages domestic electronics manufacturing. Bengaluru's tech hub is witnessing increased activity in semiconductor design and embedded system development.
Application Processor Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered market structure for application processors. The industry exhibits consolidation at the advanced manufacturing nodes, yet fragmentation persists among numerous fabless design houses. Strategic archetypes include integrated device manufacturers, fabless design firms emphasizing IP development, and specialized IP providers. Companies engage in strategic partnerships, capacity expansion, and technology licensing to maintain competitive positioning and navigate complex supply chains.
At the scale-driven end of the market, Qualcomm Technologies exemplifies leadership in mobile and 5G technologies, leveraging its extensive patent portfolio to command a premium. Apple, through its custom silicon designs, represents the growing trend of original equipment manufacturers pursuing in-house development for tight hardware-software integration within their ecosystems. MediaTek occupies a strong position in the mid-range smartphone segment, competing aggressively on performance-per-dollar and securing significant volume in consumer electronics.
| Leading Market Players |
|---|
| Samsung Electronics |
| NVIDIA Corporation |
| Qualcomm Technologies |
| HiSilicon Technologies |
| NXP Semiconductors |
| Apple |
| Intel Corporation |
| Texas Instruments |
| MediaTek |
| Others |
Cost & Logistics Intelligence
Silicon wafer prices, a foundational commodity benchmark, directly cascade through the application processor supply chain, influencing fabrication costs and ultimately the pricing tiers for finished System on Chip (SoC) products. This fundamental input cost establishes a baseline for subsequent value-added processes.
Pricing Analysis
Cost-down pressure on mid-range application processors accelerates because smartphone OEMs demand aggressive price points for volume segments, especially in markets like India and China. The dominant pricing model involves complex contract-based long-term offtake agreements for foundry services, alongside IP licensing for core architectures like ARM. Price differentiation stems from the advanced process node (e.g., 3nm vs. 5nm) and the level of customization offered by fabless design houses. Premium device manufacturers, like Apple, exhibit lower price sensitivity due to their integrated ecosystems, while mid-range smartphone vendors are highly price-sensitive.
Supply Chain Analysis
Skilled workforce availability in advanced semiconductor manufacturing geographies like Taiwan and South Korea underpins the application processor supply chain. Supply concentration centers heavily in these nations for cutting-edge fabrication, with China also playing a significant role in packaging and assembly. Raw material dependencies include advanced lithography equipment, particularly Extreme Ultraviolet (EUV) tools, and high-purity silicon wafers. Geopolitical risk, specifically surrounding the Taiwan Strait, represents a critical structural vulnerability for the entire fabless ecosystem. Distribution runs primarily through direct contracts between fabless design companies and foundries, then onward to Original Equipment Manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The application processor market is fundamentally supply-constrained, with the immense capital expenditure for advanced process node fabrication serving as a significant bottleneck propping up pricing for leading-edge components.
For Market Incumbents:Hedge against foundry concentration risk by actively diversifying manufacturing partnerships beyond traditional East Asian hubs, potentially exploring new facilities in the United States or Europe. Invest heavily in advanced packaging technologies like chiplets to improve yield and modularity for complex SoCs, addressing thermal management limits. Focus R&D efforts on enhancing neural processing unit (NPU) capabilities to maintain leadership in Edge AI workloads, a key differentiator against emerging specialized processor designs. Secure long-term supply agreements for critical materials and lithography equipment to mitigate future supply chain disruptions.
For New Entrants and Emerging Players:Industrial automation firms represent an underserved buyer archetype seeking highly reliable, specialized embedded solutions for robotics and machine vision systems. Target the open-source RISC-V instruction set architecture as a viable alternative to proprietary cores, enabling lower licensing costs and greater customization for niche applications. The most penetrable segment lies within IoT devices and custom embedded controllers, where power efficiency and specific functional integration are paramount. A compelling go-to-market angle involves offering comprehensive software development kits and ecosystem support for RISC-V based designs.
For Investors and Strategic Acquirers:Distressed-cycle entries favor acquirers with strong balance sheets in advanced semiconductor design and manufacturing capabilities, particularly in regions like the United States and Europe. The long-term viability of high-performance computing and Edge AI workloads ensures sustained demand for application processors over the next decade. Acquisition targets should include fabless design houses specializing in RISC-V or specialized AI accelerators, along with companies innovating in advanced packaging solutions. The adoption rate of RISC-V in automotive or critical infrastructure applications is a key signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secures future supply of advanced process nodes for leading-edge application processors. |
| Strategic Partnership | Facilitates joint development of next-generation architectures and mitigates R&D costs. |
| Technology Licensing | Expands market reach for proprietary IP and generates recurring revenue streams. |
| Ecosystem Development | Fosters broader adoption of new instruction sets like RISC-V across diverse applications. |
| Advanced Packaging Investment | Enables higher performance and miniaturization for multi-chip module processors. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a broad understanding of market dynamics and regional trade flows for application processors. This was triangulated with primary interviews conducted with semiconductor design engineers, foundry executives, automotive electronics procurement managers, and smartphone OEM product leads. The approach incorporated both bottom-up market sizing from individual product segments and top-down validation against macroeconomic indicators.
Market segmentation was modeled at a granular level across processor type, device application, integration level, end-user segment, and regional demand patterns over the projection horizon. Compound Annual Growth Rates (CAGRs) were derived from historical trends, projected technological shifts, and expert consensus on future adoption rates. Industry-specific forecast inputs included advancements in semiconductor process node technology and the global expansion rates of 5G network infrastructure.
Revisions become necessary when significant geopolitical events, unexpected technological breakthroughs, or major shifts in regulatory frameworks materialize within the application processor market. Forecasts reflect assumptions regarding economic stability and predictable innovation cycles. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Data Center Chip Market
Chipset and Processors
Europe Wi-Fi Chipset Market
Chipset and Processors
High-Performance Dual-Core Processor Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Automotive Gateway Chips Market
Chipset and Processors
Consumer Electronics Chip Market
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
PLL Clock Generator Market
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
Car Chip Market
Chipset and Processors
ARM-Based Servers Market
Chipset and Processors
Tablet Application Processor Market
Chipset and Processors
Artificial Intelligence (AI) Chipsets Market
Chipset and Processors
Processor Chip Market
Chipset and Processors
Tablet and E-Reader Application Processor Market
Chipset and Processors
South Korea Data Center Processor Market