
 Latin America Neuromorphic Chip Market | 2026-2036
Latin America Neuromorphic Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Neuromorphic Chip Market Foresight
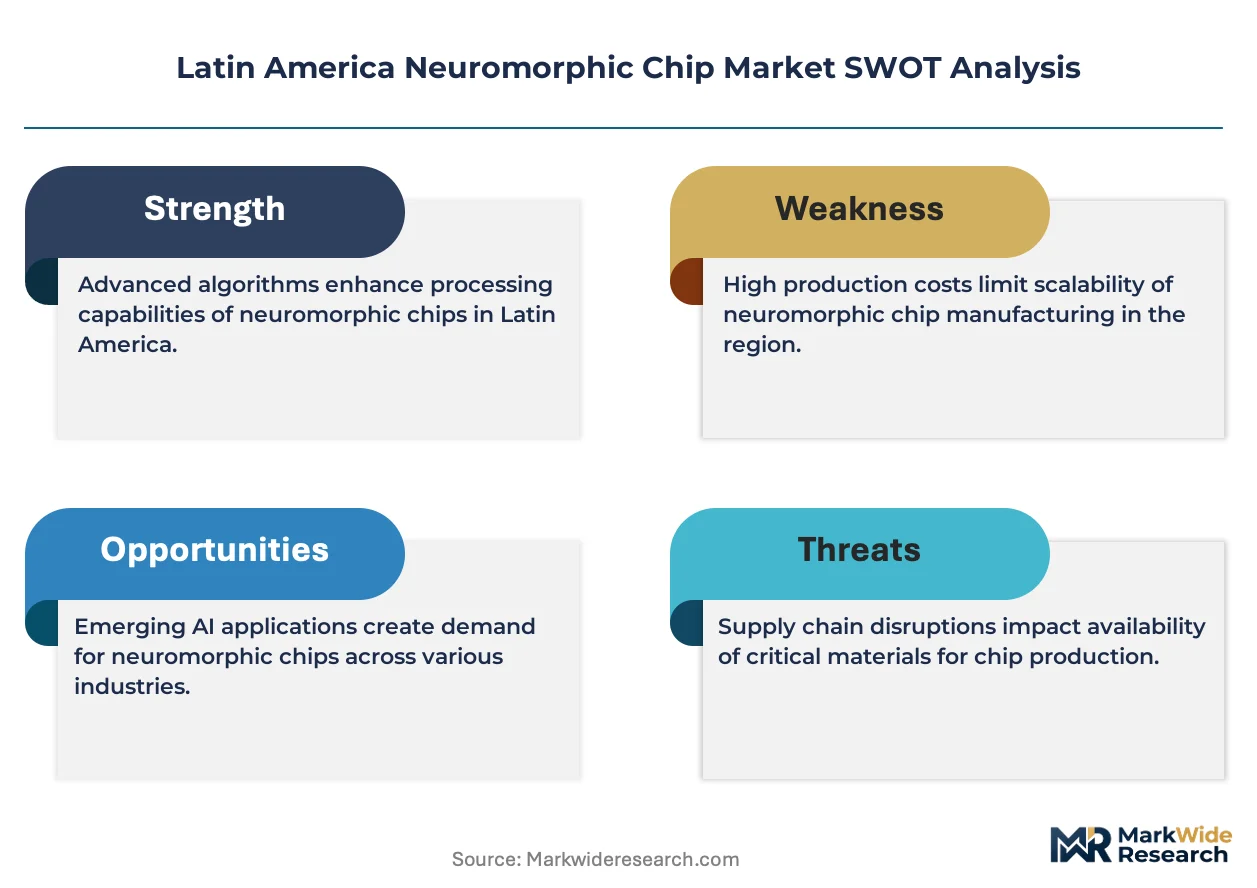
A shortage of analog-mixed-signal designers is redrawing competitive boundaries across Latin America. BrainChip Holdings Ltd leverages its Akida architecture to target edge AI deployments with ultra-low power budgets. Intel Corporation anchors regional demand through its Loihi research platforms and university partnerships in Mexico and Brazil. Qualcomm Incorporated competes by extending its Snapdragon portfolio into neuromorphic-adjacent sensor fusion for automotive Tier-1 suppliers.
Neuromorphic chips are integrated circuits that emulate biological neural architectures through spiking neuron models and memristive synaptic arrays, typically fabricated at nodes between 22nm and 65nm with event-driven activation schemes that consume sub-milliwatt standby power; their primary purpose is enabling real-time pattern recognition and adaptive learning in power-constrained edge devices. Digital chips currently dominate volume shipments due to mature CMOS compatibility and foundry accessibility, while event-driven architectures represent the fastest-growing product category as Brazilian industrial IoT vendors prioritize asynchronous processing for vibration monitoring and predictive maintenance. Memristor-based implementations capture concentrated R&D investment from São Paulo-based research consortia seeking non-volatile synaptic storage for always-on wearable diagnostics.
Brazil's national telecommunications regulator ANATEL certifies electromagnetic compatibility for edge AI modules deployed in connected vehicle infrastructure, while Mexico's Ministry of Economy coordinates semiconductor workforce standards through its federal innovation programs. Argentina's national standards body IRAM maintains electromagnetic emissions protocols that constrain import timelines for non-compliant neuromorphic accelerators. Stakeholders must monitor how Chile's proposed data center energy regulations will reshape locational decisions for neuromorphic inference clusters serving Pacific Rim latency requirements.
Market Dynamics
Analog-mixed-signal designer scarcity is compressing competitive timelines across Latin America, forcing fabless houses in São Paulo to poach talent from automotive sensor divisions and slowing time-to-tapeout for industrial automation clients.
Growth Catalysts
- ANATEL certification pathways:Brazil's telecommunications regulator streamlines electromagnetic compatibility approvals for edge AI modules in connected vehicle infrastructure, accelerating deployment timelines for Tier-1 automotive suppliers.
- Event-driven architectures:Brazilian industrial IoT vendors prioritize asynchronous processing for vibration monitoring and predictive maintenance, pulling demand for ultra-low-power inference hardware.
- Memristor R&D concentration:São Paulo-based research consortia channel federal innovation funding into non-volatile synaptic storage for always-on wearable diagnostics.
Market Restraints
- Analog-mixed-signal talent scarcity:Regional engineering programs graduate insufficient designers proficient in sub-threshold circuit design, constraining fabless house expansion.
- IRAM emissions protocols:Argentina's national standards body maintains electromagnetic compatibility requirements that extend import certification timelines for non-compliant neuromorphic accelerators.
- Digital CMOS foundry lock-in:Mature 22nm to 65nm fabrication nodes dominate accessible regional foundry capacity, limiting memristor-based device prototyping.
Strategic Opportunities
- Chilean data center energy regulations:Proposed efficiency mandates for inference clusters serving Pacific Rim latency requirements will reshape locational decisions for neuromorphic edge deployments.
- University partnership pipelines:Mexico's federal innovation agency coordinates semiconductor workforce standards that expand the regional engineering pipeline for spiking neural network research.
- Automotive sensor fusion convergence:Integration of neuromorphic inference with lidar and radar processing creates specification white space for Brazilian OEM electronics divisions.
Industry Challenges
- Event-driven programming expertise gap:Embedded systems clusters lack sufficient firmware engineers trained in asynchronous spiking neuron model implementation.
- Legacy industrial protocol integration:Fieldbus and EtherCAT compatibility requirements complicate retrofit deployments for predictive maintenance accelerators in São Paulo manufacturing plants.
- Multi-jurisdiction certification stacking:Separate ANATEL, IRAM, and federal innovation agency approval processes extend product launch timelines for regional fabless vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Neuromorphic Chip Market |
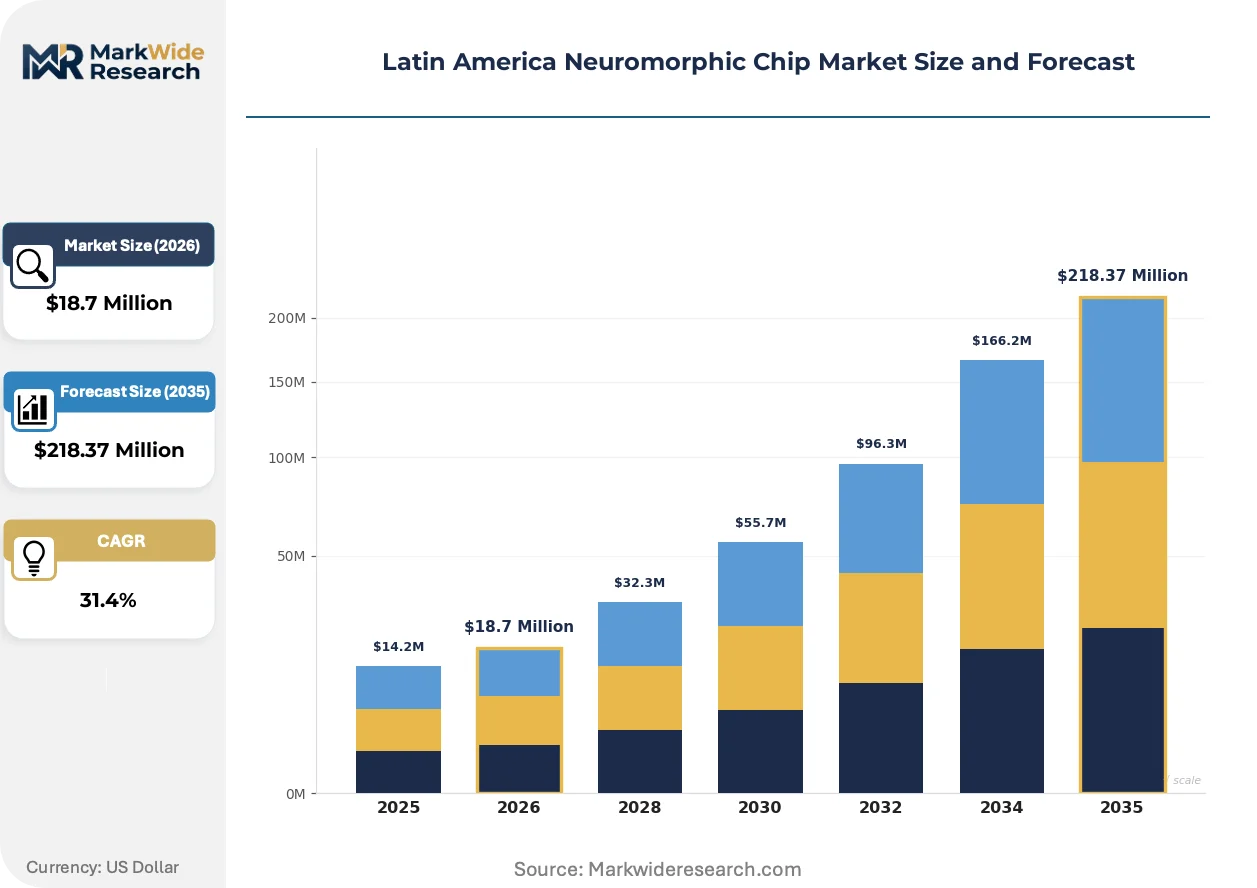
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $218.37 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Chips, Digital Chips, Hybrid Chips, Event-Driven Chips Application: Machine Learning, Robotics, Image Processing, Natural Language Processing End User: Automotive, Consumer Electronics, Aerospace, Healthcare Technology: Memristors, Spintronics, Optical Neurons, Quantum Circuits |
| Companies Covered | Intel Corporation, IBM Corporation, BrainChip Holdings Ltd, Samsung Electronics Co., Ltd., Qualcomm Incorporated, Hewlett Packard Enterprise Co, SK hynix Inc., NXP Semiconductors, SynSense, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Neuromorphic Chip Market Shifts & Advancements
Spiking neural network architectures are redrawing hardware-software boundaries across Latin American edge deployments. Three developments are compressing competitive positioning.
Memristor-based synaptic arrays are displacing static RAM implementations in always-on wearable diagnostic prototypes. São Paulo research consortia are fabricating test devices at accessible 65nm nodes. The shift is compressing standby power budgets below one milliwatt for continuous vital sign monitoring applications.
ANATEL's electromagnetic compatibility framework for connected vehicle infrastructure is tightening certification requirements for edge AI modules. Brazilian automotive electronics divisions must demonstrate spurious emission suppression across 400 MHz to 6 GHz bands. Tier-1 suppliers are front-loading pre-compliance testing to avoid retest cycles that delay production ramp.
Buyer concentration among São Paulo industrial automation clusters is compressing vendor negotiation cycles. Procurement teams at embedded systems houses now bundle neuromorphic inference hardware with predictive maintenance software licenses. Mexican federal innovation agency workforce programs are responding by embedding commercial negotiation modules into semiconductor engineering curricula.
Latin America Neuromorphic Chip Market Segmentation
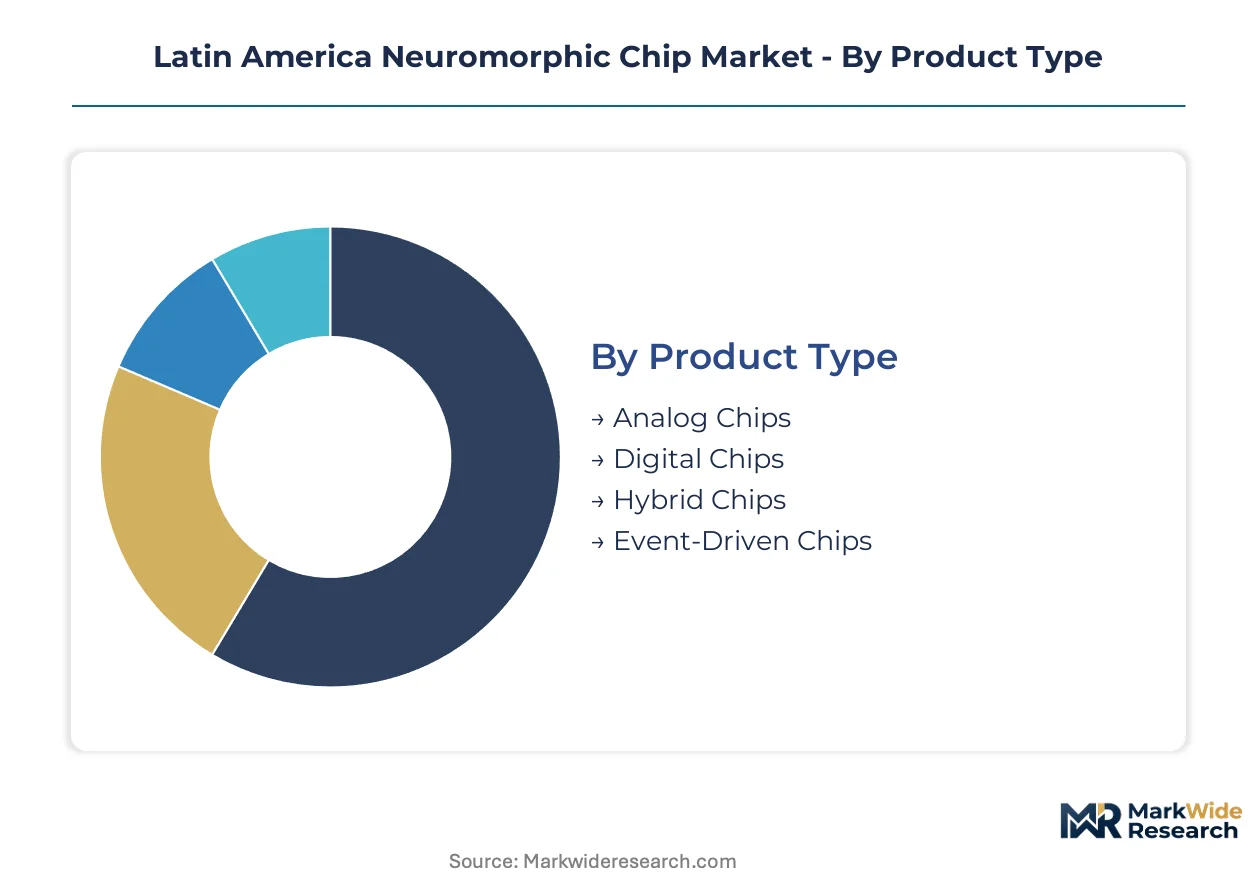
Neuromorphic chip architectures in Latin America fragment across competing implementation philosophies, each carrying distinct foundry dependencies and power-performance trade-offs. Procurement teams in São Paulo and Mexico City evaluate these segments against specific latency budgets and certification pathways.
Product Type:
Substitution pressure from conventional GPU and FPGA accelerators weighs heaviest on digital implementations, forcing analog and hybrid architectures to differentiate through sub-threshold power efficiency.
- Digital Chips:Fabricated at mature 22nm to 65nm CMOS nodes with synchronous clocking and static RAM synaptic storage. São Paulo's industrial automation cluster sources these for predictive maintenance deployments where foundry accessibility outweighs power optimization.
- Event-Driven Chips:Asynchronous activation schemes fire only on input spikes, compressing standby power below one milliwatt for always-on sensor nodes. Brazilian automotive Tier-1 suppliers specify these for connected vehicle edge modules subject to ANATEL electromagnetic compatibility certification.
- Analog Chips:Sub-threshold circuit designs emulate biological neuron dynamics through continuous current-mode computation. Research consortia in Mexico's federal innovation programs prototype these for wearable diagnostic applications.
- Hybrid Chips:Mixed-signal architectures partition computation between analog neuron cores and digital synaptic routing. Argentina's IRAM emissions protocols constrain import timelines for non-compliant variants.
Digital chips retain volume leadership; event-driven chips hold the steepest expansion curve.
Application:
Cost tier stratification separates high-compute training workloads from inference-optimized edge deployments, with robotics and image processing commanding premium pricing.
- Image Processing:Convolutional spiking neural networks execute real-time feature extraction for lidar and radar fusion in Brazilian OEM electronics divisions. ANATEL certification requirements for 400 MHz to 6 GHz spurious emission suppression front-load pre-compliance testing costs.
- Robotics:Closed-loop motor control and tactile sensing demand sub-millisecond latency from neuromorphic inference hardware. Mexican workforce development programs embed commercial negotiation modules to address buyer concentration among São Paulo procurement teams.
- Machine Learning:Pattern recognition workloads span supervised and unsupervised training paradigms with varying synaptic plasticity requirements.
- Natural Language Processing:Sequential audio processing for voice command interfaces in consumer electronics drives demand for recurrent spiking architectures.
Image processing commands the highest average selling prices; robotics is climbing the fastest.
End User:
Application maturity diverges sharply, with automotive and consumer electronics pushing toward volume production while aerospace and healthcare remain in qualification phases.
- Automotive:Connected vehicle infrastructure and sensor fusion applications specify neuromorphic accelerators for vibration monitoring and predictive maintenance. Brazilian manufacturing plants require EtherCAT and Fieldbus compatibility for retrofit deployments.
- Healthcare:Always-on wearable diagnostics prioritize memristor-based non-volatile synaptic storage for continuous vital sign monitoring. São Paulo research consortia fabricate test devices at accessible 65nm nodes.
- Consumer Electronics:Voice assistants and gesture recognition interfaces drive integration with Snapdragon-adjacent sensor fusion platforms.
- Aerospace:Radiation-hardened requirements and extended qualification timelines limit near-term procurement volume.
Automotive retains volume leadership; healthcare holds the steepest expansion curve.
Technology:
Supply concentration in accessible foundry capacity favors memristor implementations, while optical and quantum approaches face multi-year development horizons.
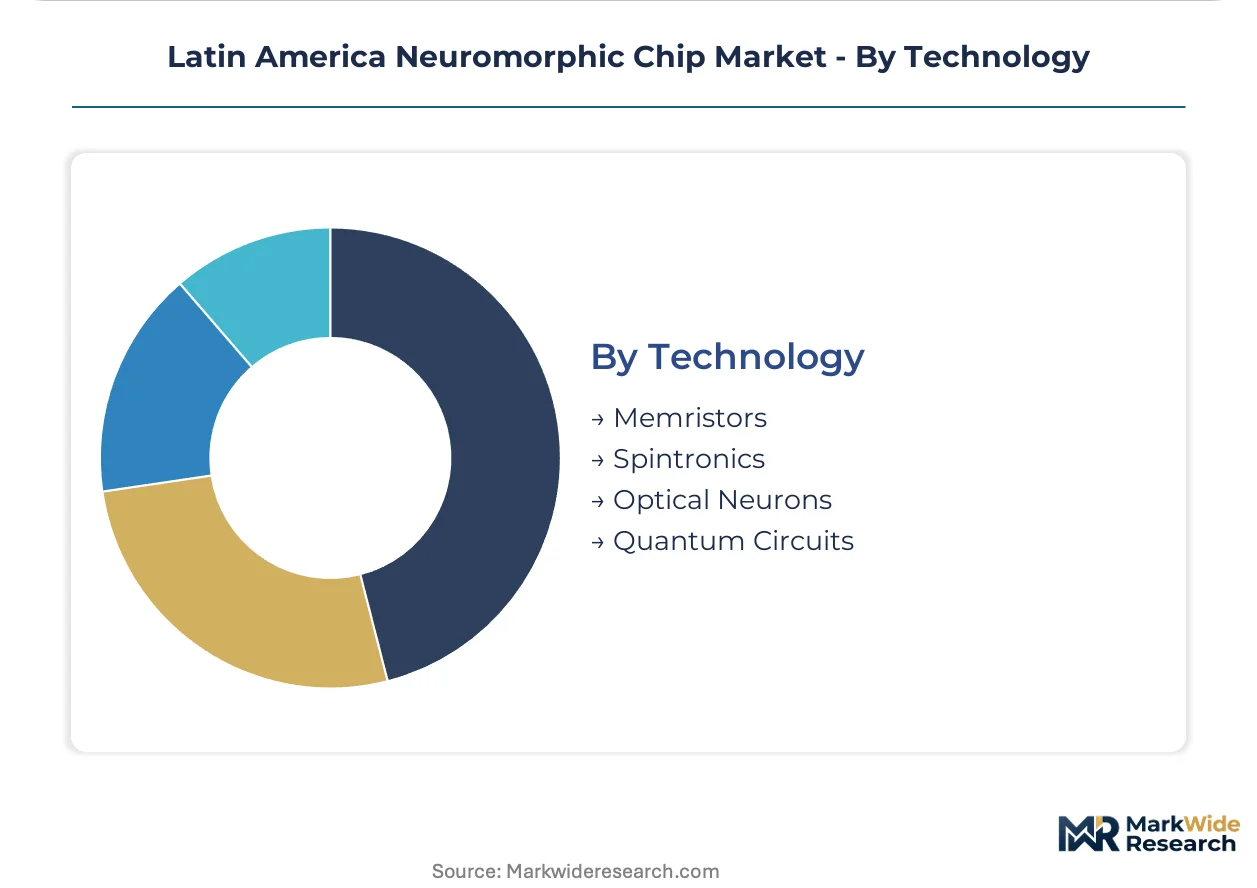
- Memristors:Non-volatile resistive switching elements provide dense synaptic storage without refresh power, enabling always-on operation. São Paulo-based research consortia channel federal innovation funding into 65nm prototyping runs.
- Spintronics:Magnetic tunnel junction devices exploit electron spin for ultra-low-power computation with inherent non-volatility. Mexican university partnerships investigate these for spiking neural network research platforms.
- Optical Neurons:Photonic integration promises femtojoule per spike energy efficiency but requires exotic foundry processes unavailable regionally.
- Quantum Circuits:Superconducting qubit implementations remain confined to research demonstrators with no near-term commercial procurement pathway.
Memristors retain volume leadership; spintronics holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANATEL anchors the dominant geography through electromagnetic compatibility certification for edge AI modules in Brazilian connected vehicle infrastructure. Mexico's federal innovation agency coordinates semiconductor workforce standards that expand regional engineering capacity. Argentina's IRAM emissions protocols and Chile's proposed data center regulations complete the regulatory landscape across the four major markets.
Brazil
Edge AI deployments in automotive manufacturing accelerate procurement of low-latency inference hardware. ANATEL certifies electromagnetic compatibility for modules deployed in connected vehicle infrastructure. São Paulo's embedded systems cluster concentrates demand where fabless design houses serve industrial automation clients with predictive maintenance accelerators.
Mexico
Federal innovation agency programs expand the semiconductor workforce pipeline for spiking neural network research. University partnerships anchor regional engineering capacity development in Mexico City and Monterrey. The Bajío Region automotive electronics divisions specify neuromorphic inference hardware for sensor fusion applications.
Argentina
IRAM maintains electromagnetic emissions protocols that constrain import timelines for non-compliant neuromorphic accelerators. Buenos Aires-based procurement teams navigate extended certification cycles for edge AI hardware. Córdoba's industrial automation sector sources predictive maintenance modules through Brazilian supply channels.
Chile
Proposed data center energy regulations reshape locational decisions for neuromorphic inference clusters serving Pacific Rim latency requirements. Santiago's cloud infrastructure operators evaluate efficiency mandates for edge deployment siting. The Valparaíso corridor attracts preliminary feasibility studies for low-latency inference facilities.
Latin America Neuromorphic Chip Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Latin America's neuromorphic chip market. The vendor base concentrates around three strategic tiers: established semiconductor conglomerates with research platforms, fabless specialists targeting ultra-low-power edge applications, and memory-integrated device manufacturers pursuing synaptic storage solutions. Competitive moves center on university partnership pipelines for workforce development and pre-compliance testing investments to accelerate ANATEL certification timelines.
Among research-platform specialists, Intel Corporation and IBM Corporation anchor the tier through university partnerships in Mexico and Brazil. BrainChip Holdings Ltd occupies a position within the fabless specialist archetype targeting edge AI deployments with event-driven architectures. Samsung Electronics Co., Ltd. represents the memory-integrated manufacturer category through non-volatile synaptic storage development. These three archetypes exemplify the competitive structure without single-player dominance.
| Leading Market Players |
|---|
| Intel Corporation |
| IBM Corporation |
| BrainChip Holdings Ltd |
| Samsung Electronics Co., Ltd. |
| Qualcomm Incorporated |
| Hewlett Packard Enterprise Co |
| SK hynix Inc. |
| NXP Semiconductors |
| SynSense |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety day tapeout cycles for 22nm to 65nm prototypes concentrate pricing power with São Paulo-based fabless houses serving ANATEL-certified automotive modules, while Mexican federal innovation agency workforce programs expand engineering capacity that moderates talent-premium inflation across the region.
Pricing Analysis
Price spreads between São Paulo and Mexico City run 12-18 percent for comparable event-driven inference modules, reflecting certification bundling with predictive maintenance software licenses as the dominant pricing structure. Price differentiation hinges on ANATEL electromagnetic compatibility tier and volume scale, with Tier-1 automotive suppliers commanding standard-tier rates and industrial automation clusters absorbing premium customization costs. Cost compression in digital CMOS implementations intensifies as Brazilian foundry accessibility improves, squeezing margins for non-differentiated suppliers. Healthcare wearable diagnostics buyers exhibit the highest price sensitivity due to memristor R&D funding dependencies, while automotive sensor fusion clients prioritize latency performance over unit economics.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for Latin American neuromorphic chip demand, with São Paulo-based research consortia prototyping memristor devices at accessible 65nm nodes locally. The supply chain draws from silicon wafers, analog-mixed-signal IP libraries, and electromagnetic shielding materials as critical inputs. Single-source vulnerability concentrates in advanced node lithography equipment subject to export control restrictions. Distribution runs through São Paulo's embedded systems cluster for industrial automation clients, with direct procurement relationships dominating automotive Tier-1 supplier channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance software licensing expands faster than hardware unit shipments, creating recurring revenue layers that justify upfront silicon development costs.
For Market Incumbents: Secure analog-mixed-signal design talent through acquisition of São Paulo fabless houses facing tapeout delays, while expanding ANATEL pre-compliance testing infrastructure to compress certification cycles for Tier-1 automotive clients. Backward integration into memristor R&D consortia protects synaptic storage roadmaps against emerging spintronics competitors. For New Entrants and Emerging Players: Anchor in Mexico's federal innovation agency workforce pipeline to access subsidized engineering capacity for spiking neural network firmware development, targeting healthcare wearable diagnostics as the most penetrable segment given concentrated buyer relationships with São Paulo research consortia. A licensing-first go-to-market model reduces foundry capex requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from memory-integrated device manufacturers with dormant neuromorphic IP portfolios and established non-volatile storage fabrication relationships. Long-term viability hinges on event-driven architecture adoption curves across Brazilian industrial IoT deployments. The signal to watch is ANATEL certification queue depth as a real-time indicator of automotive demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ANATEL Pre-Compliance Testing Investment | Front-loaded electromagnetic compatibility validation compresses Tier-1 supplier production ramp timelines. |
| University Partnership Pipeline Expansion | Mexican federal innovation agency programs embed commercial negotiation modules into semiconductor engineering curricula. |
| Memristor R&D Consortium Formation | São Paulo-based federal innovation funding channels enable 65nm prototyping for always-on wearable diagnostics. |
| Predictive Maintenance Software Licensing | Procurement teams at São Paulo embedded systems houses bundle inference hardware with recurring service contracts. |
| Automotive Sensor Fusion Integration | Brazilian OEM electronics divisions specify neuromorphic accelerators for lidar and radar processing convergence. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fabless design house executives, Tier-1 automotive supplier procurement leads, and ANATEL certification engineers; and secondary validation through SEC semiconductor filings, ANATEL electromagnetic compatibility registries, and Mexican federal innovation agency workforce program disclosures. Bottom-up unit shipment estimates triangulated against top-down addressable market calculations.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product architecture type, application latency tier, end-use industry maturity, and technology implementation node. CAGRs derived from regression analysis of historical foundry capacity expansion and certification timeline compression. Industry-specific inputs included ANATEL queue depth data and São Paulo industrial automation cluster procurement cycle observations.
Material uncertainties — analog-mixed-signal talent availability, ANATEL regulatory reinterpretation, and memristor fabrication yield rates — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision triggers in these domains. Recalibration cycles align with material shifts in federal innovation agency funding allocations and automotive sensor fusion specification releases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Europe MPU Market
Chipset and Processors
Hybrid Chip Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Graphics Processing Unit (GPU) Market
Chipset and Processors
DNA Sequencing Chip Market
Chipset and Processors
Multi-Mode Chipset Market
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
Server Microprocessor Market
Chipset and Processors
Spain Data Center Processor Market
Chipset and Processors
Micro Server IC Market
Chipset and Processors
India Data Center Processor Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
Nano Chip Market
Chipset and Processors
PLL Clock Generator Market
Chipset and Processors
China Data Center Processor Market
Chipset and Processors
Americas Digital Signal Processor Market