
 Global Microcontroller (MCU) Market | 2026-2036
Global Microcontroller (MCU) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microcontroller (MCU) Market Analytics
Platform licensing revenue is fragmenting across the MCU value chain as semiconductor vendors diversify beyond silicon sales. STMicroelectronics leverages its STM32 ecosystem to anchor developer loyalty through toolchains and reference designs. Texas Instruments sustains margin pools with proprietary analog integration alongside its MSP430 and C2000 families. Infineon Technologies dominates automotive-grade MCU supply through its AURIX platform and backward integration into power semiconductor fabrication.
A microcontroller is a self-contained system-on-chip integrating a processor core, volatile and non-volatile memory, and programmable peripheral interfaces on a single die, typically fabricated at process nodes from 90nm to 40nm for mainstream applications and operating at clock frequencies from 16 MHz to 480 MHz depending on architecture class. Its primary commercial purpose is deterministic real-time control of electromechanical systems with minimal external component count. The 32-bit and ARM Cortex categories command the deepest margin pools as embedded Linux and real-time operating system requirements displace legacy 8-bit designs in industrial automation and robotics applications. Automotive end-use demand for functional safety-certified MCUs outpaces consumer electronics growth, while Wi-Fi and Bluetooth connectivity integration is becoming standard rather than optional across smart meter and wearable device deployments.
FDA device regulations in the United States, EU MDR requirements for medical electronics, and China's GB standards administered by SAMR collectively elevate barrier thresholds for MCU suppliers targeting healthcare and automotive applications. REACH and RoHS compliance in Europe restricts hazardous substance use in semiconductor packaging materials, directly influencing foundry partner selection and bill-of-materials costs. Stakeholders must monitor how functional safety certification tiers and connectivity protocol standardization reshape procurement criteria across automotive and industrial buyer segments.
Market Dynamics
Automotive electrification and functional safety mandates are forcing MCU suppliers to requalify entire product portfolios for ISO 26262 certification tiers, compressing development timelines while expanding addressable silicon content per vehicle.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates are accelerating compressor controller upgrades across HVAC systems, requiring new MCU architectures with integrated motor control peripherals.
- ADAS sensor fusion:Camera-radar integration in Level 2+ vehicles is expanding deterministic processing requirements beyond traditional powertrain domains into chassis and cabin systems.
- China EV production:Domestic battery electric vehicle output concentration in Shenzhen and Shanghai is pulling 32-bit automotive-grade MCU procurement volumes upward.
Market Restraints
- 300mm wafer allocation:Foundry capacity for 40nm automotive nodes concentrates among three Taiwan-based suppliers, creating single-source exposure for AEC-Q100 qualified die.
- Copper and gold wire bonding:Precious metal volatility in RoHS-compliant packaging materials is compressing gross margins on sub-dollar consumer-grade units.
- RISC-V ISA fragmentation:Divergent custom extensions across Chinese and Western implementations are fragmenting software toolchain compatibility.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for semiconductor assembly are creating localized demand for 16-bit motor control MCUs in textile and food processing equipment.
- Matter protocol convergence:Thread and Wi-Fi 6 integration is opening unified smart home controller architectures that collapse multiple discrete radios into single-SoC designs.
- EU Battery Regulation:Cell monitoring IC mandates are extending MCU content into battery management systems for stationary storage and second-life automotive packs.
Industry Challenges
- Functional safety certification backlog:ISO 26262 ASIL-D validation queues at TÜV and SGS are extending time-to-revenue for new automotive product introductions.
- Legacy 8-bit code migration:Assembler-based industrial control firmware lacks portable equivalents for ARM Thumb-2 instruction sets, forcing costly rewrite projects.
- Multi-die packaging yield:Embedded flash integration at 28nm nodes suffers from defect clustering that degradates wafer-level test economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microcontroller (MCU) Market |
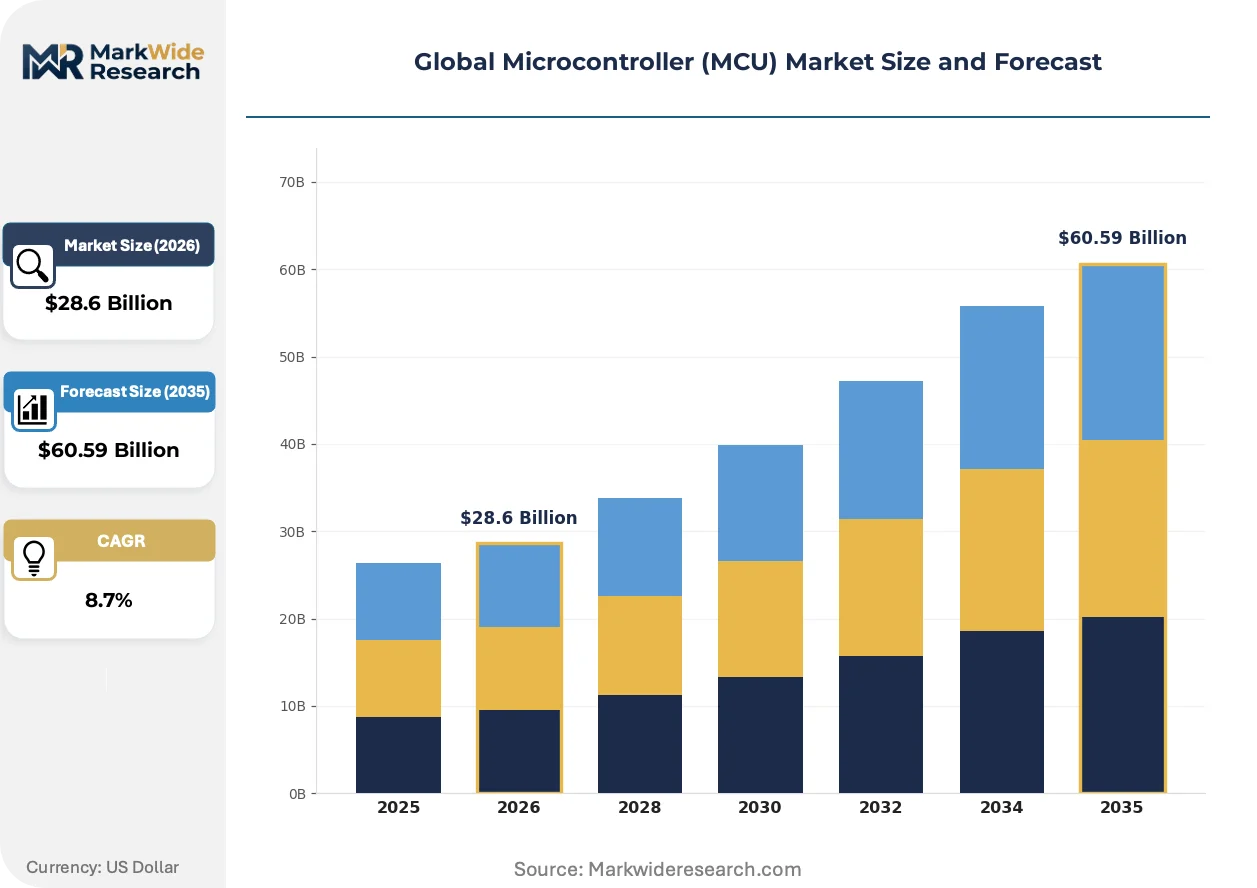
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 8-bit, 16-bit, 32-bit, ARM Cortex End User: Consumer Electronics, Automotive, Industrial Automation, Healthcare Application: Home Appliances, Wearable Devices, Smart Meters, Robotics Connectivity: Wi-Fi, Bluetooth, Zigbee, Ethernet |
| Companies Covered | STMicroelectronics, Texas Instruments, NXP Semiconductors, Toshiba, Samsung Electronics, Microchip Technology, Infineon Technologies, Rohm, Renesas Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microcontroller (MCU) Market Evolving Landscape
Deterministic edge computing requirements are dissolving the boundary between discrete MCUs and application processors, forcing architecture decisions around real-time capability versus Linux-class software stacks.
Embedded machine learning accelerators are digitizing vibration analysis and acoustic anomaly detection directly on factory floors. Discrete Fourier transform coprocessors in STM32U5 and RA6 families enable condition monitoring without cloud round-trips. Automotive tier-1s are adopting these subsystems for predictive brake pad and bearing wear algorithms.
REACH substance restrictions are banning lead-based solder alternatives in European-bound modules, forcing foundries to qualify bismuth-tin and silver-copper alloy metallurgies. Medical device OEMs face parallel EU MDR documentation burdens for MCUs with patient-contacting sensors. Japanese automotive suppliers are front-running these requirements through METI-funded green semiconductor initiatives.
Consolidated procurement desks at German and Korean automotive OEMs are collapsing vendor lists from twelve approved MCU suppliers to six, awarding multi-year sole-source contracts with attached engineering resource commitments. Tier-2 module makers must now qualify through these gatekeeper relationships rather than direct silicon vendor engagement. This concentration is most visible in powertrain controller categories where AURIX and S32K families dominate sourcing matrices.
Global Microcontroller (MCU) Market Segmentation
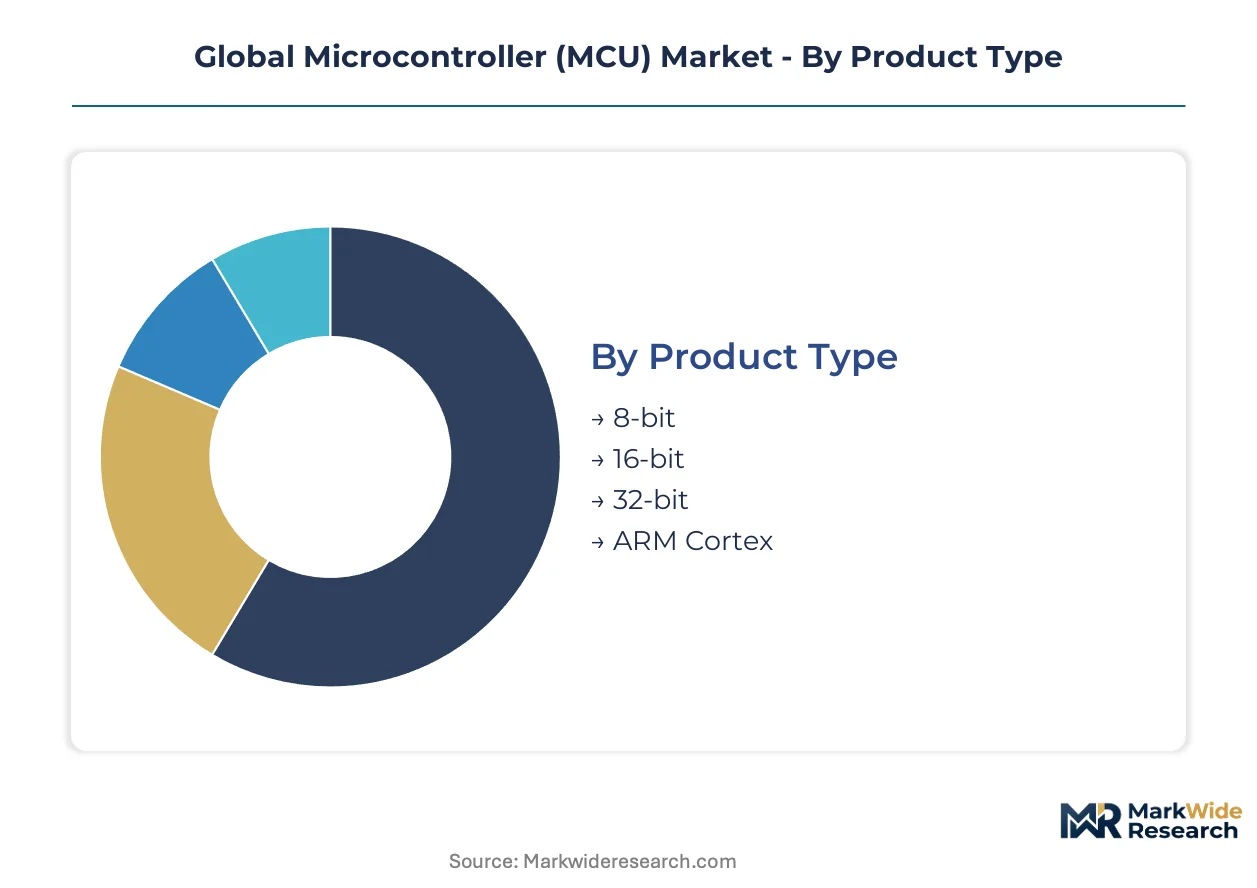
MCU procurement patterns diverge sharply across bit-width architectures and safety certification tiers. Supplier qualification requirements and toolchain migration costs create distinct competitive moats between product categories.
Product Type:
After-sales service intensity escalates with bit-width complexity, as 32-bit and ARM Cortex deployments demand ongoing firmware security patches and functional safety recertification support.
- 32-bit:These architectures integrate DSP extensions and hardware floating-point units for real-time control loops. Shenzhen and Shanghai EV manufacturers are standardizing on 32-bit MCUs for battery management and motor control, pulled by ISO 26262 ASIL-B certification mandates for powertrain modules.
- ARM Cortex:Cortex-M4 and M7 cores dominate industrial robotics through their Thumb-2 instruction efficiency and deterministic interrupt latency. German automotive tier-1s specify Cortex-M7 for chassis domain controllers, constrained by TÜV validation queues extending software release cycles.
- 8-bit:Legacy PIC and AVR architectures persist in cost-optimized home appliance motor drives.
- 16-bit:MSP430 and RL78 families anchor ultra-low-power sensor nodes in smart meter deployments.
By volume, 8-bit leads. By growth pace, 32-bit is expanding most quickly.
End User:
Margin structure varies dramatically across end-use verticals, with automotive functional safety certification creating 3-4x pricing premiums over consumer-grade equivalents.
- Automotive:AEC-Q100 Grade 0 qualification and ISO 26262 ASIL-D certification define entry barriers. Infineon AURIX and NXP S32K families capture powertrain and ADAS domain sockets, with Korean and German OEMs consolidating approved vendor lists to six suppliers.
- Industrial Automation:Real-time Ethernet protocols and safety PLC requirements favor 32-bit MCUs with integrated TSN hardware. Japanese METI-funded green semiconductor initiatives are accelerating RoHS-compliant packaging transitions for factory automation OEMs.
- Consumer Electronics:Price compression dominates white goods and wearable controller procurement.
- Healthcare:FDA 510(k) and EU MDR documentation burdens restrict MCU selection for patient-contacting diagnostic equipment.
Automotive commands the steepest pricing tiers. Healthcare is climbing fastest on regulatory upgrade cycles.
Application:
Application-specific peripheral integration determines socket win rates, as motor control PWM resolution and analog front-end precision become non-negotiable selection criteria.
- Robotics:Six-axis cobot controllers require sub-microsecond PWM synchronization and encoder interface flexibility. STM32G4 and RA6T2 families with high-resolution timers are displacing discrete DSP solutions in Shenzhen manufacturing equipment.
- Smart Meters:DLMS/COSEM protocol stacks and tamper detection accelerators define MCU selection for grid infrastructure. India's PLI scheme for semiconductor assembly is pulling 16-bit MSP430 volumes into domestic metering OEMs.
- Wearable Devices:Sub-threshold operation and compact WLCSP packaging dominate fitness tracker MCU specifications.
- Home Appliances:Variable-speed compressor control and touch-sensing integration drive white goods MCU refresh cycles.
Smart meters lead by deployment volume. Robotics is gaining share fastest on factory automation capex expansion.
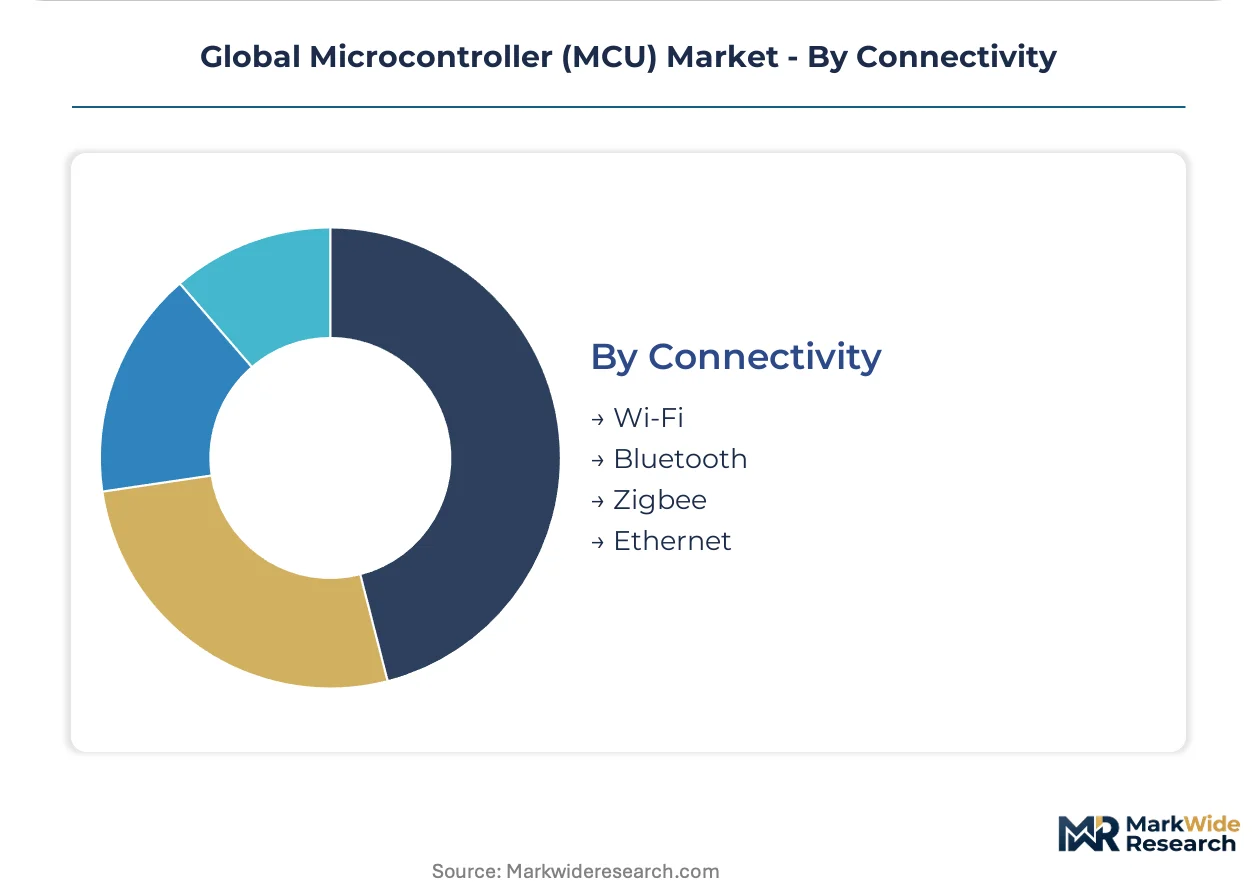
Connectivity:
Radio integration economics are collapsing discrete modem-BOM costs into single-SoC architectures, reshaping procurement criteria for IoT edge nodes.
- Wi-Fi:802.11ax (Wi-Fi 6) MAC/PHY integration with target wake time scheduling enables battery-operated smart home controllers. Matter protocol convergence is unifying Thread and Wi-Fi stacks into single-die implementations for unified smart home gateways.
- Bluetooth:LE Audio and Auracast broadcast capabilities are opening hearing aid and public address applications. Nordic Semiconductor and Silicon Labs dominate this socket with integrated protocol stacks.
- Zigbee:Smart lighting and utility metering maintain Zigbee 3.0 deployments for mesh reliability.
- Ethernet:Industrial TSN and automotive Ethernet (100BASE-T1) require dedicated MAC hardware with hardware timestamping.
Bluetooth leads by unit volume. Wi-Fi is expanding most quickly on smart home protocol consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese EV manufacturers exhibit the lowest price elasticity for automotive-grade MCUs, while European white goods OEMs negotiate aggressively on 8-bit consumer units. Indian industrial buyers occupy a middle tier, accepting modest premiums for localized assembly. German automotive procurement desks command the steepest certification-driven pricing tiers.
China
Shenzhen and Shanghai battery electric vehicle clusters are standardizing on 32-bit MCUs for battery management and motor control modules. SAMR-administered GB standards for functional safety are tightening component qualification protocols. The Pearl River Delta manufacturing corridor is pulling procurement volumes upward as domestic EV output concentrates in Guangdong and Zhejiang provinces.
Germany
KBA vehicle type-approval requirements are compressing MCU supplier lists from twelve to six approved vendors for powertrain controllers. The EU F-Gas Regulation is accelerating HVAC compressor controller upgrades requiring new motor control architectures. Bavarian automotive tier-1s in Munich and Ingolstadt are consolidating sole-source contracts with attached engineering commitments.
United States
FDA device regulations and EPA refrigerant phase-down mandates are elevating certification burdens for MCUs in medical diagnostics and HVAC systems. NHTSA functional safety guidelines are reshaping ADAS domain controller procurement. Texas and Michigan industrial automation hubs are driving demand for real-time Ethernet-capable 32-bit architectures.
Japan
METI-funded green semiconductor initiatives are accelerating RoHS-compliant packaging transitions for factory automation OEMs. JIS standards for industrial equipment are mandating extended temperature-range MCU specifications. Nagoya and Osaka automotive supplier clusters are front-running REACH substance restrictions through bismuth-tin alloy metallurgy qualifications.
India
PLI scheme incentives for semiconductor assembly are creating localized demand for 16-bit motor control MCUs in textile and food processing equipment. BIS certification requirements for smart meters are shaping procurement criteria for DLMS/COSEM protocol stacks. Gujarat and Maharashtra industrial corridors are absorbing MSP430 and RL78 family volumes into domestic metering OEM supply chains.
Global Microcontroller (MCU) Market Competitive Landscape
Capability concentration sits with automotive-grade certification specialists; scale advantage sits with broad-line semiconductor houses with multi-market exposure. The vendor base stratifies into three tiers: functional safety-certified automotive specialists, industrial-focused ecosystem providers, and consumer-optimized cost leaders. Strategic moves center on backward integration into power semiconductor fabrication and multi-year sole-source contract capture at consolidated German and Korean OEM procurement desks.
Within the automotive-certified tier, Infineon Technologies and NXP Semiconductors exemplify suppliers anchoring powertrain and ADAS domain sockets through AURIX and S32K platform dominance. Texas Instruments occupies a position bridging industrial and automotive segments through proprietary analog integration alongside its MSP430 and C2000 families. STMicroelectronics represents the ecosystem-centric archetype, leveraging STM32 toolchains and reference designs to anchor developer loyalty across robotics and smart meter applications.
| Leading Market Players |
|---|
| STMicroelectronics |
| Texas Instruments |
| NXP Semiconductors |
| Toshiba |
| Samsung Electronics |
| Microchip Technology |
| Infineon Technologies |
| Rohm |
| Renesas Electronics |
| Others |
Value Network & Pricing Analysis
Taipei-based foundry capacity for 40nm automotive nodes anchors global MCU pricing power, with wafer allocation queues at three Taiwan-based suppliers compressing margins for fabless vendors while concentrating negotiation leverage among vertically integrated IDMs. This geographic chokepoint feeds downstream into tiered contract structures that separate automotive-grade ASIL-certified silicon from consumer-grade spot procurement.
Pricing Analysis
Long-term offtake agreements dominate automotive MCU procurement, with German and Korean OEMs locking multi-year sole-source contracts at premium tiers while spot-market volatility runs through consumer-grade 8-bit units. Price differentiation hinges on ISO 26262 certification grade and volume scale, with ASIL-D validated silicon commanding substantial premiums over industrial-grade equivalents. Pricing pressure stems from precious metal volatility in RoHS-compliant packaging materials, compressing gross margins on sub-dollar consumer units. Tier-2 module makers exhibit the highest price sensitivity, while consolidated automotive procurement desks accept steep premiums for attached engineering resource commitments.
Supply Chain Analysis
Export-control regimes restricting advanced lithography equipment to Chinese fabs are fragmenting MCU supply geography toward Taiwan, South Korea, and Japan. Raw material dependencies center on 300mm silicon wafers, copper and gold wire bonding alloys, and AEC-Q100 qualified packaging substrates. Single-source vulnerability concentrates at automotive-grade 40nm nodes where three Taiwan-based suppliers control qualified die output. Distribution runs through consolidated procurement desks at German and Korean OEMs, with direct silicon vendor engagement collapsing in favor of tier-1 gatekeeper relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MCU markets are crossing a platform-economics inflection where ecosystem stickiness through toolchains and reference designs is displacing discrete silicon competition, with Matter protocol convergence and RISC-V toolchain fragmentation reshaping interoperability dynamics.
For Market Incumbents: Build certification moats by accelerating ISO 26262 ASIL-D validation pipelines ahead of TÜV and SGS queue backlogs. Expand backward integration into power semiconductor fabrication to capture margin pools currently leaking to external foundries. Defensive moves must counter RISC-V ISA fragmentation threatening ARM Cortex toolchain dominance, while channel control through tier-1 gatekeeper relationships insulates against fabless entrants.
For New Entrants and Emerging Players: India's industrial automation corridors present underpenetrated white-space for 16-bit motor control MCUs, with PLI scheme incentives lowering effective market entry costs. Target textile and food processing equipment OEMs in Gujarat and Maharashtra with localized assembly partnerships. Matter protocol convergence offers a go-to-market angle for unified smart home controller architectures collapsing discrete radios into single-SoC designs.
For Investors and Strategic Acquirers: Long-term, this sits as a functional safety certification play because automotive electrification is embedding irreversible ASIL-grade MCU content per vehicle. Acquisition targets should screen for automotive-certified product portfolios with existing TÜV validation queues and tier-1 supplier relationships. The signal to watch is consolidation velocity at German and Korean OEM procurement desks, where vendor list compression from twelve to six approved suppliers indicates platform lock-in maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Grade 0 Qualification Acceleration | Shortens TÜV validation queues for automotive powertrain socket capture. |
| Backward Integration into Power Semiconductor Fabrication | Captures margin pools currently externalized to Taiwan-based foundry partners. |
| Matter Protocol Stack Integration | Collapses Thread and Wi-Fi 6 radios into unified smart home gateway designs. |
| India PLI Scheme Localization | Positions MSP430 and RL78 family volumes into domestic metering OEM supply chains. |
| Multi-year Sole-source Contract Capture | Locks engineering resource commitments at consolidated German automotive procurement desks. |
Research Methodology
Desk research of SEC semiconductor filings, customs trade data, and AEC-Q100 qualification databases preceded structured interviews with MCU product managers at automotive tier-1 suppliers, foundry capacity planners, and industrial automation procurement leads. Primary fieldwork with platform engineering teams and secondary validation against IHS Markit vehicle production data and SAMR GB standard disclosures enabled bottom-up unit demand estimates triangulated with top-down semiconductor revenue aggregates.
Assumptions held fixed include foundry capacity allocation ratios across automotive and consumer nodes, ISO 26262 certification queue durations, and REACH substance restriction phase-in timelines. The analytical framework modeled segmentation across bit-width architecture, functional safety certification tier, connectivity integration, and regional production cluster throughout the forecast period. CAGRs derived from unit shipment trajectories indexed to EV powertrain controller penetration and industrial automation capex cycles, with embedded flash yield assumptions at 28nm nodes feeding die cost sensitivity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese RISC-V specialists or unexpected foundry capacity additions would shift outcomes. Material shifts in EU F-Gas Regulation enforcement timelines or Taiwan Strait logistics disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Edge AI Chipset Market
Chipset and Processors
Application Processor Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
India Data Center Processor Market
Chipset and Processors
NB-IoT Chipset Market
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Consumer Electronics Chip Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Surgical Chips Market
Chipset and Processors
Microserver Market
Chipset and Processors
Wireless Charging Ics Market
Chipset and Processors
Spain Data Center Processor Market
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
Multi-Core Processors Market