
 Global Laser Tracker Market | 2026-2036
Global Laser Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laser Tracker Market Outlook
REACH substance restrictions and EU machinery safety directives are broadening the cost-of-entry calculus for laser tracker vendors serving European industrial customers. Hexagon AB leverages its Sweden-based manufacturing footprint to sustain compliance advantages across CE-marked product lines. FARO Technologies anchors its competitive position through specialized portable tracker configurations that navigate diverse factory floor environments. Automated Precision, Inc. differentiates via R&D intensity in interferometry-based measurement algorithms.
A laser tracker is a portable coordinate measuring instrument that employs laser interferometry and angular encoders to determine three-dimensional positions with micron-level precision, typically operating over spherical measurement volumes exceeding thirty meters in diameter. The device serves primarily to verify geometric tolerances, align large-scale tooling, and validate as-built dimensions against CAD specifications in heavy manufacturing and engineering construction. Portable trackers occupy the dominant revenue position due to their deployment flexibility across automotive and aerospace production lines, while fixed tracker installations concentrate in semiconductor fabrication facilities where vibration-isolated measurement stations support wafer-stage calibration. Infrastructure tracker adoption accelerates in bridge and tunnel surveying applications where extended range and environmental sealing prove critical, though this segment remains narrower than portable alternatives.
FDA device quality regulations, ISO 10360 dimensional measurement standards, and China's GB calibration certification requirements collectively shape product development roadmaps and market access protocols for laser tracker manufacturers. The FDA's emphasis on traceable measurement records in medical device production creates specialized demand for audit-ready metrology workflows, while China's SAMR-administered GB standards mandate domestic calibration laboratory partnerships for imported equipment. Stakeholders must monitor evolving MDR traceability requirements in Europe and assess whether dual-carbon compliance pressures in China will accelerate domestic tracker production capabilities.
Market Dynamics
AS9100 quality mandates in aerospace manufacturing are compressing tolerance verification cycles, forcing metrology departments to absorb portable laser trackers into production-line workflows rather than isolate them in quality labs.
Growth Catalysts
- AS9100 Rev D Tightening:Aerospace suppliers in Germany and the United States face mandatory first-article inspection protocols that demand spherical coordinate verification across assembly jigs exceeding fifteen meters.
- East Asian Automotive JIT:Just-in-time dimensional inspection at Toyota City and Hyundai Motor's Ulsan complex reduces rework costs by catching tooling drift before serial production begins.
- Interferometry Algorithm Advances:Multi-path error compensation software now enables reliable tracking through factory floor thermal gradients that previously destabilized measurement confidence.
Market Restraints
- Precision Optics Input Concentration:German and Japanese suppliers dominate stabilized HeNe laser tube manufacturing, exposing tracker OEMs to single-source fragility in vacuum-sealed cavity components.
- REACH Substance Compliance:ECHA restrictions on lead-containing optical coatings force reformulation of retroreflector assemblies, extending R&D cycles by twelve to eighteen months for CE-marked product lines.
- Indoor GPS Substitution:Ultrawideband local positioning systems from Pozyx and Ubisense capture dimensional data at lower capital cost for applications tolerating sub-millimeter accuracy.
Strategic Opportunities
- Indian Defense Manufacturing:Offset obligations under the country's Defence Procurement Procedure compel foreign aerospace primes to establish local metrology capability for fighter airframe assembly.
- EU Green Deal Alignment:Carbon border adjustment mechanisms incentivize European heavy machinery exporters to document as-built dimensional compliance for remanufacturing and circular economy claims.
- LiDAR Convergence:Solid-state scanning modules from automotive autonomy programs are expanding into industrial metrology through time-of-flight integration with traditional interferometric architectures.
Industry Challenges
- Interferometry Specialist Scarcity:The pool of engineers capable of diagnosing multi-path error sources in spherical coordinate systems remains concentrated in Stuttgart, Tokyo, and Boston metropolitan clusters.
- Multi-Standard Certification Burden:Simultaneous pursuit of FDA 21 CFR Part 820 traceability for medical device clients, ISO 10360 calibration lab accreditation, and China's GB certification for SAMR compliance fragments quality engineering resources.
- Legacy CMM Integration:Bridge coordinate measuring machines from the 1990s dominate automotive stamping plant floors, forcing tracker deployments to accommodate incompatible data formats and probe compensation tables.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laser Tracker Market |
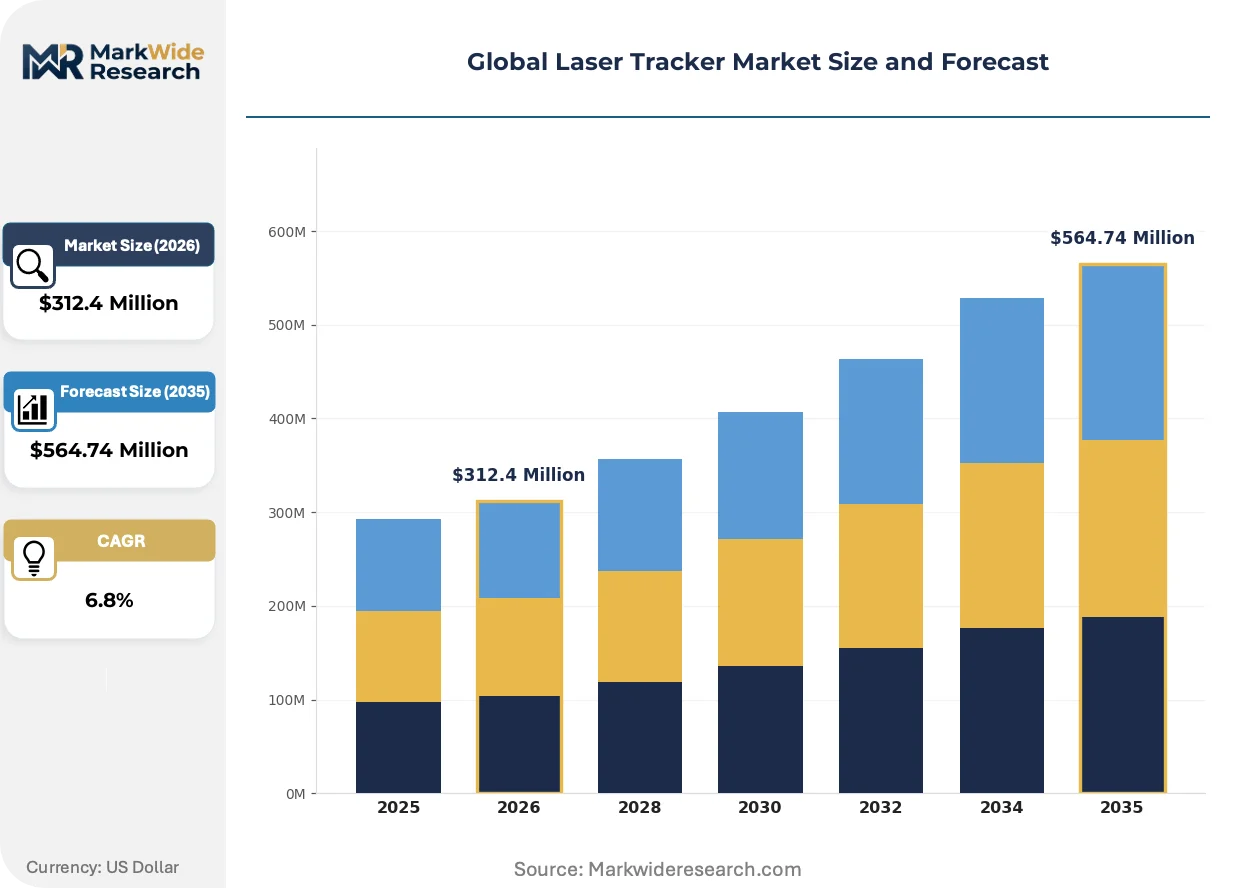
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Tracker, Fixed Tracker, Infrastructure Tracker, Hybrid Tracker End User: Manufacturing, Aerospace, Construction, Automotive Technology: Phase Shift, Time of Flight, 3D Laser Scanning, Optical Application: Dimensional Inspection, Reverse Engineering, Alignment, Quality Control |
| Companies Covered | Hexagon AB, FARO Technologies, Inc., Automated Precision, Inc., Leica Geosystems AG, Mitutoyo Corporation, InnovMetric Software Inc., PLX Inc., CHOTEST TECHNOLOGY INC., VMT GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laser Tracker Market Strategic Shifts
Photogrammetry fusion and solid-state emitter architectures are displacing purely interferometric measurement paradigms, while regulatory traceability mandates in medical device and defense verticals reshape software development priorities.
Multistation photogrammetry is expanding into large-volume metrology through synchronized camera arrays that triangulate target positions without line-of-sight constraints. Wind turbine blade manufacturers in Denmark and Spain deploy these systems across nacelle assembly halls where tracker occlusion from cranes and scaffolding previously interrupted measurement sequences. The technology is expanding into applications previously reserved for laser interferometry, compressing the addressable market for entry-level portable trackers in civil engineering surveying.
REACH substance restrictions and RoHS recast obligations are forcing optical component suppliers to eliminate lead-based index-matching compounds from retroreflector assemblies. ECHA enforcement actions against non-compliant importers have triggered supply chain audits across Swedish and German tracker manufacturers, accelerating qualification of alternative glass-ceramic formulations. The regulatory pressure most severely affects infrastructure tracker segments where environmental sealing specifications previously relied on legacy solder-sealed optical windows.
After-sales service unbundling is fragmenting traditional hardware-plus-support contracts into subscription-based calibration and software maintenance tiers. Automotive tier-one suppliers in Stuttgart and Wolfsburg now procure tracker hardware through capital budgets while routing annual recertification through operational expenditure channels managed by Hexagon's regional service centers. The behavioral shift is most visible in Germany's automotive belt, where procurement departments resist bundled five-year service commitments in favor of usage-calibrated maintenance schedules.
Global Laser Tracker Market Segmentation
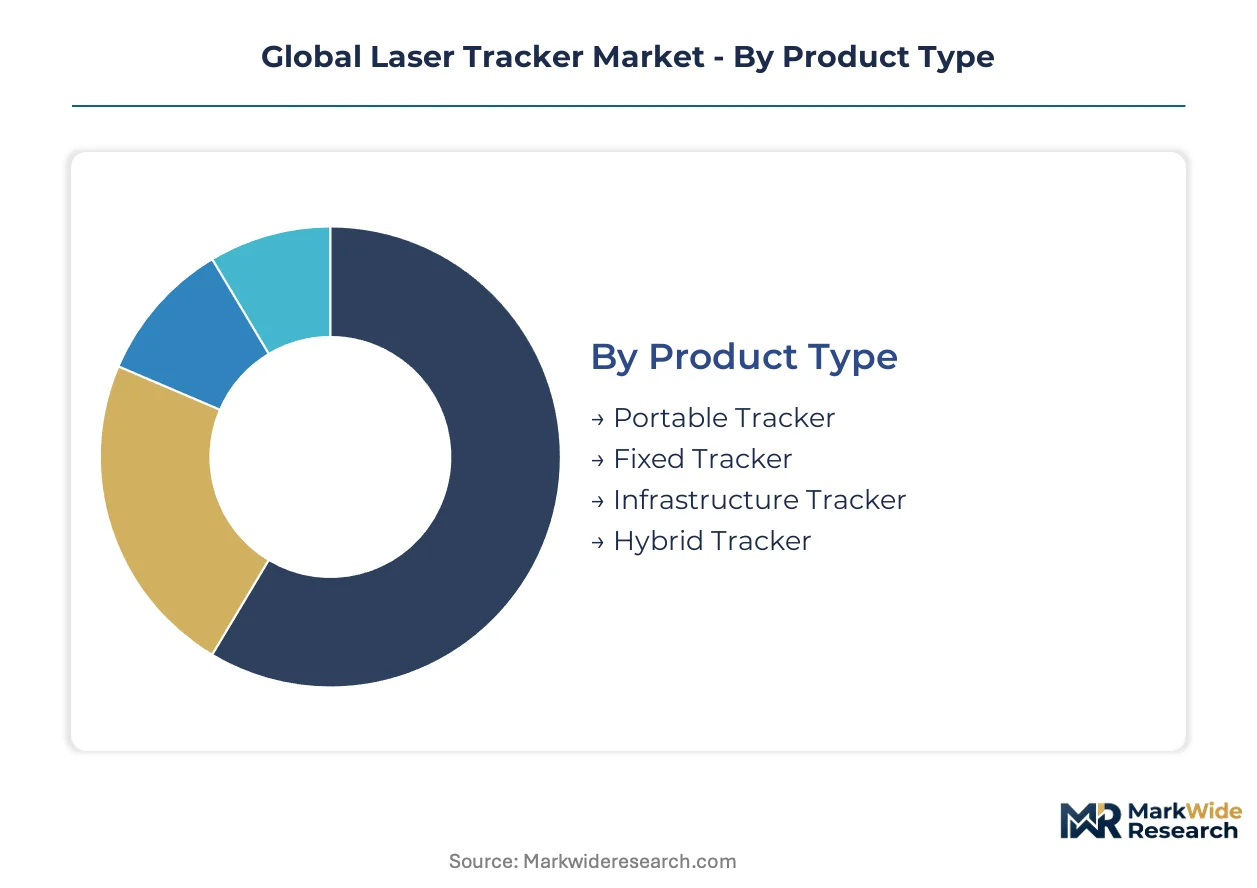
Laser tracker segmentation reveals divergent capital requirements across deployment models, with portable configurations demanding lower upfront investment than fixed installations while generating recurring service revenue. Technology choices determine optical subsystem complexity, creating tiered R&D intensity that separates interferometry specialists from time-of-flight integrators.
Product Type:
Capital intensity varies dramatically across installation permanence, with fixed trackers requiring vibration-isolated foundations and climate-controlled enclosures that multiply total cost of ownership.
- Portable Tracker:Battery-powered units with integrated controllers deploy directly to factory floors without civil works. Stuttgart automotive suppliers and Ulsan shipyards absorb the majority of shipments, driven by AS9100-mandated inline inspection protocols that eliminate work-in-process movement to quality labs.
- Fixed Tracker:Permanent installations in semiconductor fabs demand active vibration damping and thermal stabilization systems. Taiwan Semiconductor Manufacturing and Samsung's Pyeongtaek complex anchor demand for wafer-stage calibration stations where sub-micron repeatability justifies seven-figure capital commitments.
- Infrastructure Tracker:Extended-range units with sealed optical paths serve bridge surveying and tunnel alignment. German civil engineering contractors deploy these across Autobahn expansion projects where 80-meter spherical volumes replace total station networks.
- Hybrid Tracker:Modular architectures combining interferometric precision with photogrammetric coverage target wind turbine blade manufacturers. Vestas and Siemens Gamesa operations in Denmark and Spain pilot these for nacelle assembly halls where tracker occlusion previously interrupted sequences.
Portable trackers absorb the bulk of installed capacity; hybrid configurations are expanding most quickly.
End User:
Procurement authority structures differ sharply across verticals, with defense contractors requiring audit-ready traceability chains that automotive tier-ones rarely demand.
- Manufacturing:Heavy machinery producers in Germany's Ruhr region and Japan's Nagoya industrial corridor deploy trackers for large casting verification. Carbon border adjustment documentation requirements are accelerating metrology budget expansion for remanufacturing compliance claims.
- Aerospace:Boeing's Everett facility and Airbus Hamburg operations mandate spherical coordinate verification across wing assembly jigs exceeding fifteen meters. First-article inspection protocols under AS9100 Rev D compress tolerance verification cycles from weeks to hours.
- Construction:Civil engineering applications concentrate in German infrastructure megaprojects and Japanese Shinkansen extensions. Environmental sealing specifications for tunnel surveying exceed standard industrial ratings, narrowing qualified supplier pools.
- Automotive:Toyota City and Hyundai's Ulsan complex integrate trackers into just-in-time workflows. Tooling drift detection before serial production begins reduces rework costs that previously eroded margin on high-volume stamping programs.
Aerospace absorbs the bulk of premium-tier shipments; automotive applications are climbing the fastest.
Technology:
Intellectual property concentration separates established interferometry houses from emerging time-of-flight entrants leveraging automotive LiDAR spillover.
- Phase Shift:Heterodyne interferometry with stabilized HeNe laser tubes achieves sub-micron resolution over thirty-meter volumes. German and Japanese suppliers dominate vacuum-sealed cavity manufacturing, exposing OEMs to single-source fragility in critical optical inputs.
- Time of Flight:Solid-state emitter architectures from automotive autonomy programs expand into industrial metrology. Lower capital cost positions these for applications tolerating sub-millimeter accuracy, compressing entry-level tracker addressable markets.
- 3D Laser Scanning:Multistation photogrammetry arrays triangulate target positions without line-of-sight constraints. Danish wind turbine manufacturers deploy synchronized camera systems across nacelle halls where crane occlusion previously interrupted measurement sequences.
- Optical:Conventional angular encoder systems with LED illumination target price-sensitive calibration laboratory markets. China's domestic SAMR-accredited facilities favor these for GB certification workflows.
Phase shift systems retain the bulk of precision-critical installations; time-of-flight architectures are gaining share fastest.
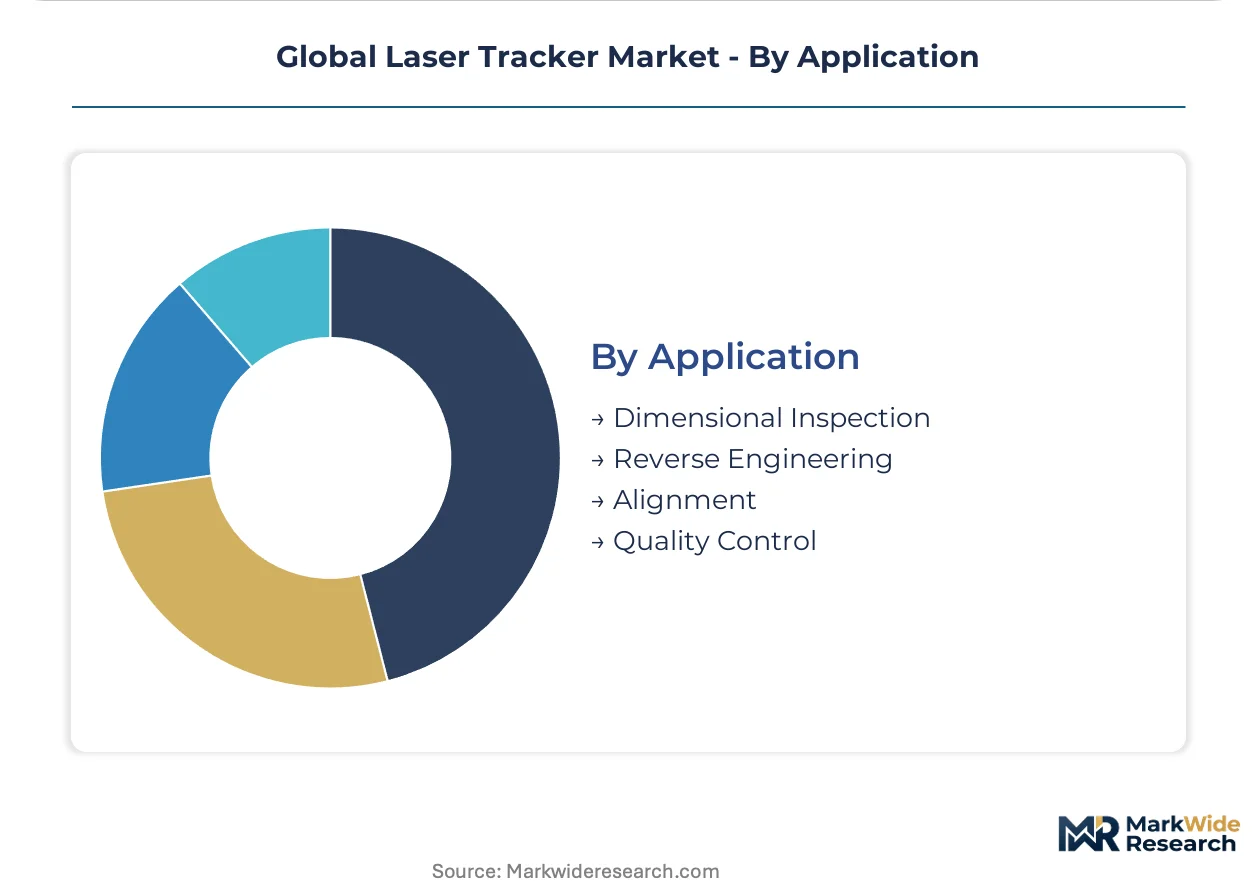
Application:
Software workflow integration requirements vary by use case, with reverse engineering demanding CAD-native output formats that alignment applications rarely require.
- Dimensional Inspection:Geometric tolerance verification against CAD specifications dominates aerospace and automotive quality departments. FDA 21 CFR Part 820 traceability mandates in medical device production create specialized demand for audit-ready measurement records.
- Reverse Engineering:As-built documentation of legacy tooling without original design files serves remanufacturing and obsolescence management. EU Green Deal circular economy claims accelerate adoption for heavy machinery refurbishment programs.
- Alignment:Large-scale tooling and fixture positioning in shipyards and aircraft assembly halls. Huntington Ingalls and DSME operations in Virginia and South Korea anchor demand for spherical coordinate guidance of sub-assembly joining operations.
- Quality Control:Statistical process control integration with manufacturing execution systems. Stuttgart automotive belt suppliers route measurement data directly into Siemens and SAP production planning platforms.
Dimensional inspection commands the bulk of software licensing revenue; reverse engineering applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Lingang Special Area and Singapore's Jurong Innovation District concentrate precision metrology demand through aerospace and semiconductor manufacturing incentives. Tax-advantaged zones in Germany's Ruhr region and India's Tamil Nadu corridor accelerate tracker deployment for defense offset compliance and automotive quality mandates.
United States
Boeing's Everett facility and Huntington Ingalls operations in Virginia drive spherical coordinate verification demand for wing assembly jigs and shipyard sub-assembly alignment. FDA 21 CFR Part 820 traceability mandates in medical device production create specialized procurement protocols for audit-ready metrology workflows. Greater Boston's interferometry specialist cluster anchors diagnostic capability for multi-path error compensation.
Germany
Airbus Hamburg operations and Stuttgart's automotive belt absorb portable trackers for AS9100-mandated inline inspection and just-in-time tooling drift detection. ECHA REACH restrictions on lead-containing optical coatings force reformulation of retroreflector assemblies for CE-marked product lines. Ruhr region heavy machinery producers deploy trackers for carbon border adjustment documentation supporting remanufacturing claims.
China
TSMC's Nanjing fabrication complex and BYD's Shenzhen automotive operations anchor demand for wafer-stage calibration and battery pack dimensional verification. SAMR-administered GB standards mandate domestic calibration laboratory partnerships for imported equipment. Yangtze River Delta semiconductor clusters drive fixed tracker installations requiring sub-micron repeatability.
Japan
Toyota City and Nagoya industrial corridor integrate portable trackers into statistical process control workflows feeding Siemens and SAP production planning platforms. METI industrial standardization programs accelerate JIS calibration certification for domestic metrology service providers. Kyushu semiconductor facilities concentrate demand for vibration-isolated measurement stations.
India
Defence Procurement Procedure offset obligations compel foreign aerospace primes to establish local metrology capability for fighter airframe assembly in Bengaluru and Hyderabad. BIS certification requirements shape procurement specifications for imported dimensional measurement equipment. Tamil Nadu's defense manufacturing corridor attracts tracker deployments for Sukhoi airframe alignment operations.
Global Laser Tracker Market Competitive Environment
Swedish and German producers anchor the premium interferometry tier; American specialists hold positions in portable configurations and software-integrated workflows. The vendor base separates into three strategic tiers: precision optics houses with vacuum-sealed cavity manufacturing, portable system integrators emphasizing factory floor deployment flexibility, and software-centric platforms fusing photogrammetry with traditional coordinate measurement. Competitive moves concentrate on R&D intensity in multi-path error compensation algorithms and geographic expansion through regional calibration service centers.
Within the precision optics tier, Hexagon AB exemplifies European manufacturing footprint advantages sustaining REACH and RoHS compliance across CE-marked product lines. FARO Technologies, Inc. represents the portable configuration specialist archetype, occupying positions emphasizing deployment flexibility across diverse industrial environments. Automated Precision, Inc. anchors the algorithm-intensive segment, with its Maryland-based operations reflecting American concentration in interferometry-based measurement software development.
| Leading Market Players |
|---|
| Hexagon AB |
| FARO Technologies, Inc. |
| Automated Precision, Inc. |
| Leica Geosystems AG |
| Mitutoyo Corporation |
| InnovMetric Software Inc. |
| PLX Inc. |
| CHOTEST TECHNOLOGY INC. |
| VMT GmbH |
| Others |
Value Chain & Pricing Dynamics
Captive manufacturing of stabilized HeNe laser tubes in Germany and Japan anchors both supply security and premium pricing power for precision-tier tracker OEMs. This backward integration into vacuum-sealed cavity production insulates incumbents from spot-market volatility while forcing non-integrated competitors to absorb extended lead-time premiums on critical optical inputs.
Pricing Analysis
Short lead-time premiums of thirty to fifty percent over standard delivery schedules separate emergency procurement from planned capital budgets across aerospace and semiconductor verticals. Three-tier pricing structure across interferometry-precision, time-of-flight mid-market, and optical-encoder economy levels reflects certification-grade differentiation and after-sales bundling intensity. Pricing pressure stems from solid-state LiDAR spillover compressing entry-level tracker margins. Automotive tier-one suppliers in Stuttgart exhibit highest price sensitivity due to procurement department resistance to bundled five-year service commitments, while FDA-regulated medical device manufacturers accept premium positioning for audit-ready traceability workflows.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Boeing's Everett facility and TSMC's Nanjing complex, while distributor networks serve mid-market calibration laboratories and regional automotive suppliers. German and Japanese suppliers dominate stabilized HeNe laser tube manufacturing, with Chinese glass-ceramic formulators emerging as alternative retroreflector sources under REACH reformulation pressures. Single-source vulnerability in vacuum-sealed cavity components exposes tracker OEMs to supply interruption risks from specialty optics houses. Distribution runs through authorized metrology service centers for CE-marked and GB-certified equipment requiring domestic calibration partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around REACH compliance burdens and interferometry specialist scarcity that marginalize capital-constrained challengers. Regulatory recertification costs for lead-free optical coatings and multi-standard certification burdens fragment quality engineering resources, forcing weaker players toward exit.
For Market Incumbents: Anchor defensive positioning through captive supply agreements with Stuttgart and Tokyo metropolitan optics clusters, securing prioritized allocation of stabilized HeNe laser tubes against single-source fragility. Deepen algorithm R&D investment in multi-path error compensation software to maintain precision-tier differentiation against solid-state time-of-flight encroachment. Control regional calibration service center networks to lock in recurring revenue streams and raise switching costs for automotive and aerospace accounts.
For New Entrants and Emerging Players: The price-point gap between phase-shift interferometry premium systems and optical-encoder economy units creates white-space opportunity for solid-state time-of-flight architectures targeting sub-millimeter tolerance applications. Target wind turbine blade manufacturing in Denmark and Spain where photogrammetry fusion requirements favor modular hybrid tracker configurations. Pursue software-native positioning emphasizing CAD-native output formats and manufacturing execution system integration rather than hardware-centric competitive framing.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to precision optics houses seeking interferometry algorithm capabilities and regional service footprints. Long-term viability favors targets with established SAMR calibration laboratory partnerships in China and FDA 21 CFR Part 820 traceability workflows in medical device verticals. Monitor ECHA enforcement intensity against lead-containing optical coatings as inflection indicator for accelerated consolidation among non-compliant component suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Tube Manufacturing | German and Japanese vacuum-sealed cavity captive supply secures allocation priority against single-source fragility risks. |
| Multi-Standard Certification Investment | Simultaneous FDA, ISO 10360, and SAMR GB qualification expands addressable market across medical, aerospace, and China semiconductor verticals. |
| Photogrammetry Fusion Platform Development | Danish and Spanish wind turbine manufacturers adopt hybrid architectures overcoming crane occlusion in nacelle assembly halls. |
| Regional Calibration Service Center Expansion | Stuttgart and Wolfsburg automotive suppliers unbundle hardware procurement from operational expenditure maintenance schedules. |
| REACH-Compliant Optical Component Reformulation | ECHA restrictions on lead-based index-matching compounds force twelve to eighteen month R&D cycles for CE-marked retroreflector assemblies. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this laser tracker market assessment. Primary interviews with metrology engineering directors, aerospace quality assurance leads, semiconductor fab equipment planners, and automotive tier-one procurement officers combined with secondary validation from ECHA substance restriction databases, SAMR GB standard publications, and FDA 21 CFR Part 820 guidance documents. Bottom-up shipment analysis across portable, fixed, infrastructure, and hybrid tracker configurations triangulated against top-down capital expenditure surveys from heavy manufacturing and aerospace defense verticals.
Data-stream reconciliation across product type, technology architecture, end-user vertical, and geographic production cluster dimensions shaped the analytical framework across the analysis window. CAGRs derived from weighted average of historical shipment trajectories and forward-looking capital budget intentions from identified demand anchors. Industry-specific forecast inputs incorporated AS9100 Rev D mandate implementation timelines and carbon border adjustment documentation requirements affecting German heavy machinery remanufacturing programs.
Inputs from ECHA enforcement actions, SAMR calibration laboratory accreditation records, and aerospace prime contractor metrology budget disclosures were available through the study window; gaps in real-time inventory positions at German and Japanese laser tube manufacturers introduce uncertainty bands around supply-side assumptions. Forecasts reflect documented base-case assumptions regarding REACH recast implementation schedules and LiDAR convergence technology maturation. Periodic stress-testing of base assumptions against regulatory enforcement intensity and automotive autonomy program spillover rates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Electrical Test Equipment Market
Test and Measurement
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market
Test and Measurement
Temperature Humidity Chambers Market
Test and Measurement
Radio Frequency Test Equipment Market
Test and Measurement
Ground Grid Tester Market
Test and Measurement
Structure Tester Market
Test and Measurement
Distortion Meter Market
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
Advanced Node Wafer Defect Inspection Systems Market
Test and Measurement
Fluorometers Market
Test and Measurement
Mechanical Testing Equipment Market
Test and Measurement
Automated Calibration-as-a-Service Platforms for Test and Measurement Assets Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Roughness Tester Market
Test and Measurement
Asia-Pacific Electronic Test and Measurement Market
Test and Measurement
Battery Resistance Tester Market